
 Citrus Yogurt Market | 2026-2036
Citrus Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Yogurt Market Analysis
Buyer concentration is expanding across health-focused retail channels as supermarkets and online platforms consolidate shelf-space decisions for functional dairy. Chobani LLC leverages its direct-to-consumer infrastructure to sustain brand loyalty in the citrus-flavored Greek yogurt segment. General Mills Inc. anchors mass-market distribution through conventional grocery networks. Danone S.A. competes with specialized probiotic positioning in organic citrus variants.
Citrus yogurt denotes fermented dairy or plant-based substrates infused with citrus fruit extracts, juices, or essential oils, typically containing live bacterial cultures and achieving pH ranges of 4.0 to 4.6 for shelf stability and tartness balance; manufacturers employ cold-pressing or aseptic blending to preserve volatile citrus terpenes during production. Greek Yogurt occupies the premium tier with thicker texture and higher protein content that commands margin premiums, while Non-Dairy Yogurt captures the fastest expansion as oat and coconut bases attract lactose-intolerant consumers. Online Retail channels are restructuring price discovery and subscription mechanics for repeat citrus yogurt purchases.
The FDA oversees dairy labeling standards and probiotic health claims in the United States, while the USDA administers organic certification requirements that constrain ingredient sourcing for citrus yogurt producers. China's SAMR enforces national food safety standards including GB 19302 for fermented milk products, which governs additive limits and microbial specifications. Stakeholders must monitor evolving clean-label enforcement and alternative protein regulation as these frameworks determine market access and formulation freedom across jurisdictions.
Market Dynamics
Clean-label mandates from the FDA and USDA are compressing formulation timelines while cold-pressing technology preserves volatile citrus terpenes for shelf-stable products. Dairy processors must reformulate rapidly to meet additive restrictions without sacrificing tartness balance.
Growth Catalysts
- Probiotic Health Claims:FDA guidance on live culture labeling permits functional positioning that commands retail shelf space in United States supermarkets.
- China's Urban Middle Class:Households in Shanghai and Beijing are expanding refrigerated dairy purchases as disposable incomes rise.
- Oat Base Fermentation:Enzymatic hydrolysis technology enables creamy mouthfeel in plant-based substrates without dairy proteins.
Market Restraints
- Citrus Input Volatility:Florida orange harvest fluctuations concentrate price risk for processors dependent on cold-pressed Valencia extracts.
- Supply Concentration Risk:Three domestic dairy cooperatives control aseptic blending capacity in the Upper Midwest, creating bottleneck exposure.
- pH Stability Ceiling:Volatile terpene degradation above 4.6 pH limits ambient distribution reach for clean-label formulations.
Strategic Opportunities
- Subscription Direct-to-Consumer:Chilled delivery infrastructure in the Northeast Corridor enables recurring revenue capture outside conventional grocery.
- Dual Carbon Goals:China's national climate targets incentivize low-carbon fermentation processes for domestic producers.
- Pediatric Functional Positioning:Vitamin C fortification meets parental demand for immunity-supporting snacks in daycare channels.
Industry Challenges
- Clean-Label Reformulation Timelines:USDA organic certification requires 36-month ingredient traceability that delays new product launches.
- Terpenes Preservation Expertise:Scarcity of flavor chemists trained in cold-press aseptic integration constrains R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Yogurt Market |
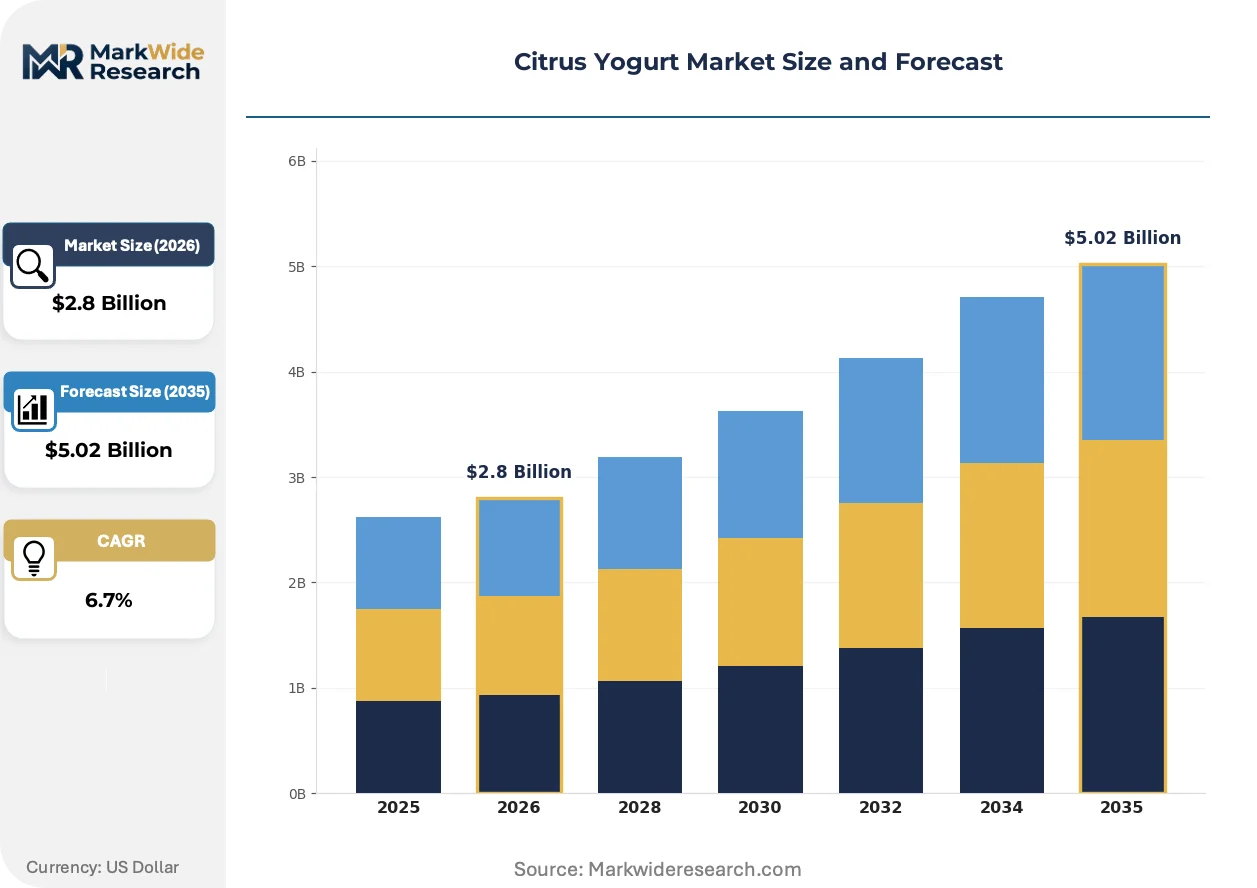
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Low-Fat Yogurt, Non-Dairy Yogurt, Organic Yogurt Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Stores Consumer Segment: Fitness Enthusiasts, Health-Conscious Individuals, Children, Seniors Flavor Profile: Orange, Lemon, Lime, Grapefruit |
| Companies Covered | Danone S.A., Chobani LLC, General Mills Inc., Nestlé S.A., FAGE International S.A., Arla Foods amba, Lactalis, Fonterra Co-operative Group Limited, China Mengniu Dairy Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Yogurt Market Emerging Trajectories
Functional dairy is fragmenting across substrate types as fermentation science enables plant-based parity with conventional mouthfeel. Cold-chain logistics and direct-to-consumer infrastructure are compressing traditional retail gatekeeper roles.
High-pressure processing is overtaking conventional pasteurization for citrus yogurt production. This non-thermal technology eliminates pathogens while preserving heat-sensitive vitamin C and volatile aroma compounds. Premium organic brands in California and New York are adopting HPP at commercial scale. The technology is overtaking legacy thermal methods by enabling 90-day refrigerated shelf life without chemical preservatives.
China's SAMR enforcement of GB 19302 additive limits is tightening formulation standards for fermented milk products. Domestic producers must reduce synthetic stabilizer use or reformulate with approved natural alternatives. Mengniu and regional competitors are accelerating clean-label R&D to maintain national distribution licenses.
Millennial and Gen Z households are consolidating purchases through subscription platforms that bypass conventional grocery slotting fees. This channel compression rewards brands with direct fulfillment infrastructure and punishes mass-market players dependent on retailer negotiations. The shift is most pronounced in coastal metropolitan areas where cold-chain delivery density supports weekly replenishment cycles.
Citrus Yogurt Market Segmentation
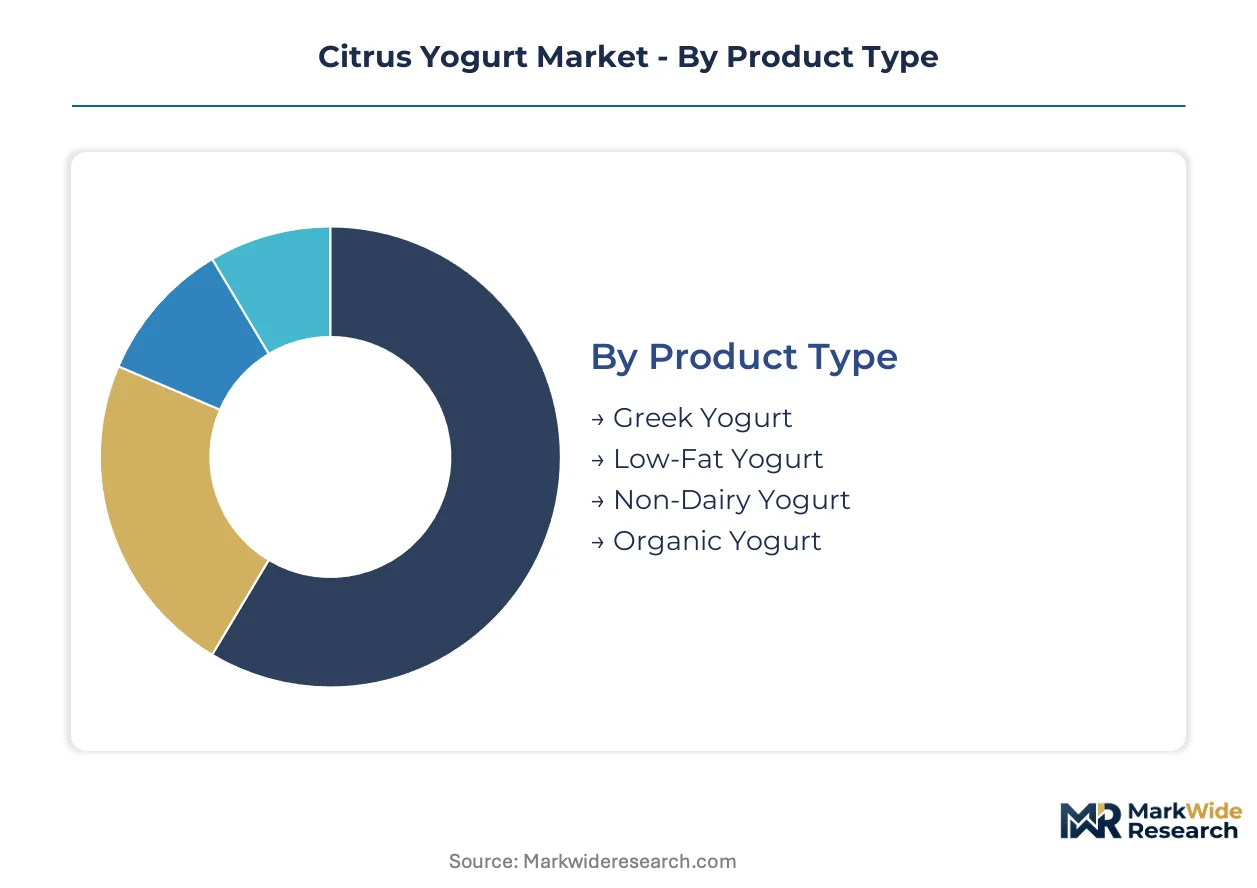
Citrus yogurt manufacturers calibrate formulation and positioning across four distinct taxonomies. Product type determines margin architecture and substrate technology. Distribution channel governs cold-chain investment and pricing power. Consumer segment shapes functional claims and packaging formats. Flavor profile dictates terpene preservation requirements and regional preference mapping.
Product Type:
Greek Yogurt commands the premium tier through protein density and texture differentiation, while Non-Dairy Yogurt climbs fastest on oat and coconut fermentation advances.
- Greek Yogurt:Strained dairy substrate achieving 10-15% protein content through whey separation. Demand concentrates in United States coastal metros where Chobani and Fage anchor refrigerated case positioning with citrus-infused variants. FDA live-culture labeling permits functional probiotic claims that sustain retail slotting fees.
- Non-Dairy Yogurt:Fermented oat, coconut, or almond bases using enzymatic hydrolysis for creamy mouthfeel. Health-conscious millennials in California and New York drive expansion as lactose intolerance reshapes household dairy purchases. Clean-label requirements from the USDA constrain stabilizer selection across organic SKUs.
- Low-Fat Yogurt:Reduced-fat dairy formulations targeting calorie-conscious consumers through modified fermentation protocols.
- Organic Yogurt:USDA-certified ingredient sourcing with 36-month traceability requirements governing supply base qualification.
Today's leader: Greek Yogurt. Tomorrow's challenger: Non-Dairy Yogurt.
Distribution Channel:
Supermarkets retain volume dominance through refrigerated case infrastructure, while Online Retail restructures subscription economics and price discovery mechanics.
- Supermarkets:Conventional grocery networks with controlled cold-chain display cases. United States mass-market penetration depends on slotting fee negotiations with Kroger, Albertsons, and regional banners. Chobani leverages direct-store-delivery to defend shelf positioning.
- Online Retail:Direct-to-consumer platforms with chilled last-mile logistics. Northeast Corridor density enables weekly replenishment cycles that bypass conventional retail gatekeepers. Subscription mechanics capture recurring revenue from millennial households.
- Convenience Stores:Ambient and refrigerated grab-and-go formats targeting immediate consumption occasions.
- Health Food Stores:Curated SKU selection emphasizing organic certification and functional ingredient transparency.
Supermarkets still move the tonnage. Online Retail is capturing the margin.
Consumer Segment:
Fitness Enthusiasts anchor high-protein Greek yogurt demand, while Health-Conscious Individuals fragment across substrate types and clean-label requirements.
- Fitness Enthusiasts:Protein-seeking consumers prioritizing post-workout recovery formats. United States gym-channel partnerships and sports nutrition positioning command per-ounce premiums. Chobani and General Mills target this cohort with portable cup formats.
- Health-Conscious Individuals:Broad demographic spanning probiotic awareness, organic preference, and sugar reduction. China's urban middle class in Shanghai and Beijing expands refrigerated dairy purchases as disposable incomes rise and SAMR enforcement tightens additive standards.
- Children:Pediatric positioning with vitamin C fortification for immunity claims in daycare and school channels.
- Seniors:Digestive health and bone-density functional claims targeting aging population nutrient needs.
The core volume sits with Health-Conscious Individuals. The growth vector points to Fitness Enthusiasts.
Flavor Profile:
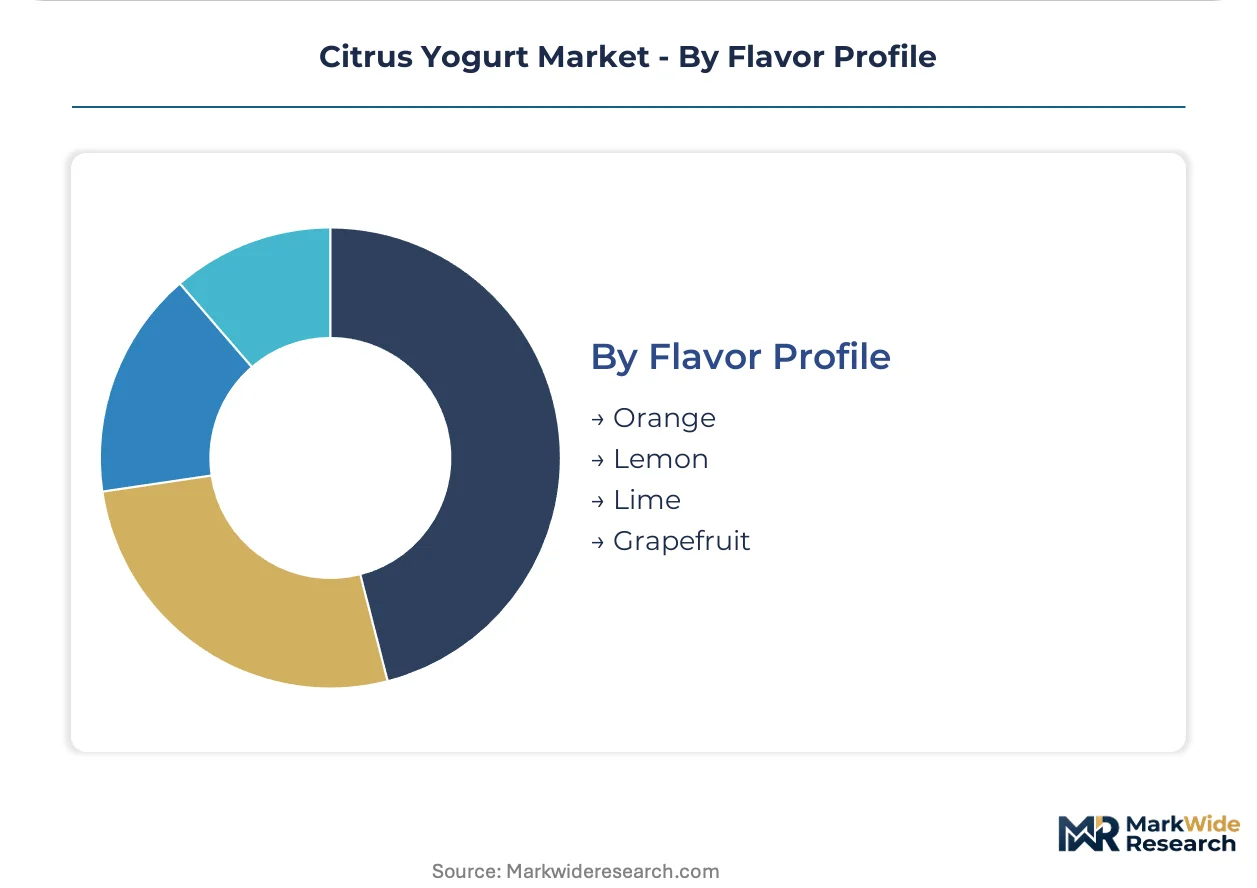
Orange dominates formulation runs and consumer recognition, while Grapefruit occupies niche premium positioning with bitterness management challenges.
- Orange:Valencia and blood orange extracts delivering familiar sweetness with terpene complexity. Florida harvest volatility concentrates input cost risk for cold-pressed processors. Mengniu and domestic Chinese producers favor orange for mass-market palatability.
- Lemon:Higher acidity profile requiring pH calibration between 4.0-4.6 for shelf stability. Mediterranean and California sourcing provides year-round supply continuity.
- Lime:Distinctive aromatic profile with Mexican and Persian varietal sourcing. Cocktail-inspired positioning targets adult snacking occasions.
- Grapefruit:Bitterness compounds requiring sugar balance or stevia modulation. Premium organic brands in California adopt high-pressure processing to preserve volatile aroma compounds.
Orange owns the present. Grapefruit is testing the premium ceiling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists trained in cold-press aseptic integration concentrate in California's Central Valley and New York's Hudson Valley, anchoring formulation expertise for premium citrus yogurt production.
United States
Health-conscious millennials and Gen Z consumers in coastal metros drive probiotic functional positioning. FDA live-culture labeling guidance permits shelf-space claims that sustain retail negotiations. California's Central Valley clusters high-pressure processing facilities for organic brands seeking 90-day refrigerated shelf life.
China
Urban middle-class households in Shanghai and Beijing expand refrigerated dairy purchases as disposable incomes rise. SAMR enforcement of GB 19302 additive limits tightens formulation standards for fermented milk products. Mengniu anchors national distribution through clean-label R&D investments in citrus-infused portfolios.
France
Premium organic yogurt demand concentrates in Paris and Lyon metropolitan areas. EFSA probiotic health claim regulations constrain functional positioning while enabling quality differentiation. Brittany's dairy cooperatives supply aseptic blending capacity for Mediterranean citrus sourcing.
Germany
Clean-label requirements from EU organic certification reshape ingredient traceability standards. ECHA chemical safety assessments influence stabilizer selection across plant-based substrates. Bavaria's food technology institutes advance enzymatic hydrolysis for oat-base fermentation parity.
Australia
Lactose-intolerant consumers in Sydney and Melbourne accelerate non-dairy yogurt adoption. FSANZ food standards govern probiotic labeling and additive limits for fermented products. Victoria's Gippsland region clusters specialty dairy processors targeting Asian export markets.
Citrus Yogurt Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate technologies and distribution channels. Market structure tiers around scale-driven mass-market players, premium organic specialists, and emerging plant-based innovators. Three archetypes dominate: multinational dairy conglomerates with global cold-chain infrastructure, regional pure-plays with direct-to-consumer subscription platforms, and domestic champions leveraging local citrus sourcing advantages. Competitive moves concentrate on portfolio diversification into oat and coconut bases and backward integration into cold-pressing capacity.
Among multinational dairy conglomerates, Danone S.A. and Nestlé S.A. exemplify scale-driven archetypes with global refrigerated distribution networks. Chobani LLC occupies a specialist position within the premium Greek yogurt tier, leveraging direct-to-consumer infrastructure to bypass conventional retail gatekeepers. China Mengniu Dairy Company Limited anchors the domestic champion archetype, concentrating clean-label R&D investments for national distribution under SAMR regulatory frameworks.
| Leading Market Players |
|---|
| Danone S.A. |
| Chobani LLC |
| General Mills Inc. |
| Nestlé S.A. |
| FAGE International S.A. |
| Arla Foods amba |
| Lactalis |
| Fonterra Co-operative Group Limited |
| China Mengniu Dairy Company Limited |
| Others |
Supply Flow & Price Mechanics
Clean-label mandates from the FDA and USDA are forcing dairy processors to source certified organic citrus extracts and cold-press capacity, compressing margins and elevating procurement costs for reformulated SKUs. This demand-side specification shift concentrates buying power among three Upper Midwest dairy cooperatives that control aseptic blending infrastructure.
Pricing Analysis
Capacity additions in China's fermentation facilities are reshaping price floors for oat-base substrates that compete with conventional dairy. Three-tier pricing structure across premium, standard, and economy levels separates HPP-treated organic citrus yogurt from conventional thermal-pasteurized lines and private-label economy tiers. Price differentiation hinges on USDA organic certification tier and cold-chain delivery density. Cost compression in the standard tier is intensifying as Mengniu and domestic Chinese producers scale clean-label R&D. Health-Conscious Individuals in coastal metros show lowest price sensitivity; convenience channel grab-and-go buyers exhibit highest.
Supply Chain Analysis
Reverse-logistics infrastructure for chilled citrus yogurt remains underdeveloped, with expired product flows concentrated in conventional grocery rather than direct-to-consumer channels. Supply concentrates in the United States, China, and France. Raw material dependencies include Florida Valencia oranges, Mediterranean lemon extracts, and enzymatically hydrolyzed oat bases. Single-source vulnerability runs through Florida orange harvest fluctuations that concentrate price risk for cold-pressed processors. Distribution runs through supermarket refrigerated cases with direct-store-delivery networks defending shelf positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Citrus yogurt has entered a late-cycle quality phase where premium specifications—HPP processing, 90-day refrigerated shelf life, and SAMR-compliant clean labels—command sustainable margin premiums over commodity thermal-pasteurized alternatives.
For Market Incumbents: Acquire cold-pressing and aseptic blending capacity in the Upper Midwest or California Central Valley to secure terpene preservation expertise. Consolidate backward into Florida citrus sourcing partnerships to hedge harvest volatility. Defend against oat-base substitutes by accelerating HPP adoption for dairy substrates. For New Entrants and Emerging Players: Begin with subscription direct-to-consumer infrastructure in the Northeast Corridor, where chilled last-mile density enables weekly replenishment cycles outside supermarket slotting fee structures. Target pediatric functional positioning with vitamin C fortification for immunity claims in daycare channels. Partner with enzymatic hydrolysis technology providers for oat-base mouthfeel parity. For Investors and Strategic Acquirers: Asymmetric upside sits with regional pure-plays possessing captive cold-chain logistics and SAMR-compliant clean-label portfolios in China. Five-to-ten-year viability favors producers with integrated fermentation and citrus processing capabilities. Monitor GB 19302 enforcement intensity and Florida orange yield reports as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Capacity Acquisition | Secures terpene preservation expertise for clean-label shelf stability under FDA guidance. |
| HPP Technology Deployment | Enables 90-day refrigerated shelf life without chemical preservatives for organic SKUs. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees and captures recurring revenue from millennial households. |
| Oat-Base Fermentation Scale-Up | Addresses lactose-intolerant demand through enzymatic hydrolysis technology advances. |
| SAMR Compliance Investment | Maintains national distribution licenses under tightening GB 19302 additive limits in China. |
Methodological Framework
Bottom-up substrate modeling reconciled against top-down cold-chain infrastructure tracking forms the analytical core of this study. Primary interviews with dairy R&D directors, flavor chemists specializing in terpene preservation, supermarket category buyers, and SAMR regulatory consultants combined with secondary validation from FDA guidance documents, USDA organic certification databases, GB 19302 standards filings, and Nielsen retail audit data. Triangulation across these sources reconciles formulation cost structures with shelf-space negotiation dynamics.
Input-output matrices map citrus yogurt production across substrate type, distribution channel, and regional regulatory cluster throughout the forecast period. Modeled segmentation dimensions include product type, flavor profile, consumer segment, and cold-chain investment tier. CAGRs derive from volume trajectory analysis calibrated against disposable income elasticity in China's urban middle class and probiotic health claim penetration in United States coastal metros. Forecast inputs incorporate HPP adoption curves and oat-base fermentation yield improvements.
Several conditions sit outside the modeled scope, including abrupt Florida citrus crop failures, SAMR enforcement discontinuities, and breakthroughs in ambient-stable probiotic cultures. Forecasts reflect documented assumptions about clean-label compliance timelines and cold-chain density expansion. Practitioners should monitor Florida orange harvest reports, GB 19302 amendment proposals, and HPP equipment capacity utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Fresh Milk Market
Dairy Products
Cheddar Cheese Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Cheese Color Market
Dairy Products
Milk Retentate Market
Dairy Products
United States Dairy Desserts Market
Dairy Products
United States Milk Protein Market
Dairy Products
Global Milk Protein Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Reduced Fat Cheeses Market