
 Qatar Dairy Products Market | 2026-2036
Qatar Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Dairy Products Market Analytics
Multi-pack yogurt bundling is expanding across Qatar's retail channels as grocers respond to household bulk-buying patterns and price-sensitive expatriate segments. Baladna Food Industries leverages its integrated farm-to-shelf operations to dominate fresh milk supply. Nestle SA competes through specialized nutrition lines that target pediatric and elderly dietary needs. Danone SA anchors its position with probiotic-forward yogurt portfolios tailored to regional taste profiles.
Qatar dairy products encompass fluid milk, fermented goods, and fat-based derivatives processed through pasteurization, homogenization, and ultra-high-temperature treatment to achieve shelf stability and microbial safety for commercial distribution. Milk and yogurt occupy the largest volume share, while cheese commands premium margins in foodservice channels. Tetra Pak packaging extends ambient reach for wholesalers supplying remote retail points across the peninsula. Online retail is gaining traction among time-constrained urban households seeking subscription-based delivery.
The Qatar General Authority of Standardization and Qatar Ministry of Public Health enforce halal integrity, nutritional labeling, and cold-chain compliance that determine both import clearance and domestic manufacturing licensure. The Ministry of Municipality and Environment oversees dairy farm licensing and feed import protocols that constrain local herd expansion. Stakeholders must monitor evolving shelf-life standards and sustainability disclosure requirements that will reshape supplier qualification criteria and capital allocation priorities.
Market Dynamics
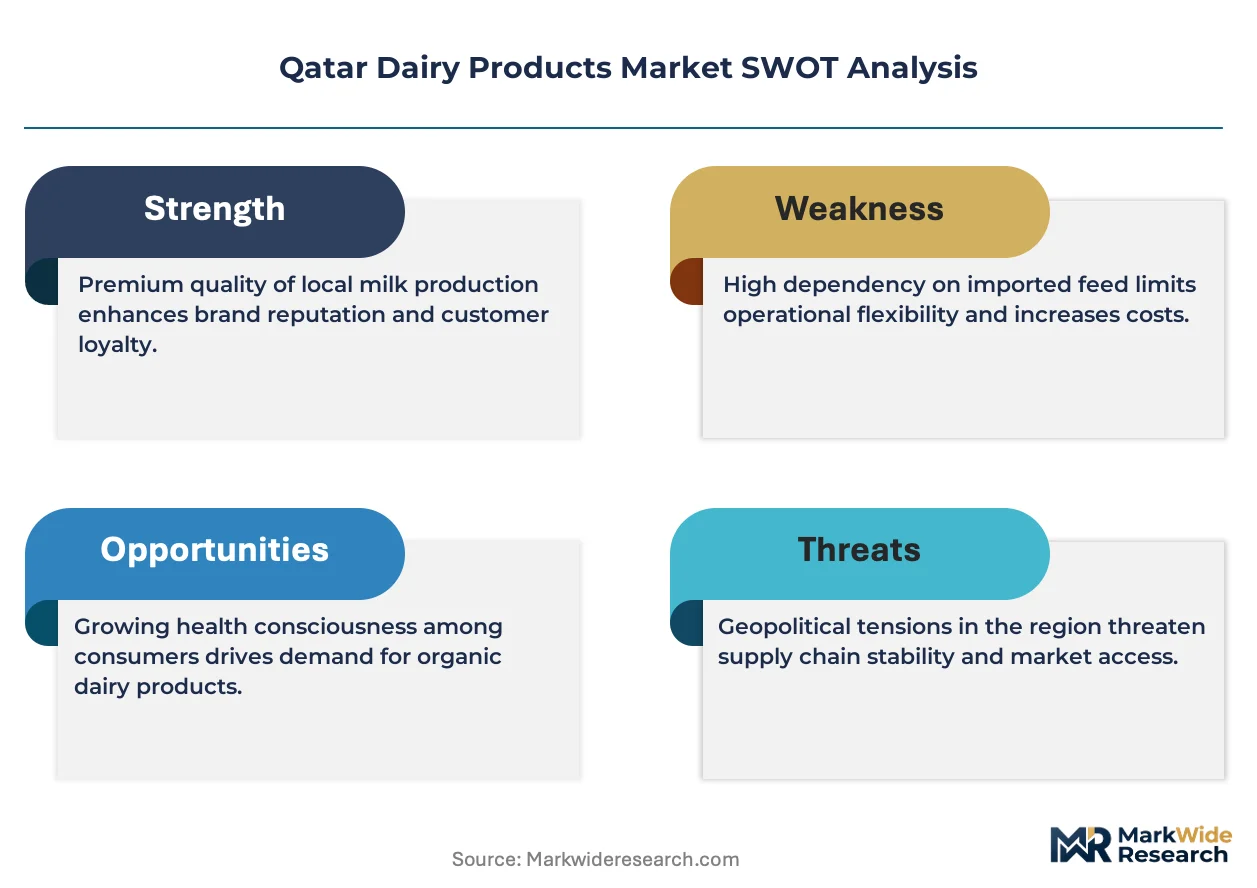
Qatar's dairy sector faces acute supply concentration risk as local production capacity remains tethered to imported feed grains and breeding stock, while the Qatar General Authority of Standardization tightens halal traceability requirements that favor integrated domestic operators over fragmented import-reliant distributors.
Growth Catalysts
- Foodservice format standardization:Hotels and airline caterers in Doha now mandate portion-controlled dairy SKUs, pulling processors toward automated filling lines and single-serve packaging formats that reduce waste and labor cost.
- Qatar National Food Security Strategy:State-backed capital subsidies for dairy farm expansion and cold-storage infrastructure are compressing payback periods for local milk production investments.
- Extended ambient distribution:UHT processing and aseptic Tetra Pak filling is extending product reach to remote retail points across the northern and southern peninsula where refrigerated logistics remain sparse.
Market Restraints
- Feed import dependency:Local dairy herds rely on alfalfa and soybean meal shipped from Argentina and the United States, exposing margins to freight rate volatility and currency fluctuation.
- Water scarcity constraints:Groundwater extraction limits enforced by the Ministry of Municipality and Environment cap herd expansion regardless of capital availability or demand signals.
- Halal certification friction:The Qatar General Authority of Standardization's evolving shelf-life labeling and slaughter-derived additive rules delay import clearance for European and South American suppliers.
Strategic Opportunities
- E-commerce subscription channels:Urban households in Doha and Al Wakrah are adopting recurring delivery platforms for fresh milk and yogurt, opening direct-to-consumer routes that bypass traditional retail markups.
- Probiotic functional positioning:Digestive health claims aligned with Qatar Ministry of Public Health nutritional guidelines allow premium pricing in pharmacy and clinic retail channels.
- Desert greenhouse fodder integration:Hydroponic barley sprouting systems are reducing feed import volumes for early-adopter farms, creating a replicable model for supply-chain backward integration.
Industry Challenges
- Cold-chain technician scarcity:Qualified refrigeration engineers and HACCP auditors are concentrated in Doha, forcing rural distribution facilities to rely on contract maintenance with extended response times.
- Dual certification timelines:Products targeting both retail and foodservice must clear separate Qatar Ministry of Public Health and Qatar General Authority of Standardization review tracks, extending launch cycles.
- Legacy ERP integration:Family-owned dairy distributors are struggling to connect inventory systems with modern traceability platforms demanded by hypermarket chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Dairy Products Market |
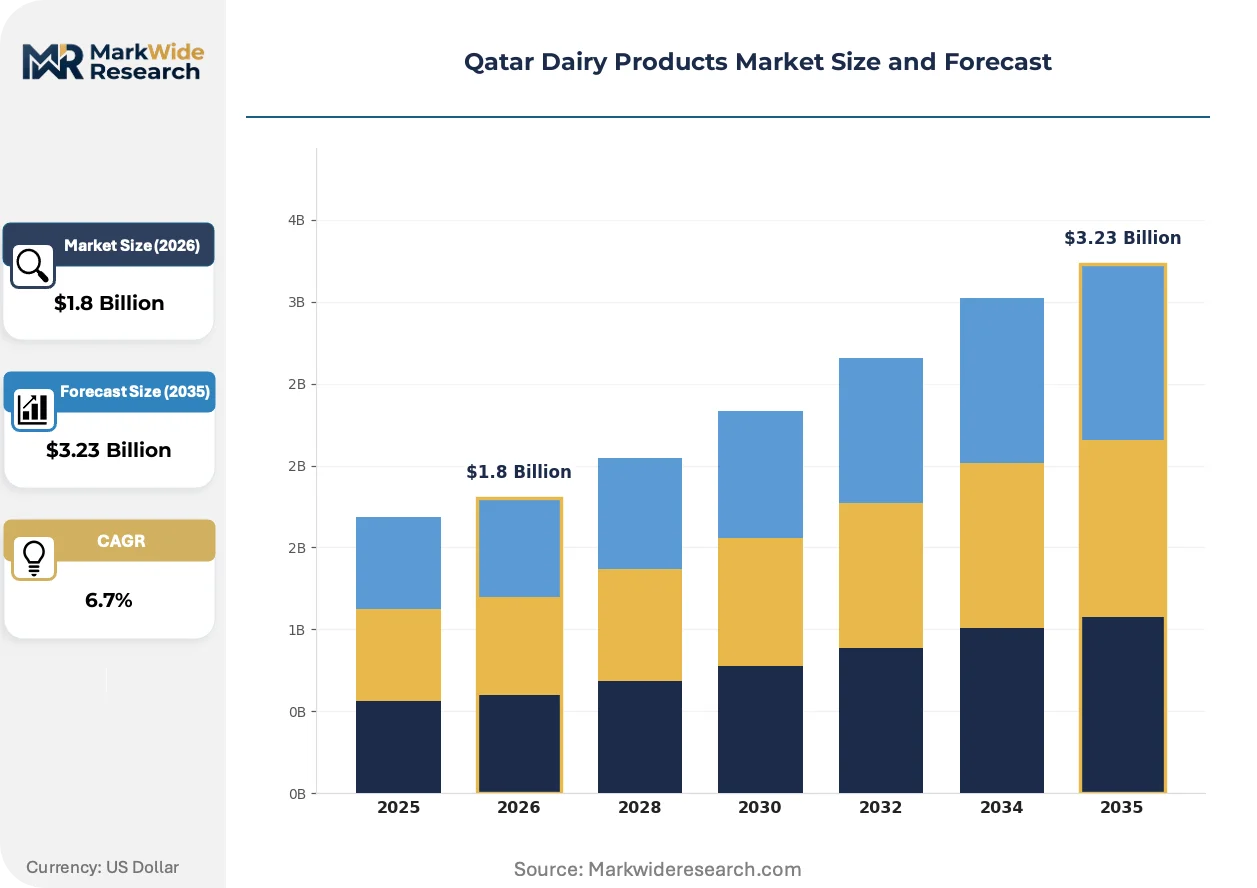
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers Customer Type: Households, Restaurants, Cafes, Foodservice Providers Packaging Type: Bottles, Tetra Packs, Cans, Cartons |
| Companies Covered | Nestle SA, Ghadeer Dairy, Baladna Food Industries, Danone SA, Yasar Holding AS, Al Maha, Arla Foods amba, Groupe Lactalis, Gulf Food Production, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Dairy Products Market Evolving Landscape
Processing technology and distribution infrastructure are converging to reshape how dairy moves from farm to consumer in Qatar's concentrated urban corridors and dispersed peripheral settlements.
Aseptic filling and modular UHT processing units are modularizing production scale decisions for mid-sized dairy processors. Operators in Doha's industrial zone now deploy containerized sterilization lines that scale in 5,000-liter increments rather than committing to fixed 50,000-liter installations. This compression of minimum efficient scale is enabling regional brands to enter ambient milk categories previously dominated by multinational supply agreements.
Qatar General Authority of Standardization enforcement of halal integrity certification and nutritional front-of-pack labeling is restructuring supplier qualification protocols. Import clearance now requires batch-level slaughter-method documentation for rennet and whey derivatives, favoring processors with captive laboratory testing capacity. Foodservice distributors are responding by consolidating supplier panels to reduce audit burden and compliance risk exposure.
Subscription-based replenishment models are displacing traditional supermarket stock-up behavior among time-constrained professional households in Doha and Lusail. Digital platforms offering weekly fresh milk and yogurt delivery are capturing recurring revenue streams that hypermarkets struggle to replicate. This channel shift is most visible in the expatriate residential compounds of West Bay and The Pearl, where delivery density supports same-day fulfillment economics.
Qatar Dairy Products Market Segmentation
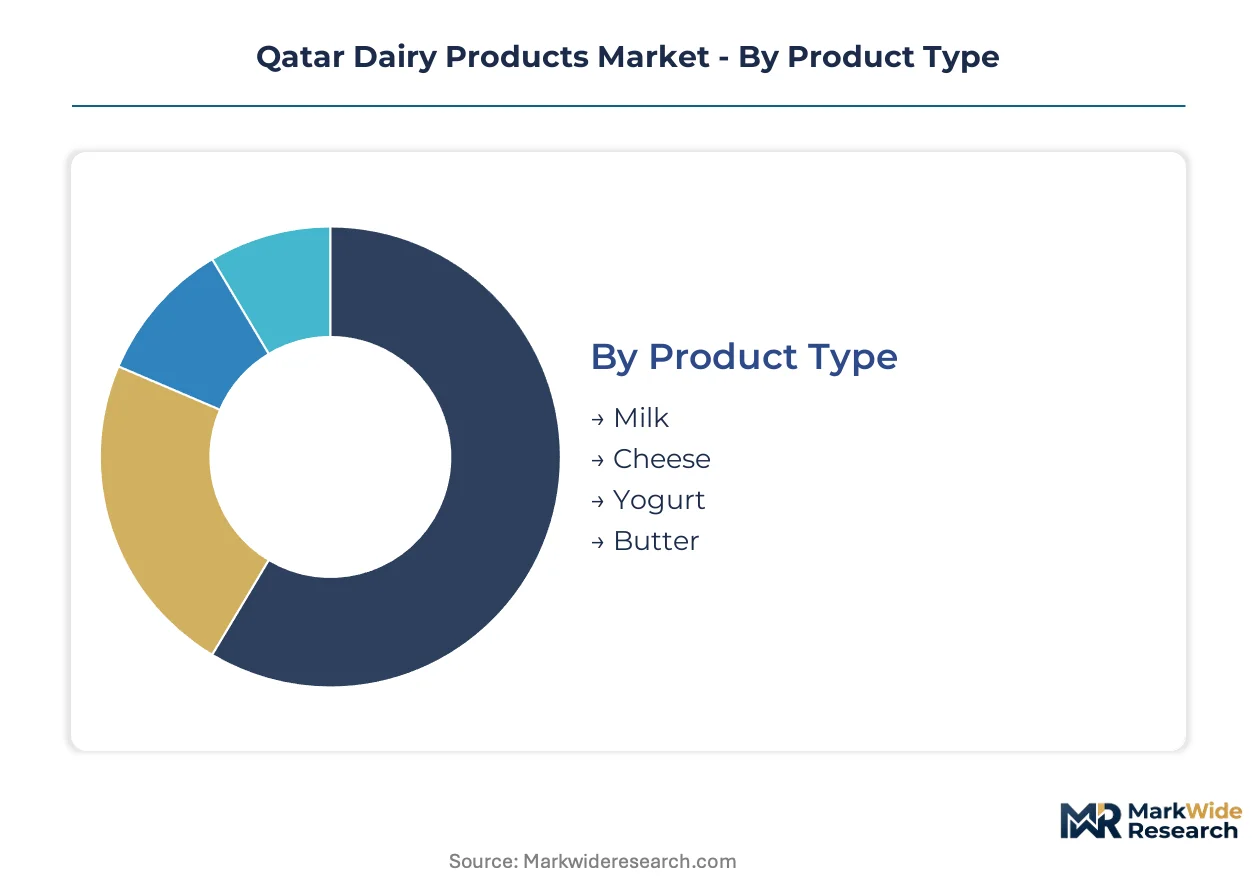
Qatar's dairy market segments reflect divergent procurement logics across retail, foodservice, and institutional channels. Each category carries distinct margin structures, shelf-life requirements, and regulatory compliance burdens that reshape supplier positioning.
Product Type:
Consumption patterns vary sharply between daily staples commanding high purchase frequency and specialty items driving premium pricing in hospitality channels.
- Milk:Pasteurized fresh milk and UHT-treated ambient variants constitute the volume foundation, with Baladna Food Industries' integrated farm operations supplying Doha's retail and foodservice networks. Household bulk-buying concentrates in hypermarkets, while single-serve portions dominate airline and hotel procurement.
- Yogurt:Probiotic-forward fermented products with tailored regional flavor profiles anchor pharmacy and clinic retail channels where digestive health claims command premium positioning. Danone SA's portfolio targets this functional positioning.
- Cheese:Rennet and whey derivatives face Qatar General Authority of Standardization batch-level slaughter-method documentation requirements that delay import clearance.
- Butter:Fat-based spreads serve bakery and confectionery foodservice segments with concentrated demand in Doha's hotel and catering corridors.
Milk leads volumes today; yogurt is gaining share fastest through functional health positioning.
Distribution Channel:
Channel selection determines cold-chain investment intensity and regulatory touchpoint density for dairy operators.
- Supermarkets:Hypermarket chains in Doha and Al Wakrah demand modern traceability platform integration that strains family-owned distributor ERP systems. Multi-pack bundling and promotional pricing dominate household procurement patterns here.
- Online Retail:Subscription-based replenishment platforms capture recurring revenue from expatriate compounds in West Bay and The Pearl, where same-day delivery density supports fulfillment economics.
- Convenience Stores:Small-format retail in residential neighborhoods prioritizes ambient UHT products with extended shelf stability over fresh refrigerated inventory.
- Wholesalers:Bulk distributors supply remote retail points across Qatar's northern and southern peninsula where refrigerated logistics remain sparse and Tetra Pak ambient formats extend reach.
Supermarkets retain the largest transaction volume; online retail is climbing the fastest among time-constrained professional households.
Customer Type:
End-user procurement specifications diverge between price-sensitive household budgeting and foodservice format standardization mandates.
- Households:Expatriate segments in Doha's metropolitan corridor exhibit bulk-buying behavior that drives multi-pack yogurt bundling, while Qatari nationals prioritize halal-certified fresh milk from domestic integrated operations.
- Foodservice Providers:Hotels and airline caterers mandate portion-controlled SKUs with automated filling compatibility, pulling processors toward single-serve packaging that reduces waste and labor cost.
- Restaurants:Independent dining establishments in Lusail and The Pearl concentrate cheese demand for menu differentiation, accepting premium margins for specialized import products.
- Cafes:Beverage-focused outlets drive butter and cream procurement for espresso-based drink preparation, with concentrated demand in Doha's commercial districts.
Households dominate absolute consumption; foodservice providers are expanding most quickly through procurement standardization mandates.
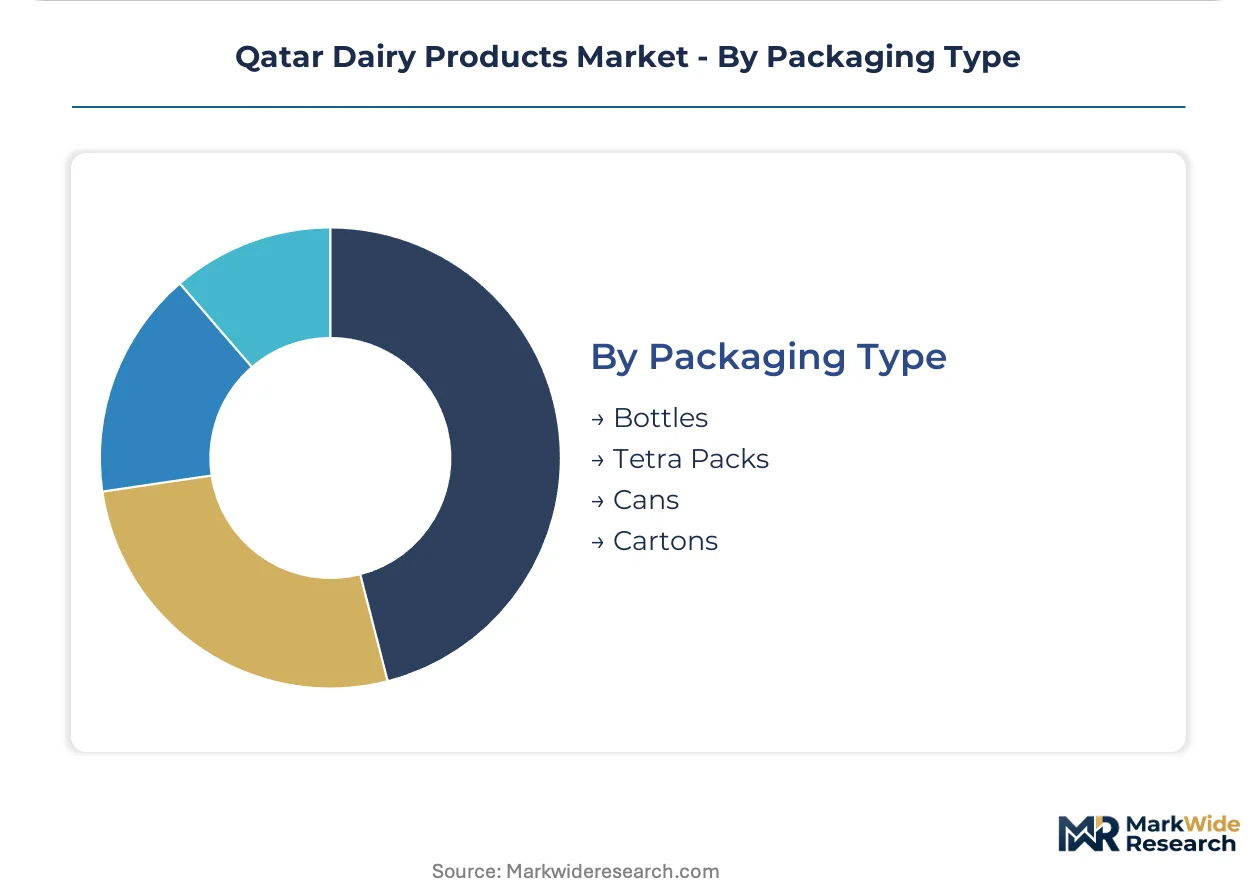
Packaging Type:
Material selection shapes shelf-life extension capabilities, logistics economics, and Qatar General Authority of Standardization labeling compliance requirements.
- Tetra Packs:Aseptic carton filling enables ambient distribution to remote retail points without refrigerated infrastructure, supporting Qatar National Food Security Strategy objectives for geographic coverage extension.
- Bottles:HDPE and PET formats dominate fresh pasteurized milk in Doha's retail corridor, where cold-chain density supports shorter shelf-life products and consumer preference for visible liquid clarity.
- Cartons:Gable-top refrigerated containers serve yogurt and fermented products with intermediate shelf-life requirements in supermarket dairy cases.
- Cans:Metal packaging retains niche application for evaporated milk and emergency stockpiling formats aligned with national food security reserve protocols.
Tetra Packs lead volume for ambient reach; bottles retain dominance in fresh milk segments with steepest expansion trajectory for aseptic variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial dairy processing in Qatar traces its modern lineage to state-led agricultural investments during the 1980s, when the first integrated dairy farms emerged to reduce import dependency. The sector has since concentrated in metropolitan Doha and its surrounding industrial corridors.
Doha Metropolitan Corridor
Hotel procurement mandates for portion-controlled dairy SKUs are reshaping processor investment toward automated filling lines. The Qatar General Authority of Standardization enforces halal traceability and shelf-life labeling that determines import eligibility. Al Wakrah industrial zones host cold-storage consolidation facilities serving foodservice distributors.
Al Rayyan Municipality
Expatriate residential compounds drive subscription-based fresh milk delivery adoption among time-constrained professional households. The Qatar Ministry of Public Health regulates nutritional front-of-pack labeling for products entering pharmacy retail channels. Baladna Food Industries operates integrated farm-to-shelf facilities in this corridor.
Umm Salal Municipality
Groundwater extraction caps enforced by the Ministry of Municipality and Environment constrain herd expansion regardless of capital availability. State-backed subsidies under the Qatar National Food Security Strategy compress payback periods for dairy farm investments. Remote retail points here rely on Tetra Pak ambient distribution from Doha-based wholesalers.
Al Khor and Al Thakhira
Northern peninsula settlements exhibit sparse refrigerated logistics infrastructure, extending demand for UHT-processed products with ambient stability. The Qatar General Authority of Standardization's batch-level documentation requirements for whey derivatives delay import clearance. Wholesalers supply convenience stores with extended-shelf-life formats.
Al Wakra and Mesaieed
Southern industrial zones concentrate food manufacturing clusters with concentrated butter and cream demand from bakery and confectionery segments. Dual certification timelines through the Qatar Ministry of Public Health and Qatar General Authority of Standardization extend product launch cycles. Family-owned distributors here struggle with legacy ERP integration demands from hypermarket chains.
Qatar Dairy Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across halal certification integration and cold-chain density. The market exhibits tiered concentration with integrated domestic operators commanding fresh milk supply while multinational nutrition specialists compete in functional yogurt segments. Three archetypes dominate: vertically integrated farm-to-shelf operators, probiotic-forward functional nutrition platforms, and import-reliant distribution consolidators. Competitive moves center on backward integration into captive feed production and automated portion-control packaging line deployment.
Among the integrated domestic operators, Baladna Food Industries anchors the fresh milk supply tier through its captive farm operations. Danone SA and Nestle SA occupy positions within the functional nutrition specialist tier, with the former representing probiotic-forward yogurt positioning and the latter exemplifying pediatric and elderly dietary specialization. These three entities collectively illustrate the competitive structure stratification between local production dominance and multinational brand leverage in specialized segments.
| Leading Market Players |
|---|
| Nestle SA |
| Ghadeer Dairy |
| Baladna Food Industries |
| Danone SA |
| Yasar Holding AS |
| Al Maha |
| Arla Foods amba |
| Groupe Lactalis |
| Gulf Food Production |
| Others |
Value Network & Pricing Analysis
Imported alfalfa and soybean meal from Argentina and the United States feed into Qatar's dairy pricing tiers through feed cost pass-through mechanisms that compress margins for import-reliant distributors while insulating integrated domestic operators. This input cost pathway shapes a three-tier pricing structure across premium halal-certified fresh milk, standard UHT ambient formats, and economy private-label offerings that compete on volume scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Baladna's farm-fresh halal milk from multinational UHT brands and hypermarket private labels. Price differentiation hinges on halal certification tier and cold-chain density, with premium tiers commanding markup for batch-level traceability documentation. Cost compression in the economy tier is intensifying because freight rate volatility on trans-Atlantic feed shipments erodes distributor margins. Expatriate households in West Bay compounds exhibit highest price sensitivity, while foodservice procurement teams at Doha hotels prioritize format standardization over unit cost.
Supply Chain Analysis
Qualified refrigeration engineers and HACCP auditors concentrate in Doha's industrial zones, forcing rural distribution facilities to rely on contract maintenance with extended response times. Manufacturing inputs draw from the United States, Argentina, and the Netherlands for breeding stock, feed grains, and processing equipment respectively. Single-source vulnerability runs through the alfalfa import corridor from Argentina, where drought cycles and port congestion disrupt scheduled deliveries. Distribution runs through hypermarket chains in Doha's metropolitan corridor that demand modern traceability platform integration from upstream suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's dairy sector functions as a regulatory compounder where Qatar General Authority of Standardization shelf-life labeling mandates and halal traceability requirements continuously reshape supplier qualification criteria and capital allocation priorities.
For Market Incumbents: Cement market position by deepening backward integration into captive hydroponic barley sprouting systems that reduce feed import exposure, while deploying automated portion-control packaging lines to capture foodservice format standardization mandates from Doha hotel procurement teams. Threat substitution from subscription-based e-commerce platforms demands channel control investment to defend recurring revenue streams. For New Entrants and Emerging Players: Modular UHT processing technology offers entry into ambient milk categories previously blocked by multinational supply agreements, with particular white-space opportunity in pharmacy retail channels where probiotic functional positioning aligns with Qatar Ministry of Public Health nutritional guidelines. Target Al Wakrah and Lusail expatriate compounds with direct-to-consumer subscription platforms that bypass hypermarket retail markups. For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned distributors struggle to connect legacy ERP systems with modern traceability platforms demanded by retail chains. Long-term viability favors vertically integrated operators with captive feed production and laboratory testing capacity for halal certification compliance. Watch Qatar National Food Security Strategy subsidy allocation announcements as inflection indicators for domestic production investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydroponic Feed Production | Reduces alfalfa import dependency for farms operating under Ministry of Municipality and Environment groundwater caps. |
| Automated Portion-Control Packaging Deployment | Captures foodservice procurement mandates from Doha hotel and airline catering operations seeking waste reduction. |
| Direct-to-Consumer Subscription Platform Launch | Bypasses hypermarket retail markups in West Bay and The Pearl expatriate residential compounds. |
| Laboratory Testing Capacity Expansion | Accelerates Qatar General Authority of Standardization halal certification clearance for whey derivative imports. |
| Cold-Storage Infrastructure Buildout | Extends fresh milk distribution reach to Al Khor and Mesaieed under Qatar National Food Security Strategy subsidies. |
Research Methodology
Direct dialogue with dairy farm operations managers, hypermarket category buyers, foodservice procurement directors, and Qatar General Authority of Standardization compliance officers grounded this analysis in operational reality. Secondary validation drew from Qatar Ministry of Public Health regulatory filings, Qatar General Authority of Standardization shelf-life labeling protocols, customs import records for feed grains, and Baladna Food Industries integrated operations disclosures. Bottom-up volume modeling across product type, distribution channel, and customer type segments triangulated against top-down macroeconomic indicators.
Segment-level projections across milk, yogurt, cheese, and butter categories combined with distribution channel penetration rates yielded value estimates over the projection horizon. CAGRs were derived from historical volume trajectories adjusted for Qatar National Food Security Strategy subsidy impacts and feed import cost volatility. Modeled inputs included groundwater extraction caps enforced by the Ministry of Municipality and Environment, halal certification timeline assumptions, and cold-chain infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Qatar General Authority of Standardization regulatory evolution and trans-Atlantic freight rate fluctuations. Forecasts reflect documented assumptions on subsidy continuity and certification processing efficiency. Material deviation in feed import cost trajectories or groundwater policy enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Organic Dairy Market
Dairy Products
South America Yogurt Market
Dairy Products
Sheep Milk Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
North America Sour Cream Market
Dairy Products
GCC Cheese Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Paneer Market
Dairy Products
Blue Cheese Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Dairy Blends Market