
 Global Military Thermal Imaging Market | 2026-2036
Global Military Thermal Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Thermal Imaging Market Foresight
Platform upgrade and sustainment revenue is tilting toward integrated sensor refurbishment and software-defined thermal payloads. Lockheed Martin leverages its position in fighter jet sensor fusion architectures to capture recurring modernization contracts. L3Harris Technologies anchors naval and ground platform thermal sight programs through long-term defense procurement agreements. Elbit Systems specializes in helmet-mounted display integration for dismounted soldier programs across multiple allied defense forces.
Military thermal imaging detects infrared radiation emitted by objects and converts thermal signatures into visible imagery using cooled or uncooled sensor arrays operating across long-wave infrared (LWIR) and mid-wave infrared (MWIR) spectral bands, enabling target identification in complete darkness, smoke, or obscured battlefield conditions. Vehicle-mounted systems dominate procurement value as armored platform modernization cycles accelerate across mechanized infantry and armored cavalry units. Uncooled microbolometer technology leads unit volume due to lower power requirements and reduced lifecycle maintenance, while cooled sensors sustain premium positioning in long-range target acquisition and airborne reconnaissance applications where resolution thresholds determine mission effectiveness.
Defense procurement standards from the US Department of Defense, NATO STANAG agreements, and the EU's European Defence Fund collectively shape sensor interoperability mandates and cross-border equipment certification pathways. The US ITAR regime and EU dual-use export controls restrict technology transfer and influence supplier geographic concentration. Stakeholders must monitor evolving classification thresholds for uncooled sensor performance as commercial thermal technology advances toward military-grade specifications.
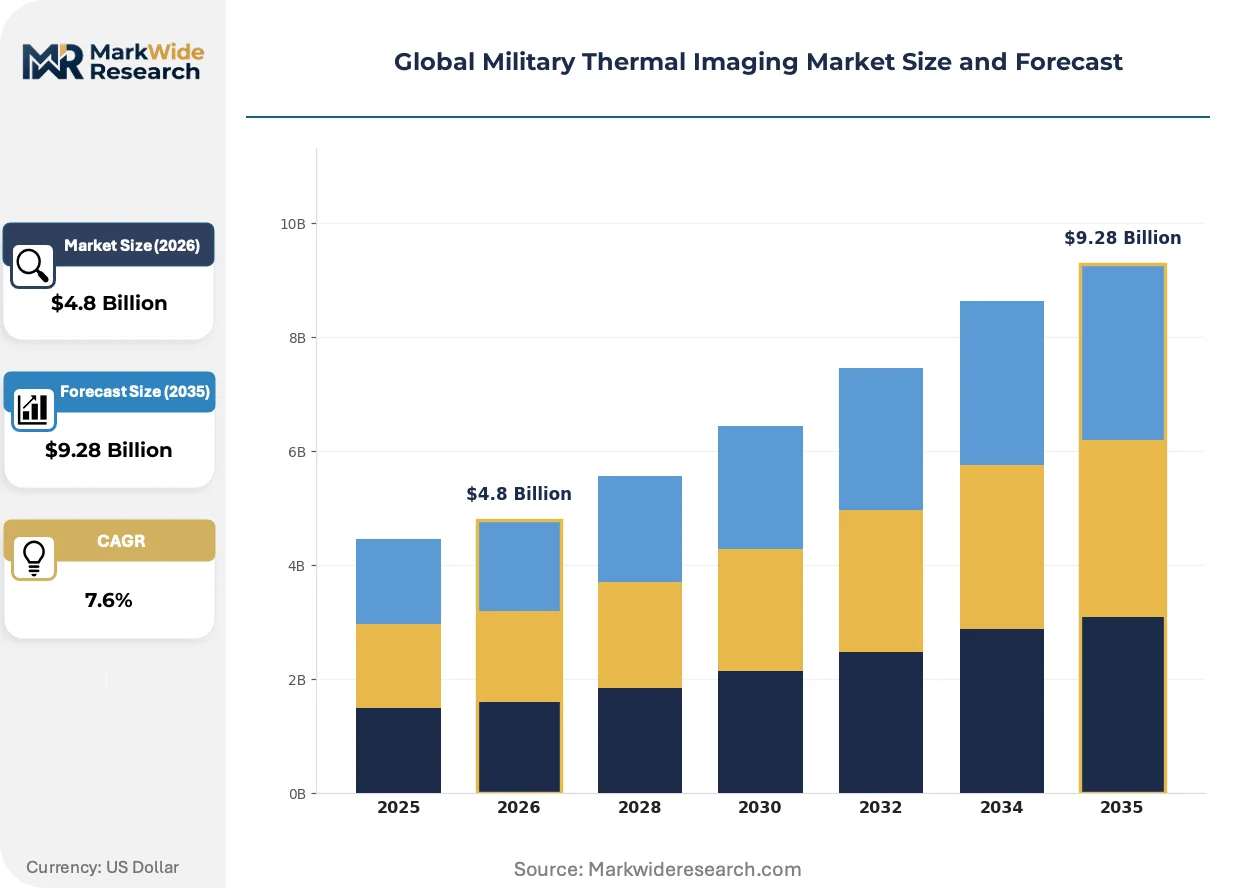
Market Dynamics
Defense procurement agencies are consolidating thermal sensor specifications around NATO STANAG interoperability mandates, forcing suppliers to reengineer product architectures for cross-platform compatibility rather than proprietary lock-in.
Growth Catalysts
- US DoD modernization directives:The Pentagon's ground combat platform upgrade schedules mandate thermal imaging retrofits for armored vehicle fleets, creating sustained program demand through 2035.
- Border surveillance infrastructure:NATO member states are expanding vehicle-mounted thermal procurement for frontier monitoring, driven by revised collective defense posture requirements.
- Uncooled microbolometer maturation:Advances in vanadium oxide detector fabrication are extending mission duration for dismounted soldier systems without cryogenic cooling logistics.
Market Restraints
- Indium antimonide supply concentration:Cooled MWIR sensor production depends on limited gallium arsenide foundry capacity concentrated in East Asian semiconductor manufacturing hubs.
- US ITAR classification thresholds:Export control restrictions on focal plane array resolution specifications fragment supplier access to allied defense procurement programs.
- Helium-3 conservation protocols:Detector cooling systems face input cost volatility as nuclear non-proliferation agreements constrain neutron detection demand competition for cryogenic gas supplies.
Strategic Opportunities
- Urban warfare sensor miniaturization:Australian and Canadian special operations forces are piloting helmet-mounted thermal fusion with augmented reality overlays for close-quarters combat.
- Dual-use technology convergence:Integration of military thermal cores with commercial drone platforms creates aftermarket retrofit demand from law enforcement agencies.
- EU European Defence Fund cross-border certification:Harmonized equipment standards enable suppliers to access pooled procurement across multiple member state defense ministries.
Industry Challenges
- SWaP-C engineering talent scarcity:Size, weight, power, and cost optimization for airborne gimbal systems requires specialized optomechanical design expertise concentrated at prime contractors.
- Legacy analog interface integration:Digital thermal payloads must maintain backward compatibility with Vietnam-era platform wiring architectures still operational in reserve armored units.
- Environmental qualification timelines:MIL-STD-810H testing for thermal shock and salt fog resistance extends product validation cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Thermal Imaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Vehicle-Mounted Systems, Helmet-Mounted Displays, Drone-Mounted Cameras, Fixed Surveillance Units Technology: Cooled Thermal Sensors, Uncooled Thermal Sensors, Quantum Well Infrared Photodetectors, Microbolometers, Thermopile Arrays Application: Night Vision Reconnaissance, Border Surveillance, Target Acquisition, Search & Rescue Operations, Threat Detection End User: Defense Forces, Special Operations Units, Security Contractors, Military Research Labs |
| Companies Covered | Lockheed Martin Corporation, RTX Corporation, Teledyne FLIR LLC, L3Harris Technologies, Inc., BAE Systems Plc, Leonardo S.p.A., Thales Group S.A., Northrop Grumman Corporation, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Thermal Imaging Market Shifts & Advancements
Software-defined thermal architectures are displacing fixed-function hardware, enabling post-deployment algorithm updates that extend platform operational relevance without physical sensor replacement.
Artificial intelligence-enabled target recognition is rendering obsolete manual operator interpretation in high-clutter environments. Mechanized infantry units in Poland and Romania are fielding AI-augmented thermal sights that autonomously flag vehicle signatures. This compression of cognitive load is shifting procurement criteria toward compute-integrated sensor packages rather than standalone optics.
EU F-Gas Regulation phase-down schedules are accelerating alternative cooling technology development for high-performance MWIR systems. Industrial gas restrictions are forcing detector manufacturers toward Stirling cycle microcoolers and thermoelectric alternatives. German and French defense procurement offices are now specifying fluorinated gas-free cooling in next-generation airborne reconnaissance tenders.
Defense agencies are unbundling sensor hardware from software maintenance contracts, creating discrete revenue streams for algorithm update subscriptions. Prime contractors face margin pressure as government buyers separate physical platform procurement from recurring digital service fees. This disaggregation is most advanced in US Army ground vehicle programs and UK MoD helicopter modernization initiatives.
Global Military Thermal Imaging Market Segmentation
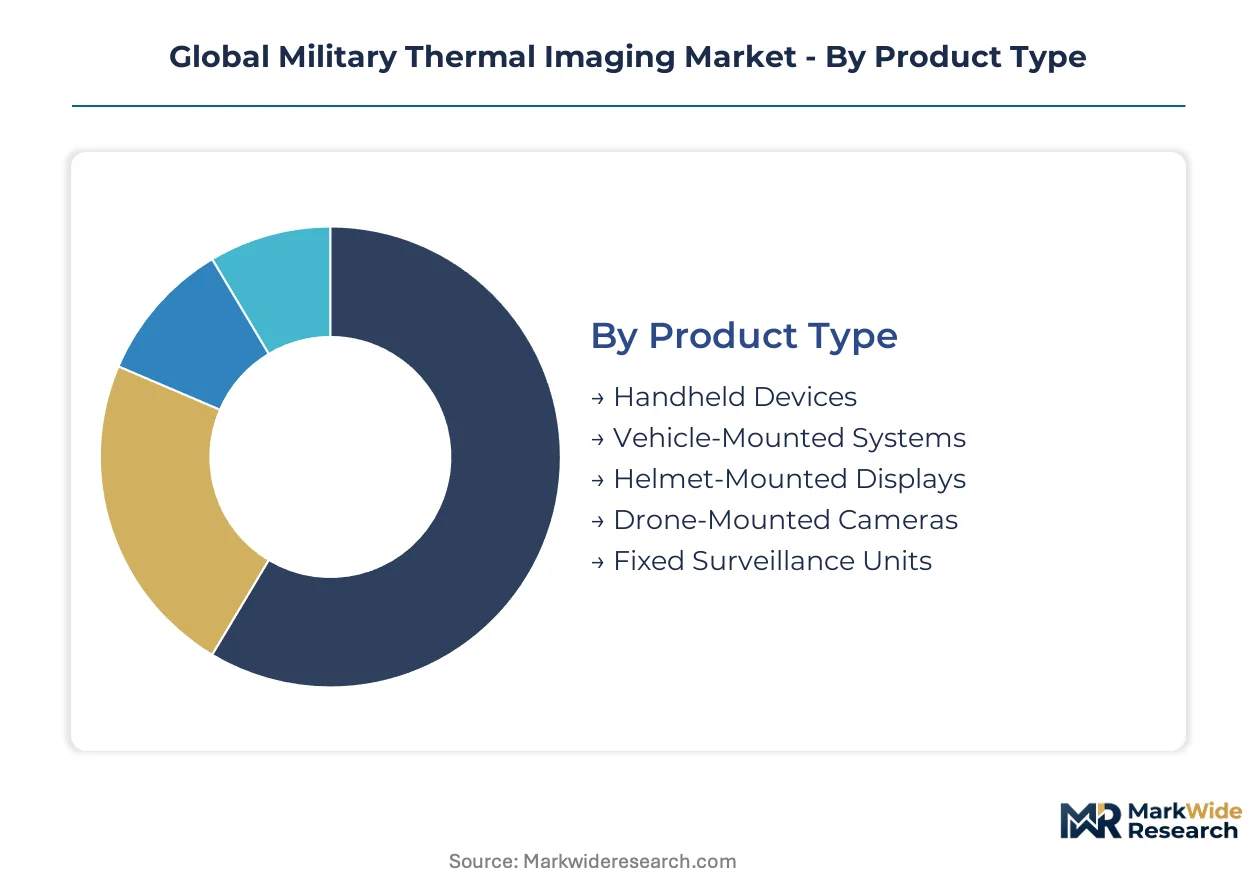
Thermal imaging procurement patterns diverge sharply across platform types, with sustainment contracts and software upgrade cycles creating distinct aftermarket revenue profiles for each segment category. Defense procurement agencies now specify lifecycle service requirements upfront, embedding maintenance obligations into initial acquisition awards.
Product Type:
Aftermarket service intensity varies dramatically by mounting configuration, with vehicle-integrated systems demanding depot-level overhaul capabilities while dismounted soldier equipment relies on field-replaceable module programs.
- Handheld Devices:Portable monocular and binocular units built around uncooled microbolometer cores serve dismounted infantry and forward observers. Polish and Romanian mechanized units are fielding these for squad-level thermal capability without vehicle dependence. Maintenance cycles concentrate at battalion-level forward support companies.
- Vehicle-Mounted Systems:Stabilized gimbal assemblies integrate with armored platform fire control architectures, requiring alignment with NATO STANAG 4694 interoperability mandates. US Army ground combat platform upgrade schedules prioritize these retrofits through 2035. Depot-level refurbishment and software recertification generate recurring revenue streams exceeding initial hardware value over fifteen-year service lives.
- Helmet-Mounted Displays:Elbit Systems anchors this segment through fusion architectures combining thermal imagery with direct-view optics. Australian and Canadian special operations forces pilot augmented reality overlay integration.
- Drone-Mounted Cameras:Miniaturized payloads for tactical unmanned aerial systems exploit commercial microbolometer cost curves while meeting MIL-STD-810H environmental qualification. Dual-use law enforcement retrofit demand is expanding.
- Fixed Surveillance Units:Permanent installations for critical infrastructure and frontier monitoring emphasize detection range and false-alarm rejection algorithms over mobility. NATO border surveillance infrastructure programs favor these for persistent coverage.
Vehicle-mounted systems hold the largest share; momentum sits with helmet-mounted displays.
Technology:
Cost tier stratification separates cryogenically cooled premium performance from solid-state uncooled volume deployment, with foundry capacity constraints determining supply availability.
- Cooled Thermal Sensors:Indium antimonide and mercury cadmium telluride focal plane arrays operating at cryogenic temperatures deliver the resolution thresholds required for long-range airborne reconnaissance. East Asian gallium arsenide foundry concentration constrains production scaling. EU F-Gas Regulation phase-down schedules are accelerating Stirling cycle microcooler adoption to replace fluorinated gas cooling.
- Uncooled Thermal Sensors:Vanadium oxide microbolometers eliminate cryogenic logistics, extending mission duration for dismounted soldier applications. Advances in detector fabrication are narrowing the performance gap with cooled alternatives. Volume procurement concentrates in US Army soldier modernization programs.
- Quantum Well Infrared Photodetectors:GaAs/AlGaAs heterostructure devices offer tailored spectral response for specific threat signatures. Military research labs evaluate these for hyperspectral thermal fusion applications.
- Microbolometers:Amorphous silicon and vanadium oxide variants dominate unit volume through lower power requirements and reduced lifecycle maintenance. Commercial foundry compatibility enables cost scaling.
- Thermopile Arrays:Lower-cost alternatives for proximity detection and perimeter monitoring where resolution requirements are modest. Security contractor procurement favors these for budget-constrained installations.
Uncooled thermal sensors command the greatest volume; cooled thermal sensors retain the steepest expansion trajectory in next-generation airborne programs.
Application:
Operational tempo and platform integration complexity determine procurement cycle timing, with reconnaissance and surveillance applications leading hardware refresh schedules.
- Night Vision Reconnaissance:Airborne and dismounted platforms exploit thermal contrast for covert observation in complete darkness. Software-defined architectures enable post-deployment algorithm updates that extend operational relevance. US DoD modernization directives prioritize these capabilities for special operations forces.
- Border Surveillance:Persistent monitoring of frontier zones combines vehicle-mounted mobile patrols with fixed surveillance infrastructure. NATO member states are expanding procurement following revised collective defense posture requirements. Procurement packages increasingly bundle hardware with multi-year algorithm update subscriptions.
- Target Acquisition:Fire control integration demands precise ranging and stabilization for weapon system handoff. AI-augmented autonomous flagging of vehicle signatures is compressing operator cognitive load.
- Search & Rescue Operations:Thermal contrast detection of human signatures in challenging terrain supports combat search and rescue missions. Helicopter-mounted systems dominate this niche.
- Threat Detection:Standoff detection of concealed weapons, disturbed earth, and engine heat signatures supports force protection and route clearance operations. Machine learning classification reduces false alarm rates.
Border surveillance holds the largest share; night vision reconnaissance is climbing the fastest as software-defined payloads extend platform utility.
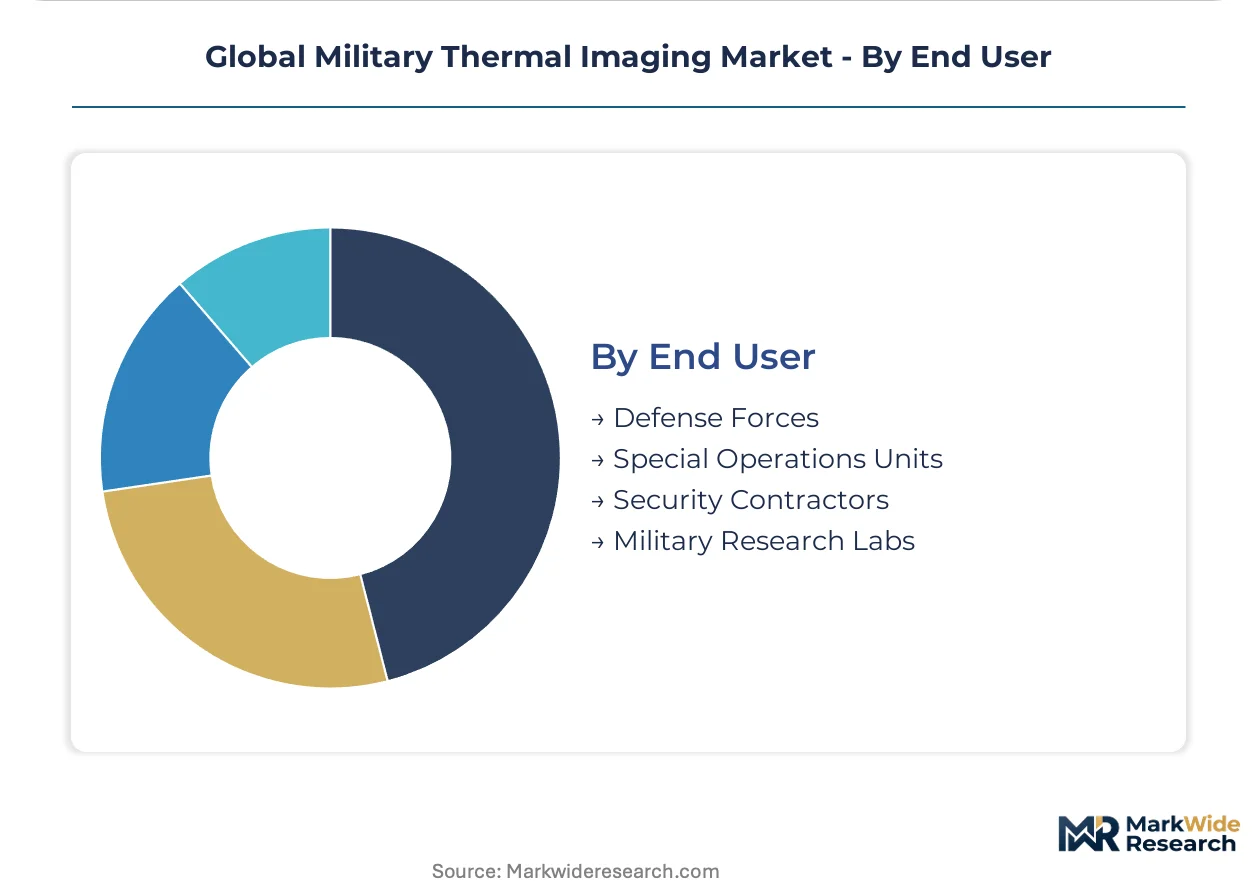
End User:
Customer type determines procurement authority levels, certification requirements, and discretion over supplier selection, with defense ministry programs subject to strictest interoperability mandates.
- Defense Forces:National military services operate the largest fleet inventories, driving standardization around NATO STANAG agreements and US DoD specifications. Long-term defense procurement agreements with Lockheed Martin and L3Harris Technologies anchor this segment. Multi-billion dollar program budgets sustain prime contractor ecosystems.
- Special Operations Units:Small-unit procurement authority enables rapid fielding of experimental technologies before formal adoption. Australian and Canadian forces pilot helmet-mounted thermal fusion with augmented reality overlays. Acquisition timelines compress from years to months.
- Security Contractors:Private military and critical infrastructure protection services source commercial-derivative systems below ITAR classification thresholds. Dual-use technology convergence creates aftermarket retrofit demand from law enforcement agencies.
- Military Research Labs:Defense Advanced Research Projects Agency and equivalent European organizations fund detector technology maturation and algorithm development. Procurement concentrates on experimental quantities for concept validation.
Defense forces hold the largest share; momentum sits with special operations units as rapid acquisition pathways bypass traditional procurement bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement patterns diverge sharply by geography. The United States prioritizes platform modernization at scale, while European allies emphasize cross-border interoperability mandates. Asian defense ministries concentrate investment in maritime surveillance applications.
United States
The Pentagon's ground combat platform upgrade schedules sustain thermal imaging demand through 2035. US ITAR classification thresholds restrict focal plane array exports while shaping domestic supplier ecosystems. Defense contractors in Texas and Arizona anchor production for armored vehicle retrofit programs.
Germany
Bundeswehr mechanized infantry modernization drives vehicle-mounted thermal procurement for Leopard and Puma platforms. EU F-Gas Regulation phase-down schedules accelerate Stirling cycle microcooler adoption in Bavarian defense manufacturing clusters. Munich-based sensor integrators lead alternative cooling technology development.
Poland
Border surveillance infrastructure expansion along eastern frontiers concentrates procurement in vehicle-mounted systems. NATO STANAG interoperability mandates shape specification requirements for domestic integrators. Warsaw defense contractors partner with Western primes for technology transfer under offset agreements.
Australia
Special operations forces pilot helmet-mounted thermal fusion with augmented reality overlays for close-quarters combat. Defence Strategic Review priorities redirect procurement toward Indo-Pacific surveillance capabilities. Melbourne and Adelaide defense clusters concentrate on dismounted soldier system integration.
Israel
Helmet-mounted display integration for allied defense forces anchors export-oriented production. National regulator frameworks emphasize rapid fielding cycles for experimental technologies. Tel Aviv-area defense electronics specialists supply fusion architectures to multiple NATO member programs.
Global Military Thermal Imaging Market Competitive Landscape
Capability concentration sits with prime contractors holding long-term defense procurement agreements; scale advantage sits with diversified aerospace conglomerates. The market structures around tiered supplier relationships where sensor hardware specialists feed into platform integrators. Three archetypes dominate: vertically integrated defense primes, component-focused sensor houses, and software-defined payload specialists. Competitive moves concentrate on strategic partnerships for algorithm development and geographic expansion through offset arrangements.
Among US-based defense primes, Lockheed Martin and L3Harris Technologies exemplify contrasting approaches to thermal imaging market positioning. Lockheed Martin occupies a position anchored in fighter jet sensor fusion architectures, while L3Harris Technologies represents the naval and ground platform sight program specialist archetype. Elbit Systems, an Israel-based defense electronics limited company, sits within the helmet-mounted display integration tier serving dismounted soldier programs across allied forces.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| RTX Corporation |
| Teledyne FLIR LLC |
| L3Harris Technologies, Inc. |
| BAE Systems Plc |
| Leonardo S.p.A. |
| Thales Group S.A. |
| Northrop Grumman Corporation |
| Elbit Systems Ltd. |
| Others |
Supply & Pricing Matrix
East Asian gallium arsenide foundry clusters in Taiwan and South Korea concentrate indium antimonide wafer production, anchoring pricing power for cooled MWIR sensor arrays and forcing Western defense primes to absorb input cost volatility through long-term offtake structures.
Pricing Analysis
Long-term defense procurement agreements dominate contract structures, with fifteen-year platform sustainment schedules locking in recurring software recertification revenue alongside initial hardware delivery. Price differentiation rests on NATO STANAG certification tier and cryogenic cooling performance grade, with cooled sensors commanding substantial premiums over uncooled microbolometer alternatives. Cost compression in uncooled tiers is intensifying as commercial foundry scale erodes military-grade pricing premiums. Security contractors exhibit highest price sensitivity, while US DoD programs prioritize interoperability compliance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning as ITAR classification thresholds fragment focal plane array sourcing options. Detector manufacturing draws from Japan, Germany, and Israel for precision optomechanical components and cryogenic cooling subsystems. Indium antimonide, mercury cadmium telluride, and vanadium oxide microbolometer wafers constitute critical input dependencies. Single-source vulnerability concentrates in East Asian gallium arsenide foundry capacity. Distribution runs through prime contractor integration facilities in Texas, Arizona, and Bavaria before final platform assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial thermal imaging cores advancing toward military-grade specifications threaten incumbent positioning, demanding active substitution defense through software-defined payload differentiation and algorithm lock-in.
For Market Incumbents: Build switching-cost moats through software-defined thermal architectures that embed post-deployment algorithm update dependencies. Deepen backward integration into vanadium oxide detector fabrication to secure uncooled sensor supply chains against commercial foundry competition. Fortify NATO STANAG certification pipelines to maintain interoperability gatekeeper status against emerging sensor houses. For New Entrants and Emerging Players: Build out helmet-mounted display integration capabilities for special operations rapid acquisition pathways that bypass traditional prime contractor procurement timelines. Target Australian and Canadian defense clusters where augmented reality thermal fusion pilots create white-space demand before formal program adoption. Pursue dual-use law enforcement retrofit channels below ITAR classification thresholds. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined payload specialists over fixed-function hardware manufacturers as defense agencies unbundle sensor hardware from recurring digital service contracts. Long-term viability concentrates on algorithm development capabilities and NATO interoperability certification pipelines. Monitor EU F-Gas Regulation enforcement intensity as inflection indicator for Stirling cycle microcooler adoption curves.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Development | Enables post-deployment algorithm updates that extend platform operational relevance without physical sensor replacement across US Army ground vehicle programs. |
| Stirling Cycle Microcooler Adoption | Addresses EU F-Gas Regulation phase-down requirements for German and French airborne reconnaissance tenders. |
| Helmet-Mounted Display Integration | Captures special operations rapid acquisition pathways in Australian and Canadian defense modernization initiatives. |
| Uncooled Microbolometer Scale-Up | Exploits commercial foundry cost curves to serve security contractor and law enforcement dual-use demand below ITAR thresholds. |
| NATO STANAG Certification Investment | Secures cross-platform interoperability mandates required for Polish and Romanian border surveillance infrastructure procurement. |
Research Methodology
A spread of perspectives from defense procurement officers, sensor hardware engineering directors, prime contractor program managers, and military research lab technology evaluators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against US DoD budget justification documents, NATO STANAG technical specifications, EU European Defence Fund tender announcements, and SEC 10-K filings from listed defense primes. Bottom-up segment sizing triangulated against top-down defense expenditure allocation models.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled across platform mounting configuration, cooling technology tier, spectral band application, and end-user procurement authority level. CAGRs were derived from program budget trajectory analysis and platform modernization cycle timing. Forecast inputs incorporated US Army ground combat vehicle retrofit schedules, EU F-Gas Regulation implementation timelines, and indium antimonide foundry capacity expansion announcements.
Stress conditions across gallium arsenide foundry output constraints, ITAR classification threshold adjustments, and helium-3 cryogenic gas supply volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about defense procurement continuity and interoperability mandate adherence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Defense Geospatial Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Military Radar Systems Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
UXO Detection Market