
 EO/IR Gimbal Market | 2026-2036
EO/IR Gimbal Market Size, Share, and Industry Trends Forecast 2026-2036
EO/IR Gimbal Market Intelligence
The US National Defense Authorization Act is recalibrating the cost-of-entry calculus for foreign gimbal suppliers seeking Pentagon contracts. Teledyne FLIR leverages its vertically integrated infrared detector fabrication to sustain price competitiveness against European rivals. Lockheed Martin Corporation anchors its gimbal portfolio around classified aerial platforms where security clearance requirements create natural moats. Raytheon Technologies differentiates through captive gallium arsenide foundry capacity for cooled infrared sensors.
An EO/IR gimbal is a motorized stabilization platform housing electro-optical and infrared sensors, typically achieving pointing accuracies below 50 microradians while compensating for aircraft vibration and wind gusts through inertial measurement units and closed-loop servo motors. Its primary purpose is delivering persistent surveillance, target tracking, and intelligence collection across defense, homeland security, and commercial inspection missions. Infrared gimbals command the largest revenue share due to military night-operation mandates, while dual-use gimbals represent the fastest-expanding category as law enforcement agencies adopt military-derived thermal imaging for search operations. The aerial surveillance application segment concentrates the highest margin pools, since fixed-wing and rotary-wing drone programs specify extended-range optics with embedded laser designators.
The US Federal Aviation Administration and the European Union Aviation Safety Agency impose conflicting airworthiness certification paths for gimbal-equipped unmanned systems, fragmenting product development roadmaps for multinational suppliers. The International Traffic in Arms Regulations and EU Green Deal dual-use export controls further complicate cross-border component flows for cooled infrared cores. Stakeholders must monitor how divergent military-civil certification timelines reshape platform integration priorities and supplier qualification cycles.
Market Dynamics
Defense procurement agencies are consolidating sensor payload specifications around modular open-architecture standards, forcing gimbal suppliers to re-engineer proprietary interfaces into interoperable form factors compatible with NATO STANAG protocols.
Growth Catalysts
- ITAR modernization:The US State Department's revised Category VIII controls are streamlining licensing timelines for uncooled infrared cores destined for allied unmanned platforms.
- Border surveillance infrastructure:European coast guard agencies are deploying persistent aerial monitoring networks requiring stabilized long-range optics across the Mediterranean corridor.
- Synthetic aperture radar fusion:Multi-sensor payloads combining EO/IR gimbals with SAR modules are penetrating maritime patrol aircraft retrofit programs.
Market Restraints
- Germanium lens supply:Chinese export licensing for optical-grade germanium concentrates 70% of raw material refining in a single jurisdiction.
- Dual-use export friction:EU Green Deal due diligence requirements are extending component qualification cycles for cooled detector arrays.
- Stabilization performance ceiling:Mechanical gyroscope-based platforms face displacement by fiber-optic inertial units in high-vibration rotary-wing applications.
Strategic Opportunities
- Urban air mobility inspection:Commercial drone operators in Singapore are adopting military-derived thermal gimbals for building envelope surveys.
- CE marking harmonization:The EU AI Act's risk-classification framework is creating a regulatory on-ramp for autonomous tracking algorithms in security applications.
- Hyperspectral convergence:Integration of SWIR detectors with traditional MWIR channels is opening precision agriculture analytics contracts.
Industry Challenges
- Embedded software certification:DO-178C compliance for airborne gimbal control systems requires specialized avionics engineering talent pools concentrated in Toulouse and Wichita.
- Supply chain reconfiguration:Gallium arsenide foundry capacity constraints are forcing redesigns around alternative substrate materials.
- Platform integration complexity:Legacy manned aircraft bus architectures lack bandwidth for high-definition video streams from modern multi-spectral payloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EO/IR Gimbal Market |
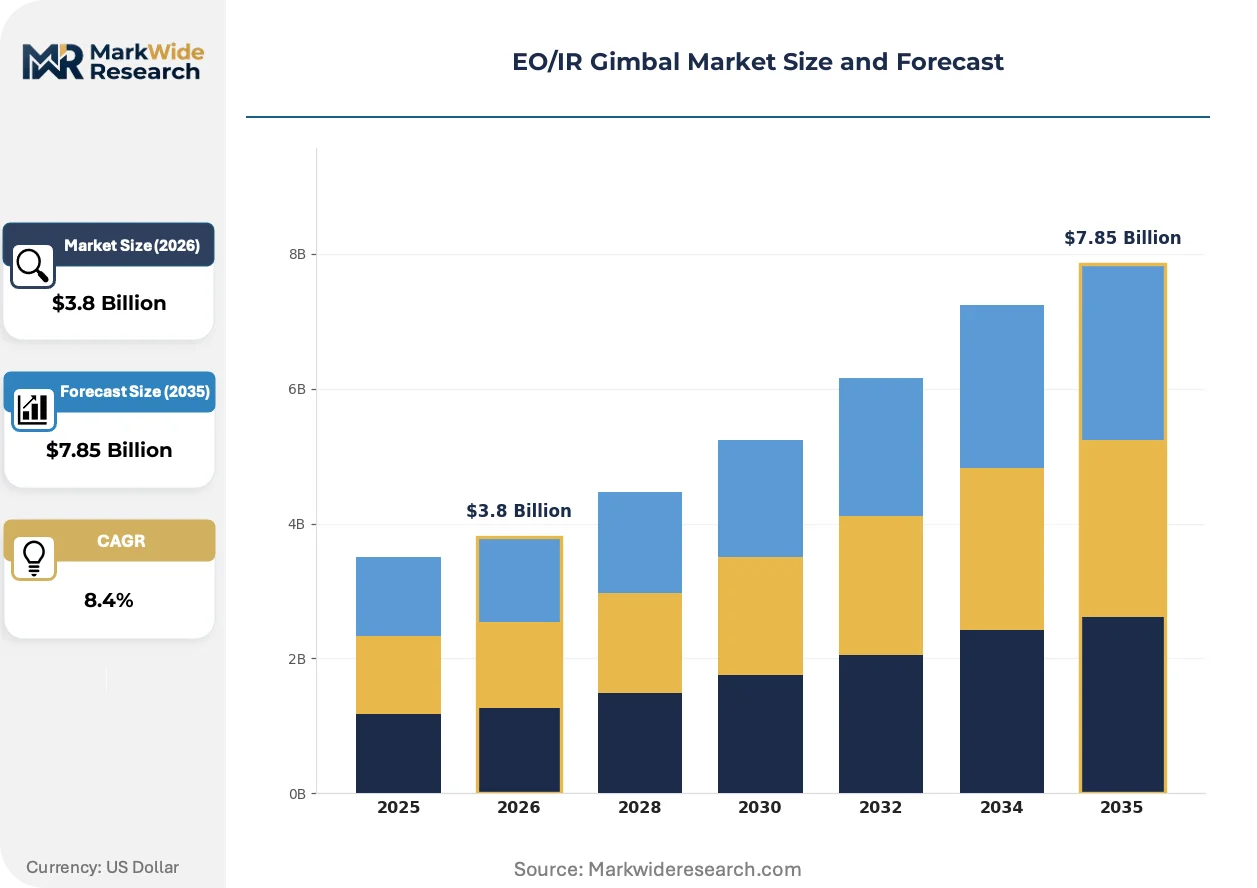
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Gimbals, Electro-Optical Gimbals, Dual-Use Gimbals, Stabilized Gimbals Technology: Active Cooling, Passive Cooling, Digital Signal Processing, Optical Zoom Application: Aerial Surveillance, Ground Surveillance, Search & Rescue, Border Patrol End User: Military, Law Enforcement, Search & Rescue Organizations, Commercial Operators |
| Companies Covered | Teledyne FLIR, Raytheon Technologies, Lockheed Martin Corporation, CONTROP Precision Technologies, AeroVironment, L3Harris Technologies, Leonardo DRS, Thales Group, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EO/IR Gimbal Market Strategic Shifts & Innovations
Computational imaging algorithms are compressing hardware requirements for target identification, allowing lighter payloads on smaller unmanned platforms while maintaining detection ranges previously requiring 15-inch stabilized turrets.
Silicon carbide (SiC) power electronics are integrating into gimbal motor drives, cutting thermal dissipation by 40% compared to silicon IGBTs. Naval aviation programs are adopting SiC-based servo amplifiers for carrier-deck environments. This transition is integrating advanced wide-bandgap semiconductors into platforms where size and cooling constraints previously limited performance.
REACH Annex XIV restrictions on lead-based solders are compelling redesigns of detector dewar assemblies for European defense contractors. The European Chemicals Agency's sunset dates for traditional interconnect materials are accelerating qualification of alternative metallurgy in Stuttgart and Munich manufacturing clusters. Cooled infrared gimbals destined for EU member state procurement face the tightest compliance deadlines.
Defense agencies are unbundling sensor hardware from integrated platform contracts, creating direct procurement relationships with gimbal specialists. The US Army's Future Tactical Unmanned Aircraft System program exemplifies this disaggregation, with separate vendor selection for airframes and payloads. This pattern is most pronounced in NATO member states pursuing sovereign industrial base preservation.
EO/IR Gimbal Market Segmentation
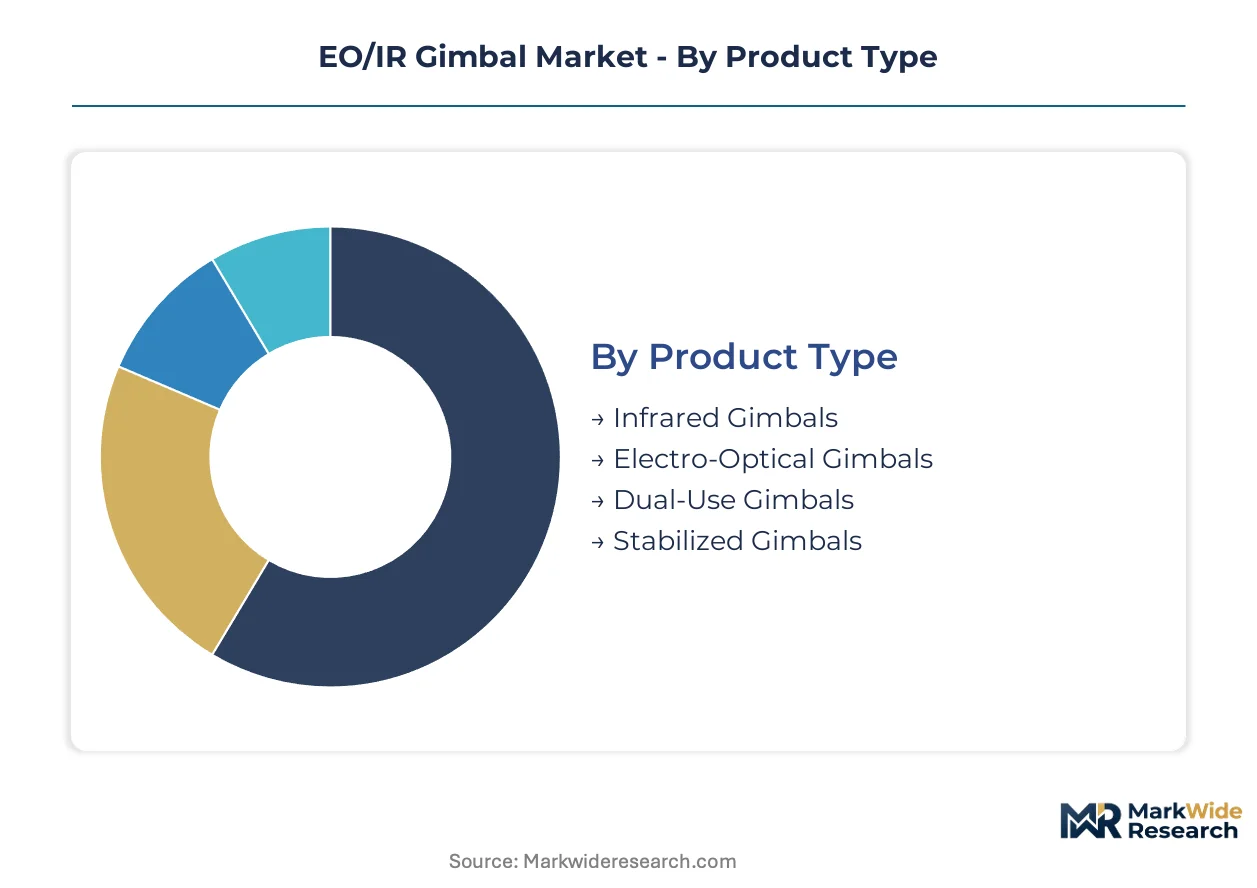
EO/IR gimbal procurement decisions hinge on mission endurance requirements, environmental operating conditions, and platform integration constraints. Defense agencies segment purchases across cooling architectures, stabilization performance tiers, and sensor fusion capabilities to match specific operational profiles.
Product Type:
Military procurement agencies prioritize thermal detection range and all-weather reliability when selecting gimbal product categories for unmanned platforms.
- Infrared Gimbals:These systems house cooled or uncooled thermal detector arrays, typically achieving detection ranges exceeding 10 kilometers against vehicle-sized targets in total darkness. NATO member states concentrate orders here due to night-operation mandates for drone fleets. German and Turkish defense ministries specify MWIR-cooled configurations for maritime patrol applications.
- Dual-Use Gimbals: Military-derived thermal imaging packages adapted for law enforcement and commercial inspection represent the category climbing fastest. Singaporean building surveyors and European coast guard agencies drive adoption of these exportable configurations with simplified ITAR classifications.
- Electro-Optical Gimbals: Visible-spectrum systems dominate daylight reconnaissance missions where color identification matters. Israeli border surveillance programs specify these for daytime corridor monitoring.
- Stabilized Gimbals: Mechanical isolation platforms achieve sub-50 microradian pointing accuracy through fiber-optic gyroscope feedback. US Navy carrier aviation programs require these for high-vibration rotary-wing environments.
Infrared gimbals lead on scale; dual-use gimbals lead on momentum.
Technology:
Cooling architecture selection directly determines detector sensitivity, power consumption, and export control classification for cross-border sales.
- Active Cooling:Stirling-cycle dewars maintain detector temperatures near 77 Kelvin, enabling long-range target identification through atmospheric obscurants. US ITAR Category VIII restrictions apply to these cooled cores, limiting supplier pools for allied procurement.
- Digital Signal Processing: Real-time image enhancement algorithms compress hardware requirements for smaller unmanned platforms. Computational imaging advances here allow lighter payloads to match previous 15-inch turret detection ranges.
- Passive Cooling: Uncooled microbolometer arrays eliminate mechanical coolers, reducing power draw and maintenance intervals. European defense contractors favor these for short-range tactical drones where SWAP-C constraints dominate.
- Optical Zoom: Continuous magnification systems from 10x to 30x enable positive identification at extended standoff distances. Maritime patrol aircraft retrofits specify these for littoral surveillance missions.
Active cooling dominates military specification sheets; digital signal processing gains share fastest.
Application:
Operational environment dictates stabilization performance requirements, sensor payload mass budgets, and integration complexity with host platforms.
- Aerial Surveillance:Fixed-wing and rotary-wing drone programs specify extended-range optics with embedded laser designators here. This application concentrates the highest margin pools due to military-grade performance thresholds.
- Border Patrol: Persistent monitoring networks across the Mediterranean corridor require stabilized long-range optics for coast guard agencies. European procurement is accelerating for these land and maritime boundary applications.
- Ground Surveillance: Tripod-mounted and vehicle-integrated systems prioritize rapid deployment over extreme range. Law enforcement agencies specify these for perimeter security and event monitoring.
- Search & Rescue: Thermal detection of human heat signatures in wilderness and urban collapse scenarios drives adoption. Military-derived gimbals penetrate this segment as equipment transfers to civilian emergency response units.
Aerial surveillance leads on scale; border patrol leads on momentum.
End User:
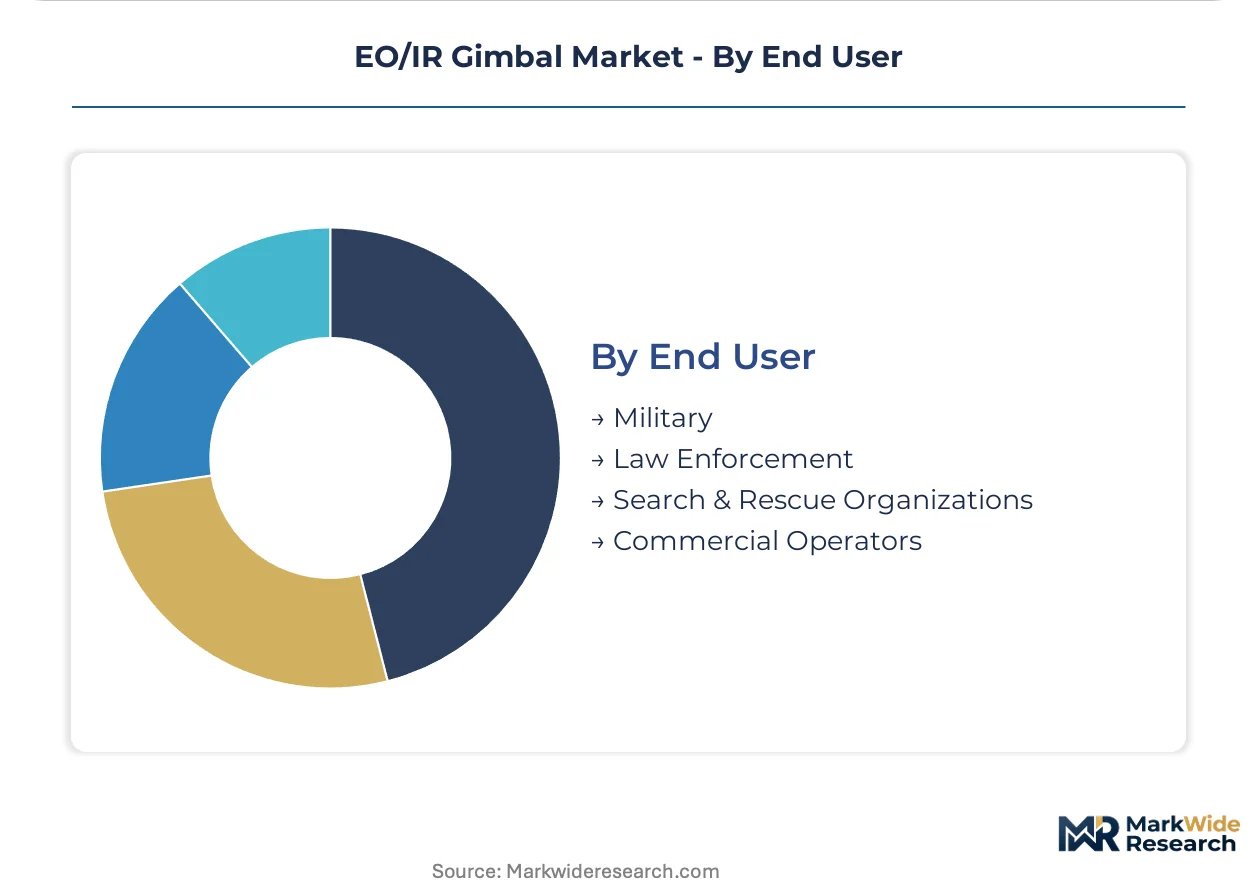
Budget cycles, security clearance requirements, and regulatory compliance obligations segment buyer behavior across institutional categories.
- Military:Classified platform integrations and NATO STANAG protocol compliance dominate procurement specifications. The US Army's Future Tactical Unmanned Aircraft System program disaggregates airframe and payload vendor selection.
- Law Enforcement: Agencies adopt military-derived thermal imaging for search operations and tactical response. Budget constraints favor dual-use gimbals with simplified export classifications.
- Commercial Operators: Infrastructure inspection and precision agriculture drive demand for SWIR-enhanced multi-spectral payloads. Singaporean building envelope surveys exemplify this emerging adoption pattern.
- Search & Rescue Organizations: Non-governmental and governmental emergency response units prioritize portability and rapid deployment over maximum range. Civil aviation certification requirements apply differently here than for military procurement.
Military end users lead on scale; commercial operators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized avionics engineering talent pools concentrate in Toulouse, Wichita, and Stuttgart, anchoring gimbal control system development clusters. These workforce concentrations shape regional competitive advantages across certification, manufacturing, and platform integration capabilities.
United States
The US Army's Future Tactical Unmanned Aircraft System program and Pentagon sensor payload standardization drive procurement volume. FAA airworthiness certification paths for gimbal-equipped unmanned systems create regulatory complexity for domestic suppliers. Greater Wichita's aviation manufacturing cluster hosts servo motor and inertial measurement unit production for military-grade stabilization platforms.
Israel
Border surveillance programs and classified aerial platform integrations sustain demand for visible-spectrum daylight reconnaissance systems. The country's national defense procurement agency maintains close integration between domestic gimbal manufacturers and national drone programs. Tel Aviv's defense technology corridor concentrates electro-optical engineering talent for stabilized turret development.
Turkey
Domestic unmanned aerial vehicle programs and maritime patrol applications generate orders for MWIR-cooled configurations. The national defense ministry's sovereign industrial base preservation policies favor local gimbal suppliers. Ankara's aerospace manufacturing cluster hosts production lines for tactical drone payload integration.
Germany
European coast guard agencies deploy persistent aerial monitoring networks requiring stabilized long-range optics across Mediterranean corridors. REACH Annex XIV restrictions on lead-based solders compel redesigns of detector dewar assemblies for defense contractors. Stuttgart and Munich manufacturing clusters accelerate qualification of alternative metallurgy for cooled infrared gimbals destined for EU member state procurement.
Singapore
Commercial drone operators adopt military-derived thermal gimbals for building envelope surveys and infrastructure inspection missions. The Civil Aviation Authority of Singapore's unmanned systems regulations create a compliance pathway for dual-use payload certification. The city-state's precision engineering hub supports sensor fusion integration for urban air mobility applications.
EO/IR Gimbal Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the EO/IR gimbal supply base. The market structure tilts toward consolidation among vertically integrated defense contractors possessing captive infrared detector fabrication. Three archetypes dominate: prime contractors with classified platform access, component specialists with STANAG protocol expertise, and dual-use suppliers leveraging simplified export classifications. Competitive moves center on modular open-architecture re-engineering and gallium arsenide foundry capacity expansion.
Among US-based defense primes, Teledyne FLIR, Raytheon Technologies, and Lockheed Martin Corporation occupy positions spanning the infrared detector, cooled sensor, and classified platform integration vectors. These entities exemplify the vertically integrated archetype through in-house production of critical detector substrates and captive supply of stabilization electronics. CONTROP Precision Technologies represents the specialist tier with focused expertise in precision stabilization and NATO interoperability standards.
| Leading Market Players |
|---|
| Teledyne FLIR |
| Raytheon Technologies |
| Lockheed Martin Corporation |
| CONTROP Precision Technologies |
| AeroVironment |
| L3Harris Technologies |
| Leonardo DRS |
| Thales Group |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
NATO military procurement agencies concentrate purchasing power through consolidated sensor payload contracts, anchoring pricing around modular open-architecture compliance rather than standalone unit costs. This buyer concentration rewards suppliers with captive infrared detector fabrication and STANAG protocol expertise, while marginalizing pure-play assemblers lacking backward integration into cooled core production.
Pricing Analysis
Bundled platform-payload contracts are unbundling into separate airframe and gimbal vendor selections, compressing margins on integrated systems while elevating pricing power for discrete payload specialists. Three-tier pricing structure across ITAR-restricted, NATO-exportable, and commercial-grade configurations differentiates offerings, with certification grade and captive foundry capacity as primary price drivers. Cost compression in uncooled microbolometer segments is intensifying because European defense contractors are qualifying alternative metallurgy for REACH compliance. Law enforcement agencies exhibit highest price sensitivity due to budget constraints, while classified military programs show lowest sensitivity given security clearance requirements.
Supply Chain Analysis
Refurbishment flows for Stirling-cycle dewar assemblies and fiber-optic gyroscope units are concentrating in Stuttgart and Wichita maintenance clusters, extending component lifecycles and reshaping spare parts demand. Optical-grade germanium refining concentrates in China, while gallium arsenide foundry capacity centers on US and Israeli defense contractors. The supply chain rests on germanium lens supply, gallium arsenide substrates, and silicon carbide power electronics as critical inputs. Single-source vulnerability in Chinese export licensing for optical-grade germanium creates structural supply risk. Distribution runs through prime contractor integration contracts and direct procurement relationships with gimbal specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on silicon carbide power electronics integration cutting thermal dissipation costs, alongside premium-tier demand for MWIR-cooled configurations in maritime patrol applications.
For Market Incumbents: Acquire gallium arsenide foundry capacity or Stirling-cycle cooler assembly lines to secure supply chain control against Chinese germanium export licensing volatility. Lockheed Martin Corporation and Raytheon Technologies exemplify this defensive posture through captive detector fabrication. Incumbents should simultaneously re-engineer proprietary interfaces into NATO STANAG-compatible form factors to defend against modular open-architecture mandates disaggregating platform and payload contracts. For New Entrants and Emerging Players: Capture commercial operator segments in Singapore and European coast guard agencies where dual-use export classifications simplify market entry. Urban air mobility inspection and precision agriculture analytics represent the most penetrable white-space applications, with SWIR-enhanced multi-spectral payloads as the specific go-to-market angle. New entrants should leverage CE marking harmonization under the EU AI Act's risk-classification framework to accelerate autonomous tracking algorithm certification. For Investors and Strategic Acquirers: Defense primes with classified platform access are the most active acquirers in this space, seeking STANAG protocol expertise and precision stabilization capabilities. Long-term viability over the coming decade favors vertically integrated specialists with in-house infrared detector production and NATO interoperability credentials. The signal to watch is ITAR modernization timelines for uncooled core licensing, which would expand addressable markets for allied procurement and trigger valuation inflection for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Arsenide Foundry Expansion | Captive substrate production insulates against supply chain reconfiguration forcing alternative material redesigns. |
| Modular Open-Architecture Re-engineering | NATO STANAG compliance preserves prime contractor access to disaggregated Future Tactical Unmanned Aircraft System procurement. |
| Silicon Carbide Power Electronics Integration | Wide-bandgap semiconductors cut thermal dissipation by 40% in carrier-deck naval aviation environments. |
| REACH-Compliant Metallurgy Qualification | Alternative interconnect materials in Stuttgart and Munich clusters secure EU defense contractor market access. |
| Dual-Use Payload Certification Pathway | Simplified ITAR classifications for exportable configurations penetrate Singaporean commercial drone inspection markets. |
Research Approach
Direct dialogue with defense procurement officers, gimbal control system engineers, electro-optical engineering directors, and avionics certification specialists grounded qualitative insights. Secondary validation drew from US State Department ITAR filings, EU Green Deal due diligence disclosures, FAA airworthiness certification databases, and NATO STANAG protocol documentation. Bottom-up and top-down triangulation cross-checked component-level production estimates against consolidated platform procurement disclosures.
Bottom-up modeling segmented volume and value across cooling architecture, stabilization performance tier, sensor fusion capability, and platform integration complexity. CAGRs were derived from weighted regression across military procurement cycles, export control liberalization scenarios, and commercial drone adoption curves. Industry-specific forecast inputs included synthetic aperture radar fusion penetration in maritime patrol retrofits and computational imaging algorithm deployment in tactical unmanned platforms.
Underlying measurement precision varies by segment; classified military integrations carry tighter precision than commercial operator estimates due to disclosure constraints. Forecasts reflect assumptions around ITAR modernization timelines, REACH Annex XIV compliance deadlines, and FAA-EASA certification harmonization progress. Practitioners should monitor Chinese export licensing shifts for optical-grade germanium and EU AI Act implementation guidance for autonomous tracking algorithms as early revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Military Jammer Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Military Radar Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Airborne Target Acquisition Systems Market