
 Air-Based Military Electro-Optical and Infrared Systems Market | 2026-2036
Air-Based Military Electro-Optical and Infrared Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Based Military Electro-Optical and Infrared Systems Market Outlook
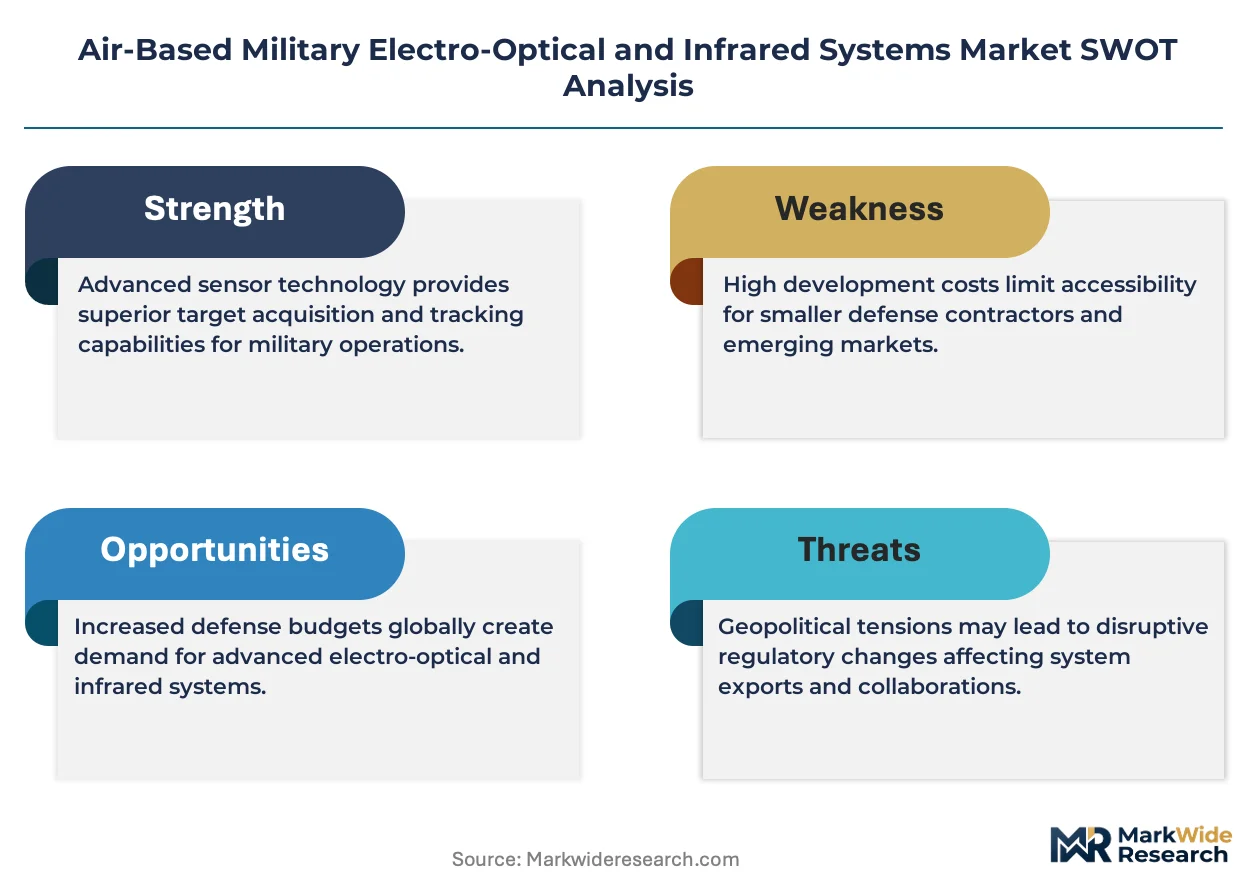
REACH compliance on restricted substances in optical coatings is pivoting supplier qualification timelines for European defense primes. Lockheed Martin leverages captive semiconductor foundries to sustain supply security for focal plane arrays. Raytheon Technologies anchors its position through classified programs that integrate multi-band seekers with fire control systems. L3Harris Technologies differentiates via modular payload architectures that swap sensor packages across fixed-wing and rotary-wing platforms.
Air-based military electro-optical and infrared systems comprise stabilized gimbal-mounted sensor suites operating across visible, short-wave, mid-wave, and long-wave infrared spectra, typically cooled to 77 Kelvin via Stirling engines for thermal sensitivity below 25 millikelvin noise-equivalent temperature difference. These systems enable passive detection, tracking, and targeting of ground and aerial objects under day, night, and degraded-weather conditions for manned and unmanned combat aircraft. Imaging systems dominate installed base value due to platform retrofit cycles, while targeting systems represent the fastest-growing product category as precision-strike requirements expand beyond traditional fighter missions. LWIR technology leads volume shipments for airborne surveillance applications, though SWIR adoption accelerates for atmospheric-penetration missions where moisture obscuration degrades MWIR performance.
The US FAA coordinates airworthiness certification for military derivative aircraft carrying EO/IR payloads, while the EPA regulates hazardous material disposal from cooled detector dewars. EMA and REACH shape European procurement by restricting cadmium and mercury in detector materials, compelling manufacturers to qualify alternative substrate technologies. Stakeholders must monitor how ITAR reform discussions affect cross-border sensor component flows between Five Eyes partners and NATO allies.
Market Dynamics
Multi-spectral sensor fusion architectures are compressing procurement cycles for NATO air forces, forcing primes to requalify single-payload designs that previously separated SWIR, MWIR, and LWIR channels across discrete units.
Growth Catalysts
- Contested-environment survivability mandates:The US Department of Defense's hardened requirements for fighter and ISR platforms are accelerating electro-optical upgrades across legacy fleets.
- REACH substance restrictions:ECHA regulations on cadmium and mercury in detector materials are pivoting supplier qualification timelines toward alternative substrate technologies.
- Unmanned platform proliferation:NATO military UAV programs are driving stabilized multi-spectral turret demand for persistent surveillance missions.
Market Restraints
- Mercury cadmium telluride supply concentration:Focal plane array substrate production clusters among a handful of specialized foundries, creating single-source vulnerability for cooled LWIR detectors.
- ITAR cross-border friction:US export controls on sensor components restrict component flows to Five Eyes partners and NATO allies, elongating procurement timelines.
- Stirling cooler maintenance burden:Cryogenic cooling systems operating at 77 Kelvin require specialized logistics support, constraining deployment flexibility for expeditionary forces.
Strategic Opportunities
- SWIR atmospheric penetration missions:Moisture-obscured environments where MWIR performance degrades present untapped demand for short-wave infrared adoption in maritime patrol applications.
- Modular payload architectures:Rotary-wing and fixed-wing platform interchangeability enables sensor package swapping across diverse mission profiles without airframe modification.
- EPA hazardous material disposal protocols:Cooled detector dewar end-of-life regulations are creating aftermarket service revenue streams for certified refurbishment operations.
Industry Challenges
- Cryogenic engineering talent scarcity:Stirling engine design and 25 millikelvin NETD optimization require specialized thermal management expertise concentrated among aging workforce cohorts.
- FAA airworthiness certification complexity:Military derivative aircraft carrying EO/IR payloads face elongated validation timelines for software-intensive sensor fusion systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Based Military Electro-Optical and Infrared Systems Market |
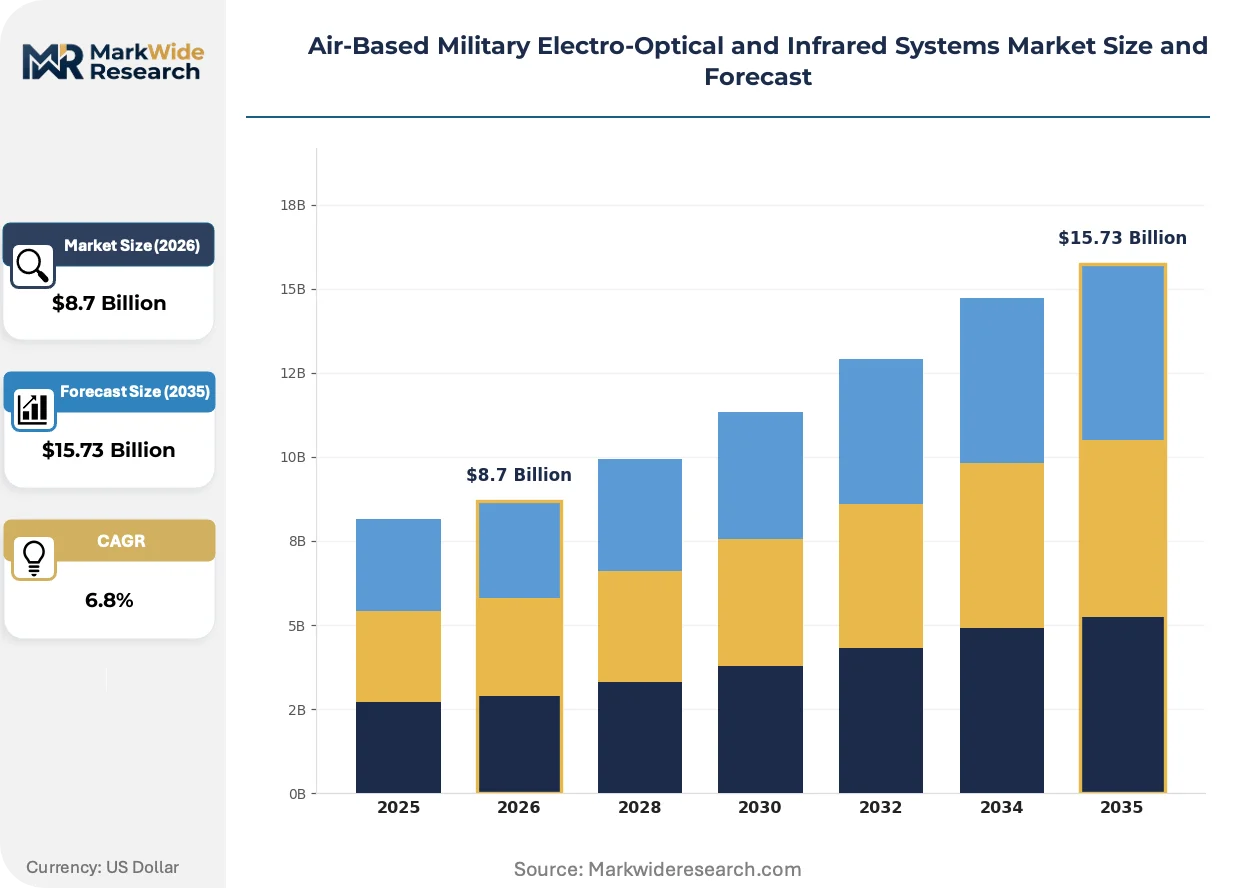
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Targeting Systems, Sensors, Cameras Application: Surveillance, Reconnaissance, Target Acquisition, Fire Control End User: Military Forces, Defense Contractors, Government Agencies, Security Organizations Technology: SWIR, MWIR, LWIR, Visible Light |
| Companies Covered | Lockheed Martin Corporation, Raytheon Technologies Corporation, L3Harris Technologies, Northrop Grumman Corporation, BAE Systems plc, Teledyne FLIR, Leonardo S.p.A., Thales Group, Elbit Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Based Military Electro-Optical and Infrared Systems Market Strategic Shifts
Sensor miniaturization and algorithmic image processing are collapsing the traditional boundary between imaging and targeting system categories, enabling single payloads to serve multiple mission phases without hardware reconfiguration.
Uncooled microbolometer arrays are overtaking cooled detectors for certain airborne surveillance applications where thermal sensitivity requirements have relaxed. Maritime patrol operators are adopting these sensors for persistent wide-area coverage missions. The technology is overtaking legacy Stirling-cooled architectures in cost-constrained procurement environments while compressing sustainment logistics.
EMA and REACH substance restrictions are compelling European defense primes to requalify optical coating suppliers ahead of cadmium and mercury phase-out deadlines. Alternative substrate technologies including indium gallium arsenide and type-II superlattices are gaining traction in focal plane array production. German and French procurement offices are accelerating qualification timelines to maintain supply security.
Defense agencies are consolidating sensor procurement under platform-centric acquisition models rather than discrete subsystem competitions. Prime contractors are absorbing tier-two payload specialists to capture integrated airframe-sensor contracts. The United Kingdom and Australia demonstrate this pattern most visibly through their respective maritime patrol and fighter modernization programs.
Air-Based Military Electro-Optical and Infrared Systems Market Segmentation
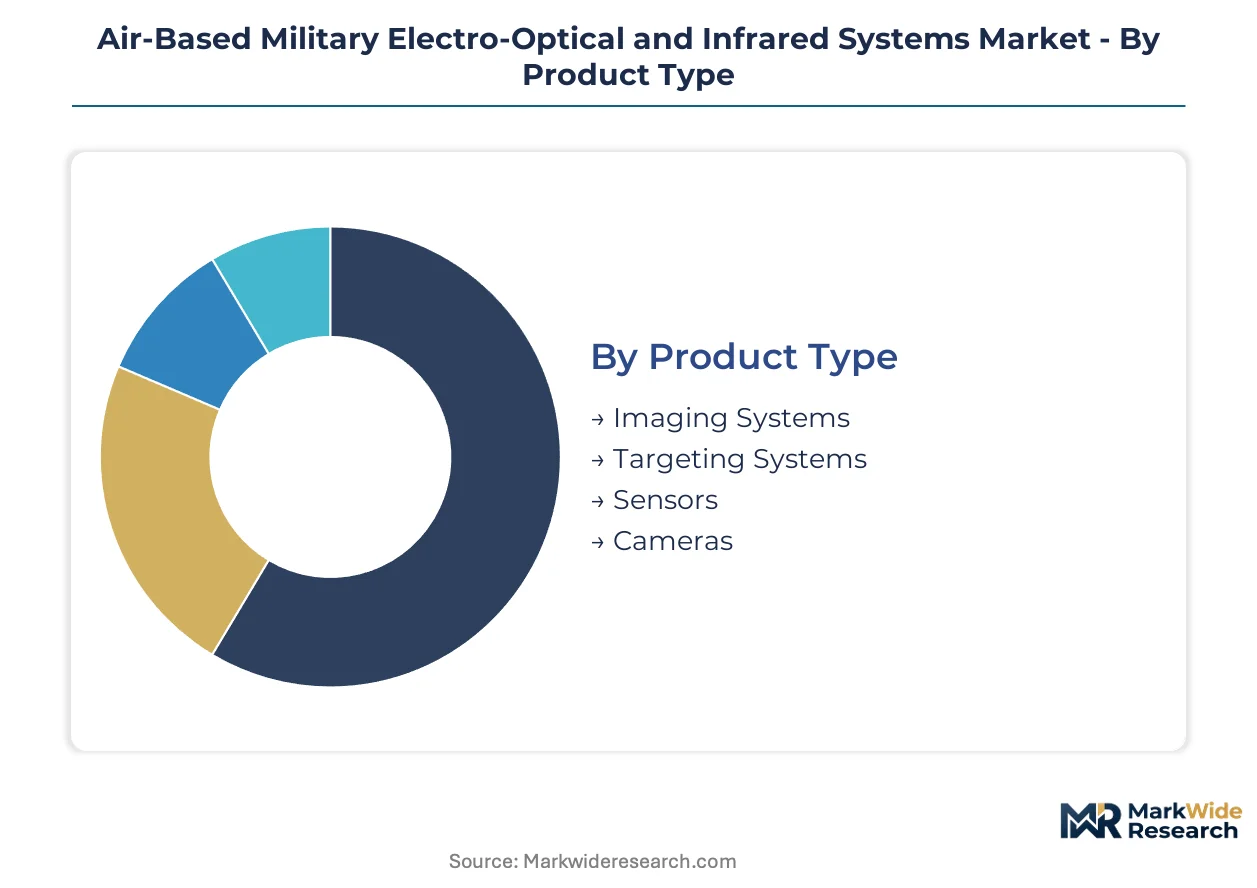
Segmentation in air-based military EO/IR systems reveals how procurement priorities diverge across mission profiles and thermal sensitivity requirements. Platform operators select payload configurations based on atmospheric conditions, target signatures, and sustainment logistics rather than unit cost alone.
Product Type:
Defense buyers differentiate primarily by mission phase integration—whether systems must support passive observation only or active targeting engagement.
- Imaging Systems:Stabilized gimbal-mounted sensor suites capturing visible through LWIR spectra for situational awareness and route reconnaissance. Demand concentrates in US Air Force fighter retrofit programs where legacy pods require electro-optical upgrades without airframe modification.
- Targeting Systems:Multi-spectral fire control payloads combining SWIR, MWIR, and LWIR channels with laser designation capability for precision strike. NATO unmanned platform programs are accelerating procurement as contested-environment survivability mandates compress single-payload qualification timelines.
- Sensors:Discrete detector assemblies and focal plane arrays supplying tier-two integrators.
- Cameras:Visible-spectrum recording devices for training and post-mission analysis.
Volume sits with Imaging Systems; growth tilts toward Targeting Systems.
Application:
Mission duration and rules of engagement determine whether operators prioritize wide-area persistence or rapid target handoff.
- Surveillance:Persistent wide-area coverage missions using LWIR for thermal detection of ground vehicles and personnel signatures. Maritime patrol operators in the United Kingdom and Australia favor uncooled microbolometer architectures for reduced logistics burden during extended sorties.
- Reconnaissance:Route and area survey missions requiring high-resolution imagery for intelligence exploitation. US Navy carrier aviation programs dominate demand as electromagnetic spectrum management constraints drive passive sensor adoption.
- Target Acquisition:Detection and classification of priority objects for engagement authorization.
- Fire Control:Real-time tracking and laser designation for weapon release.
Surveillance commands installed base value; Reconnaissance shows steepest expansion trajectory as electromagnetic signature control gains priority.
End User:
Budget authority and platform ownership structure create distinct procurement rhythms and certification requirements.
- Military Forces:Uniformed services operating manned and unmanned combat aircraft with organic maintenance capability. US Air Force and Navy modernization timelines prioritize electro-optical upgrades for fighter and ISR platforms under contested-environment survivability mandates.
- Defense Contractors:Prime integrators absorbing tier-two payload specialists to capture platform-centric contracts. The United Kingdom's maritime patrol program and Australia's fighter modernization demonstrate this consolidation pattern.
- Government Agencies:Civilian defense research organizations and test ranges.
- Security Organizations:Border patrol and coast guard services with airborne surveillance missions.
Military Forces anchor procurement volume; Defense Contractors are gaining share fastest through vertical absorption of payload specialists.
Technology:
Thermal sensitivity thresholds and atmospheric transmission windows dictate channel selection for specific altitude and humidity conditions.
- LWIR:Long-wave infrared systems cooled to 77 Kelvin via Stirling engines, achieving noise-equivalent temperature difference below 25 millikelvin. Airborne surveillance applications lead volume shipments due to established supply chains for mercury cadmium telluride focal plane arrays.
- SWIR:Short-wave infrared exploiting atmospheric transmission windows where moisture obscuration degrades MWIR performance. Maritime patrol missions in high-humidity environments are accelerating adoption as ECHA REACH restrictions pivot supplier qualification toward indium gallium arsenide substrates.
- MWIR:Mid-wave infrared for clear-weather targeting and seeker applications.
- Visible Light:Daylight-only imaging for training and non-combat identification.
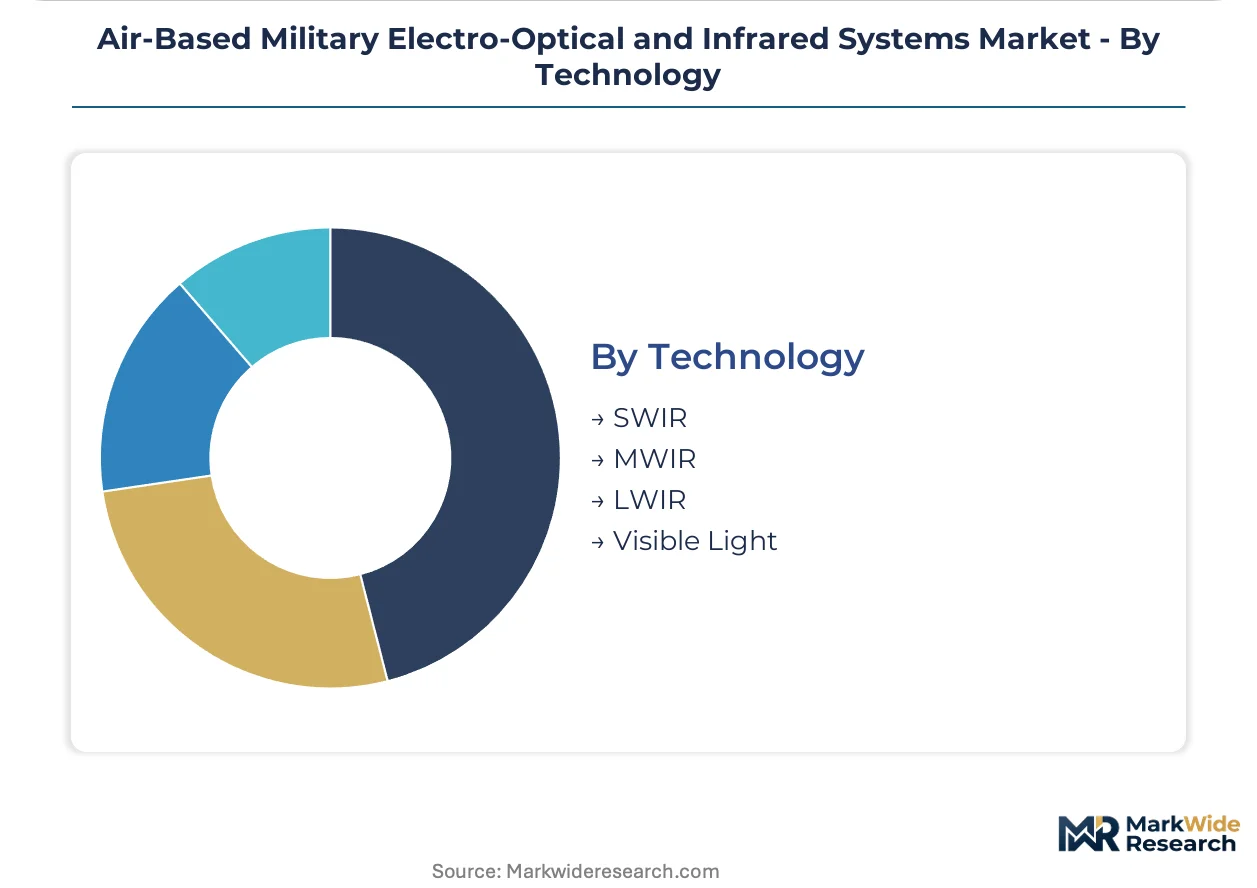
LWIR dominates current shipments; SWIR climbs the fastest as atmospheric penetration requirements expand beyond traditional fighter missions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement concentrates over half of worldwide military EO/IR system demand through Air Force and Navy modernization programs. Fighter retrofit cycles and unmanned platform proliferation drive sustained procurement velocity. Contested-environment survivability mandates from the Department of Defense reshape supplier qualification timelines.
United States
Fighter and ISR platform modernization dominates procurement volume under contested-environment survivability mandates. The FAA coordinates airworthiness certification for military derivative aircraft carrying EO/IR payloads. Arizona and Florida host concentrated prime contractor integration facilities where sensor fusion architectures undergo qualification.
United Kingdom
Maritime patrol programs accelerate demand for stabilized multi-spectral turrets on airborne surveillance platforms. Ministry of Defence procurement aligns with EMA and REACH substance restrictions on optical coatings. Scotland and Southwest England cluster payload integration specialists supporting RAF modernization.
Germany
ECHA REACH regulations on cadmium and mercury pivot supplier qualification timelines toward alternative detector substrates. The national aerospace regulator enforces environmental compliance on cooled detector dewar disposal. Bavaria and Baden-Württemberg concentrate focal plane array foundries qualifying indium gallium arsenide technologies.
Israel
Precision-strike requirements expand procurement of multi-band seekers integrated with fire control systems. The national defense establishment prioritizes indigenous sensor production under technology security protocols. Central Israel hosts specialized semiconductor foundries sustaining focal plane array supply security.
Australia
Fighter modernization programs demonstrate platform-centric acquisition models absorbing tier-two payload specialists. The TGA framework influences hazardous material handling protocols for cooled detector maintenance. Victoria and New South Wales cluster systems integrators supporting Royal Australian Air Force electro-optical upgrades.
Air-Based Military Electro-Optical and Infrared Systems Market Competitive Environment
United States producers anchor the prime contractor tier; European specialists hold payload integration and component supply positions. The vendor base concentrates among five major defense primes controlling platform-centric contracts, with tier-two sensor specialists facing absorption pressure. Two strategic archetypes dominate: vertically integrated primes with captive semiconductor foundries, and modular payload architects enabling rotary-wing and fixed-wing interchangeability. Competitive moves center on prime contractor absorption of tier-two specialists and qualification of alternative substrate technologies under REACH deadlines.
Within the vertically integrated tier, Lockheed Martin Corporation and Raytheon Technologies Corporation exemplify prime contractors sustaining supply security through in-house focal plane array production. L3Harris Technologies occupies a position among modular payload architects enabling sensor package swapping across diverse mission profiles. These three entities represent the competitive core where platform-centric procurement models concentrate contract authority.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| L3Harris Technologies |
| Northrop Grumman Corporation |
| BAE Systems plc |
| Teledyne FLIR |
| Leonardo S.p.A. |
| Thales Group |
| Elbit Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Contested-environment survivability mandates from the US Department of Defense are compressing qualification timelines for multi-spectral sensor fusion architectures, forcing suppliers to absorb upfront R&D costs while buyers consolidate procurement under platform-centric contracts. This demand-side pressure concentrates pricing power among prime contractors with captive focal plane array foundries, while tier-two specialists face margin compression from requalification burdens.
Pricing Analysis
Volume concentrates in legacy imaging system retrofits where unit economics favor standardized configurations, while margins expand in targeting system integrations requiring customized sensor fusion. Three-tier pricing structure across mission-certified, standard military, and commercial-off-the-shelf levels reflects differentiation by thermal sensitivity grade and airworthiness certification tier. Cost compression in commercial-off-the-shelf tiers is intensifying because uncooled microbolometer alternatives displace Stirling-cooled architectures in surveillance applications. Defense contractors show lowest price sensitivity due to platform-centric budget authority, while security organizations face procurement constraints.
Supply Chain Analysis
Dual-sourcing requirements for mercury cadmium telluride focal plane arrays are pivoting buyer qualification strategies toward alternative substrate technologies as REACH deadlines approach. Production clusters in the United States, Germany, and Israel anchor supply for cooled detector materials, while indium gallium arsenide sourcing draws from specialized foundries in France and the United Kingdom. Supply chain risk centers on single-source vulnerability for Stirling engine cryocoolers requiring specialized thermal management expertise. Distribution runs through prime contractor integration facilities in Arizona, Florida, and Bavaria before military platform assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mercury cadmium telluride foundry capacity constraints prop pricing power for vertically integrated primes, as REACH substance restrictions eliminate alternative supplier pathways faster than qualification timelines permit.
For Market Incumbents: Anticipate accelerated absorption of tier-two payload specialists as platform-centric procurement models consolidate contract authority under fighter and maritime patrol modernization programs. Lockheed Martin and Raytheon Technologies exemplify defensive positioning through captive semiconductor production securing focal plane array supply. Incumbents should prioritize backward integration into indium gallium arsenide substrate technologies ahead of European cadmium phase-out deadlines. For New Entrants and Emerging Players: The premium-to-economy pricing gap in maritime patrol applications creates entry opportunity for uncooled microbolometer architectures displacing legacy Stirling-cooled systems. White-space targets concentrate in SWIR atmospheric penetration missions for high-humidity environments where MWIR performance degrades. New entrants should pursue modular payload architectures enabling rotary-wing and fixed-wing interchangeability without airframe modification. For Investors and Strategic Acquirers: The window for entry favors specialized semiconductor foundries with alternative substrate qualification progress under ECHA timelines. Long-term viability hinges on supply security positioning as dual-source mandates expand across NATO procurement offices. Acquisition targets should demonstrate indium gallium arsenide or type-II superlattice production capability. The signal to watch is Ministry of Defence contract awards consolidating sensor procurement under platform-centric rather than discrete subsystem competitions.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Substrate Qualification | ECHA REACH compliance pivots supplier timelines toward indium gallium arsenide technologies. |
| Modular Payload Architecture Development | L3Harris Technologies demonstrates rotary-wing and fixed-wing sensor package interchangeability. |
| Cryogenic Engineering Talent Acquisition | Stirling engine design expertise concentrates among aging workforce cohorts in Germany and the United States. |
| Platform-Centric Contract Capture | United Kingdom maritime patrol and Australia fighter programs absorb tier-two payload specialists. |
| Aftermarket Service Certification | EPA hazardous material disposal protocols create revenue streams for cooled detector dewar refurbishment. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with program managers at prime contractors, procurement officers at NATO defense ministries, cryogenic engineering specialists, and focal plane array foundry operations leads. ECHA substance restriction databases, FAA airworthiness certification records, and EPA hazardous material disposal protocols provided regulatory boundary conditions. Bottom-up platform procurement tracking and top-down defense budget allocation analysis enabled triangulation across data streams.
Data-stream reconciliation across production volume estimates, contract award values, and technology adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, application mission profile, end-user budget authority, and technology thermal sensitivity tier. CAGRs were derived from fitted growth curves against historical procurement velocity and announced modernization timelines. Forecast inputs incorporated ITAR reform discussion trajectories and REACH compliance deadline schedules.
Inputs from defense ministry procurement databases and prime contractor facility records were available through the study window; gaps in classified program expenditure figures introduce uncertainty bands around targeting system growth projections. Forecasts reflect assumptions regarding NATO unmanned platform proliferation rates and contested-environment survivability mandate implementation timelines. Deviation in ECHA substance restriction enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
North America Passive Radar Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Passive Radar Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Military Jammer Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
UXO Detection Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Laser Telemetry Binoculars Market