
 Global Vein Finders Market | 2026-2036
Global Vein Finders Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vein Finders Market Outlook
Hospital procurement consolidation is recalibrating vein finder purchasing patterns across major healthcare systems. Koninklijke Philips N.V. leverages its imaging heritage to dominate premium hospital installations. Christie Medical Holdings, Inc. specializes in near-infrared visualization for pediatric and geriatric vascular access. AccuVein Inc. anchors the ambulatory clinic segment with portable, battery-operated devices.
Vein finders are non-invasive medical devices that project or detect subcutaneous blood vessels using near-infrared light, ultrasound waves, or thermal gradients, typically operating at wavelengths between 700 and 1000 nanometers to maximize hemoglobin absorption contrast against surrounding tissue. Their primary purpose is to reduce venipuncture failure rates, minimize patient discomfort, and lower clinician time expenditure during vascular access procedures. Infrared vein finders lead installed base volumes due to mature optics supply chains and lower per-unit costs, while ultrasound vein finders capture expanding margin pools in intensive care and bariatric settings where deep or collapsed vessels challenge optical methods. Hybrid technology platforms that fuse infrared and electrical impedance sensing represent the fastest-growing segment as manufacturers pursue differentiation through multi-modal accuracy.
FDA 510(k) clearance pathways and CE marking under the EU MDR govern device safety and electromagnetic compatibility for vein finders sold in the United States and European Union respectively. Japan's PMDA enforces JIS standards for medical electrical equipment that constrain market entry for non-compliant manufacturers. India's CDSCO has tightened import registration for near-infrared devices, redirecting vendor attention toward local clinical validation studies. Stakeholders must monitor evolving reimbursement codes for vascular access assistance in Medicare and national health insurance schemes, as coding recognition directly determines hospital capital allocation for these devices.
Market Dynamics
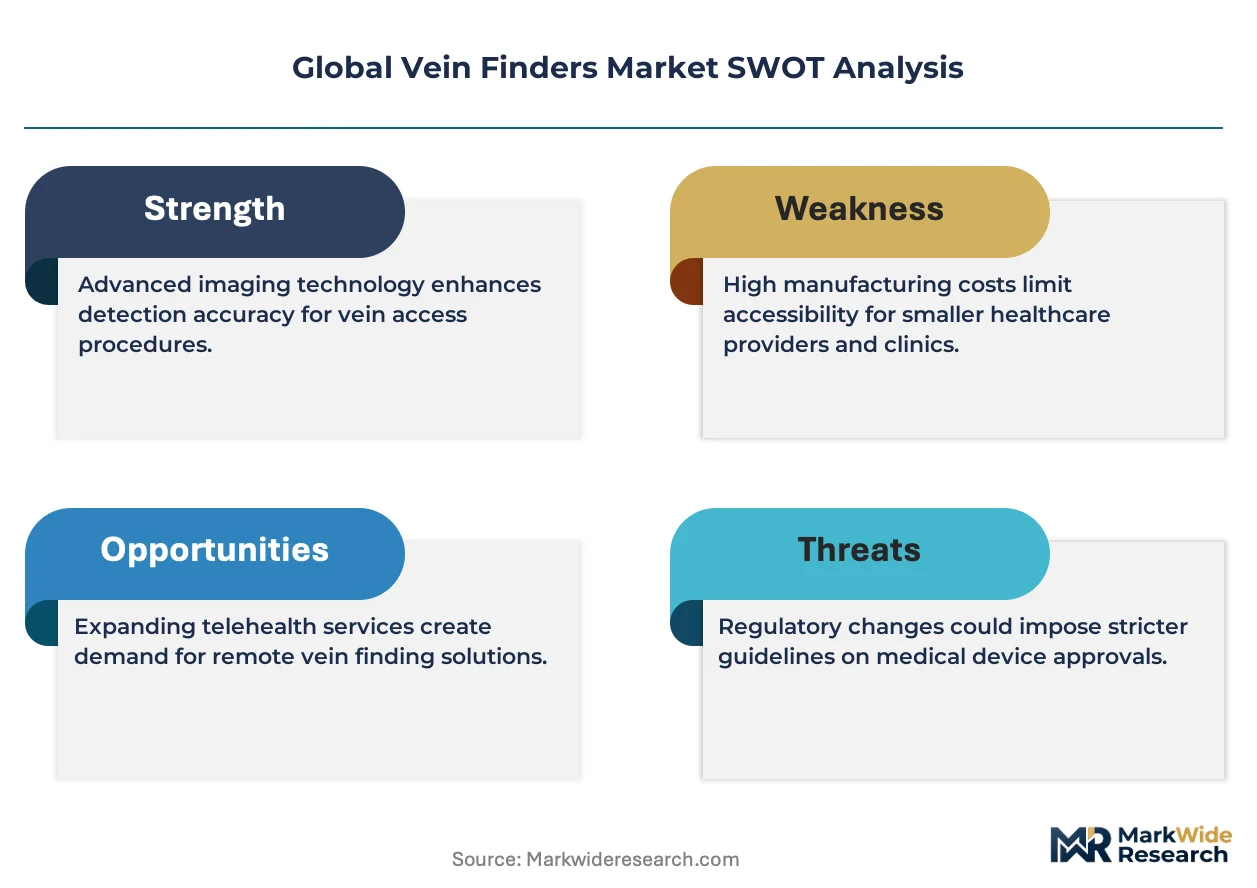
Hospital procurement consolidation is compressing vendor margins while favoring multi-modal platforms that bundle infrared, ultrasound, and electrical impedance sensing under single enterprise contracts.
Growth Catalysts
- EU MDR enforcement:Stricter CE marking requirements for near-infrared devices are filtering out low-quality imports, creating shelf space for compliant manufacturers in German and French hospital systems.
- Geriatric vascular complexity:Aging populations in Japan and Italy elevate venipuncture failure rates, forcing nursing staff to adopt visualization aids for peripheral IV insertion.
- Hybrid platform development:Multi-sensor fusion combining infrared and electrical impedance is unifying accuracy benchmarks across ambulatory and acute care settings.
Market Restraints
- Optics supply concentration:Near-infrared LED and CMOS sensor production clusters in East Asian foundries, exposing device assemblers to single-source fragility.
- Reimbursement coding gaps:Medicare's absence of discrete CPT codes for vascular access assistance forces capital expenditure onto hospital operational budgets rather than procedure revenue.
- Ultrasound cost floor:Piezoelectric transducer arrays and signal processing chipsets maintain per-unit manufacturing costs above infrared alternatives by a factor of three.
Strategic Opportunities
- India's CDSCO pathway:Local clinical validation requirements for near-infrared device registration create first-mover advantage for manufacturers establishing domestic trial infrastructure.
- Home infusion expansion:Portable battery-operated vein finders penetrate home healthcare channels as IV antibiotic and biologic administration shifts outside hospital walls.
- Japan's PMDA harmonization:Alignment with IEC 60601 medical electrical standards streamlines approval for devices already holding FDA 510(k) clearance.
Industry Challenges
- Vascular access specialist shortages:Certified infusion nurses require 40+ hours of training on ultrasound-guided techniques, constraining device utilization rates in understaffed wards.
- Legacy EMR integration:Device data output formats lack standardization, forcing IT departments to build custom HL7 interfaces for documentation in Epic and Cerner systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vein Finders Market |
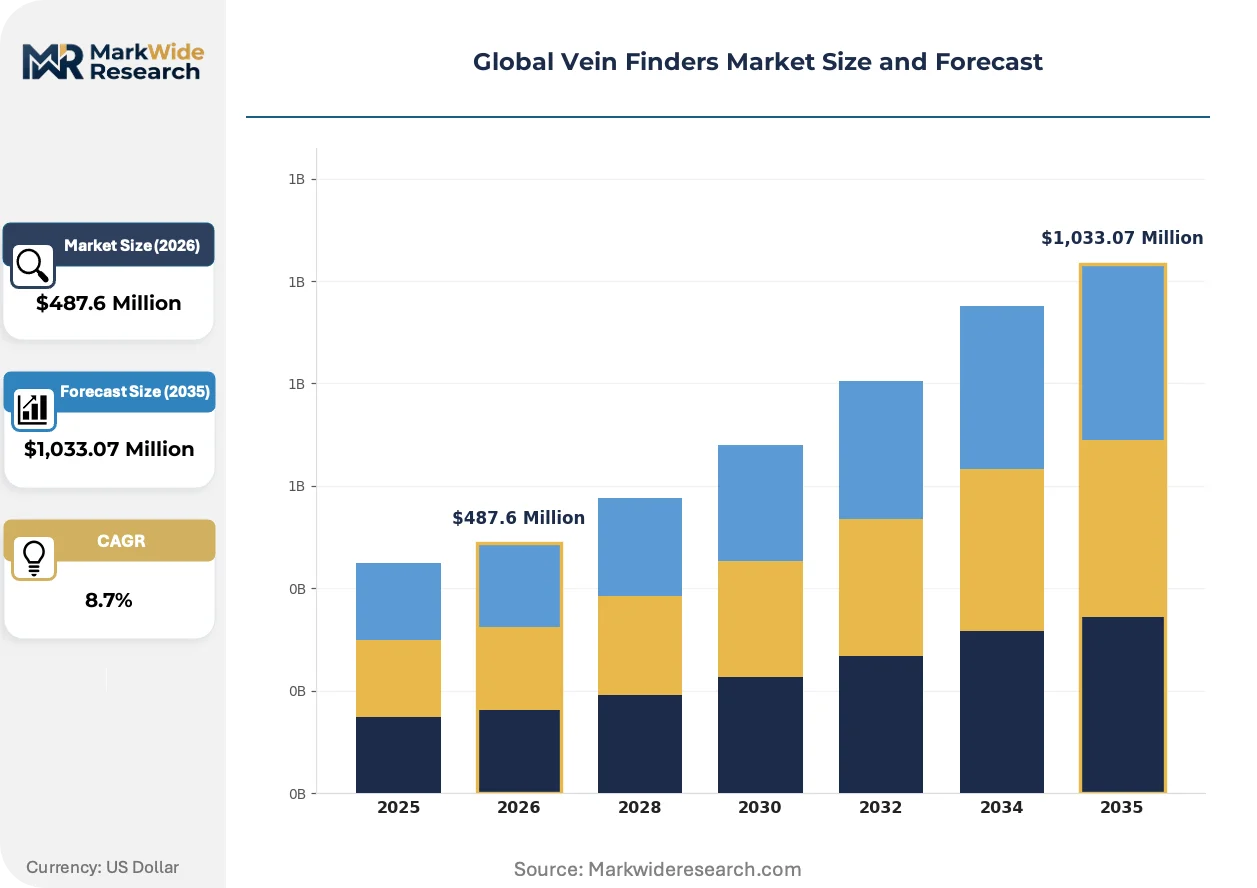
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Vein Finders, Ultrasound Vein Finders, Transilluminators, Laser Vein Finders End User: Hospitals, Clinics, Laboratories, Home Care Providers Technology: Optical Technology, Thermal Technology, Electrical Impedance Technology, Hybrid Technology Application: Venipuncture, IV Insertion, Blood Donation, Patient Monitoring |
| Companies Covered | AccuVein Inc., Christie Medical Holdings, Inc., Koninklijke Philips N.V., Teleflex Incorporated, Venoscope LLC, ZD Medical Inc., TransLite LLC, Infinium Medical, Inc., B. Braun SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vein Finders Market Strategic Shifts
Multi-modal sensing architectures are displacing single-technology devices, while regulatory tightening and procurement centralization reshape competitive positioning across developed healthcare systems.
Hybrid vein visualization is unifying infrared projection with real-time electrical impedance mapping to eliminate guesswork in vessel depth estimation. Intensive care units in the United States and Germany are piloting these platforms for central line placement. The convergence is compressing the installed base advantage of pure-play infrared vendors by raising accuracy thresholds for new hospital tenders.
Japan's PMDA has tightened electromagnetic compatibility testing under revised JIS T 0601-1 standards, extending approval timelines for near-infrared devices by six to nine months. Domestic manufacturers with established quality management systems capture incremental share as foreign competitors navigate retesting requirements. Pediatric hospitals represent the most affected segment due to stricter safety margins for neonatal applications.
Hospital procurement departments now mandate five-year total cost of ownership analyses that bundle device acquisition, disposable accessories, training, and maintenance. This analytical rigor disadvantages low-cost infrared-only vendors lacking service infrastructure. The shift is most visible in United States health systems pursuing Vizient and Premier group purchasing contracts.
Global Vein Finders Market Segmentation
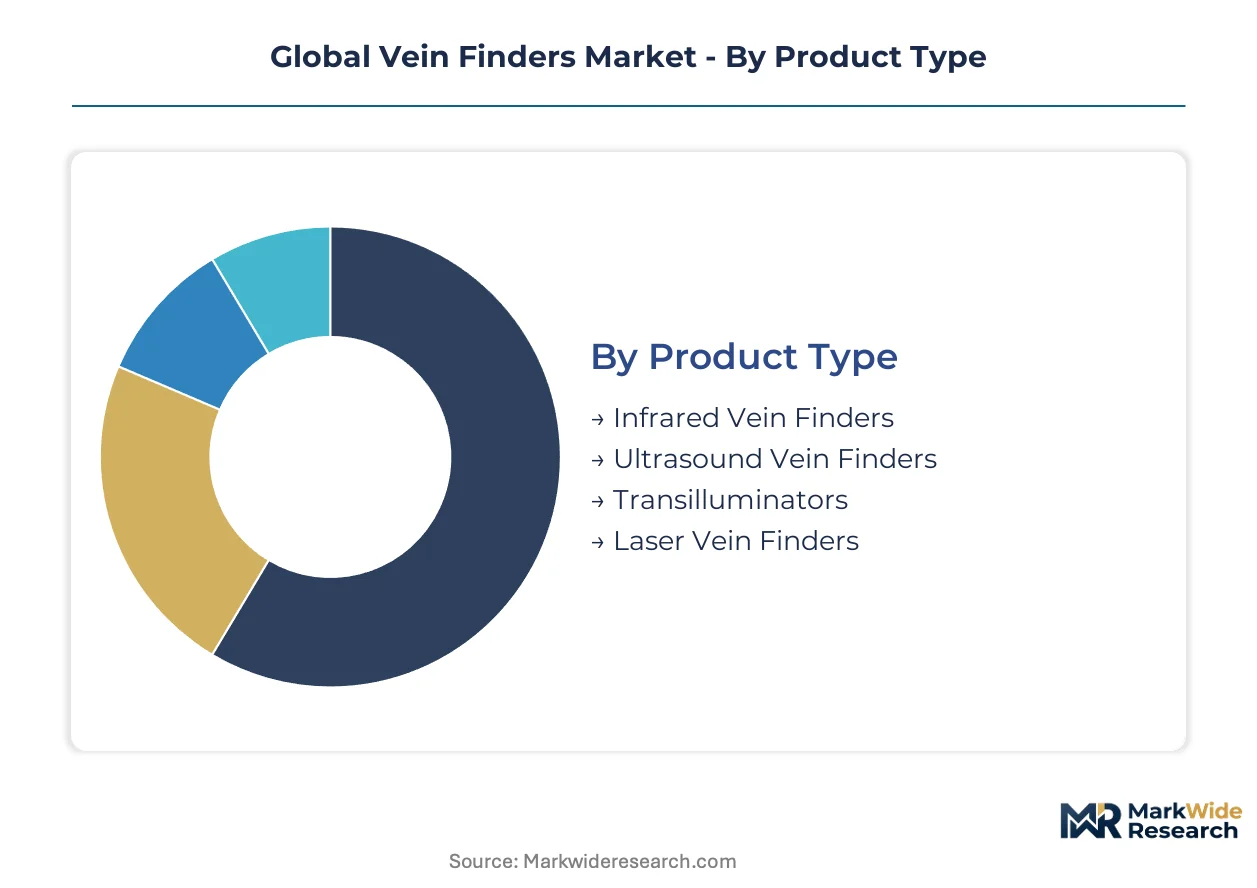
Vein finder segmentation reflects divergent clinical workflows across acute care and ambulatory settings. Technology choices cascade through procurement decisions, reimbursement pathways, and staff training requirements. Understanding these segment boundaries clarifies where manufacturers must prioritize integration depth versus standalone portability.
Product Type:
Infrared devices dominate standalone deployments in high-volume phlebotomy bays, while ultrasound platforms anchor embedded vascular access workflows in intensive care units.
- Infrared Vein Finders:These devices project near-infrared light at 700-1000 nanometer wavelengths to visualize superficial vessels through hemoglobin absorption contrast. German hospital systems and Japanese geriatric wards deploy them for routine peripheral IV placement where vessel depth remains under 10 millimeters.
- Ultrasound Vein Finders:Piezoelectric transducer arrays generate real-time cross-sectional imaging of deep or collapsed vessels. United States bariatric centers and cardiac intensive care units in France rely on these systems when optical methods fail due to adipose tissue or edema.
- Transilluminators:Simple LED-based devices illuminate subcutaneous tissue for pediatric and neonatal applications in Italian maternity wards.
- Laser Vein Finders:Coherent light sources target dermatology and cosmetic surgery clinics in South Korea for spider vein mapping.
Volume placements concentrate in infrared vein finders; the faster expansion belongs to ultrasound platforms.
End User:
Procurement authority and reimbursement structure determine how each end-use channel sources visualization technology.
- Hospitals:Enterprise contracts bundle multi-modal platforms across emergency departments, operating rooms, and infusion centers. United States health systems pursuing Vizient group purchasing agreements favor five-year total cost of ownership models.
- Clinics:Ambulatory settings in Germany and Japan prioritize portable battery-operated infrared devices for same-day surgery and chemotherapy infusion.
- Laboratories:High-throughput phlebotomy operations in India and Brazil deploy fixed-mount infrared systems to accelerate specimen collection.
- Home Care Providers:Home infusion nurses in the United States carry handheld devices for IV antibiotic administration outside hospital walls.
Capital expenditure flows heaviest through hospital procurement; home care channels are climbing the fastest.
Technology:
Single-sensor architectures face displacement as hybrid platforms unify accuracy benchmarks across care settings.
- Optical Technology:Near-infrared and visible light systems leverage mature CMOS sensor supply chains. These dominate installed bases in United States outpatient clinics and Indian diagnostic chains due to manufacturing scale.
- Thermal Technology:Infrared thermography detects temperature differentials between blood vessels and surrounding tissue. Niche deployment persists in French burn centers and Japanese wound care facilities.
- Electrical Impedance Technology:Bioimpedance sensing maps vessel boundaries without optical constraints. German research hospitals pilot these systems for patients with dark skin tones where near-infrared contrast degrades.
- Hybrid Technology:Multi-sensor fusion combines infrared projection with electrical impedance mapping. Intensive care units in the United States and Germany pilot these platforms for central line placement accuracy.
Optical platforms retain the deepest installed base; hybrid architectures are expanding most quickly.
Application:
Procedure reimbursement codes and failure-rate economics shape which applications justify capital investment in visualization aids.
- Venipuncture:Routine blood draws in United States hospital laboratories and German physician offices drive baseline demand for rapid vessel location. Medicare's absence of discrete CPT codes for vascular access assistance forces operational budget absorption.
- IV Insertion:Peripheral and central line placement in Japanese geriatric wards and Italian oncology units elevates adoption as aging populations complicate vascular access. Certified infusion nurse shortages constrain utilization rates.
- Blood Donation:Mobile collection units in India and Brazil use portable infrared devices to accelerate donor throughput and reduce phlebotomist fatigue.
- Patient Monitoring:Continuous vascular assessment in United States cardiac intensive care units supports hemodynamic monitoring through integrated ultrasound platforms.
IV insertion commands the highest per-procedure value; blood donation applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation concentrates demand in three major healthcare systems where aging demographics and chronic disease prevalence elevate venipuncture complexity. Each national market presents distinct regulatory barriers and reimbursement structures that shape vendor entry strategies.
United States
Medicare's absence of discrete CPT codes for vascular access assistance forces hospital operational budgets to absorb device costs. FDA 510(k) clearance pathways govern near-infrared and ultrasound-based systems. Texas Medical Center clusters in Houston anchor enterprise purchasing for multi-modal platforms across emergency departments and infusion centers.
Germany
Geriatric vascular complexity in Bavarian and North Rhine-Westphalian hospital systems elevates adoption of visualization aids for peripheral IV insertion. EU MDR enforcement filters out low-quality imports through stricter CE marking requirements. Berlin-Brandenburg research hospitals pilot hybrid platforms combining infrared projection with electrical impedance mapping.
Japan
Aging populations in Kanto and Kansai regions complicate venipuncture procedures for nursing staff. PMDA enforcement of revised JIS T 0601-1 standards extends approval timelines by six to nine months. Domestic manufacturers with established quality management systems capture incremental share as foreign competitors navigate retesting requirements.
India
High-throughput phlebotomy operations in Maharashtra and Karnataka deploy fixed-mount infrared systems to accelerate specimen collection. CDSCO has tightened import registration requirements, redirecting vendor attention toward local clinical validation studies. Diagnostic chains in Delhi-NCR drive volume demand for cost-optimized optical devices.
United Kingdom
NHS procurement frameworks bundle vein visualization into vascular access pathway contracts for London and Southeast hospital trusts. MHRA alignment with EU MDR transitional provisions maintains regulatory continuity post-Brexit. Midlands-based infusion centers prioritize portable battery-operated devices for same-day surgery workflows.
Global Vein Finders Market Competitive Environment
United States and European producers anchor the premium tier through imaging heritage and regulatory compliance; Asian specialists hold cost-optimized segments through manufacturing scale. The vendor base stratifies across three tiers: diversified medical technology conglomerates, pure-play vascular access specialists, and regional assembly operations. Two dominant competitive moves define current positioning: enterprise contract bundling of multi-modal platforms and backward integration into CMOS sensor supply chains.
Within the diversified medical technology tier, Koninklijke Philips N.V. and B. Braun SE exemplify archetypes that leverage existing hospital relationships to bundle vein visualization into broader capital equipment contracts. Christie Medical Holdings, Inc. occupies a specialist position focused on near-infrared applications. These three entities represent distinct strategic postures—imaging conglomerate diversification, infusion therapy integration, and vascular access specialization—without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| AccuVein Inc. |
| Christie Medical Holdings, Inc. |
| Koninklijke Philips N.V. |
| Teleflex Incorporated |
| Venoscope LLC |
| ZD Medical Inc. |
| TransLite LLC |
| Infinium Medical, Inc. |
| B. Braun SE |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consolidation across United States health systems and German hospital networks concentrates buying power into enterprise contracts that favor multi-modal platforms over standalone infrared devices. This buyer concentration enforces value-based pricing models where five-year total cost of ownership calculations determine vendor selection rather than per-unit acquisition cost.
Pricing Analysis
High-volume infrared vein finders compete on manufacturing scale and CMOS sensor cost curves, while ultrasound platforms command margin premiums through piezoelectric transducer performance. Price differentiation separates FDA 510(k) cleared devices with full service infrastructure from economy-tier imports lacking domestic validation. Pricing pressure stems from EU MDR compliance costs filtering out low-quality CE marking holders. Ambulatory clinics in India and Brazil exhibit highest price sensitivity; United States academic medical centers prioritize accuracy over unit cost.
Supply Chain Analysis
Freight cost volatility and component lead time uncertainty are reshaping sourcing strategies as near-infrared LED and CMOS sensor production clusters in Taiwan, South Korea, and China. Device assemblers draw from East Asian foundries for optical components while piezoelectric transducers for ultrasound platforms source from Japanese and German specialty manufacturers. Single-source vulnerability in CMOS sensor supply creates exposure to geopolitical disruption. Distribution runs through hospital group purchasing organizations in North America and direct tender contracts in European national health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Near-infrared LED foundry capacity constraints and EU MDR retesting bottlenecks are sustaining pricing power for compliant manufacturers despite buyer consolidation. Supply scarcity in qualified optical component vendors props margins for established players.
For Market Incumbents: Lock in captive supply agreements with Taiwan-based CMOS sensor foundries before capacity allocation tightens further. Defend hospital enterprise contracts by bundling hybrid platform upgrades with training and maintenance services to raise switching costs against emerging ultrasound specialists. For New Entrants and Emerging Players: Begin with India's CDSCO registration pathway where local clinical validation requirements create defensible first-mover positioning. Home infusion channels in the United States offer the most penetrable white space as IV antibiotic administration shifts outside hospital walls. Pursue portable battery-operated infrared form factors to bypass capital expenditure approval cycles. For Investors and Strategic Acquirers: The window for entry favors hybrid technology specialists with FDA 510(k) clearance and established electrical impedance sensing IP. Long-term viability hinges on reimbursement code recognition for vascular access assistance in Medicare and national health insurance schemes. Monitor CPT code proposal submissions as the critical inflection signal for hospital capital allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Retesting timelines extend six to nine months for near-infrared devices, filtering competition. |
| Hybrid Platform Development | Multi-sensor fusion unifies accuracy benchmarks across intensive care and ambulatory settings. |
| India CDSCO Registration | Local clinical validation requirements redirect vendor attention toward domestic trial infrastructure. |
| Hospital GPO Contracting | Vizient and Premier agreements bundle five-year total cost of ownership analyses favoring service depth. |
| Reimbursement Strategy | CPT code recognition for vascular access assistance determines operational versus capital budget sourcing. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and vascular access specialists combined with FDA 510(k) databases, EU MDR notified body records, and hospital procurement databases. Bottom-up device shipment estimates and top-down healthcare capital expenditure patterns were triangulated to validate market sizing.
Granularity-level modeling deployed technology splits at the component level, end-user channels at the procurement authority level, and geographic markets at the national regulator level. CAGRs were derived from procedure volume elasticity to device adoption rates and replacement cycle analysis across acute care settings. Forecast inputs incorporated certified infusion nurse training capacity constraints and EMR integration cost trajectories.
Underlying measurement precision varies by segment; infrared device volumes carry tighter precision than emerging hybrid platform estimates due to established trade data availability. Forecasts reflect assumptions about reimbursement code evolution and procurement consolidation velocity. Stakeholders should weight assumptions against their own operating context and local regulatory timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Rapid Infuser Market
Medical Devices
Respiratory Oxygen Delivery Devices Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Internal Nasal Dilators Market
Medical Devices
Vaginal Specula Market
Medical Devices
Global Gynecological Dilators Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Global Robotic Endoscopy Devices Market
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Urology Guidewires Market
Medical Devices
Latin America Biomedical Sensors Market