
 Automotive Battery Pack Pressure Equalization Membrane Market | 2026-2036
Automotive Battery Pack Pressure Equalization Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Pack Pressure Equalization Membrane Market Insights
Solid-state and semi-solid battery architectures is reconfiguring how pressure equalization membranes integrate into thermal runaway management systems. W. L. Gore & Associates leverages its fluoropolymer expertise to anchor premium membrane supply for next-generation pack designs. Donaldson Company competes through filtration-adjacent manufacturing scale, while Freudenberg Sealing Technologies specializes in automotive sealing applications that extend into battery enclosure interfaces.
An automotive battery pack pressure equalization membrane is a microporous barrier, typically 10–50 micrometers thick and composed of PTFE, PVDF, or polyethylene, that permits gas venting while blocking liquid ingress and particulate contamination to protect lithium-ion cells from pressure differentials and moisture damage. Microporous membranes dominate current procurement volumes due to their established cost-performance balance, though composite membranes are gaining fastest in high-voltage platforms where multilayer structures address combined thermal and mechanical stresses. Among applications, electric vehicles absorb the largest share of membrane output, while energy storage systems represent an emerging margin pool as grid-scale battery deployments multiply.
China's MIIT and SAMR enforce GB standards for battery pack sealing and venting performance, while South Korea's MFDS and KATS align membrane material certifications with cell safety protocols. The EU's Battery Regulation and REACH compliance requirements are reshaping material selection criteria for membranes sold into European vehicle programs. Stakeholders must track how regional divergence in fire-safety testing protocols affects membrane specification harmonization across multinational battery supply chains.
Market Dynamics
Cell-to-pack architectures are compressing membrane integration timelines as battery OEMs eliminate module housings and expose pressure management films to direct thermal runaway pathways.
Growth Catalysts
- GB Standard 38031:China's MIIT mandates enhanced venting performance for lithium-ion packs, forcing membrane upgrades across domestic EV platforms.
- Semi-solid electrolyte platforms:Next-generation cell chemistries require redesigned gas permeability specifications that favor advanced fluoropolymer membranes.
- South Korean cell manufacturing:MFDS-aligned safety protocols at SK On and LG Energy Solution facilities are standardizing membrane procurement volumes.
Market Restraints
- PTFE resin concentration:Virgin polymer supply chains cluster with Chemours and Daikin in Japan and the US, creating input cost volatility.
- Technical thickness floors:Microporous films below 15 micrometers suffer mechanical failure rates that disqualify them from high-voltage platforms.
- REACH substance restrictions:ECHA scrutiny of perfluorinated compounds is forcing material reformulation timelines for European-bound products.
Strategic Opportunities
- India's PLI scheme:Battery cell manufacturing incentives are creating first-mover membrane specification windows for suppliers establishing local technical service.
- Grid-scale energy storage:Containerized battery deployments require pressure equalization at scale, opening volume contracts outside automotive procurement cycles.
- Solid-state convergence:Oxide and sulfide electrolyte platforms demand hybrid membranes combining thermal barrier and gas venting functions.
Industry Challenges
- Fluoropolymer processing expertise:Biaxial stretching and node-fibril formation require specialized technicians scarce outside Japan and Germany.
- Cell-level certification timelines:UN 38.3 and UL 9540A testing sequences extend membrane qualification cycles to 18-24 months.
- Pack architecture fragmentation:Proprietary cell formats from CATL, BYD, and Panasonic prevent membrane standardization across OEM programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Pack Pressure Equalization Membrane Market |
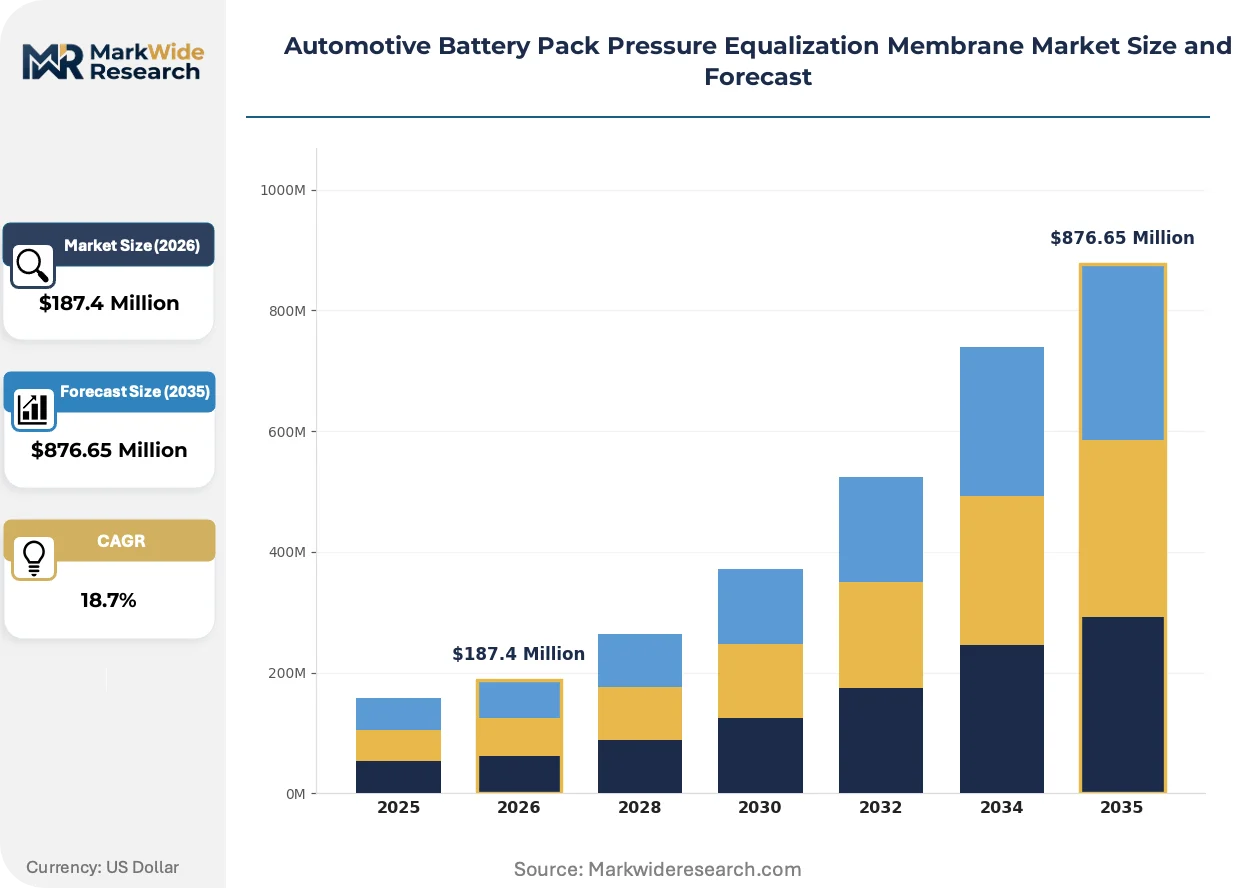
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polytetrafluoroethylene, Polypropylene, Polyvinylidene Fluoride Application: Electric Vehicles, Hybrid Vehicles, Energy Storage Systems, Commercial Fleets End User: Battery Manufacturers, Electric Mobility Providers, Fleet Operators, Battery Recycling Firms Technology: Microporous Membranes, Composite Membranes, Nanofiber Membranes, Laminated Membranes |
| Companies Covered | W. L. Gore & Associates, Donaldson Company, Freudenberg Sealing Technologies, Saint-Gobain Performance Plastics, Nitto Denko Corporation, Parker Hannifin, MANN+HUMMEL, Porex Corporation, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Pack Pressure Equalization Membrane Market Trends and Innovations
Membrane engineering is pivoting toward multifunctional barriers that combine pressure relief with thermal insulation and electromagnetic shielding as pack energy densities climb.
PTFE-based microporous films currently dominate automotive procurement due to their chemical inertness and tunable pore structures. High-voltage platform engineers at European and Chinese OEMs are migrating from single-layer PTFE toward laminated composites incorporating polyimide or ceramic interlayers. This migration from monolithic to hybrid architectures is compressing qualification timelines while expanding addressable performance envelopes.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are tightening material disclosure requirements for membranes sold into European vehicle programs. ECHA's 2023 PFAS restriction proposal forces suppliers to document fluoropolymer content across supply tiers. Membrane manufacturers serving Volkswagen Group and Stellantis programs are accelerating fluorine-free alternative development while defending existing PTFE portfolios through polymer exemption arguments.
Cell manufacturers are consolidating membrane procurement under long-term supply agreements rather than spot purchasing through pack integrators. BYD and CATL now specify membrane grades directly, compressing distributor margins and favoring suppliers with captive resin production. China-based procurement teams are establishing annual volume commitments with Japanese and German membrane specialists, locking in capacity ahead of domestic competitor scale-up.
Automotive Battery Pack Pressure Equalization Membrane Market Segmentation
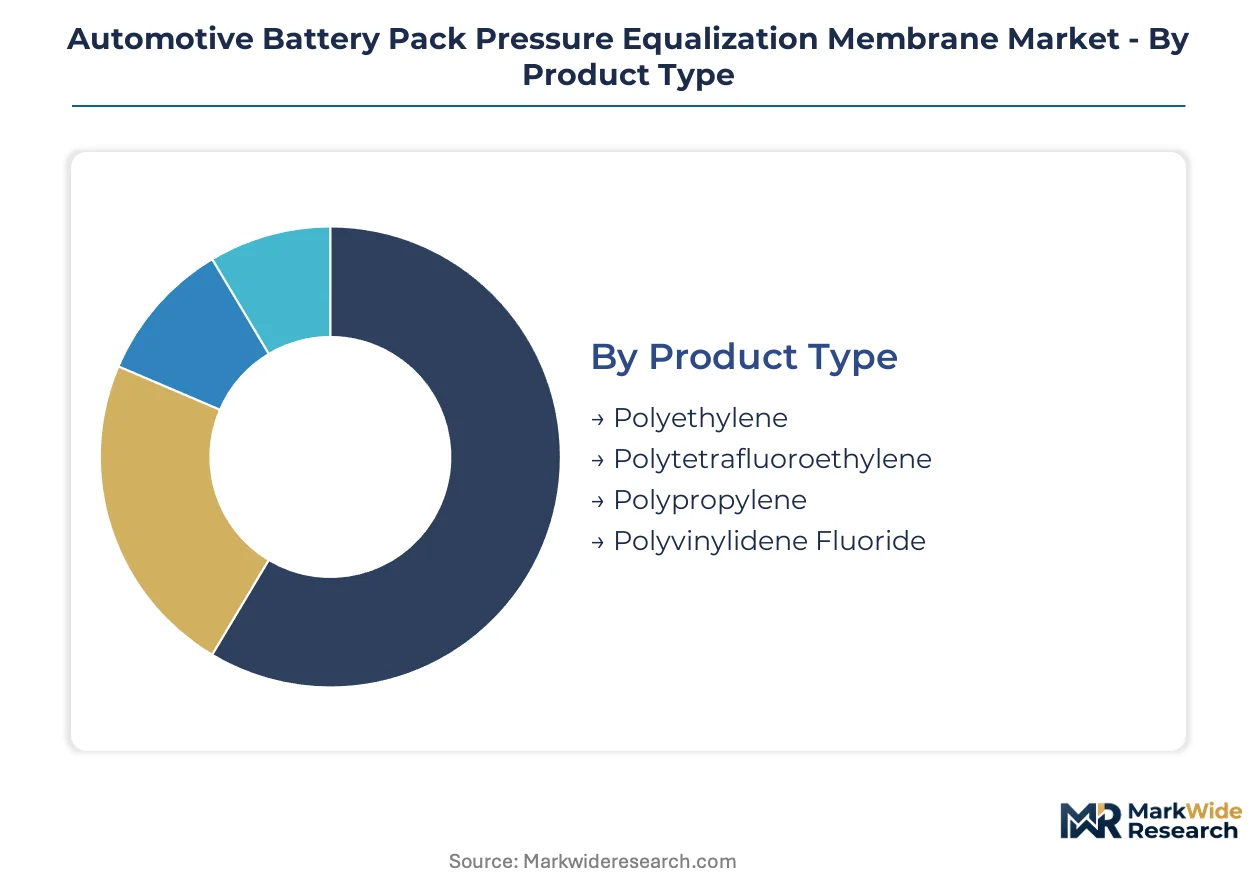
Membrane procurement patterns diverge sharply across material chemistries and pack architectures, forcing suppliers to align technical roadmaps with distinct qualification timelines and performance thresholds. Understanding how segments interlock reveals where specification power concentrates and margin pools form.
Product Type:
After-sales service intensity varies dramatically by polymer chemistry, with fluoropolymer membranes demanding specialized installation protocols and field validation that polyethylene alternatives rarely require.
- Polyethylene:Cost-optimized barrier films dominate entry-level hybrid vehicle programs where moisture protection requirements sit below electric vehicle thresholds. Chinese pack integrators at BYD and CATL procurement centers specify these grades for cost-sensitive module designs where 20-micrometer thickness floors suffice.
- Polytetrafluoroethylene:Chemically inert microporous structures with tunable node-fibril architectures anchor premium electric vehicle platforms. SK On and LG Energy Solution facilities in South Korea standardize PTFE membranes for high-voltage cell-to-pack architectures where GB Standard 38031 venting performance is mandatory.
- Polypropylene:Intermediate cost-performance positioning serves commercial fleet retrofits and aftermarket replacement cycles where original equipment specifications loosen.
- Polyvinylidene Fluoride:Piezoelectric properties suit sensing-integrated membranes in next-generation thermal runaway detection systems.
By volume, polyethylene leads. By growth pace, polytetrafluoroethylene is ahead.
Application:
Pack energy density trajectories reshape membrane specifications differently across mobility modes, with electric vehicles pushing thinnest viable films while energy storage tolerates thicker, lower-cost alternatives.
- Electric Vehicles:Cell-to-pack architectures expose membranes directly to thermal runaway pathways, demanding sub-25-micrometer fluoropolymer barriers with validated pore collapse temperatures. NMPA and MIIT certification timelines in China compress development cycles for suppliers serving NIO and Xpeng programs.
- Hybrid Vehicles:Moderate energy densities and established module housings permit thicker polyethylene membranes with less stringent venting performance requirements. Toyota and Honda procurement specifications prioritize cost stability over extreme thinness.
- Energy Storage Systems:Containerized grid-scale deployments at Sungrow and Fluence facilities favor composite membranes combining pressure equalization with fire-retardant interlayers.
- Commercial Fleets:Heavy-duty cycle durability and standardized pack formats enable volume procurement agreements with predictable replacement intervals.
Electric vehicles absorb the largest membrane tonnage. Energy storage systems are expanding most quickly.
End User:
Procurement authority is consolidating upstream as cell manufacturers bypass pack integrators to specify membrane grades directly, compressing distributor margins and favoring resin-captive suppliers.
- Battery Manufacturers:CATL and BYD now issue annual volume commitments to Japanese and German membrane specialists, locking in capacity ahead of domestic competitor scale-up. Direct specification authority eliminates tier-two distributor margins.
- Electric Mobility Providers:NIO, Xpeng, and Li Auto procurement teams are establishing technical service partnerships with membrane suppliers for rapid pack redesign cycles.
- Fleet Operators:Standardized replacement schedules and total-cost-of-ownership calculations favor proven membrane grades over experimental thin-film alternatives.
- Battery Recycling Firms:Secondary material recovery protocols are creating specification windows for remanufactured membrane barriers in non-automotive reuse applications.
Battery manufacturers command the largest procurement volumes. Electric mobility providers are gaining specification influence fastest.
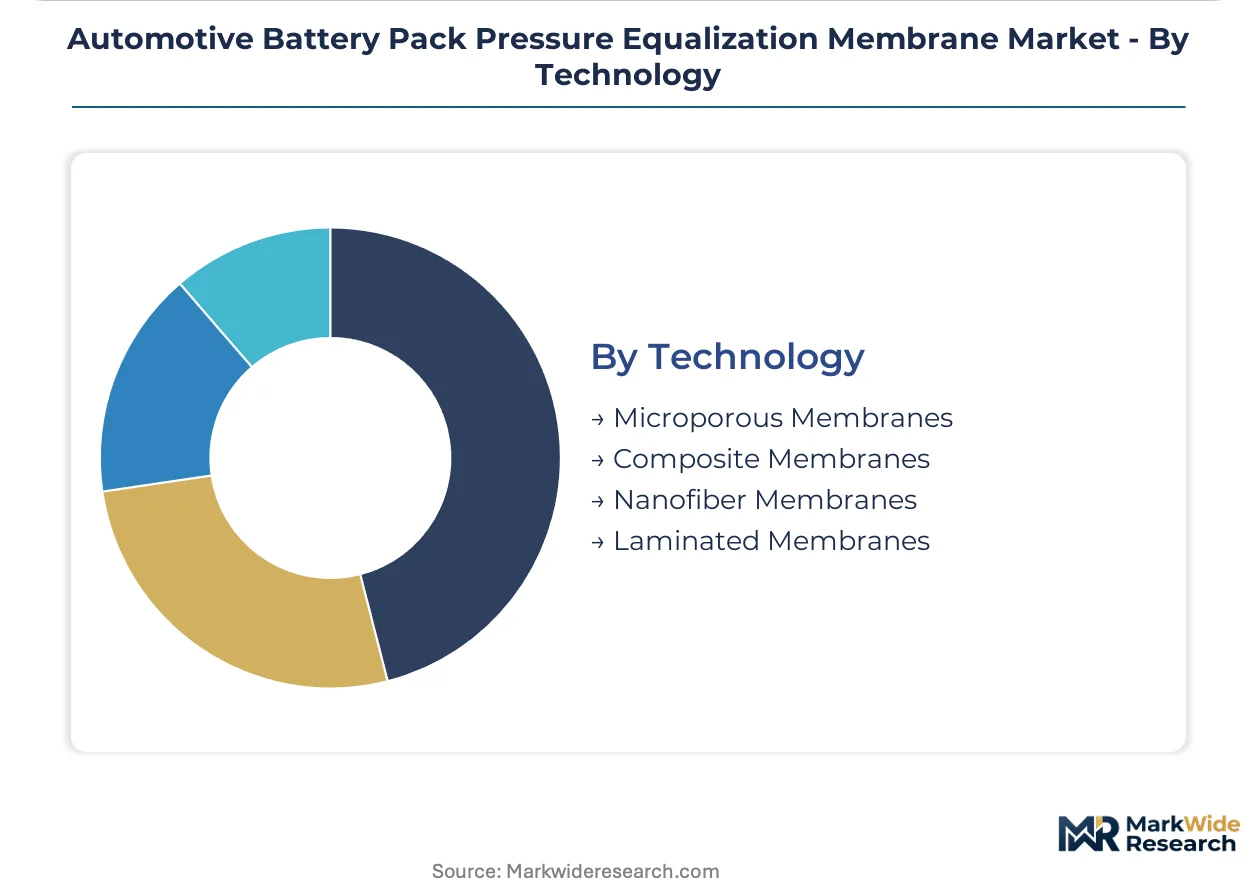
Technology:
Manufacturing process complexity creates capability scarcity, with biaxial stretching expertise concentrated among Japanese and German specialists who dominate qualification timelines for advanced architectures.
- Microporous Membranes:Established PTFE and polyethylene films with proven pore tortuosity control anchor current automotive procurement volumes. W. L. Gore & Associates and Donaldson Company production lines supply these grades at scale for programs requiring 18-24 month UN 38.3 certification cycles.
- Composite Membranes:Laminated fluoropolymer-polyimide-ceramic structures address combined thermal and mechanical stresses in 800-volt platforms. European OEMs at Volkswagen Group and Stellantis are migrating specifications toward these hybrid architectures despite compressed qualification timelines.
- Nanofiber Membranes:Electrospun architectures promise thinner barriers with maintained mechanical integrity, though commercial scale-up remains constrained by processing yield challenges.
- Laminated Membranes:Multi-layer bonding techniques enable functional integration of pressure relief with electromagnetic shielding in premium pack designs.
Microporous membranes dominate current procurement. Composite membranes are climbing the fastest as high-voltage platforms multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in pressure equalization membranes track battery manufacturing migration patterns, with East Asian production clusters supplying European and North American pack assembly facilities while building regional captive capacity.
China
CATL and BYD procurement teams dominate membrane specification authority through direct annual volume commitments to Japanese and German suppliers. MIIT enforces GB Standard 38031 for enhanced venting performance, tightening qualification requirements for domestic EV platforms. The Yangtze River Delta battery manufacturing corridor concentrates membrane technical service partnerships with NIO and Xpeng engineering centers.
South Korea
SK On and LG Energy Solution facilities standardize PTFE membrane grades for high-voltage cell-to-pack architectures serving export markets. MFDS-aligned safety protocols mandate membrane material certifications synchronized with cell-level testing sequences. The Busan-Ulsan industrial cluster hosts membrane qualification laboratories supporting 18-24 month UN 38.3 certification cycles for European OEM programs.
Japan
Sumitomo Electric Industries and Nitto Denko anchor fluoropolymer membrane supply through captive resin processing and biaxial stretching expertise concentrated with METI-supported equipment makers. JIS standards for battery pack sealing interface with international OEM qualification requirements. The Kansai manufacturing belt maintains specialized technician pools for node-fibril formation processes scarce outside domestic production lines.
Germany
Volkswagen Group and Stellantis procurement specifications are migrating toward laminated composite membranes despite REACH Annex XVII scrutiny of perfluorinated compounds forcing material disclosure across supply tiers. KBA vehicle type approval processes incorporate membrane performance validation within pack-level safety assessments. The Baden-Württemberg automotive supplier corridor integrates membrane engineering with thermal management system development for 800-volt platforms.
United States
Domestic battery cell manufacturing incentives under the IRA are creating qualification windows for membrane suppliers establishing technical service proximity to emerging facilities. EPA and NHTSA regulatory frameworks for EV battery safety are converging with UN 38.3 testing protocols. The Michigan-Ohio industrial corridor hosts pack engineering centers specifying membrane grades for commercial fleet electrification programs with standardized replacement intervals.
Automotive Battery Pack Pressure Equalization Membrane Market Competitive Landscape
On the supply side, the industry is consolidating around resin-captive specialists with fluoropolymer processing expertise and filtration-adjacent manufacturers leveraging scale economies. Three strategic archetypes dominate: Japanese and German biaxial stretching specialists with proprietary node-fibril formation capabilities, diversified industrial conglomerates with automotive sealing heritage, and membrane-focused mid-caps serving qualification-intensive niche applications. Competitive positioning hinges on backward integration into virgin polymer supply and geographic proximity to cell manufacturer technical centers.
Among fluoropolymer specialists, W. L. Gore & Associates anchors premium-tier supply through established microporous PTFE architectures, while Donaldson Company occupies a scale-driven position leveraging filtration manufacturing infrastructure. Freudenberg Sealing Technologies exemplifies the automotive sealing heritage archetype, extending enclosure interface expertise into battery pack applications. These three represent distinct capability configurations: proprietary stretching technology, volume manufacturing scale, and systems integration experience.
| Leading Market Players |
|---|
| W. L. Gore & Associates |
| Donaldson Company |
| Freudenberg Sealing Technologies |
| Saint-Gobain Performance Plastics |
| Nitto Denko Corporation |
| Parker Hannifin |
| MANN+HUMMEL |
| Porex Corporation |
| Sumitomo Electric Industries |
| Others |
Pricing and Supply Chain Analysis
PTFE resin concentration with Chemours and Daikin determines both three-tier pricing structure across premium, standard, and economy levels and supply chain configuration, as virgin polymer scarcity compresses margins at membrane converters while rewarding resin-captive specialists with pricing power over European OEM programs.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure, with price differentiation resting on certification grade alignment with GB Standard 38031 and volume scale commitments. Cost compression in polyethylene tiers is intensifying because Chinese pack integrators at BYD and CATL procurement centers prioritize cost-sensitive module designs. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership calculations, while battery manufacturers with direct specification authority show the least.
Supply Chain Analysis
Virgin PTFE resin feedstock draws from Japan, the United States, and Germany, where biaxial stretching equipment and node-fibril formation expertise concentrate. Raw material dependencies center on fluoropolymer resins, polyimide films for composite architectures, and ceramic nanopowders for thermal barrier interlayers. Single-source vulnerability runs through Japanese equipment makers for specialized stretching lines. Distribution runs through direct annual volume commitments from CATL and BYD to membrane specialists, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against fluorine-free membrane alternatives as ECHA's PFAS restriction proposal accelerates material reformulation timelines for European-bound products.
For Market Incumbents: Entrench fluoropolymer processing expertise through captive resin production and specialized technician training pools concentrated in Japan and Germany. Defend against fluorine-free substitute threats by accelerating hybrid membrane development combining PTFE thermal performance with REACH-compliant disclosure frameworks, while locking in long-term supply agreements with SK On and LG Energy Solution facilities.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme battery cell manufacturing corridors where first-mover membrane specification windows remain open for suppliers with local technical service. Target grid-scale energy storage containerized deployments at Sungrow and Fluence facilities as the most penetrable segment, leveraging volume contracts outside automotive procurement cycles as the primary go-to-market angle.
For Investors and Strategic Acquirers: ECHA's 2023 PFAS restriction proposal reshapes the acquisition landscape toward resin-captive membrane specialists with backward integration into virgin polymer supply. Long-term viability over the next decade hinges on positioning for solid-state battery convergence where hybrid thermal barrier and gas venting functions command premium positioning. Watch for membrane qualification laboratory capacity expansion in South Korea's Busan-Ulsan cluster as the signal for inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Virgin Polymer Supply | Chemours and Daikin resin access secures margin defense against input cost volatility for membrane converters. |
| Composite Membrane Qualification Investment | Volkswagen Group and Stellantis 800-volt platform migration demands laminated fluoropolymer-polyimide-ceramic validation cycles. |
| Technical Service Partnership Expansion | NIO and Xpeng engineering centers in China's Yangtze River Delta require rapid pack redesign cycle support. |
| Fluorine-Free Alternative Development | REACH Annex XVII scrutiny forces material reformulation timelines for European vehicle program compliance. |
| Grid-Scale Energy Storage Volume Contracts | Sungrow and Fluence containerized battery deployments open margin pools outside automotive procurement cycles. |
Research Methodology
Initial hypotheses were tested against primary input from battery OEM platform engineers, Tier 1 supplier procurement leads, membrane converter technical directors, and cell manufacturer quality assurance heads, and refined through secondary validation against SEC 10-K filings from fluoropolymer resin producers, customs and trade data tracking PTFE membrane flows, IHS Markit vehicle production databases, and GB standard certification registries. Bottom-up membrane volume estimates from pack-level bill-of-materials analysis were triangulated against top-down market sizing from regional battery manufacturing capacity announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including material chemistry, pack architecture type, voltage platform tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to cell-to-pack adoption trajectories and solid-state battery development timelines, with inputs from MIIT production license data and MFDS-aligned safety protocol implementation schedules.
Stress conditions across ECHA PFAS restriction enforcement timing, GB Standard 38031 venting performance upgrade cycles, and PTFE resin supply disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cell-to-pack architecture penetration and qualification timeline compression. Material shifts in solid-state battery commercialization schedules or REACH substance restriction scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
High-Performance Electric Sports Cars Market
Electric Vehicles
Used EV Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Folding E-Scooter Market