
 US Electric Mobility Market | 2026-2036
US Electric Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
US Electric Mobility Market Intelligence
Multi-source battery supply contracting is broadening across the US electric mobility value chain as automakers reduce dependence on single-cell suppliers. Tesla leverages its Nevada-based cell production to sustain vertical integration advantages in the premium passenger segment. Ford anchors its commercial truck strategy through dedicated fleet service channels and charging infrastructure bundling. Rivian competes in the delivery van category through purpose-built electric platforms designed for logistics operators.
US electric mobility encompasses battery-electric, fuel-cell, and hybrid-electric vehicles operating on road networks with zero or reduced tailpipe emissions, typically powered by lithium-ion packs with energy densities exceeding 250 watt-hours per kilogram and managed through thermal regulation systems for cycle stability. The primary commercial purpose centers on displacing internal combustion propulsion in passenger transportation and freight logistics to comply with emissions mandates and reduce operating costs. Passenger vehicles dominate current volume within the vehicle type dimension, while commercial trucks command premium pricing and faster fleet turnover cycles. Fast charging networks within charging infrastructure attract the majority of capital deployment, though home chargers retain the largest installed base among consumer end users.
The National Highway Traffic Safety Administration administers Federal Motor Vehicle Safety Standards that govern crashworthiness and electrical system integrity for electric powertrains, while the Environmental Protection Agency oversees greenhouse gas emissions regulations that tighten corporate average fuel economy requirements. The Inflation Reduction Act's domestic content rules for clean vehicle tax credits are reshaping supply chain localization decisions and battery sourcing strategies. Stakeholders must monitor evolving EPA emissions benchmarks and NHTSA safety rulemakings to anticipate compliance cost trajectories and product planning requirements.
Market Dynamics
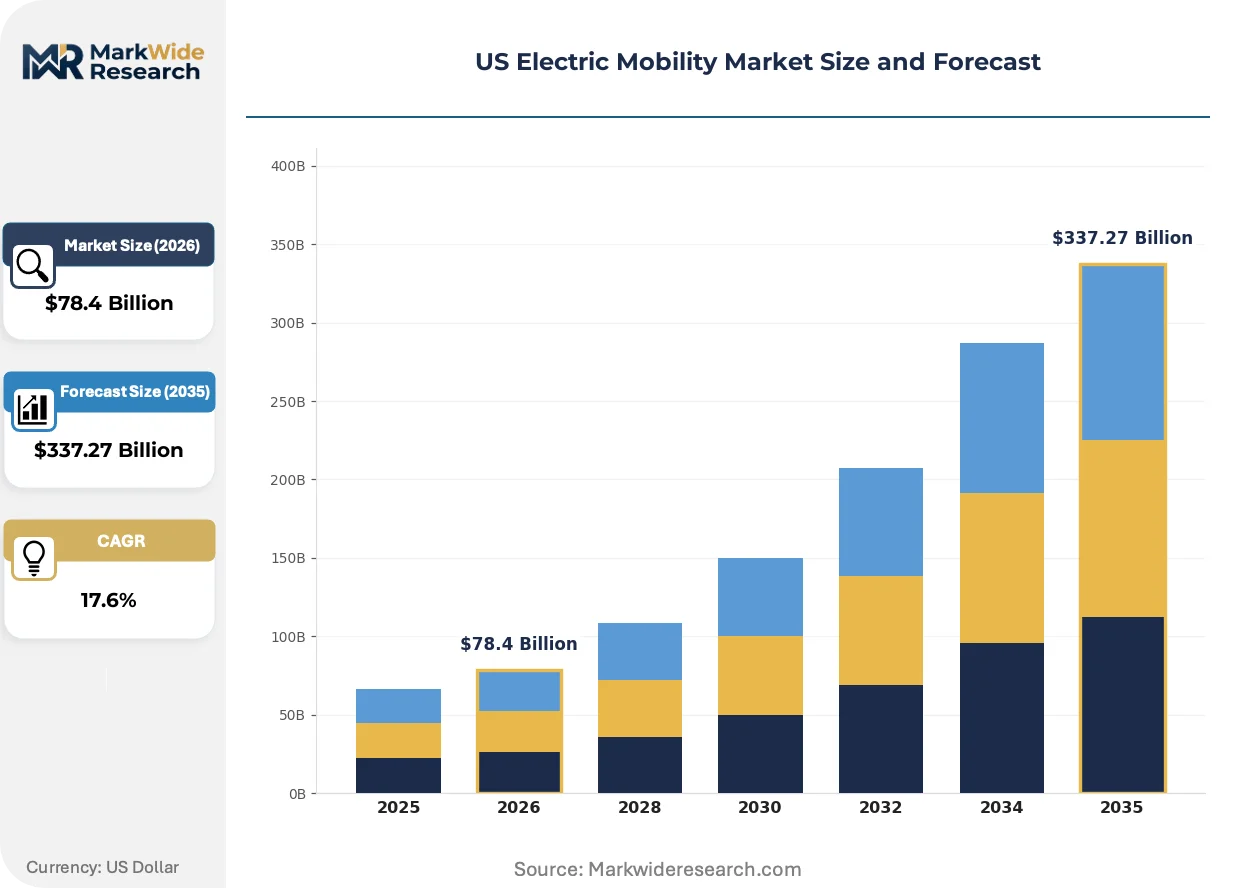
The Inflation Reduction Act's domestic content requirements are forcing automakers to reconfigure battery supply chains and localize manufacturing footprints across the US electric mobility landscape.
Growth Catalysts
- Inflation Reduction Act tax credits:The IRA's clean vehicle tax credits are lowering total cost of ownership for commercial fleet buyers, accelerating procurement timelines for delivery van and medium-duty truck operators.
- Last-mile electrification:E-commerce logistics networks are mandating zero-emission vehicle deployment in California's metropolitan corridors, creating concentrated demand pull for purpose-built electric platforms.
- Lithium iron phosphate chemistry:LFP cell formulations are reducing thermal runaway risks and extending cycle life for high-utilization commercial applications.
Market Restraints
- Critical mineral concentration:Cobalt and lithium refining capacity concentrates in Chinese processing facilities, exposing US automakers to geopolitical supply disruptions and forced labor compliance risks.
- Fast charging infrastructure gaps:Highway corridor charging density remains insufficient for long-haul freight electrification, limiting battery-electric truck deployment to regional haul routes.
- Grid interconnection queues:Utility-scale charging hub projects face multi-year Federal Energy Regulatory Commission interconnection delays, constraining depot charging expansion for fleet operators.
Strategic Opportunities
- Texas Triangle urban cluster:Houston-Dallas-San Antonio freight corridors present underpenetrated demand for electric medium-duty trucks serving distribution center networks.
- Vehicle-to-grid integration:Bidirectional charging hardware is converging with utility demand response programs, enabling fleet operators to monetize stationary battery assets.
- IRA domestic assembly incentives:The act's manufacturing production credits are attracting cell and pack assembly investment to the US Southeast, reducing import dependence.
Industry Challenges
- High-voltage technician scarcity:The National Institute for Automotive Service Excellence reports insufficient certified EV repair specialists to service projected commercial fleet volumes.
- Battery recycling infrastructure:End-of-life pack processing capacity lags deployment rates, creating stranded asset risks for fleet operators managing turnover cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electric Mobility Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $337.27 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Vehicles, Commercial Trucks, Buses, Two-Wheelers Power Source: Lithium-ion Batteries, Fuel Cells, Hybrid Systems, Ultra Capacitors Charging Infrastructure: Public Charging Stations, Home Chargers, Fast Charging Networks, Wireless Charging End User: Consumers, Fleet Operators, Municipalities, Ride-Sharing Services |
| Companies Covered | Lucid Motors, ChargePoint, Tesla, Stellantis, WiTricity, Rivian, Ford, Volvo Cars, General Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electric Mobility Market Strategic Shifts & Innovations
Technology convergence between battery hardware and software-defined vehicle architectures is compressing development cycles and enabling over-the-air performance optimization across the US electric mobility sector.
Solid-state electrolyte research is converging with silicon-anode material science to push energy density thresholds beyond 400 watt-hours per kilogram. Ford and General Motors are piloting prototype cells for premium passenger applications, though manufacturing scalability remains unproven. This convergence is compressing the performance gap between laboratory achievements and production-grade pack integration.
The Environmental Protection Agency's tightened greenhouse gas emissions standards for model years 2027 through 2032 are mandating fleet-average CO2 reductions. Commercial truck manufacturers must accelerate zero-emission vehicle mix targets or face substantial compliance penalties. California's Advanced Clean Trucks regulation is forcing early compliance investment ahead of federal timelines.
Fleet procurement is consolidating around total cost of ownership analytics that incorporate fuel, maintenance, and resale value forecasts. Large logistics operators are displacing traditional dealer relationships with direct manufacturer partnerships and bundled charging infrastructure contracts. This behavioral shift is most visible among national last-mile delivery networks operating high-utilization routes in metropolitan California and Texas corridors.
US Electric Mobility Market Segmentation
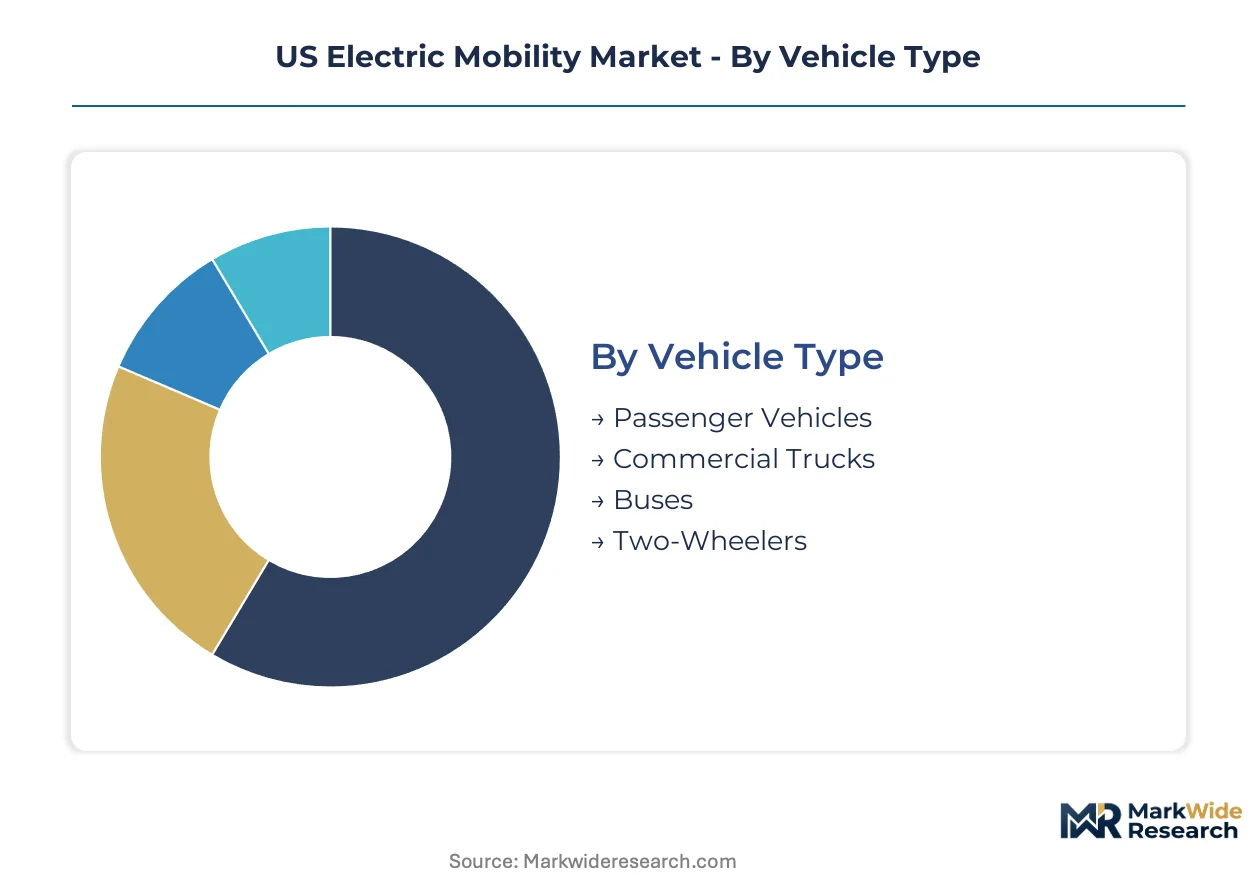
Segmentation in US electric mobility reveals how capital, policy incentives, and operational requirements concentrate across distinct hardware configurations and customer archetypes. Understanding these divisions exposes where procurement volumes, infrastructure investment, and regulatory compliance burdens diverge most sharply.
Vehicle Type:
The customization-to-standardization spectrum runs from purpose-built commercial platforms with fleet-specific modifications to mass-market passenger vehicles with limited configurability.
- Passenger Vehicles:Battery-electric sedans, crossovers, and SUVs dominate current sales volume, with lithium-ion packs typically ranging 60-100 kWh. Demand concentrates in California's metropolitan corridors where state rebates stack with IRA credits and HOV lane access privileges reduce commute times for solo drivers.
- Commercial Trucks:Medium-duty and heavy-duty electric platforms serve regional haul and last-mile delivery routes with gross vehicle weight ratings above 10,000 pounds. Fleet operators in the Texas Triangle urban cluster are expanding procurement fastest, drawn by depot charging feasibility and predictable return-to-base duty cycles that minimize range anxiety.
- Buses:Transit agencies deploy battery-electric and fuel-cell variants for fixed-route urban service, with procurement driven by Federal Transit Administration low- and no-emission grant programs.
- Two-Wheelers:Electric motorcycles and scooters address urban commuting and delivery gig work, with lighter regulatory burden from NHTSA safety standards compared to four-wheeled categories.
Most installed capacity flows through Passenger Vehicles. Expansion is steepest in Commercial Trucks.
Power Source:
Cost tiering separates mature lithium-ion chemistries from emerging alternatives still seeking manufacturing scale and supply chain maturity.
- Lithium-ion Batteries:NMC and LFP cell formulations power the vast majority of deployed electric vehicles, with energy densities exceeding 250 watt-hours per kilogram and established thermal management protocols. NHTSA crashworthiness standards and EPA emissions compliance both assume this chemistry as the baseline for safety and performance testing.
- Fuel Cells:Proton-exchange membrane systems convert hydrogen to electricity for heavy-duty applications where battery weight would exceed payload constraints. California's hydrogen hub funding and the Department of Energy H2USA initiative are concentrating early deployment along the I-5 freight corridor.
- Hybrid Systems:Plug-in and non-plug-in architectures retain internal combustion range extenders, appealing to fleet operators in regions with charging infrastructure gaps.
- Ultra Capacitors:High-power-density storage devices supplement batteries in applications requiring rapid charge-discharge cycles, such as regenerative braking energy recovery in urban bus duty cycles.
Lithium-ion Batteries absorb the majority of manufacturing investment. Fuel Cells are climbing the fastest as heavy-duty OEMs diversify beyond battery-electric platforms.
Charging Infrastructure:
Application context determines whether charging assets serve dispersed residential demand or centralized fleet depots with predictable utilization patterns.
- Public Charging Stations:Level 2 and DC fast charging installations serve retail parking, workplace, and highway corridor locations. NEVI formula funding is directing capital toward interstate highway gaps, though FERC interconnection queues delay utility-scale hub completion.
- Home Chargers:Level 1 and Level 2 residential equipment represents the largest installed base by unit count, with consumer adoption concentrated in single-family housing markets across suburban California and Texas metropolitan areas.
- Fast Charging Networks:150-350 kW DC infrastructure targets highway corridor coverage and commercial fleet mid-route replenishment, with Tesla's Supercharger network and Electrify America competing for NEVI-funded locations.
- Wireless Charging:Inductive pad systems eliminate connector wear and enable automated fleet charging, with pilot deployments at municipal bus depots in California testing operational integration.
Home Chargers account for the greatest unit penetration. Fast Charging Networks are gaining share fastest as fleet operators prioritize route flexibility.
End User:
Customer type stratifies procurement behavior across individual purchase decisions, centralized fleet management, public agency mandates, and platform-mediated mobility services.
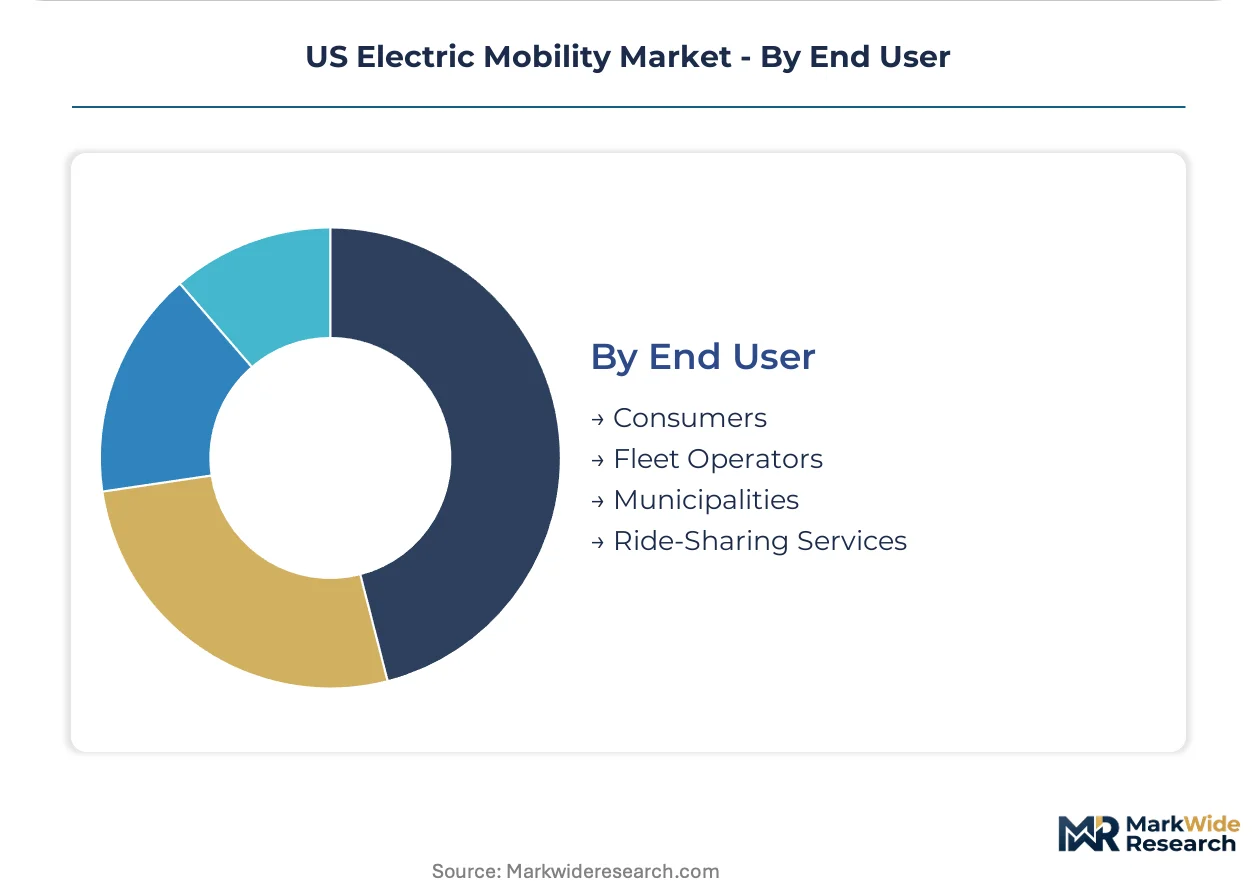
- Consumers:Individual buyers respond to total cost of ownership calculations incorporating fuel savings, maintenance reduction, and resale value projections. IRA clean vehicle tax credits are reshaping purchase economics most dramatically for this segment.
- Fleet Operators:National logistics and delivery companies deploy electric vehicles at scale, negotiating direct manufacturer relationships and bundled charging infrastructure contracts that displace traditional dealer networks.
- Municipalities:City and county governments procure electric buses, refuse trucks, and administrative fleets under sustainability mandates and Federal Transit Administration grant requirements.
- Ride-Sharing Services:Transportation network companies impose electrification requirements on driver-partners, with high-utilization duty cycles accelerating battery degradation and replacement timelines.
Fleet Operators command the largest aggregate procurement volume. Ride-Sharing Services are expanding most quickly as platform electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Triangle urban cluster anchors domestic demand concentration for electric commercial trucks, with Houston-Dallas-San Antonio freight corridors driving fleet procurement. California's metropolitan corridors maintain passenger vehicle volume leadership through stacked state and federal incentives. Geographic expansion is accelerating across the Southeast as IRA manufacturing credits attract cell assembly investment.
California
Zero-emission vehicle mandates from the California Air Resources Board compel fleet electrification timelines for delivery operators. The state's Advanced Clean Trucks regulation enforces manufacturer sales quotas ahead of federal EPA schedules. Metropolitan Los Angeles and San Francisco Bay Area logistics networks concentrate purpose-built electric van deployment.
Texas
Depot charging feasibility and predictable return-to-base duty cycles attract medium-duty truck procurement across distribution center networks. ERCOT grid operators negotiate demand response agreements with fleet operators for vehicle-to-grid revenue streams. The Dallas-Fort Worth metroplex hosts expanding last-mile delivery electrification programs.
Michigan
Automotive engineering talent concentration supports battery pack assembly and electric powertrain development for commercial vehicle platforms. NHTSA safety rulemaking consultations engage Detroit-area manufacturer technical centers for crashworthiness standard development. The Detroit-Warren corridor maintains prototype testing infrastructure for heavy-duty electric platforms.
Southeast
IRA domestic assembly incentives are attracting cell and pack manufacturing investment to Georgia and Tennessee industrial sites. Utility-scale charging hub projects face shorter interconnection queues compared to congested coastal ISO regions. The Atlanta metropolitan area serves as a regional distribution hub for electric commercial vehicle deployment.
Pacific Northwest
Hydrogen hub funding from the Department of Energy concentrates fuel-cell truck pilot programs along the I-5 freight corridor. Bonneville Power Administration hydroelectric surplus supports low-carbon charging economics for fleet operators. Seattle-Tacoma port complexes mandate zero-emission drayage vehicle transitions under municipal sustainability ordinances.
US Electric Mobility Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue purpose-built platforms for fleet-specific applications. The market structures around three tiers: vertically integrated cell manufacturers, commercial vehicle specialists with charging infrastructure bundling, and passenger-focused automakers adapting sedan and SUV architectures. Competitive positioning depends on battery supply security and direct fleet relationship depth. Primary competitive moves include multi-source cell contracting and dedicated service channel construction for logistics operators.
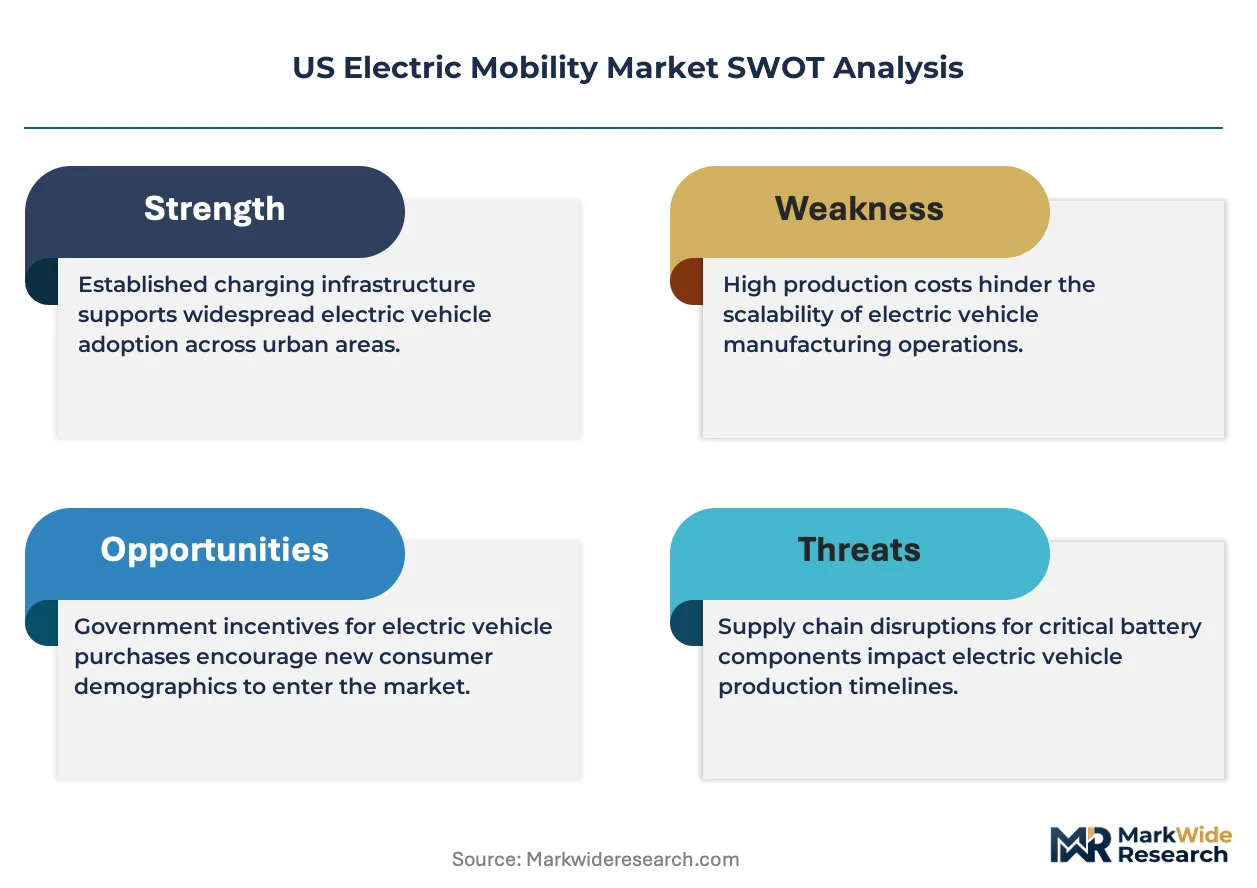
Among US-based electric vehicle manufacturers, Tesla and Rivian occupy distinct archetype positions within the competitive landscape. Tesla exemplifies vertical integration advantages through Nevada-based cell production serving premium passenger segments. Rivian represents the purpose-built commercial platform specialist category with logistics-operator-focused design. Ford anchors the legacy automaker transition archetype, leveraging established fleet service relationships for commercial truck electrification. Lucid Motors sits within the premium sedan technology-intensive tier. ChargePoint and WiTricity represent charging infrastructure hardware specialists competing for NEVI-funded highway corridor locations and wireless induction pilot deployments respectively.
| Leading Market Players |
|---|
| Lucid Motors |
| ChargePoint |
| Tesla |
| Stellantis |
| WiTricity |
| Rivian |
| Ford |
| Volvo Cars |
| General Motors |
| Others |
Cost & Logistics Intelligence
Lithium iron phosphate chemistry migration is compressing cell production costs while redistributing supply chain leverage toward cathode material specialists with captive mining offtake. This transition simultaneously lowers thermal management overhead for fleet operators and concentrates procurement power among cell manufacturers with integrated upstream positions.
Pricing Analysis
Input-cost pass-through from lithium carbonate and nickel sulfate volatility is compressing margins for pack assemblers lacking long-term offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates Tesla's vertically integrated premium positioning from Ford's fleet-bundled commercial offerings and emerging LFP-based economy alternatives. Pricing pressure stems from IRA domestic content bonuses rewarding localized assembly. Fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny, while premium passenger buyers remain least sensitive to cell cost fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cobalt and lithium refining capacity, which feeds the majority of global cathode precursor production. The US electric mobility supply chain draws from Australian spodumene mining, Chilean lithium brine extraction, and Indonesian nickel processing for diversified upstream feedstock. Tariff exposure on Chinese-processed materials threatens cost predictability for automakers without alternative supplier qualification. Distribution runs through Tier 1 pack integrators supplying final assembly plants in Michigan, Tennessee, and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Electric Mobility Market functions as a regulatory compounder where EPA emissions benchmarks and IRA manufacturing credits accelerate fleet turnover cycles beyond organic replacement rates.
For Market Incumbents: Deepen captive cell supply through Southeast-based joint ventures to hedge against Chinese processing concentration. Secure NHTSA safety certification leadership for high-voltage architectures before 2027 model year compliance windows tighten. Prioritize fleet service channel density in Texas Triangle distribution corridors where depot charging feasibility anchors medium-duty truck procurement. For New Entrants and Emerging Players: Begin with wireless charging hardware pilots at municipal bus depots, where operational integration testing lacks established vendor relationships. Target underpenetrated hydrogen corridor infrastructure along I-5 freight routes where fuel-cell truck alternatives remain supply-constrained. Pursue direct utility partnerships for vehicle-to-grid revenue sharing rather than competing against entrenched charging network incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among commercial vehicle charging infrastructure specialists with FERC interconnection queue management capabilities. Long-term viability hinges on exposure to fleet operator consolidation rather than consumer passenger volatility. Monitor EPA rulemaking timelines as the primary inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in LFP cell volume from Southeast assembly plants qualifying for IRA credits. |
| Charging Infrastructure Partnership | Secures NEVI-funded highway corridor locations ahead of Electrify America expansion. |
| Software-Defined Vehicle Investment | Enables over-the-air battery optimization reducing fleet degradation costs. |
| Geographic Manufacturing Footprint | Positions pack assembly within Texas Triangle freight corridors for logistics proximity. |
| Platform Standardization | Reduces component variance across medium-duty truck and delivery van architectures. |
Research Approach
Direct dialogue with OEM platform engineers, fleet procurement directors, utility demand response managers, and charging infrastructure developers grounded qualitative assessments in operational reality. Secondary validation drew from EPA emissions filings, NHTSA safety rulemaking dockets, FERC interconnection queue data, and IRA tax credit implementation guidance. Bottom-up cell demand modeling triangulated against top-down vehicle registration projections across the analysis window.
Output metrics combined unit shipment forecasts with content-per-vehicle estimates for battery capacity, charging hardware, and power electronics. Segmentation dimensions spanned vehicle class, propulsion architecture, fleet versus consumer end use, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting calibrated to historical fleet turnover patterns and policy incentive phase-out schedules.
Caveats apply where FERC interconnection delays, critical mineral export restrictions, or grid reliability events could materially shift the outlook. Forecasts reflect assumptions about IRA credit continuity and EPA rulemaking finalization without presuming specific administrative actions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Transporters Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
North America Electric Truck Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Poland E-Bike Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
Light Electric Vehicle Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
China Electric Bus Market
Electric Vehicles
BEV On-Board Charger Market