
 Middle East and Africa Automated Guided Vehicles Market | 2026-2036
Middle East and Africa Automated Guided Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Automated Guided Vehicles Market Foresight
The Middle East and Africa Automated Guided Vehicles Market is pivoting along a widening gap between premium LIDAR-guided systems and commodity magnetic-track installations. Daifuku Co Ltd leverages its deep integration with port automation projects to dominate high-value installations across Jebel Ali and King Abdullah Port. Dematic Corp sustains competitive positioning through specialized software layers that orchestrate mixed fleets of tugger vehicles and mobile robots in regional distribution centers.
Automated Guided Vehicles are self-propelled material handling systems that navigate via embedded guidance technologies—LIDAR, magnetic tape, vision cameras, or inductive wire—typically operating at speeds up to 2 meters per second while carrying loads from 500 kilograms to 50 tonnes. Their primary purpose is to eliminate manual forklift circuits in repetitive, high-throughput environments such as assembly lines and inventory management vaults. Unit load cars currently anchor the installed base across Gulf manufacturing facilities, yet mobile robots represent the fastest-expanding category as vision navigation costs decline and retrofit complexity drops. Warehousing end users command the dominant share of new orders, though healthcare logistics in South African hospital networks is emerging as a concentrated margin pool for specialized compact platforms.
Saudi Arabia's SFDA and the UAE's MOHAP are tightening safety certification requirements for autonomous equipment deployed in pharmaceutical and food-grade facilities, directly shaping product design standards for regional suppliers. CE marking alignment and EU AI Act proximity rules are pressuring Gulf-based integrators to preemptively embed explainable navigation logging in systems destined for re-export to European supply chain partners. Stakeholders must weigh whether to prioritize backward integration into sensor hardware or deepen software differentiation as local assembly incentives under Saudi and Emirati industrial policies reshape cost structures.
Market Dynamics
Vision-guided navigation is compressing deployment timelines for Automated Guided Vehicles across Middle East warehousing, collapsing the traditional 12-week magnetic tape installation into 48-hour commissioning cycles that bypass infrastructure retrofit entirely.
Growth Catalysts
- Vision 2030 Industrial Automation Targets:Saudi Arabia's national transformation program mandates autonomous material handling systems in new manufacturing zones, channeling sovereign capital toward AGV fleet procurement.
- Logistics Free Zone Expansion:Dubai South and Jebel Ali Port are embedding AGV networks into multimodal cargo operations, creating anchor demand for high-throughput unit load carriers.
- E-commerce Fulfillment Density:Gulf Cooperation Council warehousing operators are scaling automated storage and retrieval integration to manage peak seasonal volumes exceeding manual forklift capacity.
Market Restraints
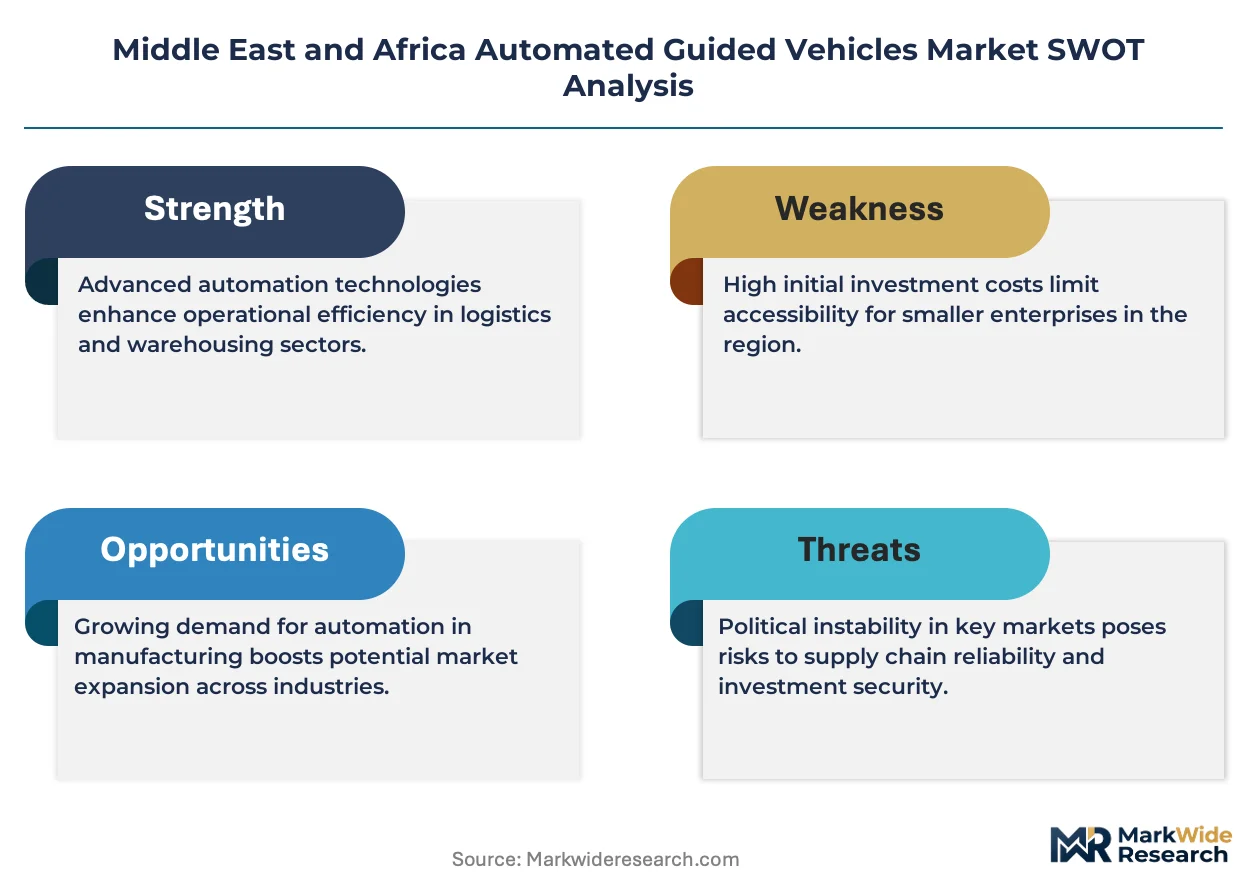
- LIDAR Sensor Supply Concentration:Premium navigation hardware depends on concentrated Asian component suppliers, exposing integrators to 16-week lead time volatility and currency fluctuation pass-through.
- Magnetic Track Infrastructure Lock-in:Existing Gulf manufacturing facilities with deployed tape-guided systems face high switching costs that delay technology refresh cycles.
- Safety Certification Friction:Saudi SFDA and UAE MOHAP pharmaceutical-grade facility requirements impose extended validation timelines that compress vendor margins on compact platform deliveries.
Strategic Opportunities
- South African Healthcare Logistics:Hospital network central sterile supply departments represent concentrated demand for specialized narrow-aisle mobile robots with bioburden-resistant enclosures.
- EU AI Act Alignment:Gulf-based integrators embedding explainable navigation logging gain preferential positioning for re-export contracts to European supply chain partners.
- Local Assembly Incentives:Saudi and Emirati industrial policies offering tariff relief for in-country sensor integration are reshaping cost structures for regional system builders.
Industry Challenges
- Commissioning Engineer Scarcity:Vision navigation calibration and fleet management software configuration require specialized technicians that Gulf technical institutes have not yet trained at scale.
- Legacy Warehouse Management System Integration:Older ERP platforms in regional distribution centers lack API compatibility with modern AGV orchestration layers, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Automated Guided Vehicles Market |
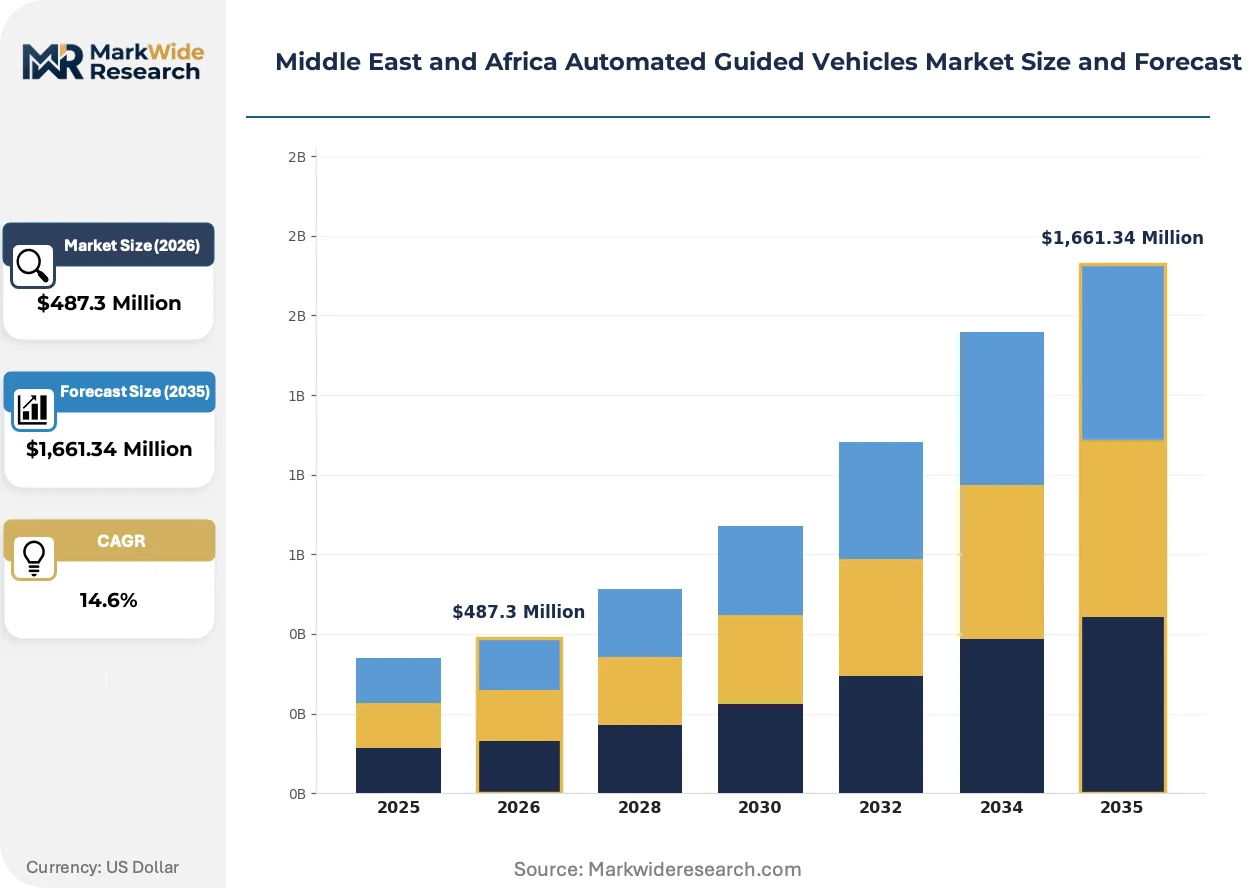
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unit Load Cars, Tugger Vehicles, Automated Pallet Jacks, Mobile Robots End User: Manufacturing, Warehousing, Retail, Healthcare Technology: LIDAR, Magnetic Guidance, Vision Navigation, Inductive Guidance Application: Assembly Lines, Inventory Management, Order Fulfillment, Transportation |
| Companies Covered | Daifuku Co Ltd, Dematic Corp, Jungheinrich AG, Konecranes Plc, Murata Machinery Ltd, Toyota Industries Corporation, KUKA Group, Swisslog Holding AG, SSI Schaefer AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Automated Guided Vehicles Market Shifts & Advancements
Natural feature recognition is collapsing the cost barrier between fixed-path and free-navigation Automated Guided Vehicles, enabling retrofit deployment in legacy Gulf warehousing without infrastructure modification.
LIDAR-based simultaneous localization and mapping is overtaking magnetic tape guidance as the default navigation architecture for new Middle East installations. E-commerce fulfillment centers in Dubai South are adopting these systems at accelerated pace to accommodate dynamic route optimization. This shift is compressing the addressable market for traditional wire-guided installations while expanding retrofit opportunities in existing facilities.
CE marking alignment requirements under the EU AI Act proximity rules are forcing Gulf integrators to embed audit-ready navigation logging in systems destined for European re-export. Industrial consequence includes mandatory algorithmic transparency documentation that adds 8-12 weeks to product development cycles. Pharmaceutical and food-grade facility deployments across Saudi Arabia and the UAE are most affected, with vendors pre-certifying platforms to avoid downstream customs delays.
Service contract unbundling is fragmenting traditional AGV procurement into separate hardware, software, and maintenance line items. Third-party logistics operators in Jebel Ali Port are driving this shift, preferring subscription-based fleet management platforms over capital purchase models. This pattern is most visible in UAE logistics free zones where operating lease structures dominate new automation investments.
Middle East and Africa Automated Guided Vehicles Market Segmentation
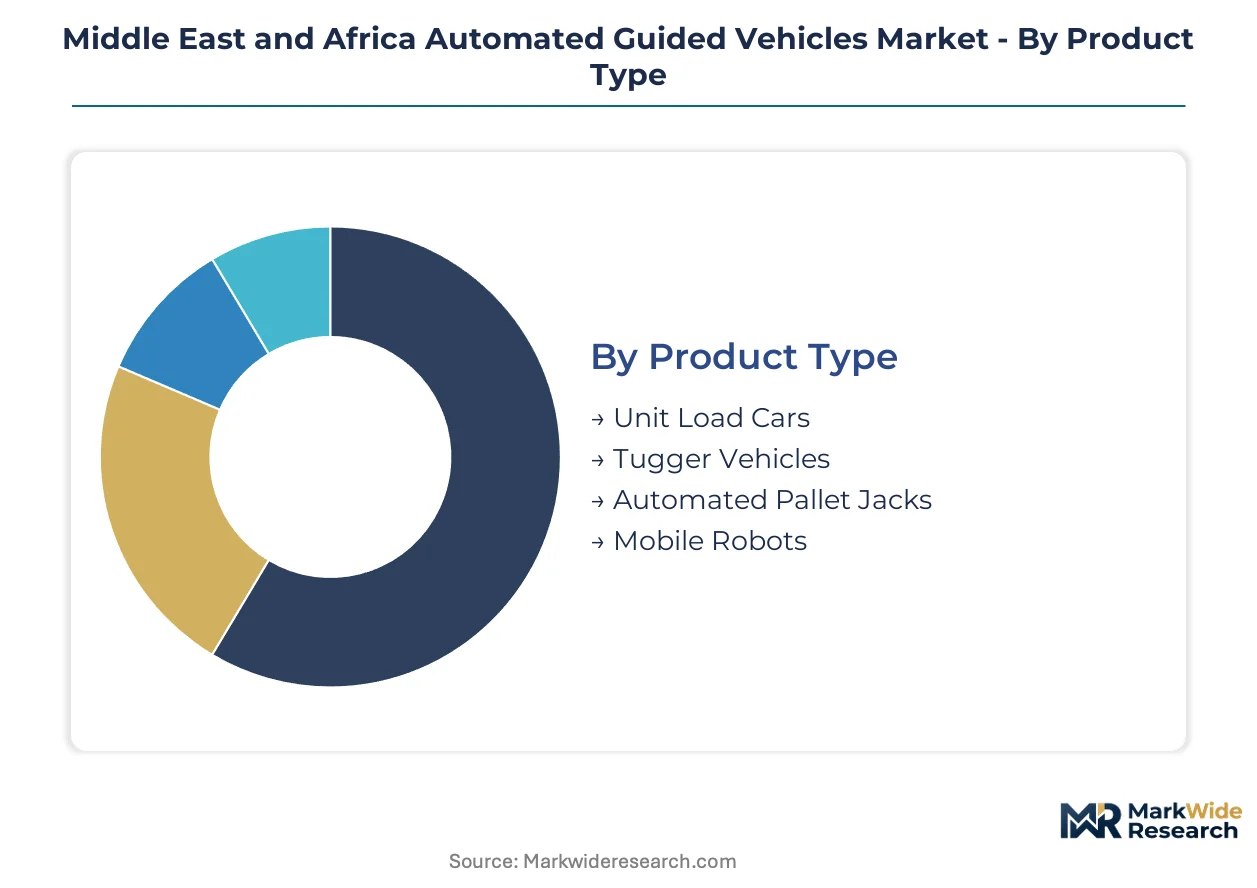
Segmentation in the Middle East and Africa Automated Guided Vehicles Market reveals how capital allocation priorities diverge between established Gulf manufacturing hubs and emerging healthcare logistics corridors. Technology choices and product configurations directly shape deployment economics across Saudi Arabia's Vision 2030 industrial zones and South African hospital networks.
Product Type:
Capital intensity varies sharply across product categories, with heavy-load systems demanding substantially higher upfront investment than compact mobile platforms.
- Unit Load Cars:These platforms handle single pallets or containers up to 2,000 kilograms through fork-based lifting mechanisms. Saudi manufacturing zones and UAE logistics free zones deploy these systems extensively for repetitive inbound material flows. Their mechanical simplicity reduces maintenance overhead but limits flexibility in dynamic routing environments.
- Mobile Robots:Vision-guided autonomous mobile robots navigate without fixed infrastructure using onboard cameras and SLAM algorithms. Dubai South e-commerce fulfillment centers and Jebel Ali Port operators are scaling these fleets to accommodate seasonal volume spikes without facility retrofit. Their software-defined architecture commands premium pricing but collapses commissioning timelines from weeks to days.
- Tugger Vehicles:These systems pull multiple cart trains along defined circuits in automotive assembly plants.
- Automated Pallet Jacks:Compact units serve narrow-aisle warehousing in Saudi pharmaceutical distribution facilities.
Unit Load Cars absorb the bulk of installed capacity across Gulf manufacturing; Mobile Robots are expanding most quickly in UAE logistics corridors.
End User:
Application context determines procurement scale, with multi-facility warehouse operators commanding fleet volumes that dwarf single-site manufacturing deployments.
- Warehousing:Third-party logistics operators in Dubai South and King Abdullah Economic City manage automated storage and retrieval integration at scale. These facilities process e-commerce fulfillment volumes that exceed manual forklift capacity during peak seasons, driving continuous AGV fleet expansion.
- Healthcare:South African hospital central sterile supply departments represent concentrated demand for specialized narrow-aisle platforms with bioburden-resistant enclosures. Saudi SFDA and UAE MOHAP safety certifications shape product specifications for pharmaceutical-grade facility deployments.
- Manufacturing:Automotive and electronics assembly plants in Saudi industrial cities deploy fixed-path systems for just-in-time component delivery.
- Retail:Regional distribution centers serving Gulf Cooperation Council consumer markets adopt mobile robots for back-of-store inventory movement.
Warehousing commands the dominant share of new capital deployment; Healthcare logistics is climbing the fastest as hospital network centralization accelerates across South Africa.
Technology:
Navigation architecture selection directly determines infrastructure retrofit requirements and long-term operational flexibility.
- LIDAR:Laser-based simultaneous localization and mapping enables centimeter-precision positioning without facility modification. Jebel Ali Port and Dubai South fulfillment centers specify these systems for dynamic route optimization in high-throughput environments. Component supply concentration in Asian sensor markets creates procurement lead time exposure.
- Vision Navigation:Camera-based natural feature recognition collapses deployment timelines by eliminating magnetic tape installation. Saudi manufacturing zones with legacy warehousing are adopting these systems to bypass infrastructure retrofit entirely.
- Magnetic Guidance:Tape-based systems anchor existing Gulf manufacturing installations but lock facilities into fixed paths.
- Inductive Guidance:Wire-embedded floor systems persist in automotive assembly applications requiring absolute positional repeatability.
LIDAR systems anchor new high-value installations across UAE logistics hubs; Vision Navigation is gaining share fastest as retrofit demand surges in Saudi industrial cities.
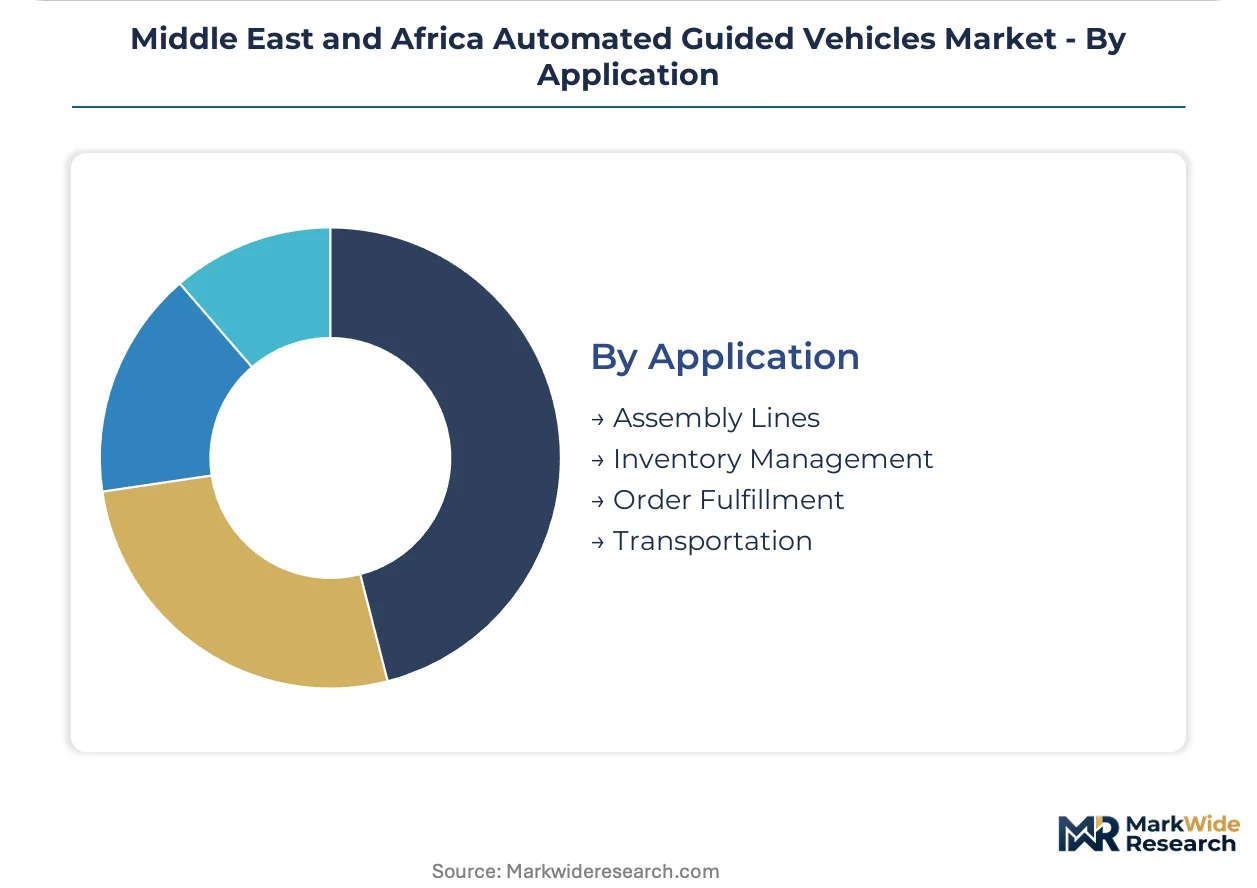
Application:
Operational workflow complexity shapes technology requirements, with transportation applications demanding more sophisticated fleet coordination than static inventory storage.
- Order Fulfillment:Piece-picking and case-picking operations in Dubai South e-commerce facilities require mobile robots with dynamic path replanning capabilities. These systems integrate with warehouse management software to optimize pick sequences across multi-zone layouts.
- Inventory Management:Automated storage and retrieval vaults in Saudi pharmaceutical distribution centers deploy unit load cars for high-density pallet positioning. SFDA validation requirements extend commissioning timelines for these installations.
- Assembly Lines:Sequenced component delivery in automotive plants uses magnetic-guided tugger trains.
- Transportation:Inter-facility material movement across Jebel Ali Port multimodal terminals employs LIDAR-guided carriers.
Inventory Management retains the largest installed base in Gulf manufacturing; Order Fulfillment is expanding most quickly as e-commerce infrastructure scales across UAE logistics free zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port anchors regional demand concentration, with Dubai South and King Abdullah Economic City forming complementary logistics corridors that absorb the majority of AGV fleet deployments across the Gulf.
United Arab Emirates
Dubai South's e-commerce fulfillment centers and Jebel Ali Port's multimodal terminals drive sustained demand for vision-guided mobile robots. MOHAP pharmaceutical-grade facility certifications shape procurement specifications for warehouse operators serving healthcare supply chains. Abu Dhabi's Khalifa Industrial Zone is integrating AGV networks into aluminum processing and aerospace component logistics.
Saudi Arabia
Vision 2030 industrial automation mandates channel sovereign capital toward autonomous material handling in new manufacturing zones. SFDA tightening of safety certification requirements for pharmaceutical facilities extends validation timelines for specialized platform deliveries. King Abdullah Economic City and NEOM Northwest are embedding AGV infrastructure into greenfield industrial developments.
South Africa
Hospital network centralization is accelerating demand for narrow-aisle mobile robots in central sterile supply departments. The country's national health regulator imposes bioburden-resistant enclosure standards that filter supplier qualification. Gauteng province's pharmaceutical distribution corridors concentrate specialized compact platform deployments.
Israel
Defense and aerospace manufacturing clusters generate demand for high-precision automated guided vehicles in component assembly operations. The country's national standards authority aligns certification frameworks with EU AI Act proximity rules for systems destined for European re-export. Tel Aviv metropolitan industrial zones are piloting natural feature recognition navigation in legacy facility retrofits.
Egypt
Suez Canal Economic Zone expansion is attracting logistics operators evaluating AGV integration for transshipment cargo handling. The country's industrial development authority offers tariff relief for automation equipment imports into qualified zones. Alexandria and Port Said port complexes are assessing fleet deployment economics against manual labor cost structures.
Middle East and Africa Automated Guided Vehicles Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates high-value installations around integrated port automation specialists while fragmenting mid-tier warehousing deployments. Japanese and German industrial conglomerates anchor premium-tier positioning through captive sensor supply chains and software orchestration layers. Three strategic archetypes dominate: full-stack port automation integrators, warehouse-focused fleet management platforms, and component-specialist system builders. Competitive dynamics center on M&A consolidation of navigation software capabilities and geographic expansion into Gulf logistics free zones through local partnership structures.
Among Japanese industrial conglomerates, Daifuku Co Ltd and Toyota Industries Corporation exemplify the full-stack integration archetype, leveraging deep project experience in port automation to anchor high-value installations. Dematic Corp represents the warehouse-centric fleet orchestration model, with software-defined architectures that compress commissioning timelines for e-commerce fulfillment operators. These three companies occupy positions across the premium-mid-tier spectrum, with geographic origin and corporate structure signaling divergent approaches to regional market development.
| Leading Market Players |
|---|
| Daifuku Co Ltd |
| Dematic Corp |
| Jungheinrich AG |
| Konecranes Plc |
| Murata Machinery Ltd |
| Toyota Industries Corporation |
| KUKA Group |
| Swisslog Holding AG |
| SSI Schaefer AG |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers in Saudi Arabia and the UAE anchor supply-side discipline through local assembly incentives that compress landed costs for regional integrators while forcing price competition on foreign entrants lacking tariff relief. Japanese and German industrial conglomerates defend premium positioning through captive sensor supply chains, whereas mid-tier warehouse fleet operators drive subscription-based pricing fragmentation across Gulf logistics free zones.
Pricing Analysis
Throughput-linked service contracts anchor value-based pricing for AGV deployments across Jebel Ali Port and Dubai South fulfillment centers, with operators paying per pallet-move rather than capital purchase. Three-tier pricing structure across premium LIDAR-guided systems, standard vision-navigation platforms, and economy magnetic-track configurations reflects certification grade and software orchestration depth. Cost compression in the economy tier intensifies because Chinese component suppliers are flooding Gulf markets with unbundled hardware kits. Third-party logistics operators in UAE free zones exhibit highest price sensitivity due to operating lease structures, while Saudi pharmaceutical facilities under SFDA mandates accept premium pricing for validated platforms.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Saudi Vision 2030 industrial zones and UAE port automation projects, bypassing distribution intermediaries for multi-million-dollar fleet contracts. LIDAR sensor production concentrates in Japan, South Korea, and select Chinese manufacturing hubs, with navigation software development anchored in Germany and the United States. Regional system builders draw from Taiwanese semiconductor foundries for embedded controllers and German precision drive manufacturers for motion systems. Single-source vulnerability in Asian LIDAR component supply exposes integrators to procurement disruption. Distribution runs through local assembly partnerships in Saudi Arabia's King Abdullah Economic City and UAE's Khalifa Industrial Zone.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Automated Guided Vehicles Market is navigating a technology-transition phase as vision-guided navigation displaces magnetic tape infrastructure across legacy Gulf warehousing facilities.
For Market Incumbents: Deepen software orchestration differentiation to defend against unbundled hardware competitors from Chinese component suppliers threatening margin compression. Prioritize backward integration into sensor calibration capabilities to reduce dependency on concentrated Asian LIDAR supply chains. Lock in long-term service contracts with Dubai South and Jebel Ali Port operators before subscription-based pricing fully commoditizes fleet management platforms. For New Entrants and Emerging Players: Capture South African healthcare logistics corridors where hospital network centralization creates concentrated demand for bioburden-resistant narrow-aisle platforms with limited incumbent penetration. Target Saudi pharmaceutical distribution facilities facing extended SFDA validation timelines that favor agile specialized suppliers over bureaucratic conglomerates. Lead with rapid 48-hour commissioning propositions that exploit vision navigation's infrastructure-free deployment advantage against tape-guided legacy systems. For Investors and Strategic Acquirers: King Abdullah Economic City and NEOM Northwest greenfield automation announcements are the leading indicator that sovereign capital allocation toward AGV infrastructure will sustain multi-year deployment cycles. Position acquisition screening around navigation software specialists with EU AI Act compliance capabilities for European re-export positioning. Watch for commissioning engineer training program launches at Gulf technical institutes as the signal that local talent scarcity is resolving sufficiently to support scaled fleet rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Navigation Software Acquisition | Consolidates fleet orchestration capabilities as unbundled procurement fragments hardware margins across UAE logistics operators. |
| Local Assembly Partnership | Unlocks Saudi and Emirati tariff relief for sensor integration while shortening delivery timelines to Vision 2030 industrial zones. |
| EU AI Act Compliance Certification | Positions Gulf-based integrators for preferential re-export contracts to European pharmaceutical supply chain partners. |
| Healthcare Logistics Specialization | Captures concentrated margin pools in South African hospital central sterile supply departments with bioburden-resistant platform variants. |
| Commissioning Engineer Training Program | Addresses capability scarcity that currently constrains vision navigation deployment velocity across Saudi manufacturing retrofits. |
Research Methodology
Trade flow databases, customs clearance records, and industrial automation equipment registration filings formed the secondary backbone for installed base estimation across Gulf Cooperation Council member states. Primary interviews with port automation project directors, warehouse fleet procurement managers, pharmaceutical facility validation engineers, and AGV system integration specialists informed deployment timeline assumptions and technology transition patterns. Bottom-up unit economics for LIDAR, vision navigation, and magnetic guidance configurations were triangulated against top-down capital expenditure tracking from Saudi Vision 2030 and UAE logistics free zone development authorities.
Historical trendline analysis of AGV adoption intensity in comparable port automation and e-commerce fulfillment markets established baseline penetration curves for the projection horizon. Segmentation modeling incorporated product type, navigation technology, end-use application, and geographic regulatory cluster dimensions across the analysis window. CAGRs were derived from fitted adoption curves weighted by sovereign capital commitment visibility and infrastructure commissioning schedules. Forecast inputs included LIDAR sensor cost decline trajectories and vision navigation algorithm performance benchmarks from semiconductor industry disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Saudi SFDA and UAE MOHAP regulatory evolution, Asian component supply disruption, and Gulf technical institute training program effectiveness. Forecasts reflect documented assumptions regarding sovereign capital allocation continuity and e-commerce fulfillment volume growth. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Autonomous Truck Technology Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Global Driverless Car Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market
Autonomous Vehicles
Autonomous Delivery Robots Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) and Blind Spot Detection (BSD) Market
Autonomous Vehicles
Latin America ADAS Market