
 Electric Vehicle Rental Market | 2026-2036
Electric Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Rental Market Insights
Corporate fleet managers are unwinding long-standing reliance on daily tourist rentals as the dominant revenue archetype. Enterprise Holdings Inc. leverages its airport dominance to capture business traveler EV demand, while Sixt SE differentiates through premium EV positioning in European urban cores. Zoomcar anchors its model on subscription-based access in dense Asian metro corridors, competing with asset-light local aggregators.
Electric vehicle rental denotes short-to-medium-term mobility access to battery-electric passenger or light commercial vehicles, typically governed by state-of-charge protocols, connector-type compatibility, and residual battery guarantees at return. The service exists to decouple transportation utility from vehicle ownership burdens, serving intermittent-use patterns across corporate, leisure, and municipal buyer sets. Sedan and SUV categories within vehicle type lead current fleet composition, though van segments are gaining structural weight as last-mile logistics operators electrify. Short-term rental duration pools generate the highest transaction velocity, yet subscription pricing models are capturing expanding margin pools through predictable recurring revenue structures.
The EPA tailpipe standards and EU Green Deal framework jointly compress internal-combustion fleet economics, redirecting procurement budgets toward zero-emission rental assets. NHTSA crash-test protocols and ISO battery safety standards further shape vehicle eligibility and insurer willingness to underwrite EV rental portfolios. Stakeholders must monitor charging interoperability mandates and battery degradation liability frameworks as these rules will determine which fleet operators can scale profitably.
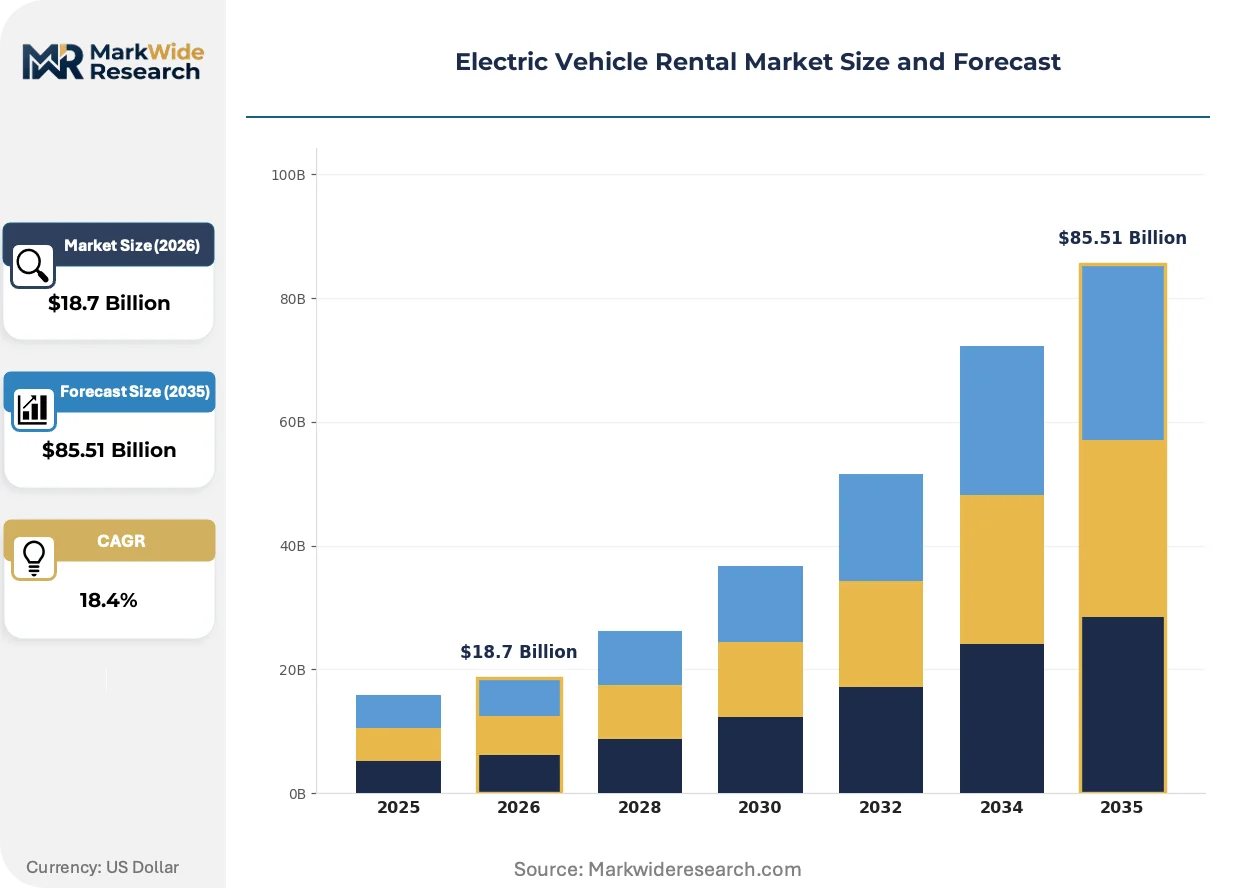
Market Dynamics
Fleet procurement budgets are rechanneling from internal-combustion assets toward zero-emission rentals as EPA tailpipe standards and EU Green Deal emissions frameworks compress legacy vehicle economics. Battery swapping infrastructure deployment is compressing dwell times and unlocking new rental use cases previously uneconomical for electrified fleets.
Growth Catalysts
- EU Green Deal emissions rules:Corporate fleet managers face tightening sustainability mandates that redirect procurement toward zero-emission rental assets. The framework accelerates electrification timelines across European logistics operators.
- Battery swapping infrastructure:Dense swapping station networks in Chinese and German urban corridors eliminate range anxiety for short-term renters. The technology reduces vehicle downtime and expands addressable trip profiles.
- Last-mile logistics electrification:E-commerce fulfillment operators in the United States are electrifying van fleets through rental models to avoid capital-intensive ownership. This demand concentrates in California and New York metro areas with zero-emission delivery zones.
Market Restraints
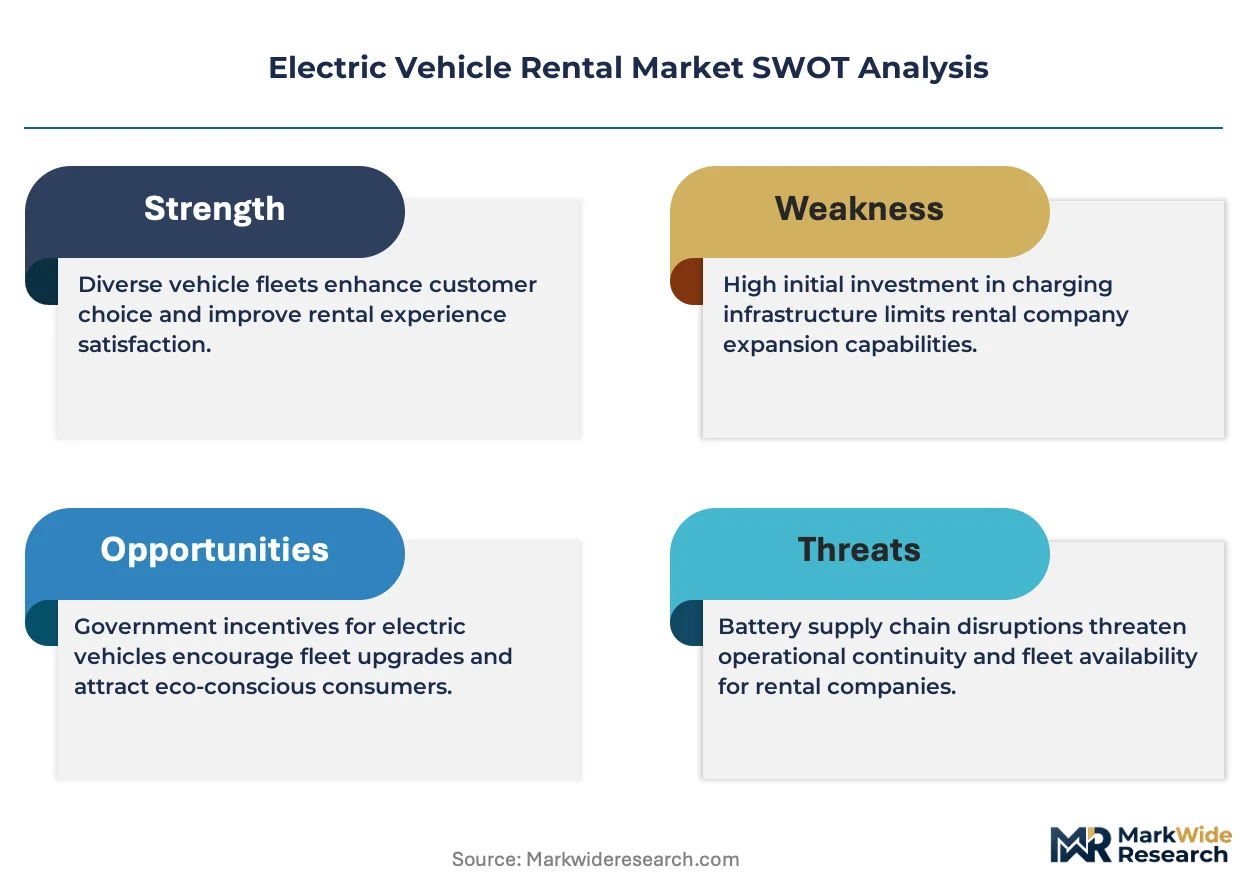
- Lithium-ion cell supply concentration:Cathode and cell production clusters in China create geopolitical exposure for fleet operators dependent on battery supply continuity. Western rental firms face input cost volatility from concentrated upstream refining.
- Residual battery value uncertainty:Depreciation curves for high-mileage rental EVs remain poorly modeled, constraining insurer willingness to underwrite fleet portfolios. ISO battery safety standards provide limited guidance on secondary-use valuation.
- Charging interoperability fragmentation:Connector-type incompatibility across North American, European, and Asian markets forces fleet operators to maintain redundant charging hardware. NHTSA has not mandated unified connector protocols.
Strategic Opportunities
- Subscription pricing models:Predictable recurring revenue structures capture expanding margin pools from corporate buyers seeking to decarbonize mobility without ownership burdens. The model concentrates in dense Asian metro corridors.
- Vehicle-to-grid integration:Bidirectional charging capability converges with utility demand-response programs, enabling rental fleets to monetize stationary battery assets. German grid operators pilot vehicle-to-grid tariffs with commercial fleet partners.
- Municipal zero-emission zones:City-level access restrictions in London, Paris, and Amsterdam create captive demand for compliant rental EVs. Operators with pre-positioned electric fleets capture displacement from banned internal-combustion vehicles.
Industry Challenges
- Battery degradation liability frameworks:Ambiguous state-of-charge guarantees at return create dispute exposure between renters and fleet operators. Contract standardization lags behind fleet electrification velocity.
- Charging infrastructure capex intensity:Depot electrification for commercial rental hubs requires substantial capital outlay for grid upgrades and high-power dispensers. Smaller operators face financing constraints for site hardening.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Rental Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Van Rental Duration: Short-term, Long-term, Monthly, Daily Customer Type: Corporate Clients, Individual Renters, Tourists, Government Contracts Pricing Model: Flat Rate, Per Mile, Subscription, Tiered Pricing |
| Companies Covered | Avis Budget Group Inc., Enterprise Holdings Inc., The Hertz Corporation, Europcar Mobility Group, Sixt SE, Zoomcar, Green Motion International, Ekar, UFODrive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Rental Market Trends and Innovations
Technology convergence and regulatory compression are reshaping how rental fleets acquire, deploy, and monetize electric assets. Three distinct vectors dominate competitive positioning.
Vehicle-to-grid bidirectional charging is supplanting unidirectional fleet charging as the default infrastructure specification for commercial rental operators. Large fleet buyers in Germany and the Netherlands now require bidirectional capability in procurement tenders. The technology enables revenue stacking from grid services, compressing total cost of ownership calculations that previously disadvantaged electrified fleets against diesel alternatives.
EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates are forcing rental operators to accelerate fleet turnover timelines. The regulatory compression eliminates residual value recovery windows for internal-combustion assets. Corporate fleet buyers in the United States are responding by shifting from ownership to rental models that transfer obsolescence risk to fleet operators.
Corporate mobility managers are unbundling transportation utility from vehicle ownership through subscription-based access contracts. The procurement model disrupts traditional daily-rate pricing structures that dominated leisure and business traveler segments. This behavioral shift concentrates in German and Chinese urban cores where dense charging networks enable predictable monthly pricing without range contingency buffers.
Electric Vehicle Rental Market Segmentation
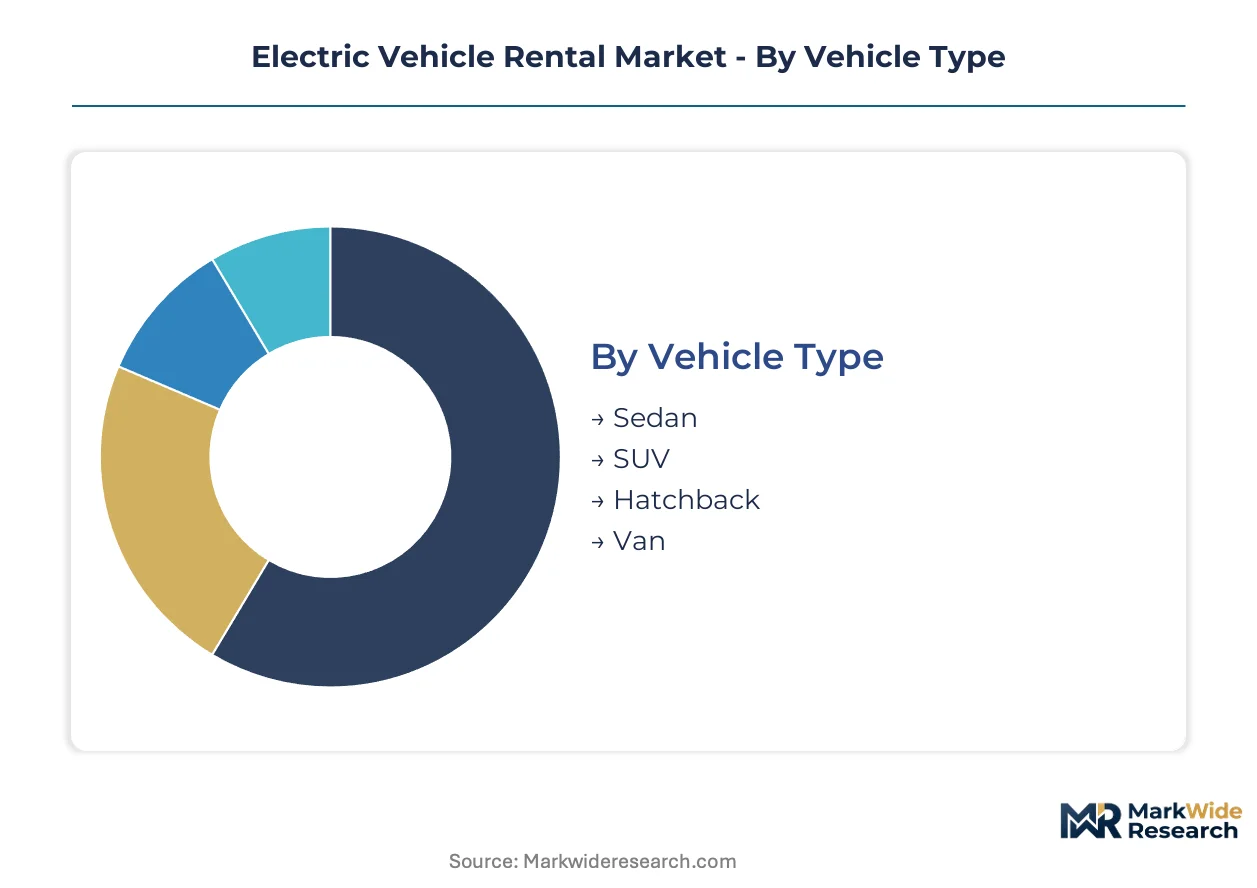
Segmentation reveals how EV rental demand fragments across use cases, procurement patterns, and pricing tolerance. Fleet operators configure vehicle mix, duration structures, and billing mechanics to match distinct mobility utility requirements.
Vehicle Type:
Channel mix varies sharply by vehicle category, with airport counters and urban hubs stocking different compositions than last-mile logistics depots.
- Sedan:Compact battery-electric sedans dominate corporate traveler procurement through airport rental counters. Germany's dense autobahn charging network and California's business corridors concentrate demand for single-occupant executive transport with predictable range profiles.
- SUV:Mid-size electric SUVs command premium positioning in European urban cores and Chinese tier-one cities. Family leisure travelers and suburban corporate shuttle contracts drive procurement, with battery capacity above 75 kWh becoming standard for fleet eligibility.
- Hatchback:Urban micro-mobility fleets in Amsterdam, Paris, and Singapore deploy compact hatchbacks for short-trip density. Municipal zero-emission zone compliance accelerates replacement of internal-combustion city car rentals.
- Van:Light commercial electric vans flow through logistics operator contracts and tradesmen rental programs. E-commerce fulfillment electrification in New York and Los Angeles metro areas expands addressable fleet deployment.
By volume, Sedan leads current fleet composition. By growth pace, Van segments are expanding most quickly as delivery electrification mandates tighten.
Rental Duration:
Duration structures align with customer liquidity preferences and asset utilization economics, with subscription models capturing recurring revenue pools.
- Short-term:Hourly and single-day rentals generate highest transaction velocity through app-based urban access. Chinese and German operators leverage dense charging infrastructure to support impulse-trip economics without range buffers.
- Long-term:Multi-week corporate assignments and extended leisure travel drive this category. Fleet operators in the United States price weekly rates to compete with lease-like ownership alternatives for temporary relocations.
- Monthly:Subscription billing converges with corporate mobility budgets seeking to decarbonize without capital deployment. Dense Asian metro corridors anchor this model's expansion.
- Daily:Traditional 24-hour pricing persists in tourist-heavy markets and insurance replacement fleets. Airport-dominant operators maintain this structure for business traveler convenience.
By transaction count, Short-term rentals dominate. By margin expansion, Monthly subscriptions are climbing the fastest as procurement shifts from ownership to access.
Customer Type:
Buyer categories determine fleet specification, contract terms, and residual risk allocation across rental portfolios.
- Corporate Clients:Enterprise mobility managers negotiate subscription contracts with sustainability reporting requirements. EU Green Deal compliance timelines redirect procurement budgets from owned fleets to rental structures that transfer obsolescence risk.
- Individual Renters:Personal mobility access concentrates in urban cores with charging infrastructure density. Weekend leisure trips and vehicle ownership gaps drive intermittent demand.
- Tourists:International leisure travelers at airport hubs generate seasonal demand spikes. Premium SUV positioning captures this segment in European destination markets.
- Government Contracts:Municipal fleet electrification mandates and public agency vehicle pools create stable procurement volume. California state contracts and German federal leasing programs anchor this channel.
By contract value, Corporate Clients lead. By procurement velocity, Individual Renters are gaining share fastest as urban charging networks mature.
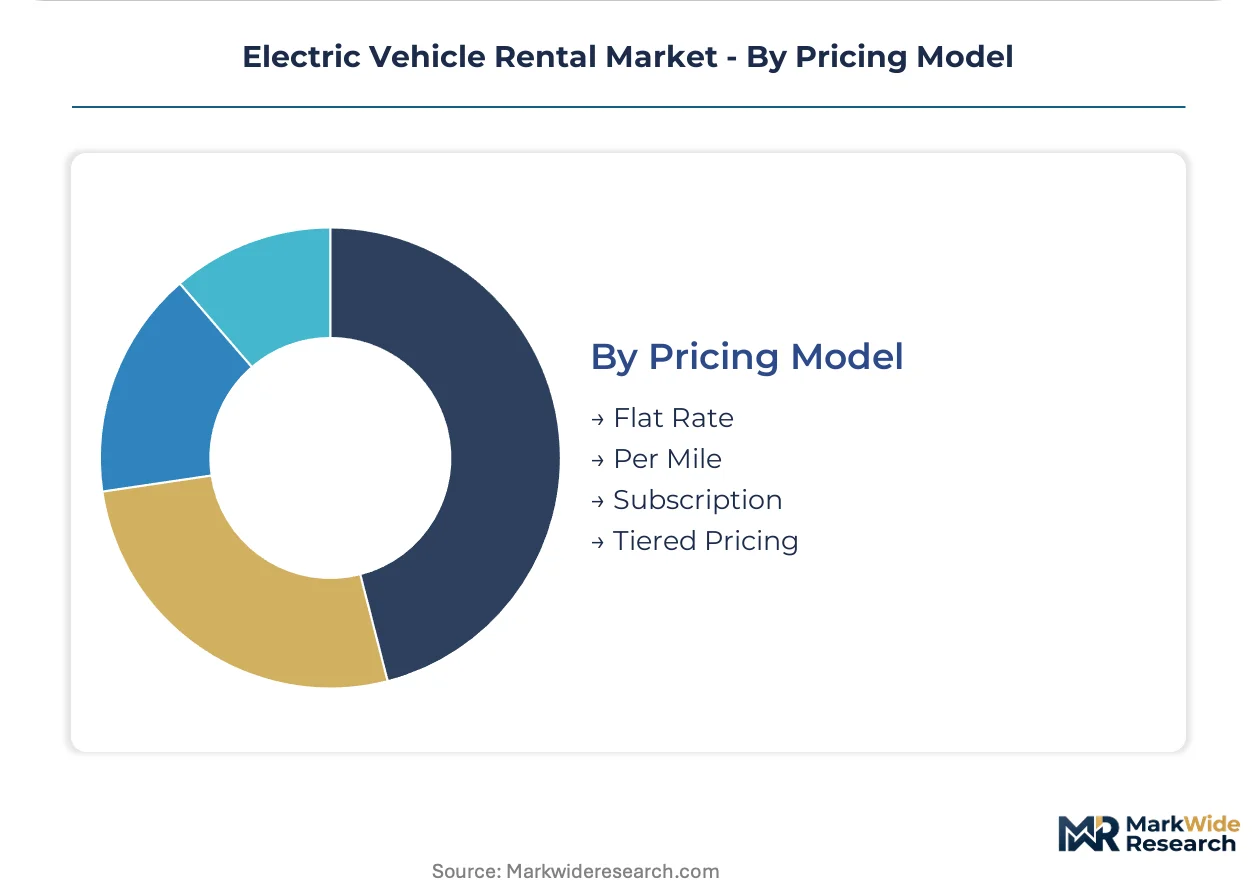
Pricing Model:
Billing mechanics segment customers by risk tolerance, trip predictability, and integration with corporate expense systems.
- Flat Rate:All-inclusive daily or weekly pricing eliminates range anxiety for risk-averse leisure travelers. Airport operators deploy this structure to compete with ride-hailing alternatives.
- Per Mile:Usage-based billing aligns costs with actual vehicle deployment, common in logistics operator contracts. Telematics integration enables accurate reconciliation for commercial van rentals.
- Subscription:Fixed monthly fees with bundled charging access capture corporate buyers seeking budget predictability. German and Chinese operators lead this model's structural expansion.
- Tiered Pricing:Vehicle class stratification separates premium, standard, and economy access levels. Fleet operators use this to optimize yield across battery capacity and interior specification tiers.
By revenue concentration, Flat Rate persists. By model innovation, Subscription billing shows the steepest expansion trajectory as recurring revenue structures displace transactional pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports battery-electric rental fleet assets to corporate buyers across the Netherlands and Scandinavian markets, with logistics operators in Hamburg and Rotterdam anchoring cross-border procurement flows.
United States
Corporate fleet managers in California and New York metro areas accelerate EV rental procurement ahead of zero-emission delivery zone enforcement. EPA tailpipe standards and California Air Resources Board mandates compress internal-combustion fleet economics. Los Angeles and San Francisco concentrate subscription-based rental deployment for last-mile logistics operators.
China
Dense battery swapping networks in Shenzhen and Shanghai unlock short-term rental use cases previously uneconomical for electrified fleets. MIIT charging interoperability mandates and dual carbon goals redirect municipal procurement toward zero-emission rental structures. Yangtze River Delta logistics corridors anchor van rental demand from e-commerce fulfillment operators.
Germany
Corporate mobility managers in Munich and Frankfurt negotiate subscription contracts with EU Green Deal compliance reporting requirements. KBA vehicle-type approval protocols and federal leasing programs accelerate municipal fleet electrification. Bavaria and North Rhine-Westphalia concentrate vehicle-to-grid pilot programs with commercial rental partners.
United Kingdom
London's ultra-low emission zone creates captive demand for compliant rental EVs among tradesmen and small logistics operators. Transport for London congestion charging rules and national net-zero mandates redirect procurement budgets from owned fleets to rental access. Southeast England and Greater Manchester anchor premium SUV positioning for airport business traveler segments.
Netherlands
Amsterdam municipal zero-emission zones displace internal-combustion vehicle access, concentrating rental demand in Randstad urban cores. EU Green Deal framework and national climate agreement timelines compress legacy fleet economics. Eindhoven Region charging infrastructure density enables predictable subscription pricing without range contingency buffers.
Electric Vehicle Rental Market Competitive Landscape
Player mix skews toward legacy fleet operators with airport dominance and asset-light digital platforms with urban subscription models. Market structure consolidates around three archetypes: multinational rental conglomerates with electrified fleet conversion programs, regional specialists with premium EV positioning, and app-based aggregators with dense metro coverage. Dominant competitive moves include strategic partnerships with charging network operators and portfolio diversification into subscription billing structures.
Within the legacy conglomerate tier, Enterprise Holdings Inc. and Avis Budget Group Inc. occupy positions representing airport-centric fleet conversion strategies. Sixt SE exemplifies premium-tier European positioning. Among asset-light platforms, Zoomcar anchors subscription-based access archetypes in Asian metro corridors. Green Motion International and Ekar sit within sustainability-focused specialist positioning, while UFODrive represents urban digital-native entry models.
| Leading Market Players |
|---|
| Avis Budget Group Inc. |
| Enterprise Holdings Inc. |
| The Hertz Corporation |
| Europcar Mobility Group |
| Sixt SE |
| Zoomcar |
| Green Motion International |
| Ekar |
| UFODrive |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal emissions frameworks gate both fleet asset qualification and subscription pricing tiers simultaneously, compressing legacy internal-combustion economics while enabling premium zero-emission positioning. Corporate mobility managers now face dual constraints: vehicles must satisfy KBA type-approval protocols and ISO battery safety standards to enter rental pools, while pricing structures must absorb residual value uncertainty that insurers price into fleet underwriting.
Pricing Analysis
Next-generation battery platforms with solid-state chemistry command 40-60% rental rate premiums over current lithium-ion fleets, while prior-generation vehicles face accelerated depreciation curves. Three-tier pricing structure across premium, standard, and economy levels segments corporate subscribers from impulse urban renters and insurance replacement pools. Cost compression in the economy tier stems from battery degradation liability disputes eroding margin predictability. Logistics operators exhibit highest price sensitivity due to telematics-enabled usage transparency, while corporate mobility managers prioritize budget predictability over per-mile optimization.
Supply Chain Analysis
Port congestion along Shanghai-Rotterdam trade lanes elevates inbound logistics costs for European fleet operators sourcing vehicles from Chinese manufacturing hubs. Cathode and cell production clusters in China, South Korea, and Japan concentrate upstream battery supply, while vehicle assembly feeds from German, Chinese, and Mexican production bases. Raw material dependencies span lithium carbonate, nickel sulfate, and cobalt hydroxide refined through concentrated upstream nodes. Single-source vulnerability in semiconductor-grade graphite creates chokepoint exposure. Distribution runs through captive charging infrastructure partnerships and airport-hub depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among corporate fleet managers negotiating multi-year subscription contracts with sustainability reporting requirements, fragmenting price-setting autonomy for rental operators. This shift demands differentiated defensive postures across incumbent, entrant, and investor archetypes.
For Market Incumbents: Fortify subscription billing infrastructure to capture recurring revenue pools before asset-light platforms commoditize urban access. Deepen backward integration into battery swapping station networks to eliminate dwell-time disadvantages against Chinese competitors. Prioritize vehicle-to-grid certification investments that unlock grid-services revenue stacking and compress total cost of ownership calculations.
For New Entrants and Emerging Players: ISO battery safety fast-track certification programs in Germany and the Netherlands offer regulatory arbitrage for fleet qualification. White-space concentration sits with municipal zero-emission zone compliance in secondary European cities where legacy operators under-position electric van assets. Target tradesmen rental programs in London and Amsterdam with bundled charging access go-to-market positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding premium EV positioning in Scandinavian and Benelux corridors. Long-term viability hinges on charging infrastructure ownership rather than vehicle fleet scale. Watch German vehicle-to-grid tariff formalization as the signal indicating which fleet operators can monetize stationary battery assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Partnership | Compresses vehicle downtime for Chinese and German urban corridor deployment. |
| Vehicle-to-Grid Certification Program | Enables revenue stacking with German grid operator demand-response pilots. |
| Subscription Billing Platform Integration | Captures corporate mobility budget shifts from ownership to access models. |
| Municipal Zero-Emission Fleet Contract | Locks in captive demand from London, Paris, and Amsterdam access restrictions. |
| Residual Battery Value Guarantee Product | Reduces insurer dispute exposure through ISO-standardized state-of-charge protocols. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, charging infrastructure operators, and corporate mobility managers; and secondary validation through EU Green Deal regulatory filings, KBA vehicle-type approval databases, and MIIT charging interoperability mandates. Fleet operator financial disclosures and municipal procurement contract registries anchored bottom-up triangulation against top-down market sizing across vehicle type, rental duration, and customer segmentation dimensions.
Across the analysis window, the forecasting framework modeled demand trajectories by propulsion architecture, fleet ownership structure, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to electrification mandate compliance timelines and charging infrastructure build-out rates. Battery swapping station deployment density and vehicle-to-grid tariff pilot expansion served as key sensitivity inputs.
Decision-makers should treat outputs as directional under sustained EPA tailpipe standard compression and EU Green Deal enforcement; material deviation in lithium-ion cell supply continuity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Spain Solar E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market