
 Mexico Automotive High Performance Electric Vehicle Market | 2026-2036
Mexico Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Automotive High Performance Electric Vehicle Market Intelligence
Premium battery specifications above 800V architecture is rotating demand toward vehicles with faster charging and sustained power delivery. Tesla leverages its supercharger network to anchor its position across Mexican metropolitan corridors. BMW differentiates through dedicated performance sub-brands targeting enthusiast segments. Kia Corporation competes on manufacturing scale from its Nuevo León assembly complex.
Mexico Automotive High Performance Electric Vehicles are battery-electric drivetrain systems delivering sustained output above 300 kW with thermal management enabling repeated acceleration cycles without derating, purpose-built for enthusiast driving and luxury mobility applications. Solid state battery research commands the deepest R&D commitments among chemistry pathways despite lithium-ion retaining current production dominance. Sports EVs occupy the highest margin pool within product type segmentation due to limited competition and price inelasticity among performance buyers. Fast charging stations represent the infrastructure segment where capital deployment is accelerating most sharply.
SEMARNAT environmental standards and NOM-001-SECRE energy efficiency mandates shape vehicle certification requirements for powertrain efficiency and emissions labeling. The Secretariat of Economy's automotive sector rules under USMCA compliance frameworks determine local content thresholds and tariff positioning for imported battery components. Stakeholders must monitor how Nuevo León and Baja California state incentive programs evolve against federal standardization efforts.
Market Dynamics
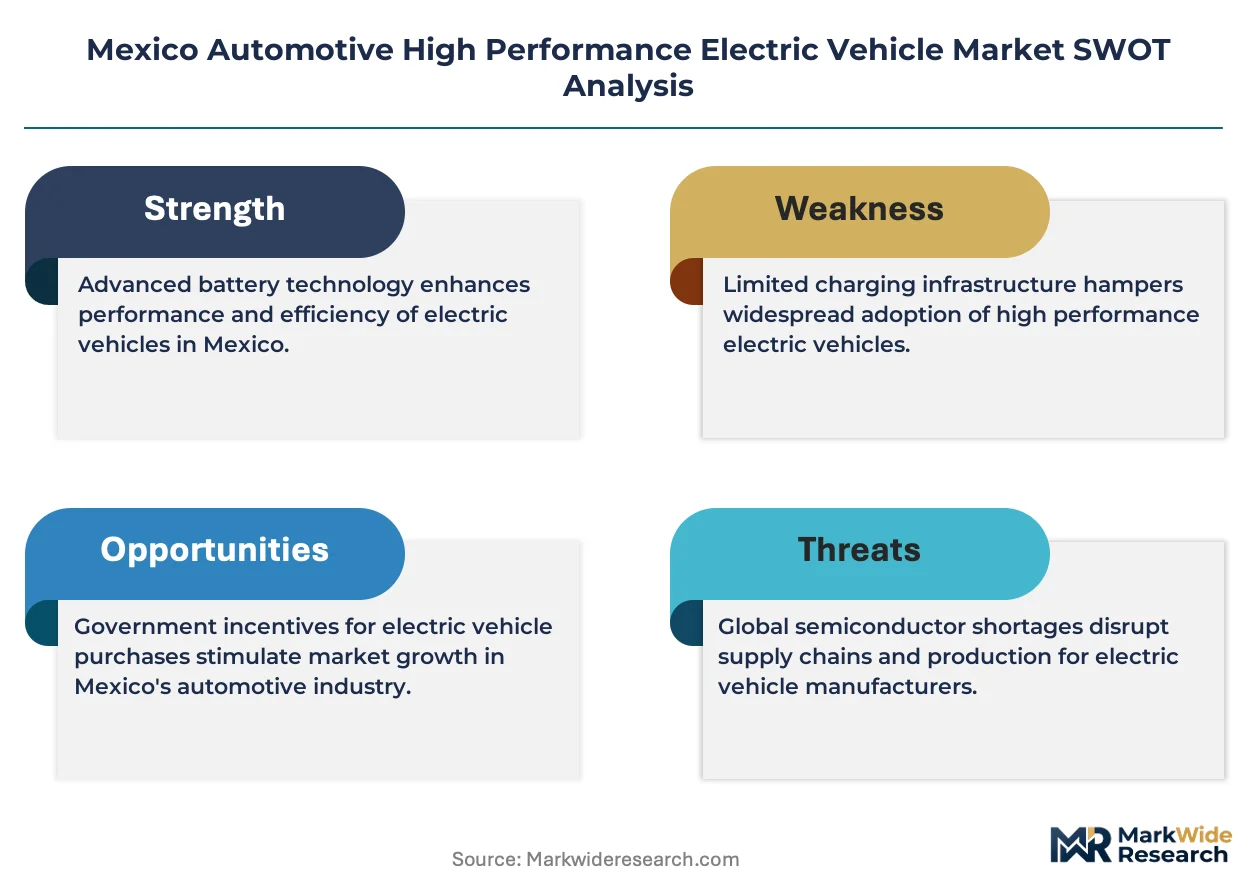
The 800V battery architecture transition is compressing charging windows and reconfiguring thermal management requirements across Mexican assembly lines. This voltage threshold shift demands simultaneous retooling of inverter designs and cooling infrastructure.
Growth Catalysts
- NOM-001-SECRE efficiency mandates:Federal energy standards are accelerating OEM investment in high-voltage drivetrain certification. Compliance timelines compress product development cycles.
- Bajío manufacturing corridor concentration:Guanajuato and Querétaro assembly ecosystems provide tiered supplier density for power electronics sourcing. Logistics costs drop with localized motor winding and inverter production.
- Solid-state battery R&D pipelines:Chemistry breakthroughs in energy density are extending range benchmarks for performance segments. Thermal runaway risk reduction opens new enclosure design freedoms.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings compress margin visibility for battery pack producers. Hedging instruments remain underdeveloped in Mexican commodity markets.
- Supercharger network geographic gaps:Fast charging infrastructure concentrates along Mexico City-Querétaro-León corridors. Intercity routes through Michoacán and Jalisco lack 350kW capacity.
- USMCA local content thresholds:Secretariat of Economy rules constrain imported cell sourcing flexibility. Battery component origin documentation adds administrative overhead.
Strategic Opportunities
- Nuevo León state incentive programs:State-level tax abatements for EV component manufacturing are attracting inverter and thermal system suppliers. Monterrey industrial parks offer expedited permitting.
- Luxury fleet operator channel:Corporate mobility services in Mexico City represent unserved demand for sustained-performance vehicles with chauffeur-duty cycles. Subscription financing models reduce upfront capital barriers.
- Silicon carbide inverter convergence:Wide-bandgap semiconductor integration with 800V architectures is cutting switching losses. Power density gains enable lighter packaging for sports EV applications.
Industry Challenges
- High-voltage technician certification gaps:Sistema Nacional de Competencias lacks standardized curricula for 800V system repair. Workforce development lags behind equipment deployment.
- SEMARNAT environmental compliance timelines:Emissions labeling and powertrain efficiency documentation requirements extend product homologation cycles. Testing backlog creates launch delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Automotive High Performance Electric Vehicle Market |
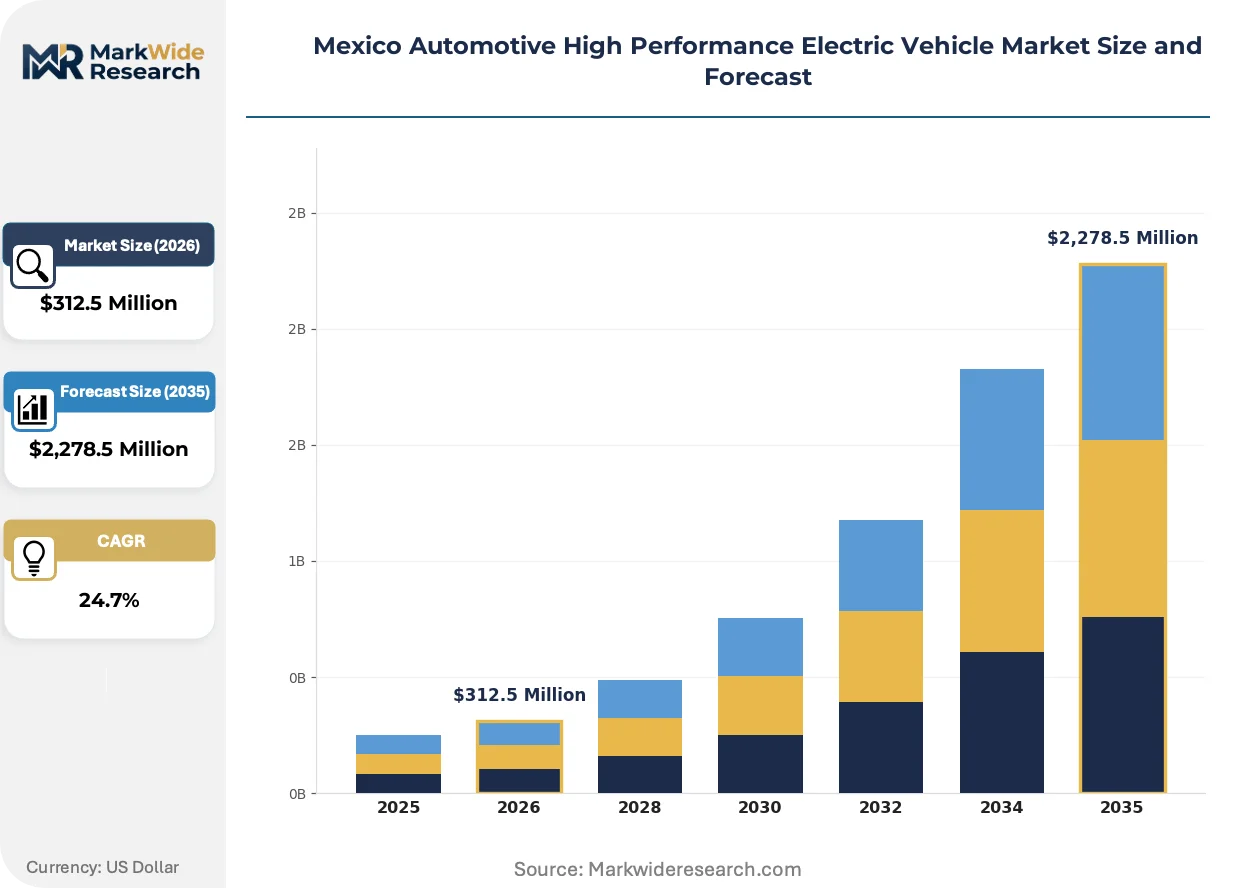
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,278.5 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury EVs, Sports EVs, SUVs, Sedans Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Graphene Charging Infrastructure: Fast Charging Stations, Home Chargers, Public Chargers, Wireless Charging Distribution Channel: Direct Sales, Dealerships, Online Platforms, Auctions |
| Companies Covered | BYD, Nissan, Tesla, Magna International, Kia Corporation, Ford Motor Company, BMW, Daimler, General Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
Thermal management architectures are undergoing fundamental redesign as sustained power delivery demands escalate. Cooling system innovation now determines acceleration repeatability and battery longevity benchmarks.
Silicon carbide power modules are replacing traditional IGBT inverters in 800V architectures. Performance EV assemblers in Querétaro are adopting these modules for switching efficiency above 99%. The technology is miniaturizing inverter packaging while cutting thermal rejection requirements by one-third.
NOM-001-SECRE energy efficiency standards are tightening certification thresholds for powertrain thermal performance. SEMARNAT labeling requirements now mandate disclosed consumption metrics under standardized duty cycles. Sports EV segments face the steepest compliance cost escalation due to high sustained-load testing protocols.
Fleet procurement in Mexico City is pivoting toward total-cost-of-ownership contracting. Luxury mobility operators are unbundling vehicle acquisition from charging infrastructure and maintenance obligations. This shift concentrates buyer power among three national fleet management platforms with direct OEM negotiation leverage.
Mexico Automotive High Performance Electric Vehicle Market Segmentation
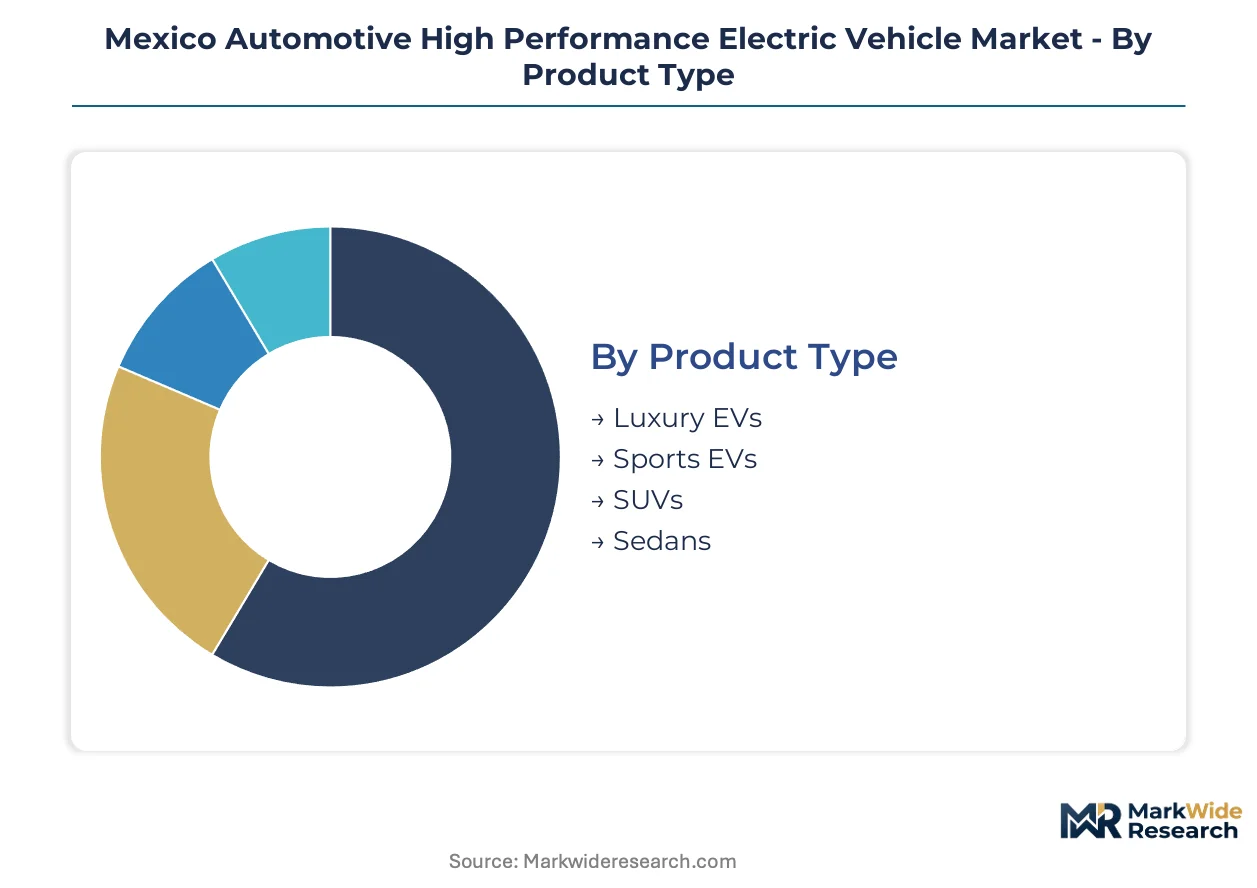
Segmentation in Mexico's high-performance EV market reveals how regulatory frameworks and infrastructure gaps reshape competitive positioning across product categories. NOM-001-SECRE compliance tiers and charging network density create divergent growth trajectories that OEMs must navigate through targeted portfolio allocation.
Product Type:
NOM-001-SECRE energy efficiency standards apply differential certification stringency across vehicle architectures, with sustained-load testing protocols creating compliance cost gradients that favor certain form factors.
- Sports EVs:Purpose-built architectures delivering sustained output above 300 kW with thermal management for repeated acceleration cycles. Demand concentrates among luxury fleet operators in Mexico City seeking chauffeur-duty performance without derating; SEMARNAT emissions labeling requirements impose steepest compliance cost escalation due to high-load testing protocols.
- Luxury EVs:Premium battery specifications above 800V architecture enable faster charging and sustained power delivery for enthusiast applications. Bajío manufacturing corridor assembly ecosystems in Guanajuato and Querétaro provide tiered supplier density for localized power electronics sourcing.
- SUVs:Higher curb weights demand larger battery packs, amplifying lithium carbonate price volatility exposure for Mexican assemblers.
- Sedans:Aerodynamic efficiency advantages reduce energy consumption metrics under standardized duty cycles, easing NOM-001-SECRE certification pathways.
Established volume favors Sports EVs; emerging adoption favors Luxury EVs.
Battery Technology:
Cost tier differentiation separates chemistry pathways by energy density benchmarks and thermal runaway risk profiles, with R&D commitment depth determining competitive moats.
- Lithium-ion:Retains current production dominance across Mexican assembly lines with established supply chains and documented recycling protocols. Querétaro inverter suppliers integrate silicon carbide power modules with these cells for switching efficiency above 99%.
- Solid State:Commands deepest R&D commitments among chemistry pathways despite manufacturing scale challenges. Nuevo León state incentive programs are attracting thermal system suppliers to support next-generation enclosure design freedoms.
- Nickel-Metal Hydride:Legacy chemistry retains niche applications where cost sensitivity outweighs energy density requirements.
- Graphene:Experimental additive formulations promise conductivity improvements but lack validated production-scale supply agreements.
Production maturity favors Lithium-ion; technology transition favors Solid State.
Charging Infrastructure:
Geographic concentration patterns determine capital deployment efficiency, with infrastructure gaps creating demand bottlenecks outside priority corridors.
- Fast Charging Stations:350kW capacity deployment concentrates along Mexico City-Querétaro-León corridors where fleet procurement pivots toward total-cost-of-ownership contracting. USMCA local content thresholds constrain imported component sourcing flexibility for station equipment.
- Home Chargers:Residential installations lag due to high-voltage technician certification gaps in Sistema Nacional de Competencias curricula.
- Public Chargers:Intercity routes through Michoacán and Jalisco lack capacity expansion, limiting range confidence for cross-regional mobility.
- Wireless Charging:Inductive systems remain pre-commercial in Mexico with no deployed pilot programs at scale.
Capital deployment favors Fast Charging Stations; network completion favors Public Chargers.
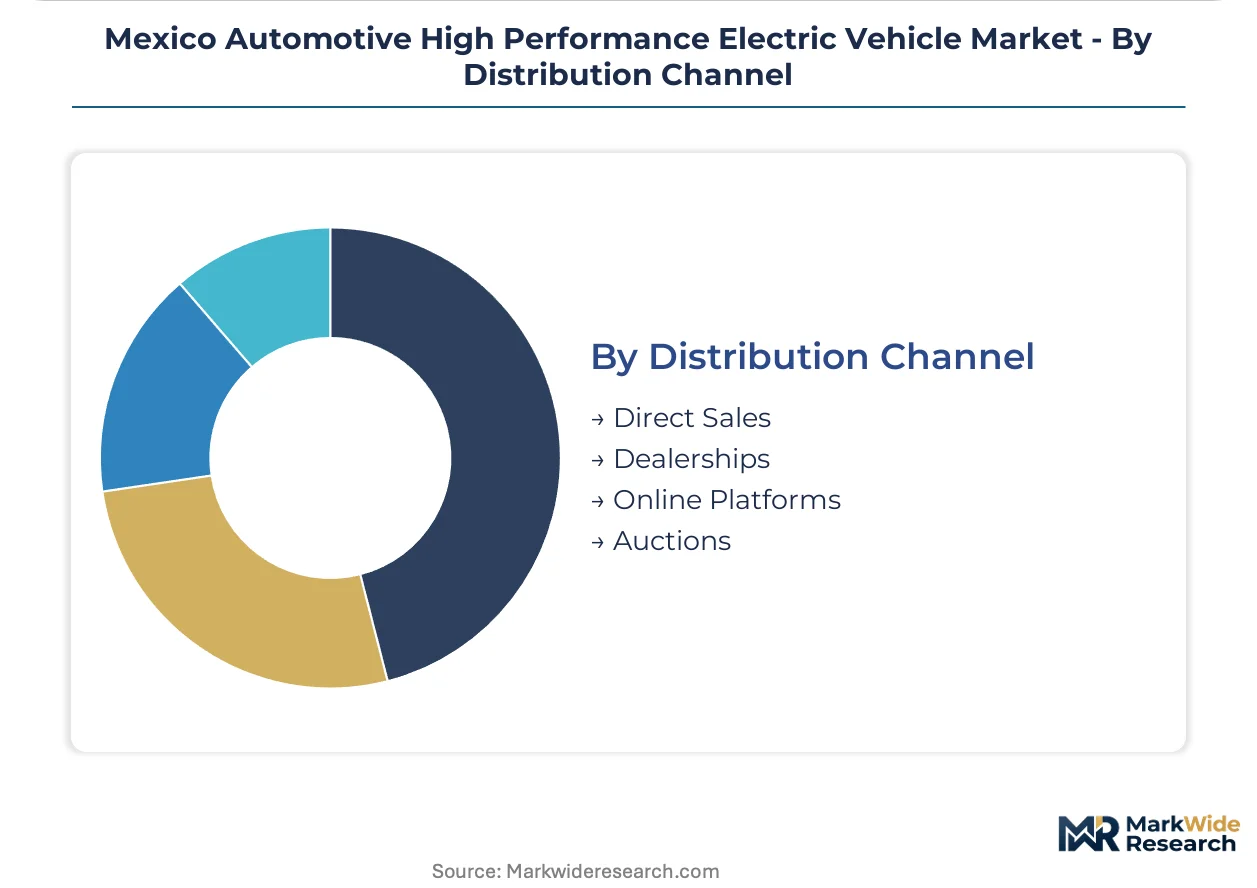
Distribution Channel:
Customer type fragmentation separates procurement patterns between individual enthusiasts and institutional fleet operators with divergent financing preferences.
- Direct Sales:OEM-controlled channels capture subscription financing models reducing upfront capital barriers for Mexico City luxury mobility operators. Three national fleet management platforms concentrate buyer power with direct negotiation leverage.
- Dealerships:Traditional networks face margin compression as 800V architecture retooling demands compress product development cycles and inventory carrying costs.
- Online Platforms:Digital configurators enable specification customization but lack physical test drive access for performance validation.
- Auctions:Secondary market liquidity remains thin given limited vehicle age in this emerging segment.
Channel control favors Direct Sales; volume accessibility favors Dealerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's export-oriented automotive sector generates substantial trade surpluses in assembled vehicles while importing high-value battery components and power electronics. The country's manufacturing clusters serve both domestic consumption and North American export markets through integrated supply chains.
Mexico City Metro
Luxury fleet operators in Mexico City represent the fastest-expanding buyer segment for sustained-performance vehicles with chauffeur-duty cycles. NOM-001-SECRE energy efficiency standards mandate federal certification for powertrain thermal performance before vehicle registration. Corporate mobility platforms concentrate procurement power through subscription financing models that reduce upfront capital barriers.
Bajío Region
Guanajuato and Querétaro assembly ecosystems provide tiered supplier density for power electronics sourcing and localized motor winding production. SEMARNAT environmental standards shape emissions labeling requirements that extend product homologation cycles. Silicon carbide inverter suppliers in Querétaro industrial parks achieve switching efficiency above 99% through wide-bandgap semiconductor integration.
Nuevo León
State-level tax abatements for EV component manufacturing attract inverter and thermal system suppliers to Monterrey industrial parks. The Secretariat of Economy's automotive sector rules under USMCA compliance frameworks determine local content thresholds for imported battery components. Kia Corporation operates assembly capacity from its Nuevo León manufacturing complex serving North American markets.
Jalisco
Intercity mobility demand through Michoacán and Jalisco faces infrastructure gaps with limited 350kW fast charging capacity along priority corridors. Federal standardization efforts for NOM-001-SECRE certification create administrative overhead for multi-state vehicle distribution. Guadalajara metropolitan area serves as a secondary demand node for enthusiast segments outside the capital.
Northern Border States
Cross-border supply chain integration with Texas and California manufacturing clusters enables just-in-time delivery of battery management systems and thermal components. USMCA rules of origin documentation adds compliance burden for imported cell sourcing from Asian suppliers. Tijuana and Matamoros assembly operations focus on export-oriented production with limited domestic market penetration.
Mexico Automotive High Performance Electric Vehicle Market Key Industry Players
Listed leaders compete with private specialists across capital access and manufacturing scale dimensions. The vendor base organizes around three strategic tiers: integrated OEMs with captive battery supply, tier-1 component suppliers with inverter specialization, and emerging Chinese entrants with cost-optimized architectures. Dominant competitive moves include silicon carbide technology licensing partnerships and backward integration into cell assembly capacity.
Within the integrated OEM tier, Tesla leverages its supercharger network infrastructure across Mexican metropolitan corridors while BMW differentiates through dedicated performance sub-brands. BYD represents the emerging Chinese archetype with vertically integrated battery and vehicle production. Kia Corporation occupies a position anchored by manufacturing scale from its Nuevo León assembly complex serving regional export demand.
| Leading Market Players |
|---|
| BYD |
| Nissan |
| Tesla |
| Magna International |
| Kia Corporation |
| Ford Motor Company |
| BMW |
| Daimler |
| General Motors |
| Others |
Cost & Logistics Intelligence
Silicon carbide power module substitution for traditional IGBT inverters is redrawing procurement geography toward Querétaro industrial parks while compressing inverter packaging costs by one-third. This semiconductor transition simultaneously concentrates supplier qualification power among wide-bandgap semiconductor integrators and reshapes tier-1 pricing leverage across 800V architecture deployments.
Pricing Analysis
Industrial OEM buyers anchor subscription financing models that unbundle vehicle acquisition from charging infrastructure obligations. Price differentiation separates NOM-001-SECRE certified vehicles from non-compliant imports facing registration barriers, with volume scale and after-sales service bundling as secondary tiering factors. Cost compression in standard battery packs is intensifying because lithium carbonate volatility erodes margin visibility for Mexican assemblers. Fleet management platforms exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while individual enthusiasts face highest capital barriers.
Supply Chain Analysis
Port congestion at Lázaro Cárdenas and Manzanillo is elevating inbound logistics costs for Asian-sourced battery cells and power electronics. Manufacturing concentration centers on China, South Korea, and Japan for lithium-ion cells, with Germany and Taiwan contributing specialized inverter components and semiconductors. The supply chain draws from Chilean lithium brine operations, Australian spodumene concentrates, and refined cobalt from the DRC. Tariff exposure under USMCA local content thresholds constrains imported cell sourcing flexibility. Distribution runs through Bajío corridor assembly ecosystems with tiered supplier density for localized power electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-001-SECRE certification mandates are accelerating product development cycles and compressing homologation timelines, creating a regulatory inflection that favors prepared incumbents with established compliance infrastructure.
For Market Incumbents: Shield market position through backward integration into silicon carbide inverter assembly capacity within Querétaro industrial parks. Deepen captive battery supply agreements with Korean cell producers to mitigate lithium carbonate volatility exposure. SEMARNAT emissions labeling backlog represents the primary threat to launch timing. For New Entrants and Emerging Players: NOM-001-SECRE fast-track certification pathways offer regulatory arbitrage for entrants with pre-validated thermal management architectures. White-space targets include Michoacán and Jalisco intercity corridors lacking 350kW charging infrastructure, plus subscription financing models for Mexico City luxury fleet operators. Go-to-market angle should emphasize chauffeur-duty cycle validation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed thermal system suppliers attracted to Nuevo León state incentive programs. Long-term viability hinges on 800V architecture standardization and solid-state battery manufacturing scale. Acquisition target archetype: tier-1 inverter specialists with silicon carbide integration capabilities. Signal to watch: federal standardization efforts preempting state-level incentive fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Standardization | Reduces retooling costs across Guanajuato and Querétaro assembly lines while enabling faster charging certification. |
| Battery Supply Agreement | Locks lithium carbonate pricing with Korean producers to stabilize margin visibility for Mexican pack assemblers. |
| Software-Defined Vehicle Investment | Enables over-the-air thermal management updates that maintain NOM-001-SECRE compliance across vehicle lifecycles. |
| Charging Infrastructure Partnership | Addresses geographic gaps in Michoacán and Jalisco through 350kW corridor deployment with fleet operators. |
| Solid-State Battery R&D Commitment | Positions Nuevo León facilities for next-generation chemistry transition with state tax abatement support. |
Research Approach
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet management operations heads, and charging infrastructure developers anchored the qualitative base. Primary interviews triangulated with secondary validation from vehicle production databases, NOM-001-SECRE certification registries, USMCA rules of origin documentation, and state incentive program filings. Bottom-up assembly capacity modeling and top-down demand segmentation from registration data converged on volume estimates.
Sensitivity analysis tested forecast robustness across lithium carbonate price scenarios and NOM-001-SECRE compliance timeline variations. The analytical framework modeled vehicle class, propulsion architecture, battery technology pathway, and regional production cluster dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and infrastructure deployment trajectories. Forecast inputs incorporated charging station capacity buildout schedules and fleet procurement contract visibility.
Underlying assumptions cover sustained federal incentive continuity, stable USMCA framework interpretation, and silicon carbide supply expansion, with deviation risk concentrated in lithium raw material volatility and SEMARNAT testing backlog duration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
North America Automotive Battery Thermal Management System Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Germany Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Solar E-Bike Market
Electric Vehicles
Electric Vehicle Skateboard Platform Market
Electric Vehicles
South Korea E-Bike Market
Electric Vehicles
Electric Transporters Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market