
 Speed Pedelec E-Bike Market | 2026-2036
Speed Pedelec E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Speed Pedelec E-Bike Market Analytics
Modular battery subscription programs paired with frame-agnostic drivetrain packages is broadening buyer choice beyond traditional ownership models. Giant leverages in-house motor production to control cost structures across premium and mid-tier configurations. Bosch sustains technology leadership through continuous refinement of its Performance Line Speed systems for 45 km/h operation. Riese & Müller specializes in full-suspension speed pedelec architectures that differentiate its portfolio in the touring segment.
Speed pedelecs are electrically power-assisted cycles with motor support up to 45 km/h, requiring type approval, registration, and helmet use under EU framework; they employ mid-drive or hub motors paired with 500–750 Wh lithium-ion packs to extend commuter range beyond 100 km per charge. City configurations dominate unit volume due to flat-terrain commuting corridors in Benelux and German metropolitan networks, while Cargo variants capture expanding margin pools as logistics operators replace van-based urban delivery. Fleet Operators represent the fastest-growing end-user channel, with central procurement offices at municipal transit authorities and courier companies placing multi-hundred-unit orders.
The EU's L1e-B vehicle classification under Regulation 168/2014 mandates speed pedelecs carry insurance plates, braking performance certification, and rear-view mirrors, directly shaping product design and market access costs for manufacturers. ECE R14 and R30 standards govern lighting and tire specifications, creating compliance barriers for non-European suppliers seeking European distribution. Stakeholders must monitor proposed revisions to the F-Gas Regulation and emerging battery passport requirements under the EU Battery Regulation, as these frameworks will reshape supply chain accountability and total cost of ownership calculations for fleet buyers.
Market Dynamics
The EU's Machinery Directive and L1e-B type-approval framework are compressing product development cycles while elevating homologation costs, forcing manufacturers to consolidate powertrain architectures across multiple national markets simultaneously.
Growth Catalysts
- Urban fleet procurement:Municipal transit authorities in Germany, the Netherlands, and Belgium are issuing multi-hundred-unit tenders for last-mile connectivity, creating predictable demand pipelines for certified L1e-B vehicles.
- F-Gas Regulation alignment:Manufacturers redesigning thermal management systems to meet emerging refrigerant phase-down schedules gain preemptive compliance positioning for EU market access.
- Mid-drive motor efficiency gains:Advances in permanent-magnet topology and integrated torque sensing are extending effective range beyond 100 km per charge, addressing range anxiety in commuter corridors.
Market Restraints
- Lithium-ion cell supply concentration:Cathode active material processing clusters in East Asia create input cost volatility and geopolitical exposure for European pack assemblers.
- Type-approval timeline friction:ECE R14 lighting certification and R30 tire homologation add 4-6 month delays to product launches, compressing effective selling seasons.
- Van-based logistics substitution:Electric light commercial vehicles with sub-3.5t ratings compete directly for urban delivery contracts, capping cargo speed pedelec pricing power.
Strategic Opportunities
- Swiss and Austrian urban corridors:Concentrated fleet adoption in alpine metropolitan networks offers premium positioning for full-suspension architectures with enhanced braking certification.
- Battery passport integration:Early compliance with EU Battery Regulation traceability mandates creates differentiation for fleet operators facing Scope 3 reporting obligations under CSRD.
- Modular subscription bundling:Frame-agnostic drivetrain packages paired with swap-station networks enable service-based revenue models beyond unit sales.
Industry Challenges
- Homologation engineering scarcity:Specialized talent for L1e-B braking performance certification and electromagnetic compatibility testing commands premium compensation, constraining R&D throughput.
- Multi-jurisdiction plate registration:Divergent national insurance and helmet enforcement regimes fragment fleet deployment protocols across Benelux and German operating territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speed Pedelec E-Bike Market |
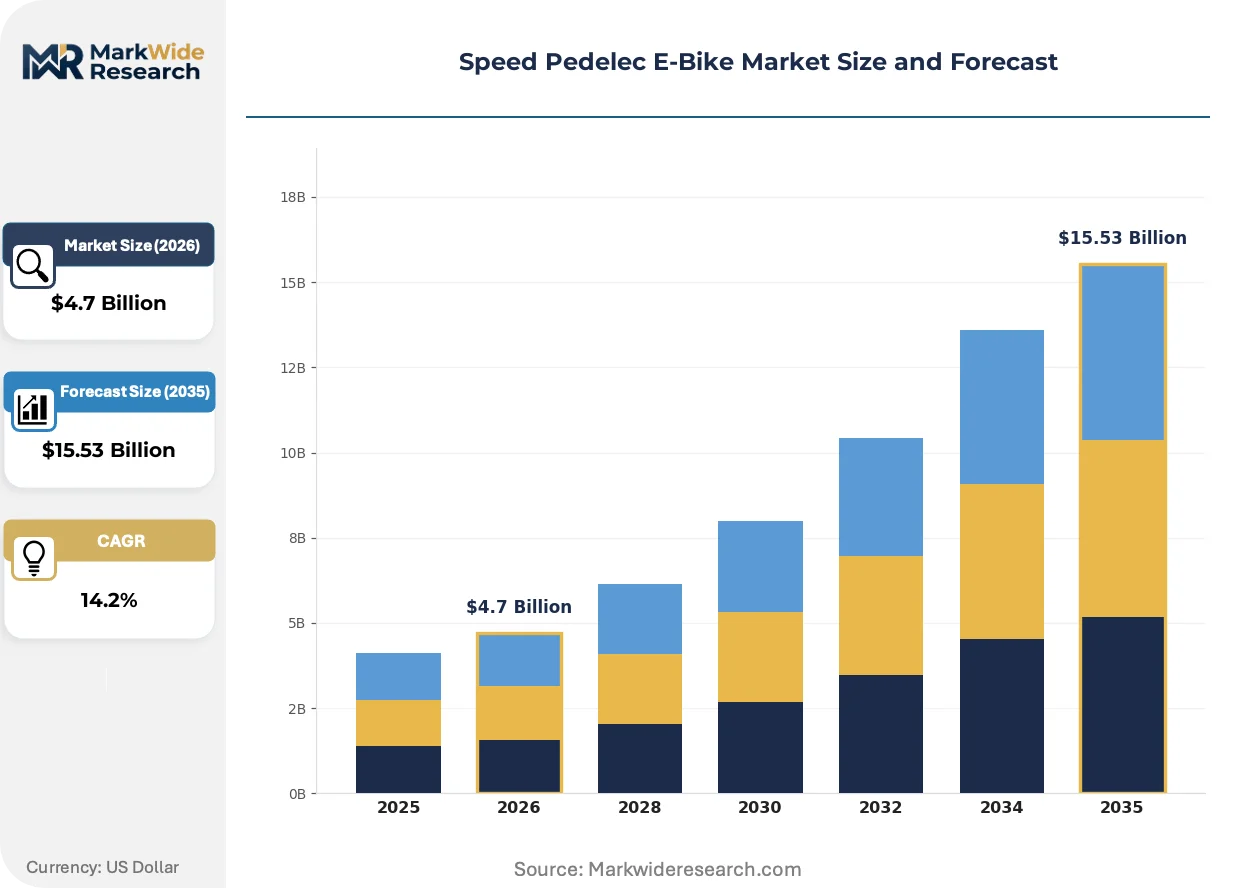
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City, Mountain, Folding, Cargo Battery Technology: Lithium-Ion, Nickel-Metal Hydride, Lead Acid, Others Usage Scenario: Commuting, Recreational, Delivery, Sport End User: Individual, Fleet Operators, Rentals, Tourists |
| Companies Covered | Giant, Hezzo, Riese & Müller, Lectric eBikes, Aventon, Specialized, Bosch, Canyon, Trek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speed Pedelec E-Bike Market Evolving Landscape
Powertrain integration and regulatory traceability are converging to redefine how speed pedelecs are specified, financed, and deployed across European urban mobility networks.
Integrated torque-sensing mid-drive systems with dual-battery hot-swap capability are electrifying fleet operator procurement criteria. Courier companies and municipal transit authorities now specify continuous motor support without thermal derating as a baseline requirement. This specification compression is electrifying competitive differentiation toward thermal management architecture and swap-station network density rather than raw motor wattage.
REACH substance restrictions on persistent organic pollutants in electrical components are forcing redesigns of cable insulation and connector housings. Manufacturers sourcing halogen-free flame-retardant compounds face 12-18 month qualification cycles with notified bodies. The touring segment with extended wiring harnesses for lighting and display integration faces disproportionate compliance burden and component cost elevation.
Fleet procurement offices are consolidating vendor relationships around outcome-based availability guarantees rather than unit purchase. Municipal transit authorities in the Netherlands and Belgium now contract for guaranteed vehicle uptime percentages, transferring maintenance risk to OEM service subsidiaries. This contractual pivot is most visible in Rotterdam and Antwerp operating territories where multi-year service agreements displace traditional warranty terms.
Speed Pedelec E-Bike Market Segmentation
Speed pedelec classification determines regulatory pathway, insurance cost, and infrastructure access across European markets. Segmentation reveals how product architecture, energy storage chemistry, and procurement channel reshape margin distribution and competitive intensity.
Product Type:
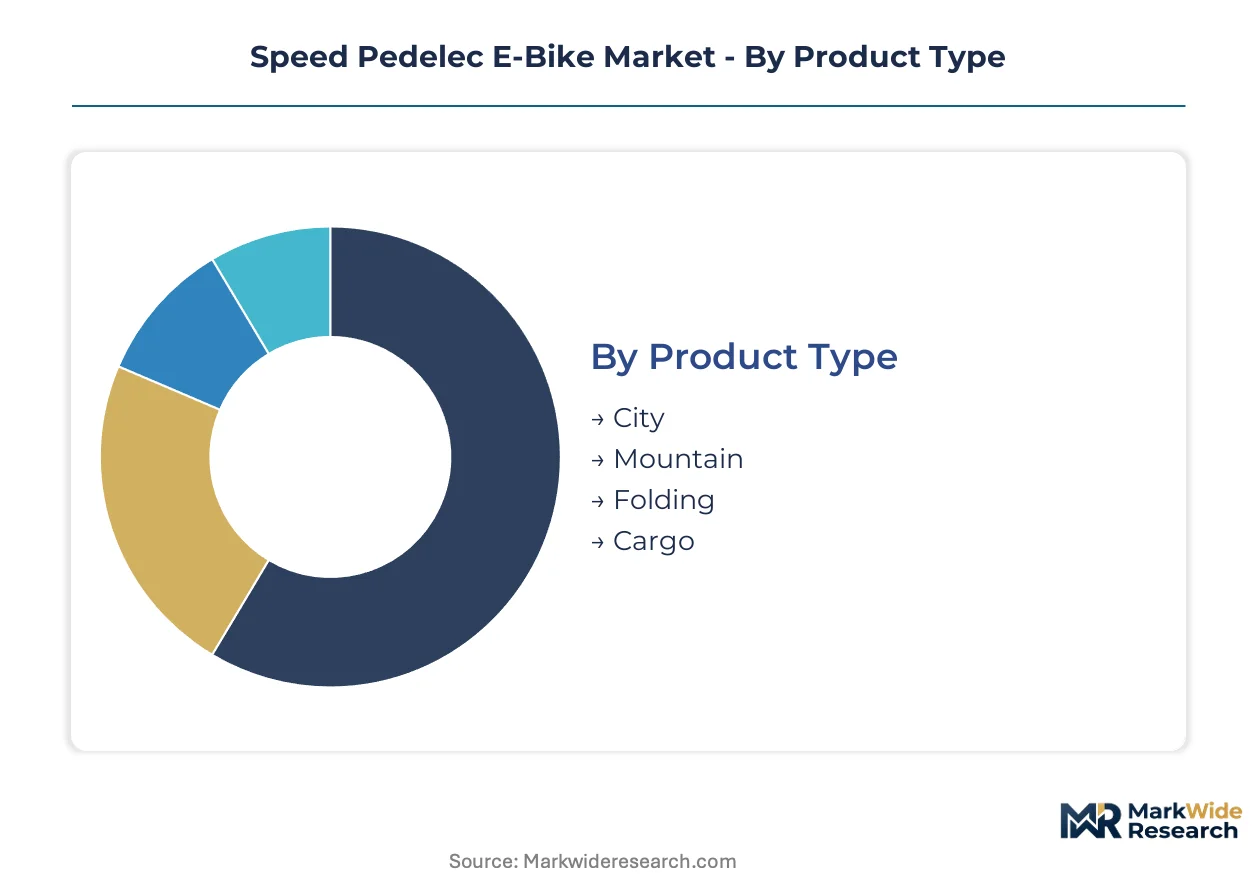
City configurations dominate unit volume through flat-terrain commuter corridors, while Cargo variants command premium positioning in logistics substitution applications.
- City:Step-through frames with integrated lighting and fender systems address daily commuter requirements in German and Dutch metropolitan networks. Municipal fleet tenders in Rotterdam and Antwerp specify this configuration for last-mile transit connectivity.
- Cargo:Extended wheelbases with reinforced frame structures support 150-200 kg payload ratings for urban delivery operators. Swiss and Austrian logistics corridors show concentrated procurement as van substitution accelerates in alpine city centers.
- Mountain:Full-suspension architectures with enhanced braking certification target recreational users in alpine terrain.
- Folding:Hinge-frame designs with reduced battery capacity address multi-modal commuters requiring train-bike integration.
Mature deployment sits with City configurations in Benelux transit networks. Newer deployment is concentrated in Cargo variants as courier operators reconfigure urban logistics.
Battery Technology:
Energy density and cycle life differentiate cost structures, with supply chain geography creating divergent compliance exposure under EU Battery Regulation traceability mandates.
- Lithium-Ion:NMC and LFP cathode chemistries deliver 500-750 Wh capacities with 1000+ cycle ratings. Cell processing concentration in East Asia creates input cost volatility for European pack assemblers serving fleet operators.
- Nickel-Metal Hydride:Lower energy density limits application to entry-tier individual purchasers in price-sensitive segments. Recycling infrastructure limitations constrain second-life value recovery.
- Lead Acid:Remaining utility confined to aftermarket replacement in legacy fleets with minimal range requirements.
- Others:Solid-state and sodium-ion prototypes under evaluation for thermal safety advantages in high-duty-cycle applications.
Established chemistry dominance rests with Lithium-Ion across certified L1e-B vehicle production. Emerging chemistry evaluation is accelerating in R&D programs targeting fleet uptime guarantees.
Usage Scenario:
Application context determines motor thermal management specifications and frame durability requirements, with contractual structures diverging between individual ownership and service-based availability models.
- Commuting:Daily 20-40 km distances with predictable charging intervals dominate procurement volume. Belgian and German employers leverage tax-advantaged leasing structures to accelerate adoption in professional workforce segments.
- Delivery:Continuous operation demands with swap-station dependency reshape vendor selection criteria toward network density guarantees. Courier companies in Dutch urban corridors contract for uptime percentages rather than unit purchase.
- Recreational:Weekend touring applications with extended range requirements drive full-suspension specification in Austrian alpine regions.
- Sport:Competitive and fitness-oriented usage with minimal regulatory compliance burden outside type-approval frameworks.
Volume concentration aligns with Commuting scenarios through employer-sponsored programs. Steepest expansion trajectory is visible in Delivery applications as logistics operators displace van-based urban distribution.
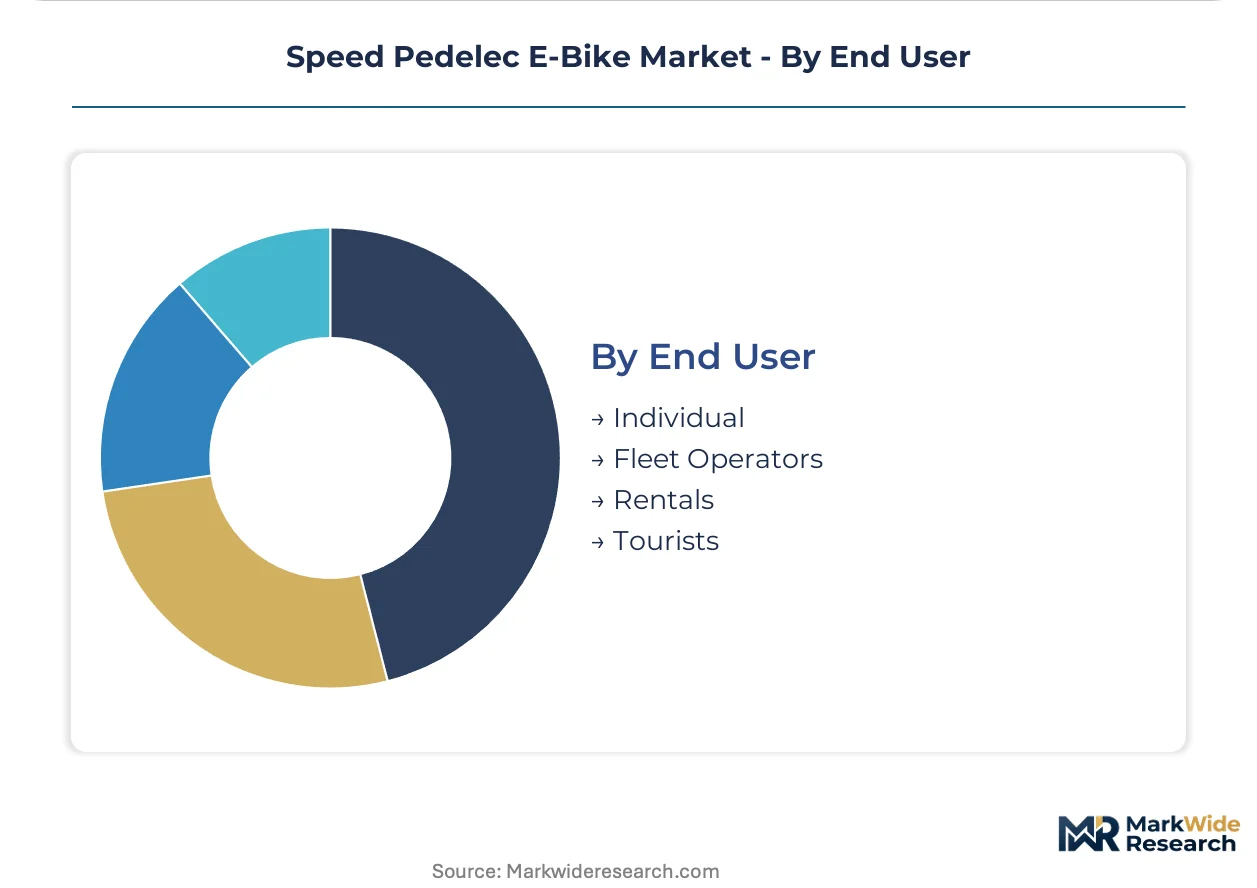
End User:
Procurement authority and total cost of ownership calculation methods create divergent pricing power and service attachment opportunities across the customer base.
- Fleet Operators:Municipal transit authorities and courier companies issue multi-hundred-unit tenders with outcome-based availability contracts. Central procurement offices in the Netherlands and Belgium now specify guaranteed uptime percentages transferring maintenance risk to OEM service subsidiaries.
- Individual:Retail purchasers with high price sensitivity and extended decision cycles dominate unit volume in German metropolitan markets. Direct-to-consumer channels with subscription bundling are displacing traditional dealership networks.
- Rentals:Tourism-focused operators in Swiss alpine corridors and Belgian historic city centers specify durable frame architectures with simplified maintenance protocols.
- Tourists:Short-duration usage with minimal specification knowledge creates demand for guided tour packages with inclusive insurance and helmet provision.
Traditional ownership patterns persist among Individual purchasers with established commuting routines. Service-based contracting is expanding most quickly among Fleet Operators facing CSRD Scope 3 reporting obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturing clusters concentrate speed pedelec assembly, yet procurement demand concentrates in specific national corridors with aligned regulatory frameworks and fleet infrastructure investments.
Germany
KBA type-approval procedures and employer-sponsored leasing tax advantages accelerate professional workforce adoption in Berlin, Munich, and Hamburg metropolitan networks. The Machinery Directive compliance burden elevates homologation costs for manufacturers, compressing development cycles. Stuttgart and Baden-Württemberg host powertrain engineering clusters where Bosch Performance Line Speed systems undergo continuous refinement for 45 km/h operation.
Netherlands
Rotterdam and Amsterdam municipal transit authorities issue multi-hundred-unit fleet tenders with guaranteed uptime percentage contracts displacing traditional warranty structures. REACH substance restrictions on persistent organic pollutants force 12-18 month qualification cycles for halogen-free cable insulation. Randstad urban corridors demonstrate concentrated battery swap-station network deployment supporting courier operator procurement.
Belgium
Antwerp operating territories exhibit service-based contracting expansion among logistics operators facing CSRD Scope 3 reporting obligations. Benelux insurance plate harmonization reduces multi-jurisdiction registration friction for cross-border fleet deployment. Flemish metropolitan networks concentrate flat-terrain city configuration demand through employer-sponsored commuter programs.
Switzerland
Swissmedic-aligned safety certification and alpine braking performance requirements elevate full-suspension architecture specification in Zurich and Geneva urban corridors. Swiss and Austrian logistics operators accelerate van substitution procurement in alpine city centers. The touring segment commands premium positioning through enhanced electromagnetic compatibility testing protocols.
Austria
Vienna municipal procurement offices specify rear-view mirror and lighting certification under ECE R14 standards for last-mile transit connectivity contracts. Austrian alpine regions drive recreational full-suspension demand with extended range requirements. Tyrol and Salzburg metropolitan networks concentrate fleet adoption where thermal management architecture without derating constitutes baseline vendor selection criteria.
Speed Pedelec E-Bike Market Competitive Landscape
The competitive structure tilts toward integrated powertrain specialists with captive motor production and full-suspension architecture differentiation. Market concentration elevates around mid-drive system efficiency leaders and frame-agnostic drivetrain package providers. Three archetypes dominate: in-house motor producers controlling cost structures, suspension specialists commanding touring premiums, and subscription-platform operators enabling service-based revenue. Competitive moves center on modular battery program expansion and swap-station network density partnerships.
Among European powertrain and frame specialists, Giant, Riese & Müller, and Bosch occupy distinct positioning archetypes. Giant represents the vertically integrated volume producer with in-house motor manufacturing capabilities spanning premium and mid-tier configurations. Riese & Müller exemplifies the full-suspension architecture specialist differentiating through touring segment premium positioning. Bosch anchors the component-system tier with Performance Line Speed technology refinement for certified L1e-B vehicle integration. These three entities collectively illustrate how competitive advantage converges on thermal management reliability and regulatory compliance depth rather than raw motor specification.
| Leading Market Players |
|---|
| Giant |
| Hezzo |
| Riese & Müller |
| Lectric eBikes |
| Aventon |
| Specialized |
| Bosch |
| Canyon |
| Trek |
| Others |
Value Network & Pricing Analysis
Integrated torque-sensing mid-drive systems with dual-battery hot-swap capability are compressing cost structures while concentrating procurement power among fleet operators with volume scale. This technology transition simultaneously elevates R&D amortization burdens for smaller assemblers and rewards manufacturers with captive motor production and swap-station network density.
Pricing Analysis
Cost-down pressure on mid-tier configurations accelerates because employer-sponsored leasing programs in Belgium and Germany prioritize total cost of ownership over upfront unit economics. Three-tier pricing structure across premium, standard, and economy levels separates full-suspension touring architectures with Swissmedic braking certification from flat-terrain city configurations and entry-tier hub-motor alternatives. Lithium-ion cell cost volatility from East Asian cathode processing clusters intensifies margin compression for European pack assemblers lacking long-term offtake agreements. Individual retail purchasers in German metropolitan markets exhibit highest price sensitivity, while Dutch municipal transit authorities with multi-hundred-unit tenders demonstrate lowest sensitivity due to outcome-based availability contracting.
Supply Chain Analysis
Reverse-logistics flows for battery passport compliance and second-life value recovery are reshaping downstream channel economics as fleet operators face CSRD Scope 3 reporting obligations. Cell processing concentrates in China, South Korea, and Japan, with European pack assembly drawing from NMC and LFP cathode chemistries subject to EU Battery Regulation traceability mandates. Raw material dependencies span cobalt from the Democratic Republic of Congo, lithium from Chile and Australia, and rare earth elements for permanent-magnet motors. Single-source vulnerability in East Asian anode and electrolyte production creates tariff exposure and geopolitical risk. Distribution runs through OEM service subsidiaries in Rotterdam and Antwerp operating territories, displacing traditional dealership networks with direct fleet contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
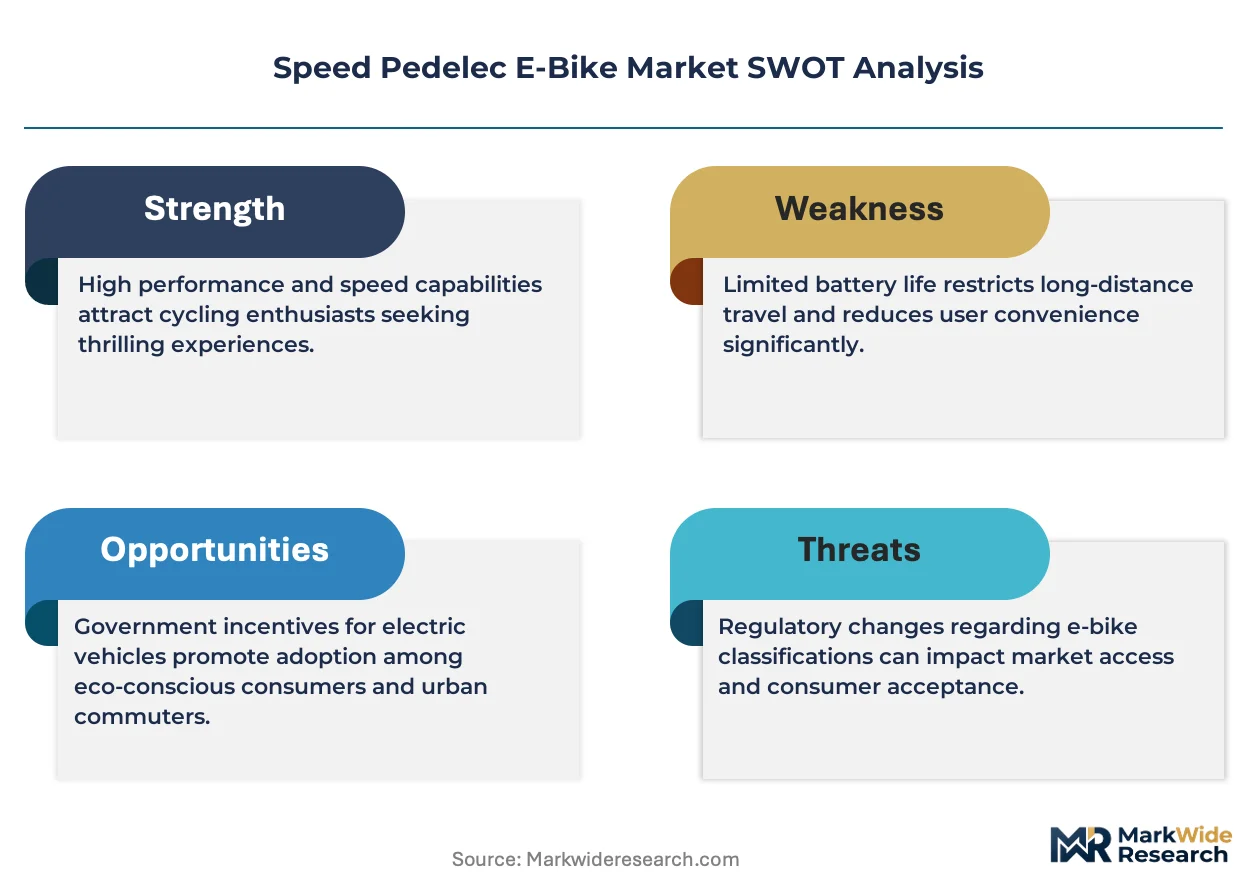
The Speed Pedelec E-Bike Market functions as a cost-of-compliance arena where the EU's L1e-B type-approval framework under Regulation 168/2014 erects substantial barriers to entry, protecting incumbents with established homologation engineering capabilities and certified powertrain architectures.
For Market Incumbents: Extend thermal management architecture leadership through continuous refinement of integrated torque-sensing systems that prevent thermal derating under continuous fleet operation. Consolidate vendor relationships with municipal transit authorities in the Netherlands and Belgium around outcome-based availability guarantees that transfer maintenance risk to OEM service subsidiaries, defending against emerging subscription-platform operators with frame-agnostic drivetrain packages. For New Entrants and Emerging Players: Launch via modular battery subscription programs paired with swap-station network partnerships in Swiss and Austrian alpine corridors where full-suspension specifications command premium positioning. Target cargo configurations in urban delivery applications as van substitution accelerates, penetrating the most penetrable segment through service-based revenue models that circumvent upfront capital requirements facing individual retail purchasers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated powertrain specialists with captive motor production given employer-sponsored leasing tax advantages accelerating professional workforce adoption across German metropolitan networks. Long-term viability favors entities with in-house Performance Line Speed system refinement capabilities and established ECE R14 lighting certification pathways. Monitor proposed F-Gas Regulation revisions and battery passport implementation timelines as inflection indicators for supply chain accountability cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Subscription Launch | Enables service-based revenue models beyond unit sales for fleet operators in Rotterdam and Antwerp. |
| Swap-Station Network Partnership | Addresses courier uptime guarantees through Randstad urban corridor density investments. |
| Full-Suspension Architecture Certification | Captures Swissmedic-aligned premium positioning in Zurich and Geneva alpine braking performance segments. |
| Homologation Engineering Consolidation | Compresses ECE R14 and R30 certification timelines against specialized talent scarcity constraints. |
| Battery Passport Compliance Integration | Creates differentiation for fleet operators facing CSRD Scope 3 reporting obligations under EU Battery Regulation. |
Research Methodology
Document review covered EU regulatory filings including ECE R14 and R30 homologation records, KBA type-approval databases, and REACH substance restriction notifications, complemented by interviews with powertrain engineering directors at Stuttgart and Baden-Württemberg manufacturing clusters, fleet procurement officers at Rotterdam and Antwerp municipal transit authorities, and courier operator logistics managers in Dutch urban corridors. Secondary validation drew from SEC filings of listed component suppliers, EU Machinery Directive implementation reports, and customs data on lithium-ion cell import flows. Bottom-up unit demand estimates from employer-sponsored leasing programs and fleet tender awards were triangulated against top-down market sizing from powertrain production capacity and battery pack shipment data.
Cross-referencing historical adoption curves from Benelux flat-terrain commuter corridors against panel input from battery swap-station network operators and thermal management system suppliers informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture (city, cargo, mountain, folding), battery chemistry (lithium-ion NMC, lithium-ion LFP, emerging solid-state), usage scenario (commuting, delivery, recreational), and procurement channel (fleet operators, individual, rentals). CAGRs were derived from logistic diffusion curves fitted to fleet penetration rates and employer program enrollment data, with specific inputs from F-Gas Regulation compliance cost trajectories and CSRD reporting obligation implementation schedules.
The model assumes a particular technology adoption path favoring integrated mid-drive systems with dual-battery hot-swap capability; alternative pathways for hub-motor configurations with extended single-battery range would alter the outlook for swap-station network density investments. Forecasts reflect assumptions on regulatory timeline adherence, lithium-ion cell cost trajectories, and fleet operator contract structure evolution. Practitioners should monitor proposed revisions to the EU Battery Regulation, F-Gas refrigerant phase-down schedules, and municipal tender specification shifts toward guaranteed uptime percentages for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Electric All-Terrain Vehicle (ATV) Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Middle-East E-Bike Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle Extruded Aluminum Battery Trays Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
North America Electric Vehicle Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market