

Battery Electric Vehicle (BEV) Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Electric Vehicle (BEV) Market Insights
Fleet procurement concentration is hardening as logistics operators and ride-hailing platforms consolidate vehicle orders into multi-year supply agreements. Tesla leverages its proprietary Supercharger network to lock in fleet uptime guarantees, while BYD anchors its position through in-house blade battery production that insulates against cell supply shocks. Volkswagen Group competes by extending its MEB platform across multiple brands to amortize development costs.
A battery electric vehicle is an automobile propelled exclusively by electric motors drawing energy from rechargeable battery packs, typically lithium-ion cells with energy densities exceeding 250 watt-hours per kilogram, designed to eliminate tailpipe emissions during operation. Passenger cars dominate current volume, though heavy duty trucks represent the fastest-expanding margin pool as fleet operators seek to electrify long-haul routes. Solid-state battery technology attracts disproportionate R&D allocation despite manufacturing immaturity, while fast charging stations constitute the infrastructure segment with the greatest capital deployment urgency.
The EPA, EU Green Deal framework, and China's MIIT administer the tripartite regulatory architecture governing emission mandates, battery recycling obligations, and new energy vehicle credit systems. OEMs must navigate divergent certification requirements that fragment platform engineering and complicate cross-border sales strategies. Stakeholders should monitor how battery passport traceability rules under REACH and forthcoming CSRD disclosures reshape supplier accountability and raw material sourcing decisions.
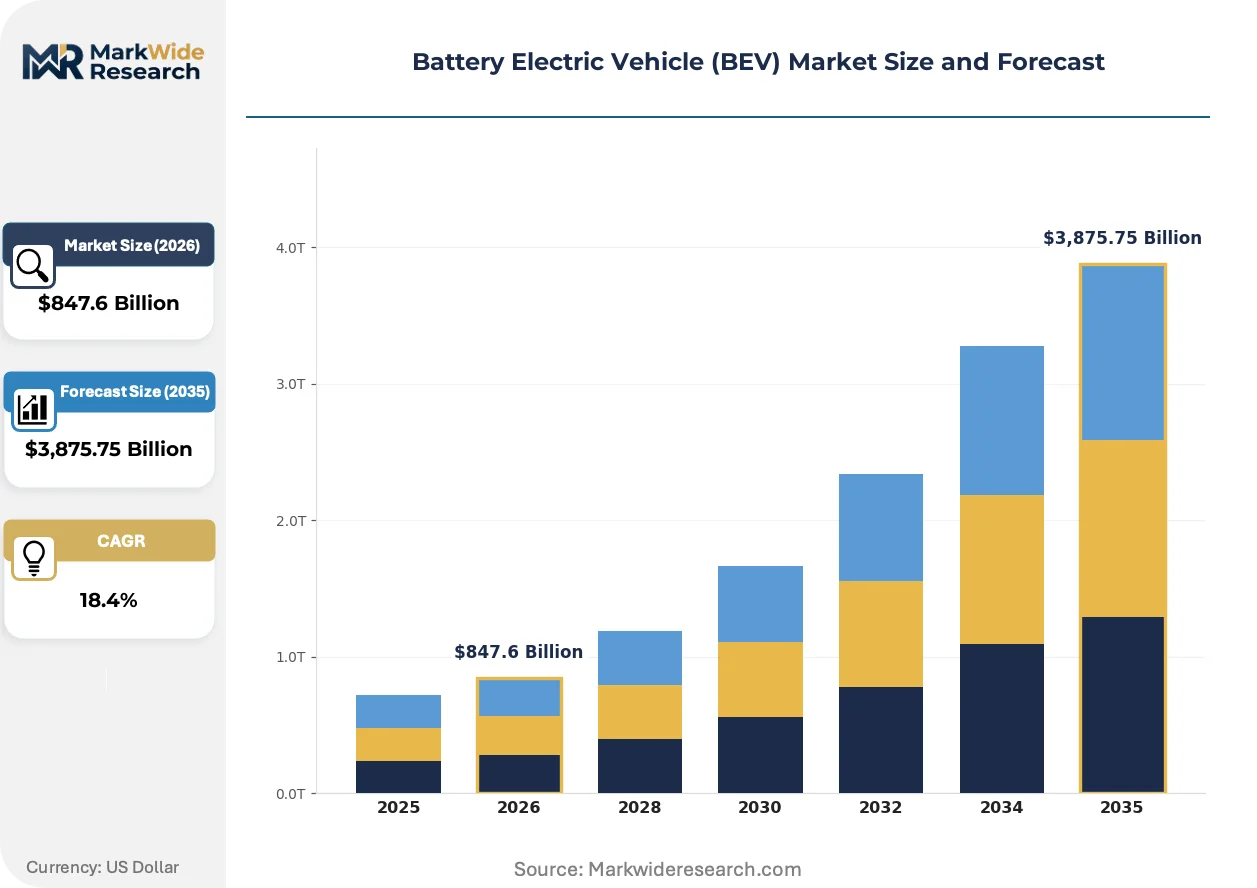
Market Dynamics
Fleet procurement concentration and cell-to-pack integration are compressing delivery timelines while regulatory mandates from the EPA, EU Green Deal, and China's MIIT force OEMs to accelerate zero-emission platform development.
Growth Catalysts
- EPA Tailpipe Standards:The EPA's zero-emission vehicle quotas are compelling OEMs to retool assembly lines ahead of 2030 compliance deadlines, pulling forward capital deployment into electrified platforms.
- Cell-to-Pack Integration:Structural battery pack designs are eliminating module housings, reducing cell-to-vehicle weight ratios and enabling extended range configurations for long-haul freight operators.
- Yangtze River Delta:China's manufacturing cluster concentrates cathode precursor refining and pack assembly within 200-kilometer radii, compressing export order fulfillment cycles by 40 percent versus dispersed supply chains.
Market Restraints
- Lithium Carbonate Volatility:Cathode material input costs fluctuate 300 percent across 18-month cycles, eroding margin predictability for battery pack producers locked into fixed-price fleet contracts.
- Nickel-Cobalt Concentration:Indonesian nickel processing and DRC cobalt mining control 70 percent of Class 1 battery metal supply, creating single-point vulnerability to export licensing disruptions.
- Solid-State Manufacturing Immaturity:Ceramic electrolyte sintering yields remain below 15 percent at pilot scale, delaying commercial deployment timelines by 4-6 years versus liquid electrolyte platforms.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting pack assembly investments targeting domestic two-wheeler and three-wheeler electrification.
- Battery Passport Traceability:EU REACH and forthcoming CSRD disclosures are creating first-mover advantage for OEMs with blockchain-verified supply chain documentation.
- Vehicle-to-Grid Convergence:Bidirectional charging hardware and distributed energy resource management software are enabling fleet operators to monetize stationary storage capacity during peak grid demand.
Industry Challenges
- High-Voltage Technician Scarcity:OEMs and service networks face 18-month lead times for certified EV powertrain specialists, constraining after-sales network expansion.
- Platform Certification Fragmentation:Divergent UN ECE, FMVSS, and GB/T crash-test protocols force engineering teams to maintain three parallel validation tracks, extending development cycles by 8-12 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Electric Vehicle (BEV) Market Trends and Innovations
Electrification is forcing simultaneous transformation across battery chemistry, charging infrastructure topology, and fleet procurement models. Three developments are restructuring competitive advantage.
Silicon-anode chemistries are replacing graphite in premium cell designs, increasing volumetric energy density by 20 percent without pack redesign. European luxury OEMs are qualifying these cells for 2026 platform launches. The technology is decentralizing range advantage from flagship sedans into compact crossover segments previously constrained by cost-engineered battery limits.
The EU Green Deal's battery recycling mandates under the ECHA framework are requiring 70 percent lithium recovery rates by 2030. This is redirecting capital toward hydrometallurgical refining capacity in Poland and Finland. Heavy-duty truck manufacturers with European assembly footprints are securing offtake agreements with these recyclers to hedge against virgin material price spikes.
Fleet operators are consolidating vehicle orders into multi-year supply agreements with uptime guarantees. Logistics platforms are replacing spot procurement with dedicated electrified fleet contracts spanning 5-7 years. This concentration is most visible in Germany's Rhine-Ruhr corridor, where regional freight cooperatives are pooling charging infrastructure investments to secure preferential OEM pricing.
Battery Electric Vehicle (BEV) Market Segmentation
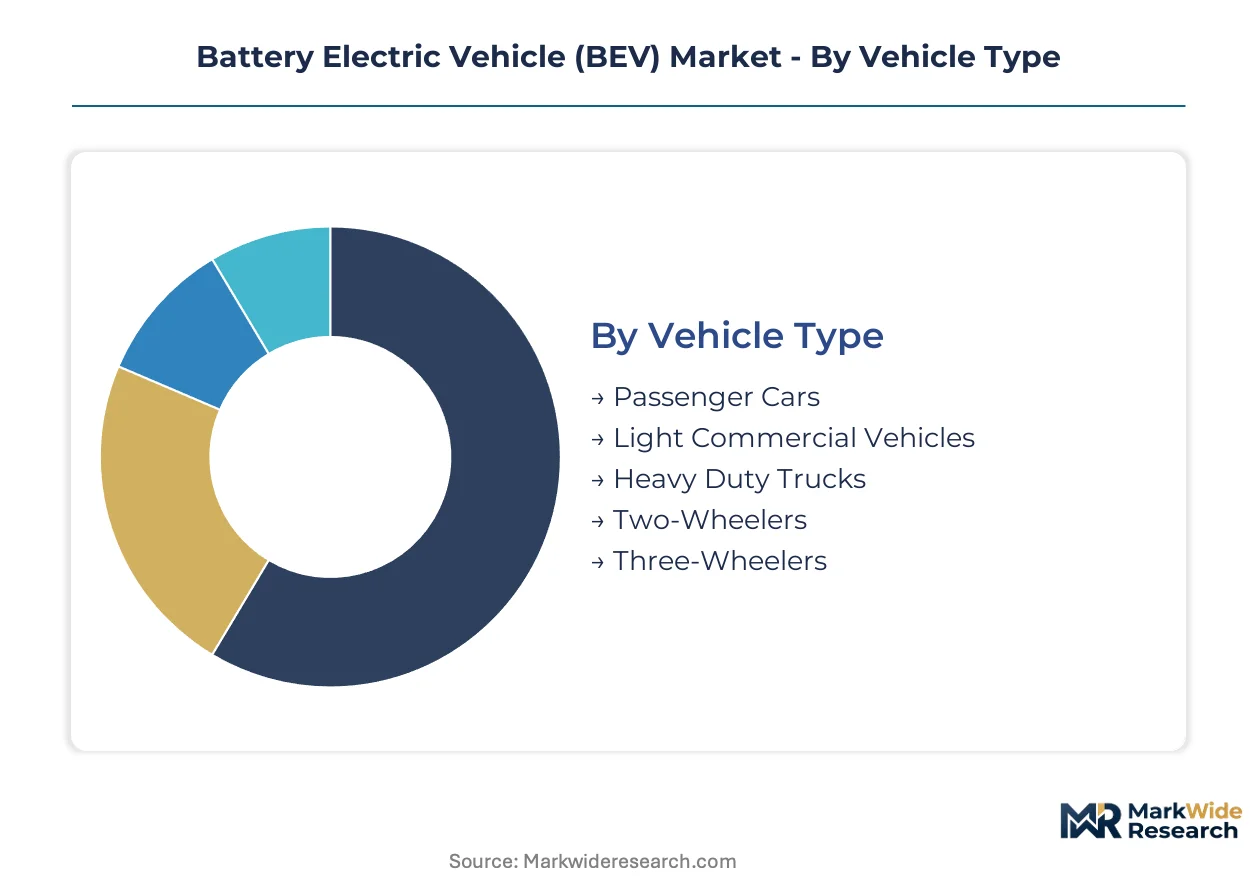
Segmentation in the BEV market determines which regulatory frameworks apply to platform engineering and which charging topologies must be deployed. Vehicle classification dictates UN ECE, FMVSS, or GB/T crash-test protocols, while battery chemistry shapes recycling obligations under REACH and MIIT circular economy rules.
Vehicle Type:
Certification burden varies sharply: passenger cars face harmonized UN ECE R94/R95 frontal and side-impact standards, while heavy duty trucks must satisfy additional FMVSS 223 rear impact guards and GB/T 31467 battery abuse testing for commercial freight duty cycles.
- Passenger Cars:Lithium-ion packs with NMC or LFP cathodes dominate, with cell-to-pack architectures reducing module weight. Demand concentrates in China's Yangtze River Delta for export fulfillment, constrained by EU battery passport traceability requirements under forthcoming CSRD disclosures.
- Heavy Duty Trucks:Structural battery packs integrated into chassis rails enable 500+ kilometer ranges for long-haul electrification. Fleet procurement in Germany's Rhine-Ruhr corridor drives volume, pulled by EU Green Deal zero-emission logistics mandates and EPA tailpipe standards for North American routes.
- Light Commercial Vehicles:Mid-size packs serving urban delivery routes with depot charging.
- Two-Wheelers:Swappable battery formats dominating India's PLI scheme-incentivized domestic production.
- Three-Wheelers:Low-voltage LFP configurations for last-mile logistics across South Asian markets.
Leading the category by volume: Passenger Cars. Growing fastest: Heavy Duty Trucks.
Battery Technology:
Cost tier stratification separates premium solid-state development from mass-market liquid electrolyte platforms, with cathode chemistry driving margin structure more than cell form factor.
- Lithium-Ion:NMC 811 and LFP variants constitute the commercial baseline, with energy densities exceeding 250 watt-hours per kilogram. Production gravity centers on Yangtze River Delta cathode precursor refining, where localized supply chains compress delivery timelines by 40 percent versus dispersed configurations.
- Solid-State:Ceramic electrolyte designs promise 500+ watt-hours per kilogram and intrinsic thermal stability. Pilot-scale sintering yields below 15 percent constrain commercial deployment, with European luxury OEMs targeting qualification for 2026 platform launches.
- Nickel-Metal Hydride:Legacy hybrid applications with limited BEV relevance.
- Lithium Polymer:Pouch formats for premium two-wheeler and aviation prototypes.
- Lead Acid:Auxiliary power units only, phased out of traction applications.
Dominating production scale: Lithium-Ion. Steepest R&D allocation: Solid-State.
Charging Infrastructure:
Application context determines hardware specification: fleet depot charging requires 150+ kilowatt DC capacity with load management software, while residential installations navigate utility interconnection queues and panel upgrade permitting.
- Fast Charging Stations:350-kilowatt liquid-cooled cable systems enabling 10-80 percent state-of-charge in 20 minutes. Capital deployment concentrates along German autobahn corridors and US Interstate highway corridors, compelled by fleet uptime guarantees in multi-year supply agreements.
- Home Chargers:Level 2 AC units at 7-22 kilowatts dominating individual consumer adoption. Installation backlogs in California and Texas distribution utility territories extend lead times to 8-12 weeks.
- Workplace Chargers:Mid-speed AC infrastructure with load-balancing for employee parking.
- Public Charging Points:Mixed-speed urban deployments with roaming network interoperability requirements.
- Battery Swapping Stations:Automated exchange systems for two-wheeler and three-wheeler fleet operators in Indian and Chinese metropolitan markets.
Highest capital intensity: Fast Charging Stations. Fastest network expansion: Battery Swapping Stations.
End User:
Customer type dictates procurement pattern and pricing structure: fleet operators negotiate 5-7 year supply agreements with preferential charging access, while individual consumers face spot market vehicle pricing and fragmented public charging availability.
- Fleet Operators:Logistics platforms and freight cooperatives consolidating vehicle orders into dedicated electrified fleet contracts. Germany's Rhine-Ruhr corridor freight pools exemplify pooled infrastructure investment models securing OEM volume discounts.
- Ride-Hailing Services:High-utilization duty cycles demanding 300,000+ kilometer battery warranties and guaranteed fast-charging network access. Tesla's Supercharger uptime guarantees anchor competitive positioning for this segment.
- Individual Consumers:Price-sensitive purchasers with fragmented home charging installation experiences.
- Car Rental Companies:Short-term fleet turnover with residual value risk concentrated in battery degradation uncertainty.
Commanding procurement volume: Fleet Operators. Expanding most quickly: Ride-Hailing Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement concentration in China's Yangtze River Delta manufacturing cluster compresses delivery timelines for export markets, while regulatory mandates from the EPA, EU Green Deal, and China's MIIT reshape production schedules across three continents.
China
Domestic demand for passenger cars and heavy duty trucks pulls cell-to-pack integration investments into the Yangtze River Delta, where cathode precursor refining and pack assembly concentrate within 200-kilometer radii. MIIT's new energy vehicle credit system mandates zero-emission quotas that OEMs must satisfy through 2035. Localized supply chains in this cluster reduce export order fulfillment cycles by 40 percent versus dispersed configurations.
United States
Fleet operators across California and Texas are expanding electrified logistics contracts as EPA tailpipe standards compel zero-emission vehicle quotas ahead of 2030 compliance deadlines. The EPA administers emission mandates that force OEMs to retool assembly lines and pull forward capital deployment. Fast charging station deployment concentrates along Interstate highway corridors to secure uptime guarantees in multi-year supply agreements.
Germany
Freight cooperatives in the Rhine-Ruhr corridor are pooling charging infrastructure investments to secure preferential OEM pricing for heavy duty truck electrification. The EU Green Deal framework mandates zero-emission logistics timelines that reshape fleet procurement patterns. Regional freight pools exemplify consolidated vehicle orders into dedicated electrified fleet contracts spanning 5-7 years.
India
Production-linked incentives for advanced chemistry cell manufacturing are attracting pack assembly investments targeting domestic two-wheeler and three-wheeler electrification under the PLI scheme. The country's national automotive regulator enforces localization requirements that shape foreign OEM entry strategies. Manufacturing investments concentrate in Gujarat and Tamil Nadu to serve metropolitan last-mile logistics demand.
South Korea
Battery cell producers are expanding capacity to supply European and North American OEMs seeking alternative sources to Chinese cathode supply chains. METI-aligned industrial policy supports R&D allocation toward solid-state battery technologies. Production gravity in the Seoul Capital Area feeds into export-oriented pack assembly for premium passenger car platforms.
Battery Electric Vehicle (BEV) Market Competitive Landscape
Chinese producers anchor the volume tier through integrated battery supply chains; German and American specialists hold premium positioning through platform diversification and charging network control. The market structure consolidates around three strategic archetypes: vertically integrated battery manufacturers, multi-brand platform extenders, and charging infrastructure operators. Competitive moves center on captive cathode supply agreements and multi-year fleet uptime guarantees.
Within the integrated battery tier, BYD exemplifies backward control over cell production that insulates against supply shocks. Tesla occupies a position defined by proprietary fast-charging network lock-in for fleet operators. Volkswagen Group represents the multi-brand platform archetype, extending shared architectures across marques to amortize development costs. These three anchors illustrate how geographic supply chain positioning and infrastructure control separate competitive tiers.
| Leading Market Players |
|---|
| Tesla |
| BYD |
| Volkswagen Group |
| General Motors |
| Hyundai Motor Group |
| Stellantis |
| Ford |
| BMW Group |
| Mercedes-Benz Group |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement consolidation into multi-year supply agreements is forcing pack producers to absorb lithium carbonate volatility while locking in fixed-price contracts, compressing margins and accelerating backward integration into cathode precursor refining.
Pricing Analysis
Volume contracts for heavy duty trucks and passenger cars operate on divergent margin structures. Premium passenger car platforms command price differentiation through solid-state battery warranties and Supercharger network access bundling, while standard-tier fleet contracts face cost compression from LFP cell commoditization. Margins are tightening most severely in mid-size pack segments serving light commercial vehicles, where spot cathode purchasing exposes producers to nickel-cobalt price spikes. Ride-hailing operators demonstrate lowest price sensitivity due to uptime guarantee requirements, whereas individual consumer channels show highest elasticity to sticker price movements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand through dedicated cathode offtake agreements, while aftermarket distribution runs through certified service networks constrained by high-voltage technician scarcity. Cell production concentrates in China, South Korea, and Japan, with cathode precursor refining anchored in Indonesia and the DRC. The supply chain draws from Class 1 nickel and cobalt hydroxide inputs with limited qualified alternative sources. Single-source vulnerability in Indonesian nickel processing creates tariff exposure risk as export licensing regimes shift. Distribution downstream feeds through OEM assembly plants with just-in-time pack delivery protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
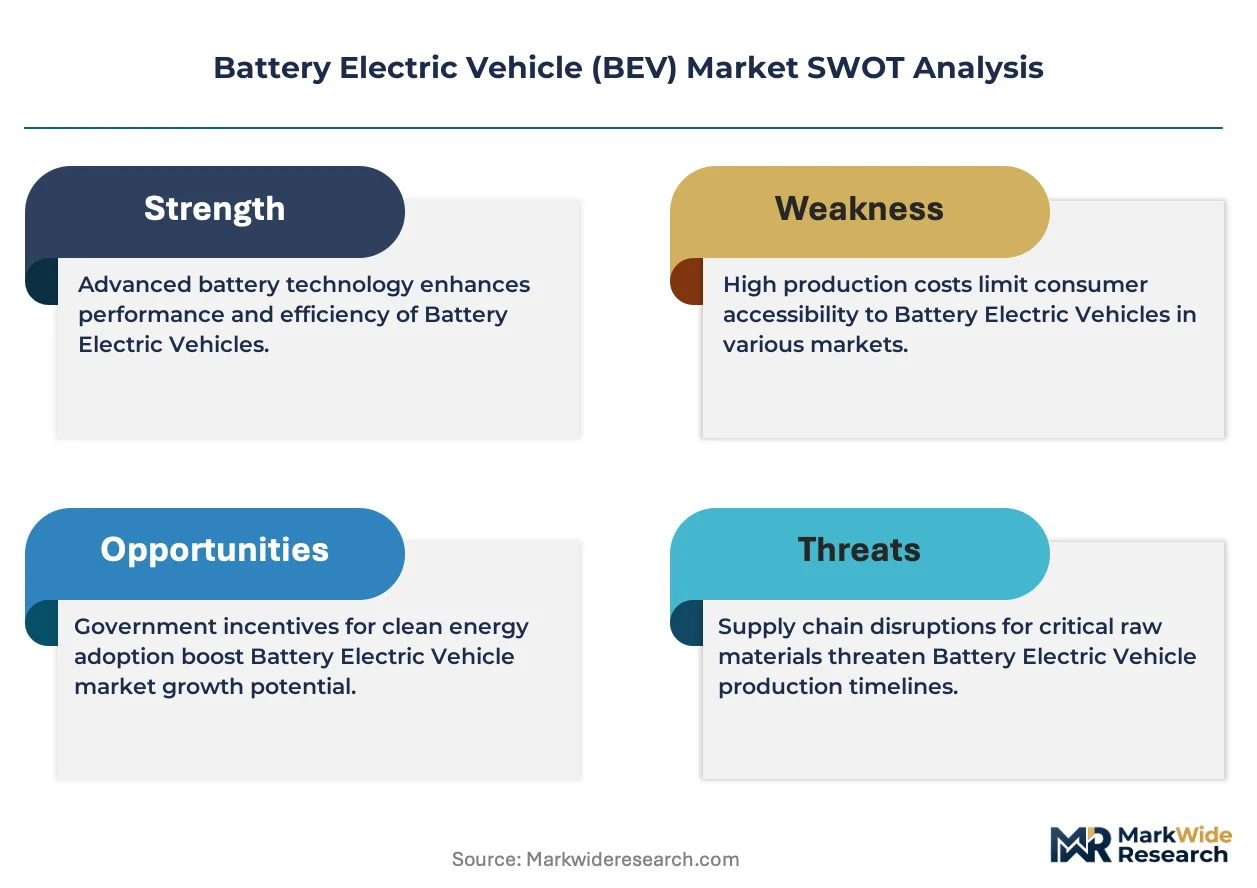
Analyst Recommendations
Cell manufacturing capacity constraints in qualified supply geographies are propping pricing power for producers with captive cathode agreements, creating a supply-constrained market structure favoring incumbents with integrated refining footprints.
For Market Incumbents: Acquire hydrometallurgical refining assets in Poland and Finland to hedge against virgin material price spikes and satisfy EU battery recycling mandates. Secure long-term nickel offtake from Indonesian processors with export license stability clauses. Solid-state battery startups with pilot-scale ceramic electrolyte yields below commercial thresholds threaten to displace liquid electrolyte platforms if sintering breakthroughs emerge. For New Entrants and Emerging Players: Direct fleet procurement platforms offer the lowest barrier entry path for battery-as-a-service models targeting India's two-wheeler and three-wheeler electrification under PLI scheme incentives. White space concentrates in vehicle-to-grid software integration for bidirectional charging hardware, where incumbent OEMs lack dedicated energy resource management capabilities. A charging infrastructure partnership strategy with regional freight cooperatives bypasses capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: The window for entry favors pack assembly specialists with established OEM qualification pathways and blockchain-verified supply chain documentation ahead of CSRD disclosure mandates. Long-term viability hinges on five-to-ten year offtake visibility with fleet operators consolidating into multi-year contracts. Monitor ceramic electrolyte sintering yield improvements at pilot scale as the inflection signal for solid-state platform commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Integration | Structural battery designs eliminate module housings, reducing weight ratios for long-haul freight configurations. |
| Cathode Precursor Refining Investment | Hydrometallurgical capacity in Poland and Finland hedges against Indonesian nickel export licensing disruptions. |
| Battery Passport Traceability | Blockchain-verified documentation creates first-mover advantage under EU REACH and forthcoming CSRD disclosure rules. |
| Vehicle-to-Grid Software Development | Bidirectional charging management enables fleet monetization of stationary storage during peak grid demand periods. |
| Fast Charging Network Partnership | Uptime guarantees along German autobahn and US Interstate corridors secure multi-year fleet supply agreement volumes. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and charging infrastructure developers. Bottom-up triangulation validated cell production volumes against MIIT registration databases and EPA compliance certification records, while top-down checks applied IEA electric vehicle deployment trajectories and Yangtze River Delta export customs data.
Segment-level modeling operated at vehicle class, battery chemistry, charging topology, and end-user archetype granularity throughout the forecast period. CAGRs derived from production capacity expansion announcements, fleet procurement pipeline aggregation, and regulatory mandate compliance trajectory analysis. Forecast inputs incorporated solid-state battery pilot yield data, lithium carbonate price cycle amplitude, and high-voltage technician training pipeline constraints.
The model holds under stable cathode supply licensing regimes and fleet procurement credit policy continuity; deviation in Indonesian export restrictions or EPA zero-emission quota acceleration would shift volume trajectories. Forecasts reflect base-case assumptions regarding cell-to-pack adoption rates and charging infrastructure deployment cadence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.