
 United States Electric Car Market | 2026-2036
United States Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Car Market Analytics
Fleet operator consolidation is repositioning procurement patterns across the United States electric car landscape. Tesla leverages its integrated charging network to sustain fleet contracts at scale. Ford anchors commercial electrification through its F-150 Lightning platform and fleet-specific service programs. Rivian competes in last-mile delivery segments with purpose-built electric vans designed for logistics operators.
United States electric cars are battery-electric or plug-in hybrid vehicles powered by rechargeable electrochemical storage systems, typically operating at 400-800 volt architectures and producing zero tailpipe emissions during electric-mode operation. Their primary purpose is to displace petroleum-based transportation with grid-connected propulsion systems that reduce operating costs and emissions intensity. The SUV segment leads unit volumes as American buyers prioritize cabin space and all-weather capability, while solid-state battery technology represents the fastest-advancing chemistry frontier with potential energy density breakthroughs. Sedans retain importance in ride-hailing and corporate fleet applications where aerodynamic efficiency and total cost of ownership dominate purchasing criteria.
The National Highway Traffic Safety Administration administers federal motor vehicle safety standards that govern crashworthiness and autonomous system performance for electric vehicles sold in the United States. The Environmental Protection Agency sets tailpipe emissions benchmarks and fuel economy equivalency ratings that determine manufacturer compliance obligations and consumer-facing efficiency labels. The Federal Energy Regulatory Commission influences interstate transmission planning that governs grid capacity available for public fast-charging expansion. Stakeholders must monitor how state-level zero-emission vehicle mandates interact with federal tax credit phase-out schedules to anticipate demand inflection points.
Market Dynamics
Fleet electrification mandates from California, New York, and Washington are compressing procurement timelines for commercial buyers while the Inflation Reduction Act's domestic assembly requirements force supply chain reconfiguration toward North American battery cell production.
Growth Catalysts
- Inflation Reduction Act Tax Credits:Federal consumer incentives up to $7,500 and commercial credits up to $40,000 accelerate fleet operator conversion timelines and expand addressable buyer pools.
- State ZEV Mandates:California's Advanced Clean Cars II regulation and its Section 177 state adopters create binding sales floor requirements that guarantee minimum demand volumes through 2035.
- Lithium Iron Phosphate Chemistry:LFP cell production scaling in Nevada and Michigan reduces battery pack costs while improving thermal stability for commercial duty cycles.
Market Restraints
- Cobalt and Nickel Supply Concentration:DRC cobalt and Indonesian nickel refining dependencies expose battery supply chains to geopolitical disruption and ESG compliance risks.
- Fast-Charging Infrastructure Gaps:Rural interstate corridors and multi-unit residential buildings lack sufficient 150kW+ station density to support mass-market adoption beyond urban cores.
- Grid Interconnection Queues:Utility interconnection delays for charging depots extend fleet electrification project timelines by 18-36 months in high-demand utility territories.
Strategic Opportunities
- Texas and Florida Market Expansion:These states lack ZEV mandates but offer deregulated retail electricity markets enabling fleet operators to negotiate direct renewable power purchase agreements for charging infrastructure.
- V2G Bidirectional Integration:Vehicle-to-grid technology convergence with utility demand response programs creates new revenue streams for fleet owners through frequency regulation services.
- Last-Mile Delivery Electrification:E-commerce logistics hubs in Illinois, Ohio, and Georgia present concentrated deployment opportunities for medium-duty electric vans with predictable route profiles.
Industry Challenges
- Battery Engineering Talent Scarcity:Cell chemistry optimization and thermal management expertise shortages constrain OEM hiring for next-generation platform development.
- Homologation Timeline Compression:NHTSA crash testing and EPA certification cycles create launch delays as manufacturers accelerate model-year refreshes to match competitive pressure.
- Service Network Reconfiguration:High-voltage technician training and specialized tooling requirements strain dealer capacity as electric vehicle sales mix rises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Car Market |
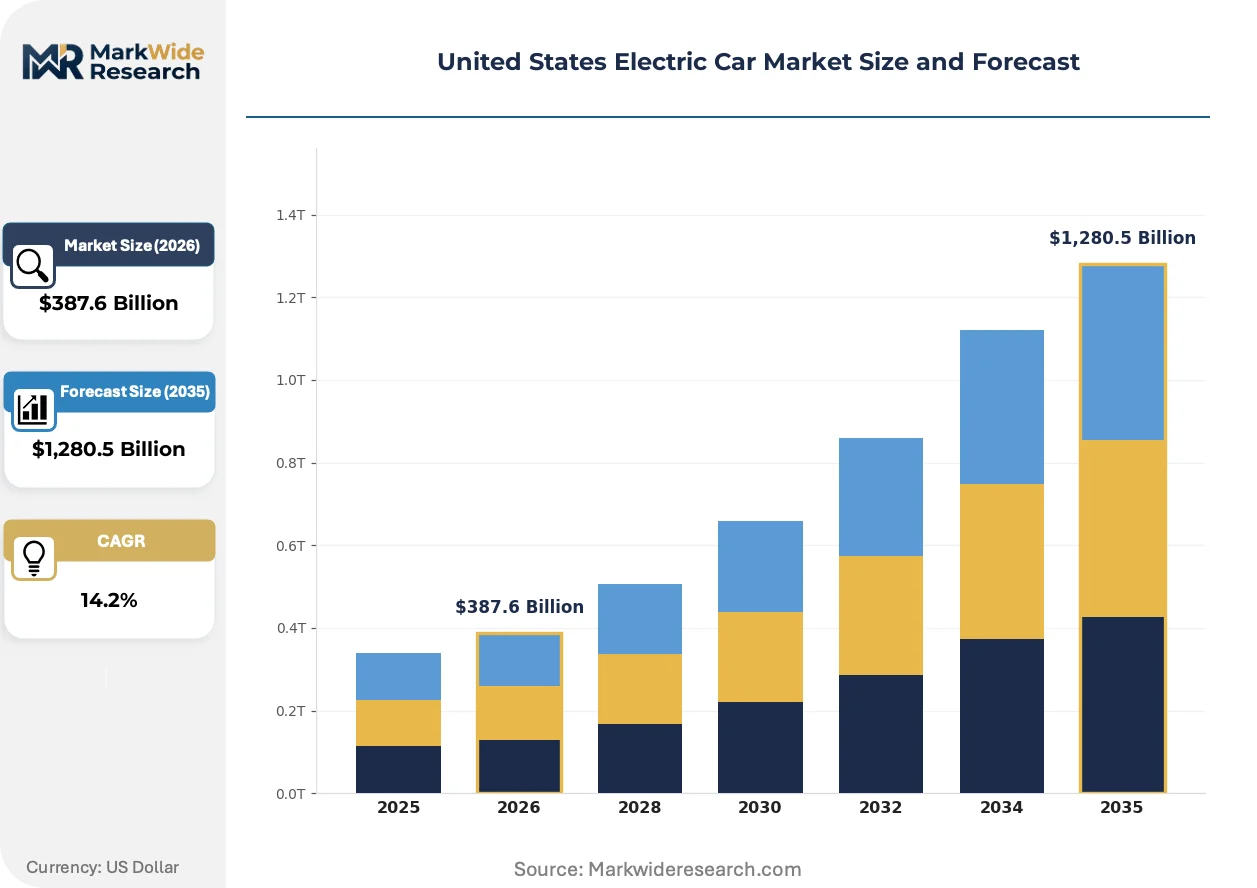
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,280.5 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Hatchbacks, Coupes Battery Technology: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Charging Infrastructure: Home Chargers, Public Charging Stations, Fast Chargers, Wireless Chargers Customer Type: Individual Consumers, Fleet Operators, Ride-Hailing Services, Corporate Users |
| Companies Covered | Tesla, Chevrolet, Ford, Hyundai, Rivian, BMW, Mercedes-Benz, Honda, Cadillac, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Car Market Evolving Landscape
Cell-to-pack battery architectures and silicon-anode chemistries are compressing cost curves while software-defined vehicle platforms enable over-the-air feature monetization. These shifts are redrawing competitive boundaries between hardware specialists and technology integrators.
Cell-to-pack designs are eliminating module housings and redundant interconnection hardware to increase volumetric energy density by 15-20%. Ford and General Motors are adopting this architecture for their next-generation Ultium and TE1 platforms. The technology is modularizing battery manufacturing by allowing standardized cell formats across multiple vehicle segments.
The EPA's pending greenhouse gas standards for model years 2027-2032 will tighten fleet-average emissions requirements and effectively mandate plug-in hybrid or battery-electric powertrains for light-duty vehicles. Manufacturers are responding by accelerating powertrain diversification and securing battery supply agreements. Commercial van and pickup segments face the steepest compliance obligations due to their higher baseline emissions profiles.
Fleet operators are consolidating procurement through direct OEM relationships and bypassing traditional dealer networks for volume transactions. Large logistics companies now negotiate enterprise service agreements covering charging infrastructure, maintenance, and residual value guarantees. This pattern concentrates most visibly in California's Central Valley agricultural processing corridors and Texas logistics hubs serving Mexico trade lanes.
United States Electric Car Market Segmentation
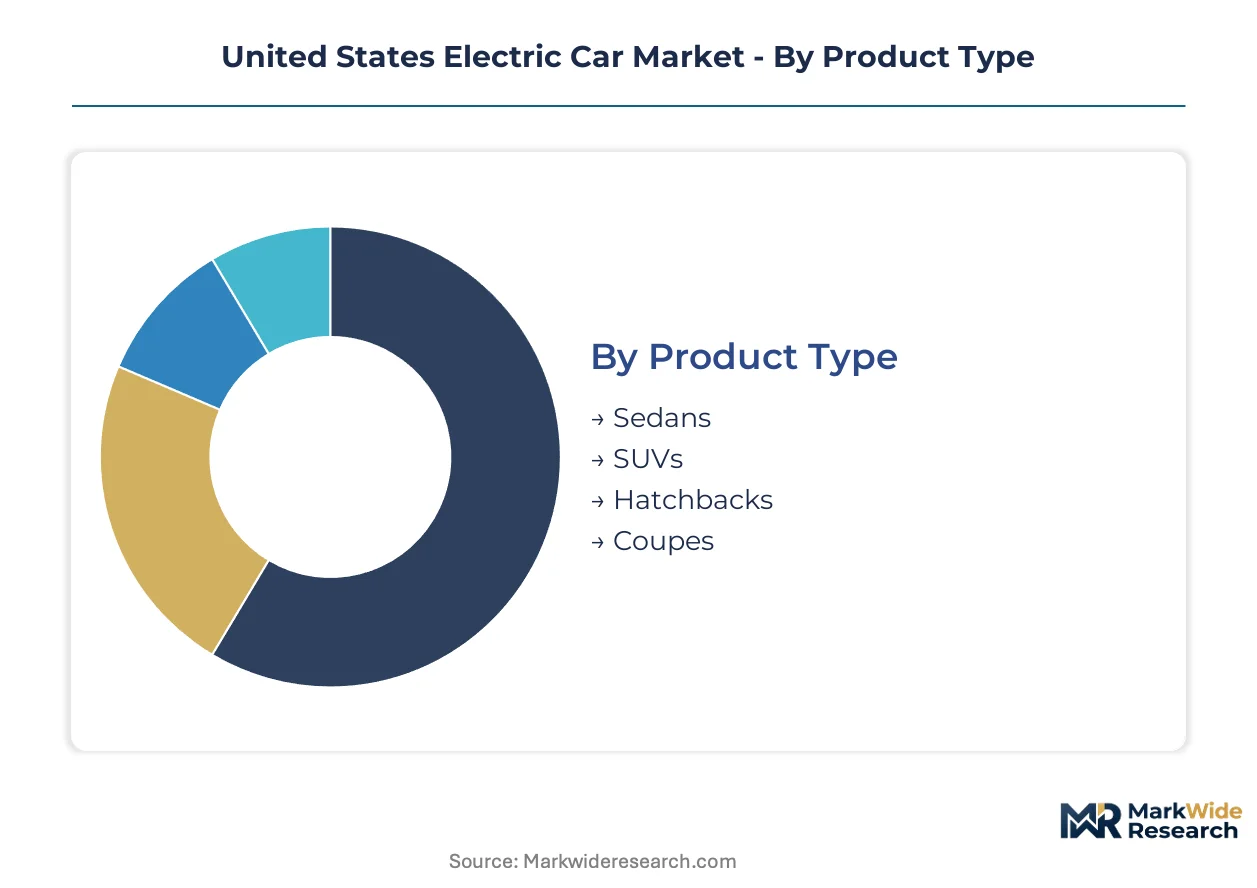
Segmentation reveals how buyer priorities diverge across the United States electric car landscape. Product configuration, energy storage chemistry, refueling access, and procurement scale each command distinct competitive strategies from manufacturers and infrastructure providers.
Product Type:
American buyers prioritize cabin utility and weather capability over aerodynamic efficiency, driving divergent platform investments across body styles.
- SUVs:Three-row and compact crossover architectures dominate unit volumes, with all-wheel-drive configurations capturing preference in Snow Belt states and mountainous regions. Demand concentrates in Texas suburban corridors and California's Central Valley, where towing capacity and ground clearance matter for recreational and agricultural use cases.
- Sedans:Slipstream body designs maximize range efficiency for high-mileage operators. Corporate fleet procurement in New York and Washington state favors these platforms for executive transport and ride-hailing deployment, where total cost of ownership calculations reward aerodynamic gains.
- Hatchbacks:Compact footprints suit urban parking constraints and single-occupant commuting patterns. These vehicles find strongest uptake in dense coastal metros with limited residential garage access.
- Coupes:Performance-oriented two-door configurations serve enthusiast segments with premium positioning. Low production volumes reflect niche demand concentrated in affluent California and Florida markets.
Volume sits with SUVs; growth tilts toward sedans as fleet electrification accelerates.
Battery Technology:
Chemistry selection determines thermal performance, cost structure, and supply chain exposure for United States electric car manufacturers.
- Lithium-Ion:NMC and LFP variants constitute the installed base, with LFP scaling rapidly in Nevada and Michigan cell plants. NHTSA crashworthiness protocols and EPA range certification requirements shape pack engineering priorities for domestic assembly compliance.
- Solid-State:Ceramic electrolyte architectures promise energy density breakthroughs and reduced fire risk. Toyota and QuantumScape pilot programs target commercialization for premium segments, though manufacturing yield challenges delay mass deployment.
- Nickel-Metal Hydride:Mature chemistry persists in hybrid-electric transitions and budget-conscious fleet retrofits. Toyota maintains production for legacy Prius platforms serving cost-sensitive municipal buyers.
- Lead-Acid:Auxiliary power applications and low-speed neighborhood electric vehicles retain this chemistry for its established recycling infrastructure and minimal thermal management requirements.
Installed capacity clusters on lithium-ion; solid-state claims the steepest expansion trajectory pending manufacturing scale.
Charging Infrastructure:
Refueling modality selection reflects housing tenure, route predictability, and time-value calculations across United States electric car user segments.
- Home Chargers:Level 2 residential installations provide overnight replenishment for single-family homeowners. California's Title 24 building codes now mandate pre-wiring in new construction, embedding infrastructure ahead of vehicle adoption.
- Public Charging Stations:Level 2 destination chargers at retail and workplace locations serve apartment dwellers and daytime parkers. Deployment concentrates in urban cores with high multi-unit housing density.
- Fast Chargers:DC rapid stations at 150kW+ enable interstate corridor travel and commercial fleet turnaround. NEVI formula funding targets rural interstate gaps identified by DOT alternative fuel corridor designations.
- Wireless Chargers:Inductive pad systems eliminate connector wear for autonomous fleet depots and luxury residential installations. SAE J2954 standardization enables interoperability across hardware suppliers.
Transaction volume flows through home installations; capital deployment shifts fastest toward fast-charging networks closing interstate coverage gaps.
Customer Type:
Procurement scale and utilization intensity separate United States electric car buyer segments, reshaping distribution and service models.
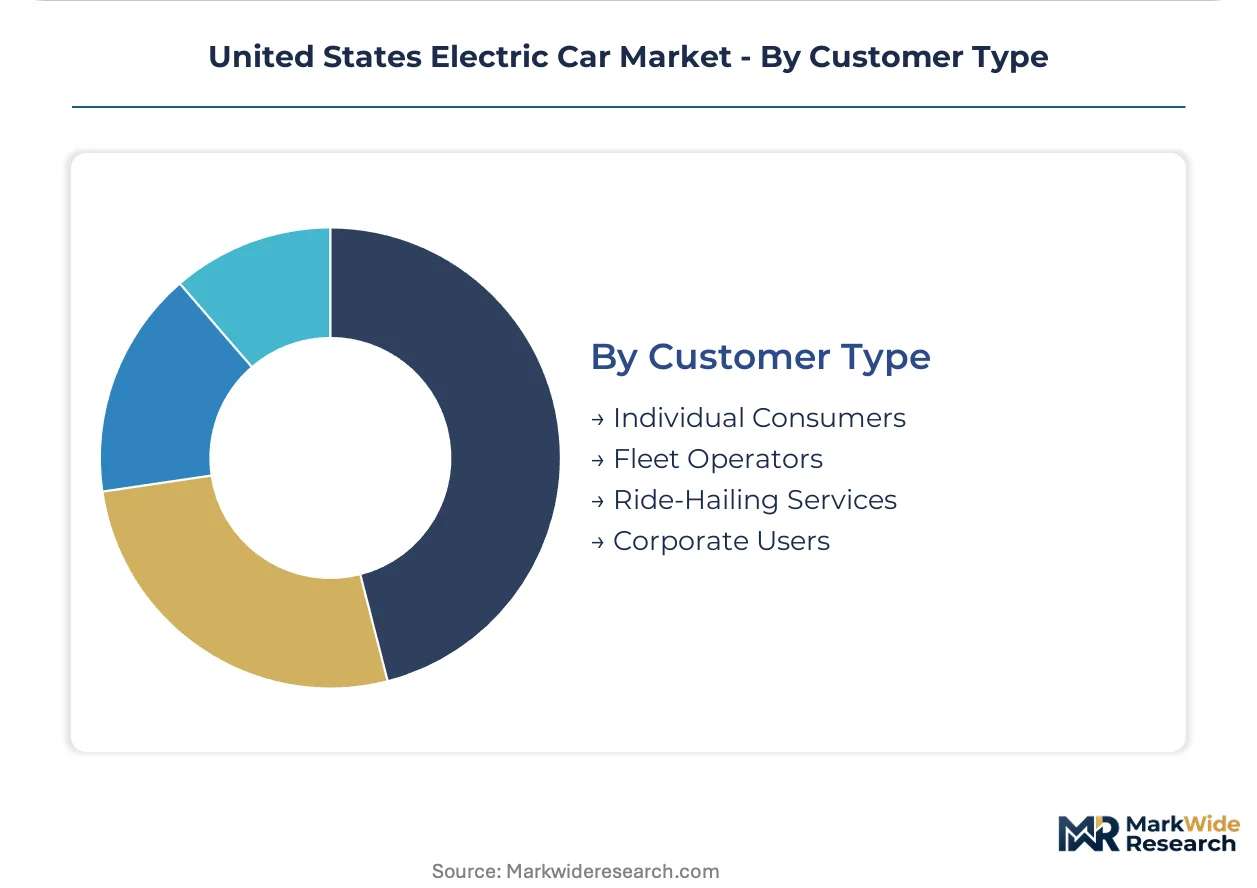
- Fleet Operators:Commercial buyers negotiate enterprise agreements covering vehicles, charging infrastructure, and maintenance through direct OEM relationships. California Advanced Clean Fleets regulation compresses procurement timelines for medium- and heavy-duty conversions.
- Individual Consumers:Retail purchasers respond to IRA tax credit eligibility and state rebate stacking. Dealer networks remain primary transaction channels, though Tesla's direct sales model pressures franchise laws in Texas and other states.
- Ride-Hailing Services:Uber and Lyft driver-partners select vehicles for passenger capacity and Supercharger network access. These operators maximize utilization intensity, accelerating battery degradation and replacement cycles.
- Corporate Users:Enterprise procurement for sales fleets and executive transport emphasizes brand alignment and service integration. Leasing structures dominate to manage residual value risk and technology obsolescence.
Fleet operators capture the fastest volume expansion; individual consumers retain the largest absolute buyer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Nevada's Thacker Pass and North Carolina's Piedmont region anchor domestic battery supply chain localization efforts. Federal incentives under the Inflation Reduction Act tie tax credit eligibility to domestic assembly and critical mineral sourcing thresholds.
California
Fleet electrification mandates from the California Air Resources Board drive medium-duty commercial vehicle conversions in Central Valley agricultural corridors. The Advanced Clean Cars II regulation imposes binding zero-emission sales floors through 2035. Tesla's Fremont manufacturing complex and Rivian's Irvine design center concentrate engineering talent in the San Francisco Bay and Los Angeles metro areas.
Texas
Deregulated retail electricity markets enable fleet operators to negotiate direct renewable power purchase agreements for charging infrastructure deployment. The state lacks zero-emission vehicle mandates but attracts manufacturing investment through property tax abatements. Tesla's Gigafactory Texas in Austin anchors cell production and final assembly operations serving central and southern markets.
Michigan
Traditional automotive engineering clusters in Detroit and Ann Arbor pivot toward battery-electric platform development and high-voltage technician training programs. The state's economic development authority offers transformation incentives for legacy supplier retooling. General Motors' Ultium cell plant in Lansing and Ford's Rouge Electric Vehicle Center in Dearborn concentrate capital deployment.
Florida
Suburban sprawl and single-family housing stock favor residential Level 2 charging adoption across the Orlando and Tampa corridors. The state offers utility rebate programs but maintains minimal regulatory mandates. Miami-Dade County's municipal fleet electrification program and Port Everglades drayage conversion projects anchor public-sector demand.
Illinois
Last-mile delivery electrification concentrates in Chicago metropolitan logistics hubs serving e-commerce distribution networks. The state matches federal tax credits with additional point-of-sale rebates for commercial buyers. Rivian's Normal manufacturing facility produces electric delivery vans for fleet operators with predictable urban route profiles.
United States Electric Car Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue purpose-built commercial segments and charging-integrated service models. The market structure reflects moderate consolidation around vertically integrated manufacturers with captive battery supply and charging networks. Three archetypes dominate: integrated platform providers combining hardware with energy services, legacy automakers retooling combustion-era supply chains, and venture-backed specialists targeting fleet niches. Competitive moves center on cell supply agreements locking lithium chemistry access and direct fleet procurement relationships bypassing dealer networks.
Within the integrated platform tier, Tesla exemplifies the charging-network-anchored model that sustains fleet contracts through infrastructure control. Among legacy manufacturers transitioning powertrain portfolios, Ford and Chevrolet represent the Detroit-based archetype leveraging existing dealer service networks for commercial buyer retention. These three companies occupy positions spanning consumer retail and enterprise procurement channels.
| Leading Market Players |
|---|
| Tesla |
| Chevrolet |
| Ford |
| Hyundai |
| Rivian |
| BMW |
| Mercedes-Benz |
| Honda |
| Cadillac |
| Others |
Value Network & Pricing Analysis
California's Advanced Clean Cars II regulation gates both qualified battery supply and premium-tier pricing access for manufacturers seeking to capture fleet procurement contracts in the United States electric car market. OEMs must demonstrate domestic assembly compliance to unlock IRA tax credit stacking, concentrating pricing power among vertically integrated producers with captive cell production.
Pricing Analysis
Volume sits with mass-market SUVs where margins compress under lithium cost volatility; premium sedans and commercial vans retain pricing power through fleet service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Tesla's integrated charging bundles from Ford's dealer-anchored service programs and budget LFP configurations. Cost compression in the standard tier is intensifying because Nevada and Michigan cell plants are scaling LFP production. Fleet operators exhibit the highest price sensitivity due to total cost of ownership calculations, while individual luxury buyers show the least.
Supply Chain Analysis
Workforce availability constraints in Nevada, Michigan, and Texas battery manufacturing corridors are forcing OEMs to compete for electrochemical engineering talent and high-voltage technician training capacity. Cathode active material supply draws from Indonesian nickel refining and DRC cobalt concentration, creating single-source vulnerability for NMC chemistry. Lithium hydroxide feedstock hinges on Australian spodumene and Chilean brine extraction. Distribution runs through direct OEM-fleet procurement relationships that bypass traditional dealer networks for volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States electric car market reads as supply-constrained: North American battery cell capacity bottlenecks prop pricing power for manufacturers with secured cathode supply agreements.
For Market Incumbents: Anchor fleet retention through charging infrastructure ownership and residual value guarantees that neutralize emerging entrants' price undercutting. Lock lithium offtake agreements with Australian and Chilean producers before capacity commitments exhaust. Defend margin position by accelerating cell-to-pack architecture adoption to reduce module-level cost. For New Entrants and Emerging Players: The Inflation Reduction Act's domestic content thresholds in the United States open a window for regional cell producers to capture commercial van procurement in Texas and Florida logistics corridors. Target last-mile delivery electrification in Illinois and Ohio where route predictability minimizes range anxiety. Pursue direct power purchase agreements with deregulated Texas utilities as a service differentiation anchor. For Investors and Strategic Acquirers: NHTSA homologation timeline compression for new platform launches is the leading indicator that engineering talent scarcity will drive consolidation among mid-tier specialists. Long-term viability favors producers with backward integration into cathode precursor refining and software-defined vehicle architectures. Watch California Air Resources Board enforcement actions on Advanced Clean Fleets compliance as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell allocation from Nevada and Michigan plants for fleet scale deployment. |
| Charging Infrastructure Partnership | Locks NEVI-funded corridor access for interstate commercial vehicle operations. |
| Software-Defined Vehicle Investment | Enables over-the-air feature monetization and fleet telematics integration. |
| Geographic Manufacturing Footprint | Positions final assembly in Texas or Michigan for IRA domestic content compliance. |
| Platform Standardization | Reduces cell format complexity across SUV and commercial van segments. |
Research Methodology
Independent corroboration across OEM platform engineering directors, fleet procurement officers at logistics operators, NHTSA regulatory affairs specialists, and utility demand response planners underwrites the qualitative findings. Secondary validation draws from EPA certification databases, FERC interconnection queue filings, state ZEV mandate compliance reports, and vehicle registration data from IHS Markit. Bottom-up segment sizing triangulates against top-down macroeconomic anchors.
Comparable-period anchoring to historical production volumes and fleet conversion timelines establishes the forecast window baseline. The analytical framework segments by vehicle class, propulsion architecture, battery chemistry, charging modality, and customer procurement scale across the projection horizon. CAGRs derive from logistic adoption curves fitted to state mandate trajectories and IRA incentive phase schedules. Forecast inputs include lithium carbonate price indices and grid interconnection approval velocity.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions on cathode material cost trajectories and NEVI deployment pacing. Material deviation in federal tax credit continuity or critical mineral sourcing rules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Germany Automotive High Performance Electric Vehicles Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Indian E-Bike Rental Market
Electric Vehicles
Water Proof E-Scooter Market