
 Fuel-Cell Electric Vehicle Insulation Market | 2026-2036
Fuel-Cell Electric Vehicle Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel-Cell Electric Vehicle Insulation Market Analysis
EU Green Deal enforcement is decoupling thermal-management compliance from legacy cost structures in European fuel-cell vehicle assembly. DuPont leverages its polymer science depth to anchor high-temperature membrane positioning across OEM supply chains. Saint-Gobain sustains ceramic fiber leadership through backward integration into alumina-silica raw material sourcing. Morgan Advanced Materials competes on proprietary microporous insulation formulations purpose-built for fuel-cell stack enclosures.
Fuel-cell electric vehicle insulation comprises engineered materials—polymer films, ceramic fibers, closed-cell foams, and metallized barriers—engineered to maintain stack operating temperatures between 60°C and 85°C while containing hydrogen permeation and electrical isolation risks. Its primary commercial purpose is protecting proton-exchange membrane stacks from thermal runaway, acoustic fatigue, and fire propagation under varying load cycles. Thermal insulation dominates current procurement volumes given the energy-density penalties of suboptimal stack temperature control, while acoustic and fire-resistant categories capture expanding share as passenger-car cabin standards tighten. Foam materials lead on weight-efficiency metrics for bus and train platforms where mass reduction directly extends hydrogen range.
FDA material-safety guidelines for hydrogen-contact surfaces, EPA emissions-certification pathways for zero-exhaust vehicles, and NHTSA crashworthiness standards for high-voltage thermal events collectively shape product-design requirements and market-access timelines in the United States. EMA REACH compliance and CE marking for automotive subsystem integration impose parallel substance-restriction and conformity-assessment burdens across European supply chains. Stakeholders must monitor evolving hydrogen-storage safety protocols and thermal-test methodologies as regulatory divergence between jurisdictions accelerates certification complexity.
Market Dynamics
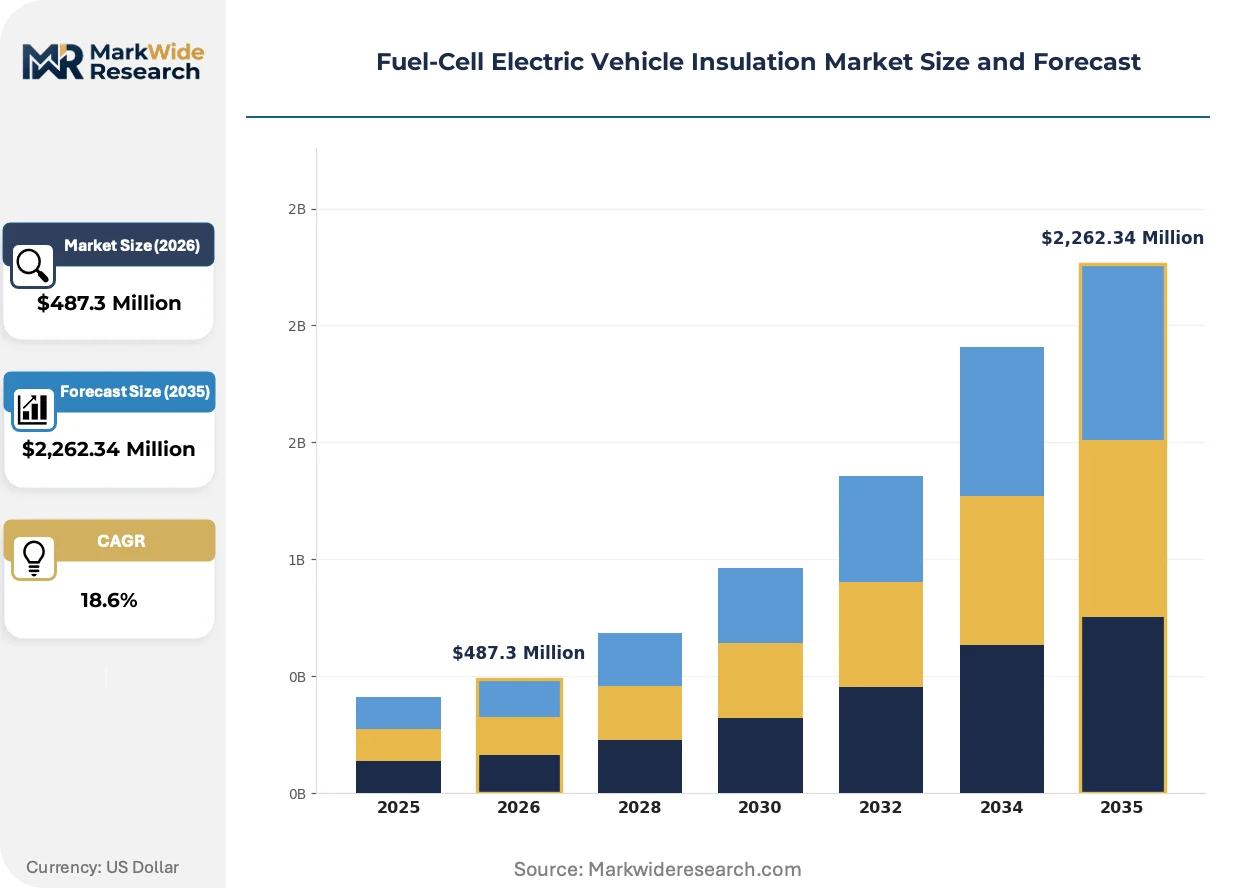
The EU Green Deal's thermal-efficiency mandates are forcing OEMs to redesign stack enclosures around higher-performance insulation architectures, decoupling procurement from legacy cost structures and accelerating specification upgrades across European assembly lines.
Growth Catalysts
- EU Green Deal enforcement:Tightening vehicle thermal-efficiency mandates in Europe are compelling automakers to replace conventional insulation with advanced ceramic and polymer composites in fuel-cell stack enclosures.
- Commercial bus fleet conversion:South Korean municipal operators are expanding procurement of fuel-cell platforms, creating concentrated demand for lightweight foam insulation systems that extend hydrogen range.
- Proton-exchange membrane thermal optimization:Stack operating temperature windows between 60°C and 85°C require precision-engineered insulation, driving replacement cycles in existing fuel-cell vehicle populations.
Market Restraints
- Alumina-silica raw material concentration:Ceramic fiber supply chains depend on backward-integrated producers controlling specialized mineral feedstocks, creating vulnerability to input cost volatility.
- Hydrogen permeation certification complexity:EMA REACH compliance and parallel substance-restriction protocols impose extended testing timelines, delaying product qualification for European subsystem integration.
- Battery electric vehicle substitution:Lithium-ion platforms with mature thermal management ecosystems compete for the same fleet procurement budgets, particularly in passenger car segments where range anxiety has diminished.
Strategic Opportunities
- German automotive manufacturing corridor expansion:Demand concentration around Stuttgart and Munich creates geographic white space for localized insulation fabrication and just-in-time supply relationships.
- Acoustic and fire-resistant category growth:Tightening passenger-car cabin standards are expanding addressable market beyond thermal insulation into multi-functional barrier systems.
- Train platform electrification:Rail operators in multiple geographies are evaluating fuel-cell traction systems, opening new end-use verticals for high-durability insulation architectures originally developed for bus applications.
Industry Challenges
- Multi-jurisdiction certification synchronization:Divergent thermal-test methodologies between EPA emissions-certification pathways and EMA REACH protocols force redundant validation cycles, compressing margin on new product introductions.
- High-voltage thermal event simulation:NHTSA crashworthiness standards require specialized testing infrastructure for electrical isolation under impact loading, elevating capex requirements for qualification laboratories.
- Hydrogen-storage safety protocol evolution:Rapidly updating material-safety guidelines for hydrogen-contact surfaces create compliance uncertainty, forcing insulation producers to maintain flexible formulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel-Cell Electric Vehicle Insulation Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,262.34 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polymer, Fiber, Foam, Metal Insulation Type: Thermal, Acoustic, Fire-Resistant, Anti-Vibration Application: Passenger Cars, Commercial Vehicles, Buses, Trains Manufacturing Process: Injection Molding, Extrusion, Compression Molding, Laminating |
| Companies Covered | DuPont, Zotefoams plc, Saint-Gobain, Elmelin Ltd., Morgan Advanced Materials, 3M, Autoneum, Unifrax, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel-Cell Electric Vehicle Insulation Market Emerging Trajectories
Material science advances and regulatory compression are reshaping competitive positioning in fuel-cell thermal management, with three distinct vectors driving specification changes across OEM supply chains.
Aerogel-infused polymer composites are consolidating market share in high-temperature membrane applications. Bus and heavy-duty truck manufacturers specify these materials for their superior weight-efficiency metrics. The technology is consolidating procurement decisions around suppliers with captive nanoporous silica production capabilities.
REACH substance restrictions and parallel RoHS amendments are eliminating legacy halogenated flame retardants from fuel-cell stack enclosures. European subsystem integrators now face reformulation mandates for electrical isolation barriers. Germany's KBA type-approval process is accelerating validation of ceramic fiber alternatives that maintain fire propagation resistance without restricted chemical content.
Fleet operators are consolidating insulation procurement through long-term supply agreements tied to vehicle platform life cycles. Direct OEM relationships are displacing tier-two distributor channels for high-volume bus and train contracts. South Korean commercial fleet managers pioneered this model, with European municipal operators now adopting similar consolidated sourcing frameworks.
Fuel-Cell Electric Vehicle Insulation Market Segmentation
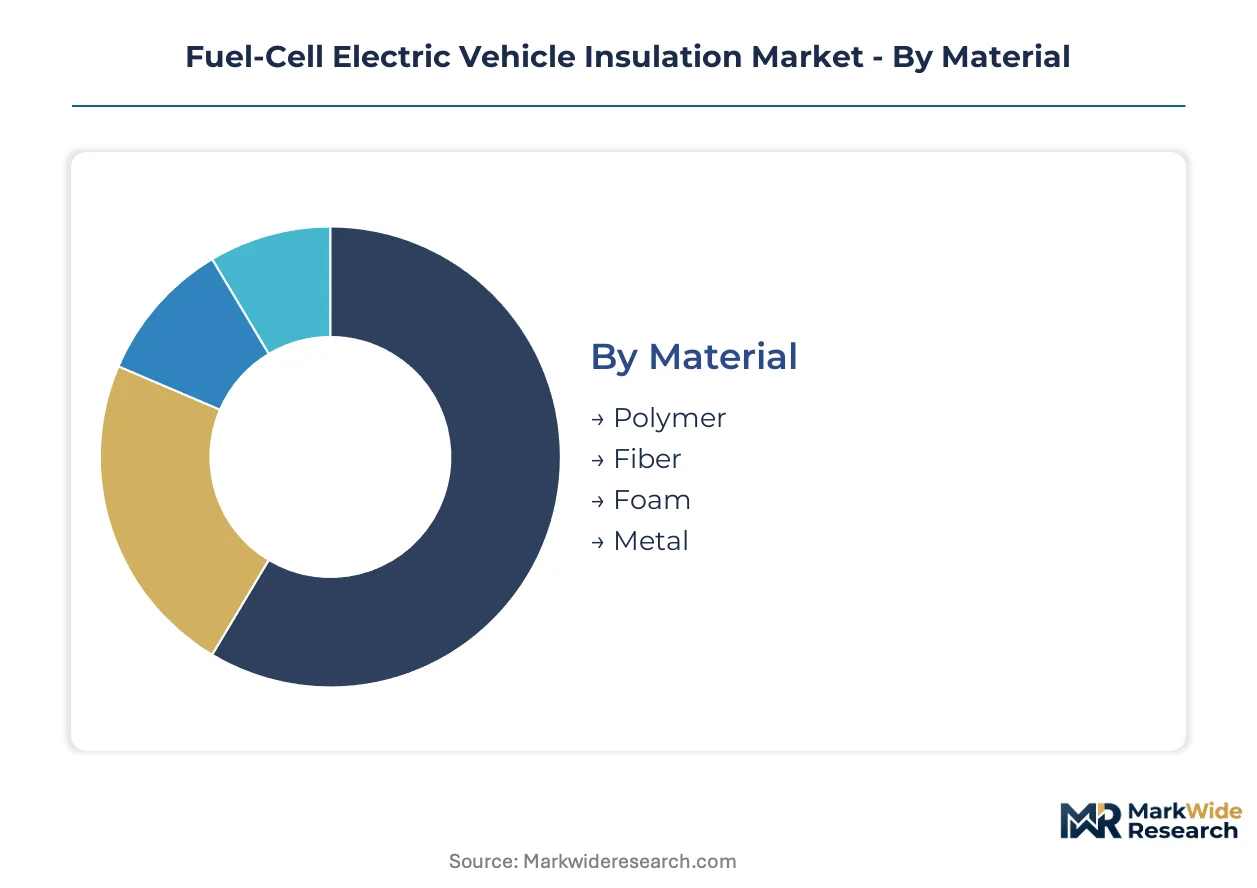
Fuel-cell insulation procurement decisions split across material performance, functional requirements, vehicle platform specifications, and manufacturing compatibility. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape supplier relationships across OEM supply chains.
Material:
Buyers prioritize thermal stability thresholds and hydrogen permeation resistance when selecting base materials for stack enclosure applications.
- Polymer:High-temperature fluoropolymer and polyimide films dominate passenger-car membrane applications. German OEMs around Stuttgart specify these materials for precision thickness control in proton-exchange membrane gaskets.
- Fiber:Alumina-silica ceramic fiber mats deliver extreme temperature endurance above 1000°C for fire barrier layers. South Korean bus manufacturers source these from backward-integrated producers controlling specialized mineral feedstocks.
- Foam:Closed-cell melamine and polyimide foams reduce stack enclosure mass. Commercial vehicle platforms favor these for hydrogen range extension.
- Metal:Metallized barrier films and aluminum honeycomb structures provide electromagnetic shielding. Train applications specify these for combined thermal-acoustic performance.
Polymer leads on scale; fiber leads on momentum.
Insulation Type:
Functional specifications track directly to regulatory pressure points across EU Green Deal thermal mandates and NHTSA crashworthiness protocols.
- Thermal:Precision-engineered materials maintain stack operating windows between 60°C and 85°C. Current procurement volumes concentrate here due to energy-density penalties from temperature drift.
- Acoustic:Multi-layer barrier systems attenuate compressor and hydrogen circulation pump noise. Passenger-car cabin standards in Germany's KBA type-approval process are accelerating specification upgrades.
- Fire-Resistant:Ceramic fiber and intumescent polymer formulations prevent stack-to-cabin fire propagation. REACH substance restrictions are eliminating legacy halogenated options.
- Anti-Vibration:Elastomeric isolation mounts protect membrane stacks from road-load fatigue. Bus and train platforms require these for extended service life.
Thermal dominates current procurement; acoustic and fire-resistant categories are climbing the fastest.
Application:
Platform selection determines weight-efficiency priorities, duty-cycle severity, and fleet procurement consolidation patterns.
- Passenger Cars:Compact stack enclosures demand thin-profile polymer composites. Cabin comfort standards drive multi-functional insulation specifications.
- Commercial Vehicles:Heavy-duty truck fuel-cell systems require durable thermal barriers under sustained load. Fleet operators consolidate procurement through platform-life supply agreements.
- Buses:Municipal operators in South Korea pioneered long-term insulation sourcing frameworks. Foam materials lead on mass reduction for hydrogen range.
- Trains:Rail operators evaluate fuel-cell traction for non-electrified corridors. High-durability architectures from bus applications transfer to this vertical.
Buses lead on procurement consolidation; trains represent the steepest expansion trajectory.
Manufacturing Process:
Process selection hinges on geometric complexity, volume scale, and integration with existing automotive component fabrication infrastructure.
- Injection Molding:High-throughput production of complex polymer gasket geometries. OEMs favor this for passenger-car scale economies.
- Extrusion:Continuous profile manufacturing for foam seals and fiber-reinforced tapes. Bus platform suppliers specify extruded profiles for consistent dimensional tolerance.
- Compression Molding:Ceramic fiber mat forming for high-temperature fire barriers. Batch processes suit lower-volume train applications.
- Laminating:Multi-layer film assembly for metallized barrier composites. Precision layer registration meets hydrogen permeation certification requirements.
Injection molding leads on throughput; laminating gains share fastest on barrier performance demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Ulsan, and Detroit anchor fuel-cell insulation development. These workforce concentrations attract polymer scientists, ceramic engineers, and thermal systems specialists. Their proximity to OEM assembly plants compresses design-to-production cycles.
Germany
Baden-Württemberg's automotive engineering density drives precision polymer specification for passenger-car stack enclosures. KBA type-approval mandates accelerate ceramic fiber validation for fire-resistant barrier systems. Stuttgart-Munich corridor suppliers co-locate fabrication facilities with Mercedes-Benz and BMW fuel-cell development centers.
South Korea
Ulsan and Busan industrial zones concentrate fuel-cell bus fleet procurement through Hyundai Motor Group supply chains. MFDS hydrogen-contact surface protocols and Ministry of Trade, Industry and Energy subsidies shape material qualification timelines. Municipal operators in Seoul Capital Area execute multi-year insulation supply agreements tied to platform life cycles.
United States
Michigan and California engineering bases support NHTSA crashworthiness certification for high-voltage thermal events. EPA zero-exhaust vehicle pathways and IRA clean hydrogen production tax credits influence OEM insulation procurement decisions. Detroit-area suppliers maintain qualification laboratories for electrical isolation testing under impact loading.
Japan
Toyota's Nagoya-centered supply chain anchors ceramic fiber and polymer composite development for Mirai platform thermal management. METI hydrogen roadmap targets and JIS automotive subsystem standards compress product validation cycles. Osaka-Kobe industrial corridor hosts backward-integrated alumina-silica feedstock processing.
China
Yangtze River Delta battery and fuel-cell manufacturing clusters absorb insulation capacity from domestic polymer film producers. MIIT new energy vehicle catalog requirements and GB standards for hydrogen fuel-cell safety systems dictate material selection protocols. Shanghai-Suzhou corridor suppliers integrate with SAIC Motor and Foton fuel-cell bus programs.
Fuel-Cell Electric Vehicle Insulation Market Vendor Landscape
The competitive structure tilts toward materials science conglomerates with captive polymer and mineral processing capabilities. Tier-one automotive suppliers and specialized ceramic manufacturers occupy distinct positioning layers. Three archetypes dominate: diversified chemical conglomerates controlling raw material inputs, automotive-focused tier suppliers with OEM integration depth, and niche ceramic specialists with extreme-temperature formulation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among diversified materials conglomerates, DuPont and BASF SE exemplify polymer science depth applied to high-temperature membrane applications. Saint-Gobain and Morgan Advanced Materials occupy positions within ceramic fiber and microporous insulation specialist tiers. 3M represents the multi-technology conglomerate archetype with cross-sector thermal management capabilities. These named entities anchor industry-level commentary without implying specific strategic actions or market positions beyond their evident structural roles.
| Leading Market Players |
|---|
| DuPont |
| Zotefoams plc |
| Saint-Gobain |
| Elmelin Ltd. |
| Morgan Advanced Materials |
| 3M |
| Autoneum |
| Unifrax |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Aerogel-infused polymer composite adoption simultaneously compresses per-kilogram manufacturing costs and concentrates procurement decisions around suppliers with captive nanoporous silica production capabilities, reshaping margin distribution across the fuel-cell insulation value chain.
Pricing Analysis
Bundled long-term supply agreements covering material, certification, and after-sales technical support command premium positioning against unbundled transactional spot purchases. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade ceramic fiber from commercial vehicle foam and generic polymer film alternatives. Price differentiation hinges on REACH compliance tier and volume scale, with municipal fleet operators leveraging platform-life contracts for standard-tier positioning. Cost compression in economy-tier polymer films is intensifying because Chinese domestic capacity expansion feeds oversupply into export markets. Commercial bus operators exhibit highest price sensitivity due to hydrogen range economics, while German passenger-car OEMs prioritize certification grade over unit cost.
Supply Chain Analysis
Reverse-logistics infrastructure for ceramic fiber mat refurbishment remains underdeveloped, forcing premature replacement cycles and inflating lifetime ownership costs for fleet operators. Raw material supply draws from Germany for precision polymer films, South Korea for alumina-silica ceramic feedstocks, and China for metallized barrier substrates. Specialized mineral processing for extreme-temperature fiber applications rests on backward-integrated producers controlling bauxite and kaolin deposits. Single-source vulnerability concentrates in nanoporous silica precursor supply for aerogel composites. Distribution runs through Tier 1 automotive subsystem integrators co-located with OEM assembly plants in Stuttgart, Ulsan, and Detroit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's thermal-efficiency mandates compound regulatory-driven demand acceleration, with KBA type-approval timelines compressing qualification windows and rewarding pre-certified insulation architectures.
For Market Incumbents: Hedge against battery electric vehicle substitution by deepening captive supply of ceramic fiber feedstocks and accelerating REACH-compliant halogen-free formulation pipelines. Saint-Gobain and Morgan Advanced Materials anchor positions through alumina-silica backward integration, while polymer specialists must defend against Chinese cost-driven entrants. Certification investment represents the critical lever, as European subsystem integrators consolidate procurement around pre-qualified suppliers. For New Entrants and Emerging Players: Aerogel composite manufacturing expertise offers technology-first wedge into train platform electrification verticals where durability specifications transfer directly from proven bus architectures. German automotive manufacturing corridor expansion creates geographic white space for localized fabrication facilities serving Mercedes-Benz and BMW fuel-cell development centers. Direct OEM relationship building displaces distributor channels for high-volume municipal contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap ceramic specialists with extreme-temperature formulation expertise but limited OEM integration depth. Long-term viability framing centers on hydrogen infrastructure buildout pace and fuel-cell platform standardization across commercial vehicle segments. Watch NHTSA crashworthiness standard finalization timelines as inflection indicator for electrical isolation testing infrastructure investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina-Silica Feedstocks | Saint-Gobain secures ceramic fiber cost stability against South Korean mineral concentrate volatility. |
| Long-term Supply Agreement with Municipal Fleet Operators | Seoul Capital Area bus procurement consolidation locks in platform-life revenue visibility. |
| REACH-Compliant Halogen-Free Formulation Investment | German OEMs accelerate KBA validation cycles for fire-resistant barrier alternatives. |
| Joint Venture for Localized German Fabrication | Stuttgart-Munich corridor suppliers compress design-to-production cycles for BMW stack enclosures. |
| Technology Licensing for Train Platform Adaptation | Bus-derived high-durability architectures transfer to rail electrification corridors in Japan and Europe. |
Methodological Framework
Direct dialogue with OEM platform engineers, Tier 1 subsystem procurement leads, ceramic fiber plant managers, and fuel-cell bus fleet operators grounded qualitative assessment in operational reality. Primary interview insights triangulated against secondary validation from KBA type-approval databases, EPA zero-exhaust vehicle certification pathways, EMA REACH substance restriction registers, and IHS Markit vehicle production data. Bottom-up segmentation modeling across material, insulation type, application, and manufacturing process dimensions converged with top-down market sizing from trade flow analysis and customs records.
Segment-level value outputs calibrated to procurement volume intensity by vehicle platform class across the projection horizon. Modeled dimensions spanned polymer-fiber-foam-metal material split, thermal-acoustic-fire-resistant functional category, passenger car-commercial vehicle-bus-train application vertical, and injection molding-extrusion-compression molding-laminating process route. CAGRs derived from fitted growth curves anchored to EU Green Deal mandate implementation phases and South Korean municipal fleet conversion schedules. Hydrogen range economics and stack operating temperature precision requirements informed platform-specific insulation content assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric vehicle substitution rates and hydrogen infrastructure deployment pace. Forecasts reflect documented assumptions regarding regulatory timeline adherence and OEM platform standardization decisions. Practitioners should monitor NHTSA high-voltage thermal event standard finalization and MFDS hydrogen-contact surface protocol updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
Electric Motorcycles and Scooters Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Ball Bearings Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Global Electric Cars Market