
 Electric Vehicle Liquid Cold Plates Market | 2026-2036
Electric Vehicle Liquid Cold Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Liquid Cold Plates Market Insights
Commercial vehicle electrification is broadening the addressable base for liquid cold plate suppliers beyond passenger cars. Valeo leverages its European manufacturing footprint to anchor supply contracts with premium OEMs pursuing modular thermal platforms. Dana competes through in-house production of aluminum cold plates tailored to North American heavy-duty electric truck programs. MAHLE specializes in integrated thermal management systems that combine liquid cooling with refrigerant circuits, differentiating its portfolio from standalone component vendors.
Electric vehicle liquid cold plates are heat exchanger components that circulate coolant through micro-channel or serpentine geometries to maintain optimal operating temperatures for batteries, motors, and power electronics. Aluminum variants dominate volume production due to favorable conductivity-to-weight ratios and compatibility with brazing processes used in automotive-scale manufacturing. Passive cold plates currently lead unit shipments across the product type spectrum, though hybrid configurations that combine liquid channels with phase-change materials are gaining traction in performance-oriented battery cooling applications. Copper and composite material segments command premium positioning where extreme thermal loads from silicon carbide inverters and hairpin motors demand higher conductivity than aluminum can provide.
The US NHTSA and EPA are tightening battery safety and efficiency benchmarks, which shapes cold plate design requirements around leak integrity and thermal uniformity. Europe's REACH regulation and F-Gas Regulation constrain coolant chemistry choices, pushing suppliers toward low-global-warming-potential alternatives that must remain compatible with plate metallurgy and sealing systems. China's GB standards and MIIT technical rules mandate specific thermal runaway propagation timelines that directly determine cold plate flow rates and channel density specifications. Stakeholders must monitor how divergent regional coolant specifications and recycling mandates reshape material selection and cross-border component qualification pathways.
Market Dynamics
China's NMPA thermal runaway mandates are compressing design cycles for liquid cold plate suppliers, forcing rapid channel density increases and aluminum brazing process upgrades across tier-1 manufacturing corridors.
Growth Catalysts
- 800V Architecture Migration:OEMs redesigning battery electric vehicle platforms around higher voltage systems require cold plates with enhanced flow rates and micro-channel precision.
- MIIT Technical Rules:China's tightened thermal propagation timelines mandate specific cooling performance benchmarks that accelerate procurement of high-density liquid cooling solutions.
- Cell-to-Pack Formats:Battery pack redesigns eliminating module housings create direct mounting surfaces for integrated cold plate assemblies.
Market Restraints
- Aluminum Price Volatility:Raw material cost swings for 6061 and 3003 series alloys compress margin structures for volume producers.
- Jiangsu-Zhejiang Supply Concentration:Tier-1 supplier clustering near CATL and BYD facilities creates geographic vulnerability to regional logistics disruptions.
- Copper Conductivity Ceiling:Extreme thermal loads from silicon carbide inverters exceed aluminum performance limits, forcing costly material upgrades.
Strategic Opportunities
- Commercial Vehicle Electrification:Heavy-duty electric truck programs in North America present untapped demand for high-capacity cooling systems.
- REACH-Compliant Coolant Formulations:Europe's F-Gas Regulation pushes development of low-global-warming-potential alternatives compatible with existing plate metallurgy.
- Hybrid Phase-Change Configurations:Convergence of liquid channels with phase-change materials opens performance-oriented battery cooling segments.
Industry Challenges
- Micro-Channel Brazing Expertise Gap:Specialized welding and vacuum brazing skills required for automotive-scale production remain scarce in emerging manufacturing regions.
- Cross-Border Qualification Timelines:Divergent regional coolant specifications and recycling mandates extend component validation cycles for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Liquid Cold Plates Market |
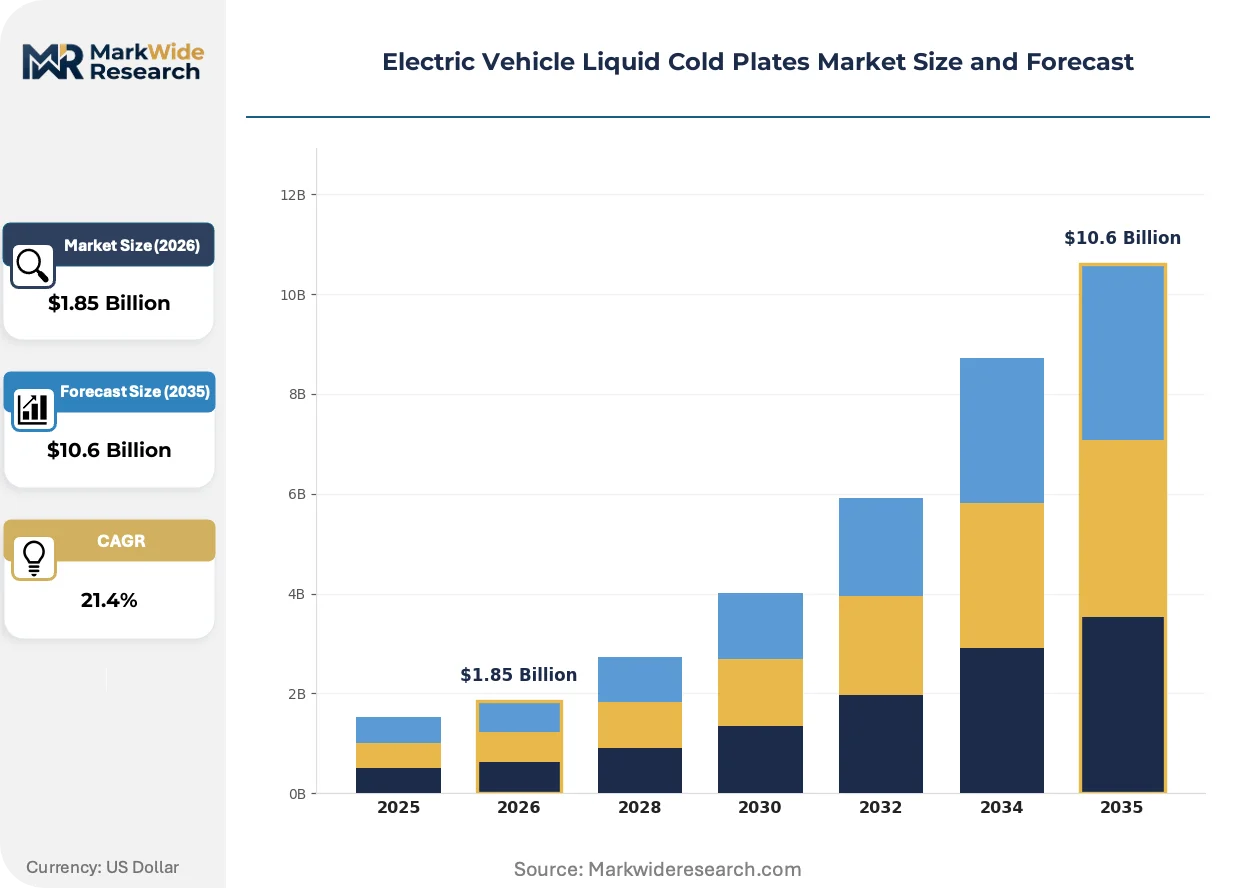
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $10.6 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active, Passive, Hybrid, Custom Material: Copper, Aluminum, Graphite, Composites End User: OEMs, Tier-1 Suppliers, Aftermarket, Research Institutions Application: Battery Cooling, Motor Cooling, Power Electronics, Thermal Management |
| Companies Covered | Valeo, MAHLE, Dana, Boyd Corporation, ESTRA Automotive, Sanhua Holding Group, Zhejiang Yinlun Machinery, Nabaichuan Holding, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Liquid Cold Plates Market Trends and Innovations
Silicon carbide power electronics and hairpin motor architectures are elevating thermal management requirements, pushing cold plate designs toward higher conductivity materials and integrated refrigerant circuits.
Serpentine channel geometries with enhanced surface area-to-volume ratios are displacing legacy straight-channel designs in premium battery electric vehicle platforms. European OEMs pursuing modular thermal architectures are adopting these configurations for 800V systems. This convergence with brazed aluminum manufacturing is compressing lead times for high-performance cold plate assemblies.
Europe's F-Gas Regulation and REACH constraints are reshaping coolant chemistry selection across the supplier base. Industrial consequence includes accelerated R&D spending on hydrofluoroolefin alternatives and CO2-based refrigerant compatibility testing. Battery cooling applications face the tightest formulation requirements, with suppliers reformulating sealing systems to maintain leak integrity under new thermal transfer fluids.
Fleet operators and commercial vehicle OEMs are consolidating procurement around integrated thermal management system suppliers rather than standalone component vendors. This channel consolidation is displacing traditional tier-2 cold plate distributors in heavy-duty electric truck segments. North American heavy-duty programs exhibit the most pronounced concentration, with direct OEM-supplier partnerships replacing multi-tier supply structures.
Electric Vehicle Liquid Cold Plates Market Segmentation
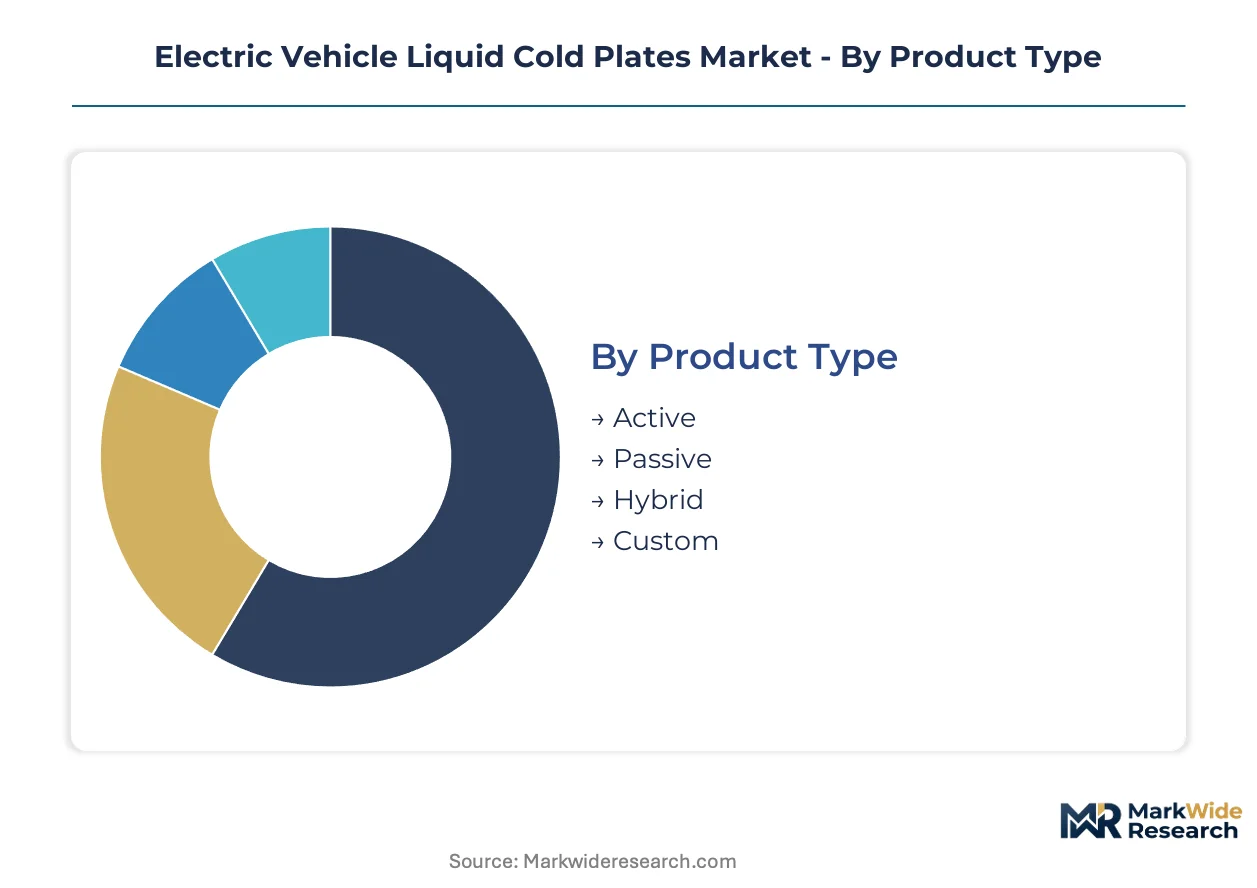
Liquid cold plate configurations diverge sharply by thermal load, manufacturing process, and integration depth. Each segment demands distinct capital commitments and carries unique qualification barriers.
Product Type:
Active cold plates absorb the heaviest upfront tooling investment due to embedded pumps and control electronics. Passive variants require less capital but compete on channel density and brazing precision. Hybrid systems sit between these poles on equipment spend.
- Active:Integrated pump assemblies and sensor arrays circulate coolant under variable pressure. OEM procurement concentrates in 800V battery platforms where dynamic thermal response prevents propagation events under MIIT-mandated timelines.
- Passive:Serpentine or micro-channel geometries rely on external coolant loops without onboard actuation. Heavy-duty electric truck programs in North America specify these for motor and inverter cooling where system simplicity reduces failure modes.
- Hybrid:Combines liquid channels with phase-change materials for peak-load buffering. Research institutions evaluate these for next-generation cell-to-pack architectures.
- Custom:Application-specific designs for prototype vehicles and low-volume performance EVs. Tier-1 suppliers maintain rapid-turn fabrication cells for these programs.
Most installed capacity flows through Passive configurations. Expansion is steepest in Hybrid systems.
Material:
Conductivity requirements and weight targets split procurement across four metallurgical classes. Copper commands premium positioning where silicon carbide inverters generate extreme heat flux.
- Aluminum:6061 and 3003 series alloys dominate automotive-scale production through vacuum brazing compatibility. Volume demand clusters in China's Jiangsu and Zhejiang manufacturing corridors serving CATL and BYD supply chains.
- Copper:C11000 and C10200 grades deliver thermal conductivity exceeding aluminum by 60 percent. Hairpin motor applications and silicon carbide power electronics drive specification in premium European battery electric vehicles.
- Graphite:Anisotropic conductivity suits planar heat spreading in pouch cell configurations. Research institutions pilot these for thermal uniformity optimization.
- Composites:Aluminum-graphite or copper-diamond matrices balance weight and conductivity. Aftermarket suppliers stock these for retrofit high-performance cooling.
Aluminum carries the highest unit volume. Copper is gaining share fastest in 800V architectures.
End User:
Procurement authority determines specification depth and validation burden. OEMs retain tightest control over thermal architecture decisions.
- OEMs:Direct sourcing for integrated battery pack designs. Cell-to-pack format adoption eliminates module housings and creates mounting surfaces for cold plate assemblies.
- Tier-1 Suppliers:Modular thermal platform vendors consolidate procurement across multiple OEM programs. Valeo and MAHLE anchor European supply through in-house brazing capacity.
- Aftermarket:Replacement demand for damaged cooling circuits and performance upgrades. Fleet operators source these for warranty repairs outside OEM service networks.
- Research Institutions:Low-volume orders for prototype validation and thermal modeling studies. Custom geometries predominate in this channel.
Tier-1 Suppliers handle the greatest production volume. OEM direct procurement is expanding most quickly as pack integration deepens.
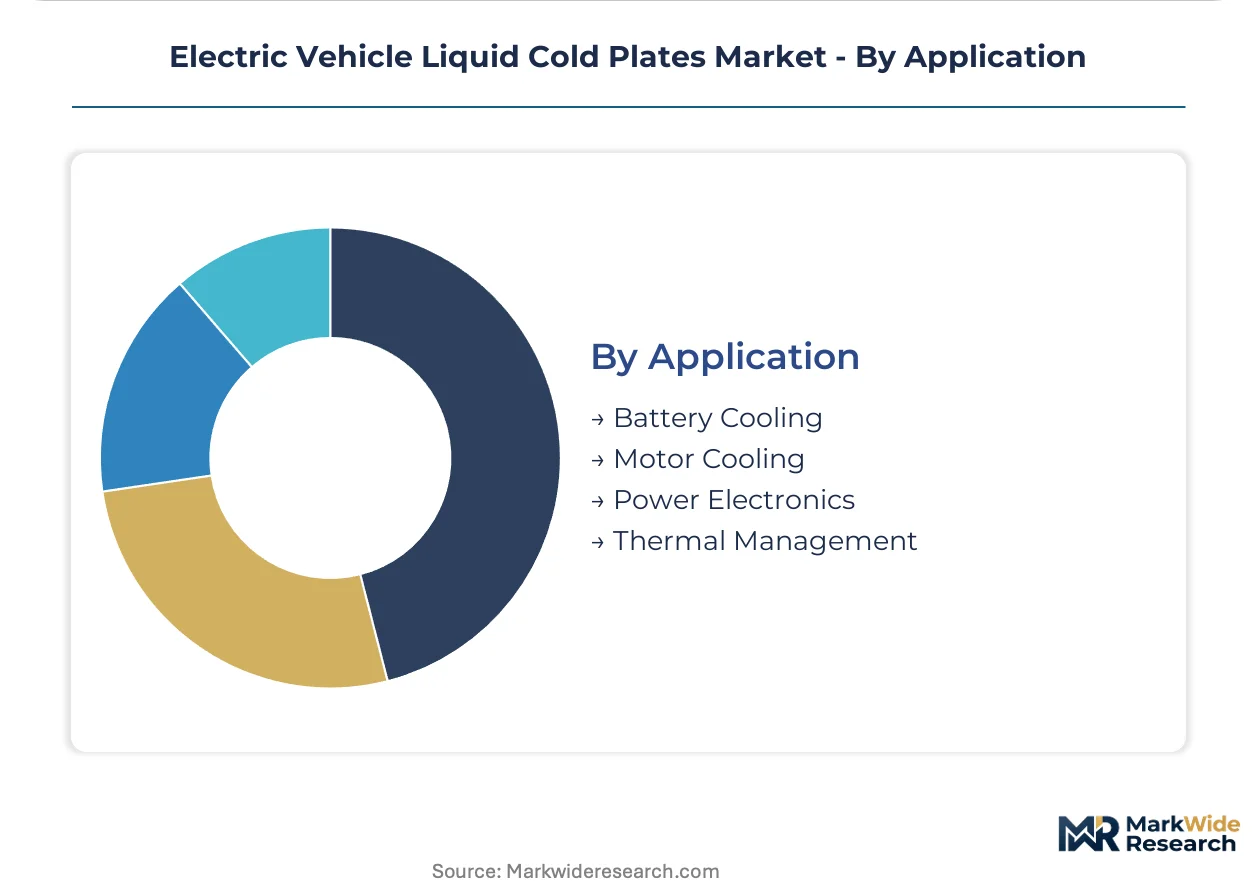
Application:
Thermal load characteristics and safety criticality differentiate specification requirements across vehicle subsystems.
- Battery Cooling:Channel density and flow uniformity determine cell temperature variance. China's NMPA thermal runaway mandates fix maximum propagation timelines that dictate cold plate performance thresholds.
- Power Electronics:Silicon carbide inverters and DC-DC converters require higher conductivity materials than aluminum provides. Copper cold plates or composite alternatives penetrate this segment.
- Motor Cooling:Hairpin stator architectures generate concentrated heat flux at winding heads. Serpentine geometries with enhanced surface area-to-volume ratios displace legacy straight-channel designs.
- Thermal Management:System-level integration combining multiple cooling loops. REACH-compliant coolant formulations and F-Gas Regulation constraints reshape sealing system specifications in European programs.
Battery Cooling absorbs the majority of installed capacity. Power Electronics is climbing the fastest as silicon carbide adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting cold plate production toward jurisdictions with lower compliance costs for aluminum brazing emissions and REACH-aligned coolant handling. Chinese manufacturing corridors absorb the largest capacity migration as NMPA thermal runaway mandates create guaranteed domestic demand.
China
CATL and BYD procurement programs are expanding liquid cold plate orders for 800V cell-to-pack architectures. MIIT technical rules compress thermal propagation timelines to five minutes maximum. Jiangsu and Zhejiang manufacturing corridors concentrate tier-1 supplier facilities within 150 kilometers of battery assembly plants.
Germany
Premium OEM thermal platform contracts are consolidating around modular cooling system vendors. REACH and F-Gas Regulation constraints are accelerating hydrofluoroolefin coolant compatibility testing. Bavaria and Baden-Württemberg host the densest clusters of aluminum brazing specialists serving European battery electric vehicle programs.
United States
Heavy-duty electric truck programs are specifying high-capacity passive cold plates for motor and inverter cooling. NHTSA battery safety benchmarks are tightening leak integrity requirements for thermal management components. Michigan and Ohio manufacturing bases are attracting supplier investments for North American commercial vehicle electrification.
Japan
Hairpin motor architectures are driving specification of serpentine-channel cold plates with enhanced surface area-to-volume ratios. METI carbon neutrality targets are accelerating silicon carbide inverter adoption that exceeds aluminum thermal conductivity limits. Kanto and Kansai industrial zones maintain precision brazing expertise for premium battery electric vehicle exports.
South Korea
Domestic battery OEMs are qualifying hybrid cold plate configurations combining liquid channels with phase-change materials. MFDS-aligned safety standards are propagating into automotive thermal management specifications. Seoul Capital Area and Busan-Ulsan corridors are expanding vacuum brazing capacity for next-generation pack designs.
Electric Vehicle Liquid Cold Plates Market Competitive Landscape
Capacity expansion dominates the current landscape as tier-1 suppliers race to install vacuum brazing lines ahead of 800V platform ramp schedules. The vendor base splits between integrated thermal management system providers and standalone component fabricators. Three archetypes define positioning: European modular platform specialists, Chinese scale-driven aluminum processors, and North American commercial vehicle-focused suppliers. M&A activity and geographic expansion represent the two most visible competitive vectors as companies seek brazing expertise in underserved manufacturing regions.
Within the integrated systems tier, Valeo and MAHLE exemplify European archetypes pursuing modular thermal platforms that combine liquid cooling with refrigerant circuits. Dana occupies a position among North American suppliers targeting heavy-duty electric truck programs through in-house aluminum cold plate production. Sanhua Holding Group represents the Chinese scale-driven fabricator archetype, anchoring supply relationships with domestic battery OEMs in the Jiangsu-Zhejiang corridor.
| Leading Market Players |
|---|
| Valeo |
| MAHLE |
| Dana |
| Boyd Corporation |
| ESTRA Automotive |
| Sanhua Holding Group |
| Zhejiang Yinlun Machinery |
| Nabaichuan Holding |
| BorgWarner |
| Others |
Pricing and Supply Chain Analysis
LME aluminum cash settlement volatility cascades through 6061 and 3003 alloy procurement contracts, compressing margin structures for volume fabricators while amplifying pricing power for Jiangsu-Zhejiang corridor suppliers with captive brazing capacity and direct CATL-BYD offtake agreements.
Pricing Analysis
Direct-to-OEM contract structures eliminate distributor markups for tier-1 thermal platform vendors, while aftermarket channels retain 15-25 point premiums for warranty repairs outside service networks. Three-tier pricing stratification separates REACH-compliant European programs from standard Asian specifications and economy-grade aftermarket replacements. Pricing pressure stems from aluminum cost compression forcing brazing specialists to absorb alloy volatility through long-term offtake commitments. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, whereas premium European OEMs prioritize thermal uniformity over unit cost.
Supply Chain Analysis
Vacuum brazing technician scarcity in China's Jiangsu-Zhejiang corridor and Germany's Bavaria-Baden-Württemberg axis constrains capacity expansion timelines for automotive-scale production. Supply concentrates in China, Germany, and the United States, with raw material dependencies on Chilean copper cathodes, Australian alumina, and domestic 3003/6061 alloy sheet. Single-source vulnerability permeates precision micro-channel extrusion tooling, where Japanese and German equipment suppliers command 18-month order backlogs. Distribution runs through tier-1 thermal system integrators for OEM direct procurement, bypassing traditional component distributors in heavy-duty electric truck segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MIIT thermal propagation timelines and NMPA safety mandates generate guaranteed demand acceleration for compliant cooling architectures.
For Market Incumbents: Anticipate margin compression from aluminum volatility by securing backward integration into alloy recycling and captive brazing capacity in the Jiangsu-Zhejiang corridor. Defensive positioning requires rapid certification investment for REACH-compliant coolant compatibility, as European F-Gas Regulation constraints are displacing legacy sealing systems from premium procurement lists. Channel control through direct OEM platform engineering relationships anchors pricing power against emerging Chinese scale fabricators. For New Entrants and Emerging Players: North American heavy-duty electric truck aftermarket distributors represent the most penetrable buyer archetype, with fleet operators consolidating procurement outside OEM service networks for warranty repairs. White-space targets include hybrid phase-change configurations for cell-to-pack validation programs and copper cold plate retrofit kits for silicon carbide inverter upgrades. Go-to-market execution should leverage rapid-turn custom fabrication cells for low-volume performance EV prototypes, bypassing tier-1 qualification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with European modular thermal platform specialists combining liquid cooling with refrigerant circuit integration, as OEM consolidation around system-level suppliers accelerates. Long-term viability over the projection horizon hinges on brazing expertise scarcity and 800V architecture migration timelines. Acquisition screening should prioritize targets with MIIT-compliant validation status and vacuum brazing capacity in underserved manufacturing regions. The signal to watch is tier-1 supplier M&A velocity in South Korea and Japan as battery OEMs qualify next-generation pack designs.| Strategic Initiative | Industry Significance |
|---|---|
| 800V Platform Thermal Architecture Migration | MIIT-mandated propagation timelines force channel density upgrades across Jiangsu-Zhejiang suppliers. |
| REACH-Compliant Coolant Compatibility Investment | F-Gas Regulation constraints reshape sealing system specifications for European battery programs. |
| Backward Integration into Aluminum Recycling | Captive alloy supply hedges LME volatility for volume brazing operations serving CATL-BYD. |
| Hybrid Phase-Change Configuration Development | Research institution pilots for cell-to-pack architectures open premium battery cooling segments. |
| North American Heavy-Duty Truck Channel Expansion | Fleet operator consolidation outside OEM networks creates aftermarket distributor acquisition targets. |
Research Methodology
Multiple input streams — OEM platform engineering disclosures, tier-1 supplier procurement protocols, and NMPA-MIIT regulatory filings — were reconciled through structured interviews with thermal management directors, battery pack integration engineers, vacuum brazing operations managers, and aftermarket fleet procurement officers. Secondary validation drew from vehicle production databases, customs alloy trade records, and REACH-F-Gas regulatory impact assessments. Bottom-up unit demand estimates and top-down thermal content-per-vehicle benchmarks were triangulated to anchor market sizing.
Data-stream reconciliation across product type, material grade, end-user procurement authority, and application thermal load generated segment-level projections across the analysis window. CAGRs were derived from regression against 800V architecture penetration curves and cell-to-pack adoption rates. Forecast inputs incorporated silicon carbide inverter deployment timelines, hairpin motor architecture migration, and regional coolant chemistry regulatory divergence.
Inputs from OEM thermal platform roadmaps and tier-1 supplier capacity expansion announcements were available through the study window; gaps in prototype validation data for hybrid phase-change configurations introduce uncertainty bands in the technology adoption curve. Forecasts reflect assumptions around MIIT timeline enforcement consistency and aluminum alloy supply elasticity. Material deviation in NMPA thermal runaway test protocol revisions or LME aluminum sustained price spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Vietnam Electric Vehicle Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market
Electric Vehicles
Solar Golf Cart Market