
 Middle East Smokeless Indoor Grills Market | 2026-2036
Middle East Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Smokeless Indoor Grills Market Insights
Ceramic-coated aluminum is hardening as the dominant cooking surface across mid-tier electric grill lines, displacing traditional non-stick coatings that degrade under sustained high-heat cycling. Philips leverages its appliance R&D footprint in the Gulf to sustain premium positioning through advanced temperature control modules. Tefal anchors volume share via broad retail distribution across Saudi Arabia's hypermarket chains. Geepas competes aggressively on price through localized assembly partnerships in the UAE.
Middle East smokeless indoor grills are electric or infrared cooking appliances engineered to reach surface temperatures of 200–260°C while channeling grease and vapor into sealed drip trays, enabling protein searing without open flames or exhaust ventilation. The primary commercial purpose is to replicate char-grilled output in confined indoor environments where gas or charcoal combustion is prohibited by building codes. Electric grills dominate residential volume due to lower unit economics and simpler maintenance requirements, while infrared variants command margin premiums in the hospitality sector where speed-to-plate and consistent heat distribution justify higher capital outlay. Multi-function grills represent the fastest-expanding product type as vendors bundle griddle, panini, and roasting capabilities into single footprints suited to shrinking Gulf kitchen dimensions.
SASO, the UAE's MOIAT, and Bahrain's BD standards body enforce divergent electrical safety and energy-efficiency certifications that fragment compliance costs for manufacturers serving multiple Gulf markets. These frameworks elevate barriers for unbranded imports while creating preferential pathways for products tested under GCC-wide harmonized protocols. Stakeholders must monitor whether Saudi Arabia extends its mandatory energy-labeling scheme to small cooking appliances, as this would force redesign cycles across the supplier base and reshape competitive rankings.
Market Dynamics
SASO's tightening energy-efficiency labeling regime is compressing product redesign cycles across the Gulf supplier base, forcing manufacturers to prioritize thermal management engineering over cosmetic differentiation.
Growth Catalysts
- Apartment dwelling surge:High-rise residential construction in Dubai and Riyadh is generating concentrated demand for flame-free cooking appliances that comply with building fire codes.
- MOIAT certification harmonization:The UAE's alignment with GCC-wide electrical safety protocols is reducing cross-border compliance duplication for distributors serving multiple emirates.
- Ceramic-coated aluminum adoption:This cooking surface technology is displacing traditional non-stick coatings in mid-tier electric grill lines due to superior heat cycling durability.
Market Restraints
- Input cost volatility:Aluminum and copper price fluctuations are squeezing margins for manufacturers reliant on imported raw materials.
- Technical heat distribution limitations:Electric coil designs struggle to match infrared variants' searing consistency, constraining penetration in hospitality applications.
- Regulatory fragmentation:Divergent BD standards body requirements in Bahrain versus SASO protocols force redundant testing for multi-market suppliers.
Strategic Opportunities
- Kuwaiti hospitality underpenetration:Hotel kitchen renovation cycles in Kuwait City lag behind Dubai and Riyadh, creating whitespace for premium infrared grill deployment.
- Multi-function convergence:Bundling griddle, panini, and roasting capabilities into single-footprint units addresses shrinking Gulf kitchen dimensions.
- E-commerce channel expansion:Direct-to-consumer platforms are bypassing traditional hypermarket gatekeepers in Saudi Arabia's secondary cities.
Industry Challenges
- Thermal engineering talent scarcity:Gulf-based manufacturers face acute shortages of specialists capable of optimizing heat flux management for ceramic-coated surfaces.
- Certification timeline compression:SASO's accelerated review schedules are forcing suppliers to parallel-track product development and compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Smokeless Indoor Grills Market |
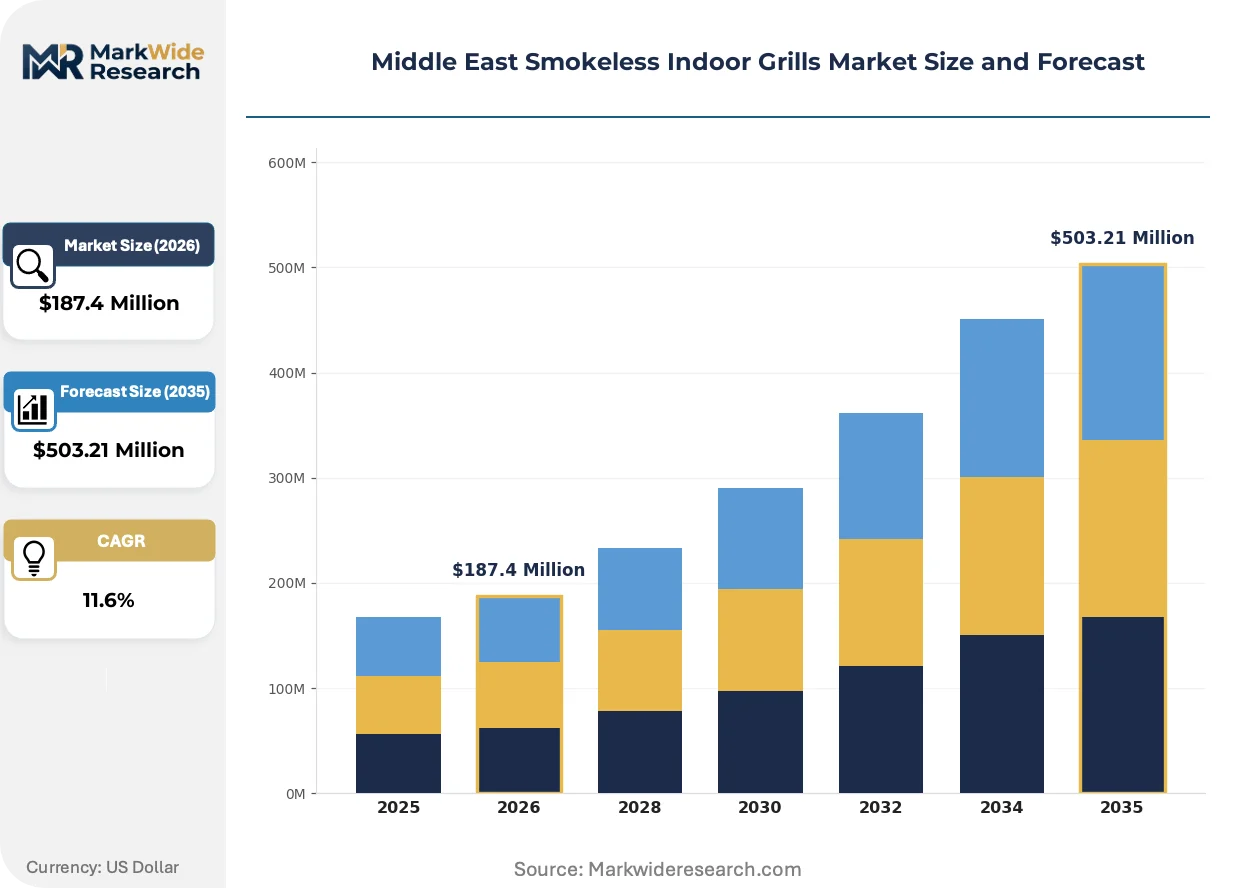
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Induction Grills, Multi-Function Grills Material: Stainless Steel, Non-Stick Coating, Cast Iron, Aluminum End User: Residential Users, Restaurants, Catering Services, Hospitality Sector Feature: Temperature Control, Easy Clean, Compact Design, Energy Efficient |
| Companies Covered | Philips, Tefal, George Foreman, Panasonic, Cuisinart, Breville, Black & Decker, Morphy Richards, Geepas, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Smokeless Indoor Grills Market Trends and Innovations
Temperature control intelligence and surface material engineering are converging to redefine performance benchmarks, while procurement patterns shift toward consolidated hospitality vendor relationships.
Infrared emitter arrays with precision zone control are modularizing commercial kitchen layouts across Abu Dhabi's hotel renovation pipeline. Large-scale hospitality operators are specifying these units for front-of-house live cooking stations. The technology is modularizing equipment footprints by eliminating the need for separate holding cabinets and exhaust hoods.
SASO's proposed extension of mandatory energy-labeling to small cooking appliances is forcing suppliers to redesign heating elements for measurable efficiency gains. Manufacturers serving Saudi Arabia must now pre-certify thermal performance metrics before import clearance. Mid-tier electric grill lines face the steepest compliance cost increases due to thinner engineering margins.
Consolidated procurement by regional hospitality groups is compressing vendor qualification timelines and favoring suppliers with GCC-wide service networks. Independent restaurants are losing purchasing leverage as chain operators centralize equipment decisions. This concentration is most visible in Dubai's hotel kitchen renovation sector, where three procurement consortia now control majority equipment spend.
Middle East Smokeless Indoor Grills Market Segmentation
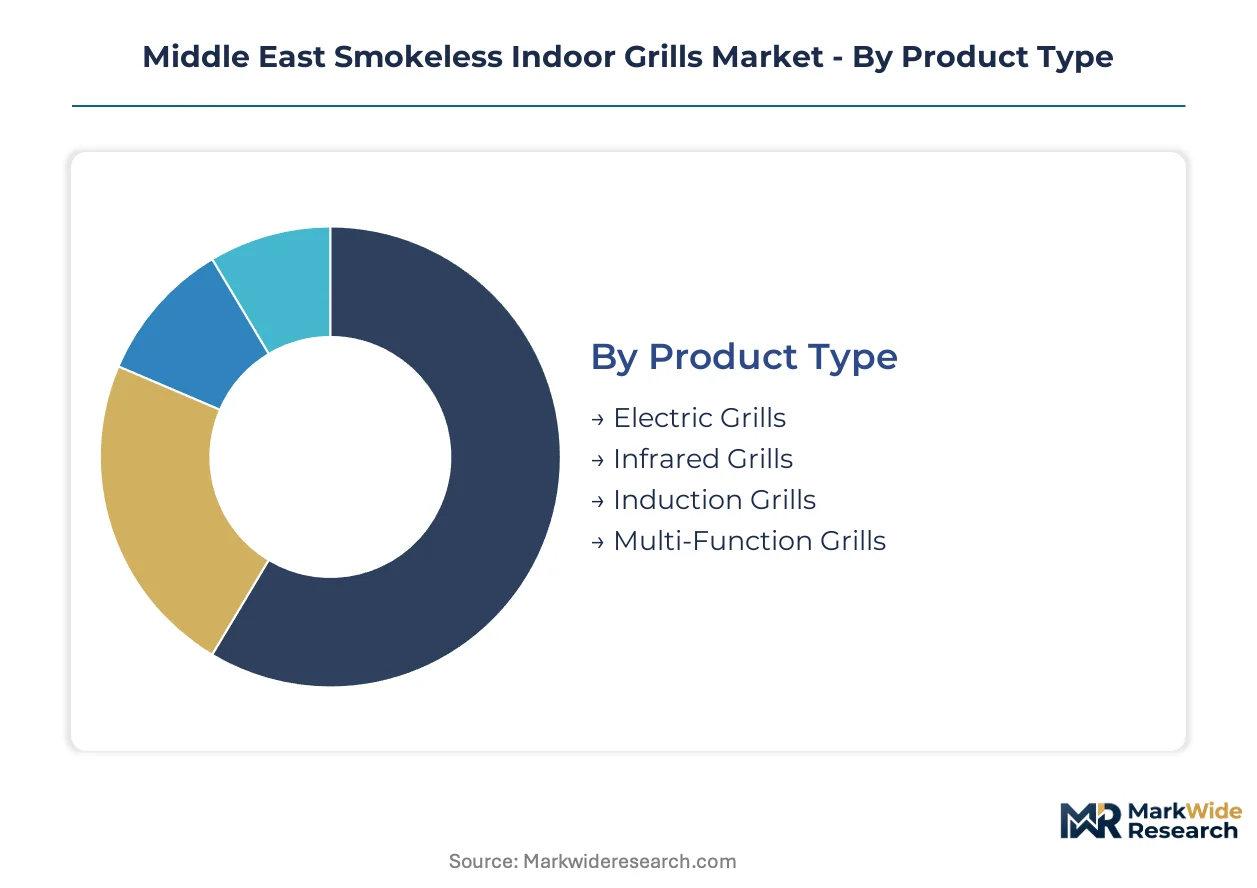
Smokeless indoor grill purchasing decisions in the Middle East hinge on kitchen footprint constraints, ventilation restrictions, and energy compliance requirements. Segmentation reveals how these forces split demand across cooking technologies, surface materials, and end-use applications.
Product Type:
Buyers prioritize heat source reliability and multi-function utility when selecting product categories.
- Electric Grills:Coil or plate-based heating elements reaching 200–260°C surface temperatures with sealed drip trays for grease containment. Apartment dwellers in Dubai and Riyadh drive residential volume due to lower unit economics and simpler maintenance protocols under SASO electrical safety frameworks.
- Multi-Function Grills:Bundled griddle, panini press, and roasting capabilities in single-footprint designs engineered for shrinking Gulf kitchen dimensions. Hospitality procurement consortia in Abu Dhabi specify these for front-of-house live cooking stations where space optimization commands premium positioning.
- Infrared Grills:Emitter arrays delivering rapid, zone-controlled heat distribution without exhaust ventilation requirements. Hotel kitchen renovations across Dubai favor these for speed-to-plate performance.
- Induction Grills:Magnetic field heating with precise wattage modulation and enhanced energy efficiency metrics. Compliance-focused buyers in Saudi Arabia respond to MOIAT-aligned efficiency protocols.
Volume sits with Electric Grills; growth tilts toward Multi-Function Grills.
Material:
Surface durability under sustained thermal cycling determines replacement cycles and total cost of ownership.
- Ceramic-Coated Aluminum:Hard-anodized substrates with ceramic deposition layers resisting degradation under repeated 200°C+ heat cycles. Mid-tier product lines across Saudi Arabia's hypermarket channels are displacing traditional non-stick coatings due to superior longevity.
- Stainless Steel:Austenitic or ferritic grades selected for corrosion resistance and commercial dishwasher compatibility. Hospitality operators in Dubai's hotel renovation pipeline specify these for back-of-house durability requirements.
- Cast Iron:Enameled or pre-seasoned ferrous surfaces retaining thermal mass for searing consistency. Premium residential segments in Kuwait City favor these for char-grilled output replication.
- Non-Stick Coating:PTFE or ceramic-polymer composites applied to aluminum substrates for food release properties. Budget-conscious buyers in Bahrain's retail channels sustain residual demand despite durability limitations.
Procurement weight favors Ceramic-Coated Aluminum; premium positioning attaches to Cast Iron.
End User:
Application environment dictates ventilation constraints, throughput requirements, and compliance exposure.
- Hospitality Sector:Hotel kitchens, resort food service operations, and banquet facilities requiring flame-free cooking appliances under building fire codes. Abu Dhabi and Dubai renovation cycles concentrate demand for infrared and multi-function configurations with GCC-wide service network requirements.
- Residential Users:Apartment dwellers in high-rise developments across Riyadh and Dubai seeking electric grill solutions that satisfy landlord and insurer ventilation restrictions. SASO energy-efficiency labeling awareness is elevating specification sophistication.
- Restaurants:Independent and chain dining establishments requiring consistent heat distribution for menu standardization. Procurement consolidation is compressing vendor qualification timelines across the UAE.
- Catering Services:Mobile and event-based food service operators prioritizing equipment portability and rapid setup. Secondary city expansion in Saudi Arabia is opening e-commerce channel opportunities.
Capital deployment concentrates in Hospitality; expansion velocity is steepest among Residential Users.
Feature:
Operational convenience and regulatory alignment shape feature prioritization across buyer segments.
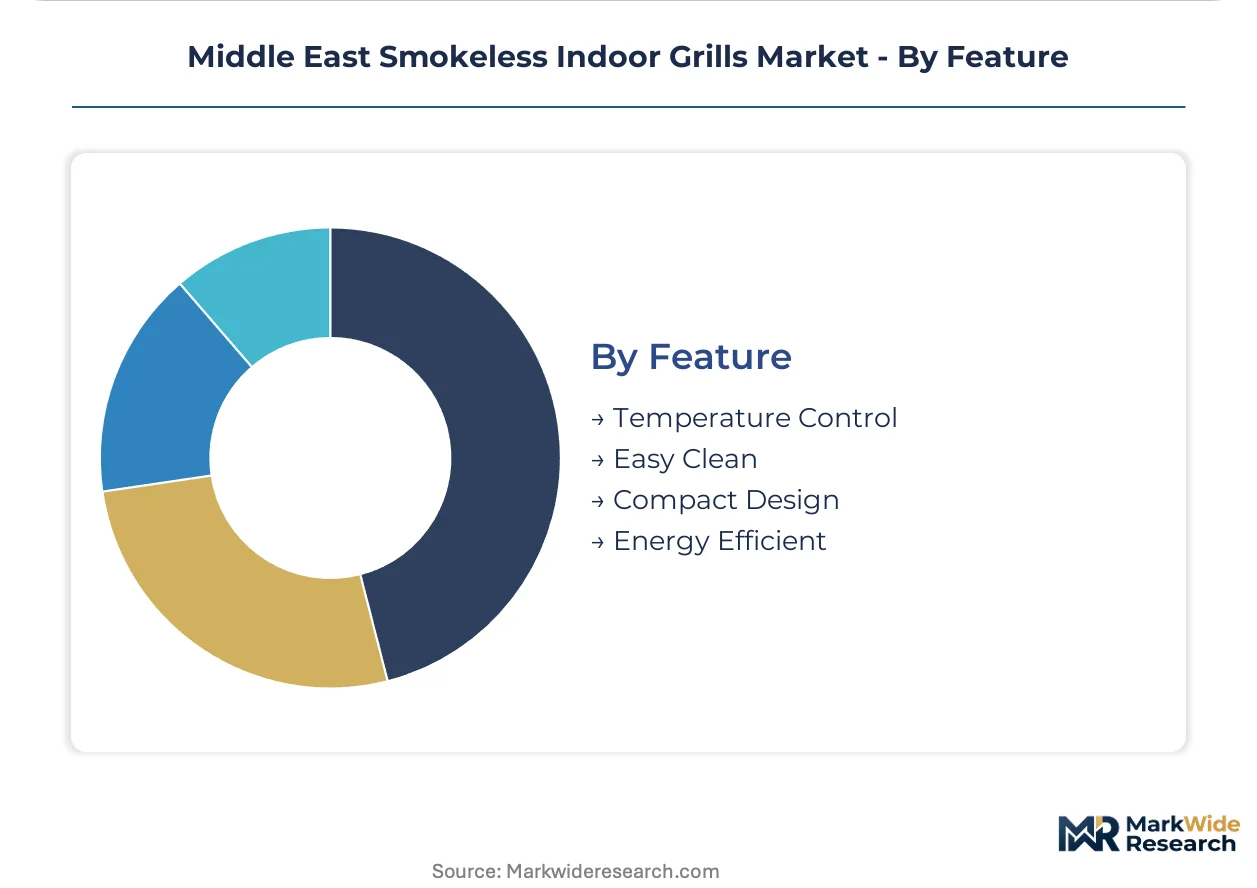
- Temperature Control:Digital or analog modulation systems enabling precise surface heat management. Philips leverages Gulf-based R&D for advanced control module integration.
- Energy Efficient:Design elements optimizing wattage consumption and thermal transfer efficiency. SASO's proposed labeling extension to small cooking appliances is forcing heating element redesigns.
- Easy Clean:Removable drip trays, dishwasher-safe components, and non-stick or ceramic-coated surfaces reducing maintenance labor. Tefal anchors volume share through retail distribution emphasizing this attribute.
- Compact Design:Reduced footprint configurations addressing shrinking kitchen dimensions in new Gulf residential construction. Geepas competes through localized assembly partnerships optimizing for space constraints.
Baseline expectations center on Easy Clean; specification premiums attach to Temperature Control intelligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Free Zone's logistics infrastructure concentrates regional distribution for smokeless grill imports serving the Gulf Cooperation Council trade corridor. Special economic zones in Dubai and Riyadh accelerate customs clearance for appliance manufacturers targeting multiple Middle Eastern markets. Tax incentives within these zones reduce landed costs for ceramic-coated aluminum components sourced from Asian suppliers.
United Arab Emirates
Hotel kitchen renovation cycles in Abu Dhabi and Dubai drive premium infrared grill procurement from hospitality procurement consortia. MOIAT certification alignment with GCC-wide electrical safety protocols streamlines cross-emirate distribution for Saudi-bound shipments. Jebel Ali's bonded warehousing enables consolidated inventory positioning for re-export across the Gulf.
Saudi Arabia
Apartment dwellers in Riyadh's high-rise residential towers generate concentrated demand for electric grills complying with SASO energy-efficiency labeling requirements. SASO's proposed extension of mandatory efficiency standards to small cooking appliances forces heating element redesigns among import suppliers. Hypermarket chains in Riyadh and Jeddah anchor volume distribution for mid-tier ceramic-coated product lines.
Kuwait
Hotel kitchen renovation activity in Kuwait City lags behind Dubai and Riyadh, creating whitespace for premium infrared grill deployment. The country's national standards body maintains electrical safety protocols that reference GCC harmonized frameworks. Hawalli Governorate's retail corridor sustains demand for compact multi-function units addressing smaller residential kitchen footprints.
Qatar
Hospitality sector investment ahead of international event cycles elevates specification requirements for front-of-house live cooking equipment. The Qatar General Organization for Standardization enforces energy-efficiency labeling that mirrors SASO protocols. Lusail City's new residential districts incorporate building fire codes that prohibit open-flame cooking appliances.
Bahrain
Budget-conscious residential buyers in Manama sustain demand for entry-level electric grills through traditional retail channels. The BD standards body maintains divergent certification requirements that force redundant testing for suppliers serving multiple Gulf markets. Muharraq's commercial districts concentrate independent restaurant procurement with limited vendor consolidation compared to Dubai.
Middle East Smokeless Indoor Grills Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium positioning concentrated among appliance multinationals while localized assembly partnerships capture price-sensitive volume. The vendor base organizes around three strategic archetypes: Gulf-based R&D hubs leveraging regional temperature control engineering, hypermarket-anchored volume players optimizing retail distribution density, and price-competitive assemblers exploiting free zone manufacturing incentives. Competitive moves center on portfolio diversification into multi-function configurations and geographic expansion through e-commerce channels bypassing traditional retail gatekeepers.
Within the branded appliance tier, Philips and Tefal occupy positions reflecting divergent strategic emphases. Philips exemplifies the Gulf-based R&D archetype through its appliance engineering footprint in the region. Tefal represents hypermarket-anchored volume capture through broad retail distribution across Saudi Arabia's chain store networks. Geepas sits within the localized assembly archetype, competing through UAE-based manufacturing partnerships that optimize for compact design requirements.
| Leading Market Players |
|---|
| Philips |
| Tefal |
| George Foreman |
| Panasonic |
| Cuisinart |
| Breville |
| Black & Decker |
| Morphy Richards |
| Geepas |
| Others |
Pricing and Supply Chain Analysis
SASO's mandatory energy-efficiency labeling gates qualified supply access and premium-tier pricing power, compressing margins for uncertified imports while rewarding compliant manufacturers with hospitality procurement eligibility. Ceramic-coated aluminum input costs and Jebel Ali logistics tariffs stratify final pricing across residential and commercial buyer segments.
Pricing Analysis
Lead-time-driven pricing separates spot inventory discounts from premium positioning for short-cycle delivery to Saudi hypermarket chains. Three-tier pricing structure across premium infrared, standard electric, and economy coil-based units reflects certification grade and after-sales bundling differentiation. Pricing pressure stems from aluminum and copper commodity volatility squeezing mid-tier engineering margins. Residential apartment dwellers in Riyadh exhibit highest price sensitivity, while Abu Dhabi hospitality consortia prioritize thermal performance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for warranty returns and refurbishment concentrate in Dubai's Jebel Ali Free Zone, where bonded warehousing enables consolidated regional service operations. Manufacturing draws from China's ceramic coating facilities, Vietnam's aluminum extrusion plants, and South Korea's infrared emitter component suppliers. Single-source vulnerability sits with precision temperature control module suppliers serving Philips' Gulf R&D footprint. Distribution runs through Saudi Arabia's hypermarket chains and UAE-based e-commerce platforms bypassing traditional retail gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers with GCC-wide certification capabilities, as SASO's accelerated compliance timelines force weaker assemblers without MOIAT-aligned testing infrastructure toward exit.
For Market Incumbents: Cement GCC-wide service network density to capture consolidated hospitality procurement decisions, locking out regional assemblers lacking multi-emirate spare parts logistics. Defend against price-competitive UAE-based partnerships by investing in ceramic-coated surface thermal engineering talent pools. Prioritize backward integration into aluminum substrate sourcing to buffer commodity volatility. For New Entrants and Emerging Players: E-commerce platform partnerships offer the fastest route around Saudi hypermarket gatekeepers in secondary cities like Dammam and Tabuk. Target Kuwait City's lagging hotel renovation cycle with premium infrared configurations before Dubai-based incumbents establish procurement relationships. Lead with compact multi-function designs optimized for Hawalli Governorate's shrinking residential kitchen footprints. For Investors and Strategic Acquirers: SASO's proposed extension of mandatory energy-labeling to small cooking appliances is the leading indicator that thermal engineering capabilities will command acquisition premiums. Long-term viability favors vertically integrated specialists with captive ceramic coating processes and Gulf-based R&D presence. Monitor MOIAT-SASO harmonization progress for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Function Product Line Expansion | Bundled griddle-panini-roasting capabilities capture shrinking Gulf kitchen demand from Dubai residential towers. |
| GCC-Wide Certification Harmonization | MOIAT-SASO alignment reduces redundant testing costs for suppliers serving multiple Gulf markets simultaneously. |
| E-Commerce Channel Bypass Strategy | Direct-to-consumer platforms unlock Saudi secondary cities beyond Riyadh-Jeddah hypermarket concentration. |
| Ceramic Coating Backward Integration | In-house ceramic deposition control buffers aluminum input volatility and accelerates SASO compliance cycles. |
| Kuwait Hospitality Preemption | Early infrared grill deployment captures whitespace before Abu Dhabi-Dubai procurement consortia extend reach. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with appliance R&D directors, Saudi hypermarket category buyers, UAE hospitality procurement managers, and ceramic coating suppliers. SASO efficiency labeling databases, MOIAT certification registries, and GCC customs harmonization protocols provided regulatory boundary conditions. Bottom-up unit shipment estimates triangulated against top-down hospitality renovation spend data across Abu Dhabi, Dubai, and Riyadh.
Product type, surface material, end-user application, and feature configuration were modeled at country-emirate level granularity across the projection horizon. CAGRs derived from regression analysis of historical appliance replacement cycles, residential construction permits, and hotel renovation pipeline disclosures. Forecast inputs incorporated SASO labeling adoption curves, aluminum price futures, and e-commerce penetration rates in Saudi secondary cities.
Several conditions sit outside the modeled scope, including geopolitical trade route disruptions, abrupt SASO protocol revisions, and unannounced hospitality project cancellations. Forecasts reflect stated regulatory trajectories and construction pipeline visibility. Practitioners should monitor MOIAT-SASO harmonization announcements and ceramic coating supplier consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
France Foodservice Market
Food Service
Gas Fryers Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Europe Online Grocery Delivery Market
Food Service
Ship Catering Service Market
Food Service
Germany Foodservice Market
Food Service
Personal Chef Services Market
Food Service
Steam Stew Pot Market
Food Service
Global Digital Food Delivery Market
Food Service
Food Logistics Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Europe Food Service Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Commercial Air Fryer Oven Market