
 France Foodservice Market | 2026-2036
France Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
France Foodservice Market Analysis
France's national food waste reduction mandate is hardening compliance requirements for commercial kitchens and contract caterers. Compass Group PLC leverages its centralized procurement infrastructure to absorb these regulatory costs across its institutional client base. Groupe Le Duff sustains competitive density in bakery-café formats through vertical control over flour milling and frozen dough production. McDonald's Corporation anchors its France network with kitchen automation investments that trim labor exposure to rising minimum wage floors.
France foodservice encompasses all commercial establishments preparing meals and beverages for immediate consumption, spanning from full-service restaurants with brigade-style kitchen hierarchies to automated fast-casual concepts deploying robotic assembly lines. The sector functions as a critical employment reservoir and a vector for agricultural product valorization, converting raw commodities into prepared food experiences at margin multiples exceeding retail grocery. Full-service restaurants dominate value capture in Paris and Lyon, where wine program depth and chef pedigree justify premium pricing. Fast-casual formats represent the fastest-expanding service type, capitalizing on compressed lunch windows among urban young professionals. Delivery channel growth is concentrating margin pressure on operators lacking proprietary logistics platforms, as aggregator commissions erode unit economics.
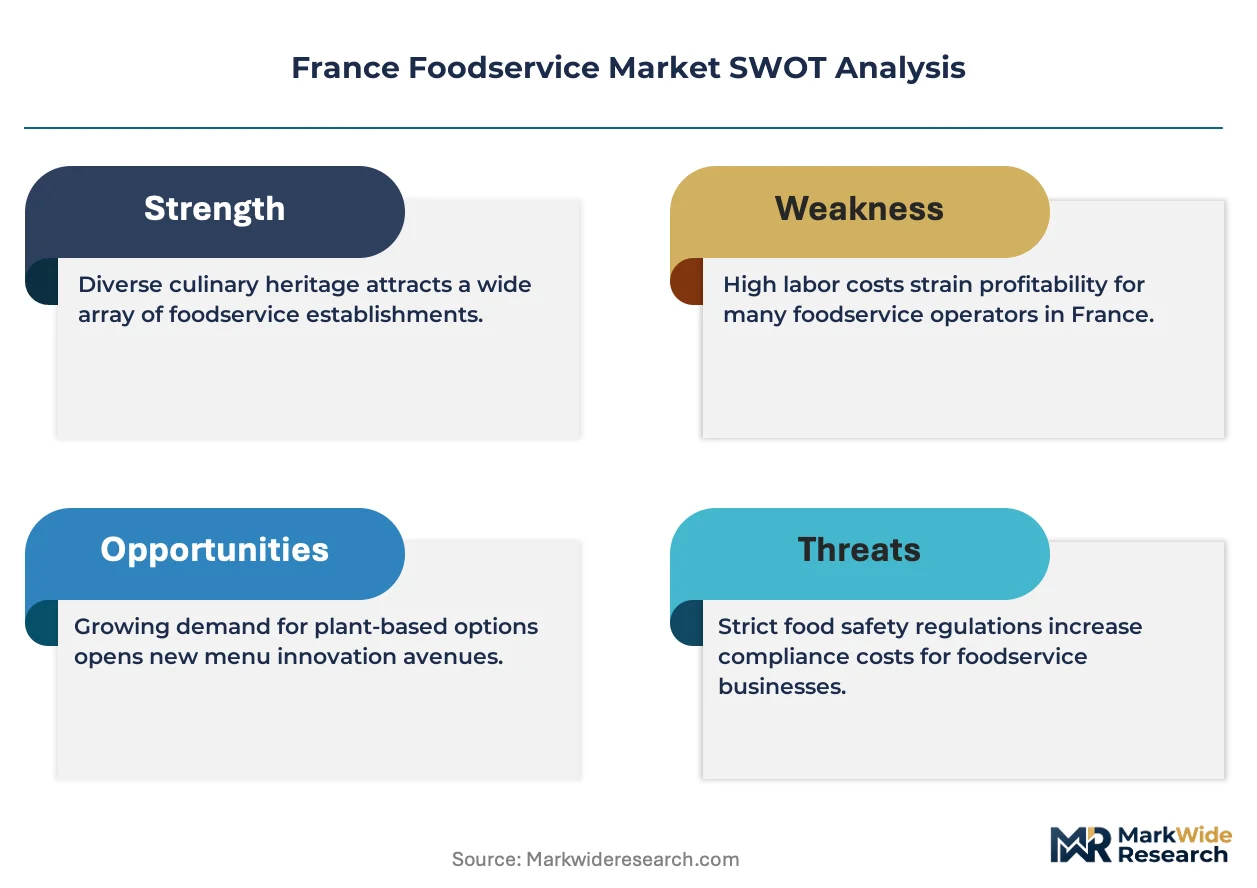
ANSM enforces allergen labeling and nutritional transparency standards that shape menu engineering decisions across chains and independents. EFSA guidelines on ultra-processed food classification are influencing procurement criteria in institutional catering contracts. The EU Green Deal's packaging waste directives are accelerating compostable container adoption, with DGCCRF conducting spot audits for greenwashing claims. Stakeholders must monitor how the convergence of labor regulation, packaging compliance, and energy cost volatility reshapes the optimal format mix between dine-in, takeaway, and delivery.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing French foodservice operators to reconfigure supply chains around compostable materials while absorbing compliance costs that compress already-thin margins in delivery-dependent formats.
Growth Catalysts
- Tourism corridor investment:Provence-Alpes-Côte d'Azur and Île-de-France are absorbing disproportionate capital deployment in premium dining capacity, anchoring revenue concentration in experiential formats.
- ANSM allergen transparency mandates:Standardized labeling requirements are accelerating digital menu engineering adoption across chains and independents, creating procurement differentiation through compliance infrastructure.
- Quick-service urban expansion:Secondary French cities are receiving accelerated chain footprint growth as primary markets saturate, extending format reach into lower-rent catchments.
Market Restraints
- Energy cost volatility:Commercial kitchen refrigeration and HVAC loads expose operators to EPEX spot price swings that erode profitability in full-service formats with extended operating hours.
- Aggregator commission structures:Third-party delivery platforms extract 15-30% per order, structurally degrading unit economics for operators lacking proprietary logistics or ghost kitchen density.
- Flour supply concentration:French milling capacity clusters in Hauts-de-France and Grand Est, creating geographic vulnerability for bakery-café chains dependent on fresh-daily supply rhythms.
Strategic Opportunities
- Institutional catering reform:EFSA ultra-processed food classification guidelines are reshaping procurement criteria in school and hospital contracts, rewarding operators with clean-label supply chain documentation.
- Channel convergence:Drive-thru formats are penetrating French suburban corridors previously resistant to American-style service models, capturing commute-time demand with limited real estate footprints.
- DGCCRF audit preparedness:Operators investing in verifiable compostable packaging systems ahead of greenwashing enforcement windows can capture premium positioning in corporate catering RFPs.
Industry Challenges
- Brigade kitchen labor scarcity:Traditional apprenticeship pipelines are failing to replenish station chef ranks, forcing full-service restaurants to simplify menu architecture or automate prep stages.
- Minimum wage compression:Rising SMIC floors are accelerating kiosk and mobile-order adoption, but front-of-house role elimination risks degrading the experiential differentiation that justifies Paris premium pricing.
- Legacy POS integration friction:Kitchen automation investments require API compatibility with entrenched reservation and payment systems, delaying rollout timelines for mid-size independent groups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Foodservice Market |
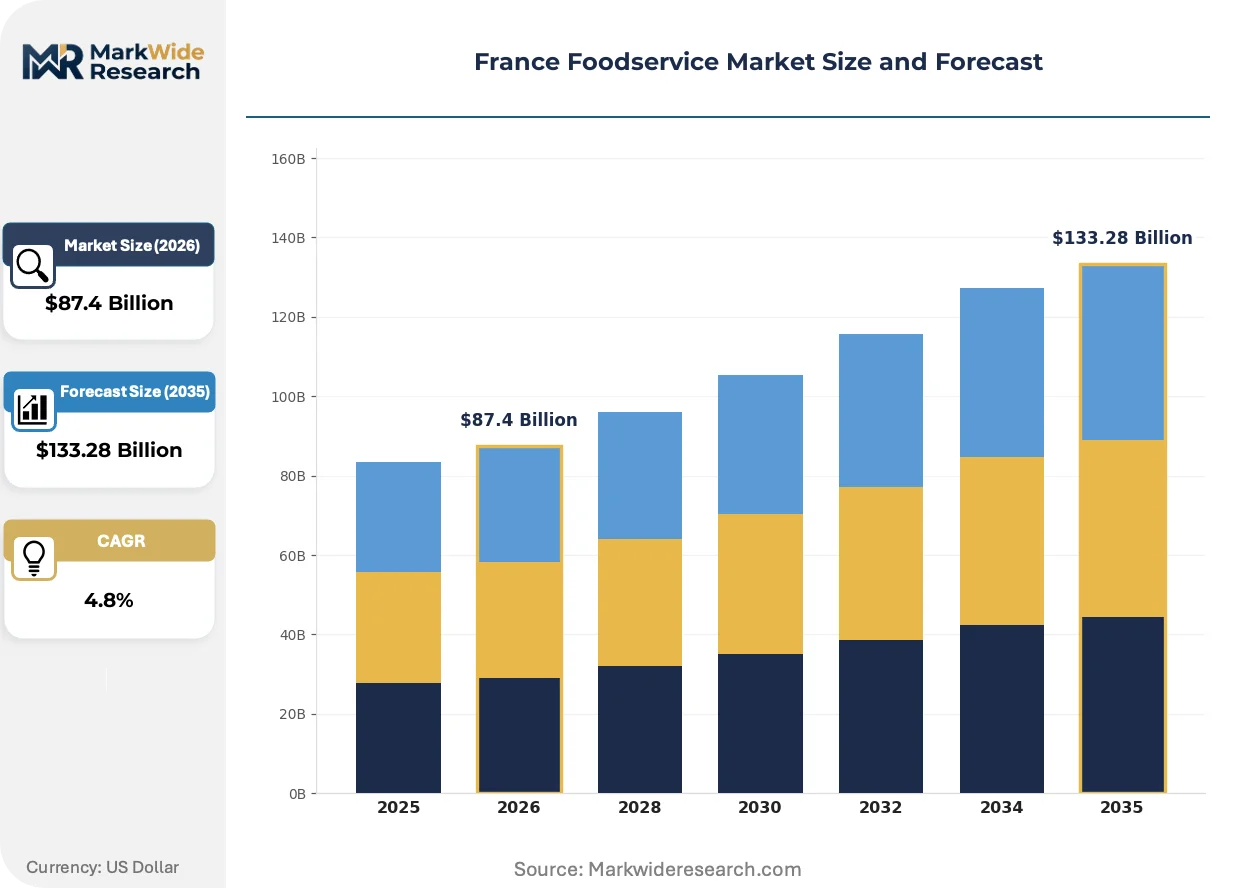
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-service Restaurants, Fast-casual, Cafés, Bars Product Type: Meals, Beverages, Snacks, Desserts Customer Type: Families, Young Professionals, Tourists, Students Distribution Channel: Dine-in, Takeaway, Delivery, Catering |
| Companies Covered | Compass Group PLC, AmRest Holdings SE, McDonald's Corporation, Groupe Bertrand, Groupe Le Duff, Starbucks Corporation, Accor S.A., Areas SAU, Yum! Brands, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Foodservice Market Emerging Trajectories
Automation, regulatory transparency mandates, and channel fragmentation are simultaneously compressing labor exposure and expanding format flexibility across French foodservice, with technology adoption pacing varying sharply by operator scale and urban density.
Robotic kitchen assembly systems are decentralizing production geography by enabling smaller-footprint formats with equivalent throughput to traditional brigade kitchens. Fast-casual chains in Lyon and Bordeaux are piloting these systems for standardized menu items. The structural consequence is reducing dependence on skilled labor pools concentrated in Paris, permitting viable expansion into secondary labor markets with tighter wage competition.
DGCCRF enforcement of EU Green Deal packaging directives is mandating compostable container adoption with spot audit verification. Operators are consolidating supplier relationships to reduce certification complexity and audit failure risk. Institutional catering contracts in Île-de-France are most affected, with contract caterers pre-qualifying vendors based on traceability documentation depth rather than unit cost alone.
Young professional lunch behavior is compressing decision windows and collapsing format boundaries between fast-casual, premium takeaway, and ghost kitchen delivery. Urban corridors in Paris intra-muros are witnessing the fastest channel switching, with operators responding through multi-format real estate strategies combining dine-in, pickup, and delivery-optimized kitchen lines within single locations.
France Foodservice Market Segmentation
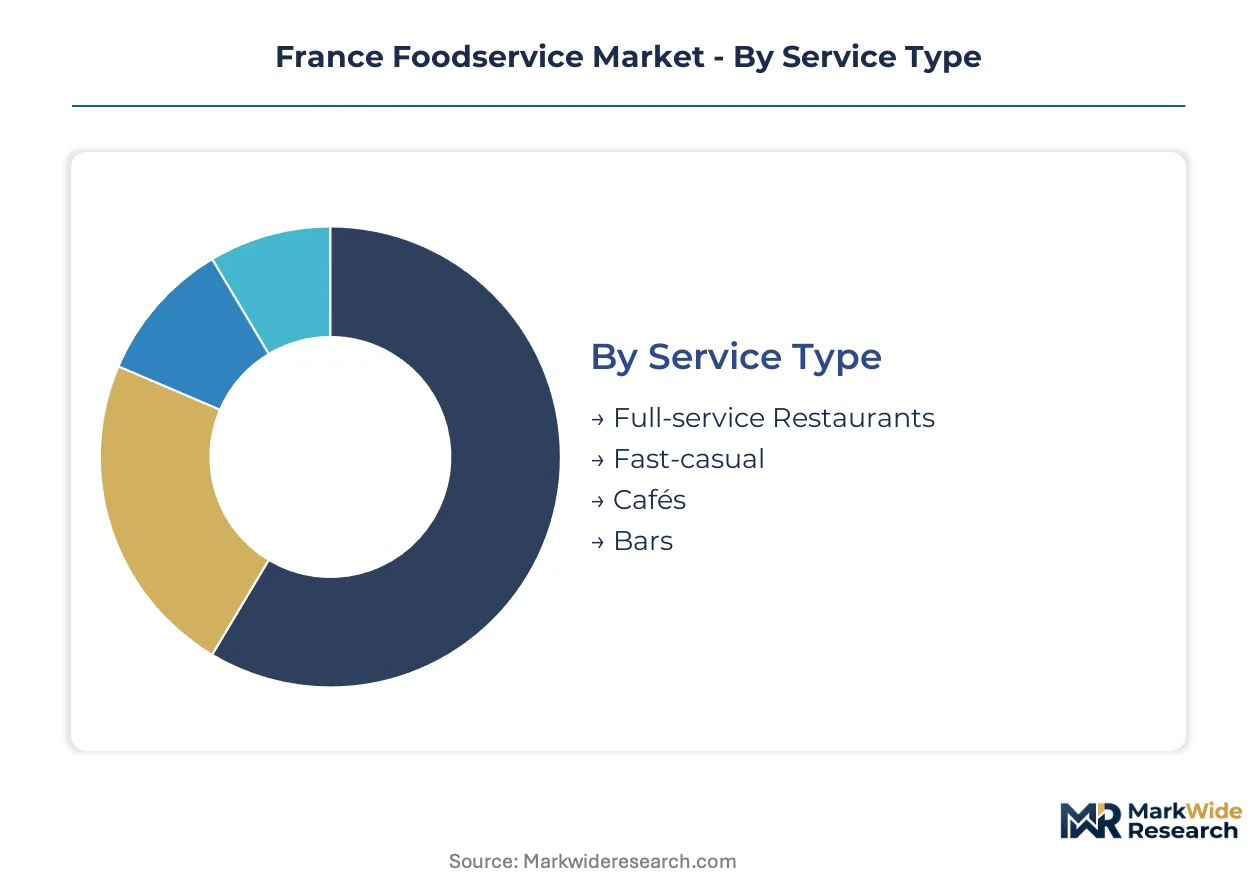
France foodservice operators configure format portfolios around labor intensity and real estate flexibility, with capital deployment varying sharply across brigade kitchens versus automated assembly concepts. Segmentation reveals where margin pressure concentrates and which customer-channel combinations justify premium infrastructure investment.
Service Type:
Full-service formats demand the heaviest upfront capital—brigade kitchen buildouts, wine cellar inventory, and front-of-house design—while fast-casual concepts compress equipment footprints through modular cooking lines.
- Full-service Restaurants:Brigade-style kitchen hierarchies require specialized stations for saucier, poissonnier, and pâtissier functions, with Paris and Lyon commanding premium rent multiples for experiential dining rooms. Labor scarcity in traditional apprenticeship pipelines is forcing simplification of menu architecture or partial automation of prep stages.
- Fast-casual:Standardized assembly lines with limited menu breadth enable replication across secondary cities with lower wage floors and reduced skilled labor dependency. Young professional lunch behavior in urban corridors is compressing decision windows and collapsing format boundaries between fast-casual and premium takeaway.
- Cafés:Bakery-café formats sustain competitive density through captive supply of flour milling and frozen dough production, with geographic clustering in Île-de-France and Provence-Alpes-Côte d'Azur absorbing disproportionate investment.
- Bars:Beverage-forward concepts with limited food preparation requirements carry lower equipment capex but face margin pressure from energy cost volatility affecting refrigeration loads and extended operating hours.
Full-service restaurants absorb the bulk of installed capacity; fast-casual is expanding most quickly.
Product Type:
Product mix determines supply chain complexity, with perishable protein and dairy workflows imposing stricter cold-chain requirements than shelf-stable snack categories.
- Meals:Prepared protein and starch combinations dominate transaction value in institutional catering contracts, where EFSA ultra-processed food classification guidelines are reshaping procurement criteria toward clean-label documentation.
- Beverages:Wine program depth justifies premium pricing in Paris full-service formats, while coffee and soft drink margins support fast-casual unit economics; ANSM allergen labeling mandates accelerate digital menu engineering for ingredient transparency.
- Snacks:Portable, low-preparation items align with compressed lunch windows and drive-thru penetration in French suburban corridors previously resistant to American-style service models.
- Desserts:Pâtisserie requirements sustain vertical integration into flour milling for bakery-café chains, with fresh-daily supply rhythms creating geographic vulnerability given milling capacity concentration in Hauts-de-France and Grand Est.
Meals command the largest revenue share; beverages deliver the highest margin per square meter.
Customer Type:
Customer segmentation maps directly to occasion-based demand patterns, with tourist and family segments concentrating in distinct geographic corridors and requiring differentiated service cadences.
- Families:Multi-generational dining occasions favor full-service formats with extended seating duration and children's menu options, concentrated in suburban catchments and tourist corridors.
- Young Professionals:Compressed lunch windows and mobile-order preference drive fast-casual and premium takeaway demand in Paris intra-muros and Lyon business districts.
- Tourists:Experiential dining investment in Provence-Alpes-Côte d'Azur and Île-de-France anchors revenue concentration in wine-forward, chef-pedigree formats with multilingual service infrastructure.
- Students:Price-sensitive demand concentrates in contract catering and university-adjacent fast-casual, with SMIC wage floors pushing operators toward kiosk adoption to defend margin position.
Young professionals generate the highest transaction frequency; tourists produce the largest average check.
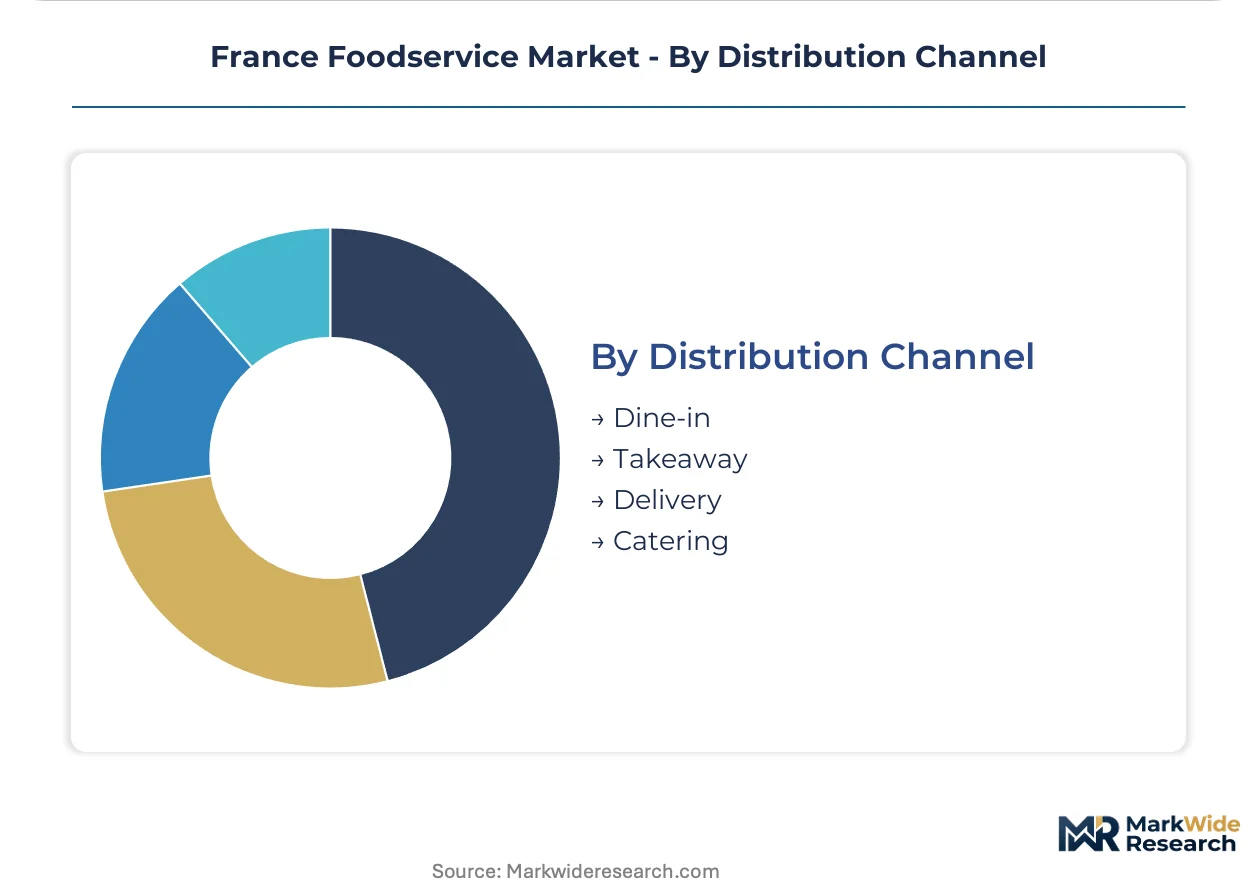
Distribution Channel:
Channel configuration determines last-mile cost structure, with proprietary logistics platforms separating profitable operators from those degraded by third-party aggregator commissions.
- Dine-in:Full-service experiential differentiation justifies premium pricing in Paris and Lyon, though rising minimum wage floors accelerate front-of-house role elimination that risks degrading the very positioning that commands rent multiples.
- Takeaway:Compostable packaging compliance with EU Green Deal directives imposes supplier consolidation and audit preparation costs, with DGCCRF spot enforcement windows creating pre-qualification barriers in corporate catering RFPs.
- Delivery:Aggregator commission structures extracting 15-30% per order structurally degrade unit economics for operators lacking ghost kitchen density or proprietary logistics platforms.
- Catering:Institutional contracts in schools and hospitals reward clean-label supply chain documentation, with EFSA guidelines on ultra-processed food classification reshaping procurement criteria toward traceability depth over unit cost.
Dine-in retains the largest revenue base; delivery is climbing the fastest despite margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ZRR tax incentive zones in Hauts-de-France and Grand Est are concentrating foodservice supply chain investment near flour milling clusters, reshaping where bakery-café chains locate commissary operations and frozen dough production facilities.
Île-de-France
Paris intra-muros commands premium rent multiples for experiential dining rooms where wine program depth justifies pricing. ANSM allergen labeling mandates accelerate digital menu engineering adoption across chains and independents. La Défense and Bercy business districts absorb disproportionate fast-casual investment targeting compressed lunch windows.
Auvergne-Rhône-Alpes
Lyon's brigade kitchen heritage sustains full-service format dominance despite labor scarcity forcing menu simplification. EFSA ultra-processed food classification guidelines reshape procurement criteria in hospital and school catering contracts. The Lyon-Part-Dieu corridor attracts ghost kitchen operators serving delivery-optimized concepts.
Provence-Alpes-Côte d'Azur
Tourist corridor investment concentrates capital deployment in chef-pedigree formats with multilingual service infrastructure. EU Green Deal packaging directives compel compostable container adoption with DGCCRF audit preparation. Nice and Cannes absorb premium dining capacity expansion targeting seasonal demand spikes.
Hauts-de-France
Flour milling capacity clustering creates geographic vulnerability for bakery-café chains dependent on fresh-daily supply rhythms. SMIC wage floors accelerate kiosk adoption in contract catering operations serving industrial zones. Lille and Valenciennes anchor quick-service expansion into secondary labor markets.
Nouvelle-Aquitaine
Bordeaux's urban core pilots robotic kitchen assembly systems for standardized menu items, reducing skilled labor dependency. Energy cost volatility from EPEX spot price swings erodes profitability in full-service formats with extended operating hours. The Atlantic coastal strip attracts drive-thru format penetration in suburban corridors.
France Foodservice Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across format portfolios, creating tiered market structure where scale advantages separate national operators from regional independents. The vendor base clusters around three strategic archetypes: institutional contract caterers with centralized procurement infrastructure, quick-service chains deploying kitchen automation, and hospitality groups anchoring premium experiential positioning. Consolidation pressure concentrates among mid-size independent groups facing POS integration friction and legacy system replacement costs. Competitive moves center on M&A for geographic density and vertical integration into captive supply chains.
Within the institutional catering tier, Compass Group PLC exemplifies scale-driven procurement centralization. Among quick-service operators, McDonald's Corporation and Yum! Brands occupy positions defined by automation investment and format flexibility. Groupe Le Duff represents bakery-café specialists leveraging upstream control over flour milling and frozen dough production. These three anchors illustrate how competitive positioning diverges across procurement infrastructure, kitchen technology, and supply chain integration strategies.
| Leading Market Players |
|---|
| Compass Group PLC |
| AmRest Holdings SE |
| McDonald's Corporation |
| Groupe Bertrand |
| Groupe Le Duff |
| Starbucks Corporation |
| Accor S.A. |
| Areas SAU |
| Yum! Brands |
| Others |
Supply Flow & Price Mechanics
EFSA ultra-processed food classification guidelines are reshaping procurement criteria in institutional catering contracts, compelling operators to source from clean-label suppliers and absorb certification premiums that stratify pricing across contract tiers.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations for fresh-daily bakery supply, with operators paying markups for same-day flour delivery from Hauts-de-France mills versus frozen-dough alternatives. Three-tier pricing structure across premium experiential, standard fast-casual, and economy contract catering levels reflects labor intensity and real estate location. Cost compression in delivery-dependent formats is intensifying because aggregator commissions extract 15-30% per order. Contract catering buyers exhibit highest price sensitivity, while tourist corridor operators in Provence-Alpes-Côte d'Azur demonstrate lowest sensitivity due to seasonal demand concentration.
Supply Chain Analysis
Compostable packaging certification under EU Green Deal directives is gating supplier qualification, with DGCCRF audit requirements consolidating vendor relationships around traceability-documented producers. Flour milling capacity clusters in France's Hauts-de-France and Grand Est regions, while specialty protein and dairy inputs draw from Belgium, the Netherlands, and domestic agricultural zones. Single-source vulnerability concentrates in fresh-daily supply rhythms for bakery-café chains tethered to geographic milling clusters. Distribution runs through centralized commissary networks serving multi-format footprints, with ghost kitchen density determining last-mile cost efficiency in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kitchen automation systems are displacing traditional brigade hierarchies, creating asymmetric returns for operators that reconfigure labor models before SMIC wage floors escalate further.
For Market Incumbents: To counter labor scarcity in traditional apprenticeship pipelines, full-service operators should automate prep stages for standardized menu components while preserving experiential front-of-house roles that justify Paris rent multiples. Consolidating supplier relationships around compostable packaging vendors with DGCCRF audit documentation reduces greenwashing enforcement risk. For New Entrants and Emerging Players: Drive-thru formats in French suburban corridors previously resistant to American-style service models represent the most penetrable white-space opportunity, capturing commute-time demand with limited real estate footprints. Ghost kitchen operators should target Lyon-Part-Dieu and Bordeaux business districts with delivery-optimized concepts, leveraging robotic assembly systems to reduce skilled labor dependency in secondary labor markets. For Investors and Strategic Acquirers: The window for entry favors mid-size independent groups with legacy POS integration friction but strong regional brand equity, as consolidation pressure concentrates among operators facing system replacement costs. Watch for inflection when ANSM enforcement windows for allergen transparency mandates accelerate digital menu engineering adoption, separating compliance-infrastructure-ready targets from laggards.| Strategic Initiative | Industry Significance |
|---|---|
| Kitchen Automation Deployment | Robotic assembly lines reduce brigade labor dependency while maintaining throughput in secondary city expansion. |
| Compostable Packaging Certification | DGCCRF-audited suppliers capture premium positioning in corporate catering RFPs ahead of enforcement windows. |
| Multi-Format Real Estate Convergence | Single locations combining dine-in, pickup, and delivery kitchen lines optimize urban rent exposure in Paris intra-muros. |
| Centralized Procurement Infrastructure | Institutional caterers with scale absorb regulatory compliance costs across school and hospital contract portfolios. |
| Vertical Control Over Flour Milling | Bakery-café chains with captive frozen dough production defend margin position against supply concentration risk. |
Methodological Framework
Multi-period observation of SMIC wage trajectory, EU Green Deal implementation timelines, and tourism corridor investment flows anchored the trend analysis, supplemented by interviews with chain procurement directors, institutional catering contract managers, ghost kitchen operators, and ANSM compliance officers. Secondary validation drew from DGCCRF enforcement bulletins, EFSA guidance documents, EU packaging directive texts, and regional tourism board investment disclosures. Bottom-up operator surveys triangulated against top-down sector expenditure estimates.
Input-output matrices modeled format-level revenue attribution across service type, product category, customer segment, and distribution channel dimensions throughout the forecast period. CAGRs were derived from segmented growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated labor cost elasticity parameters and regulatory compliance cost curves specific to French foodservice operations.
Revisions become necessary when ANSM enforcement intensity, EPEX spot price volatility, or aggregator commission structure changes materialize beyond modeled scenarios. A model refresh is warranted upon material change in EU Green Deal packaging directive implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Electric Tiffin Market
Food Service
Europe Barbeque Grill Market
Food Service
Commercial Tableware Services Market
Food Service
Cambodia Foodservice Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Flat Top Grills Market
Food Service
Commercial Rice Cooker Market
Food Service
Global Online Food Ordering Market
Food Service
United Kingdom Foodservice Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Europe Inflight Catering Market
Food Service
Haute Cuisine Market
Food Service
Europe Food Away from Home Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Malaysia Food Service Market
Food Service
Meal Kit Delivery Services Market