
 Commercial Air Fryer Oven Market | 2026-2036
Commercial Air Fryer Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Air Fryer Oven Market Outlook
The gap between premium stainless-steel builds and entry-level coated-steel units is repositioning procurement budgets across commercial kitchens. Breville Group Limited leverages its Australian engineering heritage to dominate high-capacity countertop segments. COSORI anchors its position through aggressive channel control in North American foodservice distribution. Ninja Kitchen differentiates via rapid-cook technology leadership in multi-function oven configurations.
A commercial air fryer oven is an electrically heated cooking appliance that circulates superheated air between 300°F and 450°F through a convection mechanism to produce crisped food surfaces without submersion in oil, designed for continuous-duty cycles in professional food preparation environments. Floor model units with infrared technology command the widest margin pools due to their integration into high-throughput restaurant lines. Countertop fryers lead in unit volume across catering services and food trucks where space constraints dictate equipment selection. Ventless fryer adoption is accelerating in urban hotel kitchens where hood infrastructure is limited or cost-prohibitive to install.
The FDA's Food Code equipment standards and NSF/ANSI 4 commercial cooking certification requirements govern product legality in United States foodservice establishments. Ecodesign regulations under the EU Green Deal framework are pressuring European manufacturers to improve energy efficiency ratings and reduce standby power consumption. Stakeholders must monitor evolving municipal electrification mandates in major cities and decide whether to prioritize ventless certification portfolios or invest in higher-capacity floor models for chain restaurant rollouts.
Market Dynamics
Restaurant chains in the United States and Germany are accelerating kitchen automation programs, forcing equipment manufacturers to prioritize throughput capacity and connectivity integration over standalone functionality. This automation imperative compresses replacement cycles and reshapes vendor selection criteria across commercial foodservice.
Growth Catalysts
- NSF/ANSI 4 Certification Requirements:United States foodservice establishments must deploy NSF-certified equipment to meet FDA Food Code standards, creating mandatory replacement demand in older kitchen installations.
- Ventless Technology:Urban hotel kitchens in New York, Chicago, and London are adopting ventless fryer configurations where hood infrastructure installation proves cost-prohibitive or physically constrained.
- Infrared Heating Systems:High-throughput restaurant lines in Germany are integrating infrared floor models to achieve faster recovery times and reduced energy consumption per cooking cycle.
Market Restraints
- Stainless Steel Input Volatility:Premium unit manufacturing depends on nickel-alloy stainless steel grades subject to commodity price swings from Indonesian and Russian supply sources.
- Certification Timeline Friction:NSF International and ETL listing processes extend product launch windows by eight to fourteen months for new ventless configurations entering United States distribution.
- Convection Steam Ovens:Multi-function steam-convection units from European manufacturers capture overlapping use cases in institutional catering and healthcare foodservice segments.
Strategic Opportunities
- EU Green Deal Ecodesign Pressure:European Union standby power consumption mandates are creating first-mover advantage for manufacturers achieving A-grade energy efficiency ratings ahead of compliance deadlines.
- Food Truck Channel Expansion:Mobile foodservice operators in Texas, Florida, and California require compact countertop units with generator-compatible electrical draws below 240V single-phase.
- Connectivity Integration:IoT-enabled fryers combining temperature logging with predictive maintenance algorithms are penetrating quick-service restaurant chains with centralized kitchen management systems.
Industry Challenges
- Electrical Infrastructure Retrofitting:Older United States restaurant buildings require panel upgrades and dedicated circuit installation to support high-amperage floor model deployments, extending sales-to-revenue cycles.
- Cross-Border Certification Harmonization:Manufacturers serving both United States and European Union markets must maintain parallel testing protocols for NSF, CE marking, and Ecodesign compliance, duplicating quality assurance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Air Fryer Oven Market |
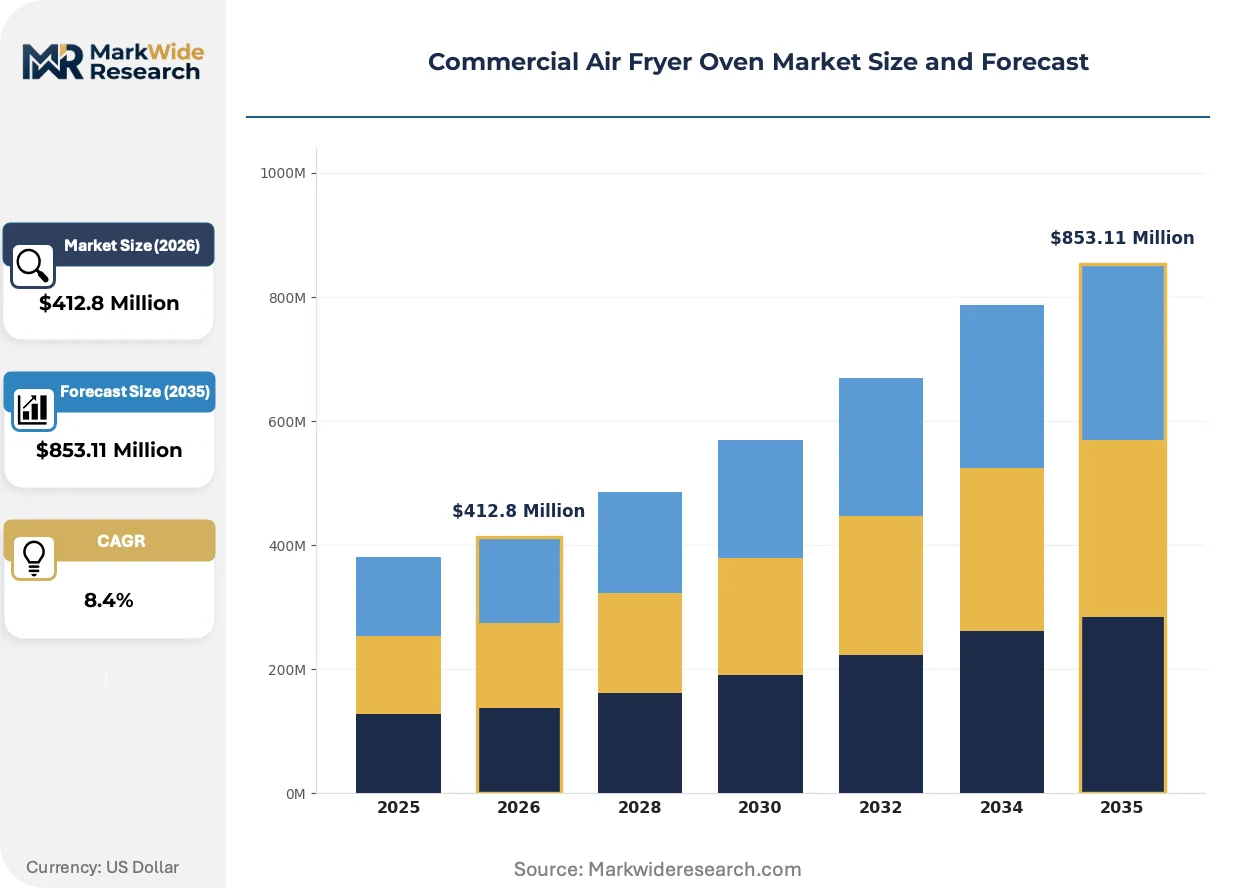
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $853.11 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Fryer, Floor Model, Multi-Function Oven, Ventless Fryer End User: Restaurants, Catering Services, Food Trucks, Hotels Technology: Convection, Infrared, Halogen, Microwave Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Philips, Breville Group Limited, Cuisinart, Ninja Kitchen, Hamilton Beach Brands, COSORI, Kalorik, Black & Decker, GoWISE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Air Fryer Oven Market Strategic Shifts
Equipment functionality is converging around multi-cavity configurations and automated menu programming, compressing the distinction between fryers, ovens, and holding cabinets. Vendors are repositioning around software-enabled cooking profiles rather than thermal engineering specifications alone.
Infrared quartz heating elements with instant-on capability are overtaking traditional calrod resistance systems in premium floor model segments. Full-service restaurant chains in the United States are specifying infrared recovery for high-volume french fry and protein operations. This thermal technology is overtaking conventional convection in applications requiring sub-two-minute recovery between batch loads.
EU Green Deal Ecodesign regulations are mandating maximum standby power thresholds and mandatory energy efficiency labeling for commercial cooking equipment sold in Germany, France, and Italy. Manufacturers must redesign control board architectures and insulation packages to achieve compliance. German commercial kitchen distributors are prioritizing A-rated inventory ahead of enforcement phases beginning in 2027.
Buying committees at United States restaurant chains are consolidating vendor relationships around single-source equipment packages spanning fryers, ovens, and holding cabinets. Independent equipment dealers are losing specification influence to direct manufacturer partnerships with corporate procurement functions. This concentration is most visible in quick-service franchise systems operating standardized kitchen templates across multiple states.
Commercial Air Fryer Oven Market Segmentation
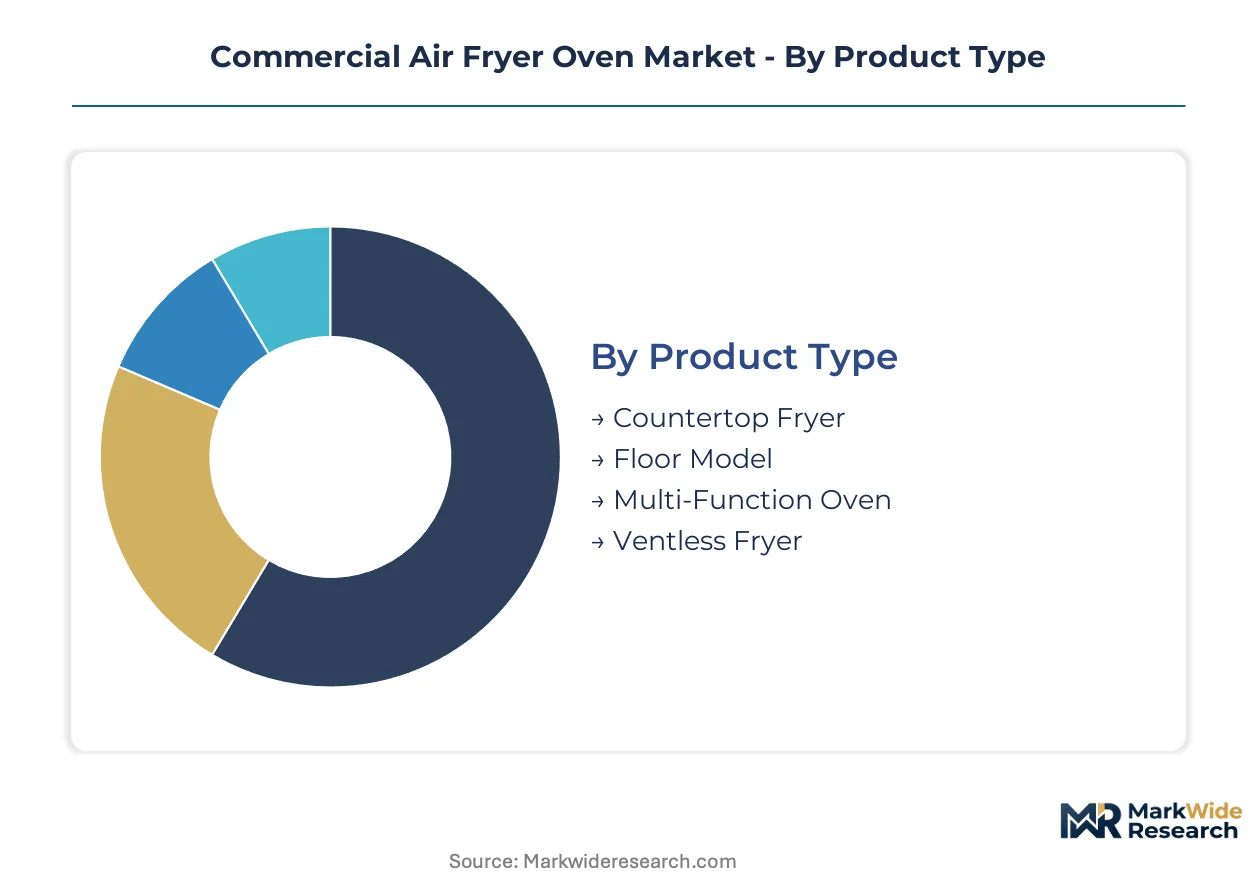
Commercial air fryer ovens fragment across four critical dimensions that determine procurement workflows and kitchen integration depth. Product type and technology choices dictate whether units operate as standalone appliances or embed into automated cooking lines. End user and capacity selections reflect throughput requirements and spatial constraints that vary sharply across foodservice verticals.
Product Type:
Integration depth separates countertop units designed for plug-and-play deployment from floor models requiring permanent kitchen infrastructure. Standalone configurations dominate mobile and retrofit applications; embedded systems anchor high-throughput restaurant lines.
- Countertop Fryer:Compact electric units with single-phase 120V or 240V draws fit food trucks and catering operations where mobility matters. Demand concentrates in Texas, Florida, and California mobile foodservice corridors where generator-compatible electrical loads below 30 amps prove essential for operational flexibility.
- Floor Model:High-capacity units with dedicated 208V three-phase connections integrate into permanent restaurant cooking lines. German full-service chains specify these for high-volume french fry and protein operations where sub-two-minute recovery between batch loads drives throughput metrics.
- Multi-Function Oven:Hybrid appliances combining air frying with baking, roasting, and holding modes reduce equipment counts in space-constrained kitchens.
- Ventless Fryer:Self-contained filtration and fire suppression systems eliminate hood infrastructure requirements. Urban hotel kitchens in New York, Chicago, and London adopt these where building constraints prohibit traditional ventilation installation.
Volume placements concentrate in countertop configurations; the faster expansion belongs to ventless technology.
End User:
Customer type determines duty cycle intensity and connectivity requirements, with chain restaurants demanding IoT integration while independent operators prioritize capital efficiency. Application context shapes whether units face continuous batch processing or intermittent peak-load service.
- Restaurants:Full-service and quick-service chains deploy high-capacity floor models with automated menu programming. United States franchise systems operating standardized kitchen templates across multiple states consolidate vendor relationships around single-source equipment packages spanning fryers, ovens, and holding cabinets.
- Catering Services:Event-based operators require rapid deployment and breakdown capabilities. Medium-capacity countertop units with generator compatibility serve outdoor venues and temporary kitchen installations where permanent infrastructure is unavailable.
- Food Trucks:Mobile operators face severe space and electrical constraints. Compact units with sub-240V single-phase draws dominate this channel.
- Hotels:Urban properties with limited hood infrastructure drive ventless fryer adoption. Breakfast service and room-service operations favor multi-function configurations that compress equipment footprints in back-of-house areas.
Restaurant chains generate the highest unit volumes; food trucks are climbing the fastest as mobile foodservice expands across Sun Belt metropolitan areas.
Technology:
Heating system selection determines energy efficiency ratings, recovery speed, and compliance with emerging Ecodesign mandates. Thermal engineering choices increasingly separate premium positioning from cost-driven procurement.
- Convection:Traditional forced-air circulation through calrod resistance elements dominates entry-level and mid-market segments. Established technology with broad service network support appeals to independent operators prioritizing maintenance accessibility.
- Infrared:Quartz heating elements with instant-on capability achieve faster recovery times and reduced energy consumption per cooking cycle. German distributors prioritize A-rated infrared inventory ahead of EU Green Deal enforcement phases.
- Halogen:Visible-light heating systems offer rapid preheating but limited penetration in commercial segments due to durability concerns under continuous-duty cycles.
- Microwave:Hybrid microwave-convection configurations accelerate cook times for specific protein applications. Niche adoption in healthcare and institutional foodservice where speed outweighs surface crisping requirements.
Convection technology holds the installed base majority; infrared systems are gaining share fastest as energy efficiency ratings become procurement criteria.
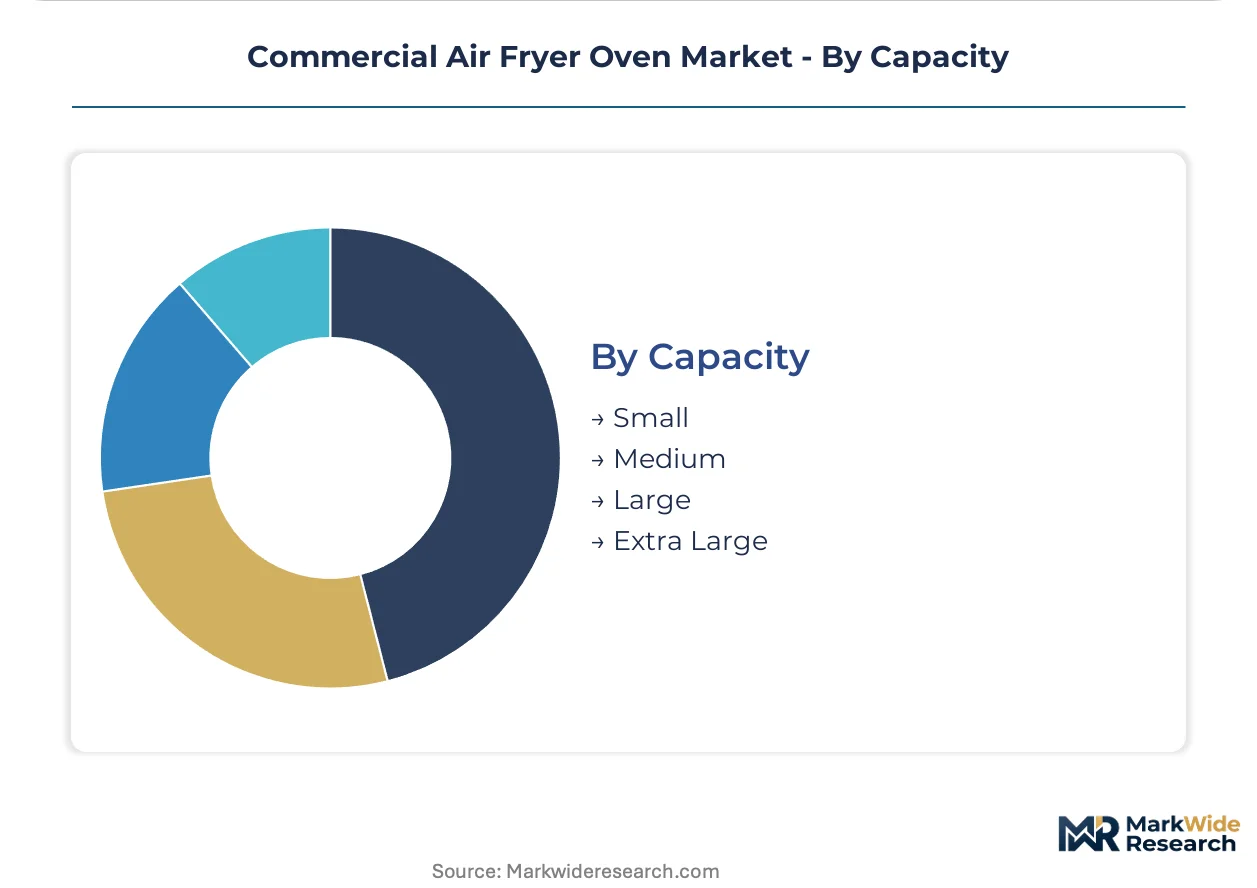
Capacity:
Scale selection correlates directly with batch size requirements and peak-hour throughput targets. Capacity tiers map to kitchen size, menu breadth, and labor deployment models across foodservice verticals.
- Small:Under 10-pound batch capacity serves food trucks, coffee shops, and limited-menu operations. Generator-compatible electrical draws enable off-grid deployment.
- Medium:10-25 pound capacity targets catering services and mid-size restaurants. Flexible enough for varied menus without excessive energy consumption during low-volume periods.
- Large:25-50 pound capacity anchors high-throughput quick-service lines. United States chain restaurants specify these for dedicated french fry and chicken protein stations.
- Extra Large:Over 50-pound batch capacity serves institutional catering, stadium concessions, and central commissary operations. Limited vendor base due to specialized engineering requirements.
Medium capacity generates the broadest placement footprint; extra large configurations show the steepest expansion trajectory as central kitchen models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American ventless fryer deployment as urban hotel kitchens confront hood infrastructure constraints. Restaurant automation programs in the metropolitan corridor accelerate replacement cycles for connected cooking equipment.
United States
Quick-service franchise systems operating standardized kitchen templates across multiple states consolidate vendor relationships around single-source equipment packages. FDA Food Code equipment standards and NSF/ANSI 4 certification requirements govern product legality in foodservice establishments. Texas, Florida, and California mobile foodservice corridors drive generator-compatible countertop unit demand.
Germany
Full-service chains specify infrared floor models for high-volume french fry and protein operations where sub-two-minute recovery drives throughput metrics. EU Green Deal Ecodesign regulations mandate maximum standby power thresholds and mandatory energy efficiency labeling for commercial cooking equipment. Commercial kitchen distributors in Bavaria and North Rhine-Westphalia prioritize A-rated inventory ahead of enforcement phases.
United Kingdom
Urban hotel properties in London adopt ventless fryer configurations where building constraints prohibit traditional ventilation installation. Ecodesign regulations under the EU Green Deal framework pressure manufacturers to improve energy efficiency ratings. The Southeast corridor concentrates procurement activity for multi-function oven configurations in space-constrained back-of-house areas.
France
Institutional catering segments in Île-de-France evaluate multi-function steam-convection alternatives for healthcare foodservice applications. Ecodesign standby power consumption mandates create first-mover advantage for manufacturers achieving A-grade energy efficiency ratings. The Auvergne-Rhône-Alpes industrial cluster hosts equipment testing facilities for CE marking and Ecodesign compliance protocols.
Japan
Compact countertop configurations serve metropolitan Tokyo foodservice operators facing severe spatial constraints in dense urban districts. METI energy efficiency standards shape product development priorities for commercial kitchen equipment. The Kansai corridor around Osaka concentrates mid-size restaurant deployment of medium-capacity units with flexible menu capabilities.
Commercial Air Fryer Oven Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and thermal technology tiers. The vendor base organizes into three structural tiers: established appliance conglomerates with broad foodservice portfolios, specialized countertop equipment fabricators, and emerging connectivity-enabled entrants. Consolidation pressure concentrates specification influence in direct manufacturer partnerships with corporate procurement functions. Dominant competitive moves include strategic partnerships for IoT platform integration and portfolio diversification into multi-function oven configurations.
Within the premium engineering tier, Breville Group Limited and Ninja Kitchen exemplify technology-differentiated positioning. COSORI anchors the North American channel control archetype through foodservice distribution relationships. Hamilton Beach Brands occupies a position bridging consumer and commercial segments with scale-driven manufacturing economics.
| Leading Market Players |
|---|
| Philips |
| Breville Group Limited |
| Cuisinart |
| Ninja Kitchen |
| Hamilton Beach Brands |
| COSORI |
| Kalorik |
| Black & Decker |
| GoWISE |
| Others |
Value Chain & Pricing Dynamics
Nickel-alloy stainless steel price indices from Indonesian and Russian supply sources cascade through commercial air fryer oven manufacturing into three distinct procurement tiers. Buyers face escalating cost compression when specifying NSF/ANSI 4 certified ventless configurations, while entry-level coated-steel countertop units absorb commodity volatility through thinner margin structures.
Pricing Analysis
Throughput-based pricing anchors commercial kitchen procurement decisions, with floor models commanding premiums tied to batch recovery speed and continuous-duty cycle ratings. Three-tier pricing structure across premium infrared, standard convection, and economy halogen configurations separates buyers by certification grade and energy efficiency rating. Pricing pressure stems from EU Green Deal Ecodesign mandates forcing control board redesigns and insulation upgrades. Independent restaurant operators exhibit highest price sensitivity, while United States quick-service franchise systems prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Trans-Pacific freight cost volatility shapes inventory positioning for manufacturers sourcing heating elements from China, control systems from Taiwan, and nickel-alloy stainless steel from Indonesia. Component fabrication draws from Guangdong Province electronics clusters, Bavarian precision engineering centers, and South Korean quartz heating element specialists. Single-source vulnerability concentrates in infrared quartz element supply where German and Japanese vendors dominate technical specifications. Distribution runs through foodservice equipment dealers, direct manufacturer partnerships with chain procurement functions, and e-commerce channels serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial air fryer oven supply remains constrained by NSF/ANSI 4 certification bottlenecks, propping pricing power for ventless-qualified manufacturers while compressing margins for uncertified competitors.
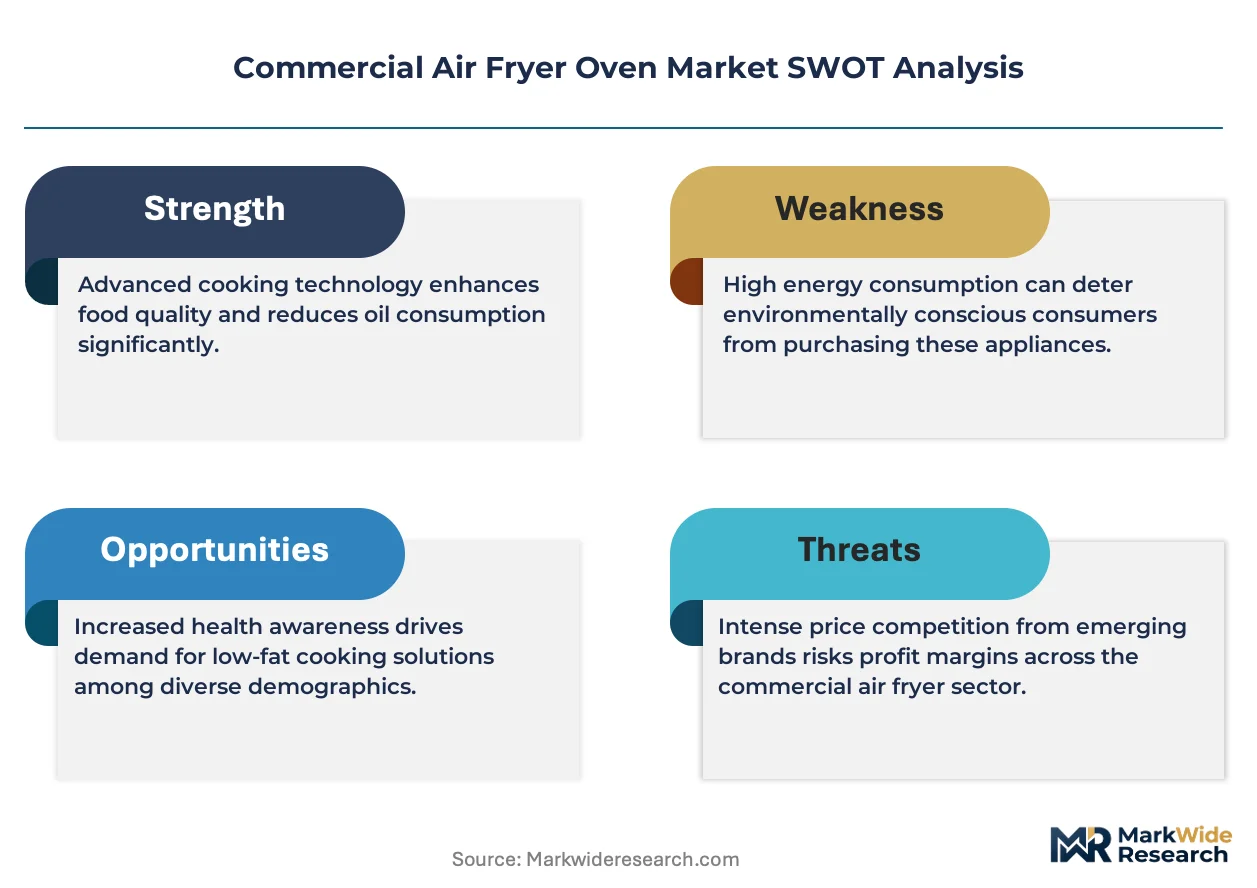
For Market Incumbents: Hedge against convection technology displacement by accelerating infrared platform development and securing captive supply of nickel-alloy stainless steel through backward integration into Indonesian sourcing relationships. Prioritize certification investment in EU Green Deal A-grade energy efficiency ratings ahead of enforcement phases. Channel control through direct partnerships with United States quick-service franchise procurement functions defends specification influence against emerging connectivity-enabled entrants. For New Entrants and Emerging Players: Food truck digital-channel routes offer lowest barrier to entry, with generator-compatible countertop units underrepresented in Texas, Florida, and California mobile foodservice corridors. Target medium-capacity configurations for catering services where established brands maintain weaker distribution presence. White-space penetration demands IoT-enabled temperature logging as a differentiated software layer rather than thermal engineering parity. For Investors and Strategic Acquirers: Distressed-cycle entries favor connectivity-enabled equipment fabricators with existing NSF/ANSI 4 certification portfolios in North American foodservice distribution. Five-to-ten year viability hinges on software-enabled cooking profile monetization rather than hardware replacement cycles alone. Watch municipal electrification mandate acceleration in major United States metropolitan areas as inflection indicator for ventless technology demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Enables predictive maintenance algorithms for quick-service restaurant chains with centralized kitchen management systems. |
| EU Green Deal Compliance Investment | Secures first-mover advantage in German, French, and Italian markets ahead of A-grade energy efficiency enforcement. |
| Ventless Certification Expansion | Captures urban hotel kitchen demand in New York, Chicago, and London where hood infrastructure is cost-prohibitive. |
| Infrared Technology Acquisition | Accelerates recovery time performance for high-throughput french fry and protein operations in German full-service chains. |
| Food Truck Channel Partnership | Penetrates Texas, Florida, and California mobile foodservice corridors with generator-compatible electrical configurations. |
Study Parameters
Document review covered FDA Food Code equipment standards, NSF International certification databases, EU Green Deal Ecodesign regulatory filings, and commercial kitchen equipment trade customs records, complemented by interviews with restaurant chain procurement directors, foodservice equipment dealers, commercial kitchen design consultants, and HVAC/fire suppression engineers. Secondary validation drew from SEC filings of publicly traded appliance manufacturers, ETL listing directories, and German commercial kitchen distributor inventory reports. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Cross-referencing historical certification timeline data against expert panel input on replacement cycle acceleration shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, heating technology, end-user vertical, and capacity tier alongside regional regulatory cluster differentiation. CAGRs derived from curve-fitting approaches applied to disclosed manufacturer shipment data and distributor inventory turnover patterns, with particular weighting assigned to ventless technology adoption curves and infrared heating element penetration rates.
The model holds under stable nickel-alloy stainless steel supply conditions and consistent NSF/ANSI 4 certification processing timelines; deviation in Indonesian export restrictions or FDA Food Code amendment cycles would shift replacement demand timing and vendor selection criteria. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Air Fryer Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Latin America Inflight Catering Market
Food Service
Global Waffle Maker Market
Food Service
Commercial Rice Cooker Market
Food Service
Pasteurized Eggs Market
Food Service
Fast Food Market
Food Service
Commercial Tandoor Oven Market
Food Service
Street Vendors Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
India Quick Service Restaurant Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Ship Catering Service Market
Food Service
Mobile Food Services Market
Food Service
Galley Equipment Market
Food Service
Tabletop Pizza Oven Market