
 Europe Online Grocery Delivery Market | 2026-2036
Europe Online Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Online Grocery Delivery Market Foresight
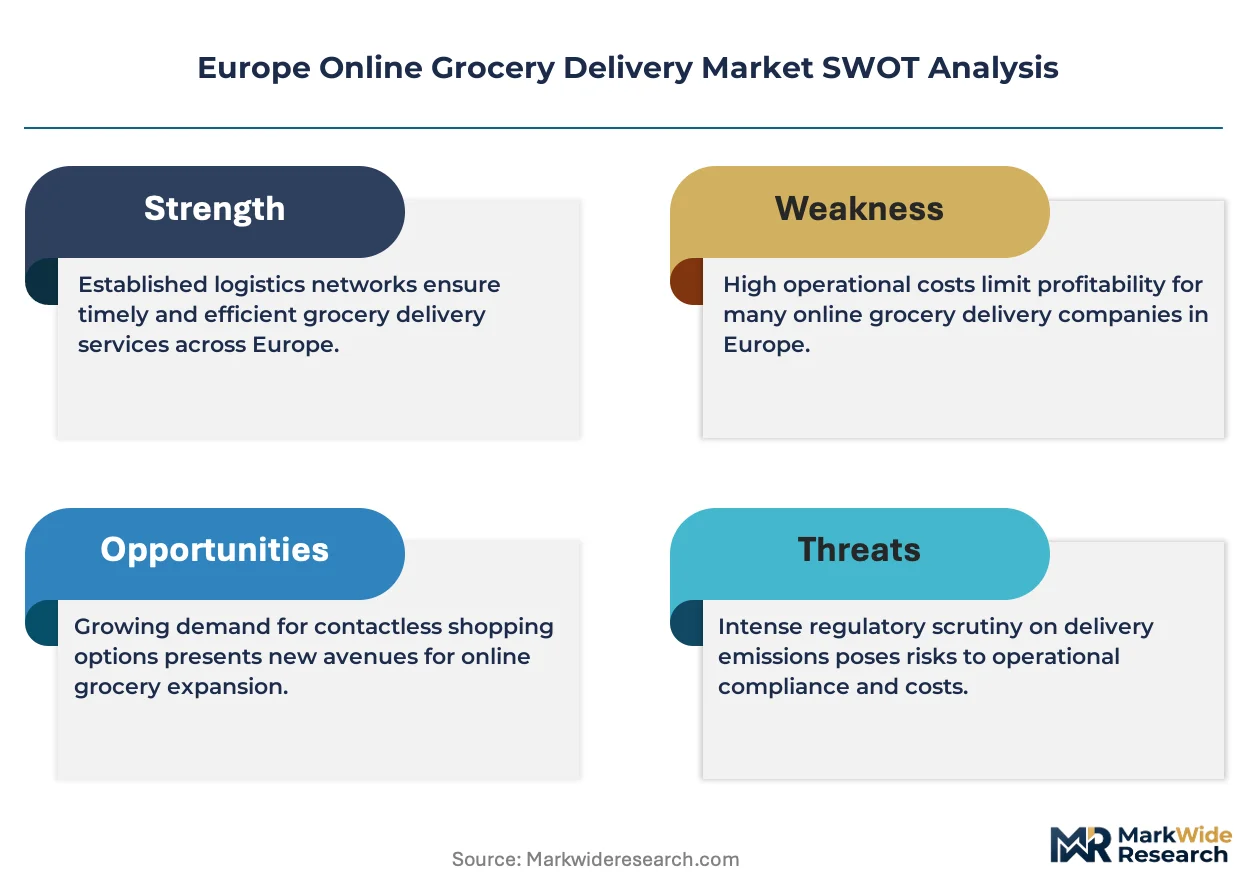
The EU Green Deal is expanding pressure on grocery delivery networks to decarbonize cold-chain logistics and eliminate single-use packaging. Ocado sustains leadership through proprietary automated warehouse technology that cuts fulfillment energy intensity. Tesco dominates British online grocery through dense store-based picking infrastructure. Flink competes via ultrafast dark-store models concentrated in German and Dutch cities.
Europe online grocery delivery denotes the digital ordering and physical distribution of food products from retailer to consumer, typically requiring temperature-controlled transport for fresh and frozen categories to preserve safety and quality. The primary commercial purpose centers on replacing or supplementing traditional store visits with convenient, time-definite fulfillment. Scheduled delivery anchors volume across suburban households planning weekly purchases, while on-demand delivery captures premium spend from urban consumers seeking immediate gratification. Subscription services deepen retention through recurring revenue structures that improve inventory predictability for operators.
The EU Green Deal and national packaging regulations in France and Germany mandate extended producer responsibility for delivery waste, forcing operators to redesign secondary packaging or face escalating compliance costs. ECHA substance restrictions and REACH chemical standards additionally govern sanitization protocols in automated fulfillment centers, elevating operational complexity. Stakeholders must weigh capital allocation between automation scale and regulatory adaptation as the primary strategic tension shaping sustainable returns.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing grocery delivery operators to redesign cold-chain logistics around reusable secondary packaging and electric last-mile fleets. This regulatory pressure intersects with urban household demand for scheduled delivery windows, creating capital allocation tension between automation scale and compliance adaptation.
Growth Catalysts
- Scheduled delivery adoption:German and French urban households are consolidating weekly purchases into pre-booked slots that improve inventory predictability for operators and reduce delivery cost per order through route density.
- EU Green Deal compliance:Extended producer responsibility mandates for delivery packaging waste are accelerating investment in returnable crate systems and electric vehicle fleets across metropolitan fulfillment networks.
- Dark-store proliferation:Ultrafast delivery models concentrated in Dutch and German city centers are compressing fulfillment times to under ten minutes through vertically integrated micro-fulfillment centers.
Market Restraints
- Energy cost volatility:Cold-chain refrigeration and electric fleet charging expose operators to wholesale electricity price swings that compress margin on temperature-controlled categories.
- Real estate concentration:Last-mile fulfillment sites in Paris, London, and Berlin command premium lease rates that limit dark-store expansion economics outside dense urban cores.
- Substitution from convenience retail:Rapidly expanded urban convenience store networks in France and Germany capture immediate-consumption demand that undercuts on-demand delivery frequency.
Strategic Opportunities
- Rural and semi-urban penetration:Scheduled delivery services remain underdeveloped in French regions outside Île-de-France and German states beyond North Rhine-Westphalia, offering expansion white space.
- Subscription model convergence:Recurring revenue structures combining grocery bundles with meal-kit components are deepening retention among dual-income households in Benelux markets.
- CSRD reporting alignment:Corporate sustainability reporting directives create procurement preference for grocery delivery operators with verified carbon accounting across Scope 3 emissions.
Industry Challenges
- Temperature-controlled logistics talent:Shortages of certified cold-chain technicians and electric vehicle fleet managers constrain operational scaling in automated fulfillment centers.
- Legacy system integration:Established retailers face friction connecting proprietary warehouse management systems with third-party delivery platform APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Online Grocery Delivery Market |
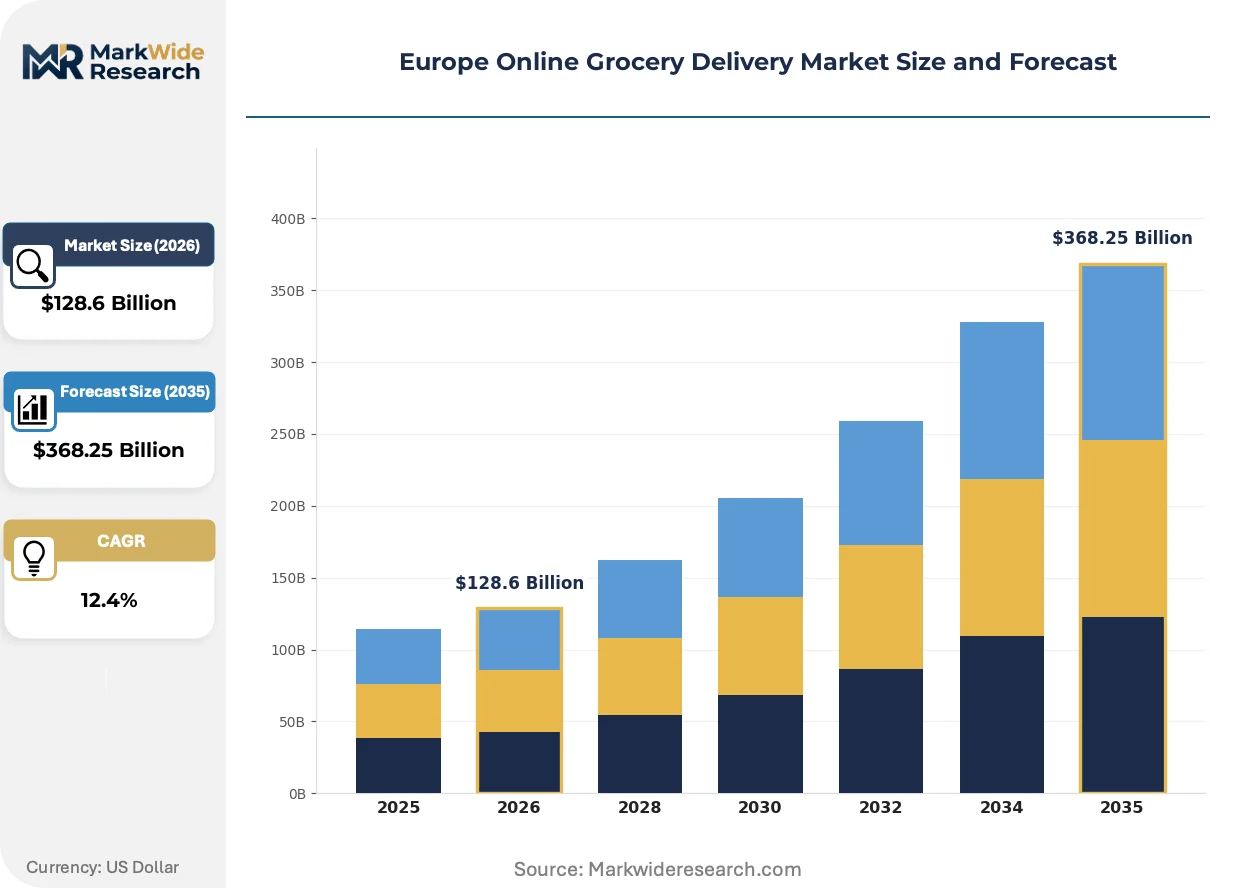
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $368.25 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Produce, Packaged Goods, Frozen Foods, Beverages Delivery Model: Scheduled Delivery, On-Demand Delivery, Subscription Services, Click and Collect End User: Households, Restaurants, Cafés, Catering Services Payment Method: Credit Card, Digital Wallets, Cash on Delivery, Bank Transfer |
| Companies Covered | Ocado, Just Eat Takeaway.com, Tesco, Uber Eats, Flink, Carrefour, Delivery Hero, REWE, Ahold Delhaize, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Online Grocery Delivery Market Shifts & Advancements
Automated fulfillment technology and regulatory packaging mandates are restructuring competitive economics around energy intensity and waste elimination. Operators are racing to deploy robotics and electric fleets ahead of compliance deadlines.
Automated warehouse robotics is consolidating fulfillment labor costs and energy intensity in large-scale grocery distribution. Ocado and established European retailers are deploying proprietary robotic picking systems that reduce per-order handling time and refrigeration exposure. This technology is consolidating market share toward operators with capital depth to own automated infrastructure rather than outsource fulfillment.
REACH chemical standards and ECHA substance restrictions are elevating sanitization protocol complexity in automated fulfillment centers. Operators must validate cleaning agents against evolving prohibited substance lists, adding operational compliance overhead. Fresh and prepared food categories face the strictest validation timelines, slowing rollout of dark-store formats handling ready-to-eat products.
Urban households are compressing purchase planning cycles from weekly to bi-weekly through subscription bundling and meal-kit integration. Traditional supermarket weekly shops are fragmenting into smaller, more frequent scheduled deliveries combined with prepared meal components. This pattern is most visible in metropolitan France and the Netherlands where dual-income density supports premium convenience spend.
Europe Online Grocery Delivery Market Segmentation
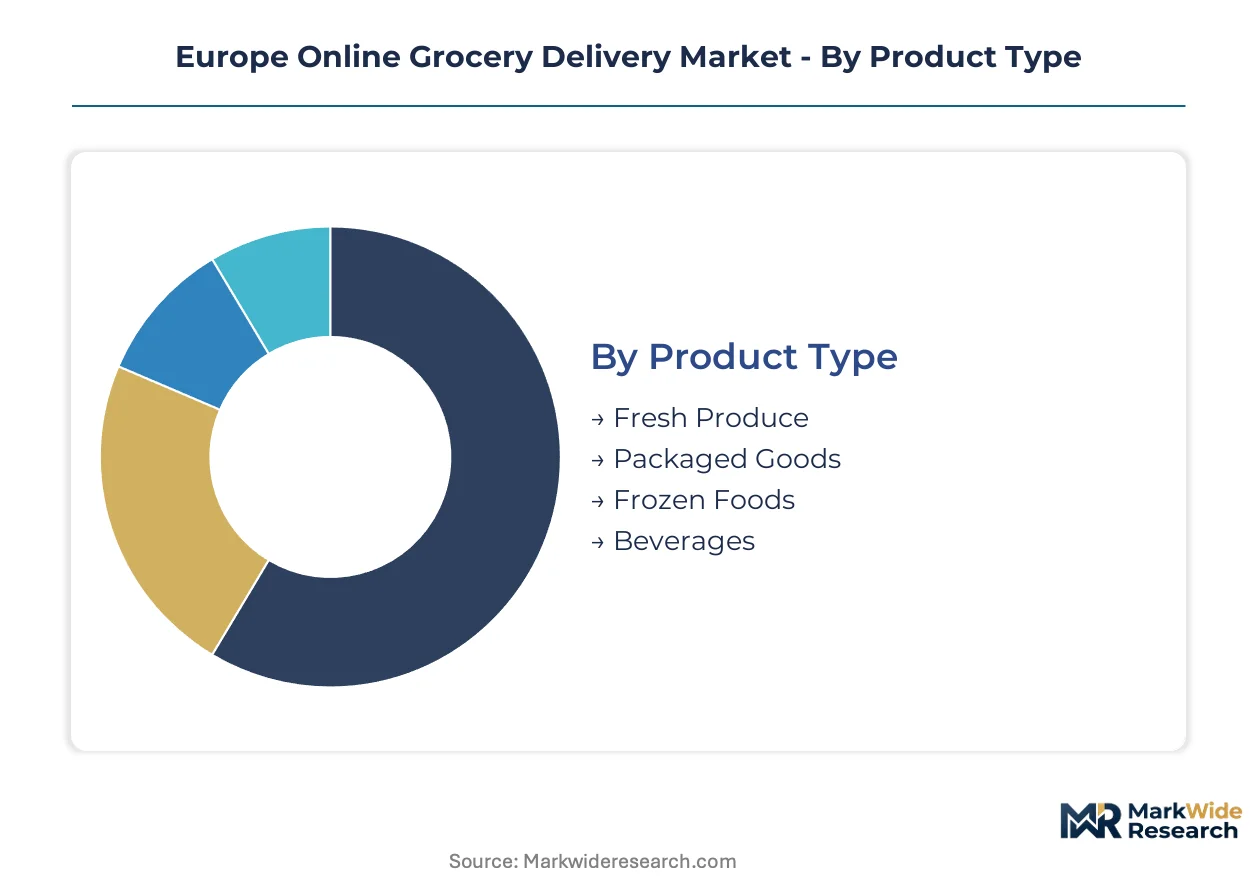
Segmentation in Europe online grocery delivery reveals divergent logistics economics and regulatory exposure across product categories and fulfillment modes. Temperature sensitivity, delivery velocity requirements, and payment infrastructure maturity each reshape capital allocation priorities for operators targeting distinct buyer profiles.
Product Type:
Buyer priority shifts between meal-planning convenience and immediate consumption needs determine category mix and fulfillment infrastructure investment.
- Fresh Produce:Temperature-controlled handling from farm gate to doorstep preserves shelf life and safety compliance under EFSA cold-chain guidelines. Demand concentrates in metropolitan France and the Netherlands where dense urban corridors support sub-two-hour scheduled windows for perishable quality assurance.
- Packaged Goods:Ambient storage requirements reduce fulfillment complexity and enable centralized automated warehouse economics. German suburban households drive volume through consolidated weekly orders that maximize route density and minimize per-unit delivery cost.
- Frozen Foods:Specialized insulated packaging and continuous refrigeration mandate dedicated fleet allocation or compartmentalized vehicles. Benelux markets show concentrated adoption where dual-income households prioritize convenience over price sensitivity.
- Beverages:High weight-to-value ratio creates unique last-mile cost challenges that subscription bundling addresses through predictable demand patterns.
Volume sits with Packaged Goods; growth tilts toward Fresh Produce.
Delivery Model:
Capital intensity and labor structure vary dramatically across fulfillment velocity tiers, with automation feasibility and real estate requirements driving operator specialization.
- Scheduled Delivery:Pre-booked windows enable batch picking, route optimization, and inventory predictability that compresses unit economics. French and German urban households anchor adoption through weekly planning habits that align with traditional supermarket replacement behavior.
- On-Demand Delivery:Sub-30-minute fulfillment demands dark-store proximity and real-time inventory synchronization that elevates operational complexity. Dutch and German city centers host the densest network of micro-fulfillment sites supporting this model.
- Subscription Services:Recurring revenue structures improve demand forecasting accuracy and reduce customer acquisition cost through retention lock-in.
- Click and Collect:Store-based fulfillment eliminates last-mile variable cost while requiring robust inventory integration between online and physical channels.
Revenue concentrates in Scheduled Delivery; On-Demand Delivery is climbing the fastest as urban density supports ultrafast infrastructure economics.
End User:
Order size, frequency, and product mix diverge sharply between household consumption and foodservice procurement, reshaping platform design and supplier relationships.
- Households:Fragmented demand across product categories requires broad assortment depth and flexible delivery windows that accommodate varying weekly schedules. Metropolitan France and the Netherlands show highest penetration among dual-income families seeking time savings.
- Restaurants:Bulk purchasing patterns and early-morning delivery requirements favor dedicated B2B platforms with negotiated contract pricing and consistent supply reliability.
- Cafés:Smaller order quantities than restaurants but similar velocity needs concentrate demand in urban commercial districts.
- Catering Services:Event-driven demand spikes create capacity planning challenges that scheduled delivery models address poorly.
Transaction volume favors Households; margin expansion tilts toward Restaurants through contract structures and predictable demand patterns.
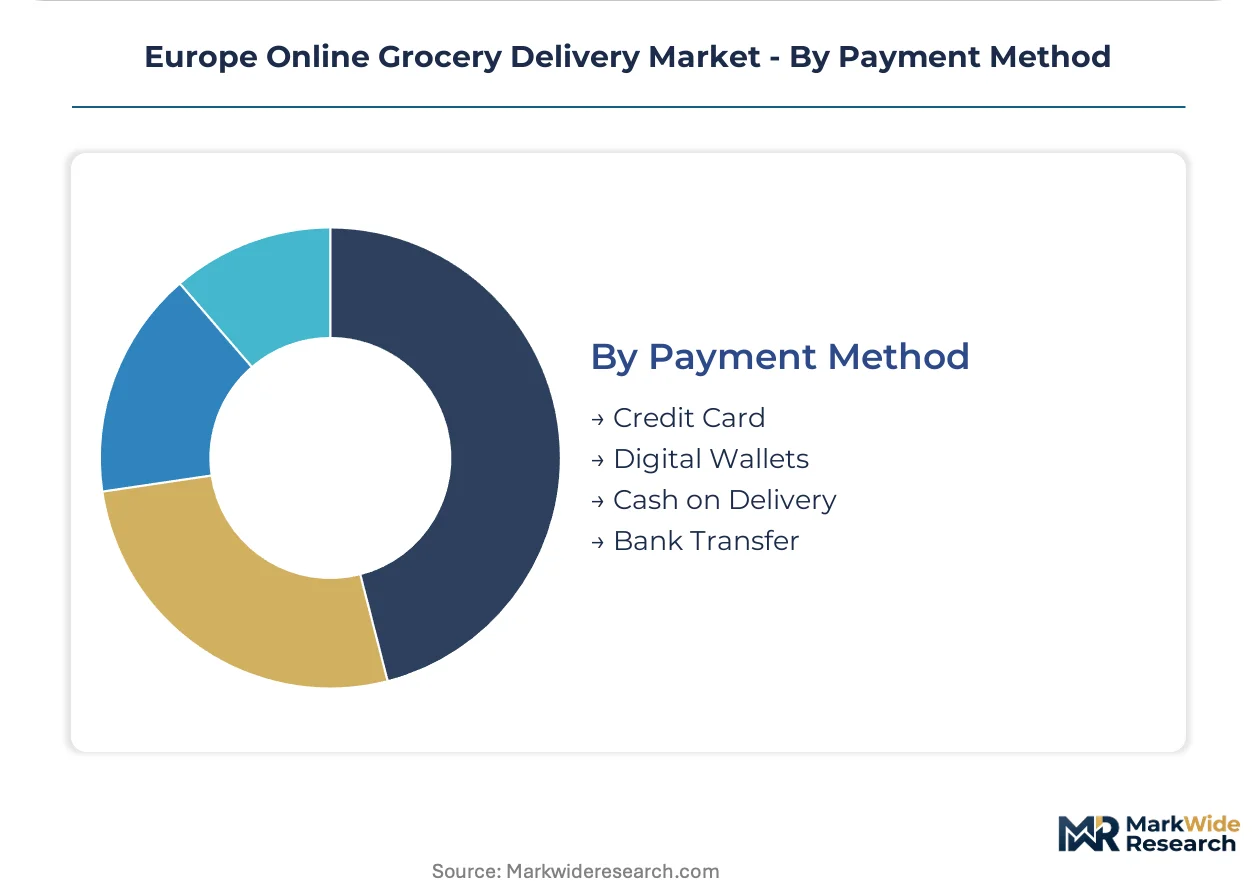
Payment Method:
Trust infrastructure and regulatory compliance around financial data shape platform technology investment and market entry sequencing across European jurisdictions.
- Credit Card:Mature fraud protection and chargeback mechanisms dominate in established markets with high banking penetration. German and French consumers show strongest preference for card-based recurring payments that enable subscription service enrollment.
- Digital Wallets:Accelerating adoption among younger demographics and mobile-first users reduces checkout friction and supports impulse-driven on-demand purchases.
- Cash on Delivery:Persistent demand in Southern European markets with lower card penetration and higher trust barriers to digital payment adoption.
- Bank Transfer:SEPA infrastructure enables low-cost settlement preferred by price-sensitive buyers in Benelux and German markets for large scheduled orders.
Transaction share rests with Credit Card; Digital Wallets are gaining share fastest as mobile-native purchasing expands across urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors European online grocery density through the Île-de-France corridor, where dual-income households and compact urban geography sustain sub-two-hour scheduled delivery economics. Metropolitan France generates disproportionate transaction volume relative to its population share.
Germany
North Rhine-Westphalia and Berlin-Brandenburg concentrate dark-store infrastructure for ultrafast delivery, with REWE and Flink operating dense micro-fulfillment networks. The EU Green Deal's extended producer responsibility mandates accelerate electric fleet deployment across German metropolitan logistics. Hamburg and Munich host the most advanced automated warehouse pilots outside the UK.
France
Scheduled delivery adoption concentrates in Île-de-France and Provence-Alpes-Côte d'Azur, where Carrefour leverages hypermarket-based picking for suburban coverage. ANSM and EFSA cold-chain guidelines enforce strict temperature validation protocols for fresh produce fulfillment. Lyon and Marseille represent the fastest-scaling secondary markets for subscription grocery services.
United Kingdom
Tesco's store-based picking infrastructure dominates British online grocery through dense suburban coverage anchored by London and the Southeast. Ocado's proprietary automated warehouses in Hatfield and Erith consolidate fulfillment energy intensity leadership. The Competition and Markets Authority scrutinizes platform consolidation, shaping partnership strategies among mid-tier retailers.
Netherlands
Ahold Delhaize and Flink compete intensely across the Randstad corridor, where Amsterdam-Rotterdam-Utrecht density supports sub-ten-minute delivery economics. The Dutch climate agreement accelerates zero-emission zone mandates for urban logistics, forcing fleet electrification timelines. Eindhoven and Utrecht emerge as secondary dark-store expansion targets.
Spain
Madrid and Barcelona concentrate on-demand delivery adoption, though scheduled grocery remains underdeveloped relative to Northern Europe. Delivery Hero and local platforms capture urban convenience demand through restaurant-to-grocery cross-selling. Spanish packaging regulations lag EU Green Deal implementation, creating compliance preparation gaps for multinational operators.
Europe Online Grocery Delivery Market Competitive Landscape
The competitive structure tilts toward automated fulfillment specialists and ultrafast dark-store operators. Market concentration remains moderate, with distinct regional champions rather than continental dominance. Three archetypes define positioning: proprietary technology owners, store-based fulfillment networks, and vertically integrated rapid delivery platforms. Competitive moves center on warehouse automation licensing partnerships and geographic expansion through acquisition rather than organic buildout.
Within the technology-centric tier, Ocado represents automated fulfillment specialization through proprietary robotics and software licensing. Among diversified retail conglomerates, Tesco and Carrefour exemplify store-based picking models that leverage existing hypermarket infrastructure. At the rapid-delivery vector, Flink and Delivery Hero occupy positions defined by dark-store density and urban logistics velocity. These three groupings illustrate divergent capital allocation priorities between automation scale, real estate breadth, and last-mile speed.
| Leading Market Players |
|---|
| Ocado |
| Just Eat Takeaway.com |
| Tesco |
| Uber Eats |
| Flink |
| Carrefour |
| Delivery Hero |
| REWE |
| Ahold Delhaize |
| Others |
Supply & Pricing Matrix
Cold-chain energy costs cascade from wholesale electricity markets through fulfillment tiers, compressing margins on temperature-controlled categories while amplifying price stratification between automated warehouse operators and store-based pickers. EU Green Deal compliance investments in electric fleets and returnable packaging systems feed into subscription pricing premiums that urban households absorb for sustainability-aligned service tiers.
Pricing Analysis
Throughput-based fulfillment fees anchor pricing structures, with operators charging per-order handling rates that scale with delivery velocity and temperature sensitivity. Three-tier pricing structure across premium, standard, and economy levels separates ultrafast on-demand delivery from scheduled window slots and click-and-collect options. Pricing pressure stems from energy cost volatility in refrigerated logistics and real estate premiums for dark-store locations. Price-sensitive suburban households in Germany favor economy scheduled slots, while least-sensitive urban dual-income buyers in the Netherlands absorb premium on-demand rates.
Supply Chain Analysis
Returnable crate flows and reverse logistics for reusable packaging reshape cold-chain fulfillment economics under EU Green Deal extended producer responsibility mandates. Automated warehouse equipment concentrates manufacturing in Germany, the Netherlands, and the United Kingdom, with specialized refrigeration components sourcing from Denmark and Italy. Supply chain risk centers on single-source vulnerability for proprietary robotic picking systems. Distribution runs through metropolitan micro-fulfillment nodes that compress last-mile radius to under three kilometers in dense urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated warehouse robotics is displacing store-based picking infrastructure as the dominant fulfillment technology, forcing capital reallocation toward proprietary systems and licensed technology partnerships. This transition phase rewards operators with capital depth and penalizes legacy-dependent competitors.
For Market Incumbents:Acquire automated fulfillment technology assets to defend against dark-store entrants eroding suburban scheduled delivery share. Prioritize licensing partnerships with robotics specialists over in-house development timelines. Channel control through exclusive supplier agreements for temperature-controlled packaging materials protects margin from EU Green Deal compliance cost spikes.
For New Entrants and Emerging Players:Begin with rural and semi-urban scheduled delivery corridors in French regions outside Île-de-France where incumbent coverage remains thin. White-space penetration in German states beyond North Rhine-Westphalia offers lower competitive intensity than saturated metropolitan cores. Meal-kit subscription bundling provides a differentiated go-to-market angle that deepens retention against transactional competitors.
For Investors and Strategic Acquirers:CSRD-aligned carbon accounting verification is the leading indicator that grocery delivery operators will secure enterprise procurement contracts and sustainability-linked financing advantages. Long-term viability favors vertically integrated platforms owning fulfillment infrastructure rather than asset-light marketplace models. Monitor electric fleet deployment timelines and automated warehouse commissioning announcements as inflection signals for operational scale readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Deployment | Ocado's proprietary robotics cuts fulfillment energy intensity and labor cost per order. |
| Electric Fleet Transition | EU Green Deal mandates accelerate zero-emission last-mile logistics in Amsterdam and Berlin. |
| Subscription Model Convergence | Meal-kit bundling deepens retention among dual-income households in Benelux markets. |
| Dark-Store Network Expansion | Flink's micro-fulfillment density compresses delivery times below ten minutes in Dutch cities. |
| CSRD Reporting Alignment | Verified Scope 3 carbon accounting creates procurement preference for enterprise grocery contracts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe online grocery delivery market assessment. Primary interviews with fulfillment operations directors, cold-chain logistics managers, grocery category buyers, and last-mile fleet planners combined with EFSA guidance documents, EU Green Deal implementation reports, and national packaging regulator filings. Bottom-up order volume modeling triangulated against top-down retail e-commerce penetration benchmarks.
Granularity-level modeling distinguished scheduled delivery, on-demand delivery, subscription services, and click-and-collect fulfillment modes at the metropolitan area level across the analysis window. Product type segmentation captured fresh produce, packaged goods, frozen foods, and beverages with distinct temperature handling requirements. CAGRs derived from logistic curve adoption modeling applied to household penetration rates and order frequency trends. Forecast inputs incorporated EU Green Deal compliance timelines and automated warehouse commissioning schedules.
Underlying measurement precision varies by segment; on-demand delivery volumes carry tighter precision than nascent subscription services due to platform disclosure practices. Forecasts reflect assumptions about electric fleet deployment rates and reusable packaging return-loop efficiency that regulatory enforcement or technology performance could revise. Practitioners should monitor ANSM cold-chain inspection outcomes and ECHA substance restriction updates for early signals of compliance cost trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Inflight Catering Market
Food Service
GCC Online Grocery Market
Food Service
Beverage Napkins Market
Food Service
United Arab Emirates Foodservice Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Peer-To-Peer Dining Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
US Food Trucks Services Market
Food Service
Quick-Service Restaurants Market
Food Service
Onboard Rail Catering Market
Food Service
Saudi Arabia Foodservice Market
Food Service
Asia Pacific Airline Catering Services Market
Food Service
Commercial Tandoor Oven Market
Food Service
Global Digital Food Delivery Market