
 Germany Smokeless Indoor Grills Market | 2026-2036
Germany Smokeless Indoor Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Smokeless Indoor Grills Market Insights
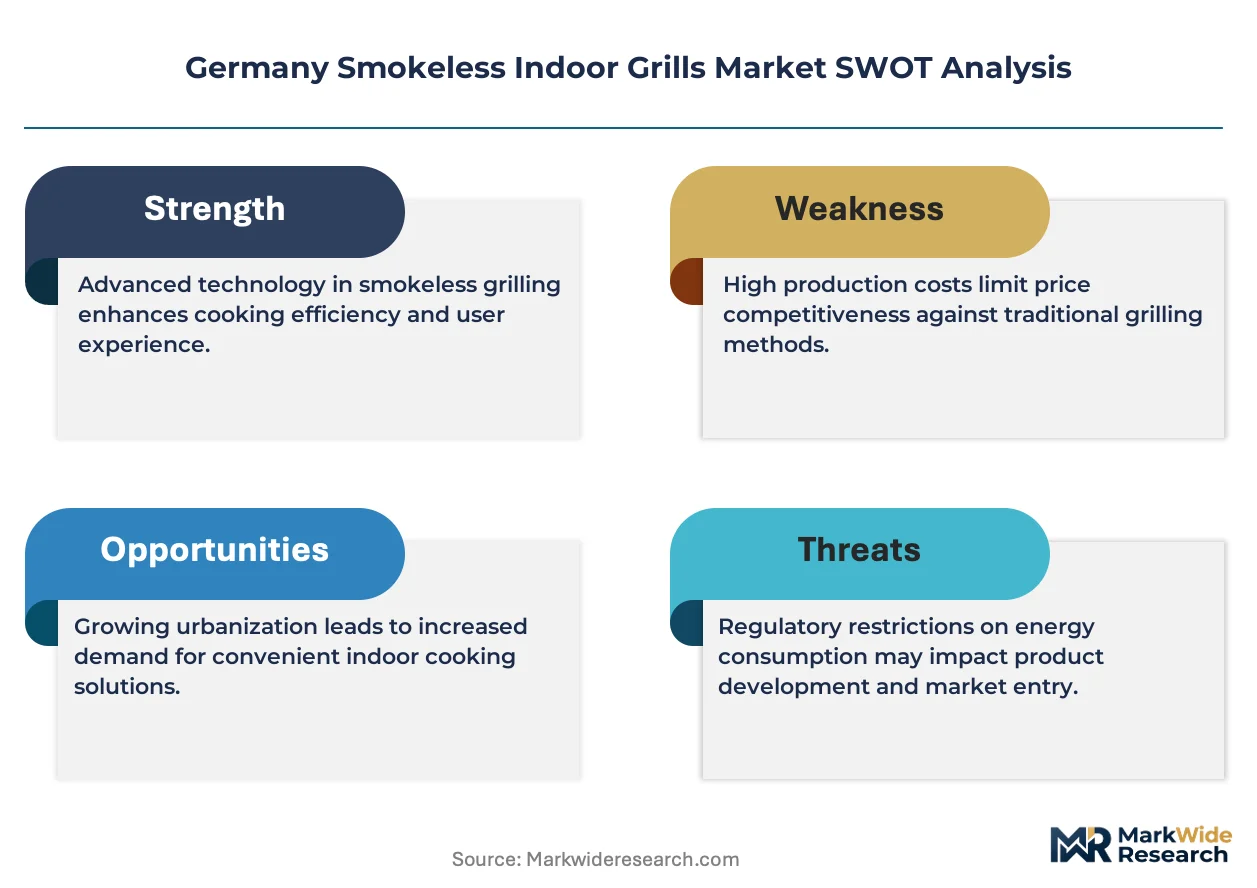
Asset-light leasing models for premium kitchen appliances is narrowing the competitive field to firms with strong balance sheets and direct-to-consumer logistics. Weber-Stephen Products LLC leverages its established German retail partnerships to sustain showroom visibility. Traeger Grills anchors its position through pellet-system specialization that differentiates it from conventional electric competitors. Lotus Grills competes via compact ceramic designs optimized for space-constrained urban kitchens.
Germany smokeless indoor grills are enclosed electric or infrared cooking appliances with integrated grease-capture systems and activated-carbon filtration, typically operating at temperatures between 200°C and 300°C to replicate searing performance without open flames or smoke emission. Their primary commercial purpose is to enable grilling in residential and food-service environments where ventilation infrastructure is limited or fire codes prohibit traditional charcoal or gas combustion. Electric grills dominate unit sales among households seeking plug-and-play convenience, while infrared variants command margin pools in restaurant and café segments where speed and surface temperature consistency matter. Compact sizing leads volume in single-person and couple households across dense German cities, whereas large-format units find traction in food trucks requiring high-throughput output within confined mobile kitchens.
Germany's Federal Emission Control Ordinance (BlmSchV) and the EU Ecodesign Directive shape product compliance requirements, forcing manufacturers to document particulate filtration efficiency and standby power consumption before market entry. The Federal Institute for Risk Assessment (BfR) and REACH regulations govern non-stick coating chemistries, restricting certain perfluorinated substances in food-contact surfaces. Stakeholders must monitor pending amendments to the EU F-Gas Regulation that could affect refrigerant-based cooling systems in premium grill models with integrated temperature zones.
Market Dynamics
Germany's revised BlmSchV emissions standards are compressing the competitive field toward manufacturers with capital reserves for filtration R&D and certification documentation. This regulatory pressure is accelerating technical differentiation while squeezing marginal players from distribution channels.
Growth Catalysts
- BlmSchV filtration mandates:Upgraded particulate capture requirements force replacement cycles in older electric grill inventories across Berlin and Munich apartment stock.
- Urban balcony restrictions:Southern German metropolitan enforcement of open-flame prohibitions redirects grilling demand toward certified indoor alternatives.
- Infrared searing technology:Restaurant and café segments adopt high-temperature electric units to replicate charcoal surface performance without ventilation infrastructure.
Market Restraints
- Activated carbon input volatility:Filtration media supply concentrates in East Asian manufacturing clusters, exposing German assemblers to freight cost swings and customs delays.
- REACH coating compliance:BfR restrictions on perfluorinated substances in non-stick surfaces extend product development timelines and limit supplier pools for food-contact materials.
- Outdoor grill substitution:Traditional charcoal and gas equipment retains price advantage in rural German regions with fewer combustion restrictions.
Strategic Opportunities
- Food truck mobility segment:Compact high-output electric grills address ventilation constraints in mobile kitchen configurations across Hamburg and Cologne street-vendor permits.
- EU F-Gas Regulation amendments:Pending cooling-system standards for premium multi-zone grills create first-mover advantage for refrigerant-compliant engineering.
- Appliance leasing channels:Asset-light subscription models for premium kitchen equipment penetrate credit-constrained younger households in Frankfurt and Stuttgart.
Industry Challenges
- Electrical certification timelines:VDE and TÜV testing protocols for high-wattage heating elements extend product launch windows beyond seasonal demand peaks.
- Cross-border component traceability:REACH documentation requirements for imported ceramics and heating coils complicate supply chain reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Smokeless Indoor Grills Market |
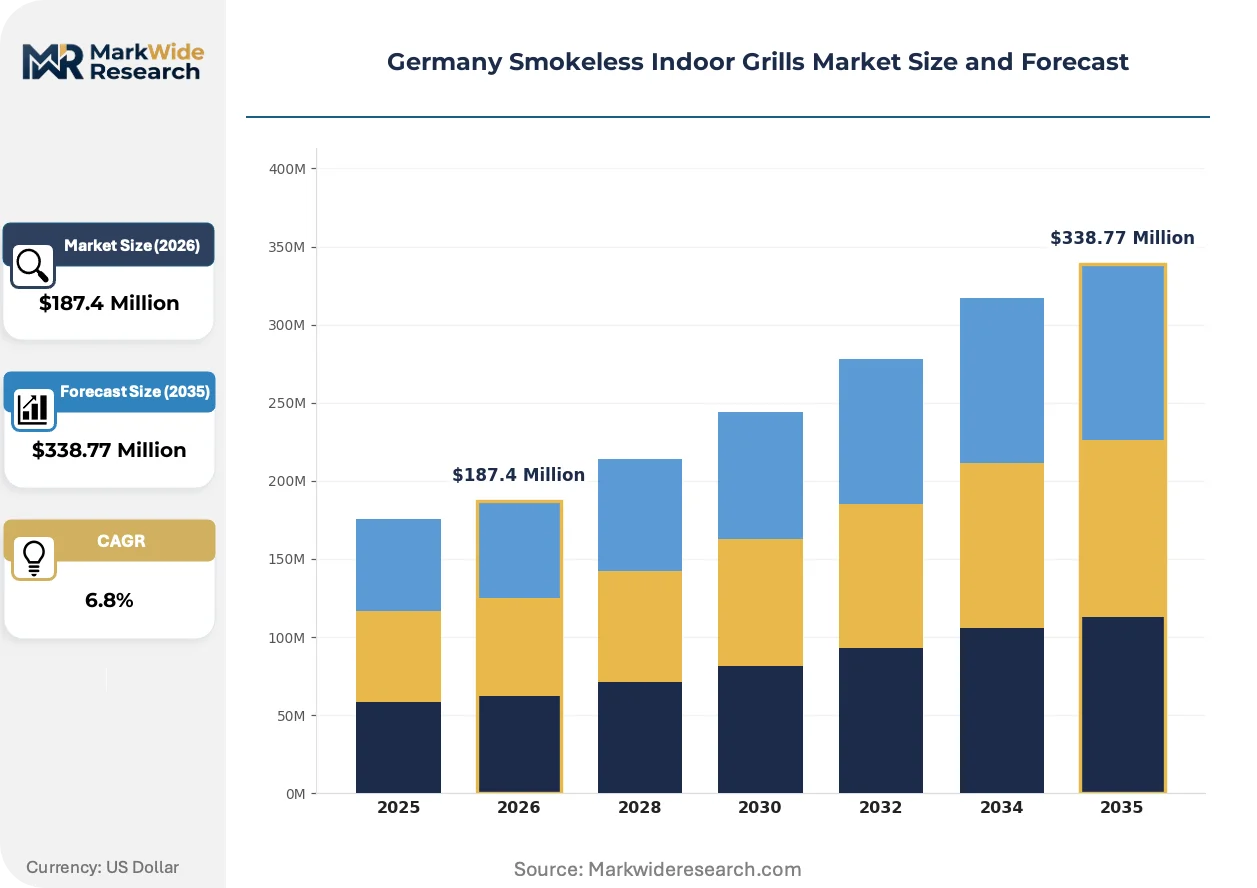
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Grills, Infrared Grills, Charcoal Grills, Portable Grills End User: Households, Restaurants, Cafés, Food Trucks Material: Stainless Steel, Aluminum, Ceramic, Non-stick Coating Size: Compact, Medium, Large, Extra Large |
| Companies Covered | Weber-Stephen Products LLC, Traeger Grills, Pit Boss Grills, Rosle, Lotus Grills, The Middle by Corporation, Landmann, Napoleon, Breville, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Smokeless Indoor Grills Market Trends and Innovations
Product development in Germany's smokeless grill segment is pivoting toward convergent heating architectures and regulatory pre-certification. Manufacturers are racing to embed compliance documentation into design phases rather than retrofitting for approval.
Ceramic-infrared composite heating elements are hybridizing thermal delivery across electric and infrared modes. Single-person households in dense Munich districts adopt these dual-mode units for space-constrained kitchens. This convergence is compressing the distinction between residential convenience models and commercial-grade searing performance.
The EU Ecodesign Directive's standby power thresholds are forcing firmware and insulation redesigns before market entry. German manufacturers must document wattage draw below one-watt thresholds to secure CE marking. Premium segment producers with integrated cooling zones face the steepest re-engineering costs under these standby mandates.
Younger households are bypassing traditional retail showrooms for direct-to-manufacturer digital channels. This disintermediation concentrates margin with brands owning logistics networks rather than distributors. Berlin's rental-heavy population exhibits the sharpest channel shift, prioritizing delivery speed and return flexibility over in-person demonstration.
Germany Smokeless Indoor Grills Market Segmentation
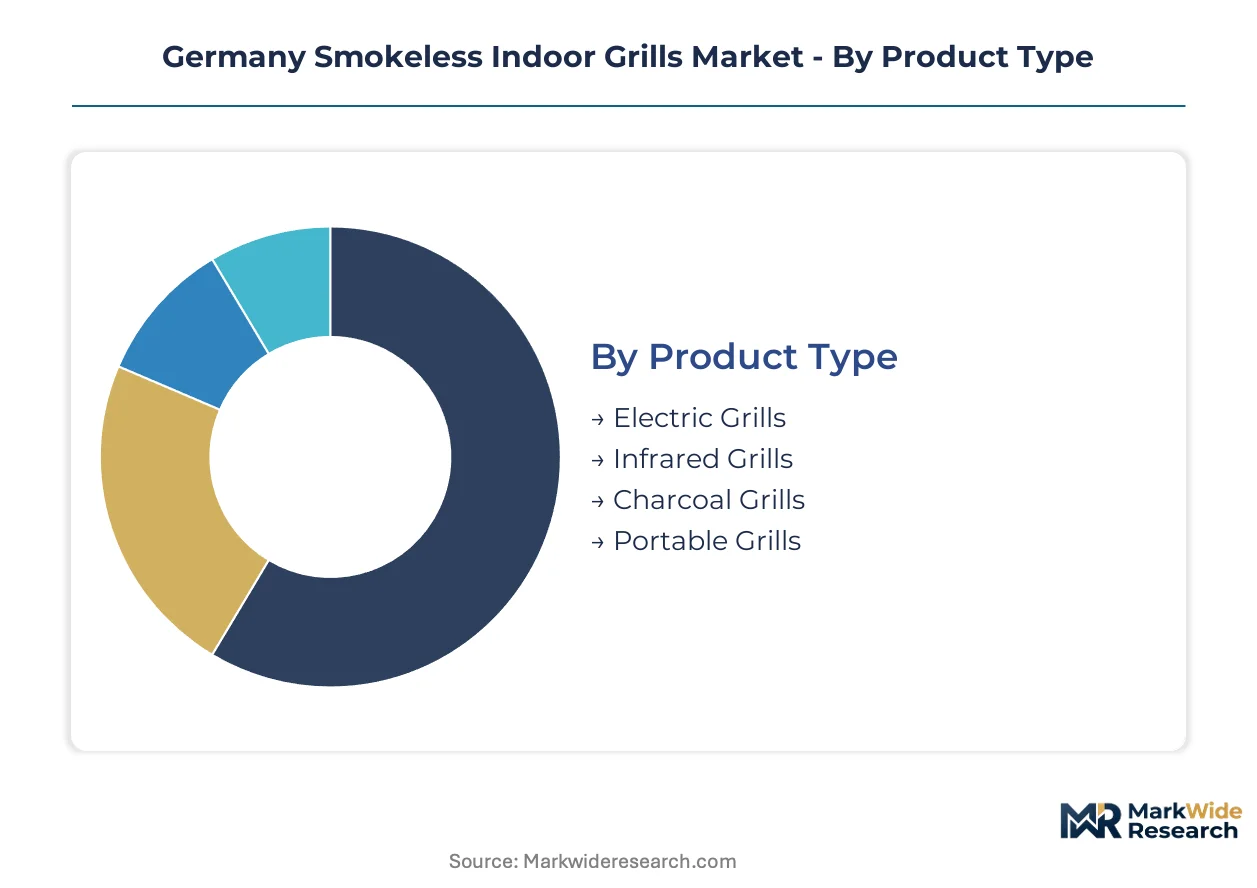
Germany's smokeless indoor grill market fragments across four structural dimensions that determine service intensity, margin capture, and channel strategy. Product type and end-user splits drive divergent warranty and replacement part economics, while material and size configurations shape logistics complexity and retail shelf economics.
Product Type:
After-sales service intensity varies sharply across heating architectures, with infrared systems demanding specialized technician networks that electric units rarely require.
- Electric Grills:Resistive coil or cast-iron plate heating elements operating at standardized wattages between 1,500W and 2,500W dominate Berlin and Munich apartment installations. Plug-and-play simplicity minimizes service calls, though heating element replacement cycles concentrate demand in rental-heavy districts where tenant turnover accelerates wear.
- Infrared Grills:Quartz or ceramic radiant elements achieve surface temperatures exceeding 300°C for searing performance that replicates charcoal crust formation. Restaurant procurement in Hamburg and Cologne drives adoption, where ventilation constraints block open-flame alternatives and speed-of-service requirements favor rapid preheat cycles.
- Charcoal Grills:Enclosed combustion designs with active filtration for indoor-safe operation occupy a narrow compliance-driven niche. Bavarian municipalities with strictest balcony enforcement generate residual demand from consumers unwilling to abandon charcoal flavor profiles entirely.
- Portable Grills:Battery or low-wattage electric configurations under 1,000W serve camping and temporary kitchen setups. Seasonal sales concentration in Black Forest and Alpine tourism corridors creates inventory management challenges for retailers.
By volume, Electric Grills lead. By growth pace, Infrared Grills are gaining share fastest as food-service procurement shifts toward high-temperature electric alternatives.
End User:
Cost tier stratification separates household price sensitivity from commercial durability requirements, with food trucks occupying a hybrid position demanding both mobility and throughput.
- Households:Single-person and couple households in Frankfurt and Stuttgart dense districts prioritize compact footprints and dishwasher-safe components. Subscription leasing penetration concentrates among credit-constrained younger demographics in rental markets.
- Restaurants:Full-service establishments in Berlin's Kreuzberg and Neukölln districts deploy large-format infrared units for menu items requiring char marks without exhaust hood investment. BlmSchV compliance documentation becomes a procurement gate.
- Cafés:Limited-menu operations favor medium-size electric grills for panini and grilled vegetable preparation. Countertop space constraints in historic building conversions drive compact specification.
- Food Trucks:Mobile kitchen configurations in Hamburg street-vendor permits demand high-output electric grills within confined footprints. Generator capacity limits and ventilation restrictions create specification ceilings that stationary kitchens rarely face.
Households generate the highest unit volumes. Food Trucks are climbing the fastest as municipal permitting tightens on combustion-based mobile food operations.
Material:
Margin pools concentrate in ceramic and advanced coating segments where REACH compliance documentation extends development timelines and limits supplier competition.
- Stainless Steel:304 and 430 grade cooking surfaces dominate commercial installations for durability and thermal mass retention. Food-service procurement in Cologne and Düsseldorf favors welded-seam construction for hygiene audit compliance.
- Aluminum:Die-cast alloy bases reduce unit weight for portable and compact residential models. Anodized surface treatments address BfR food-contact requirements without perfluorinated chemistry.
- Ceramic:Infrared-emitting honeycomb structures achieve radiant efficiency above 90% in premium residential and commercial units. Manufacturing concentration in East Asian supply clusters exposes German assemblers to freight cost volatility and customs documentation delays.
- Non-stick Coating:Ceramic-reinforced PTFE alternatives and sol-gel ceramic layers replace restricted perfluorinated substances under REACH Annex XVII. Extended product development timelines for coating qualification compress launch windows relative to uncoated alternatives.
Stainless Steel commands the largest volume position. Ceramic is expanding most quickly as infrared technology penetrates premium residential and food-service segments.
Size:
Geography of demand correlates directly with urban density gradients, with compact units dominating core cities and large formats penetrating peripheral commercial zones.
- Compact:Cooking surfaces under 30cm width target single-person households in Munich's Altstadt-Lehel and Berlin's Prenzlauer Berg micro-apartments. Shelf-space efficiency drives retail placement in electronics and general merchandise channels rather than dedicated kitchen showrooms.
- Medium:30-45cm width configurations serve couple households and small cafés with moderate throughput requirements. This tier captures the broadest price-point distribution across mass-market retail.
- Large:45-60cm surfaces address family households and restaurant line-cooking stations. Warehouse club and commercial equipment distributors dominate this channel.
- Extra Large:Multi-zone configurations exceeding 60cm width with independent temperature control serve high-volume food trucks and catering operations. Integrated cooling zones face pending EU F-Gas Regulation compliance costs that smaller formats avoid.
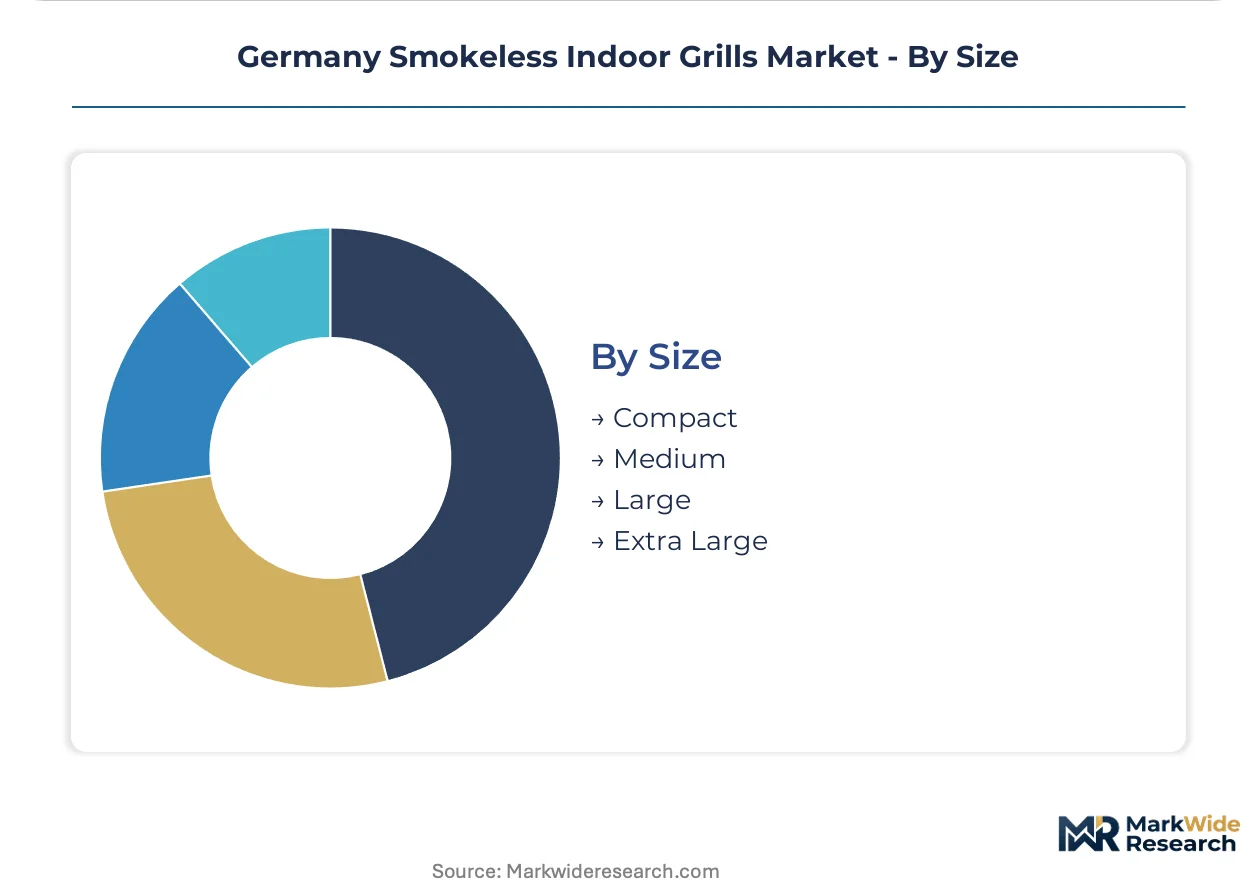
Compact sizes lead by unit volume. Extra Large configurations show the steepest expansion trajectory as food-service operators seek consolidated equipment footprints for mobile and small-format kitchens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers of smokeless indoor grills maintain a modest export surplus concentrated in premium infrared units destined for neighboring EU markets, while importing ceramic heating elements and activated carbon filtration media primarily from East Asian supply clusters.
Bavaria
Munich's dense Altstadt-Lehel district generates concentrated demand for compact electric grills among single-person rental households. The state's implementation of strictest-in-Germany balcony combustion ordinances redirects traditional grilling demand toward certified indoor alternatives. Ingolstadt's automotive supplier ecosystem is repurposing thermal engineering expertise toward ceramic-infrared heating component development.
North Rhine-Westphalia
Cologne and Düsseldorf food-service procurement drives adoption of large-format infrared units for restaurant line-cooking without exhaust hood investment. The region's commercial equipment distributors dominate warehouse club channels for extra-large multi-zone configurations. REACH compliance documentation requirements from ECHA extend coating qualification timelines for Solingen-based stainless steel fabricators.
Baden-Württemberg
Stuttgart's rental-heavy younger demographics exhibit the sharpest shift toward direct-to-manufacturer digital channels and subscription leasing models. The state's precision manufacturing base supplies welded-seam stainless steel construction for hygiene-audit-compliant commercial installations. Freiburg's university hospital procurement is piloting smokeless grill units for patient nutrition services under BfR food-contact guidelines.
Berlin-Brandenburg
Kreuzberg and Neukölln restaurant clusters deploy medium-format electric grills for panini and grilled vegetable preparation in historic building conversions with ventilation constraints. The capital's electronics retail density drives shelf-space competition for compact units in general merchandise channels. Potsdam's film studio catering operations are standardizing on portable low-wattage configurations for location shooting.
Hamburg
Street-vendor permitting in the port city's mobile food sector creates specification demand for high-output electric grills within confined generator-capacity limits. The food truck segment here is climbing fastest as municipal authorities tighten combustion-based mobile kitchen restrictions. Blankenese's waterfront residential towers enforce strictest building-level open-flame prohibitions, concentrating premium-unit demand.
Germany Smokeless Indoor Grills Market Competitive Landscape
On the supply side, the industry is consolidating toward manufacturers with capital reserves for filtration R&D and regulatory pre-certification documentation. Tiered competitive positioning separates premium infrared specialists from mass-market electric assemblers and portable-format niche players. Strategic archetypes include integrated heating-element developers, certification-focused compliance specialists, and direct-to-consumer logistics operators. Dominant competitive moves center on backward integration into ceramic component supply and geographic expansion through EU distribution partnerships.
Within the premium-tier vector, Weber-Stephen Products LLC and Traeger Grills occupy positions anchored by established retail partnerships and pellet-system specialization respectively. Lotus Grills exemplifies the compact-design archetype optimized for space-constrained urban kitchens. These three represent divergent strategic bets on heating architecture, distribution channel control, and form-factor miniaturization.
| Leading Market Players |
|---|
| Weber-Stephen Products LLC |
| Traeger Grills |
| Pit Boss Grills |
| Rosle |
| Lotus Grills |
| The Middle by Corporation |
| Landmann |
| Napoleon |
| Breville |
| Others |
Pricing and Supply Chain Analysis
East Asian ceramic honeycomb manufacturing clusters feed the premium infrared segment, anchoring margin capture in German assembly operations that bundle REACH-compliant coating documentation and BlmSchV certification. Pricing power concentrates downstream with brands controlling direct-to-consumer logistics and regulatory pre-approval workflows.
Pricing Analysis
Food-service procurement teams anchor contract-based long-term offtake for large-format infrared units, while households transact through per-unit retail channels. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade commercial equipment from compact residential convenience models. Cost compression in the portable segment intensifies as low-wattage electric configurations face commoditization from unbranded imports. Quick-service restaurants exhibit lowest price sensitivity due to ventilation constraint urgency; single-person rental households show highest sensitivity, driving subscription leasing penetration.
Supply Chain Analysis
EU dual-use export controls on advanced ceramic sintering technology limit technology transfer to competing manufacturing hubs, constraining supplier diversification. German assemblers draw ceramic heating elements from Japan and South Korea, activated carbon filtration media from China, and precision-wound resistive coils from Taiwan. Single-source vulnerability in East Asian ceramic supply exposes production schedules to freight cost volatility and customs documentation delays. Distribution runs through commercial equipment distributors for food-service segments, direct-to-manufacturer digital channels for younger urban households, and electronics retail for compact residential units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across German municipal balcony ordinances creates niche opportunities for compliance-specialized product variants, rewarding agile manufacturers with rapid certification turnaround.
For Market Incumbents: Pre-empt emerging infrared specialists by captive supply of ceramic honeycomb components through partnerships with Ingolstadt thermal engineering clusters. Accelerate VDE and TÜV pre-certification documentation to compress launch windows ahead of seasonal demand peaks. BlmSchV amendment cycles threaten margin pools for retrofit-dependent players; embed filtration R&D into design phases rather than reactive compliance. For New Entrants and Emerging Players: Northern German secondary cities exhibit underpenetration in subscription leasing channels relative to Berlin and Munich saturation. Target food truck mobility segments in Hamburg and Cologne where municipal permitting tightens fastest on combustion-based operations. Pursue direct-to-manufacturer digital-first go-to-market with return-flexibility guarantees that match rental-heavy demographic preferences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed appliance assemblers lacking backward integration into ceramic component supply. Five-to-ten-year viability hinges on regulatory pre-certification capabilities and direct logistics network ownership. Monitor EU F-Gas Regulation amendment timing as inflection indicator for premium multi-zone grill re-engineering cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Components | Captive supply of honeycomb heating elements insulates margin from East Asian freight volatility and customs delays. |
| Regulatory Pre-Certification Investment | Early VDE and TÜV documentation compresses product launch windows ahead of BlmSchV compliance deadlines. |
| Direct-to-Consumer Channel Expansion | Logistics network ownership concentrates margin with brands bypassing traditional kitchen equipment distributors. |
| Subscription Leasing Model Launch | Asset-light access penetrates credit-constrained younger demographics in Frankfurt and Stuttgart rental markets. |
| Food Truck Segment Specialization | High-output compact configurations address Hamburg and Cologne municipal permitting constraints on mobile combustion kitchens. |
Research Methodology
Operator-level perspectives from product development directors at heating element manufacturers, procurement leads at commercial food-service distributors, regulatory affairs specialists navigating REACH compliance, and category managers at electronics retail chains anchored the qualitative base. Secondary validation drew from BfR food-contact guidelines, BlmSchV amendment drafts, ECHA REACH Annex XVII updates, and customs records of ceramic component imports. Bottom-up unit economics triangulated against top-down market sizing across household, restaurant, café, and food truck end-use segments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across heating architecture, end-use durability requirements, material compliance tier, and urban density geography. CAGRs derived from fitted growth curves adjusted for regulatory replacement cycle timing and channel shift velocity. Forecast inputs incorporated BlmSchV enforcement intensity variation across Bavarian, North Rhine-Westphalian, and Baden-Württemberg municipal jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated ceramic specialists or rapid direct-channel scaling by Asian OEMs would shift outcomes. Material shifts in EU F-Gas Regulation cooling-system standards or REACH coating chemistry restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cloud Kitchen Market
Food Service
Steam Stew Pot Market
Food Service
Global Digital Grocery Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Rotisseries Market
Food Service
Sandwich Toasters Market
Food Service
Online Food Delivery Market
Food Service
China Online Food Delivery Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
Asia-Pacific Halal Food and Beverage Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
China Inflight Catering Market
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
US Food Service Market
Food Service
Restaurants and Mobile Food Services Market