
 Global Digital Food Delivery Market | 2026-2036
Global Digital Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Food Delivery Market Foresight
Last-mile logistics networks are rewriting competitive boundaries in food distribution. DoorDash Inc. leverages its suburban density advantage to sustain delivery speed benchmarks. Meituan Dianping anchors its position through in-house rider fleets and merchant SaaS tools. Uber Eats competes via cross-promotion with its mobility app ecosystem.
Digital food delivery encompasses technology-mediated platforms connecting consumers with prepared food vendors through algorithmic matching, GPS-enabled dispatch, and embedded payment rails. These systems rely on real-time inventory APIs, dynamic surge pricing engines, and thermal packaging protocols to preserve food quality across variable transit windows. The platform type dimension shows aggregators capturing the largest transaction volume while direct restaurant apps retain superior per-order margins. Application-level demand concentrates in meal delivery, though grocery and alcohol categories accelerate faster from smaller bases. Customer type segmentation reveals corporate accounts generating predictable weekday volume that offsets individual consumer churn.
FDA food safety guidelines, EU GDPR data handling standards, and China's SAMR platform antitrust framework collectively govern market access and operational protocols. Labor classification rules from California's AB5 precedent and analogous European directives reshape cost structures for gig-dependent platforms. Stakeholders must monitor evolving rider employment status rulings and their cascading effects on unit economics and platform viability.
Market Dynamics
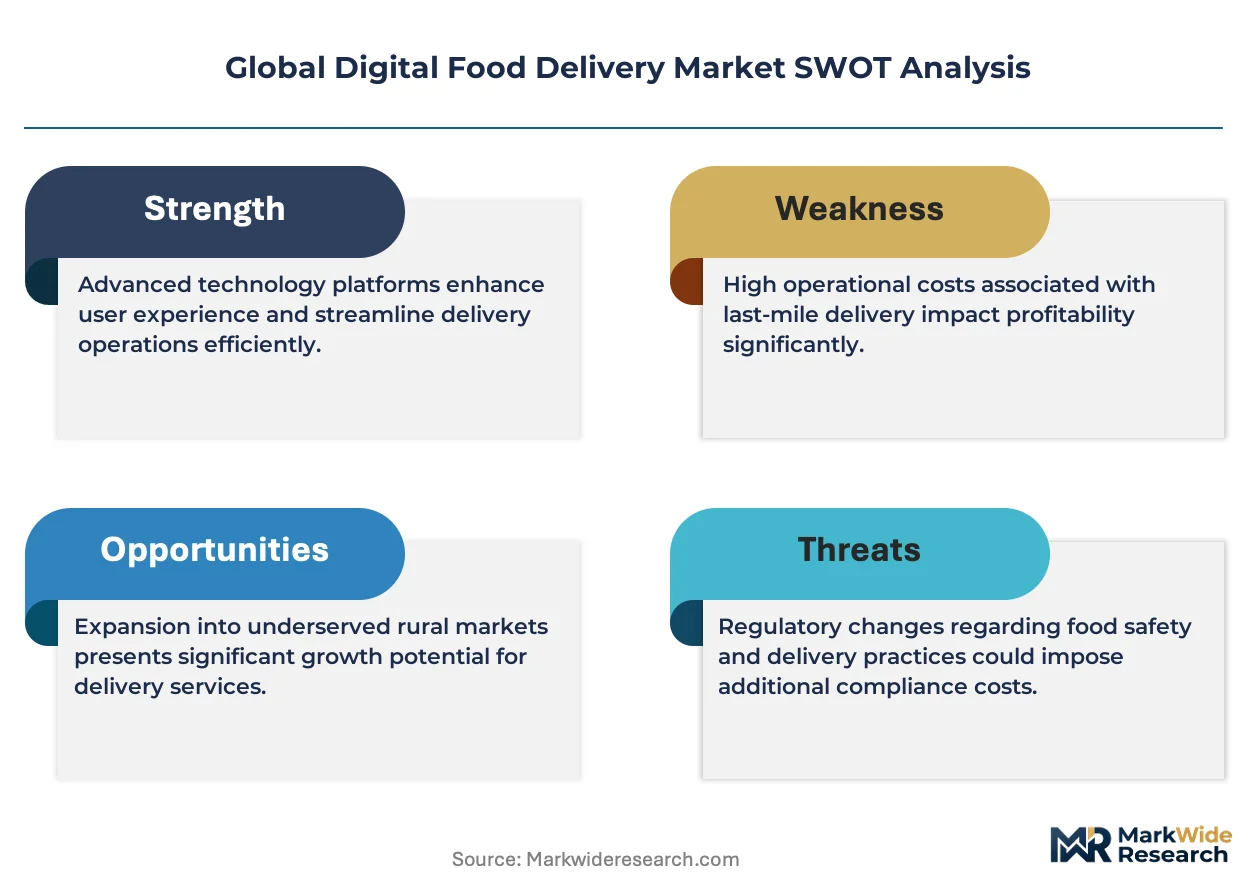
Platform labor classification rulings across multiple jurisdictions are forcing fundamental restructuring of cost models and operational architecture. The shift from contractor-based to employee-equivalent status for delivery riders compresses margins and triggers technology substitution toward autonomous logistics.
Growth Catalysts
- EU Digital Services Act:Standardized transparency requirements reduce compliance fragmentation across member states, lowering platform entry barriers for cross-border operators.
- Cloud kitchen infrastructure:Dedicated food preparation facilities without dine-in space enable pure-play digital brands to scale without real estate constraints in dense urban zones.
- Super-app convergence:Chinese consumers access food delivery through integrated ecosystems combining payments, social, and commerce, driving habitual usage frequency.
Market Restraints
- Input cost volatility:Thermal packaging materials and fuel costs fluctuate with petrochemical indices, compressing per-order contribution margins during price spikes.
- Rider employment reclassification:California's AB5 precedent and analogous European directives mandate benefits and wage floors, structurally elevating labor costs.
- Substitution threat:Quick-service restaurant chains building proprietary delivery fleets bypass aggregator fees, fragmenting volume capture.
Strategic Opportunities
- Rural and suburban India:Smartphone penetration and UPI payment rails enable first-wave digital food access in tier-2 and tier-3 cities previously underserved.
- Grocery and alcohol adjacencies:Platform infrastructure built for prepared food adapts to higher-frequency household replenishment categories with similar last-mile economics.
- AI-driven dynamic pricing:Machine learning models optimizing surge multipliers in real-time capture willingness-to-pay variance across micro-moments.
Industry Challenges
- Food safety certification complexity:FDA guidelines for time-temperature controls during transit require continuous monitoring hardware and audit trails.
- Legacy POS integration:Independent restaurants operate fragmented order management systems, creating API connectivity friction and order error rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Food Delivery Market |
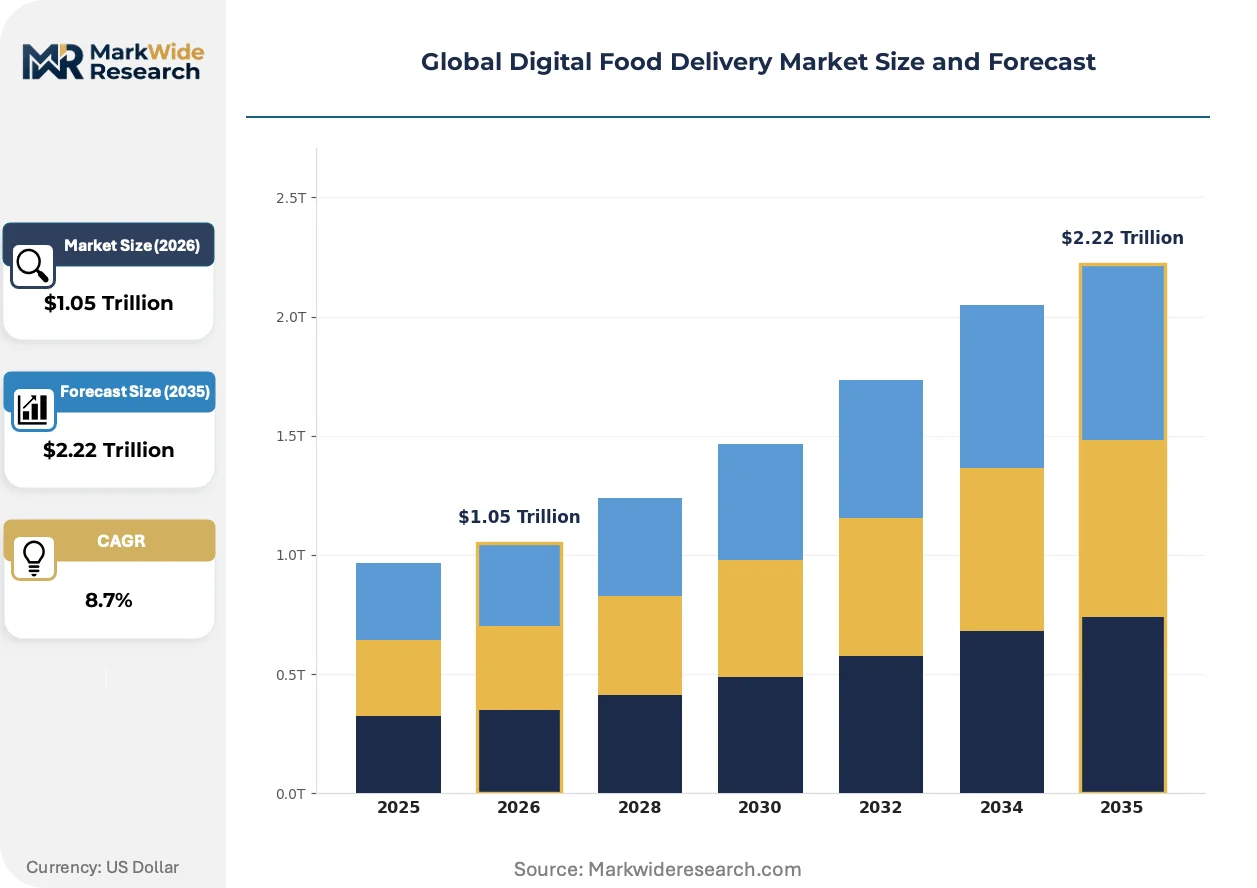
| Market Size in 2026 | $1.05 Trillion |
| Market Size in 2035 | $2.22 Trillion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Order Management, Payment Processing, Route Optimization, Customer Support, Real-Time Tracking Platform Type: Mobile Applications, Websites, Aggregator Platforms, Direct Restaurant Apps, Chatbots, Voice Ordering Customer Type: Individuals, Corporates, Institutions, Event Organizers, Subscription Users Application: Meal Delivery, Grocery Delivery, Alcohol Delivery, Retail Ready Meals, Catering Services |
| Companies Covered | DoorDash Inc., Uber Eats, Meituan Dianping, Delivery Hero SE, Grubhub Inc., Just Eat Takeaway.com, Zomato Limited, Deliveroo plc, Ele.me, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Food Delivery Market Shifts & Advancements
Algorithmic matching and autonomous dispatch systems are compressing delivery windows while reshaping labor deployment. Platform operators invest in predictive demand modeling and micro-fulfillment nodes to sustain speed benchmarks.
Dark store networks and automated micro-fulfillment centers are migrating from experimental pilots to core infrastructure. Quick-commerce operators deploy these facilities within three kilometers of dense demand clusters. This migration from centralized kitchens to distributed nodes collapses delivery radii and enables sub-15-minute service guarantees.
China's SAMR platform antitrust framework constrains exclusive merchant arrangements and data monopolization practices. The regulator mandates interoperability of payment systems and prohibits algorithmic discrimination against rival platforms. Domestic aggregators respond by diversifying revenue streams toward advertising and SaaS tools rather than transaction extraction.
Corporate procurement of group meal solutions displaces individual consumer ordering as the primary weekday volume anchor. Human resources departments negotiate platform contracts covering employee meal allowances, replacing expense reimbursement workflows. This concentration manifests most visibly in technology sector hubs across Bangalore, Singapore, and Berlin.
Global Digital Food Delivery Market Segmentation
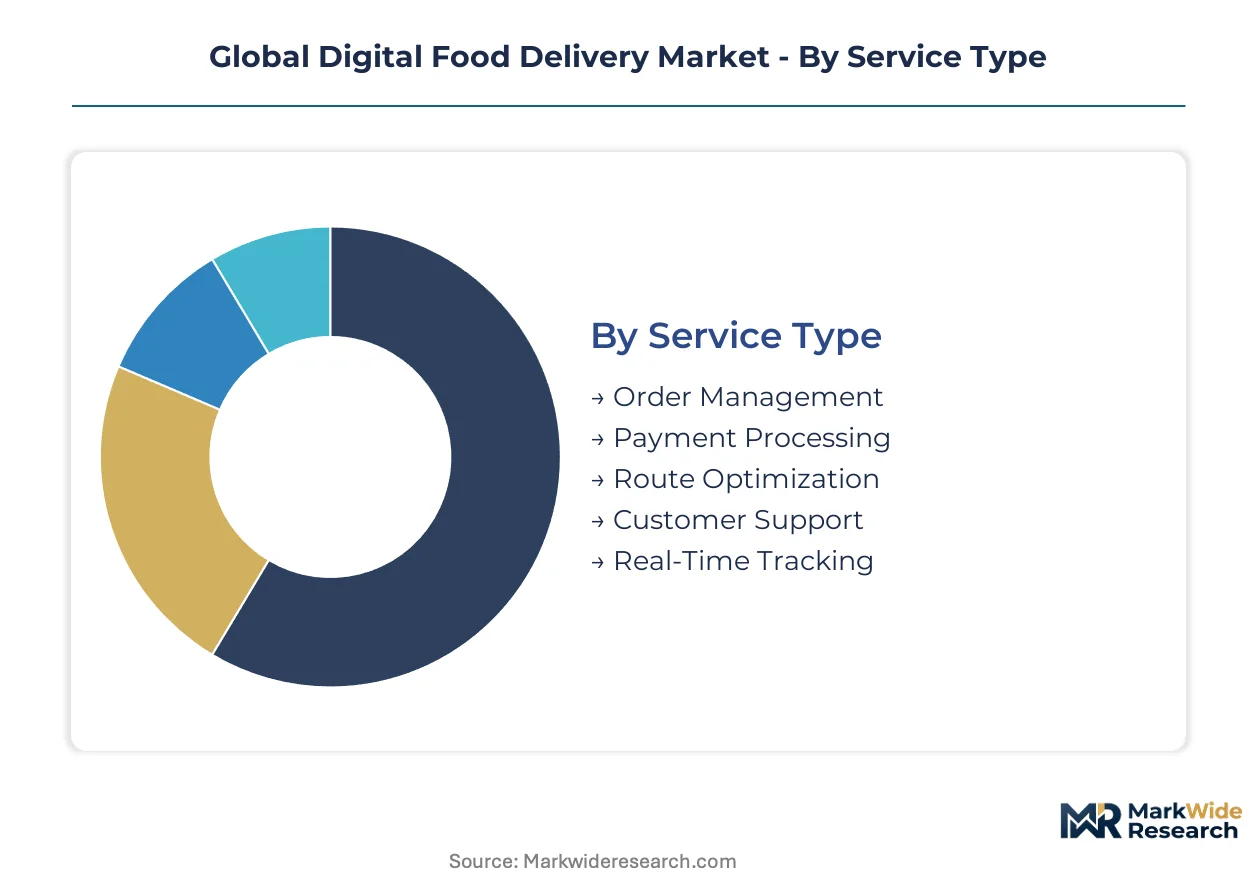
Segmentation in digital food delivery reveals how infrastructure investments and customer acquisition strategies diverge across operational layers. Platform operators allocate capital differently depending on whether they target habitual individual users or predictable corporate accounts. Service type selection directly determines technology stack requirements and margin profiles.
Service Type:
Cost tier differentiation across service modules determines platform operating leverage and vendor selection priorities.
- Order Management:Centralized middleware connecting restaurant POS systems to consumer-facing interfaces through standardized APIs. Demand concentrates among multi-location chains in Germany and Japan seeking unified inventory visibility across fragmented franchise networks.
- Payment Processing:Embedded financial rails handling escrow, split settlements, and fraud detection in real-time. Volume clusters in India and Brazil where UPI and Pix instant payment systems reduce cart abandonment versus card-on-file models.
- Route Optimization:Algorithmic dispatch engines minimizing delivery time variance through predictive traffic modeling.
- Customer Support:Hybrid chatbot-human resolution layers managing refund disputes and order modifications.
- Real-Time Tracking:GPS-enabled consumer visibility with estimated arrival windows updated dynamically.
Order Management holds installed capacity. Payment Processing is rotating up the share rankings.
Platform Type:
Application maturity shapes customer acquisition costs and retention mechanics across interface modalities.
- Mobile Applications:Native iOS and Android clients leveraging push notifications and biometric authentication for frictionless reordering. Habitual usage concentrates in South Korea and Singapore where smartphone penetration exceeds 95% and super-app ecosystems embed food delivery within broader digital commerce.
- Aggregator Platforms:Multi-merchant marketplaces capturing transaction volume through discovery algorithms and loyalty programs. Demand clusters in urban France and Spain where independent restaurants lack capital for proprietary app development.
- Websites:Responsive web interfaces serving desktop and tablet users without app installation friction.
- Direct Restaurant Apps:Single-brand applications retaining customer data and avoiding commission fees to third-party intermediaries.
- Chatbots:Conversational interfaces embedded in messaging platforms for text-based ordering.
- Voice Ordering:Speech-activated systems integrated with smart speakers and automotive infotainment.
Mobile Applications hold installed capacity. Direct Restaurant Apps are climbing the fastest.
Customer Type:
Volume predictability varies sharply between discretionary individual orders and contracted corporate commitments.
- Corporates:Human resources departments negotiating platform contracts covering employee meal allowances with centralized billing and dietary preference management. Demand concentrates in technology sector hubs across Bangalore, Berlin, and Tel Aviv replacing expense reimbursement workflows.
- Individuals:Discretionary consumers ordering through personal accounts with variable frequency and basket size.
- Institutions:Universities, hospitals, and government facilities procuring meal services at scale.
- Event Organizers:One-time bulk orders for conferences, weddings, and sporting events requiring coordinated timing.
- Subscription Users:Recurring delivery commitments with prepaid meal plans and fixed weekly schedules.
Corporates hold installed capacity. Subscription Users are gaining share fastest.
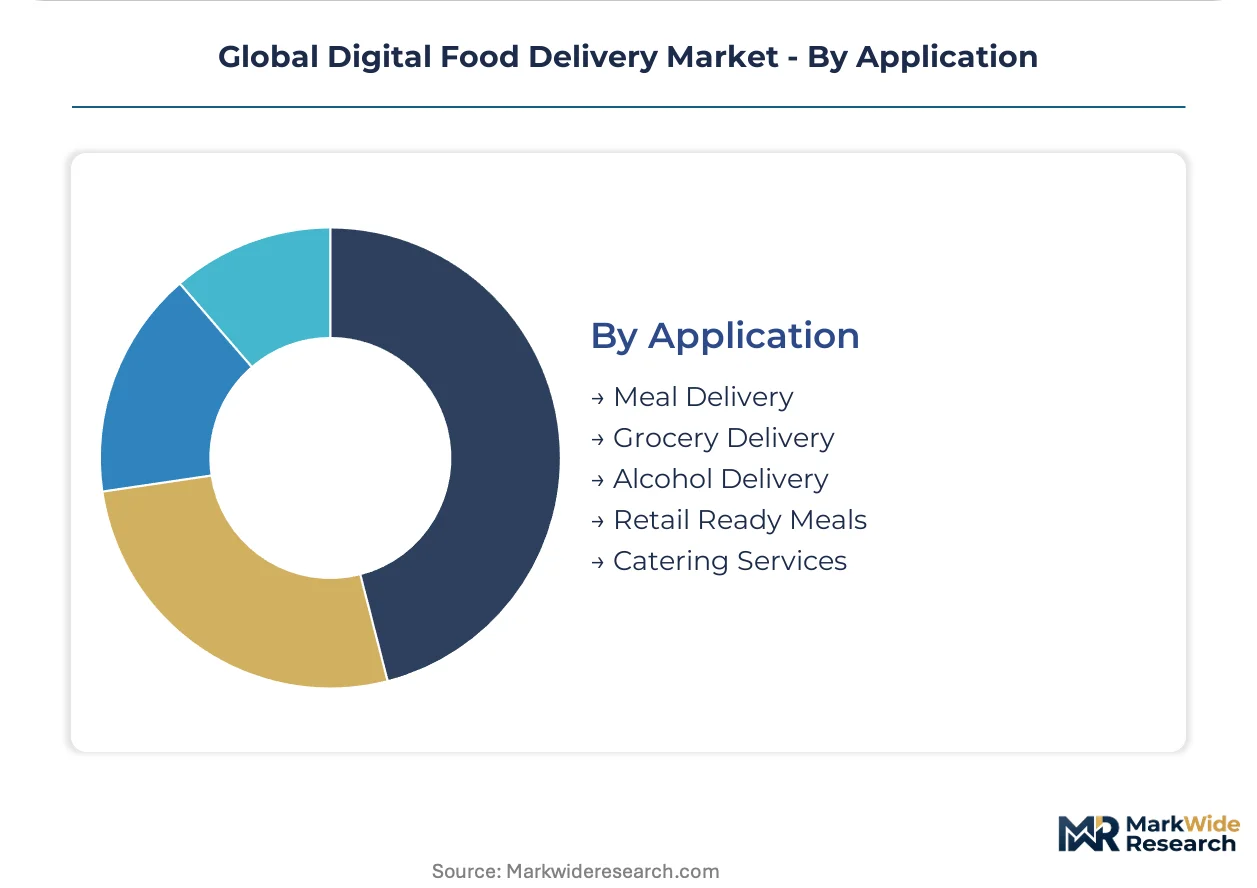
Application:
Category expansion potential depends on last-mile economics alignment with existing platform infrastructure.
- Meal Delivery:Prepared food from restaurants and cloud kitchens representing the core transaction volume base. Mature demand concentrates in tier-1 Chinese cities where Meituan and Ele.me have saturated urban coverage.
- Grocery Delivery:Fresh produce and household staples requiring temperature-controlled logistics and substitute handling protocols. Growth clusters in Poland and Mexico where quick-commerce operators deploy dark stores within three kilometers of dense demand clusters.
- Alcohol Delivery:Age-verified beverage distribution with regulatory compliance requirements varying by jurisdiction.
- Retail Ready Meals:Pre-packaged convenience foods from supermarkets and convenience stores.
- Catering Services:Large-format food preparation for corporate events and institutional feeding.
Meal Delivery holds installed capacity. Grocery Delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in China's super-app ecosystems while European operators absorb compliance costs from labor reclassification mandates. Platform margins in North America reflect suburban density advantages that compress per-unit logistics expenditure. Regulatory fragmentation across jurisdictions forces divergent capital allocation strategies.
United States
Suburban delivery density and corporate meal allowance programs sustain volume growth. California's AB5 labor classification rules elevate rider benefit costs and accelerate automation investment. DoorDash anchors operations in San Francisco and Los Angeles metro corridors where route optimization algorithms exploit residential sprawl patterns.
China
Super-app integration and cloud kitchen proliferation drive habitual usage frequency. SAMR antitrust mandates prohibit exclusive merchant arrangements and mandate payment system interoperability. Meituan and Ele.me compete across tier-1 cities including Shanghai, Beijing, and Shenzhen where in-house rider fleets enable sub-30-minute guarantees.
India
Smartphone penetration and UPI instant payment rails unlock tier-2 and tier-3 city expansion. FSSAI food safety certification requirements impose time-temperature monitoring obligations on transit logistics. Zomato and Swiggy deploy dark stores in Bangalore, Mumbai, and Delhi-NCR to collapse grocery delivery windows below fifteen minutes.
Germany
Aggregator platforms capture independent restaurant volume lacking proprietary app development capital. EU Digital Services Act transparency requirements reduce cross-border compliance fragmentation. Delivery Hero SE operates from Berlin with cloud kitchen networks penetrating Hamburg, Munich, and Frankfurt Rhine-Main corridors.
Brazil
Pix instant payment adoption reduces cart abandonment versus legacy card-on-file models. ANVISA food safety protocols govern temperature-controlled transit for prepared meals. iFood anchors market presence in São Paulo and Rio de Janeiro where quick-commerce dark stores target dense urban demand clusters.
Global Digital Food Delivery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in payment processing and route optimization modules. Market structure consolidates around three to five dominant aggregators per major geography while long-tail regional operators capture niche ethnic cuisine segments. Strategic archetypes include super-app ecosystems, pure-play delivery specialists, and quick-commerce adjacency expanders. Competitive moves concentrate on cloud kitchen infrastructure deployment and autonomous logistics technology licensing.
Among North American platform operators, DoorDash Inc. and Uber Eats exemplify divergent density strategies. Within the European aggregator tier, Delivery Hero SE and Just Eat Takeaway.com occupy positions shaped by cross-border consolidation patterns. These entities represent archetype anchors rather than definitive market share claims.
| Leading Market Players |
|---|
| DoorDash Inc. |
| Uber Eats |
| Meituan Dianping |
| Delivery Hero SE |
| Grubhub Inc. |
| Just Eat Takeaway.com |
| Zomato Limited |
| Deliveroo plc |
| Ele.me |
| Others |
Supply & Pricing Matrix
The Shanghai-Singapore freight corridor's fuel surcharge volatility compresses cloud kitchen margins while amplifying price spreads between aggregator-platform commissions and direct-restaurant premiums. This logistics cost dynamic concentrates supply power among operators with captive dark store networks, forcing smaller platforms toward SaaS-tiered subscription models to escape per-transaction margin erosion.
Pricing Analysis
The customization-premium spread separates configured corporate meal plans from standard individual consumer orders, with enterprise contracts commanding pricing premiums of 15-25% above base rates due to dietary compliance bundling and centralized billing integration. Pricing stratifies across premium white-glove catering, standard aggregator marketplace, and economy quick-commerce tiers, with differentiation driven by delivery speed guarantees and temperature-control certification grades. Cost compression in the economy tier intensifies because petrochemical-linked packaging costs spike unpredictably. Corporate accounts exhibit lowest price sensitivity due to HR budget fungibility, while individual subscription users demonstrate highest elasticity to delivery fee adjustments.
Supply Chain Analysis
Upstream feedstock dependencies in thermal packaging materials and GPS-enabled dispatch hardware draw from concentrated manufacturing bases in China, South Korea, and Vietnam. The supply chain rests on polystyrene and aluminum composite inputs for food-grade containers, plus semiconductor components for rider tracking devices. Single-source vulnerability in cold-chain packaging polymers creates exposure to petrochemical price shocks. Distribution runs through hub-and-spoke dark store networks with micro-fulfillment nodes positioned within three kilometers of dense urban demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platform-economics inflection manifests through China's SAMR-mandated payment interoperability, which dissolves data moats and forces revenue model migration toward merchant SaaS and advertising.
For Market Incumbents: Harden cloud kitchen infrastructure ownership against quick-service restaurant chains building proprietary delivery fleets, which threaten volume fragmentation. Consolidate rider employment status compliance through technology substitution toward autonomous logistics, while deepening backward integration into thermal packaging production to offset petrochemical cost volatility. For New Entrants and Emerging Players: Build out rural and suburban India penetration where smartphone density and UPI rails enable first-mover positioning in tier-2 and tier-3 cities. Target grocery delivery adjacencies as the most penetrable application expansion, leveraging existing last-mile density for higher-frequency household replenishment with similar unit economics. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate parent companies seeking to divest non-core food delivery assets amid labor reclassification cost pressures. Long-term viability hinges on autonomous logistics technology licensing revenue streams and SaaS tool penetration among merchant bases. Watch rider employment status rulings across European jurisdictions as the critical inflection signal for platform margin restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Expansion | Dedicated food preparation facilities in Shanghai and Bangalore enable pure-play digital brands to scale without dine-in real estate constraints. |
| Autonomous Logistics Technology Licensing | Self-dispatch algorithms and drone delivery patents create defensible revenue streams as labor costs escalate under AB5-type regulations. |
| Merchant SaaS Tool Penetration | Inventory management and dynamic pricing software diversifies revenue beyond transaction commissions under SAMR antitrust constraints. |
| Quick-Commerce Grocery Adjacency | Dark store networks in São Paulo and Mexico City adapt prepared-food infrastructure to higher-frequency household replenishment categories. |
| Corporate Meal Allowance Contracting | HR-negotiated platform agreements in Bangalore and Berlin replace expense reimbursement with predictable weekday volume anchors. |
Research Methodology
The analysis maps aggregator platforms, cloud kitchen operators, payment processing middleware, and route optimization software modules, each validated through platform engineering directors, restaurant chain procurement leads, rider fleet managers, and regulatory compliance officers. Primary interview insights combined with secondary validation from SEC filings, EU Digital Services Act implementation reports, SAMR antitrust enforcement disclosures, and UPI transaction data published by NPCI. Bottom-up unit economics modeling and top-down market sizing triangulate volume estimates across service type, platform type, customer type, and application dimensions.
Assumptions held fixed include prevailing labor classification frameworks, existing super-app ecosystem structures, and current fuel cost baselines, while variables tested include rider reclassification acceleration rates, autonomous logistics deployment curves, and grocery adjacency penetration speeds. Segmentation dimensions modeled encompass service tier, platform interface modality, customer contract type, and application category across the projection horizon. CAGRs derive from logistic diffusion curves fitted to smartphone penetration and payment rail adoption patterns, with cloud kitchen capacity buildout and dark store network expansion serving as industry-specific demand proxies.
Stress conditions across fuel price spikes, thermal packaging material shortages, and abrupt labor reclassification mandates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution timelines. Cross-checking against disclosed platform commission rates and merchant churn statistics from comparable market studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Pizza Oven Market
Food Service
Bangladesh Food Service Market
Food Service
North America Food Service Market
Food Service
New Zealand Foodservice Market
Food Service
Mobile Food Services Market
Food Service
Europe Food Service Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Beverage Coaster Market
Food Service
Mexico Foodservice Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Food Service Dairy Products Market
Food Service
Steam Stew Pot Market
Food Service
Cutting Boards Market
Food Service
Peer-To-Peer Dining Market
Food Service
Japan Foodservice Market
Food Service
Ice Cream Carts Market