
 Saudi Arabia Full- Service Restaurants Market | 2026-2036
Saudi Arabia Full- Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Full- Service Restaurants Market Analytics
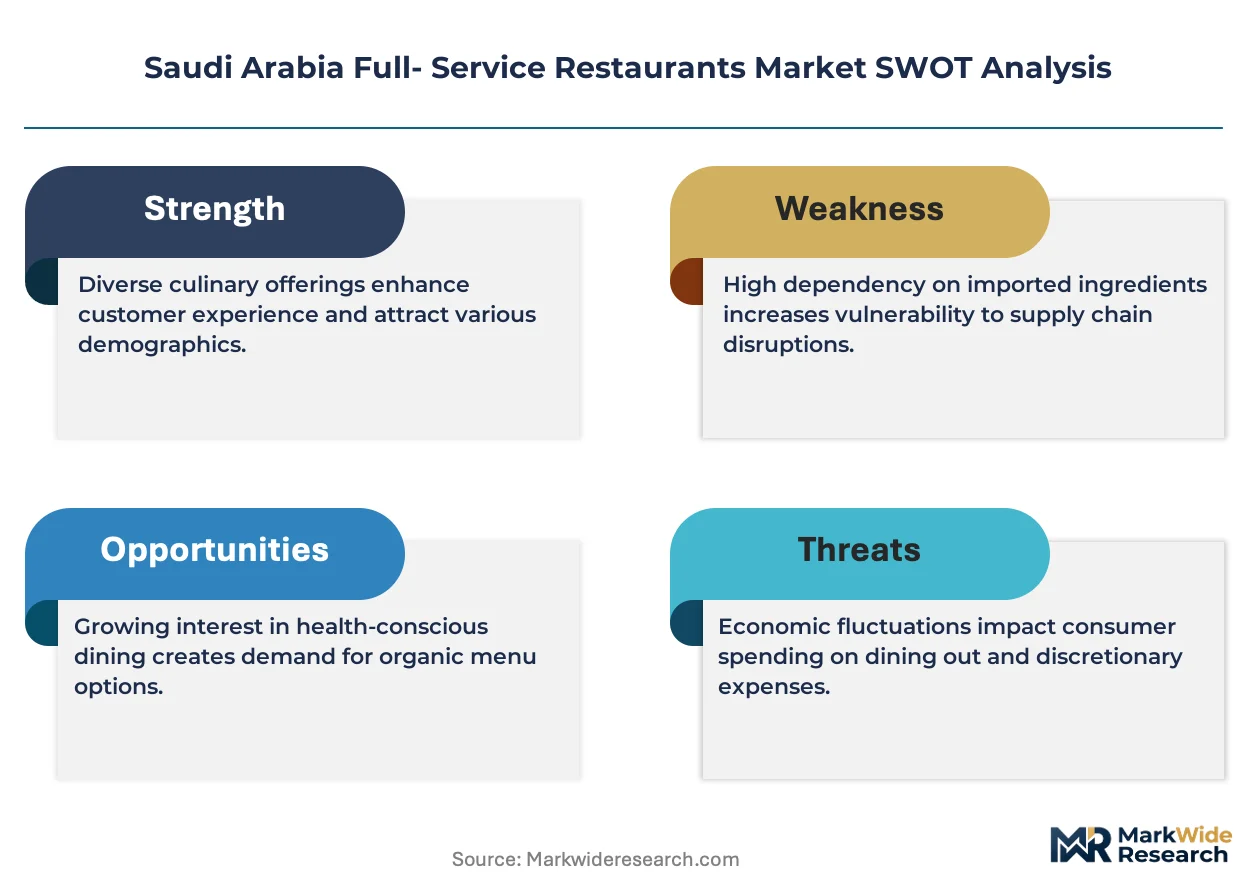
Expatriate chef availability is unwinding as a critical growth constraint across the kingdom's dining sector. ALBAIK Food Systems Company S.A. leverages its vertically integrated supply chain to maintain consistent quality at scale. Americana Restaurants International PLC anchors its position through deep brand equity in family-oriented dining formats. Herfy Food Services Co. competes aggressively on breakfast and quick-casual extensions that blur traditional full-service boundaries.
A full-service restaurant denotes an establishment where patrons order meals at tableside from printed or digital menus, with food prepared to order in back-of-house kitchens and delivered by waitstaff; seating configurations typically span 80-300 covers with average ticket durations of 45-90 minutes, serving both social and business entertainment functions. The cuisine type dimension shows Middle Eastern concepts dominating volume while Asian formats generate the fastest check-growth trajectory. Within the price tier segmentation, premium and luxury brackets capture disproportionate margin pools despite representing smaller cover counts, as the economy tier remains saturated with limited pricing power.
SFDA licensing requirements and municipal health inspections from Saudi city municipalities enforce strict kitchen hygiene and ingredient traceability standards that filter out informal operators. The General Authority for Tourism's hospitality classification system further segments eligible venues by star-rating alignment, restricting certain full-service formats from associated property developments. Stakeholders must weigh workforce localization mandates against the experiential expectations of an increasingly cosmopolitan domestic customer base.
Market Dynamics
The Saudi Arabia full-service restaurant sector operates under intensifying workforce localization mandates from the Ministry of Human Resources and Social Development, which are compressing expatriate chef availability while domestic culinary training infrastructure remains underdeveloped.
Growth Catalysts
- Vision 2030 entertainment sector expansion:The General Entertainment Authority's licensing of cinemas, concerts, and sporting venues is generating concentrated dining traffic in Riyadh and Jeddah entertainment districts.
- SFDA food safety protocol elevation:Stricter kitchen hygiene and ingredient traceability standards are filtering out informal operators and consolidating market share among compliant full-service chains.
- Young urban professional cohort expansion:Demographic shifts toward dual-income households in Riyadh's northern corridor are expanding weekday lunch and after-work dining occasions.
Market Restraints
- Expatriate chef supply contraction:Workforce localization targets are reducing experienced culinary talent pools faster than domestic hospitality institutes can replenish them.
- Imported protein cost volatility:Dependence on Australian and Brazilian beef and lamb exposes margins to currency fluctuations and shipping rate spikes.
- Real estate concentration in Riyadh:Premium dining corridor lease rates in the capital absorb disproportionate revenue share, constraining unit economics.
Strategic Opportunities
- Qassim and Asir province penetration:Secondary cities with rising disposable incomes remain underserved by premium full-service concepts relative to Riyadh and Jeddah saturation.
- SFDA export certification pathway:Compliant operators can leverage domestic food safety credentials to franchise into Gulf Cooperation Council markets with regulatory reciprocity.
- Cloud kitchen hybrid formats:Combining dine-in full-service with delivery-optimized back-of-house operations addresses divergent occasion demands without duplicate real estate.
Industry Challenges
- Saudization compliance timeline pressure:Front-of-house and kitchen management roles require rapid domestic talent development against quarterly workforce quota deadlines.
- Legacy POS integration friction:Digital ordering and payment platforms must interface with established franchise system infrastructure, complicating technology stack upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Full- Service Restaurants Market |
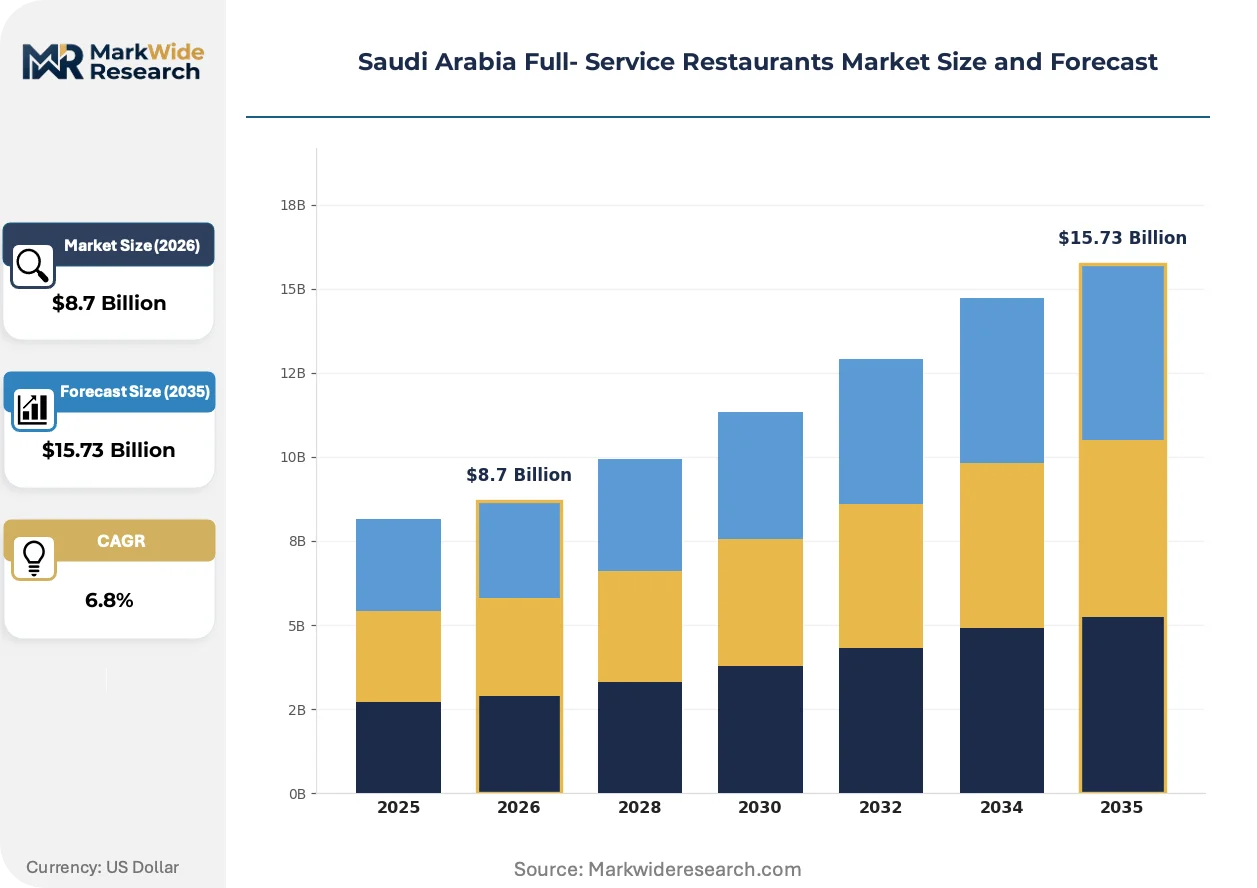
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeout, Drive-thru, Delivery Cuisine Type: Italian, Asian, American, Middle Eastern Customer Segment: Families, Business Travelers, Tourists, Locals Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | ALBAIK Food Systems Company S.A., Herfy Food Services Co., KUDU Company for Food and Catering, Americana Restaurants International PLC, Alshaya Group, Food & Entertainment Co., Reza Food Services Co. Ltd., Alamar Foods, M.H. Alshaya Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Full- Service Restaurants Market Evolving Landscape
Technology deployment and regulatory adaptation are compressing traditional operational models while creating new format hybrids that blur full-service boundaries. These shifts are redefining competitive positioning across the kingdom's dining landscape.
Tablet-based tableside ordering systems are fragmenting the traditional server-patron interaction model. Mid-scale family dining chains in Riyadh are deploying these interfaces to reduce labor intensity while capturing granular consumption data. The technology is fragmenting front-of-house staffing models and compressing training curves for new hires.
SFDA's tightened food safety protocols are mandating real-time temperature monitoring and blockchain-enabled ingredient traceability. Full-service operators must now maintain digital audit trails from supplier receipt through plate presentation. Premium concepts in Jeddah's corniche district are absorbing these compliance costs fastest, using certification as competitive differentiation.
Young urban professionals are compressing traditional meal occasion boundaries, treating full-service venues as remote workspaces and social meeting points beyond standard lunch and dinner windows. This behavior is stretching operating hour economics and reshaping seating configuration priorities. Riyadh's northern corridor restaurants report the most pronounced demand for power outlet density and WiFi reliability as selection criteria.
Saudi Arabia Full- Service Restaurants Market Segmentation
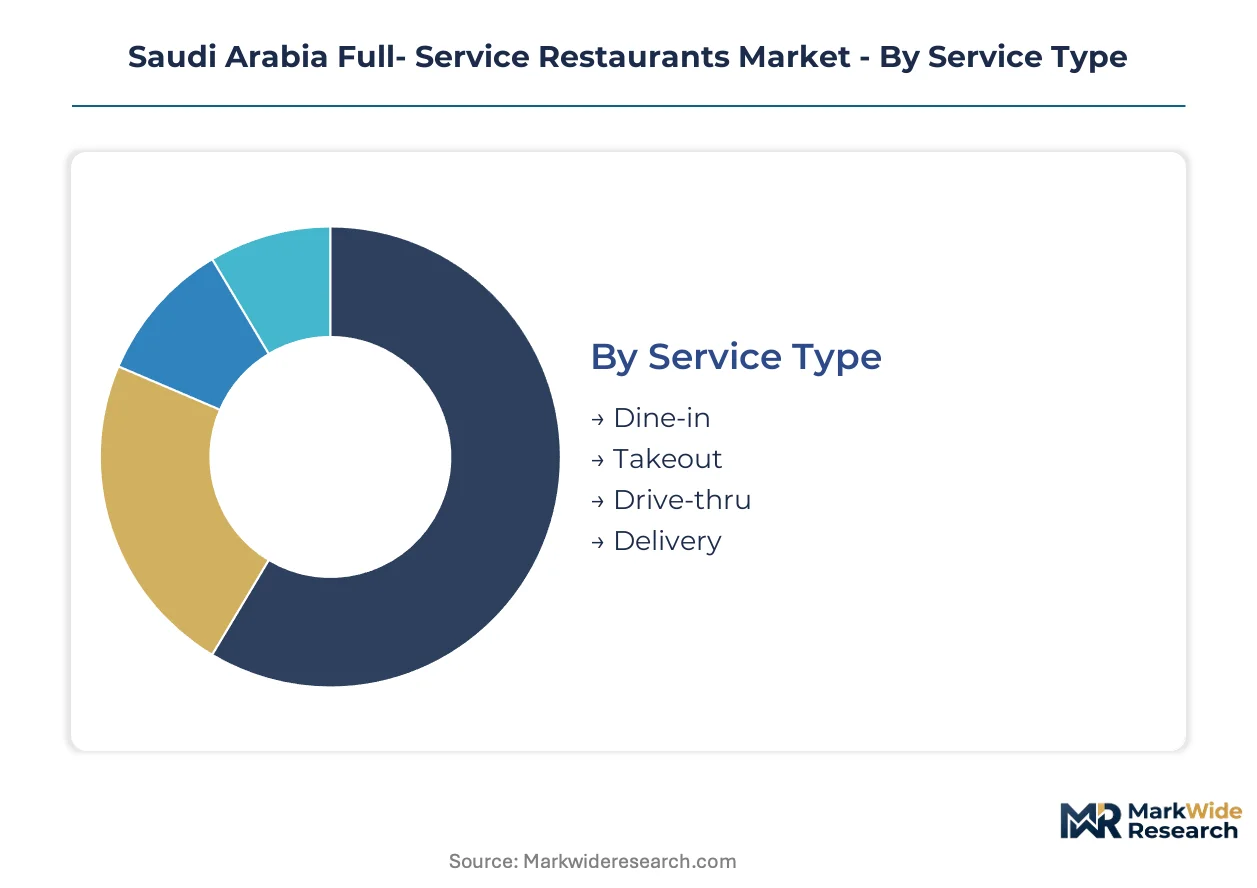
Segmentation in the Saudi Arabia full-service restaurant sector reveals how consumption occasions fragment across service modalities and price thresholds. Operators must align format investments with specific demand clusters rather than pursuing undifferentiated coverage.
Service Type:
Dine-in traffic flows through entertainment district clusters while delivery and takeout capture dispersed residential demand across Riyadh's northern corridor and Jeddah's corniche.
- Dine-in:Tableside service with 45-90 minute average ticket durations anchors revenue in Riyadh's upscale dining corridor. Young urban professionals concentrate weekday lunch and after-work occasions here, compressing traditional meal boundaries into extended social and remote work sessions.
- Takeout:Counter-collected orders prepared in back-of-house kitchens with 15-25 minute fulfillment windows. Demand clusters around office districts and residential compounds where time constraints override experiential priorities.
- Drive-thru:Vehicle-based ordering and pickup lanes attached to standalone or highway-adjacent locations. Qassim and Asir province penetration relies heavily on this format given lower real estate density.
- Delivery:Third-party platform and in-house fleet fulfillment to residential and workplace addresses. Cloud kitchen hybrid formats are expanding capacity here without duplicate dine-in real estate.
Dine-in dominates installed base. Delivery is where expansion concentrates.
Cuisine Type:
Margin profiles diverge sharply across culinary traditions, with protein cost structures and labor intensity determining viable price tier positioning.
- Italian:Pasta-forward menus with moderate ingredient complexity and scalable kitchen training curves. Premium concepts in Jeddah's corniche district absorb SFDA compliance costs fastest here, using certification as competitive differentiation.
- Asian:Wok-based preparation requiring specialized equipment and expatriate chef availability that workforce localization mandates are compressing. This cuisine climbs the fastest in check-growth trajectory among all categories.
- American:Burger and steakhouse formats with heavy dependence on Australian and Brazilian beef imports. Currency fluctuations and shipping rate spikes expose margins to volatility.
- Middle Eastern:Kabsa, mandi, and grilled protein traditions dominating volume across the kingdom. Domestic culinary training infrastructure is most developed here, easing Saudization compliance pressures.
Middle Eastern concepts dominate installed base. Asian formats are where expansion concentrates.
Customer Segment:
Occasion type dictates seating configuration, service speed, and check average more than demographic profile alone.
- Families:Multi-generational groups requiring high chair availability, portion sharing formats, and 90-120 minute dwell times. Weekend lunch and early dinner windows concentrate demand.
- Business Travelers:Solo or paired dining with expense account elasticity and speed requirements. Hotel-adjacent locations in Riyadh and Jeddah capture disproportionate share.
- Tourists:Experience-seeking visitors prioritizing cuisine authenticity and Instagram-visible ambiance. General Entertainment Authority venue licensing is generating concentrated traffic here.
- Locals:Repeat-visit households with established brand loyalties and price sensitivity at economy and mid-range tiers. Tablet-based tableside ordering systems are fragmenting traditional server interaction for this segment.
Families dominate installed base. Young urban professionals within the locals segment are where expansion concentrates.
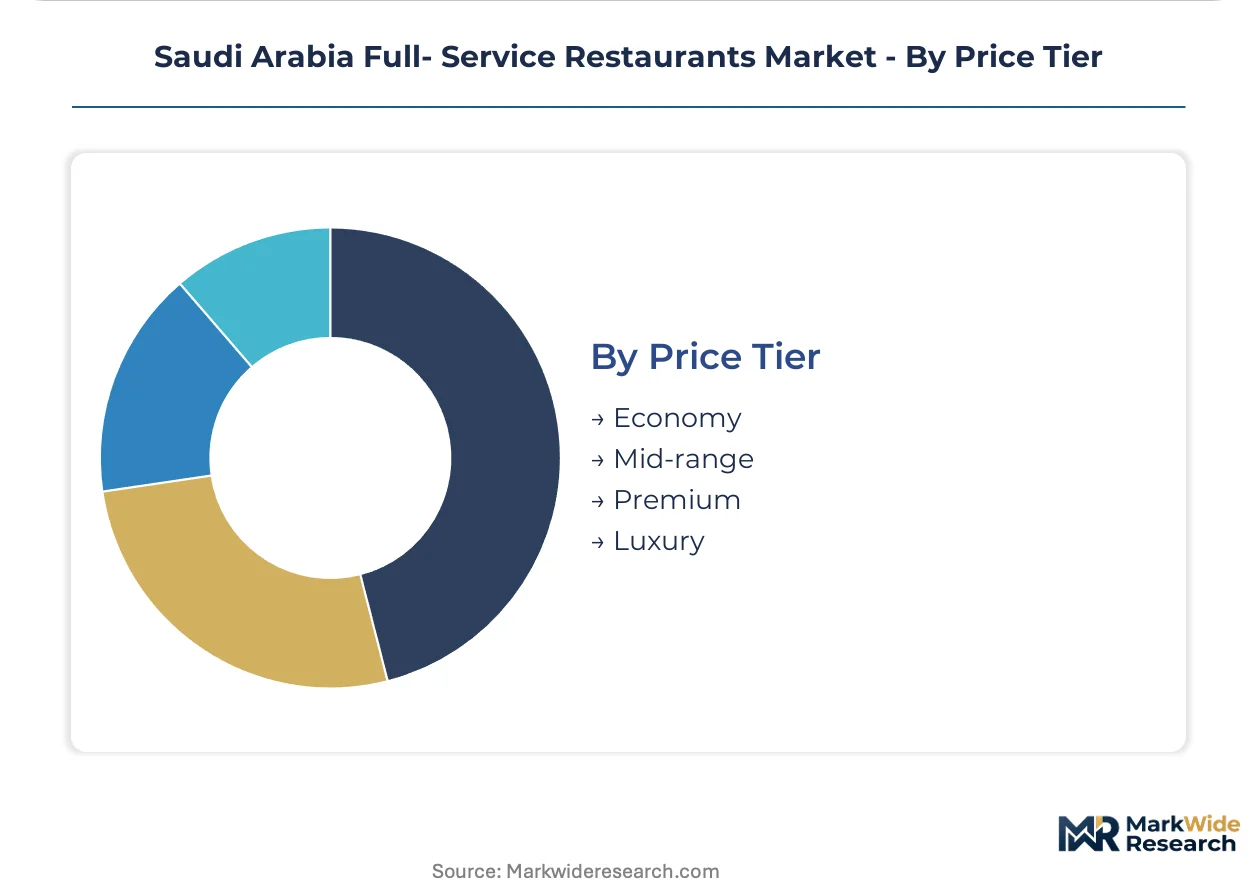
Price Tier:
Real estate absorption rates and workforce localization compliance costs determine viable tier positioning for new entrants.
- Economy:Sub-50 SAR per-person checks with limited menu breadth and self-service elements. The tier remains saturated with limited pricing power and thin margins.
- Mid-range:50-150 SAR checks balancing quality perception with accessibility. ALBAIK Food Systems Company leverages vertical integration to maintain consistent quality at scale here.
- Premium:150-400 SAR checks with full tableside service and ingredient provenance emphasis. SFDA's tightened protocols filter out informal operators, consolidating share among compliant chains.
- Luxury:400+ SAR checks with chef-driven menus and sommelier service. Premium dining corridor lease rates in Riyadh absorb disproportionate revenue share, constraining unit economics.
Economy and mid-range dominate installed base. Premium is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA's tightened food safety protocols anchor operational standards across Saudi Arabia's full-service restaurant sector, with municipal health inspections from Saudi city municipalities enforcing strict kitchen hygiene and ingredient traceability requirements that filter out informal operators.
Riyadh
Young urban professionals in Riyadh's northern corridor are compressing traditional meal boundaries into extended social and remote work sessions. The General Entertainment Authority's licensing of cinemas and sporting venues generates concentrated dining traffic in entertainment districts. Premium dining corridor lease rates absorb disproportionate revenue share, constraining unit economics for new entrants.
Jeddah
Tourist demand clusters along Jeddah's corniche district where experience-seeking visitors prioritize cuisine authenticity and Instagram-visible ambiance. Premium concepts here absorb SFDA compliance costs fastest, using certification as competitive differentiation. The Western Region's hospitality classification system segments eligible venues by star-rating alignment.
Eastern Province
Business travelers drive hotel-adjacent dining demand with expense account elasticity and speed requirements. Workforce localization mandates from the Ministry of Human Resources and Social Development compress expatriate chef availability faster than domestic hospitality institutes can replenish talent pools. Dammam and Khobar anchor the province's commercial dining infrastructure.
Qassim
Rising disposable incomes in this secondary city remain underserved by premium full-service concepts relative to Riyadh and Jeddah saturation. Drive-thru formats dominate given lower real estate density and dispersed residential patterns. Cloud kitchen hybrid formats are expanding delivery capacity without duplicate dine-in real estate investments.
Asir Province
Domestic tourism to Abha and surrounding highland areas creates seasonal demand spikes for family-oriented dining formats. The province's distance from major supply corridors exposes operators to imported protein cost volatility from Australian and Brazilian beef and lamb dependence. Tablet-based tableside ordering systems are fragmenting traditional server-patron interaction models in newer outlets.
Saudi Arabia Full- Service Restaurants Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Saudi full-service restaurant sector. The market structure concentrates around vertically integrated domestic chains and international franchise operators with deep brand equity. Three archetypes dominate: scale-driven fast-casual hybrids, premium experience specialists, and family-format anchor chains. Competitive moves center on workforce localization compliance acceleration and cloud kitchen format experimentation.
Among scale-driven domestic operators, ALBAIK Food Systems Company S.A. exemplifies vertical integration into supply chain control, while Americana Restaurants International PLC occupies a position representing international franchise depth in family-oriented formats. Herfy Food Services Co. sits within the quick-casual extension archetype that blurs traditional full-service boundaries through breakfast-focused positioning.
| Leading Market Players |
|---|
| ALBAIK Food Systems Company S.A. |
| Herfy Food Services Co. |
| KUDU Company for Food and Catering |
| Americana Restaurants International PLC |
| Alshaya Group |
| Food & Entertainment Co. |
| Reza Food Services Co. Ltd. |
| Alamar Foods |
| M.H. Alshaya Co. |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty days of frozen protein inventory anchors working capital intensity across the Saudi full-service restaurant sector, compressing margin buffers when Australian beef spot rates spike and amplifying pricing power for operators with captive cold-chain infrastructure.
Pricing Analysis
Riyadh's premium dining corridor commands three-to-four-fold check multiples over Qassim province equivalents for comparable cuisine formats. Three-tier pricing structure across premium, standard, and economy levels segments the market, with SFDA certification grade and ingredient provenance documentation serving as primary price differentiation drivers. Cost compression in the economy tier is intensifying because workforce localization mandates inflate front-of-house labor costs without corresponding quality perception gains. Family segments exhibit highest price sensitivity, while business travelers with expense account elasticity show least.
Supply Chain Analysis
Strait of Hormuz transit underwrites containerized delivery schedules for Australian beef, Brazilian lamb, and Asian seafood arriving at Jeddah Islamic Port. Geographic supply concentration centers on Australia, Brazil, and Thailand for core protein inputs. Raw material dependencies rest on imported chilled beef, frozen poultry, and specialty Asian condiments. Single-source vulnerability from Australian drought cycles exposes margin stability. Distribution runs through vertically integrated national chains and fragmented regional wholesalers serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in secondary city premium dining, where young urban professional cohort expansion outpaces branded concept penetration.
For Market Incumbents: Fortify market position through accelerated cloud kitchen format deployment in Asir and Qassim provinces before lease rate inflation follows Riyadh's trajectory. Deepen backward integration into protein processing to buffer Australian beef cost volatility. SFDA compliance certification investments create switching costs against emerging regional competitors. For New Entrants and Emerging Players: SFDA export certification fast-track unlocks Gulf Cooperation Council franchise expansion for compliant domestic operators. White-space targets include premium Asian concepts in Jeddah's corniche district and family-oriented mandi formats in Abha's seasonal tourism corridor. Go-to-market angle should emphasize tablet-based tableside ordering to compress Saudization training curves. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned restaurant groups facing succession pressure and workforce localization compliance timeline pressure. Long-term viability frames around regulatory compliance infrastructure as durable competitive moat. Monitor SFDA enforcement intensity as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Hybrid Expansion | Combines dine-in full-service with delivery-optimized operations without duplicate real estate in secondary cities. |
| SFDA Certification Fast-Track | Enables Gulf Cooperation Council market entry through regulatory reciprocity agreements. |
| Workforce Localization Acceleration | Front-of-house tablet deployment compresses training curves for Saudization compliance deadlines. |
| Vertical Supply Chain Integration | Cold-chain infrastructure insulates margins from Australian beef spot rate volatility. |
| Secondary City Premium Penetration | Qassim and Asir provinces offer underserved demand with lower lease absorption than Riyadh corridor. |
Research Methodology
The analysis maps dine-in, delivery, takeout, and drive-thru service modalities, each validated through executive interviews with restaurant operations directors, supply chain managers, municipal health inspectors, and franchise development officers. Primary fieldwork combined with secondary validation from SFDA regulatory filings, General Authority for Tourism hospitality classification databases, and Ministry of Human Resources workforce localization reports. Bottom-up unit economics modeling and top-down sector expenditure triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, cuisine category, price tier, and customer occasion type. CAGRs derived from trend extrapolation adjusted for regulatory enforcement intensity and entertainment district development pipelines. Forecast inputs incorporated workforce localization quota trajectories and imported protein cost indices.
Decision-makers should treat outputs as directional under stable regulatory enforcement and entertainment licensing expansion assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SFDA protocol evolution and expatriate visa policy adjustments unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Australia Foodservice Market
Food Service
Commercial Sink Market
Food Service
Meal Voucher Market
Food Service
Chained Consumer Foodservice Market
Food Service
Sandwich Toasters Market
Food Service
Haute Cuisine Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Halal Food and Beverages Market
Food Service
Food Service Pasta Market
Food Service
Chile Food Delivery Market
Food Service
Malaysia Food Service Market
Food Service
Europe Barbeque Grill Market
Food Service
Global Dark Store Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Middle East Smokeless Indoor Grills Market