
 Steam Stew Pot Market | 2026-2036
Steam Stew Pot Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Stew Pot Market Insights
Chinese cookware foundries in Guangdong and Zhejiang provinces is decoupling from low-margin OEM contracts toward branded production. Midea leverages its appliance ecosystem to bundle steam stew pots with smart kitchen platforms. SUPOR sustains dominance in domestic retail channels through deep distribution into China's county-level markets. Zojirushi Corporation differentiates through precision temperature control systems targeting Japanese and North American premium segments.
A steam stew pot is a lidded cooking vessel engineered to circulate saturated steam at temperatures between 100°C and 120°C, typically constructed with multi-ply stainless steel or cast iron walls and a sealed rim to prevent vapor loss, designed for slow-simmering broths, stews, and nutrient-retention cooking in both residential and foodservice environments. Electric and multi-function product types command the widest margin pools as consumers trade up from basic stovetop models toward programmable units with timer and keep-warm capabilities. Stainless steel material grades anchor the professional channel where NSF compliance and durability under continuous service outweigh upfront cost considerations.
China's SAMR enforces GB 4806 food-contact material standards that restrict heavy metal migration in metal alloys, directly shaping supplier qualification criteria for export-bound manufacturers. The EU's REACH and RoHS frameworks limit specific substance use in electrical components, affecting multi-function and induction product lines sold into European markets. Stakeholders must monitor evolving energy-efficiency thresholds in major economies and calibrate R&D allocation between smart-feature development and material compliance certification.
Market Dynamics
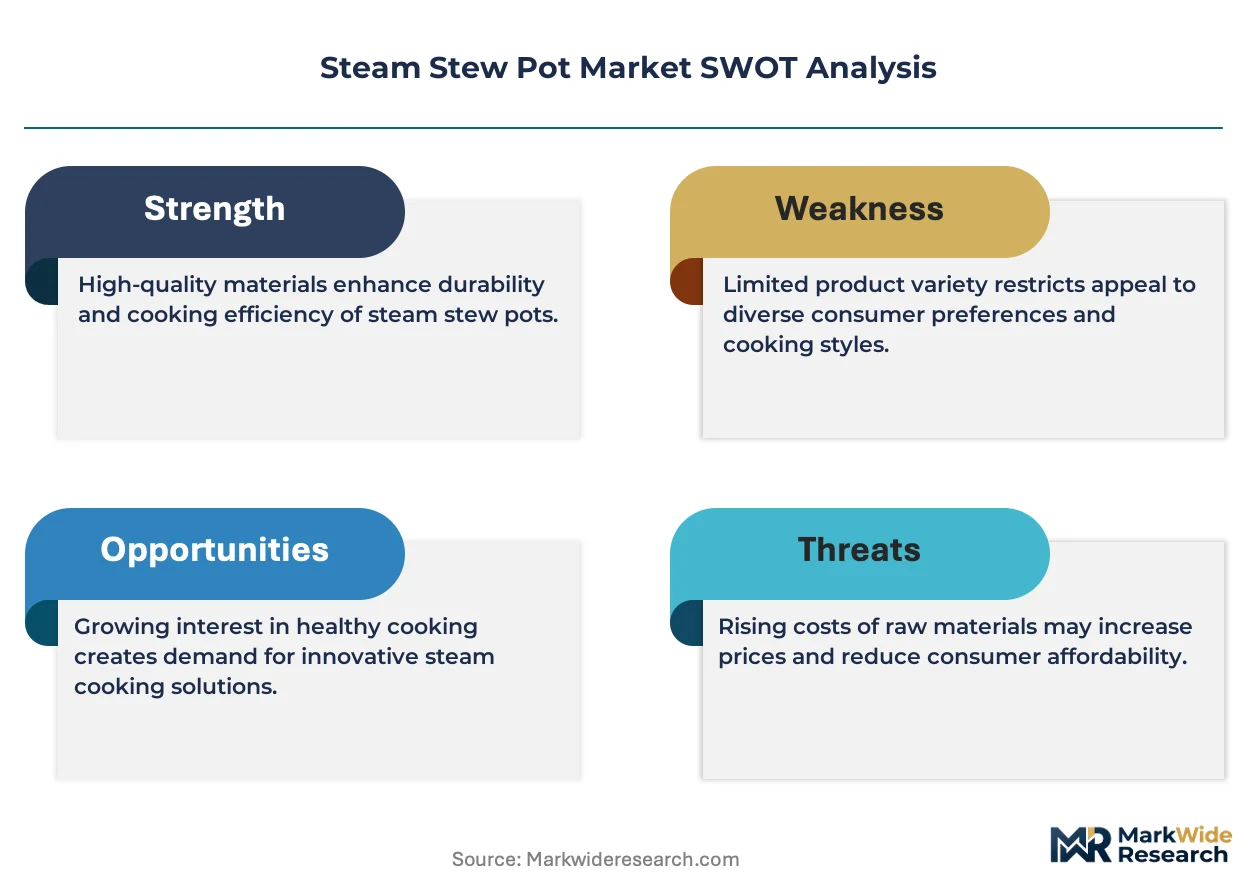
China's GB 4806 food-contact material standards and tightening energy-efficiency labeling are forcing manufacturers to reallocate R&D spending from feature innovation toward compliance certification, compressing margin pools for mid-tier producers.
Growth Catalysts
- Multi-function electric units:Commercial kitchens across Asia-Pacific are expanding procurement of programmable steam stew pots with timer and keep-warm capabilities, trading up from basic stovetop models.
- GB standards compliance:China's SAMR enforcement of food-contact material rules restricts heavy metal migration in metal alloys, creating supplier qualification barriers that favor certified domestic foundries.
- Premium restaurant upgrades:Tier-one cities in China concentrate demand for stainless steel models as professional kitchens prioritize NSF compliance and durability under continuous service.
Market Restraints
- Nickel price volatility:Multi-ply stainless steel construction depends on nickel alloy inputs subject to commodity swings, squeezing gross margins for manufacturers locked into fixed-price OEM contracts.
- Guangdong-Zhejiang supply concentration:Foundry capacity clusters in two Chinese provinces, exposing buyers to regional logistics disruptions and concentrated labor cost pressures.
- Induction compatibility limitations:Cast iron wall constructions face technical barriers achieving uniform heat distribution on induction cooktops, restricting placement in modern commercial kitchens.
Strategic Opportunities
- Smart kitchen platform integration:Appliance ecosystems are absorbing steam stew pots into connected cooking environments, enabling remote monitoring and recipe automation for tech-forward households.
- County-level distribution penetration:Deep retail networks into China's lower-tier cities remain underdeveloped for premium electric units, offering whitespace beyond saturated tier-one markets.
- EU Green Deal alignment:REACH and RoHS frameworks limiting substance use in electrical components reward early compliance investments with accelerated market access across European channels.
Industry Challenges
- Dual certification timelines:Manufacturers targeting both domestic and export markets must sequence GB 4806, NSF, and CE marking approvals, stretching product launch windows.
- Precision temperature control IP:Advanced sensor systems and algorithmic heating curves face patent thickets in Japanese and North American markets, complicating technology licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Stew Pot Market |
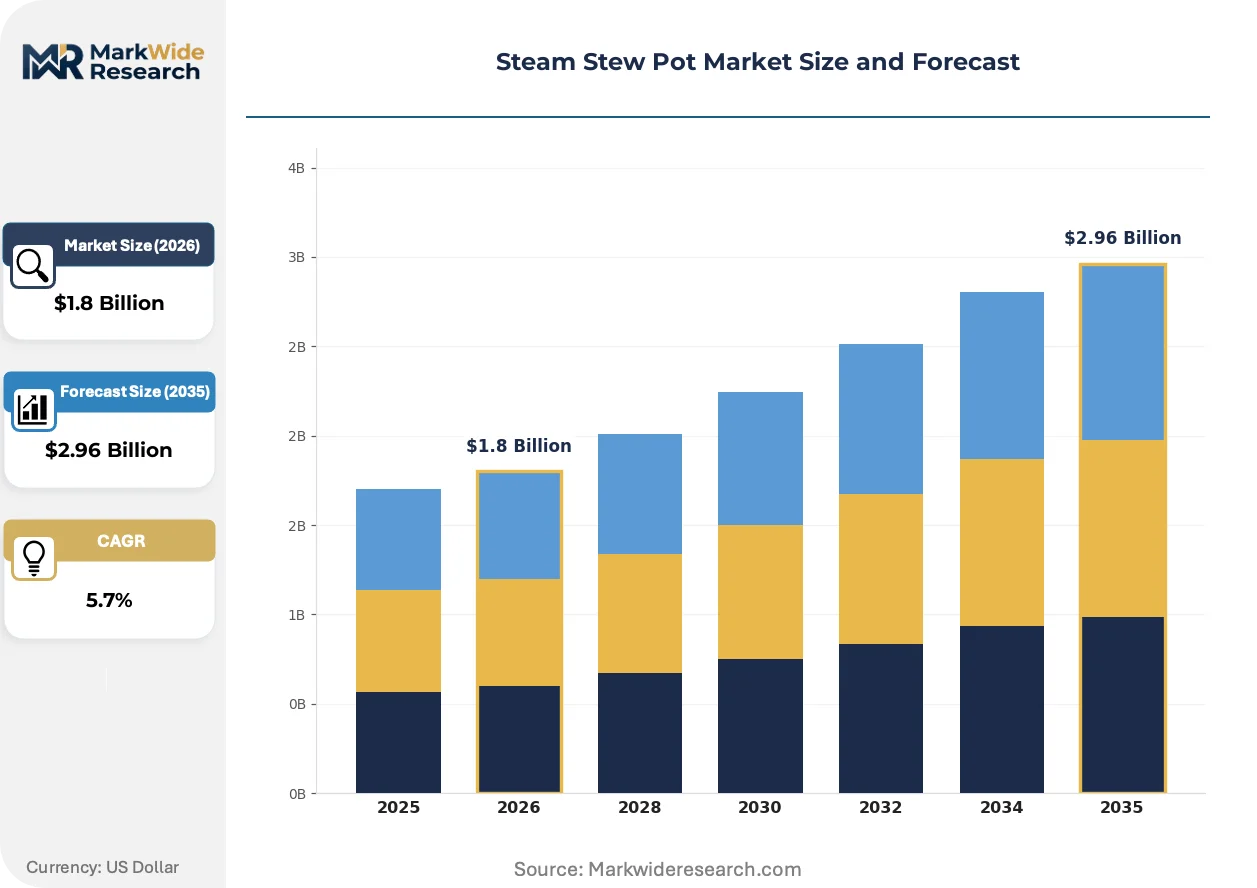
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Stovetop, Induction, Multi-Function Material: Stainless Steel, Aluminum, Non-Stick, Cast Iron Size: Small, Medium, Large, Extra Large End User: Home Cooks, Professional Chefs, Restaurants, Catering Services |
| Companies Covered | Buydeem, Morphy Richards, Midea, Bear, ZWILLING, SUPOR, Joyoung, Panasonic Corporation, Zojirushi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Stew Pot Market Trends and Innovations
Active reshaping in the steam stew pot market centers on convergence between precision cooking technology and regulatory compliance architecture, with manufacturers racing to embed smart features while meeting tightening material and energy standards.
Induction-ready multi-ply stainless steel construction is absorbing design priority across professional-grade product lines. Restaurant operators in China's tier-one cities are adopting these units at accelerated replacement cycles. The technology is absorbing market share from traditional cast iron models by delivering faster heat response and reduced energy consumption in high-throughput kitchens.
REACH substance restrictions and RoHS electrical component limits in Europe are tightening compliance thresholds for multi-function and induction product lines. Manufacturers must reformulate solder compositions and insulation materials to maintain CE marking eligibility. Export-bound producers in Guangdong and Zhejiang provinces are most affected, with qualification costs now embedded in unit economics.
County-level retail channels are displacing traditional distributor hierarchies as domestic brands build direct-to-store logistics. SUPOR and Midea are establishing captive distribution into China's lower-tier cities, bypassing wholesale intermediaries. This pattern is most visible in inland provinces where premium electric unit penetration lags coastal markets by several years.
Steam Stew Pot Market Segmentation
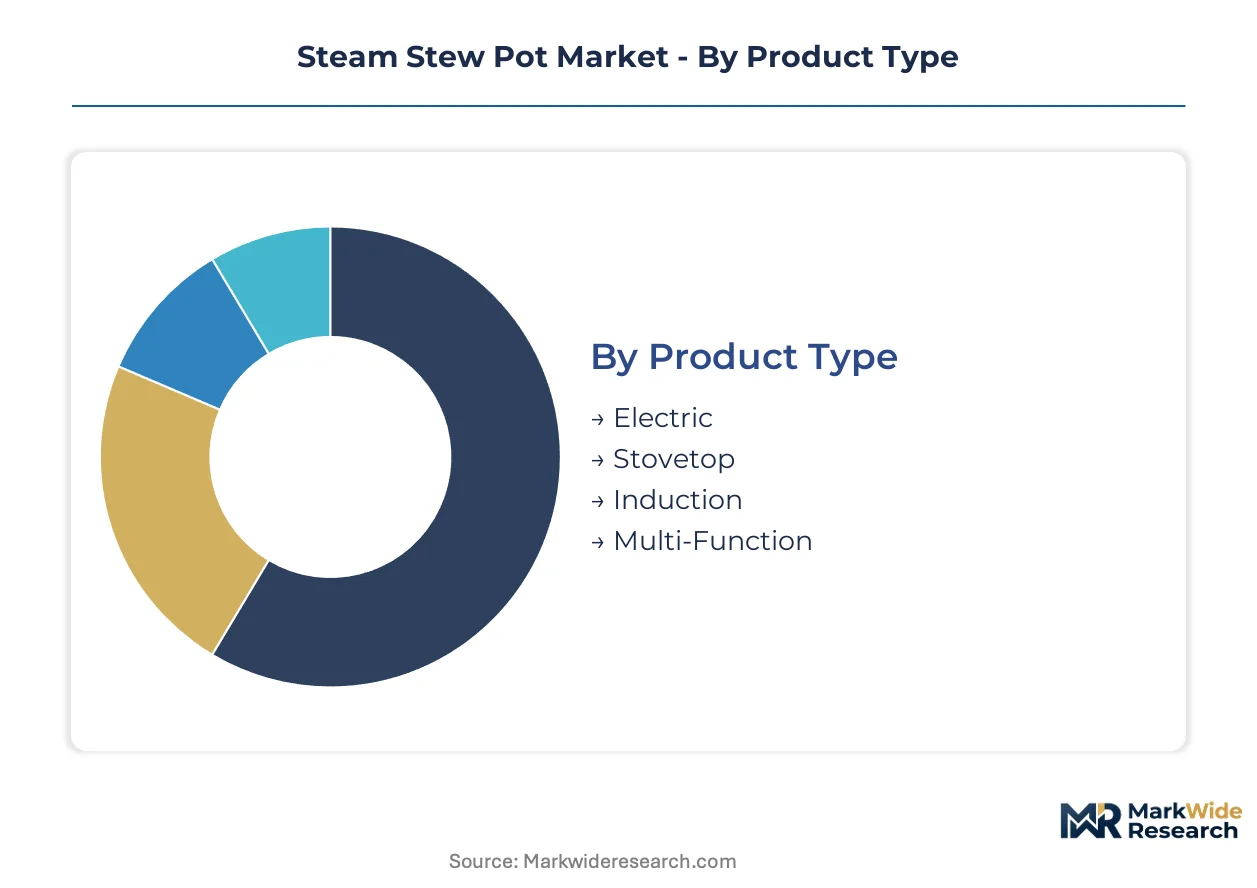
Steam stew pot purchasing decisions diverge sharply between replacement-driven residential upgrades and specification-driven commercial procurement. Understanding where programmable features, material grades, and capacity requirements concentrate across these divides shapes effective portfolio allocation.
Product Type:
Replacement cycles are shortening as kitchens trade basic stovetop units for programmable alternatives with timer and keep-warm functionality.
- Multi-Function:Programmable units integrating timer, keep-warm, and preset cooking modes command the widest margin pools. Commercial kitchens across Asia-Pacific expand procurement of these units as they replace basic stovetop models in restaurant upgrade cycles.
- Electric:Self-contained heating elements with thermostatic control enable precise temperature maintenance without stovetop dependency. China's tier-one cities concentrate residential demand as consumers seek countertop convenience in premium kitchen renovations.
- Stovetop:Traditional lidded vessels requiring external heat source remain the volume baseline. Entry-level households and cost-conscious foodservice operators in lower-tier markets sustain procurement.
- Induction:Ferromagnetic base constructions optimized for induction cooktop compatibility. Modern commercial kitchens specify these units for energy efficiency and rapid heat response.
Multi-function units sit at the top of the volume ranking, with electric models climbing the fastest as residential electrification accelerates.
Material:
Cost tiers separate professional-grade specifications from mass-market alternatives, with compliance certification acting as the primary sorting mechanism.
- Stainless Steel:Multi-ply construction with nickel-chromium alloys delivers NSF compliance and continuous-service durability. Professional kitchens prioritize these units where GB 4806 heavy metal migration limits and NSF standards govern supplier qualification.
- Cast Iron:Dense wall construction retains thermal mass for slow-simmering applications. Traditional cooking methods in residential and specialty restaurant segments sustain niche demand despite induction compatibility limitations.
- Aluminum:Lightweight, thermally conductive cores reduce unit weight and material cost. Budget residential segments and institutional foodservice procurement favor these constructions.
- Non-Stick:Coated interior surfaces simplify cleaning and reduce oil requirements. Health-conscious home cooks drive replacement demand, though coating durability concerns constrain commercial adoption.
Stainless steel captures the steepest expansion trajectory as professional channels prioritize compliance-certified durability.
Size:
Application scale dictates capacity requirements, with commercial throughput needs separating extra-large specifications from residential formats.
- Large:6-10 liter capacities serve extended-family residential cooking and small restaurant operations. China's county-level markets show rising penetration as distribution networks deepen.
- Extra Large:Vessels exceeding 10 liters accommodate high-volume catering and institutional foodservice. Banquet halls and central kitchens specify these units for batch production efficiency.
- Medium:3-5 liter formats dominate standard household replacement cycles. Nuclear family configurations across urban China sustain baseline volume.
- Small:Compact sub-3 liter units target single-person households and auxiliary cooking tasks. Premium apartment dwellers in dense urban centers drive incremental demand.
Large formats lead current volume, with extra-large units gaining share fastest as commercial catering expands.
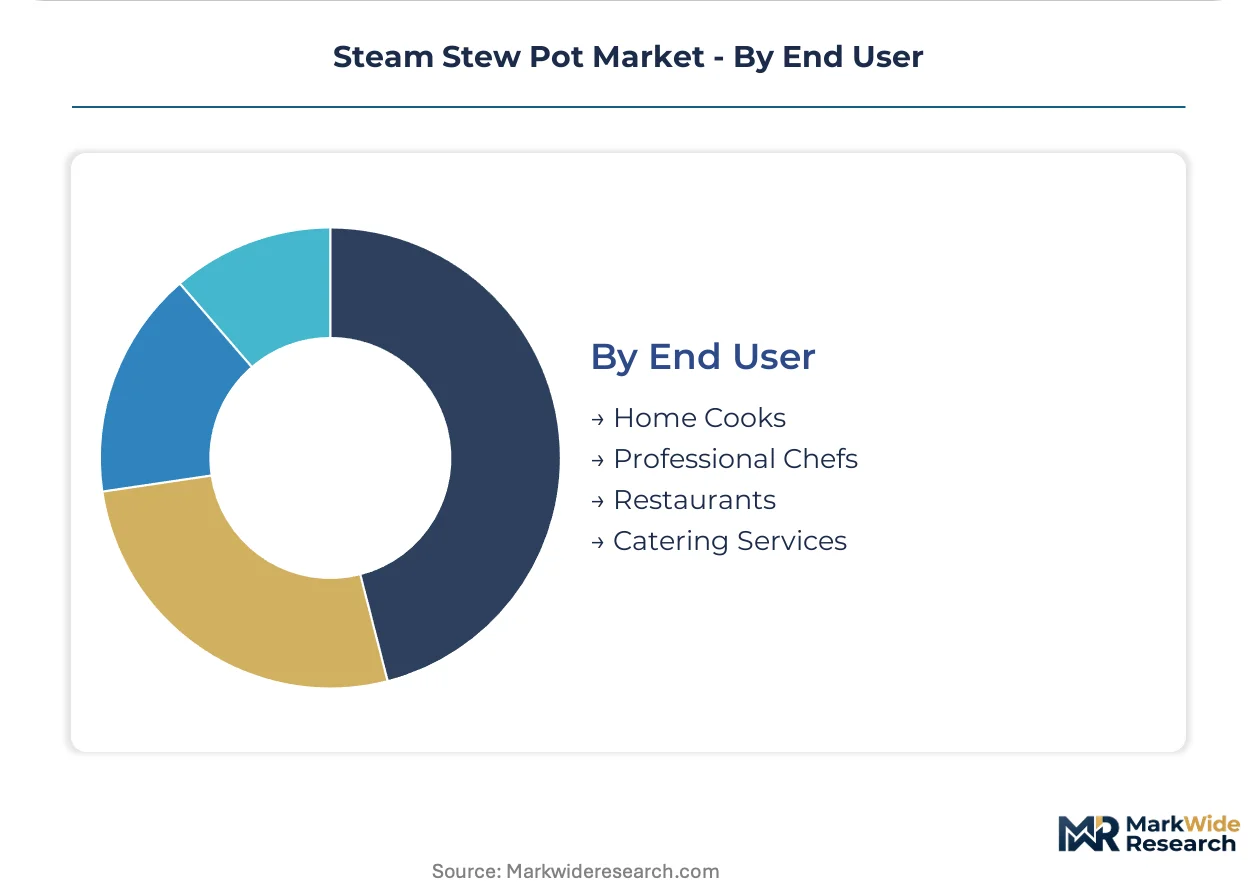
End User:
Customer type separates specification complexity, with professional procurement demanding certification documentation absent from residential transactions.
- Restaurants:High-throughput operators require NSF-compliant stainless steel with continuous-service warranties. China's tier-one cities concentrate replacement demand as kitchen upgrade cycles accelerate.
- Catering Services:Mobile and off-premise food operations prioritize durability and rapid heat recovery. Institutional contract caterers specify induction-compatible multi-ply constructions.
- Professional Chefs:Individual practitioners and culinary educators seek precision temperature control for technique development. Premium segments value Japanese and European sensor-enabled systems.
- Home Cooks:Residential consumers balance feature convenience against countertop footprint. Smart kitchen platform integration increasingly influences replacement decisions.
Restaurants anchor current volume leadership, with catering services expanding most quickly as off-premise dining formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping foundry location decisions as compliance cost differentials between China's GB standards and EU REACH protocols widen, prompting some export-bound producers to migrate toward jurisdictions with streamlined certification pathways.
China
Multi-function electric unit procurement accelerates across commercial kitchens in Shanghai, Beijing, and Guangzhou as restaurant upgrade cycles compress. SAMR enforcement of GB 4806 food-contact material standards restricts heavy metal migration in nickel-chromium alloys, elevating supplier qualification barriers. Foundry capacity concentrates in Guangdong and Zhejiang provinces where certified domestic producers are decoupling from low-margin OEM contracts.
Japan
Precision temperature control systems command premium positioning among professional chefs and culinary educators in Tokyo and Osaka metropolitan areas. METI energy-efficiency labeling requirements shape product development priorities for domestic manufacturers. Nagoya-based industrial clusters anchor sensor-enabled heating technology production for North American export channels.
Germany
REACH substance restrictions and RoHS electrical component limits tighten compliance thresholds for multi-function product lines entering European distribution. ECHA enforcement actions against non-compliant solder compositions accelerate reformulation investments. Industrial fabricators in North Rhine-Westphalia and Bavaria dominate CE marking certification services for Asia-origin manufacturers.
United States
NSF-compliant stainless steel specifications govern procurement decisions across high-throughput restaurant operators and institutional foodservice channels. FDA food-contact material oversight intersects with state-level energy efficiency mandates in California and New York. Distribution networks concentrate around Chicago and Los Angeles logistics hubs serving regional catering expansion.
South Korea
Smart kitchen platform integration drives residential replacement demand in Seoul Capital Area premium apartment developments. MFDS food-contact safety standards align with EU frameworks, reducing dual-certification burdens for export-oriented producers. Busan-Ulsan industrial corridors host induction-compatible base construction specialists supplying Japanese and North American channels.
Steam Stew Pot Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart-feature differentiation and platform ecosystem integration. Market structure exhibits moderate consolidation with three to five dominant domestic champions in major Asian markets alongside specialized premium exporters. Strategic archetypes include ecosystem-integrated appliance conglomerates, precision-control technology specialists, and certified foundry-to-brand vertical integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology licensing agreements accelerating sensor-enabled feature deployment.
Among China-based appliance conglomerates, Midea and SUPOR exemplify ecosystem-integrated archetypes leveraging captive distribution networks. Zojirushi Corporation occupies a position within the precision-control specialist tier, anchoring premium positioning through Japanese and North American channel presence. These three entities represent contrasting strategic vectors: scale-driven platform integration, county-level retail penetration, and sensor-technology premiumization.
| Leading Market Players |
|---|
| Buydeem |
| Morphy Richards |
| Midea |
| Bear |
| ZWILLING |
| SUPOR |
| Joyoung |
| Panasonic Corporation |
| Zojirushi Corporation |
| Others |
Pricing and Supply Chain Analysis
Nickel-chromium alloy costs cascade through multi-ply stainless steel fabrication into three distinct buyer tiers, with GB 4806-certified foundries in Guangdong and Zhejiang provinces capturing premium positioning while uncertified competitors absorb margin compression in spot-market transactions.
Pricing Analysis
Distributor markups separate NSF-compliant stainless steel units bound for professional kitchens from basic stovetop models moving through wholesale channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with tier-one city restaurant operators showing lowest price sensitivity due to warranty and durability requirements. Cost compression in mid-tier electric units is intensifying because SAMR enforcement timelines are compressing product launch windows. County-level retail channels exhibit highest price sensitivity as distribution networks penetrate inland provinces.
Supply Chain Analysis
GB 4806 qualification gates access to China's domestic foodservice procurement, filtering supplier pools toward certified foundries in Guangdong and Zhejiang provinces. Raw material feeds from Indonesian nickel smelters and domestic chromium refiners rest on maritime logistics routes through South China Sea chokepoints. Single-source vulnerability concentrates in induction-compatible base construction capacity clustered around Busan-Ulsan corridors. Distribution runs through captive retail networks established by appliance conglomerates and independent distributor hierarchies serving fragmented county-level markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where SAMR's tightening GB 4806 enforcement creates replacement demand cycles as non-compliant inventory exits commercial channels.
For Market Incumbents: Deepen backward integration into certified foundry capacity to lock in nickel-chromium alloy supply ahead of qualification bottlenecks. Secure captive distribution in county-level retail channels before emerging appliance brands establish logistics footholds. Prioritize dual-certification sequencing for CE marking and NSF compliance to accelerate European and North American market access. For New Entrants and Emerging Players: Direct-to-consumer e-commerce routes offer lowest barrier entry for smart-featured electric units targeting premium apartment households in Seoul Capital Area and Tokyo metropolitan zones. County-level markets in China's inland provinces remain most penetrable whitespace given underdeveloped premium electric unit distribution. Position around smart kitchen platform integration as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision-control technology specialists because patent thickets in Japanese and North American markets create acquisition scarcity for sensor-enabled heating systems. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than feature differentiation alone. Monitor ECHA enforcement actions against non-compliant solder compositions as the inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Kitchen Platform Integration | Midea's appliance ecosystem demonstrates bundling potential with connected cooking environments. |
| Dual-Certification Investment | Sequencing GB 4806 with NSF and CE marking approvals accelerates multi-regional product launches. |
| County-Level Distribution Buildout | SUPOR's captive logistics into lower-tier cities captures whitespace beyond saturated coastal markets. |
| Precision Temperature Control R&D | Zojirushi's sensor-enabled systems command premium positioning in professional chef segments. |
| Induction-Compatible Base Development | Busan-Ulsan industrial clusters anchor ferromagnetic construction for modern commercial kitchen specifications. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with commercial kitchen procurement managers, appliance brand product directors, GB certification auditors, and nickel alloy sourcing specialists were validated against secondary sources including SAMR regulatory filings, ECHA substance restriction updates, NSF certification databases, and customs trade records for stainless steel cookware categories.
Historical replacement cycle analysis across restaurant upgrade waves and residential electrification trends informs the projection framework. Segmentation dimensions span product type, material grade, capacity tier, and end-user archetype across the analysis window. CAGRs derive from fitted trendlines calibrated to observed procurement elasticity in tier-one city commercial channels and county-level retail penetration rates.
The model assumes a particular technology adoption path; alternative pathways for induction-compatible multi-ply construction would alter the outlook if cast iron thermal retention experiences unexpected resurgence in traditional cooking segments. Forecasts reflect assumptions about SAMR enforcement consistency and nickel price volatility bands. A model refresh is warranted upon material change in ECHA REACH substance restriction scope or GB 4806 heavy metal migration limit revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Chile Food Delivery Market
Food Service
Bangladesh Food Service Market
Food Service
Food Service Disposables Market
Food Service
US Healthcare/Hospital Food Services Market
Food Service
United States Foodservice Market
Food Service
Commercial Sink Market
Food Service
Food Truck Services Market
Food Service
Australia Foodservice Market
Food Service
India Online Grocery Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Bottled Water Cooler Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Food Service Market
Food Service
Smoker Grill Market
Food Service
Food Logistics Market