
 Middle East and Africa Electric Vehicle Battery Materials Market | 2026-2036
Middle East and Africa Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Electric Vehicle Battery Materials Market Insights
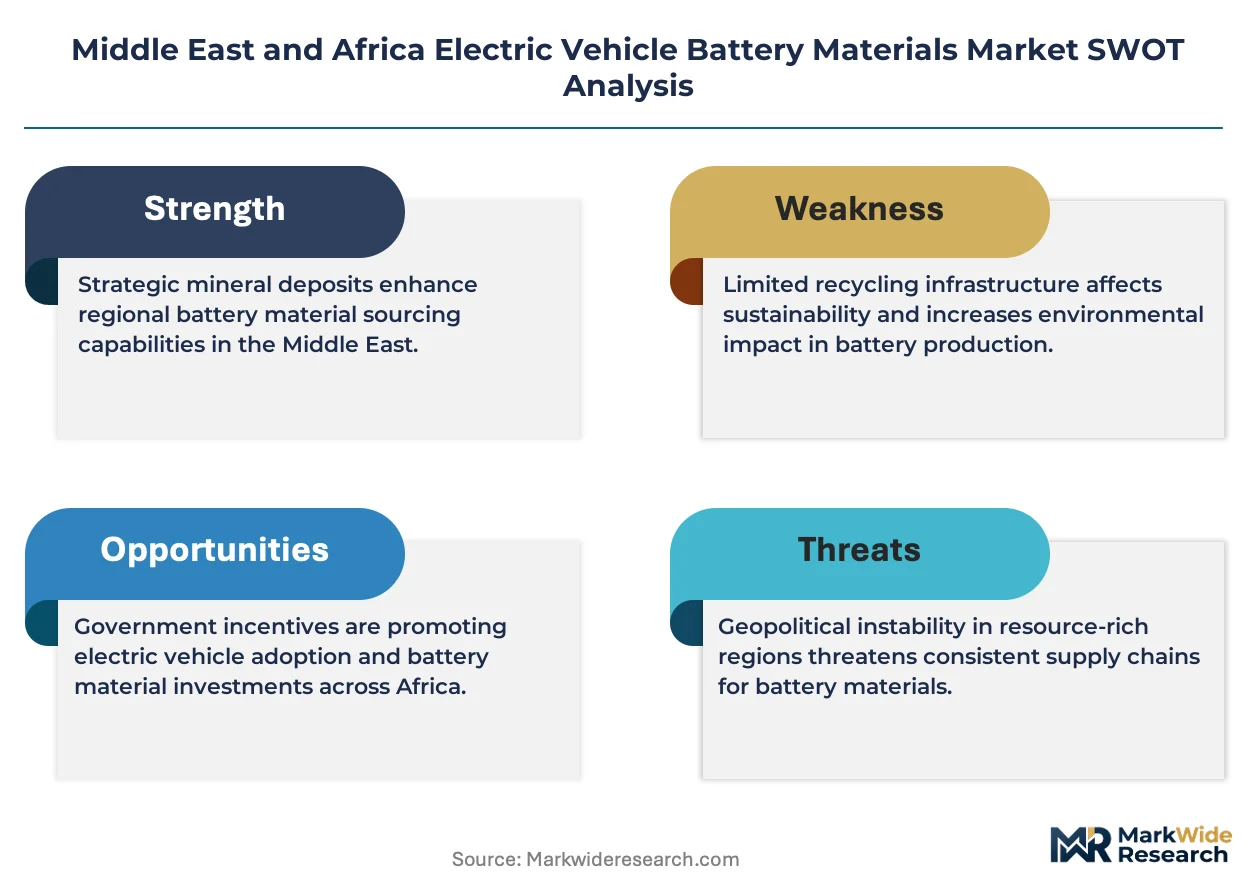
High-nickel cathode specifications are redrawing procurement priorities across the Middle East and Africa Electric Vehicle Battery Materials Market. Umicore SA leverages its precursor synthesis expertise to anchor supply relationships with regional cell producers. Anglo American Platinum dominates platinum group metal recovery streams that sustain local catalyst-to-battery material pathways. BASF SE competes through controlled distribution of electrolyte additives calibrated for hot-climate degradation profiles.
Middle East and Africa Electric Vehicle Battery Materials encompass refined active powders, current collectors, separators, and electrolyte formulations engineered to store and transfer electrochemical energy within lithium-ion architectures, with nickel-cobalt-manganese ratios and thermal stability thresholds determining cycle life in ambient temperatures exceeding 40°C. The primary commercial purpose centers on enabling rechargeable energy storage for electric drivetrains deployed across passenger vehicles, commercial trucks, buses, and two-wheelers. Lithium and nickel material types command the dominant volume positions given their structural role in high-energy-density cathodes, while LFP battery chemistry segments expand fastest among fleet operators prioritizing thermal safety and extended cycle counts in desert operating conditions. OEM end users concentrate margin capture through captive offtake agreements, whereas aftermarket providers occupy fragmented service layers with shorter contract durations.
South Africa's Department of Mineral Resources and Energy enforces beneficiation requirements on platinum group metal exports that shape local precursor processing investments, while Morocco's investment promotion agency aligns automotive sector incentives with EU Green Deal battery passport traceability standards. Saudi Arabia's dual carbon goals and industrial localization mandates under Vision 2030 are redirecting petrochemical capital toward cathode active material pilot facilities. Stakeholders must monitor how Gulf sovereign wealth deployment into African mining concessions reshapes raw material access terms before committing to fixed-price offtake structures.
Market Dynamics
Fleet electrification mandates across Gulf Cooperation Council states are compressing cathode material procurement timelines, forcing suppliers to pre-position inventory before beneficiation infrastructure matures.
Growth Catalysts
- Saudi Vision 2030 industrial localization:Sovereign capital reallocation toward cathode active material pilot facilities creates captive demand for regional precursor synthesis capacity.
- EU Green Deal battery passport traceability:Moroccan automotive sector incentives align with European import standards, accelerating Tangier-Med corridor investment in certified material streams.
- High-nickel cathode chemistry penetration:Urban logistics operators specify NCM 811 formulations for commercial trucks operating above 40°C ambient thresholds.
Market Restraints
- Platinum group metal beneficiation bottlenecks:South Africa's Department of Mineral Resources and Energy export requirements delay precursor processing capacity scaling despite raw ore availability.
- Lithium hydroxide import dependency:Spodumene concentrate flows through concentrated Asian refining corridors, exposing regional cell producers to tolling margin volatility.
- Desert thermal degradation profiles:Electrolyte additive formulations require 30-40% higher loading than temperate climate specifications, compressing pack-level energy density targets.
Strategic Opportunities
- East African lithium pegmatite development:Zimbabwe and DRC hard-rock deposits offer alternative spodumene supply routes outside South American brine dominance.
- Second-life battery material recovery:Bus fleet operators in Cairo and Lagos generate predictable retired pack volumes for hydrometallurgical black mass processing.
- Gulf sovereign wealth mining concession deployment:Pre-emptive offtake structuring before African raw material access terms reset.
Industry Challenges
- Electrochemical engineer scarcity:Regional universities lack specialized battery materials curricula, forcing producers to recruit from Asian cell manufacturing hubs at premium compensation.
- Hot-climate validation timelines:UN 38.3 and UN ECE R100 certification protocols require extended thermal cycling data from regional testing facilities with limited capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Electric Vehicle Battery Materials Market |
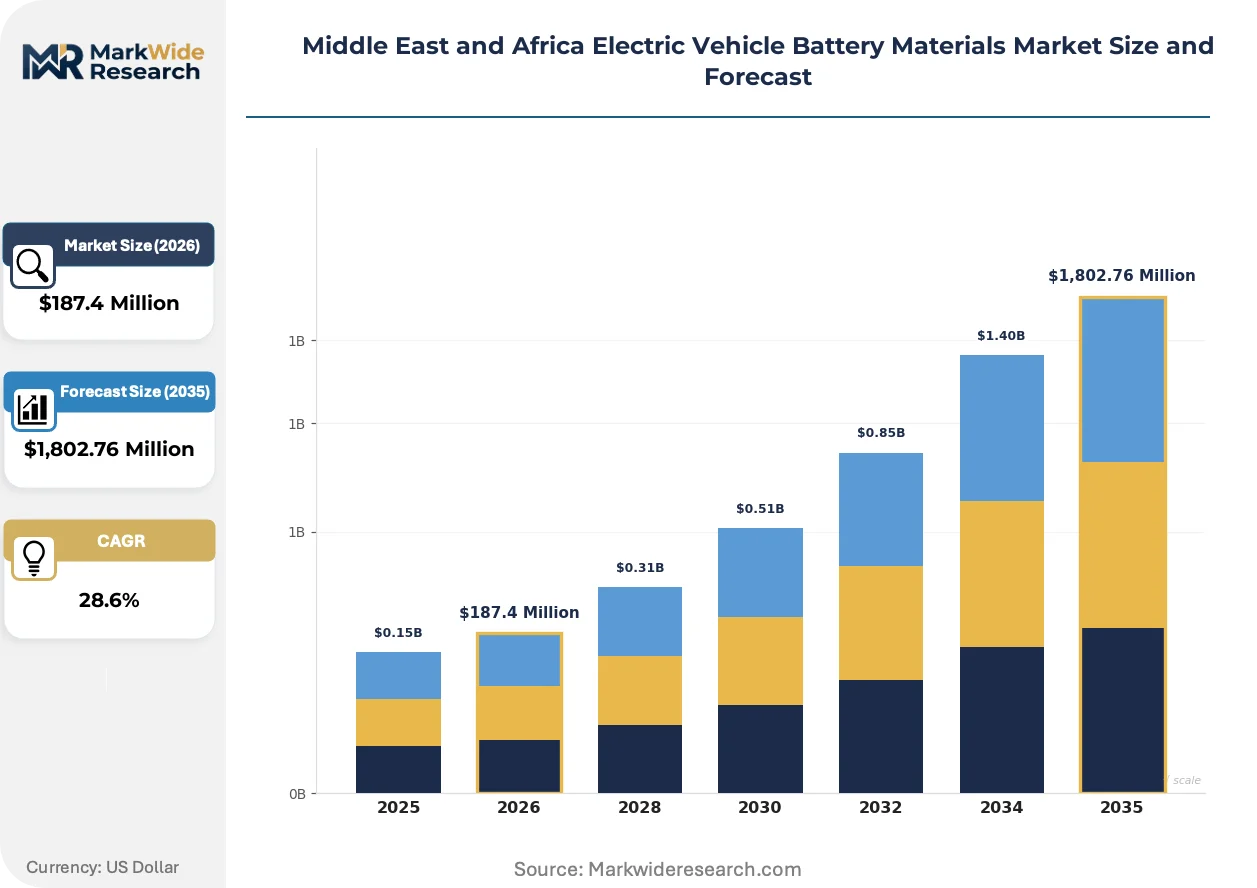
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium, Cobalt, Nickel, Manganese Battery Chemistry: LFP, NMC, NCA, LTO End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Application: Passenger Vehicles, Commercial Trucks, Buses, Two-Wheelers |
| Companies Covered | Middle East Battery Company, Umicore SA, Targray Technology International Inc, Arkema SA, Sumitomo Chemical Co Ltd, BASF SE, SGL Carbon, Anglo American Platinum, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Electric Vehicle Battery Materials Market Trends and Innovations
Solid-state electrolyte architectures and silicon-anode formulations are converging to redefine thermal management requirements for battery materials deployed across Middle Eastern and African operating environments.
Silicon-carbon composite anodes are miniaturizing conventional graphite loadings in high-energy cells destined for premium passenger electric vehicles. Regional OEMs in the UAE and Saudi Arabia specify 10-15% silicon content for 2026 model year launches. This substitution is miniaturizing pack footprint requirements while demanding novel binder chemistries to accommodate 300% volume expansion during lithiation.
South Africa's beneficiation enforcement on platinum group metal exports is restructuring cathode precursor supply geography. Local refiners must achieve 30% value-add thresholds before export authorization. This policy compresses investment timelines for integrated pgm-to-precursor facilities serving regional NCM cathode production.
Long-term service contracts are displacing spot procurement for cathode active materials among municipal bus operators. Cairo Transport Authority and Riyadh Bus now structure 7-10 year material supply agreements with price collars indexed to London Metal Exchange nickel futures. This contractual evolution concentrates supplier qualification leverage with fleet procurement departments rather than cell manufacturer purchasing teams.
Middle East and Africa Electric Vehicle Battery Materials Market Segmentation
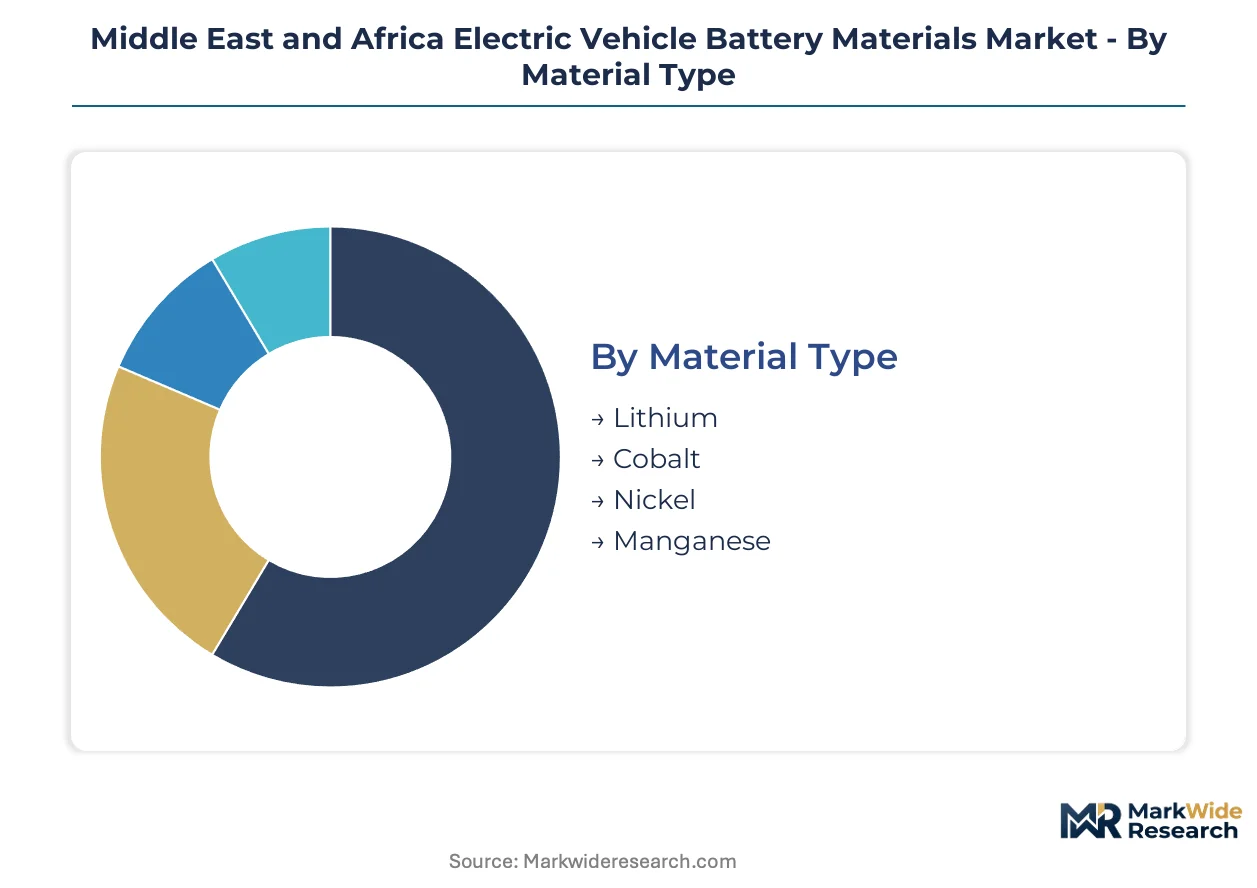
Material specification choices in the Middle East and Africa Electric Vehicle Battery Materials Market determine thermal resilience thresholds and procurement contract structures. Fleet operators and OEMs segment demand through chemistry selection, end-user integration depth, and vehicle application duty cycles.
Material Type:
Highest margin capture concentrates in refined nickel products given precursor synthesis complexity and beneficiation bottlenecks.
- Nickel:High-purity nickel sulfate and hydroxide feed high-nickel cathode specifications for commercial trucks operating above 40°C ambient. South Africa's beneficiation enforcement on platinum group metal exports is restructuring local precursor supply geography and compressing investment timelines.
- Lithium:Lithium hydroxide and carbonate compounds form the electrochemical foundation for all lithium-ion architectures. Spodumene concentrate flows through concentrated Asian refining corridors, exposing regional cell producers to tolling margin volatility and supply interruption risks.
- Cobalt:Cathode stabilizer in NCM ratios, sourced primarily through DRC mining concessions with Gulf sovereign wealth deployment reshaping access terms.
- Manganese:Cost-effective cathode dopant in LFP and medium-nickel NCM formulations, with lower purity requirements than nickel or cobalt.
Nickel holds installed capacity. Lithium is rotating up the share rankings.
Battery Chemistry:
Application thermal profiles and cycle life requirements determine chemistry selection across the region's divergent operating environments.
- LFP:Lithium iron phosphate formulations prioritize thermal safety and extended cycle counts in desert operating conditions. Fleet operators across Cairo and Riyadh bus networks specify LFP for predictable 7-10 year service contracts with municipal procurement departments.
- NMC:Nickel-manganese-cobalt layered oxides, particularly NCM 811 ratios, deliver highest energy density for premium passenger vehicles. Urban logistics operators in UAE and Saudi Arabia specify these formulations for commercial trucks despite higher electrolyte additive loading requirements.
- NCA:Nickel-cobalt-aluminum cathodes occupy niche positions in high-performance applications with limited regional adoption.
- LTO:Lithium titanate anode systems enable extreme fast-charging for bus depot operations with reduced energy density tradeoffs.
LFP dominates fleet procurement volumes. NMC is climbing the fastest in commercial truck specifications.
End User:
Contract duration and qualification leverage vary sharply between captive OEM offtake and fragmented aftermarket service layers.
- OEMs:Original equipment manufacturers concentrate margin capture through multi-year cathode active material offtake agreements with price collars indexed to London Metal Exchange nickel futures.
- Fleet Operators:Municipal and commercial fleet procurement departments now structure direct material supply agreements, bypassing cell manufacturer purchasing teams.
- Tier-1 Suppliers:Cell producers and pack integrators occupy intermediate positions with shorter contract durations and higher supplier switching frequency.
- Aftermarket Providers:Fragmented service layers address replacement cell demand with limited forward contract visibility and spot procurement dominance.
OEMs hold pricing power through scale. Fleet operators are rotating up the share rankings via direct contracting.
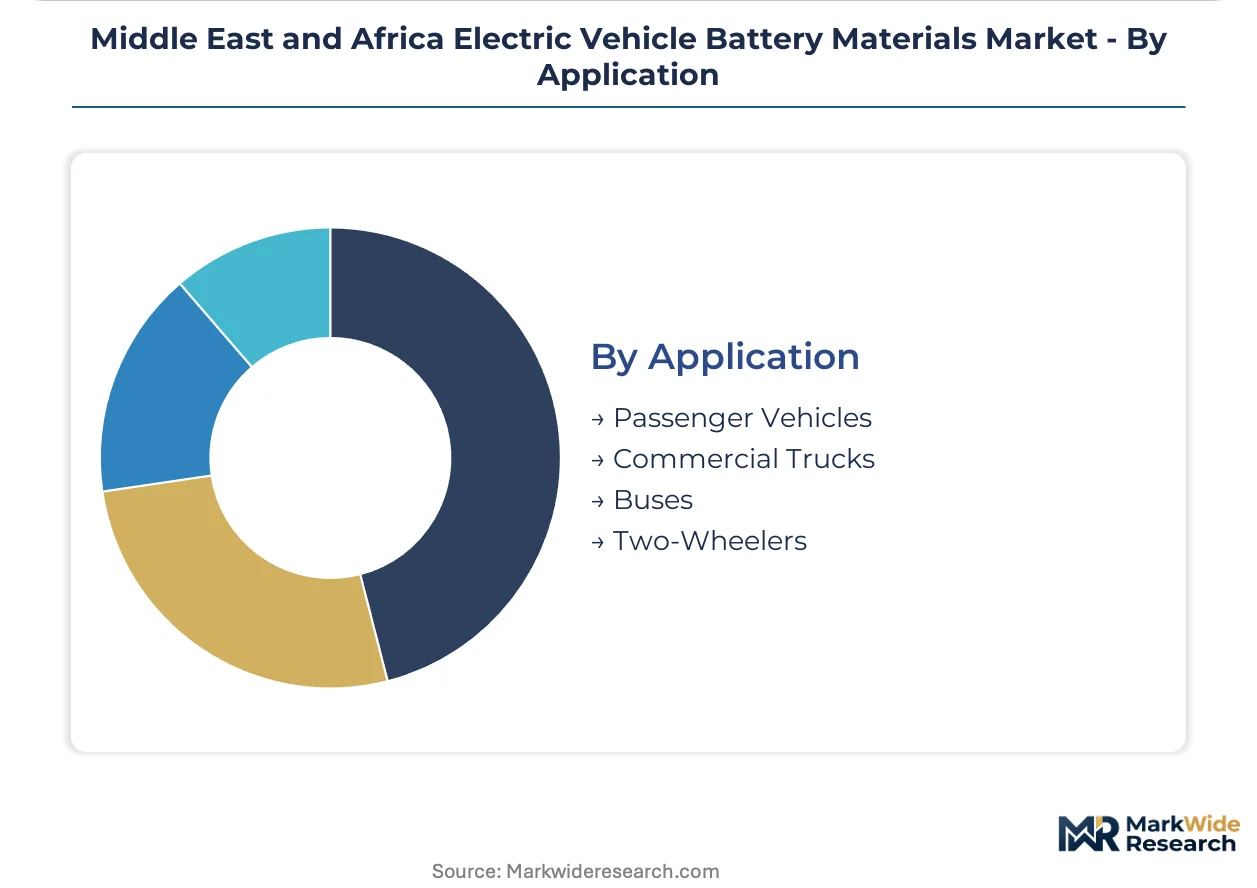
Application:
Duty cycle intensity and thermal exposure duration create divergent material performance requirements across vehicle categories.
- Commercial Trucks:Heavy-duty urban logistics vehicles impose sustained high-current discharge profiles and regenerative braking stress. NCM 811 specifications with enhanced electrolyte additive loading address 40°C-plus ambient operating thresholds.
- Buses:Predictable route profiles and depot charging infrastructure enable LFP chemistry dominance with second-life recovery potential for retired pack volumes.
- Passenger Vehicles:Premium segments in UAE and Saudi Arabia specify silicon-carbon composite anodes with 10-15% silicon content for footprint miniaturization.
- Two-Wheelers:Cost-sensitive applications prioritize LFP standardization with simplified thermal management requirements.
Commercial trucks hold technology specification leadership. Buses are rotating up the share rankings through fleet electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in processed cathode materials are redirecting investment flows across the Middle East and Africa. Regional governments deploy beneficiation mandates and industrial localization incentives to capture value-add stages previously concentrated in Asian refining corridors.
Saudi Arabia
Vision 2030 sovereign capital reallocation is funding cathode active material pilot facilities near Jubail Industrial City. SFDA and the Ministry of Industry and Mineral Resources coordinate battery-grade chemical licensing frameworks. NEOM's manufacturing zone is attracting precursor synthesis investments from European technology licensors seeking desert-climate validation sites.
Morocco
Automotive sector incentives from the Moroccan Investment and Export Development Agency align with EU Green Deal battery passport traceability requirements. Tangier-Med port infrastructure supports certified material stream exports to European cell manufacturers. Renault's local assembly operations are generating captive demand for regional cathode precursor supply.
South Africa
The Department of Mineral Resources and Energy enforces 30% value-add thresholds on platinum group metal exports, compressing timelines for integrated pgm-to-precursor facilities. Bushveld Complex mining concessions feed local beneficiation investments. Anglo American Platinum's refining operations anchor catalyst-to-battery material pathways for regional NCM cathode production.
United Arab Emirates
Dubai's commercial truck electrification mandates and Riyadh's municipal bus procurement are creating concentrated demand for hot-climate battery specifications. MOHAP and the Emirates Authority for Standardization and Metrology coordinate thermal testing protocols. Jebel Ali industrial zone hosts electrolyte additive blending operations calibrated for 40°C-plus ambient degradation profiles.
Egypt
Cairo Transport Authority's 7-10 year material supply agreements are establishing direct fleet-operator contracting precedents. The General Authority for Investment and Free Zones negotiates industrial zone incentives for cell assembly operations. Suez Canal Economic Zone positioning targets European market access for processed active materials.
Middle East and Africa Electric Vehicle Battery Materials Market Competitive Landscape
Listed leaders compete with private specialists across precursor synthesis and materials recovery segments. The vendor base spans Belgian chemical conglomerates, Japanese trading houses, and South African mining-integrated refiners. Three archetypes dominate: diversified chemical majors with electrolyte additive portfolios, platinum group metal miners with beneficiation mandates, and specialized carbon material producers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers pre-position inventory before regional beneficiation infrastructure matures.
Within the diversified chemical tier, Umicore SA and BASF SE exemplify European-listed players leveraging precursor synthesis expertise to anchor supply relationships with regional cell producers. Anglo American Platinum occupies a distinct position as a mining-integrated refiner subject to South African beneficiation requirements. These three companies represent the convergence of chemical processing capability and raw material access that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Middle East Battery Company |
| Umicore SA |
| Targray Technology International Inc |
| Arkema SA |
| Sumitomo Chemical Co Ltd |
| BASF SE |
| SGL Carbon |
| Anglo American Platinum |
| Mitsubishi Chemical Group Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day cathode precursor lead times concentrate pricing leverage with Asian tolling houses, compressing regional cell producers into long-term offtake structures before local beneficiation infrastructure matures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with collars indexed to London Metal Exchange nickel futures. Price differentiation hinges on battery passport certification grade and volume scale commitments. Cost compression in standard-grade cathode materials intensifies as Moroccan automotive corridor capacity scales. Fleet procurement departments exhibit highest price sensitivity due to municipal budget constraints, while premium passenger OEMs absorb thermal stability premiums.
Supply Chain Analysis
Strategic stockpiling of spodumene concentrate supersedes just-in-time preferences given Asian refining corridor concentration and tolling margin volatility. Raw material flows draw from South African platinum group metal deposits, Zimbabwean hard-rock lithium pegmatites, and DRC cobalt concessions. Single-source vulnerability permeates lithium hydroxide supply given concentrated Asian refining. Distribution runs through Tangier-Med port infrastructure for EU-facing certified material streams and Jebel Ali industrial zone for Gulf domestic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story underpinned by Gulf sovereign wealth deployment into African mining concessions reshaping raw material access terms.
For Market Incumbents: Fortify precursor synthesis capacity in Morocco's Tangier-Med corridor ahead of EU Green Deal battery passport enforcement. Secure captive offtake with Saudi Vision 2030 cathode pilot facilities to preempt emerging trading house entrants. Deepen backward integration into Zimbabwean spodumene concessions to offset Asian tolling dependency. For New Entrants and Emerging Players: UN ECE R100 certification fast-tracks unlock municipal bus fleet procurement in Cairo and Riyadh where direct material supply agreements displace cell manufacturer intermediaries. Target LFP chemistry segments for desert thermal safety specifications. Pursue hydrometallurgical black mass recovery partnerships with Lagos and Cairo operators. For Investors and Strategic Acquirers: Long-term, this sits as a beneficiation infrastructure play because South African Department of Mineral Resources and Energy enforcement creates forced localization economics. Acquire integrated pgm-to-precursor refiners with 30% value-add thresholds already achieved. Watch Gulf sovereign wealth mining concession deployment velocity as inflection indicator for raw material access term resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into African Lithium Pegmatites | Zimbabwean and DRC hard-rock deposits reduce Asian spodumene tolling dependency for regional cell producers. |
| EU Battery Passport Certification Investment | Moroccan Investment and Export Development Agency incentives align Tangier-Med corridor with European import standards. |
| Long-Term Cathode Offtake Structuring | Cairo Transport Authority and Riyadh Bus 7-10 year agreements concentrate supplier qualification leverage with fleet procurement. |
| Hot-Climate Electrolyte Additive Blending | MOHAP-coordinated protocols in Jebel Ali address 40°C-plus ambient degradation profiles for Gulf commercial trucks. |
| Second-Life Battery Material Recovery | Predictable retired pack volumes from Cairo and Lagos bus fleets feed hydrometallurgical black mass processing capacity. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings across this analysis. Plant managers at cathode active material facilities, procurement leads at Gulf fleet operators, technical R&D directors at electrolyte additive blenders, and distribution channel partners across Tangier-Med and Jebel Ali provided operational ground-truth. Secondary sources include South African Department of Mineral Resources and Energy beneficiation enforcement records, EU Green Deal battery passport traceability standards, Saudi Vision 2030 industrial localization disclosures, and customs trade data for spodumene concentrate flows. Bottom-up capacity build-up and top-down demand absorption triangulation validate segment-level outputs.
Sensitivity analysis across nickel price volatility bands, beneficiation enforcement timelines, and fleet electrification mandate acceleration scenarios stress-tests projection robustness. Segmentation dimensions span material type, battery chemistry, end-user integration depth, and vehicle application duty cycles. CAGRs derive from installed capacity build-out schedules, offtake contract visibility, and thermal stability specification penetration curves. Hot-climate validation timelines and electrochemical engineer scarcity constraints inform supply-side elasticity assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained Gulf sovereign wealth deployment and South African beneficiation enforcement continuity; material deviation would warrant model refresh. Revision becomes warranted when lithium hydroxide import dependency ratios or platinum group metal export authorization delays cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
EV Battery Cells Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Canada Electric Vehicle Battery Electrolyte Market
EV Batteries
EV Battery Water Cold Plates Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Auto Storage Battery Market
EV Batteries
France EV Battery Pack Market