
 Electric Vehicle Battery Thermal Management Systems Market | 2026-2036
Electric Vehicle Battery Thermal Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Battery Thermal Management Systems Market Intelligence
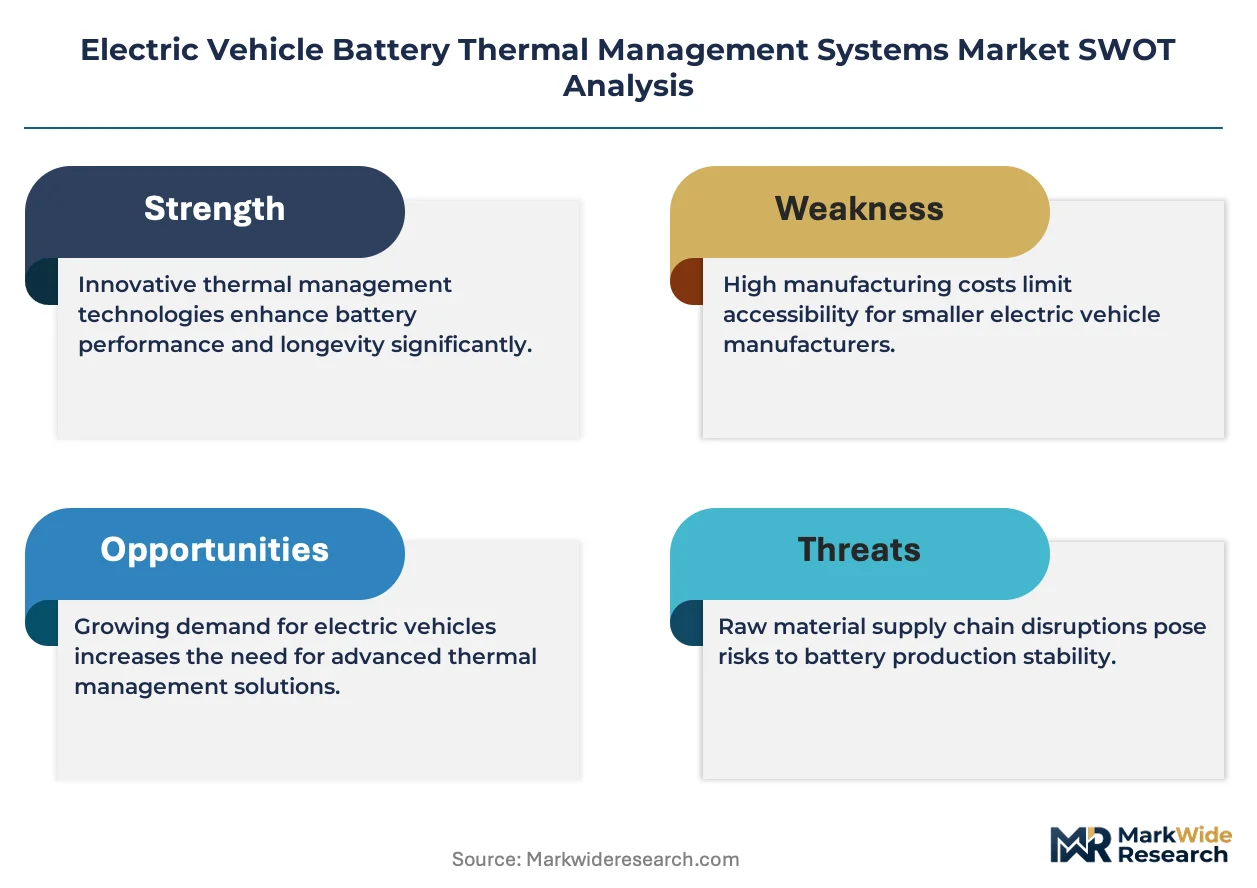
Software-defined thermal calibration is decoupling hardware sales from lifetime performance guarantees, shifting vendor economics toward recurring revenue models. Robert Bosch GmbH leverages its embedded control software stack to anchor long-term service contracts with European OEMs. Continental AG competes through integrated sensor-to-actuator architectures that reduce pack-level assembly complexity.
Electric vehicle battery thermal management systems regulate cell operating temperatures through liquid coolant loops, phase change material layers, or forced air channels to prevent thermal runaway and preserve cycle life. Liquid cooling dominates passenger car platforms due to its heat flux capacity exceeding 500 W per cell group, while phase change materials gain traction in compact two-wheeler packs where space constraints limit active circulation. Control units and sensors capture expanding margin pools as OEMs demand predictive thermal algorithms that preempt degradation rather than react to overtemperature events.
The EU Battery Regulation and China's GB standards mandate traceable thermal performance data across cell lifecycles, forcing suppliers to embed logging capabilities. EPA tailpipe rules and NHTSA battery safety investigations in the United States further tighten validation requirements for thermal runaway propagation resistance. Stakeholders must weigh capital allocation between next-generation coolant chemistry and control software that extends hardware replacement intervals.
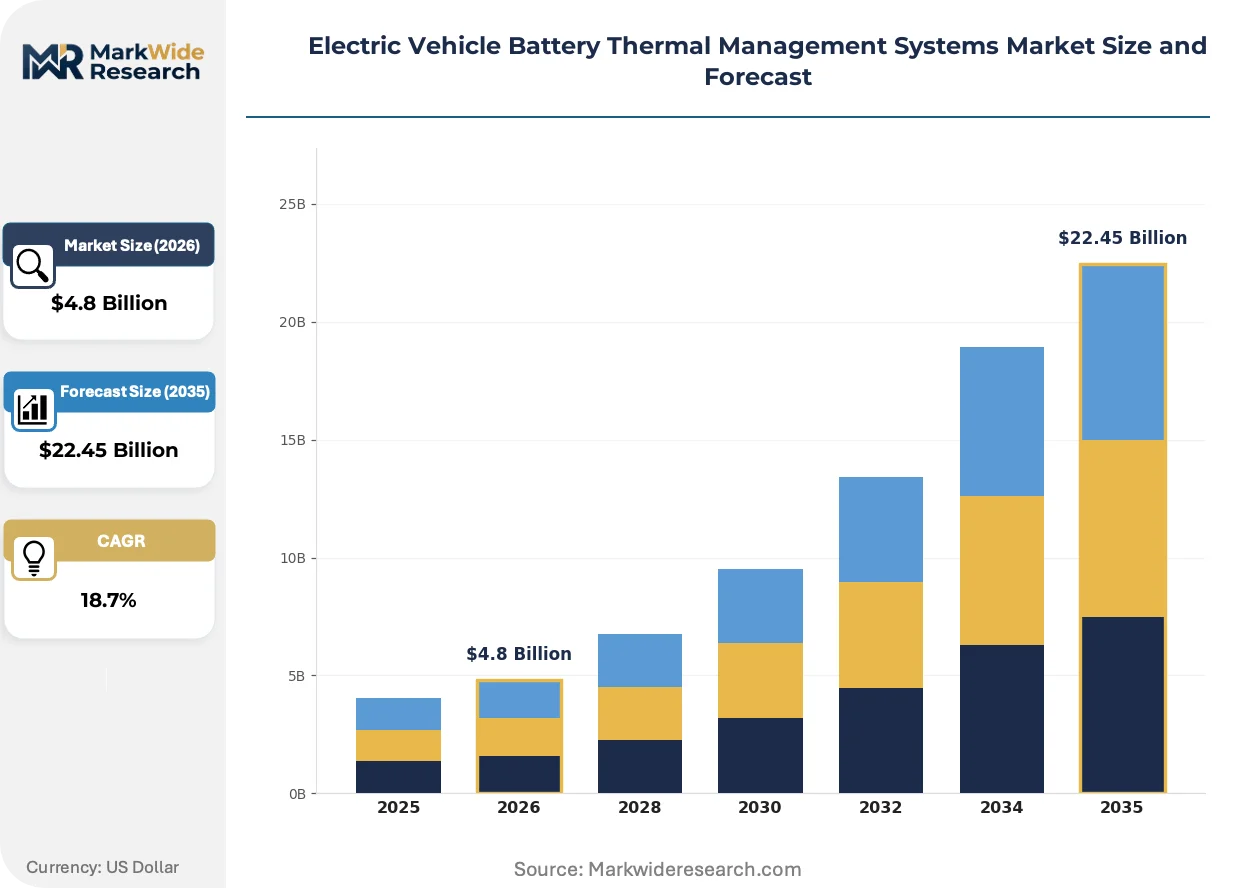
Market Dynamics
Passenger car OEM procurement of liquid-cooled battery packs is accelerating as GB standards and EU Battery Regulation tighten energy density and thermal runaway propagation mandates, compressing validation timelines and forcing hardware-software integration investments.
Growth Catalysts
- China's NEV subsidy regime:Tiered incentives for precision thermal control hardware are pulling cell gigafactory investments toward liquid-cooled architectures with embedded logging capabilities.
- EU battery passport requirements:Traceable thermal performance data mandates across cell lifecycles are forcing suppliers to embed sensor-to-actuator architectures that capture expanding margin pools.
- Passenger car electrification:Heat flux demands exceeding 500 W per cell group are displacing air-cooled designs in favor of active circulation systems with predictive thermal algorithms.
Market Restraints
- Coolant chemistry supply concentration:Fluorinated fluid production clusters in Germany and Japan, exposing pack assemblers to input cost volatility and currency-driven procurement risk.
- Phase change material substitution:Compact two-wheeler OEMs in India and Southeast Asia are adopting passive thermal layers where space constraints limit active circulation hardware.
- NHTSA battery safety investigation timelines:Extended validation protocols for thermal runaway propagation resistance are stretching certification cycles and freezing capital in pre-production tooling.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Domestic gigafactory construction is creating first-mover openings for coolant loop integrators able to localize precision machining and sensor calibration.
- Software-defined thermal calibration:Recurring revenue service contracts are displacing one-time hardware sales as European OEMs demand lifetime performance guarantees from embedded control stacks.
- Second-life battery thermal retrofit:Stationary energy storage applications are emerging as a channel for refurbished liquid-cooling hardware with downgraded heat flux specifications.
Industry Challenges
- Multiphysics simulation talent scarcity:Cell-to-pack thermal modeling requires cross-trained engineers fluent in both electrochemistry and computational fluid dynamics, with universities lagging curriculum updates.
- ISO 26262 functional safety certification:Control unit software validation for ASIL-D compliance demands 18-24 month timelines that misalign with compressed vehicle platform launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Battery Thermal Management Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Hybrid Systems Component: Heat Exchangers, Thermal Insulation, Control Units, Sensors End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses Application: Battery Safety, Performance Optimization, Range Extension, Thermal Regulation |
| Companies Covered | Robert Bosch GmbH, GENTHERM Incorporated, Continental AG, Denso, Valeo, Mahle GmbH, BorgWarner Inc., Hanon Systems, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Battery Thermal Management Systems Market Strategic Shifts & Innovations
Active thermal management architectures are decoupling from fixed hardware configurations as predictive algorithms and embedded software stacks redefine how cell temperatures are regulated across operating lifecycles.
Dielectric coolant formulations with enhanced electrical insulation properties are displacing conventional glycol-water mixtures in high-voltage architectures. Korean and Chinese cell manufacturers are adopting these fluids for 800V platforms to reduce ionic contamination risks. This chemistry shift is converging with sensor fusion architectures that merge temperature, pressure, and flow data into unified control loops.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluorinated thermal fluids used in premium passenger car segments. Chemical suppliers are accelerating bio-based alternatives through ECHA pre-registration pathways. Battery pack assemblers in Germany and France are most exposed, with several Tier 1 suppliers already qualifying hydrofluoroether replacements.
Fleet operators and energy-as-a-service providers are unbundling thermal hardware procurement from long-term performance contracts. This model transfers degradation risk to system integrators who must guarantee cycle life through predictive maintenance algorithms. The shift is most visible in North American commercial vehicle deployments where total-cost-of-ownership calculations dominate capital allocation decisions.
Electric Vehicle Battery Thermal Management Systems Market Segmentation
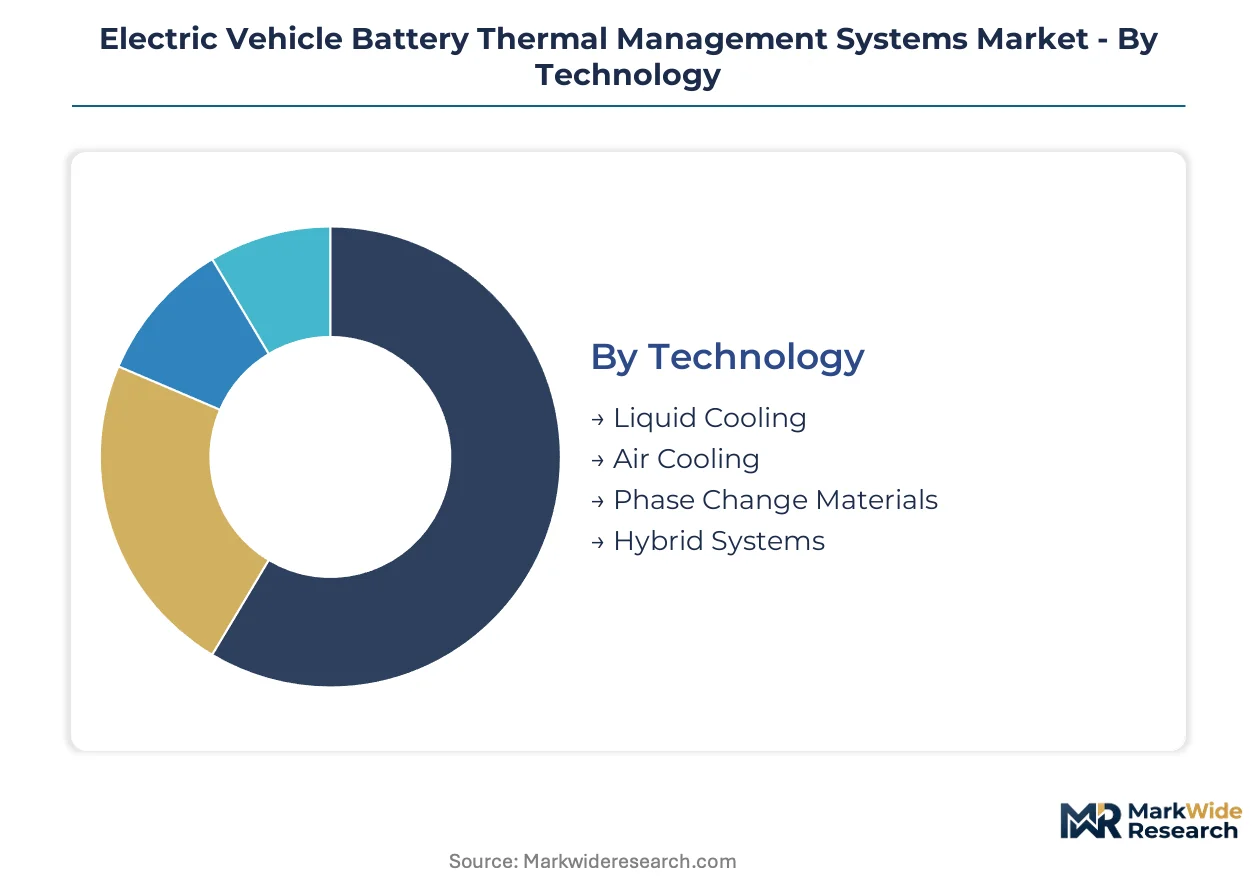
Technology choices in EV battery thermal management lock in hardware replacement cycles spanning platform lifecycles. Component selection determines margin capture between one-time sales and recurring service revenue. End user segmentation reveals divergent heat flux requirements and validation protocols.
Technology:
Upgrade cycles diverge sharply between active and passive architectures as cell chemistry shifts toward higher energy densities.
- Liquid Cooling:Circulates dielectric or glycol-water mixtures through cold plates bonded to cell surfaces, achieving heat flux capacity above 500 W per cell group. Procurement concentrates in German and South Korean passenger car OEMs as GB standards and EU Battery Regulation tighten thermal runaway propagation mandates.
- Phase Change Materials:Absorb latent heat through solid-liquid transitions without active pumping, enabling compact pack geometries. Demand clusters in Indian and Southeast Asian two-wheeler OEMs where space constraints and cost sensitivity limit liquid loop hardware.
- Air Cooling:Forces ambient or conditioned air across cell surfaces through ducted channels, sacrificing thermal uniformity for system simplicity. Remains viable in low-cost commercial vehicle retrofit applications.
- Hybrid Systems:Combines liquid loops for high-load operation with passive layers for thermal buffering during transient events. Emerging in 800V architectures where Korean cell manufacturers seek ionic contamination risk reduction.
Volume placements concentrate in liquid cooling; the faster expansion belongs to phase change materials.
Component:
Margin pools shift toward intelligence layers as predictive algorithms displace reactive thermal control.
- Control Units:Embedded software stacks execute predictive thermal algorithms that preempt degradation rather than respond to overtemperature events. European OEMs are anchoring long-term service contracts to these capabilities, displacing one-time hardware sales.
- Sensors:Temperature, pressure, and flow transducers feed unified control loops with fused data streams. EU battery passport requirements mandate traceable thermal performance logging across cell lifecycles, embedding these components in compliance architectures.
- Heat Exchangers:Aluminum or stainless steel assemblies transfer waste heat to vehicle HVAC or dedicated refrigerant loops. Fluorinated fluid supply concentration in Germany and Japan exposes assemblers to input cost volatility.
- Thermal Insulation:Aerogel and ceramic fiber barriers prevent thermal runaway propagation between cell groups. NHTSA battery safety investigations are stretching validation timelines for these passive safety layers.
Revenue concentration sits with control units; sensor volumes are climbing the fastest as logging mandates expand.
End User:
Application scale dictates hardware complexity and software sophistication thresholds.
- Passenger Cars:Liquid-cooled architectures dominate as heat flux demands exceed 500 W per cell group. China's NEV subsidy regime pulls cell gigafactory investments toward precision thermal control hardware with embedded logging.
- Commercial Vehicles:Fleet operators are unbundling thermal hardware procurement from long-term performance contracts, transferring degradation risk to system integrators. North American deployments lead this shift where total-cost-of-ownership calculations dominate capital allocation.
- Two-Wheelers:Compact packs favor passive thermal layers where space constraints limit active circulation. India's PLI scheme for cell manufacturing is creating first-mover openings for coolant loop integrators able to localize precision machining.
- Buses:High-duty cycles and rapid charging requirements demand robust active cooling with redundant circulation loops. Procurement clusters around municipal fleet electrification programs in Germany and France.
Passenger cars anchor current volume; commercial vehicles show the steepest expansion trajectory as fleet electrification accelerates.
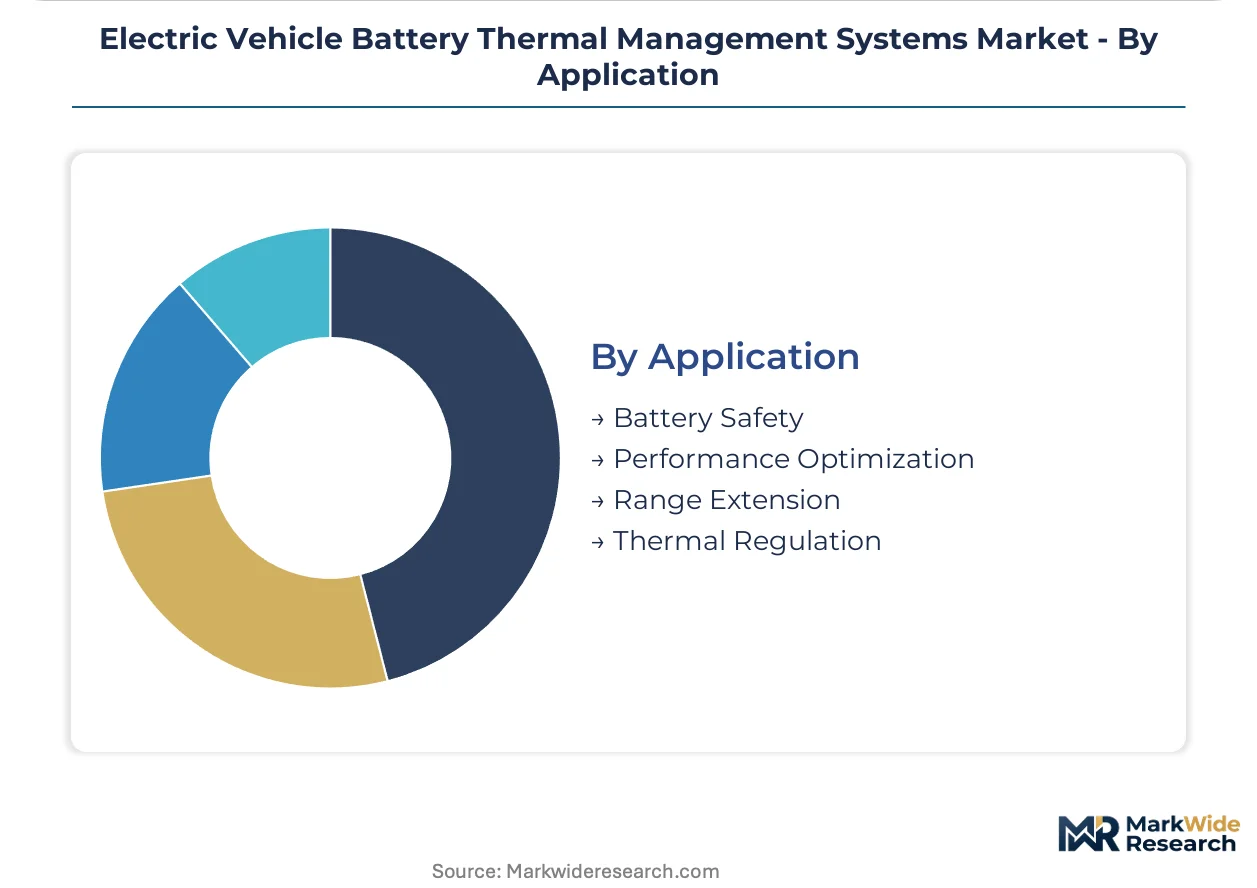
Application:
Functional prioritization determines sensor density and algorithm complexity investments.
- Battery Safety:Thermal runaway propagation resistance mandates multilayer passive barriers and active suppression systems. EPA tailpipe rules and NHTSA investigations are tightening validation requirements.
- Performance Optimization:Cell operating temperature uniformity preserves cycle life and discharge rates. Predictive thermal algorithms from embedded control stacks are displacing reactive threshold-based management.
- Range Extension:Thermal conditioning of cells during preconditioning and fast charging minimizes energy diverted from propulsion. Critical for 800V platform adoption where Korean manufacturers lead.
- Thermal Regulation:Baseline temperature maintenance within electrochemical optimal windows. Software-defined thermal calibration is decoupling hardware configurations from lifetime performance guarantees.
Safety applications dominate current procurement; performance optimization is gaining share fastest as OEMs compete on cycle life warranties.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European procurement of liquid-cooled battery packs as German OEMs compress validation timelines under EU Battery Regulation mandates. Cell gigafactories cluster around established automotive supply chains across three continents.
China
Tiered NEV subsidies pull cell gigafactory investments toward precision thermal control hardware with embedded logging capabilities. GB standards mandate traceable thermal performance data across cell lifecycles. Shenzhen and Ningbo host pack assembly plants serving domestic OEMs and export markets.
Germany
EU battery passport requirements force suppliers to embed sensor-to-actuator architectures capturing expanding margin pools. ECHA REACH restrictions on fluorinated fluids accelerate hydrofluoroether qualification timelines. Stuttgart and Munich concentrate coolant loop integrators and control unit development centers.
United States
EPA tailpipe rules and NHTSA battery safety investigations tighten validation requirements for thermal runaway propagation resistance. Michigan and Tennessee host pack assembly plants clustered around cell gigafactories. Extended certification protocols freeze capital in pre-production tooling.
South Korea
800V platform adoption drives dielectric coolant demand for ionic contamination risk reduction. Domestic cell manufacturers anchor sensor fusion architectures merging temperature, pressure, and flow data. Gyeonggi Province concentrates thermal management R&D facilities serving premium passenger car exports.
India
PLI scheme for cell manufacturing creates first-mover openings for coolant loop integrators localizing precision machining. Two-wheeler OEMs favor passive thermal layers where space constraints limit active circulation hardware. Tamil Nadu and Gujarat host emerging pack assembly capacity.
Electric Vehicle Battery Thermal Management Systems Market Key Industry Players
Capital-heavy producers compete with asset-light designers across thermal management value chains. Tier 1 automotive suppliers dominate liquid cooling hardware while specialized sensor vendors capture expanding software margin pools. Three archetypes define competitive positioning: integrated system integrators bundling hardware-software stacks, component specialists focusing on single-layer thermal materials, and control software vendors anchoring recurring revenue service contracts. M&A activity concentrates on sensor-to-actuator architecture consolidation and geographic expansion into emerging cell manufacturing clusters.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the system integrator archetype with embedded control capabilities. Mahle GmbH occupies a position within the component specialist tier. These entities represent divergent strategic bets on hardware-software bundling versus modular component supply.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| GENTHERM Incorporated |
| Continental AG |
| Denso |
| Valeo |
| Mahle GmbH |
| BorgWarner Inc. |
| Hanon Systems |
| Dana Incorporated |
| Others |
Cost & Logistics Intelligence
Passenger car OEM procurement concentration around liquid-cooled battery packs anchors value-based pricing tied to thermal runaway propagation guarantees rather than per-component hardware costs. Tier 1 suppliers capture recurring revenue through embedded control software stacks that decouple upfront hardware sales from lifetime performance warranties.
Pricing Analysis
Value-based pricing anchored to cycle life guarantees and thermal runaway prevention outcomes dominates as OEMs demand software-defined thermal calibration. Three-tier pricing structure across premium dielectric coolant systems, standard glycol-water architectures, and economy air-cooled retrofits reflects certification grade differentiation under EU Battery Regulation and GB standards. Cost compression in economy tiers intensifies as Indian and Southeast Asian two-wheeler OEMs adopt passive phase change materials. Commercial vehicle fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while compact two-wheeler manufacturers face acute margin pressure.
Supply Chain Analysis
Dual-sourcing requirements mandated by European and North American OEMs force qualification of alternative fluorinated fluid suppliers beyond dominant German and Japanese chemical producers. Dielectric coolant chemistry draws from concentrated fluoropolymer feedstock streams, with sensor fusion architectures resting on semiconductor supply anchored in South Korea and Taiwan. Single-source vulnerability in fluorinated fluid production exposes pack assemblers to input cost volatility and currency-driven procurement risk. Distribution runs through Tier 1 automotive supplier networks with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as predictive thermal algorithms displace reactive threshold-based management systems. Software-defined thermal calibration is replacing fixed hardware configurations across passenger car and commercial vehicle platforms.
For Market Incumbents: To counter margin erosion from software commoditization, anchor long-term service contracts through embedded control stack investments and pursue backward integration into dielectric coolant formulation. Robert Bosch GmbH and Continental AG demonstrate this defensive posture through sensor-to-actuator architecture consolidation that captures compliance-driven logging mandates. For New Entrants and Emerging Players: Launch via India's PLI scheme for cell manufacturing where domestic gigafactory construction creates first-mover openings for coolant loop integrators able to localize precision machining. Target commercial vehicle fleet operators unbundling thermal hardware procurement from performance contracts, with white-space in refurbished liquid-cooling hardware for second-life stationary storage applications. For Investors and Strategic Acquirers: The window for entry favors control software vendors with ASIL-D functional safety certification and predictive algorithm IP. Long-term viability hinges on recurring revenue service contract attach rates rather than one-time hardware sales. Watch NHTSA battery safety investigation timelines as the inflection signal—accelerated thermal runaway propagation standards would compress validation cycles and favor incumbent system integrators with pre-certified architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Thermal Calibration Investment | European OEMs anchor lifetime performance guarantees to embedded control stacks, displacing transactional hardware sales. |
| Dielectric Coolant Chemistry Partnership | Korean cell manufacturers adopt 800V-compatible formulations to reduce ionic contamination risks in high-voltage architectures. |
| Sensor-to-Actuator Architecture Consolidation | EU battery passport requirements force traceable thermal performance data capture across cell lifecycles. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme creates first-mover openings for coolant loop integrators localizing precision machining in Tamil Nadu. |
| Second-Life Battery Thermal Retrofit Channel | Stationary energy storage applications emerge as distribution path for refurbished liquid-cooling hardware with downgraded specifications. |
Research Approach
Independent corroboration across OEM platform engineering leads, Tier 1 supplier procurement executives, and cell gigafactory operations managers underwrites the qualitative findings. Primary interviews with thermal management system integrators, dielectric coolant formulators, and functional safety certification specialists combined with secondary validation from vehicle production databases, SEC filings of listed automotive suppliers, and regulatory submission documents. Bottom-up segment sizing triangulates against top-down market estimates.
Comparable-period anchoring to historical platform launch cycles and cell chemistry transitions informed the projection horizon. Segmentation dimensions modeled span cooling technology type, component intelligence layer, vehicle class, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating cell gigafactory capacity announcements, NEV subsidy tier structures, and thermal runaway propagation standard adoption trajectories. Inputs include OEM procurement pipeline visibility and coolant chemistry qualification timelines.
Subsidy regime discontinuation, REACH restriction acceleration on fluorinated substances, and NHTSA thermal runaway investigation conclusion delays are the dominant revision risks. Deviation in EU Battery Regulation enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
Asia-Pacific LFP Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Traction Battery Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Asia-Pacific Electric Vehicle Solid State Battery Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
EV Battery Cells Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market