
 Second Life Electric Vehicle Battery Market | 2026-2036
Second Life Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Second Life Electric Vehicle Battery Market Analysis
Lithium iron phosphate chemistry is broadening the addressable economics of second-life battery packs by retaining higher cycle stability after automotive retirement than nickel-manganese-cobalt alternatives. Nissan Motors Corporation leverages its LEAF battery ecosystem to sustain refurbishment throughput across Japanese and European facilities. Renault Group anchors its circular economy strategy through dedicated re-manufacturing plants in France, while Connected Energy competes on system integration expertise for grid-scale stationary storage.
Second life electric vehicle batteries comprise retired automotive traction battery packs that retain sufficient capacity for non-automotive duty cycles, typically operating at state-of-health thresholds between 70% and 80% of original rated capacity. These units undergo diagnostic sorting, module reconfiguration, and battery management system reprogramming to serve stationary applications requiring lower discharge rates and shallower depth-of-cycling than propulsion demands. The repurposing technology segment leads current deployment volumes because it preserves more embedded energy value than recycling pathways that deconstruct cells to elemental materials. Grid support applications attract the fastest-growing demand as transmission operators seek distributed flexibility resources, while utility end users command the deepest procurement budgets and longest contract horizons.
The EU Battery Regulation and REACH framework mandate traceability and recycled content thresholds that reshape product standards for second-life systems entering European markets. EPA guidelines in the United States govern hazardous waste classification thresholds that determine whether retired packs qualify for reuse exemption or fall under full recycling obligations. Stakeholders must monitor how divergent national interpretations of end-of-waste status affect cross-border shipment economics and liability allocation.
Market Dynamics
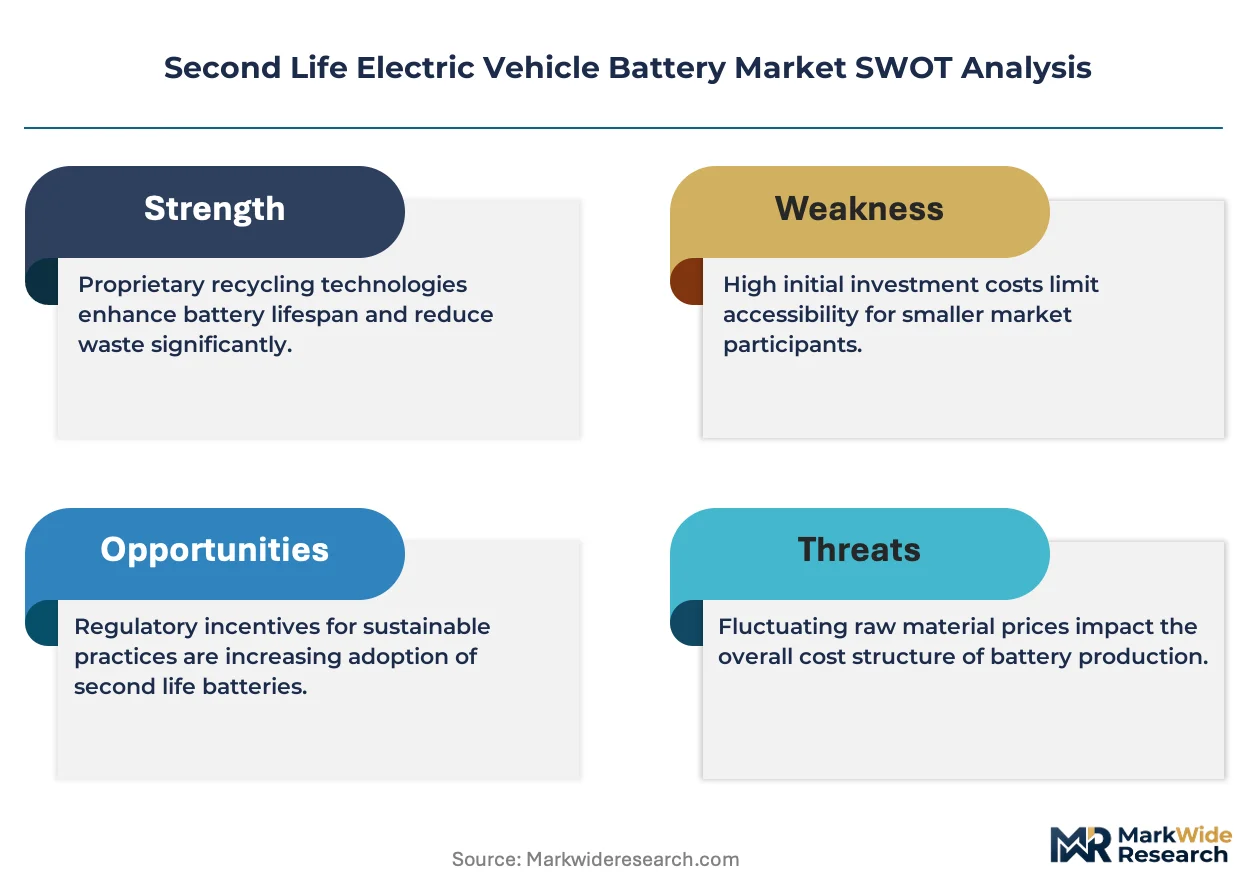
The EU Battery Regulation's mandatory recycled content thresholds are compressing time-to-market for second-life systems while forcing parallel investments in traceability infrastructure and re-manufacturing capacity.
Growth Catalysts
- REACH traceability mandates:Battery passports create standardized data fields that reduce due diligence costs for pack aggregators trading across European borders.
- Grid-scale stationary storage:Transmission operators in Germany and the Netherlands procure distributed flexibility resources to defer substation upgrades.
- Lithium iron phosphate chemistry:Superior cycle stability after automotive retirement expands addressable duty cycles for behind-the-meter commercial installations.
Market Restraints
- Feedstock supply concentration:End-of-life pack availability clusters around Stuttgart and Wolfsburg industrial corridors, creating geographic procurement risk.
- Cell-to-cell variability:State-of-health dispersion across retired modules forces expensive reconfiguration and redundant capacity provisioning.
- Primary battery cost curves:Declining new lithium-ion cell prices compress the economic window for second-life refurbishment.
Strategic Opportunities
- Behind-the-meter commercial storage:C&I facilities in France and Spain seek peak-shaving assets with lower capital intensity than new battery procurement.
- Vehicle-to-grid integration:Bidirectional charging protocols enable mobile storage assets to participate in ancillary service markets.
- CE marking harmonization:Unified safety standards reduce certification duplication costs for pack integrators serving multiple EU member states.
Industry Challenges
- Diagnostic technician scarcity:Module-level state-of-health assessment requires electrochemistry expertise that outpaces vocational training pipeline output.
- Re-manufacturing capex intensity:Automated disassembly lines and cleanroom cell grading facilities demand upfront capital that squeezes mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second Life Electric Vehicle Battery Market |
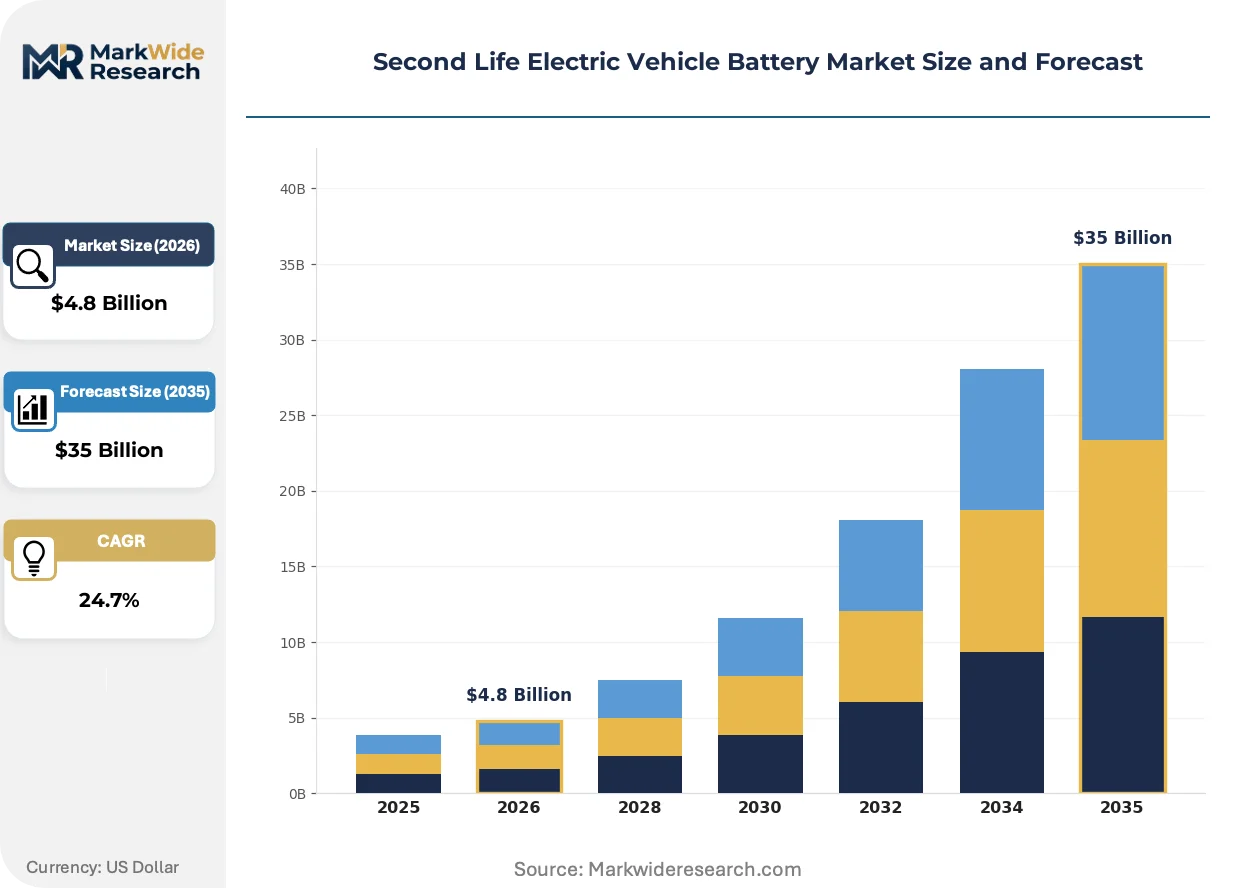
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
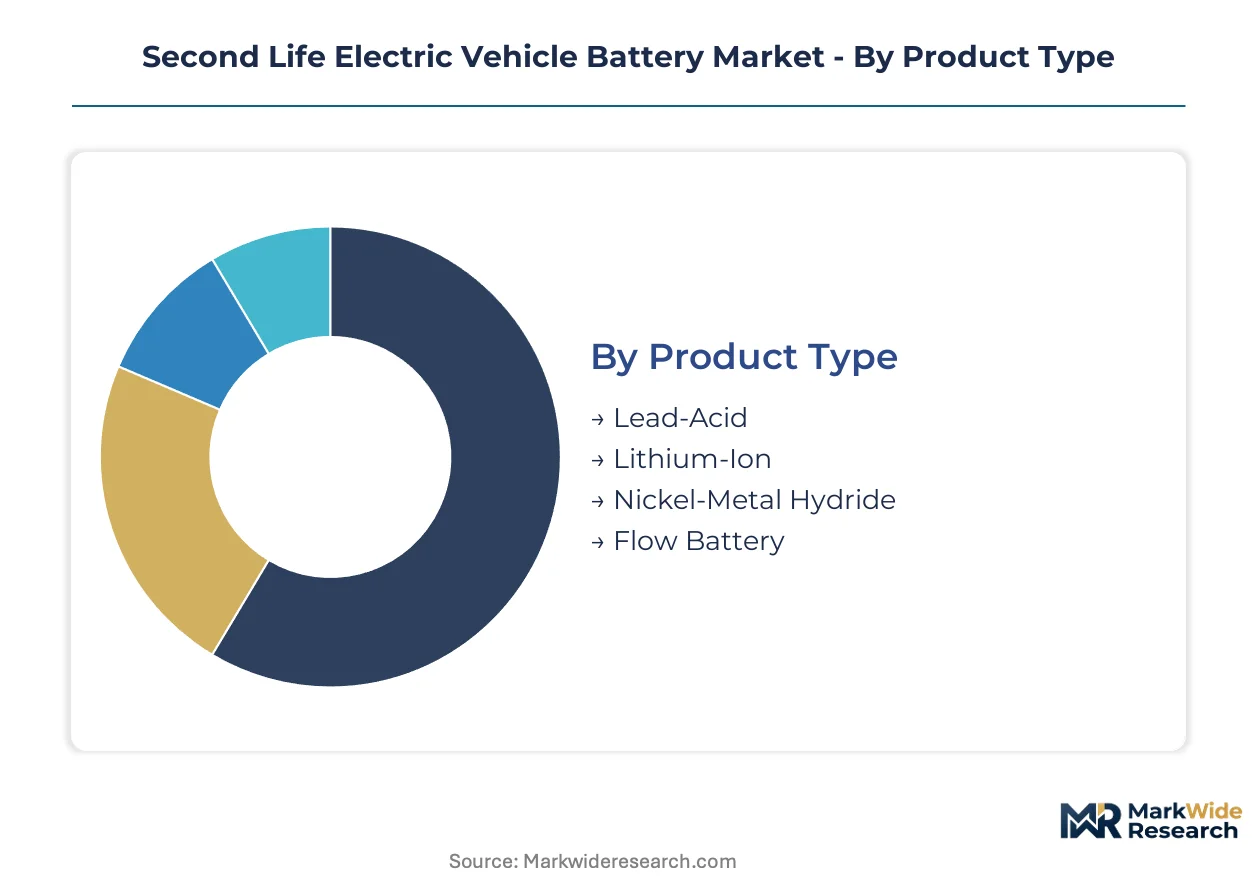
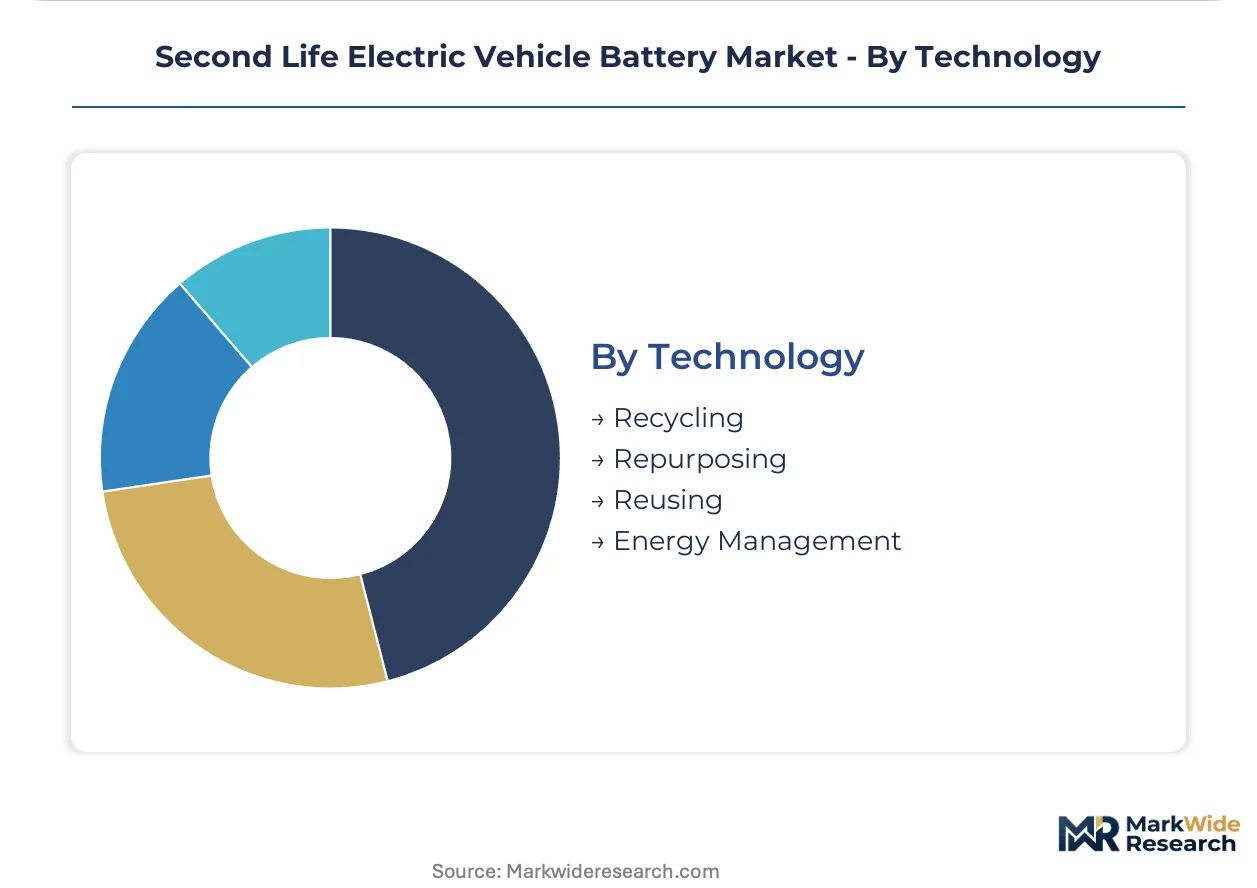
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Flow Battery Application: Energy Storage, Grid Support, Backup Power, Renewable Integration End User: Utilities, Commercial, Residential, Industrial Technology: Recycling, Repurposing, Reusing, Energy Management |
| Companies Covered | Mercedes-Benz Group AG, Mitsubishi Motors Corporation, Nissan Motors Corporation, Connected Energy, Enel X S.R.L, Fortum, Hyundai Motor Company, Element Energy, Renault Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second Life Electric Vehicle Battery Market Emerging Trajectories
Standardized battery management system architectures are collapsing integration costs while regulatory data requirements are embedding traceability into hardware design cycles.
Artificial intelligence-driven predictive algorithms are absorbing cell degradation forecasting into pack configuration decisions. Grid operators in Germany deploy these tools to match retired automotive modules with stationary duty cycles. The technology is absorbing uncertainty premiums that previously inflated insurance and warranty costs for second-life installations.
REACH substance restrictions are tightening cobalt and nickel content thresholds for batteries entering European circulation. Re-manufacturers must document material provenance through supply chain audits. Pack integrators serving utility procurement channels are responding by prioritizing lithium iron phosphate feedstocks with cleaner chemistry profiles.
Long-term service contracts are displacing upfront equipment sales in utility procurement channels. Asset-light integrators such as Connected Energy retain ownership and sell energy storage-as-a-service to transmission operators. This shift concentrates most visibly in the United Kingdom where capacity market mechanisms favor operational expenditure structures over capital ownership.
Second Life Electric Vehicle Battery Market Segmentation
Second-life battery economics vary sharply across chemistry types and duty cycles. Segmentation reveals where refurbishment margins hold against primary battery cost compression.
Product Type:
Supply concentration in automotive retirement streams favors chemistries with established collection infrastructure and diagnostic protocols.
- Lithium-Ion:Dominant chemistry in retired automotive packs, with lithium iron phosphate variants retaining superior cycle stability post-retirement. German utilities around Stuttgart prioritize these feedstocks for grid-scale installations due to predictable degradation curves.
- Lead-Acid:Mature recycling infrastructure and lower energy density limit second-life applicability to backup power in commercial buildings. The segment relies on cost-sensitive procurement in Southern European markets.
- Nickel-Metal Hydride:Legacy hybrid vehicle batteries with moderate residual capacity serve residential energy storage in Japanese prefectures with established Toyota and Honda retirement pipelines.
- Flow Battery:Vanadium and zinc-bromide systems from stationary applications enter second-life cycles for long-duration storage in Dutch industrial zones.
Lithium-ion absorbs the bulk of installed capacity; lead-acid is expanding most quickly in cost-constrained backup applications.
Application:
Margin structures diverge based on discharge rate requirements and contract duration flexibility.
- Grid Support:Transmission operators in Germany and the Netherlands procure distributed flexibility resources to defer substation upgrades. Long-term service contracts dominate procurement channels.
- Energy Storage:Behind-the-meter commercial installations in France and Spain seek peak-shaving assets with lower capital intensity than new battery procurement.
- Renewable Integration:Solar and wind farms in Portugal pair retired automotive modules with variable generation to smooth output volatility.
- Backup Power:Data centers and manufacturing facilities in Poland deploy refurbished packs for uninterruptible power supply during grid instability events.
Grid support commands the deepest procurement budgets; renewable integration gains share fastest as solar deployment accelerates.
End User:
Customer sophistication determines diagnostic requirements and warranty terms.
- Utilities:Transmission operators in Germany deploy predictive algorithms to match retired modules with stationary duty cycles. The segment demands comprehensive traceability documentation under EU Battery Regulation mandates.
- Commercial:C&I facilities in France prioritize lithium iron phosphate feedstocks with cleaner chemistry profiles to satisfy REACH substance restrictions.
- Industrial:Manufacturing clusters around Wolfsburg integrate second-life storage into captive renewable microgrids.
- Residential:Homeowners in Spain adopt refurbished packs for self-consumption optimization alongside rooftop solar.
Utilities anchor procurement volume; residential adoption climbs the fastest as retail electricity tariffs rise.
Technology:
Process maturity dictates capital recovery timelines and scale economics.
- Repurposing:Module reconfiguration and battery management system reprogramming preserve more embedded energy value than elemental recovery. Automated disassembly lines in French re-manufacturing plants process LEAF and Zoe retirement streams.
- Recycling:Hydrometallurgical and pyrometallurgical recovery of cobalt, nickel, and lithium serves EU Battery Regulation recycled content mandates.
- Reusing:Direct redeployment of intact packs with minimal modification targets low-duty applications in emerging markets.
- Energy Management:AI-driven state-of-health forecasting absorbs uncertainty premiums that previously inflated insurance costs for second-life installations.
Repurposing dominates current deployment volumes; energy management represents the steepest expansion trajectory as predictive tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial free-trade zones in Germany's Stuttgart corridor concentrate re-manufacturing capacity under EU Battery Regulation compliance frameworks. Tax-advantaged facilities in Wolfsburg and Flins cluster diagnostic equipment and module grading operations near automotive retirement streams.
Germany
Transmission operators in Bavaria and Baden-Württemberg procure distributed flexibility resources to defer substation upgrades. The EU Battery Regulation's mandatory recycled content thresholds compress time-to-market for second-life systems entering German utility procurement channels. Stuttgart industrial clusters host automated disassembly lines processing LEAF and Zoe retirement streams for grid-scale stationary storage.
France
Commercial and industrial facilities in Île-de-France seek peak-shaving assets with lower capital intensity than new battery procurement. REACH substance restrictions tighten cobalt and nickel content thresholds, forcing re-manufacturers to document material provenance through supply chain audits. Renault Group anchors circular economy operations through dedicated re-manufacturing plants in Flins.
United Kingdom
Capacity market mechanisms favor operational expenditure structures over capital ownership for transmission-connected storage. The Environment Agency governs hazardous waste classification thresholds determining whether retired packs qualify for reuse exemption. Connected Energy retains asset ownership and sells energy storage-as-a-service to grid operators in England and Wales.
Netherlands
Transmission system operators procure distributed flexibility resources to manage congestion on low-voltage networks. ECHA administers REACH traceability mandates creating standardized data fields that reduce due diligence costs for pack aggregators. Dutch industrial zones in North Brabant deploy vanadium and zinc-bromide flow battery systems from stationary applications entering second-life cycles.
Spain
Behind-the-meter commercial installations in Catalonia and Madrid seek self-consumption optimization alongside rooftop solar deployment. The national climate law establishes recycled content benchmarks that reshape product standards for second-life systems. Manufacturing facilities in the Basque Country integrate refurbished packs into captive renewable microgrids for grid instability protection.
Second Life Electric Vehicle Battery Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive OEMs controlling feedstock access while independent integrators compete on system design. The vendor base organizes around three strategic archetypes: captive re-manufacturing arms of vehicle manufacturers, independent pack integrators with grid-scale project expertise, and energy management specialists selling predictive analytics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure long-term service contracts with transmission operators.
Among automotive-origin re-manufacturers, Nissan Motors Corporation and Renault Group occupy positions exemplifying captive circular economy strategies, while Connected Energy sits within the independent integrator tier representing system integration expertise for utility procurement channels. These three entities anchor the competitive structure by demonstrating alternative pathways to market access—feedstock control versus technical specialization—without requiring scale-driven consolidation.
| Leading Market Players |
|---|
| Mercedes-Benz Group AG |
| Mitsubishi Motors Corporation |
| Nissan Motors Corporation |
| Connected Energy |
| Enel X S.R.L |
| Fortum |
| Hyundai Motor Company |
| Element Energy |
| Renault Group |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EU Battery Regulation-compliant systems and non-compliant refurbished packs manifests in pricing spreads exceeding fifty percent, with Stuttgart-based integrators commanding premiums for traceability documentation while Wolfsburg corridor suppliers absorb margin compression from REACH audit costs. This divergence feeds directly into supply chain configuration choices, as automotive OEMs restrict feedstock access to certified re-manufacturers while independent aggregators compete on throughput volume without passport infrastructure.
Pricing Analysis
Volume throughput at French re-manufacturing plants competes against margin capture at German utility-facing integrators, with the latter extracting value from long-term service contracts rather than equipment sales. Price differentiation rests on battery passport completeness and module-level state-of-health transparency, with transmission operators in Bavaria least sensitive to capital expenditure and residential buyers in Spain most responsive to upfront cost. Cost compression in the independent aggregator tier is intensifying because primary lithium-ion cell prices continue declining, eroding the refurbishment window for packs below seventy percent residual capacity.
Supply Chain Analysis
Diagnostic technician shortages in Baden-Württemberg and Île-de-France constrain re-manufacturing throughput despite automated disassembly investments. Feedstock concentration clusters in Germany, France, and the Netherlands, with retired Nissan LEAF and Renault Zoe batteries dominating European availability. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide for cell replacement modules. Single-source vulnerability runs through Chinese cathode active material supply. Distribution runs through utility procurement channels in Germany, energy-as-a-service platforms in the United Kingdom, and direct commercial sales in France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's mandatory recycled content thresholds and passport infrastructure requirements constitute a cost-of-compliance moat that favors incumbents with existing traceability systems and squeezes capital-constrained entrants.
For Market Incumbents: Lock in feedstock supply agreements with Stuttgart and Wolfsburg automotive clusters before OEMs tighten circular economy partnerships, while accelerating automated disassembly capex to offset diagnostic technician scarcity that threatens throughput scaling. For New Entrants and Emerging Players: Energy-as-a-service platforms offer the lowest barrier-to-entry pathway, with Spanish behind-the-meter commercial storage presenting the most penetrable segment given rising retail electricity tariffs and limited incumbent presence outside utility channels. For Investors and Strategic Acquirers: Re-rating potential sits with independent pack integrators possessing predictive algorithm capabilities given grid operator procurement shifts toward operational expenditure structures; monitor German transmission operator RFP volume as the inflection signal for second-life asset class legitimacy.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Passport Infrastructure Investment | EU Battery Regulation compliance creates defensible positioning against non-certified competitors in German utility procurement. |
| Automated Disassembly Line Deployment | French re-manufacturing plants reduce labor cost exposure from diagnostic technician scarcity affecting throughput scaling. |
| Long-term Service Contract Structuring | United Kingdom capacity market mechanisms favor operational expenditure models over capital ownership for grid-connected storage. |
| Feedstock Supply Agreement with OEMs | Nissan and Renault captive circular economy strategies restrict independent aggregator access to LEAF and Zoe retirement streams. |
| Predictive Algorithm Development | AI-driven state-of-health forecasting absorbs uncertainty premiums previously inflating insurance costs for second-life installations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with re-manufacturing plant managers, utility procurement officers at German transmission operators, battery management system engineers, and REACH compliance consultants. Secondary validation drew from EU Battery Regulation implementation guidance, ECHA substance restriction databases, automotive OEM sustainability reports, and grid operator flexibility procurement documentation. Bottom-up module throughput estimates from Stuttgart and Wolfsburg facilities triangulated against top-down stationary storage deployment projections.
Segment-level granularity modeled chemistry type, application duty cycle, and end-user sophistication across the projection horizon, with separate treatment of utility, commercial, industrial, and residential procurement channels. CAGRs derived from fitted adoption curves incorporating primary battery cost trajectory assumptions and regulatory compliance timeline acceleration. Forecast inputs included automotive retirement pipeline estimates from German and French production clusters, plus transmission operator substation deferment demand from TenneT and Amprion planning documents.
The model holds under sustained EU Battery Regulation enforcement and primary lithium-ion cost decline rates within historical bands; deviation in automotive electrification pace or REACH substance restriction tightening would shift feedstock availability and refurbishment economics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charger Market
Electric Vehicle Charging
PV BESS EV Charging Systems Market
Electric Vehicle Charging
Electric Vehicle Battery Charger Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
High-Thermal-Conductivity Gap-Fill Adhesives for EV Battery Cooling Plates Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
Two Wheel Electric Vehicle Charger Market
Electric Vehicle Charging
Electric Vehicle 800-Volt Charging Pile Market
Electric Vehicle Charging
Global Electric Vehicle Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Charging Adapter Market
Electric Vehicle Charging
Portable Charging Units Market