
 Auto Storage Battery Market | 2026-2036
Auto Storage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Storage Battery Market Analysis
UN ECE R100 certification for rechargeable energy storage systems is reorganizing supplier eligibility for EV battery programs. Clarios leverages its global recycling infrastructure to recover lead-acid materials at scale. LG Energy Solution anchors cell supply contracts with Detroit and European OEMs. BYD Company Ltd. competes through in-house production of lithium iron phosphate cells.
An auto storage battery is an electrochemical device with nominal voltages ranging from 12V for starter applications to 400-800V architectures for traction power, engineered to store and discharge energy through reversible redox reactions. Lead-acid chemistry retains dominance in aftermarket starter applications due to established recycling economics and cold-cranking reliability. Lithium-ion chemistry captures the fastest expansion in electric vehicle and hybrid vehicle applications where energy density above 250 Wh/kg enables extended range. Smart Battery Systems technology concentrates margin pools through battery management integration that optimizes cycle life and thermal performance.
EPA tailpipe standards and UN ECE R100 in the United States and Europe mandate crashworthiness and thermal runaway containment, forcing cell architecture redesigns and expanded testing protocols. China's MIIT enforces GB standards for battery cell format and safety testing that gate market access for imported suppliers. Stakeholders must monitor how divergent certification timelines across EPA, ECE, and GB frameworks reshape sourcing geography and capital deployment for new cell capacity.
Market Dynamics
EPA tailpipe standards and UN ECE R100 certification timelines are compressing supplier qualification windows, forcing battery architecture redesigns and accelerating capital deployment toward crash-tested cell formats before 2027 model-year lock-ins.
Growth Catalysts
- EPA Tier 3 Emission Standards:Tightened tailpipe rules in the United States mandate electrified powertrains, pulling lithium-ion pack orders from passenger vehicle OEMs and commercial truck manufacturers.
- Lithium Iron Phosphate Chemistry:Cell producers are expanding LFP capacity for entry-level electric vehicles where thermal stability and cost structure outweigh energy density requirements.
- China:Dominant cell production clusters in Fujian and Jiangsu provinces supply cathode active materials and separator films to European and North American pack assemblers under long-term offtake contracts.
Market Restraints
- Lithium Carbonate Volatility:Spot market prices for battery-grade lithium salts swing 40-60% annually, compressing cathode producer margins and triggering force majeure renegotiations in supply agreements.
- Concentrated Separator Supply:Wet-process polypropylene separators for high-nickel cells originate from three East Asian chemical conglomerates, creating single-source vulnerability for European gigafactories.
- Solid-State Technical Limitation:Sulfide-based electrolyte manufacturing requires moisture-free dry rooms exceeding Class 1000 cleanliness, constraining pilot-line throughput and delaying automotive qualification timelines.
Strategic Opportunities
- India:Production-linked incentive schemes for advanced chemistry cell manufacturing offer capital expenditure subsidies to foreign cell producers establishing local gigafactory capacity for two-wheeler and three-wheeler electrification.
- Second-Life Stationary Storage:Retired electric vehicle battery packs with 70-80% state-of-health are repurposing for grid-scale frequency regulation and commercial peak-shaving installations.
- Battery Passport Mandate:EU Battery Regulation requirements for full lifecycle traceability create service revenue pools for digital platform providers certifying carbon footprint and recycled content claims.
Industry Challenges
- UN ECE R100 Certification Timeline:Revised thermal runaway propagation tests add 8-12 months to cell-to-pack validation schedules, delaying platform launches and inflating engineering burn rates.
- Electrolyte Formulation IP:Patent thickets around fluorinated additive combinations for high-voltage cathodes are triggering infringement disputes between Korean and Japanese chemical suppliers.
- Legacy 12V Lead-Acid Integration:Smart battery management systems must maintain backward compatibility with starter motor architectures while enabling bidirectional charging through 800V traction busses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Storage Battery Market |
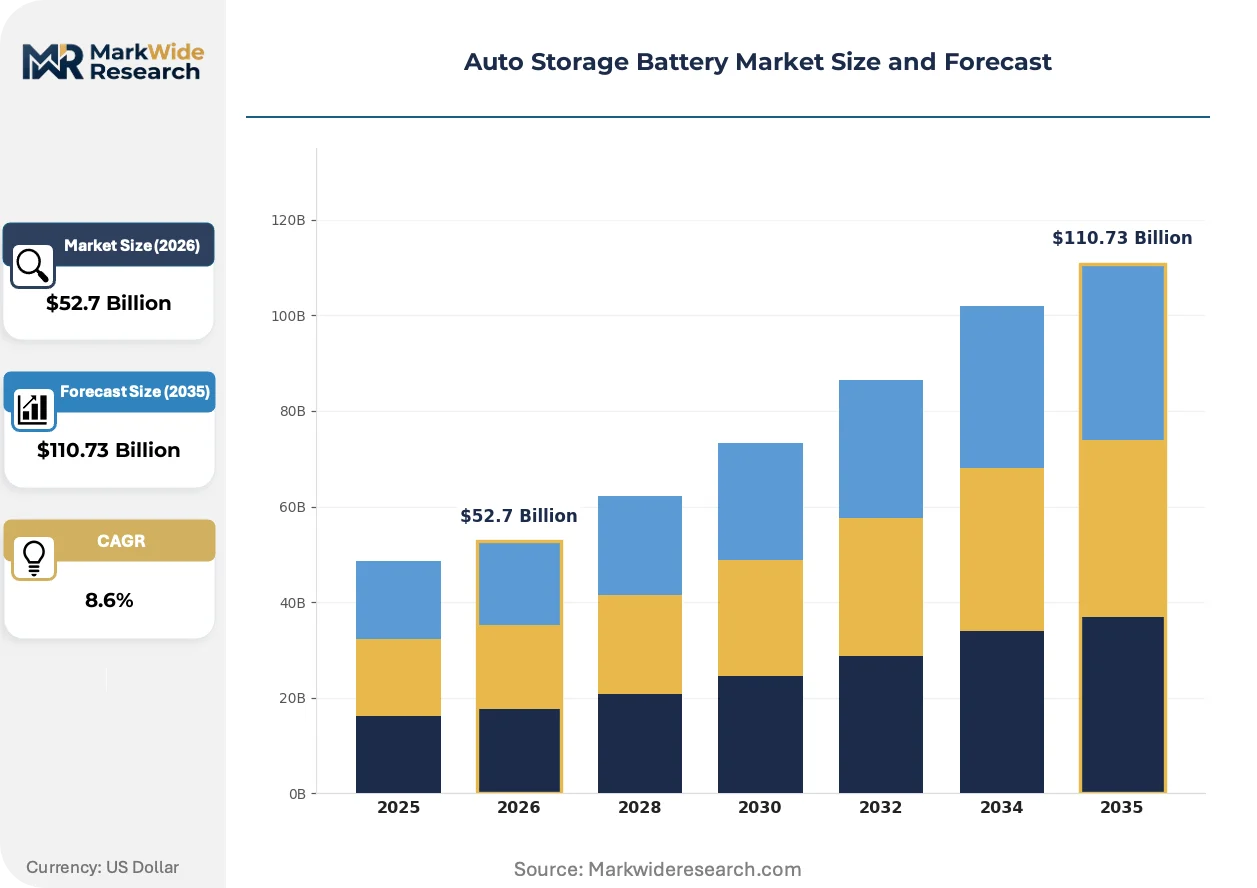
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Flow Batteries Application: Electric Vehicles, Hybrid Vehicles, Start-Stop Systems, UPS Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Technology: Rechargeable, Fast Charging, Smart Battery Systems, Energy Density |
| Companies Covered | Exide Technologies, EnerSys, Clarios, East Penn Manufacturing, GS Yuasa, Hitachi Ltd., Panasonic Holdings Corporation, BYD Company Ltd., LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Storage Battery Market Emerging Trajectories
Cell chemistry diversification and pack architecture modularity are fragmenting procurement patterns, with OEMs qualifying multiple suppliers per platform and tiering performance specifications across vehicle trim levels.
Solid-state electrolyte research is miniaturizing ceramic separator thickness below 20 microns while maintaining ionic conductivity above 10 mS/cm. Luxury electric vehicle platforms from German and South Korean OEMs are piloting these cells for 2028 model-year introductions. The technology is compressing thermal management hardware requirements and enabling cell-to-pack designs that eliminate module-level housings.
EU Battery Regulation mandatory recycled content thresholds are restructuring material sourcing geography. Cell producers must document 16% cobalt, 85% lead, and 6% lithium from recovery streams by 2031, forcing partnerships with hydrometallurgical refiners in Belgium and Finland. Premium passenger vehicle segments face the steepest compliance cost escalation as they source high-purity cathode materials.
Fleet operators are consolidating battery procurement through vehicle-as-a-service contracts that unbundle pack ownership from asset utilization. Commercial van and last-mile delivery segments in the Netherlands and California are adopting this model, transferring residual value risk to finance providers and conditioning supplier selection on guaranteed cycle life performance rather than upfront cell cost.
Auto Storage Battery Market Segmentation
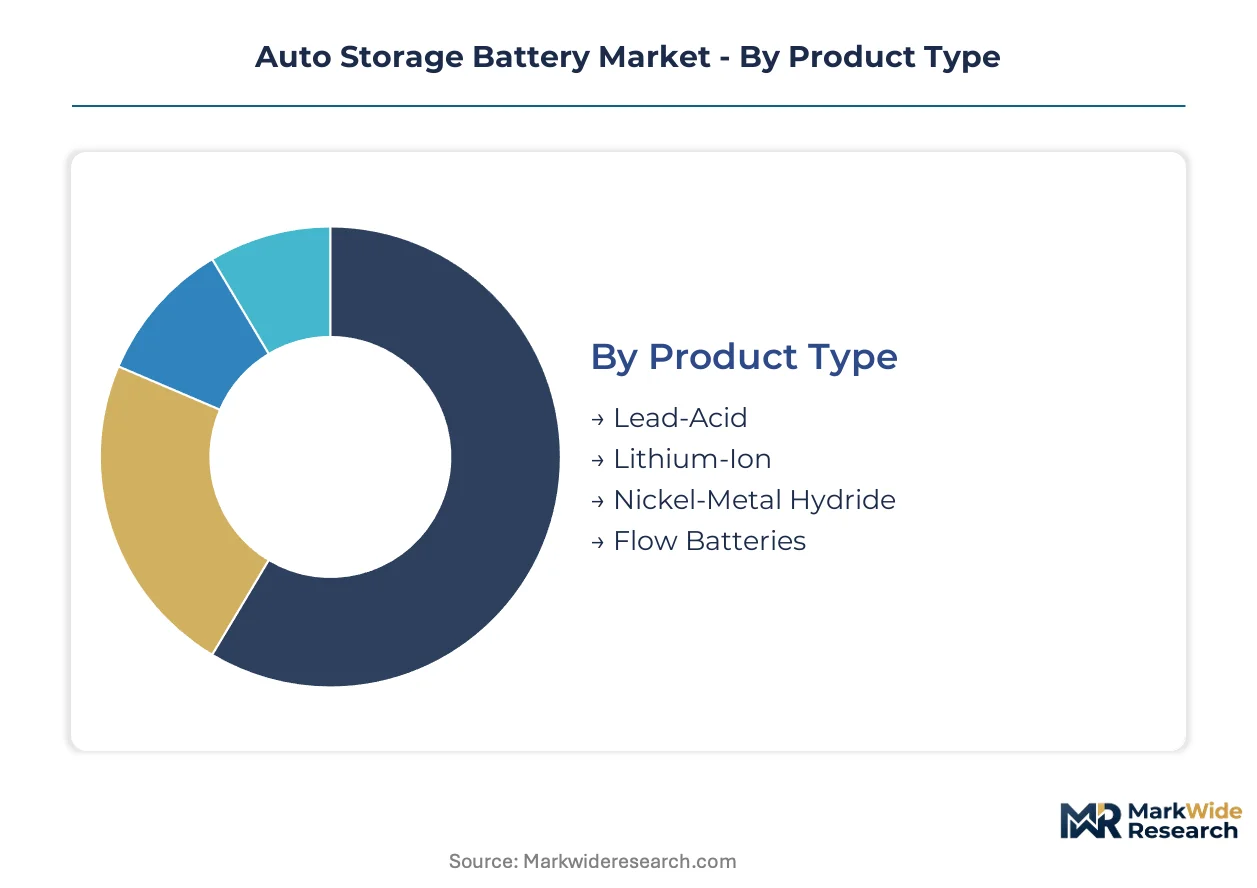
Battery chemistry and application splits determine procurement economics, certification requirements, and margin profiles across the auto storage battery value chain. OEMs tier supplier qualifications by segment, creating divergent competitive dynamics for incumbent lead-acid producers versus lithium-ion challengers.
Product Type:
Substitution pressure from lithium-ion chemistries is compressing lead-acid revenue pools in starter applications while opening premium pricing corridors for next-generation formats.
- Lead-Acid:Flooded and absorbed glass mat constructions deliver 12V nominal output with cold-cranking amperage optimized for internal combustion starter motors. Demand concentrates in aftermarket replacement channels across the United States and India where recycling infrastructure and established distribution networks sustain cost competitiveness against lithium alternatives.
- Lithium-Ion:NCM and LFP cell architectures enable 400-800V traction bus architectures with energy density exceeding 250 Wh/kg. Electric vehicle OEMs in Germany and South Korea are scaling pack orders for EPA-compliant model year programs, with LFP gaining share in entry-level vehicle segments where thermal stability outweighs energy density requirements.
- Nickel-Metal Hydride:Mature chemistry retains position in hybrid vehicle applications where proven cycle life and temperature tolerance support power-split transmission architectures.
- Flow Batteries:Vanadium redox systems serve stationary grid-buffering applications for commercial fleet depots with extended dwell times and predictable charge cycles.
Lead-acid anchors the volume base while lithium-ion gains share at the steepest rate.
Application:
Regulatory tailpipe mandates are reordering application priorities, with electrified powertrain segments capturing capital deployment previously directed toward conventional starter systems.
- Electric Vehicles:Full-electric platforms require 60-100 kWh pack capacities with cell-to-pack thermal management and UN ECE R100 crashworthiness certification. OEM qualification timelines in Europe and the United States are compressing supplier windows ahead of model year lock-ins.
- Hybrid Vehicles:Power-assist architectures demand high-rate discharge capability for regenerative braking energy recovery. Japanese and South Korean OEMs maintain NMH supply contracts for parallel hybrid transmissions where battery weight tradeoffs favor proven reliability over energy density.
- Start-Stop Systems:Enhanced flooded battery and AGM formats support micro-hybrid idle-stop functionality with cycling durability above 200,000 engine restarts.
- UPS Systems:Stationary backup applications prioritize calendar life and float charge stability for commercial and industrial facility power quality assurance.
Start-stop systems deliver the largest unit volumes while electric vehicle applications expand most quickly.
End User:
Procurement concentration varies sharply by customer type, with fleet operators consolidating purchasing power through vehicle-as-a-service contracts that transfer residual value risk to finance providers.
- OEMs:Direct pack procurement from cell producers and module assemblers with multi-year offtake agreements governing cathode active material supply and pricing escalation clauses tied to lithium carbonate indices.
- Aftermarket Providers:Distributor and retailer networks serving replacement demand for starter batteries across passenger vehicle and commercial truck parc, with lead-acid dominating due to established recycling economics and installation tooling compatibility.
- Fleet Operators:Consolidated procurement through leasing structures in the Netherlands and California commercial van segments, conditioning supplier selection on guaranteed cycle life performance rather than upfront cell cost.
- Individual Consumers:Fragmented retail channel with price-sensitive replacement behavior and limited brand loyalty in 12V starter battery categories.
OEMs command the steepest pricing premiums while fleet operators are consolidating procurement fastest.
Technology:
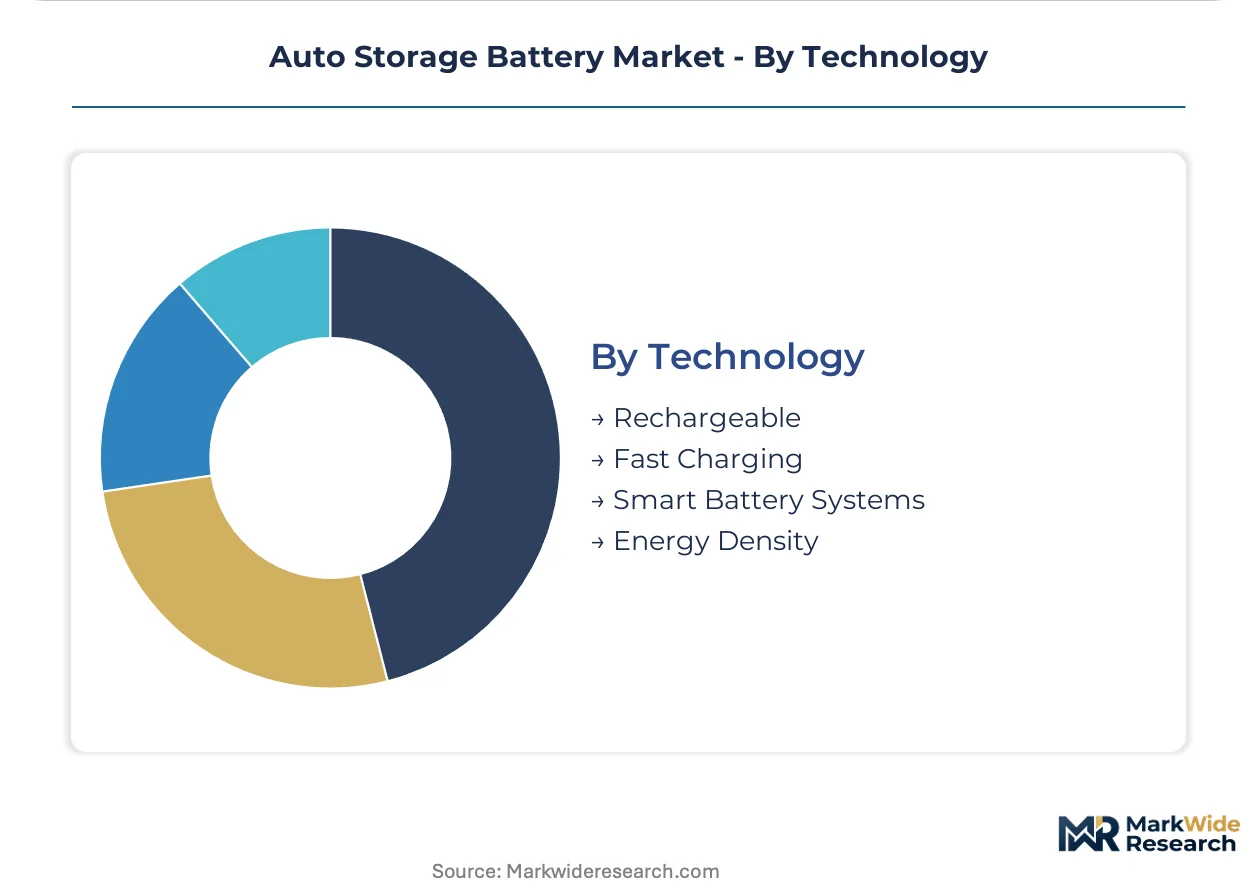
Smart integration features are concentrating margin pools away from commodity cell production toward battery management system software and thermal control hardware.
- Rechargeable:Electrochemical reversibility through intercalation chemistry enables deep-cycle operation for traction and stationary applications with cycle life specifications above 1,000 full equivalent cycles.
- Fast Charging:Silicon-anode and high-nickel cathode formulations support 350 kW DC charging protocols, with cell producers in China and South Korea qualifying 10-80% state-of-charge times below 20 minutes for premium electric vehicle platforms.
- Smart Battery Systems:Integrated battery management units with cell balancing, thermal runaway detection, and predictive state-of-health algorithms optimize cycle life and enable warranty risk transfer to cell suppliers.
- Energy Density:Wh/kg and Wh/L metrics governing vehicle range and pack packaging efficiency, with solid-state research targeting 400+ Wh/kg for 2028 model year luxury vehicle introductions.
Rechargeable technology underpins all volume applications while smart battery systems capture margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and passenger vehicle OEMs concentrate procurement in manufacturing clusters where cathode active material supply and pack assembly capacity co-locate. Buyer archetypes split between volume-contract OEMs in Germany and China and price-sensitive aftermarket distributors in India and the United States.
China
MIIT enforces GB standards for cell format and safety testing that gate market access for imported suppliers. The country's national industrial regulator mandates traceability documentation for lithium carbonate sourcing. Fujian and Jiangsu provinces host cathode active material refineries supplying European and North American pack assemblers under long-term offtake contracts.
Germany
Luxury electric vehicle OEMs scale orders for 800V traction architectures with UN ECE R100 crashworthiness certification. KBA oversees type approval for battery systems entering European type plates. Bavaria and Baden-Württemberg anchor gigafactory investments serving regional OEM demand for EPA-compliant export programs.
United States
EPA Tier 3 tailpipe rules compress supplier qualification windows ahead of 2027 model-year lock-ins. The national environmental regulator mandates electrified powertrain penetration rates that pull lithium-ion pack orders from Detroit and commercial truck manufacturers. Michigan and Tennessee concentrate cell-to-pack assembly capacity for domestic OEM platforms.
India
Production-linked incentive schemes for advanced chemistry cell manufacturing offer capital expenditure subsidies to foreign producers establishing local gigafactory capacity. The national industrial promotion authority conditions subsidy disbursement on domestic value-add thresholds. Gujarat and Tamil Nadu attract two-wheeler and three-wheeler battery investments targeting fleet electrification mandates in Delhi and Bengaluru.
South Korea
Cell producers anchor supply contracts with European and North American OEMs through high-nickel cathode formulations. MFDS maintains pharmaceutical-grade chemical purity standards that extend to electrolyte additive manufacturing. Gyeonggi and Ulsan industrial zones concentrate separator film production and wet-process chemical conglomerate headquarters.
Auto Storage Battery Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive cathode material supply and independent pack assemblers sourcing cells under tolling arrangements. Market structure concentrates around three to five cell producers supplying multiple OEM platforms under multi-year offtake agreements. Strategic archetypes include backward-integrated material suppliers, pure-play cell manufacturers, and recycling-led circular economy operators. Competitive moves center on capacity expansion in European and North American free-trade zones and strategic partnerships with hydrometallurgical refiners for EU Battery Regulation compliance.
Among Asia-Pacific-based conglomerates, BYD Company Ltd., LG Energy Solution, and Panasonic Holdings Corporation exemplify divergent strategic positions. BYD represents the archetype of automotive OEMs with captive cell production and in-house lithium iron phosphate chemistry deployment. LG Energy Solution occupies a position as a pure-play cell producer with multi-regional gigafactory footprints. Panasonic anchors the tier of Japanese electronics conglomerates transitioning industrial battery expertise toward automotive traction applications.
| Leading Market Players |
|---|
| Exide Technologies |
| EnerSys |
| Clarios |
| East Penn Manufacturing |
| GS Yuasa |
| Hitachi Ltd. |
| Panasonic Holdings Corporation |
| BYD Company Ltd. |
| LG Energy Solution |
| Others |
Supply Flow & Price Mechanics
Twenty-one-day cathode active material lead times in early 2024 compressed inventory buffers across European pack assemblers, amplifying pricing power for Chinese and South Korean chemical conglomerates while forcing Detroit OEMs into premium contract tiers for lithium carbonate offtake certainty.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate cell procurement, with pricing stratifying across UN ECE R100-certified premium tiers, standard automotive qualification tiers, and economy aftermarket lead-acid replacement tiers. Price differentiation hinges on certification grade and volume scale, with OEM direct contracts commanding 15-20% premiums over tolling arrangements. Pricing pressure stems from lithium salt volatility forcing cathode producers to renegotiate force majeure clauses. Fleet operators consolidating through vehicle-as-a-service contracts exhibit lowest price sensitivity, while individual aftermarket consumers remain most elastic.
Supply Chain Analysis
Inventory compression at separator film producers has extended wet-process polypropylene lead times to fourteen weeks, exposing European gigafactories to single-source vulnerability. Supply concentrates in China, South Korea, and Japan for cathode active materials, separator films, and electrolyte additives respectively. Raw material dependencies rest on lithium carbonate from South American brine operations, nickel sulfate from Indonesian integrated facilities, and cobalt hydroxide from Central African copperbelt refiners. Distribution runs through long-term offtake contracts with quarterly price renegotiation rather than spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation in California and the Netherlands has shifted buyer power toward volume-contract holders, fragmenting pricing leverage previously concentrated with OEM direct purchasing departments.
For Market Incumbents: Shield market position by accelerating backward integration into cathode active material refining in Belgium and Finland to meet EU Battery Regulation recycled content thresholds. Prioritize UN ECE R100 certification investment ahead of 2027 model-year lock-ins to defend against emerging Chinese LFP challengers with faster validation timelines.
For New Entrants and Emerging Players: UN ECE R100 fast-track certification programs in Germany offer qualification acceleration for cell-to-pack architectures targeting commercial van fleet operators in the Netherlands. White-space opportunities concentrate in second-life stationary storage repurposing and India PLI-subsidized two-wheeler battery manufacturing. Go-to-market positioning should emphasize guaranteed cycle life performance rather than upfront cell cost to differentiate from incumbent commodity suppliers.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive separator film production but lacking automotive traction battery qualification. Long-term viability centers on hydrometallurgical refining partnerships and solid-state pilot line throughput rather than commodity cell capacity expansion. Watch solid-state ceramic separator thickness miniaturization below 20 microns as the inflection signal for 2028 luxury platform adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Multi-year offtake contracts with Detroit OEMs lock in cathode material allocation ahead of EPA Tier 3 compliance deadlines. |
| Backward Integration | Captive lithium carbonate refining in Chile and Australia hedges against South American brine supply disruptions. |
| Geographic Manufacturing Footprint | Tennessee and Michigan cell-to-pack assembly capacity serves domestic OEM platforms under IRA domestic content incentives. |
| Platform Standardization | Cell format harmonization across 400V and 800V architectures reduces tooling duplication for European luxury OEMs. |
| Charging Infrastructure Partnership | 350 kW DC fast-charging protocol alignment with silicon-anode cell qualification enables premium electric vehicle range claims. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributor operations managers, and cell producer R&D leads provided ongoing calibration across quarterly review cycles. Primary interview findings triangulated against customs trade data for lithium carbonate and cathode precursor movements, SEC filings from integrated chemical conglomerates, vehicle production databases tracking electrified platform launches, and MIIT GB standard certification registries. Bottom-up cell capacity buildouts reconciled with top-down OEM electrification commitment announcements.
Consistency checks validated volume and value outputs against IEA electric vehicle deployment projections, EIA battery storage installation records, and EU Battery Regulation implementation timelines. Segmentation modeling spanned battery chemistry, application architecture, end-user procurement type, and regional regulatory cluster across the analysis window. CAGRs derived from fitted growth curves incorporating lithium-ion pack cost trajectories and EPA tailpipe rule stringency schedules.
Underlying assumptions cover lithium carbonate price stabilization, UN ECE R100 certification timeline adherence, and PLI scheme disbursement continuity, with deviation risk concentrated in solid-state technical delays and separator supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
EV Battery Heating System Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
China EV Battery Pack Market
EV Batteries
US EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Germany EV Battery Pack Market