
 Microseismic Monitoring Technology Market | 2026-2036
Microseismic Monitoring Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Microseismic Monitoring Technology Market Outlook
Geothermal developers and carbon sequestration operators are reorganizing procurement priorities for microseismic arrays as hydrocarbon majors scale back exploration budgets. Schlumberger Limited leverages its integrated geomechanics platform to anchor long-term service contracts across North American shale plays. Halliburton Company competes through dense sensor networks optimized for real-time fracture diagnostics. Baker Hughes Company differentiates via fiber-optic distributed acoustic sensing systems that extend monitoring reach beyond conventional geophone limits.
Microseismic monitoring technology encompasses subsurface sensing instrumentation, data acquisition hardware, and analytical software that detects, locates, and characterizes acoustic emissions from rock mass deformation, typically resolving events between moment magnitude -3.0 and 2.0 at depths from hundreds of meters to several kilometers. The primary industrial purpose spans hydraulic fracture mapping, reservoir compaction tracking, caprock integrity verification, and induced seismicity management across energy and geotechnical sectors. Seismic sensors and distributed acoustic sensing systems capture the dominant share of hardware expenditure as operators prioritize channel count and signal fidelity over legacy geophone deployments. Monitoring software and interpretation tools represent the fastest-expanding margin pool where machine-driven event classification and cloud-based visualization are displacing manual processing workflows.
The US EPA underground injection control program and the EU Green Deal's carbon storage certification frameworks are mandating continuous microseismic surveillance for Class VI wells and CO2 storage sites, directly expanding addressable instrumentation demand. China's GB standards for mine safety and India's CEA seismic monitoring directives for hydropower projects are creating parallel compliance-driven procurement channels across Asia. Stakeholders must evaluate whether to build captive interpretation capabilities or partner with specialized analytics providers as regulatory granularity intensifies and data volumes scale exponentially.
Market Dynamics
Regulatory mandates for continuous subsurface surveillance are compressing deployment timelines and forcing operators to choose between building captive analytics capabilities or outsourcing to specialized providers as data volumes scale exponentially.
Growth Catalysts
- EPA Class VI Well Mandates:The US EPA's underground injection control program now requires continuous microseismic monitoring for carbon sequestration sites, directly expanding instrumentation procurement for CO2 storage operators.
- Hydraulic Fracture Mapping Intensification:Unconventional oil and gas operators in the Permian Basin are deploying denser passive monitoring arrays to characterize complex fracture networks in multi-well pad developments.
- Geothermal Expansion:Enhanced geothermal systems developers are repurposing microseismic arrays originally designed for hydrocarbon applications to monitor reservoir stimulation and induced seismicity risks.
Market Restraints
- Sensor Hardware Cost Concentration:High-channel-count acquisition systems and fiber-optic distributed acoustic sensing cables remain concentrated among a limited supplier base, creating input cost volatility for procurement teams.
- Technical Resolution Limits:Conventional geophone deployments struggle to resolve microseismic events below moment magnitude -2.0 in noisy near-surface environments, constraining shallow monitoring applications.
- EU Green Deal Compliance Friction:Carbon storage certification frameworks require extensive baseline seismic surveys before injection permits, extending project timelines and front-loading capital requirements.
Strategic Opportunities
- India Hydropower Monitoring:The Central Electricity Authority's seismic monitoring directives for large dam projects are creating new procurement channels for real-time rock mass stability systems.
- Machine Learning Convergence:Cloud-based event classification algorithms trained on labeled waveform databases are reducing manual processing bottlenecks and enabling automated alert systems for induced seismicity.
- Mine Safety Applications:China's GB standards for underground coal mine safety are mandating microseismic monitoring for rockburst prediction, opening industrial minerals and hard-rock mining segments.
Industry Challenges
- Geophysicist Talent Scarcity:The specialized skill set required for waveform analysis and moment tensor inversion is concentrated among a shrinking pool of experienced practitioners, constraining interpretation service scaling.
- Legacy System Integration Complexity:Operators with decades of analog geophone networks face costly retrofitting challenges when migrating to digital acquisition platforms with real-time telemetry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microseismic Monitoring Technology Market |
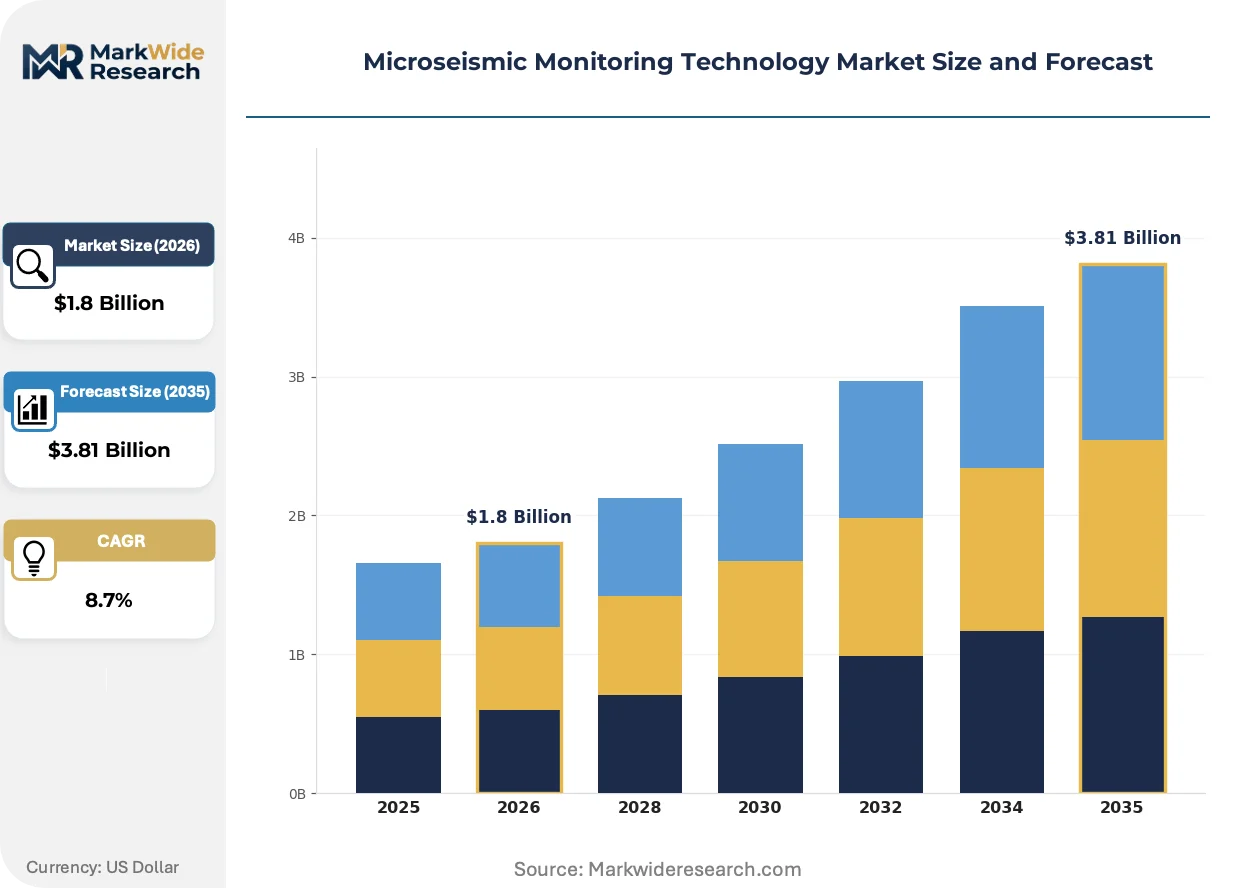
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismic Sensors, Data Acquisition Systems, Monitoring Software, Interpretation Tools End User: Oil & Gas Companies, Mining Firms, Construction Companies, Research Institutions Installation: Onshore, Offshore, Underground, Surface Technology: Passive Monitoring, Active Monitoring, Distributed Acoustic Sensing, Geophone Systems |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Geospace Technologies Corporation, MicroSeismic Inc., ESG Solutions, Silixa Ltd, OptaSense, Güralp Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microseismic Monitoring Technology Market Strategic Shifts
Passive seismic monitoring hardware is bifurcating into two distinct performance tiers as operators segment procurement between high-fidelity research-grade arrays and cost-optimized compliance-only systems. This technological divergence is reshaping vendor R&D priorities and service contract structures across energy and geotechnical sectors.
Distributed acoustic sensing technology is bifurcating the traditional geophone market by converting standard fiber-optic cables into dense seismic arrays. Oilfield service providers are deploying DAS systems along existing wellbores and pipelines, achieving channel counts orders of magnitude higher than nodal geophone deployments at comparable installed cost. The structural consequence is compressing margins for conventional sensor manufacturers while expanding addressable monitoring geometry into previously inaccessible wellbore configurations.
The EU Green Deal's carbon storage certification frameworks are mandating pre-injection baseline seismic surveys and continuous post-closure monitoring periods extending decades beyond operational life. This regulatory architecture is forcing CO2 storage developers to budget for long-term instrumentation maintenance and data archival infrastructure. European project developers are responding by negotiating multi-decade service contracts with monitoring providers rather than capitalizing one-time hardware purchases.
Buyer contracting patterns are rotating from capital equipment purchases toward integrated monitoring-as-a-service agreements. Geothermal developers and carbon sequestration operators now favor subscription-based arrangements where vendors retain ownership of sensor networks and deliver interpreted event catalogs rather than raw waveforms. This shift is most visible in North American shale plays where operators face pressure to reduce capital intensity while maintaining regulatory compliance coverage.
Microseismic Monitoring Technology Market Segmentation
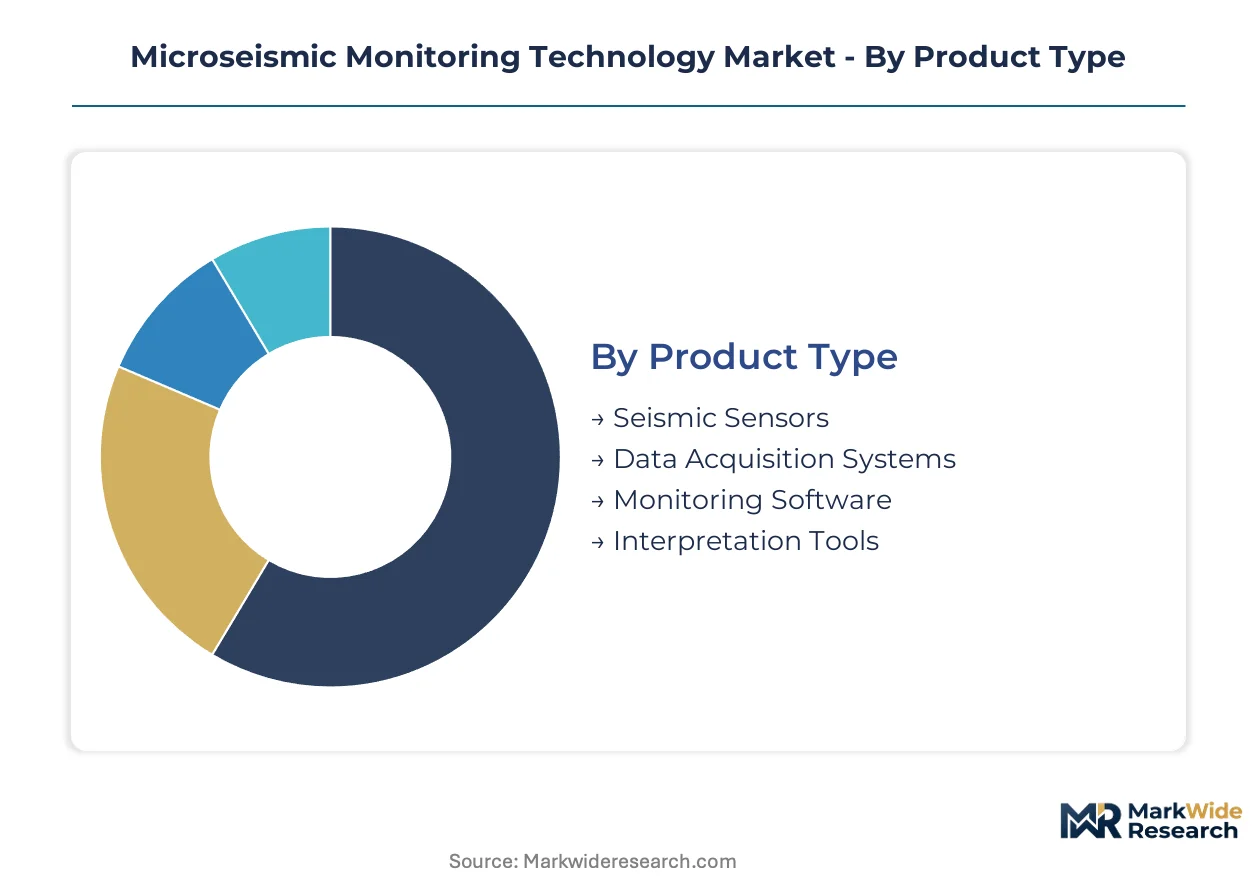
Microseismic monitoring technology segments around distinct hardware-software boundaries and deployment contexts that shape procurement economics. Channel strategies diverge sharply between capital-intensive sensor sales and recurring software subscriptions.
Product Type:
Channel economics bifurcate between one-time hardware transactions and recurring software licenses, with vendors pursuing divergent margin strategies across each tier.
- Seismic Sensors:Piezoelectric and MEMS-based geophones detect ground velocity variations with frequency response calibrated for 1 Hz to 1 kHz bandwidth. Permian Basin operators are concentrating procurement for multi-well pad arrays where channel density drives fracture mapping resolution. DAS fiber-optic interrogators are displacing conventional nodal deployments in new installations.
- Data Acquisition Systems:Multi-channel digitizers with GPS-synchronized timing enable real-time telemetry from field arrays to processing centers. Oil and gas service contracts now specify acquisition hardware as bundled infrastructure rather than standalone purchases, compressing visible revenue for equipment vendors.
- Monitoring Software:Event detection algorithms and cloud-based visualization platforms are migrating to SaaS delivery models. Mining safety regulators in China are mandating automated alert capabilities that favor subscription-based code over perpetual licenses.
- Interpretation Tools:Moment tensor inversion and source mechanism analysis modules require specialized geophysicist workflows. Research institutions represent the residual on-premise installation base resistant to cloud migration.
Seismic sensors dominate installed base. Monitoring software is where expansion concentrates.
End User:
Procurement authority concentrates differently across sectors, with regulated industries favoring long-term service contracts and private operators retaining equipment ownership.
- Oil & Gas Companies:Unconventional reservoir operators in Texas and New Mexico deploy passive arrays for hydraulic fracture mapping and induced seismicity compliance. Capital discipline is shifting procurement toward monitoring-as-a-service structures where vendors retain sensor ownership.
- Mining Firms:Underground coal and hard-rock operations use microseismic arrays for rockburst prediction and pillar stability assessment. China's GB mine safety standards are mandating continuous monitoring systems for high-stress extraction environments.
- Construction Companies:Tunnel boring and foundation work applications require portable, rapid-deployment sensor networks for ground stability verification. Urban infrastructure projects in India are creating demand for real-time vibration monitoring during metro expansion.
- Research Institutions:Academic and government laboratories operate reference-grade arrays for crustal deformation studies and induced seismicity research. Funding cycles favor modular, upgradeable hardware platforms over integrated commercial systems.
Oil and gas companies anchor hardware revenue. Mining firms are climbing the fastest as safety mandates tighten.
Installation:
Deployment geometry determines sensor specification, telemetry architecture, and maintenance access economics for each configuration.
- Onshore:Surface and shallow-buried arrays for unconventional oil and gas and geothermal development. Permian Basin deployments favor wireless nodal systems that minimize surface disturbance and permitting complexity.
- Offshore:Ocean-bottom cable and autonomous node deployments for reservoir monitoring and platform integrity assessment. Harsh environment specifications concentrate supply among marine seismic specialists.
- Underground:Borehole and tunnel-mounted installations for mining safety and deep geological storage verification. Carbon sequestration Class VI well requirements are expanding demand for deep monitoring infrastructure.
- Surface:Near-surface arrays for construction, dam safety, and environmental compliance applications. India's Central Electricity Authority directives for hydropower projects are standardizing surface network specifications.
Onshore installations dominate unit volume. Underground configurations are gaining share fastest as carbon storage and mining safety regulations expand.
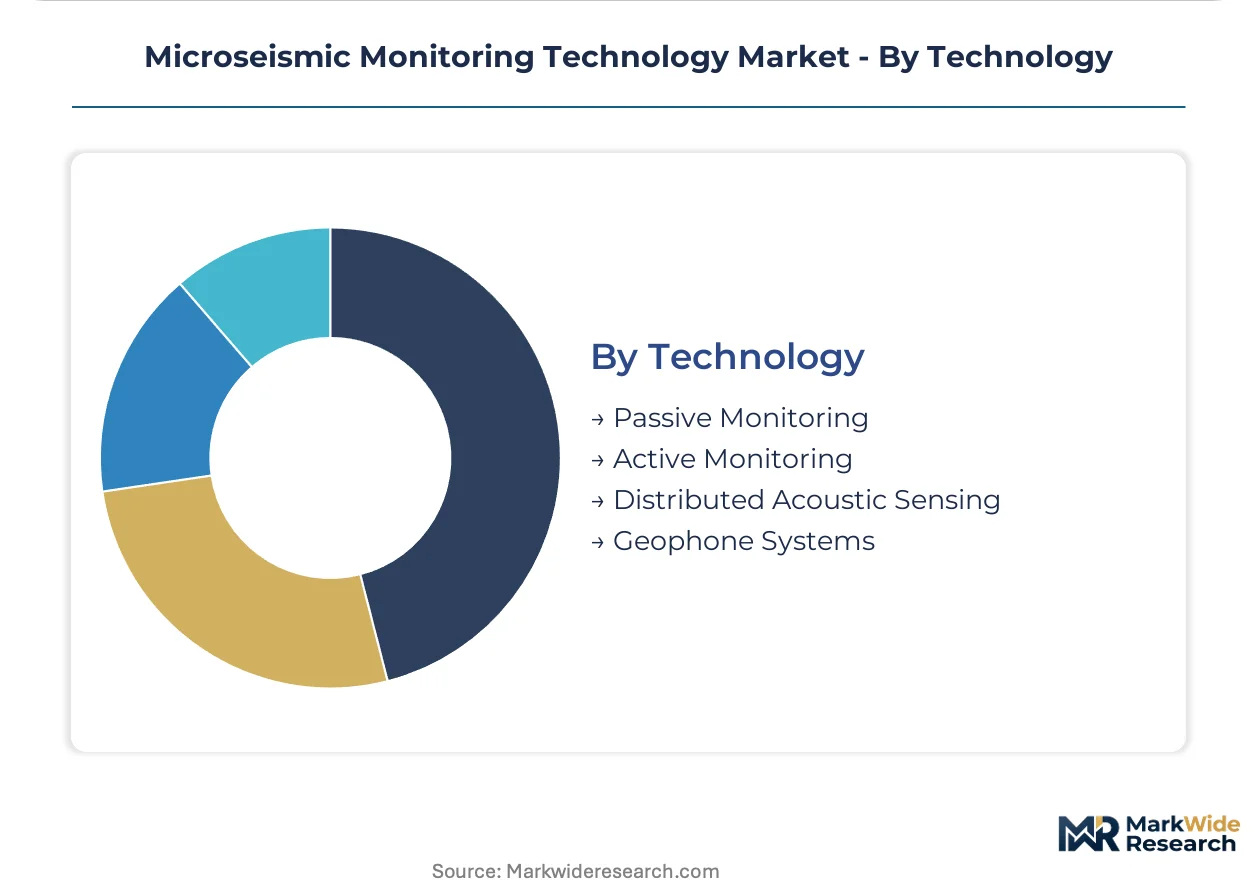
Technology:
Technical performance tiers are fragmenting the vendor landscape between high-resolution research systems and cost-optimized compliance platforms.
- Passive Monitoring:Continuous recording of naturally occurring or induced microseismic events without artificial energy sources. Unconventional oil and gas operators rely on passive arrays for hydraulic fracture geometry characterization in multi-stage completions.
- Active Monitoring:Controlled-source seismic methods including crosswell tomography and time-lapse surveys for reservoir property calibration. Geothermal developers employ active techniques for reservoir stimulation monitoring where induced event magnitudes exceed passive detection thresholds.
- Distributed Acoustic Sensing:Fiber-optic cables converted into dense seismic arrays through coherent Rayleigh backscatter interrogation. DAS achieves channel counts orders of magnitude above nodal geophones at comparable installed cost, compressing margins for conventional sensor manufacturers.
- Geophone Systems:Traditional velocity transducers with proven reliability in harsh subsurface environments. Legacy installed base and established interpretation workflows sustain demand despite displacement pressure from optical alternatives.
Geophone systems anchor the installed base. Distributed acoustic sensing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oilfield service buyers concentrate procurement authority in Texas and New Mexico, while carbon storage operators in Europe and mining safety mandates in Asia are redistributing demand across three distinct regulatory zones.
United States
Permian Basin operators deploy dense passive arrays for multi-well pad fracture mapping while EPA Class VI mandates force CO2 storage developers into continuous monitoring contracts. The EPA underground injection control program now requires real-time seismic surveillance for carbon sequestration permits. Houston anchors vendor headquarters and service logistics for North American shale plays.
China
Underground coal operators face mandatory microseismic installation under GB mine safety standards for rockburst prediction in high-stress extraction environments. The MIIT dual carbon goals are accelerating carbon capture pilot projects that replicate hydrocarbon monitoring architectures. Shanxi Province coal basins represent the densest concentration of mine safety procurement.
Germany
Geothermal developers in the Upper Rhine Graben repurpose oilfield microseismic arrays for reservoir stimulation monitoring and induced seismicity compliance. The EU Green Deal carbon storage certification frameworks mandate decades-long post-closure surveillance periods. Berlin-based research institutions coordinate European reference-grade array standards.
India
Hydropower developers install surface seismic networks under Central Electricity Authority directives for large dam rock mass stability assessment. The CEA seismic monitoring mandates are standardizing procurement specifications across Himalayan and Western Ghats projects. Maharashtra and Himachal Pradesh contain the most active dam construction corridors.
Australia
Hard-rock mining operations in Western Australia deploy microseismic systems for pit wall stability and underground rockburst risk management. The country's mining safety regulators are harmonizing state-level seismic monitoring requirements for tier-one producers. The Kalgoorlie-Norseman belt concentrates underground gold mining procurement.
Microseismic Monitoring Technology Market Competitive Environment
Player mix skews toward integrated oilfield service conglomerates with captive geomechanics platforms, while fiber-optic sensing specialists and regional interpretation boutiques occupy profitable niches. Three archetypes dominate: full-service energy technology providers with bundled hardware-software contracts, distributed acoustic sensing pure-plays exploiting fiber-optic displacement of conventional geophones, and mining-focused safety system integrators leveraging regulatory compliance mandates. Competitive moves concentrate on multi-decade monitoring-as-a-service contract structures and machine learning convergence for automated event classification.
Among integrated service providers, Schlumberger Limited, Halliburton Company, and Baker Hughes Company occupy positions as archetype anchors for bundled subsurface monitoring platforms. These firms exemplify the shift toward retained-ownership sensor networks and subscription-based interpretation delivery rather than capital equipment transactions. Their scale advantages concentrate in North American shale plays where operator capital discipline favors operational expenditure structures over upfront hardware procurement.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Geospace Technologies Corporation |
| MicroSeismic Inc. |
| ESG Solutions |
| Silixa Ltd |
| OptaSense |
| Güralp Systems Ltd. |
| Others |
Value Chain & Pricing Dynamics
Monitoring-as-a-service contracts with 10-year duration lock in supply access for DAS fiber-optic interrogators while capping price volatility for Permian Basin operators facing EPA Class VI compliance deadlines. This structure transfers sensor ownership risk to vendors and compresses upfront capital requirements for carbon sequestration developers.
Pricing Analysis
Cost-plus arrangements with labor and electronics indexation dominate North American service contracts, insulating vendors from MEMS geophone component inflation while exposing buyers to telemetry bandwidth escalation. Pricing stratifies across premium research-grade arrays, standard multi-well pad configurations, and economy single-borehole compliance systems. Margins are tightening due to DAS displacement pressure on conventional geophone manufacturers. Mining safety procurement under China's GB standards exhibits highest price sensitivity; oilfield bundled services show lowest.
Supply Chain Analysis
Container availability constraints on the Asia-North America trade lane inflate inbound logistics costs for MEMS accelerometers and piezoelectric crystals sourced from Japanese and South Korean foundries. Manufacturing concentrates in the United States, China, and Germany for acquisition hardware; fiber-optic cable drawing centers on China and the United States. Single-source vulnerability persists for coherent Rayleigh backscatter interrogator chipsets. Distribution runs through oilfield service logistics hubs in Houston and integrated safety system integrators in Shanxi Province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates defensive moats for established players as EPA Class VI mandates and EU Green Deal certification frameworks impose multi-decade surveillance obligations that new entrants cannot shortcut.
For Market Incumbents: Secure multi-decade monitoring-as-a-service contracts with CO2 storage developers before competitor fiber-optic platforms achieve scale. Lock in exclusive DAS interrogator supply agreements with Chinese cable manufacturers to forestall margin erosion from commoditized hardware. The threat is pure-play DAS specialists capturing share in geothermal applications. For New Entrants and Emerging Players: Anchor in India's hydropower monitoring segment where CEA seismic directives are standardizing procurement specifications ahead of vendor consolidation. Target construction companies in urban metro expansion projects for rapid-deployment portable arrays. Partner with regional interpretation boutiques to bypass captive geophysicist scarcity. For Investors and Strategic Acquirers: Fiber-optic sensing pure-plays with proprietary interrogator architectures represent the most defensible acquisition profile. Long-term viability hinges on regulatory permanence of induced seismicity mandates across carbon storage and geothermal sectors. Watch for EPA enforcement intensity on Class VI well violations as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Monitoring-as-a-Service Contract Expansion | Retained-ownership sensor networks reduce capital intensity for Permian Basin operators facing EPA compliance. |
| DAS Interrogator Technology Licensing | Coherent Rayleigh backscatter patents enable channel-count advantages over nodal geophone deployments. |
| Machine Learning Event Classification | Cloud-trained algorithms automate induced seismicity alerts for China's GB mine safety mandates. |
| Backward Integration into Fiber-Optic Cable | Captive supply of sensing-grade fiber reduces input cost volatility for DAS system manufacturers. |
| Geographic Expansion into India Hydropower | CEA seismic monitoring directives standardize procurement specifications across Himalayan dam projects. |
Study Parameters
The analysis maps passive monitoring arrays, DAS fiber-optic systems, active seismic methods, and interpretation software modules, each validated through primary interviews with reservoir geophysicists, oilfield procurement directors, mining safety engineers, and carbon storage project developers. Secondary sources include EPA UIC permit filings, EU Green Deal carbon storage certification frameworks, China MIIT dual carbon goal disclosures, and India CEA hydropower directives. Bottom-up channel count and top-down addressable well population estimates were triangulated against vendor shipment disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include hardware-software boundary, installation geometry, technology performance tier, and end-use regulatory framework. CAGRs were derived from instrument deployment run-rates and service contract renewal patterns. Industry-specific inputs incorporated EPA Class VI permit approval timelines and China GB standard enforcement intensity curves.
Decision-makers should treat outputs as directional under sustained regulatory enforcement of induced seismicity mandates; material deviation in EPA budget allocation or EU carbon storage subsidy levels would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Potentiometer Market
Sensors and Controls
Predictive Touch Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Thermometer Market