
 Voltage Sensor Market | 2026-2036
Voltage Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Voltage Sensor Market Insights
East Asian semiconductor foundries is realigning capacity toward automotive-grade sensing components. Texas Instruments Incorporated leverages its analog portfolio depth to sustain design-in relationships across tier-one automotive suppliers. Siemens AG anchors European industrial automation demand with integrated voltage monitoring in drive systems. LEM Holding SA specializes in isolated current and voltage sensing for traction inverters, competing on magnetic core expertise.
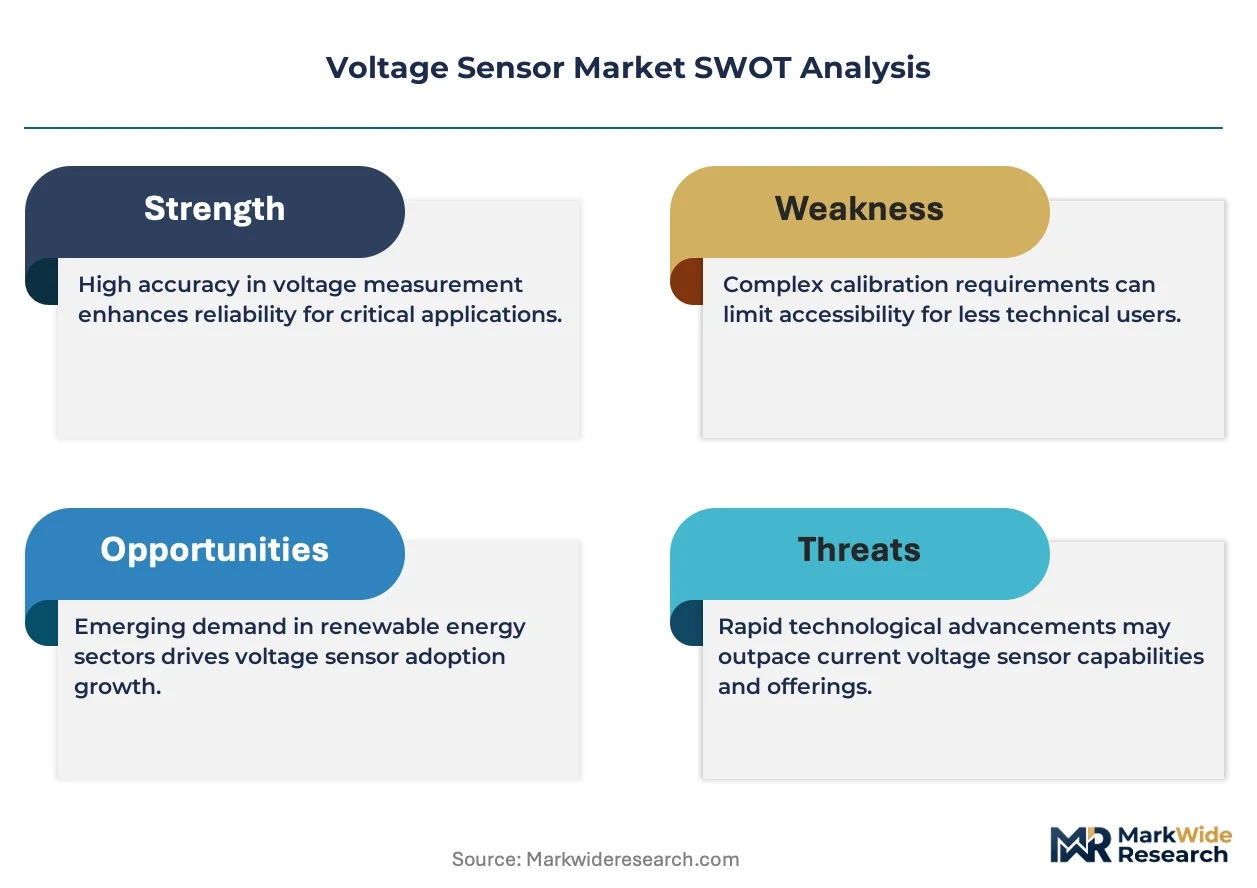
A voltage sensor detects and measures electrical potential difference between two points in a circuit, typically operating across ranges from millivolts to kilovolts with isolation ratings exceeding 2.5 kV for industrial applications. These devices convert analog voltage signals into measurable outputs for protection relays, battery management systems, and power quality monitors. Smart sensors and digital sensors capture expanding margin pools as embedded processing and bus connectivity replace passive analog outputs in automotive and renewable energy applications. Optical technology segments gain traction in high-voltage DC transmission where galvanic isolation proves critical, while resistive approaches dominate cost-sensitive consumer electronics.
FCC electromagnetic compatibility rules and IEC 61010 safety standards govern North American and European product access, forcing redesign cycles when emission thresholds tighten. China's GB standards and NMPA-equivalent certification bodies mandate local testing for grid-connected equipment, creating parallel approval tracks for multinational suppliers. Stakeholders must monitor how automotive functional safety standards propagate from passenger vehicles into commercial trucking and off-highway electrification.
Market Dynamics
The automotive electrification wave is compressing design cycles for voltage sensing architectures, as battery management systems demand higher isolation ratings and embedded diagnostics that legacy analog outputs cannot deliver.
Growth Catalysts
- Automotive functional safety mandates:ISO 26262 ASIL-D requirements for battery management systems in electric vehicles force adoption of redundant voltage monitoring architectures with built-in self-test capabilities.
- Grid-scale storage deployment:China's dual carbon goals accelerate utility-scale battery installations, each requiring hundreds of precision voltage sensors for cell-level monitoring and thermal runaway prevention.
- Optical isolation advances:Silicon photonics integration enables sub-microsecond response times in high-voltage DC transmission applications where magnetic core sensors face bandwidth limitations.
Market Restraints
- Automotive-grade silicon shortage:Foundry capacity constraints for AEC-Q100 qualified wafers extend lead times for voltage sensor ASICs beyond 40 weeks, freezing OEM qualification schedules.
- Rare earth magnet dependency:Hall-effect and fluxgate architectures rely on neodymium supply concentrated in Chinese refining operations, exposing cost volatility and export control risks.
- IEC 61010 redesign cycles:Tightening creepage and clearance requirements for industrial equipment force PCB re-spins and retesting, eroding margin on established product lines.
Strategic Opportunities
- Commercial trucking electrification:Heavy-duty vehicle battery packs above 800 V create demand for isolated sensors with extended temperature ranges that passenger car derivatives cannot satisfy.
- India PLI scheme for semiconductors:Domestic fabrication incentives under India's Ministry of Electronics and Information Technology attract voltage sensor packaging and test operations for regional automotive supply.
- Digital bus integration:CAN FD and Ethernet-APL protocols replace analog 4-20 mA loops in process automation, enabling predictive maintenance through embedded edge analytics.
Industry Challenges
- Functional safety engineering scarcity:ASIL-D system design expertise concentrates among tier-one automotive suppliers, constraining tier-two sensor vendors from direct OEM engagement.
- Multi-standard certification burden:Simultaneous UL, VDE, and GB compliance for a single industrial voltage sensor SKU extends validation timelines and fragments engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voltage Sensor Market |
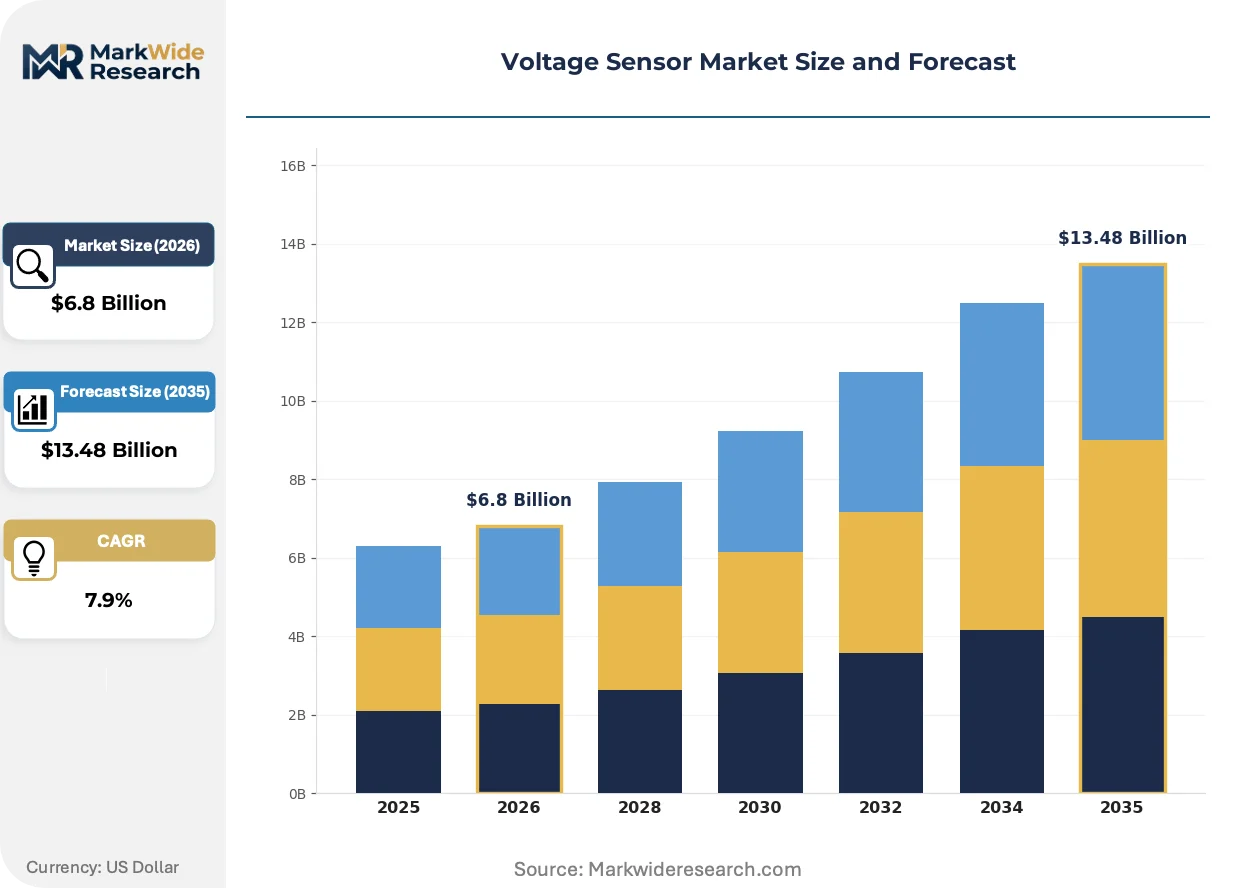
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Sensors, Digital Sensors, Smart Sensors, Capacitive Sensors Technology: Optical, Resistive, Capacitive, Magnetic Application: Power Distribution, Consumer Electronics, Automotive, Renewable Energy End User: Manufacturers, Utilities, Healthcare, Enterprises |
| Companies Covered | ABB Ltd., Siemens AG, Texas Instruments Incorporated, LEM Holding SA, Honeywell International Inc., Schneider Electric SE, Phoenix Contact GmbH & Co. KG, Murata Manufacturing Co., Ltd., TE Connectivity Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voltage Sensor Market Trends and Innovations
Digital output architectures with embedded microcontrollers are displacing passive analog sensors across automotive and renewable energy deployments, compressing bill-of-materials while enabling firmware-upgradeable measurement algorithms.
Optical voltage sensing based on Pockels effect crystals is overtaking resistive divider networks in 800 V and 1,500 V traction inverter applications. European and Chinese electric vehicle platforms specify these sensors for common-mode rejection exceeding 120 dB. The technology is overtaking incumbent magnetic solutions by eliminating saturation artifacts during rapid switching transients.
The EU's F-Gas Regulation phase-down of sulfur hexafluoride intensifies development of SF6-free gas-insulated switchgear, mandating optical voltage sensors for high-voltage substation monitoring where traditional instrument transformers depend on the banned dielectric medium. Manufacturers redesign GIS portfolios around dry-type sensors with integrated digital outputs. German and French transmission operators accelerate pilot deployments to meet 2030 reduction targets.
Automotive buyers now consolidate voltage sensor procurement with battery management system platforms rather than sourcing discrete components, compressing vendor lists and elevating system-level accountability. Tier-one suppliers absorb sensor specification authority previously held by OEM electrical engineering teams. This concentration is most visible in Chinese electric vehicle manufacturing where vertical battery-sensor integration dominates platform strategies.
Voltage Sensor Market Segmentation
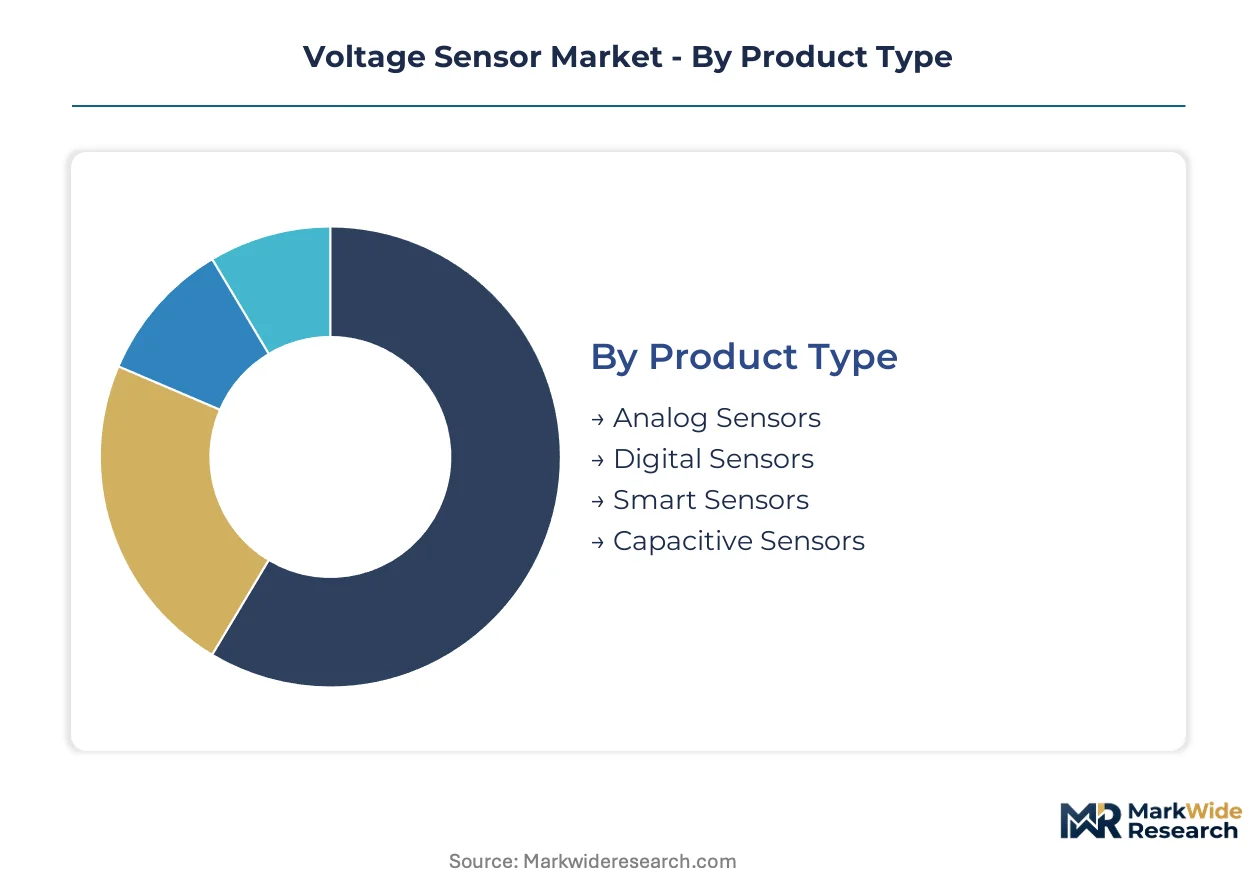
Voltage sensor architectures fragment across four critical dimensions: output signal format, physical sensing principle, deployment environment, and procurement authority. Each axis reveals divergent margin structures, certification burdens, and vendor consolidation patterns that reshape competitive positioning.
Product Type:
Buyers in this category differentiate by the intelligence embedded at the sensing node versus the cost of external signal conditioning.
- Analog Sensors:Continuous voltage output signals require external ADC conversion and isolation circuitry. Automotive battery management systems in China specify these for cell-level monitoring where cost-per-channel dominates procurement decisions.
- Digital Sensors:Embedded microcontrollers output serialized data over SPI or I2C buses, eliminating analog front-end components. Industrial automation in Germany and renewable energy deployments in Texas favor these for firmware-upgradeable measurement algorithms and predictive maintenance integration.
- Smart Sensors:Edge processing enables self-diagnostics and compensation for temperature drift without host controller intervention.
- Capacitive Sensors:Non-contact voltage detection suits high-impedance measurement in medical equipment and laboratory instrumentation.
Analog sensors lead volumes today; digital sensors are expanding most quickly as bus architectures displace 4-20 mA loops.
Technology:
Isolation bandwidth and common-mode rejection requirements separate applications across this axis.
- Optical:Pockels effect crystals and silicon photonics achieve sub-microsecond response with galvanic isolation exceeding 120 dB common-mode rejection. High-voltage DC transmission operators in China and 800 V traction inverter platforms in Europe specify these where magnetic saturation artifacts would corrupt measurements during rapid switching transients.
- Magnetic:Hall-effect and fluxgate architectures leverage neodymium-based magnetic cores for non-contact sensing in electric vehicle motor drives. Supply concentration in Chinese rare earth refining operations exposes cost volatility and export control risks.
- Resistive:Voltage divider networks dominate cost-sensitive consumer electronics where isolation requirements remain minimal.
- Capacitive:Electric field sensing enables compact form factors in wearable devices and portable medical monitors.
Magnetic technology anchors current revenue; optical approaches are climbing the fastest as silicon photonics integration matures.
Application:
Safety integrity levels and environmental exposure dictate specification stringency across deployment contexts.
- Automotive:ISO 26262 ASIL-D mandates force redundant voltage monitoring with built-in self-test capabilities for battery management systems. Electric vehicle manufacturers in China compress design cycles as platform voltages rise above 800 V, demanding isolation ratings legacy analog outputs cannot deliver.
- Renewable Energy:Grid-scale solar inverters and utility battery installations require precision cell monitoring for thermal runaway prevention. China's dual carbon goals accelerate deployments, each installation consuming hundreds of sensors.
- Power Distribution:SF6-free gas-insulated switchgear redesigns under EU F-Gas Regulation mandate optical sensors for high-voltage substation monitoring.
- Consumer Electronics:Battery fuel gauging in smartphones and laptops drives volume for low-cost resistive and capacitive variants.
Power distribution holds the steepest expansion trajectory; automotive maintains the largest absolute spend.
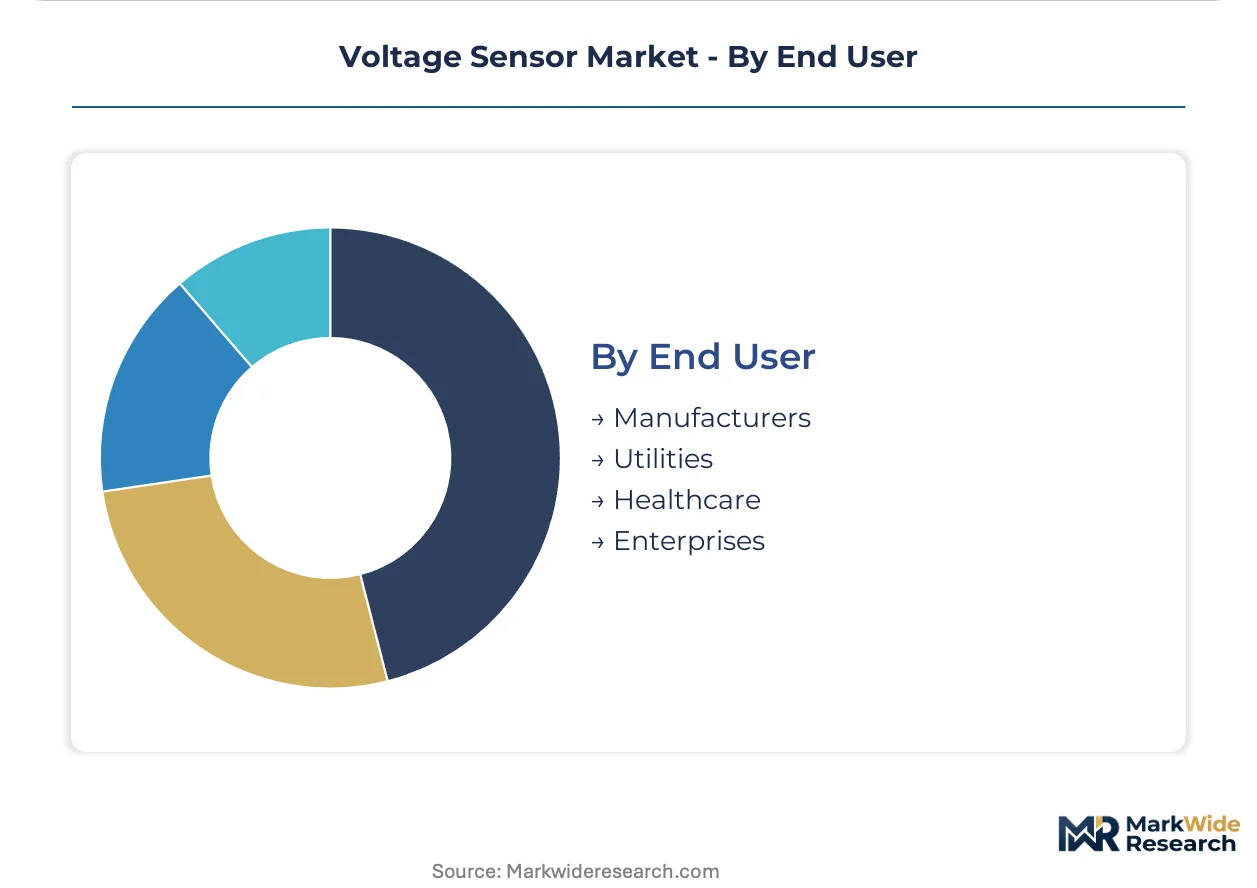
End User:
Procurement sophistication and vertical integration appetite separate buyers in this final axis.
- Utilities:Transmission operators in Germany and France specify integrated digital output sensors for SF6-free switchgear pilot programs targeting 2030 reduction deadlines. Long asset lifecycles and standardization requirements favor established suppliers with multi-decade field provenance.
- Manufacturers:Tier-one automotive suppliers absorb sensor specification authority previously held by OEM electrical engineering teams, consolidating vendor lists and elevating system-level accountability.
- Healthcare:Patient isolation requirements in diagnostic equipment drive demand for optical and capacitive technologies with medical-grade certifications.
- Enterprises:Data center power quality monitoring and building automation systems prioritize cost-optimized digital sensors with Ethernet-APL connectivity.
Manufacturers command the highest procurement volumes; utilities are gaining influence fastest as grid modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation base demands precision voltage monitoring at volumes exceeding France's grid modernization programs, yet both pale against China's electric vehicle production scale where battery management systems consume sensors by the millions.
China
Electric vehicle manufacturers in Shenzhen and Shanghai compress design cycles as platform voltages rise above 800 V, demanding isolation ratings legacy analog outputs cannot deliver. GB standards and MIIT certification protocols mandate local testing for grid-connected equipment, creating parallel approval tracks. The Yangtze River Delta anchors domestic automotive and grid-scale storage deployments where vertical battery-sensor integration dominates platform strategies.
Germany
Industrial automation in Bavaria and Baden-Württemberg sustains demand for integrated voltage monitoring in drive systems. The EU F-Gas Regulation phase-down of sulfur hexafluoride intensifies development of SF6-free gas-insulated switchgear, mandating optical sensors for high-voltage substation monitoring. Transmission operators in North Rhine-Westphalia accelerate pilot deployments to meet 2030 reduction targets.
United States
Renewable energy deployments in Texas favor digital sensors with firmware-upgradeable measurement algorithms for predictive maintenance integration. FCC electromagnetic compatibility rules govern product access, forcing redesign cycles when emission thresholds tighten. Data center power quality monitoring in Northern Virginia and building automation systems in California prioritize cost-optimized digital sensors with Ethernet-APL connectivity.
Japan
Automotive functional safety mandates propagate from passenger vehicles into commercial trucking electrification, with heavy-duty vehicle battery packs creating demand for isolated sensors with extended temperature ranges. METI and JIS standards shape domestic product requirements. The Kanto region around Tokyo concentrates semiconductor foundry capacity realignment toward automotive-grade sensing components.
India
The PLI scheme for semiconductors under the Ministry of Electronics and Information Technology attracts voltage sensor packaging and test operations for regional automotive supply. Domestic fabrication incentives target tier-two sensor vendors seeking direct OEM engagement. Maharashtra and Gujarat host emerging clusters where tier-one automotive suppliers consolidate procurement with battery management system platforms.
Voltage Sensor Market Competitive Landscape
European producers anchor one tier with integrated industrial automation portfolios; East Asian specialists hold another through magnetic core expertise and semiconductor integration. The market structures around three tiers: diversified conglomerates with broad sensing portfolios, pure-play magnetic sensing specialists, and analog semiconductor houses with automotive design-in relationships. Strategic moves concentrate on M&A for functional safety engineering capabilities and foundry partnerships for AEC-Q100 qualified wafer supply.
Among diversified European industrials, ABB Ltd. and Siemens AG exemplify the conglomerate archetype with integrated voltage monitoring embedded within broader automation and power infrastructure offerings. Texas Instruments Incorporated occupies a position bridging analog semiconductor depth with tier-one automotive supplier relationships, while LEM Holding SA represents the pure-play specialist model concentrated on isolated sensing architectures. These three anchors illustrate the competitive vectors: breadth versus depth, system integration versus component specialization, and geographic proximity to demand clusters.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Texas Instruments Incorporated |
| LEM Holding SA |
| Honeywell International Inc. |
| Schneider Electric SE |
| Phoenix Contact GmbH & Co. KG |
| Murata Manufacturing Co., Ltd. |
| TE Connectivity Ltd. |
| Others |
Pricing and Supply Chain Analysis
Neodymium oxide pricing indices cascade through voltage sensor manufacturing tiers, compressing margins on magnetic Hall-effect architectures while amplifying cost advantages for optical silicon photonics alternatives in high-isolation applications.
Pricing Analysis
Distributor markups of 15-25% separate direct-to-OEM contract pricing from spot-market component sales. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-tier variants reflects certification burden and volume scale. Pricing pressure stems from foundry capacity constraints for AEC-Q100 qualified wafers extending lead times. Chinese electric vehicle manufacturers exhibit highest price sensitivity at cell-level monitoring channels, while German transmission operators accept premium positioning for SF6-free switchgear sensors.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese rare earth refining operations, with secondary concentration in Malaysian and Australian extraction. Silicon photonics foundry capacity draws from Taiwan, South Korea, and Japan. Ceramic substrate and precision resistor networks feed from Japanese and German specialty component producers. Single-source vulnerability in rare earth processing exposes magnetic sensor architectures to export control disruption. Distribution runs through tier-one automotive suppliers consolidating procurement with battery management system platforms, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The voltage sensor market represents a late-cycle quality story as automotive electrification shifts procurement toward ASIL-D certified architectures with embedded diagnostics and firmware-upgradeable measurement algorithms.
For Market Incumbents: Lock in foundry partnerships for AEC-Q100 qualified wafer supply to freeze out emerging competitors during capacity-constrained periods. Deepen backward integration into silicon photonics packaging to capture margin migrating from magnetic core architectures. Defensive consolidation around functional safety engineering capabilities counters tier-two vendors seeking direct OEM engagement.
For New Entrants and Emerging Players: Launch via direct engagement with Indian PLI scheme beneficiaries seeking localized packaging and test operations for regional automotive supply. Target commercial trucking electrification segments where extended temperature range requirements exceed passenger car derivative specifications. White-space exists in Ethernet-APL enabled industrial sensors for predictive maintenance integration.
For Investors and Strategic Acquirers: Consolidation pressure builds where ASIL-D system design expertise concentrates among tier-one automotive suppliers, constraining tier-two sensor vendors from scaling. Long-term viability favors analog semiconductor houses with tier-one design-in relationships over pure-play magnetic specialists exposed to rare earth volatility. Watch silicon photonics integration maturity as inflection indicator for optical technology share capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for AEC-Q100 Wafers | Secures capacity for automotive-grade voltage sensor ASICs during supply-constrained periods. |
| Silicon Photonics Integration Investment | Enables sub-microsecond response times for 800V traction inverter applications in European EV platforms. |
| Functional Safety Engineering Acquisition | Builds ASIL-D system design capabilities for direct OEM engagement beyond tier-one supplier channels. |
| India PLI Scheme Localization | Captures domestic fabrication incentives for regional automotive supply chain integration. |
| SF6-Free Switchgear Sensor Development | Aligns with EU F-Gas Regulation phase-down mandates for German and French transmission operators. |
Research Methodology
Bottom-up electric vehicle and grid-scale storage modeling reconciled against top-down semiconductor foundry capacity tracking forms the analytical core. Primary interviews with tier-one automotive supplier procurement officers, battery management system platform engineers, industrial automation technical directors, and transmission operator asset managers combined with secondary validation from IEC and GB standards documentation, SEC filings of listed sensor manufacturers, and MIIT certification registry data. Cross-referencing production volume databases with component bill-of-materials estimates enables triangulation.
Input-output matrices map voltage sensor demand across propulsion architecture, isolation rating tier, and regional regulatory cluster. Output signal format, sensing technology, and procurement authority dimensions structure the segmentation model. CAGRs derive from regression analysis of historical adoption curves against policy-driven deployment schedules. Forecast inputs include automotive platform voltage roadmaps and utility-scale battery installation pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export control escalation or accelerated silicon photonics cost reduction. Automotive functional safety standard propagation and F-Gas Regulation enforcement timelines anchor assumption sensitivity. Material deviation in foundry capacity allocation or neodymium supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
Printed Antenna Market