
 Gesture Control Market | 2026-2036
Gesture Control Market Size, Share, and Industry Trends Forecast 2026-2036
Gesture Control Market Analysis
Silicon photonics is consolidating as the dominant sensing substrate for mid-range gesture modules, displacing bulkier discrete infrared LED assemblies. Intel Corporation leverages its RealSense depth-sensing portfolio to anchor design wins across industrial automation clients. Qualcomm Technologies, Inc. competes by integrating gesture inference directly into Snapdragon mobile platforms, reducing bill-of-materials overhead for Android OEMs. Samsung Electronics Co., Ltd. dominates consumer electronics deployment through its proprietary camera-to-UI pipeline in smart television product lines.
Gesture control encompasses non-contact human-machine interfaces that interpret hand, body, or facial movements through optical, electromagnetic, or acoustic sensing modalities, typically operating at 30-120 frames per second with sub-centimeter spatial resolution to trigger device commands without physical touch. The technology serves automotive, healthcare, and consumer electronics sectors where hygiene, safety, or convenience priorities restrict conventional input methods. Vision-based systems lead absolute revenue contribution due to mature camera supply chains and smartphone integration scale, while ultrasonic arrays represent the fastest-expanding category as they operate reliably in low-light industrial environments where optical occlusion limits camera performance. Sensors capture concentrated margin pools because MEMS foundry partnerships and calibration IP create defendable supply positions against commoditized controller hardware.
FCC equipment authorization requirements govern radio-frequency gesture sensors deployed in US consumer products, while EU REACH compliance constrains material selection for wearable device housings and RoHS directives limit heavy-metal content in soldered camera modules. Automotive gesture systems face NHTSA distraction-guideline scrutiny in the United States and must satisfy ECE R79 steering-control exemptions in European type-approval frameworks. Stakeholders must monitor whether IEC functional-safety standards for gesture-enabled robotics will harmonize across jurisdictions or fragment certification pathways.
Market Dynamics
Camera-based vision systems are absorbing the premium automotive cabin segment as OEMs abandon discrete infrared arrays to meet NHTSA distraction-reduction mandates and ECE R79 type-approval frameworks.
Growth Catalysts
- Automotive HMI mandates:NHTSA guidelines and ECE R79 exemptions in Europe compel OEMs to integrate touchless controls that reduce driver distraction in flagship electric vehicle lines.
- Silicon photonics maturation:MEMS foundry partnerships enable sub-centimeter spatial resolution at 30-120 frames per second, collapsing cost structures for mid-range gesture modules.
- Healthcare hygiene protocols:Post-pandemic clinical environments in Germany and Japan prioritize non-contact interfaces to minimize pathogen transmission on shared medical equipment.
Market Restraints
- Optical occlusion limits:Vision-based systems fail in low-light industrial environments where dust, steam, or physical barriers block camera sightlines, ceding ground to ultrasonic alternatives.
- Calibration IP concentration:Defendable margin pools cluster with a handful of MEMS foundries possessing proprietary sensor fusion algorithms, creating supply bottlenecks.
- FCC authorization friction:Radio-frequency gesture sensors face extended equipment authorization timelines in the United States, delaying product launches by 6-18 months.
Strategic Opportunities
- Industrial ultrasonic expansion:Manufacturing facilities in Bavaria and Stuttgart deploy acoustic arrays where optical systems cannot operate, opening white space in automotive assembly lines.
- Snapdragon integration pathway:Mobile platform consolidation enables Android OEMs to embed gesture inference without discrete controller hardware, reducing bill-of-materials overhead.
- EU AI Act compliance services:Emerging demand for explainable gesture-recognition algorithms creates consulting revenue streams around algorithmic transparency requirements.
Industry Challenges
- Functional safety certification:IEC standards for gesture-enabled robotics remain unharmonized across jurisdictions, forcing manufacturers to pursue redundant certification pathways.
- Legacy system integration:Automotive Tier 1 suppliers struggle to retrofit camera-to-UI pipelines into existing infotainment architectures without complete platform redesigns.
- MEMS talent scarcity:Specialized calibration engineers command premium compensation in Dresden and Eindhoven, constraining module production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gesture Control Market |
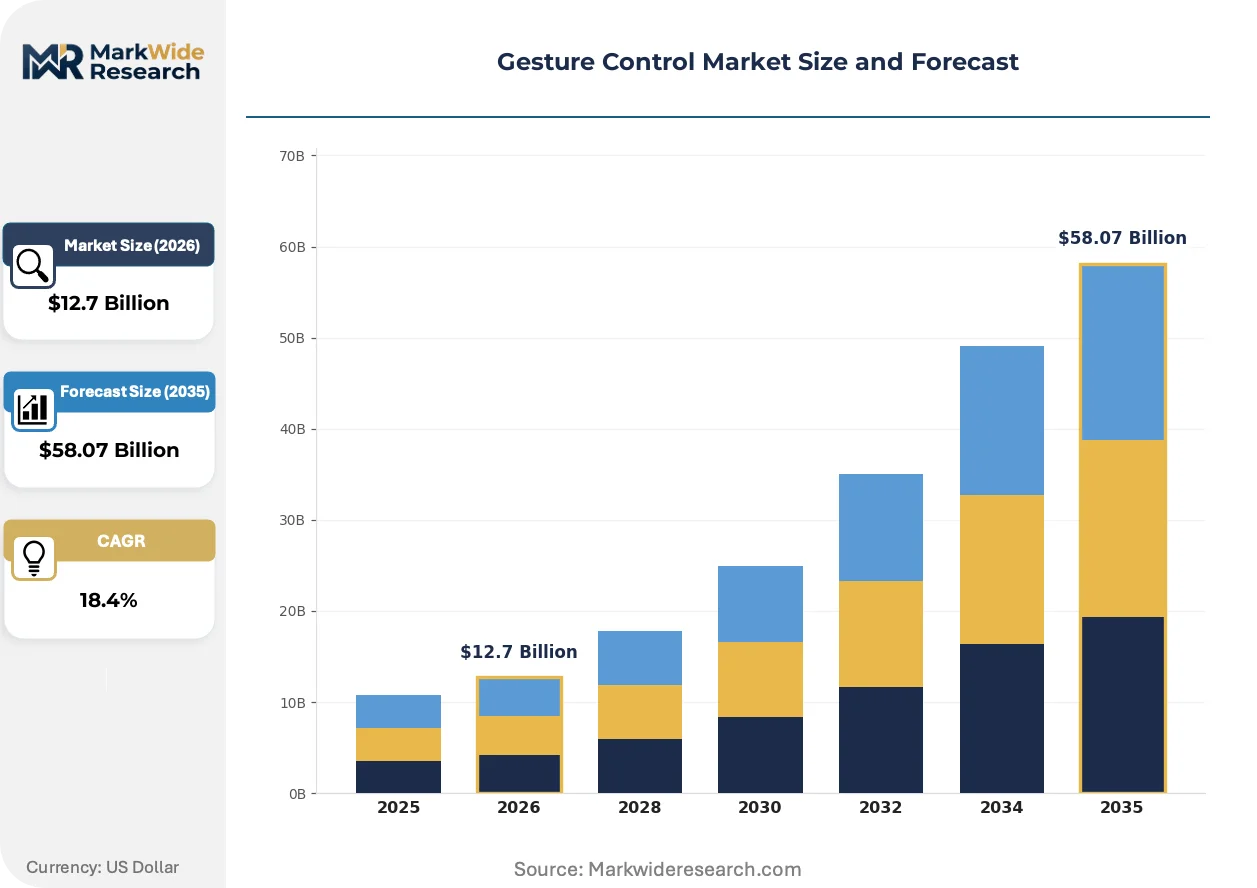
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Vision-Based, Electromagnetic, Ultrasonic, Infrared End User: Consumer Electronics, Automotive, Gaming, Healthcare Application: Smart Home, Robotics, Virtual Reality, Industrial Automation Product Type: Wearable Devices, Cameras, Sensors, Controllers |
| Companies Covered | Sony Corporation, Intel Corporation, Apple Inc., Microchip Technology Inc., Qualcomm Technologies, Inc., Microsoft Corporation, Samsung Electronics Co., Ltd., Infineon Technologies AG, Alphabet Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gesture Control Market Emerging Trajectories
Three converging forces are restructuring competitive positioning: substrate consolidation in sensing hardware, regulatory pressure on algorithmic transparency, and procurement compression among automotive OEMs.
Silicon photonics is absorbing the dominant sensing substrate role for mid-range gesture modules. Foundry-scale manufacturing enables sub-centimeter resolution at consumer price points. Automotive OEMs in Stuttgart and Wolfsburg are absorbing this transition fastest, collapsing the addressable market for discrete infrared LED assemblies.
EU AI Act algorithmic transparency requirements are reshaping software development cycles. Gesture-recognition systems deployed in European consumer products must now provide explainable decision pathways. Healthcare and automotive segments in Germany face the steepest compliance curves, driving demand for interpretable machine-learning architectures.
Automotive procurement patterns are compressing supplier qualification timelines. OEMs in Munich and Ingolstadt now bundle gesture modules with entire HMI subsystem contracts rather than sourcing discrete components. This consolidation favors vertically integrated suppliers with captive camera-to-UI pipeline capabilities, squeezing pure-play sensor vendors from Tier 1 supplier lists.
Gesture Control Market Segmentation
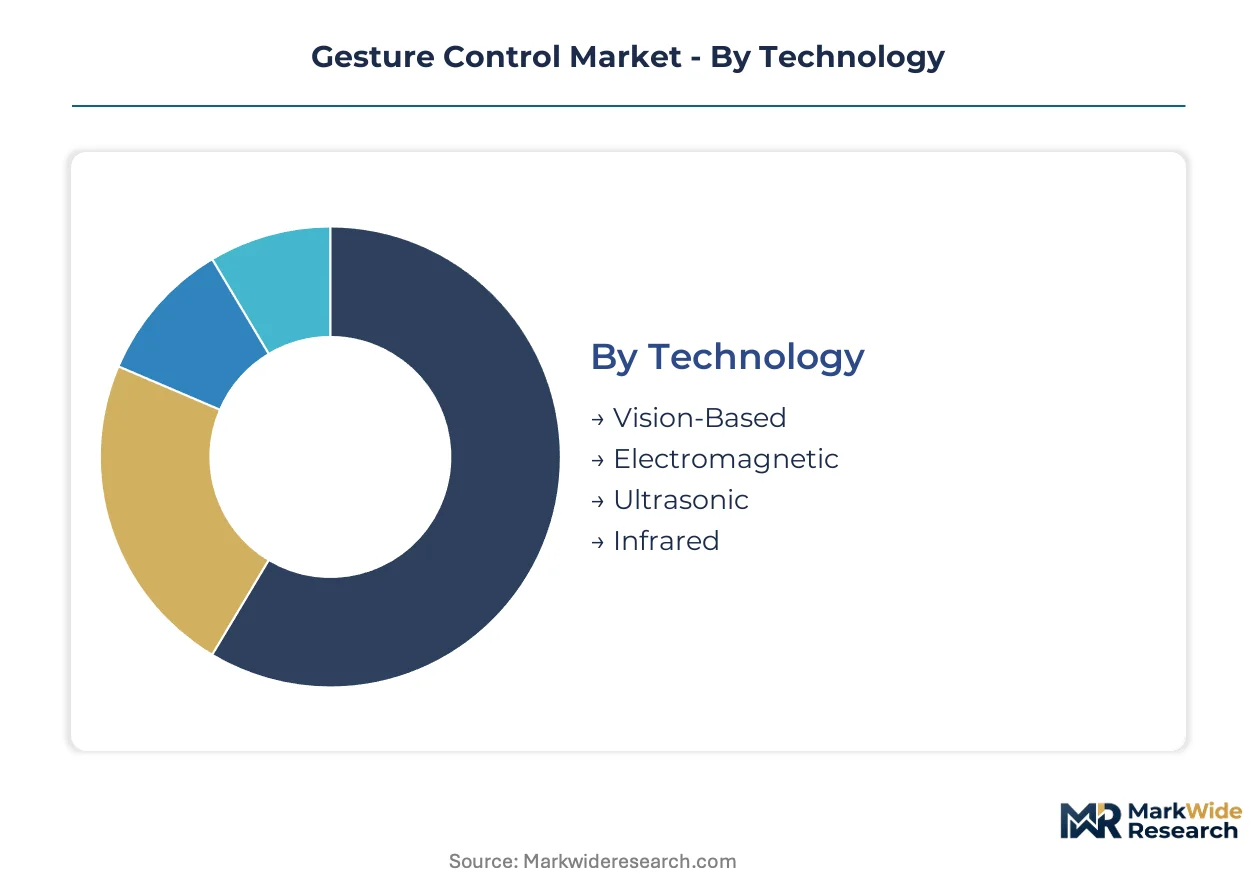
Gesture control technology fragments across sensing modalities, deployment contexts, and hardware form factors. Understanding these divisions reveals where integration complexity concentrates and which segments command premium positioning.
Technology:
Standalone vision modules require discrete processing pipelines, while electromagnetic and ultrasonic alternatives embed more readily into existing system architectures.
- Vision-Based:Camera arrays capture hand and body movements at 30-120 frames per second with sub-centimeter resolution. Automotive cabins in Germany absorb the bulk of premium deployments as NHTSA and ECE R79 regulations mandate distraction-reduction interfaces.
- Ultrasonic:Acoustic arrays transmit high-frequency pulses that detect gestures through physical barriers. Manufacturing facilities in Bavaria and Stuttgart deploy these where dust, steam, or darkness occlude optical systems.
- Electromagnetic:Field-based sensing tracks hand position through magnetic disturbance patterns.
- Infrared:Legacy LED arrays are losing ground to silicon photonics substrates in mid-range applications.
Volume placements concentrate in Vision-Based systems; the faster expansion belongs to Ultrasonic arrays.
End User:
Cost tiers separate consumer-facing deployments from regulated industrial and medical environments where certification overhead reshapes supplier economics.
- Automotive:OEMs bundle gesture modules into flagship electric vehicle HMI subsystems rather than sourcing discrete components. Procurement compression in Munich and Ingolstadt favors vertically integrated suppliers with captive camera-to-UI pipelines.
- Healthcare:Post-pandemic clinical protocols in Germany and Japan prioritize non-contact interfaces on shared diagnostic equipment to minimize pathogen transmission.
- Consumer Electronics:Smart television product lines in Korea integrate proprietary vision pipelines.
- Gaming:Motion-capture peripherals serve console and PC entertainment markets.
Revenue concentration sits with Automotive; Healthcare posts the steepest expansion trajectory as hygiene mandates harden.
Application:
Customer maturity varies sharply between consumer smart home installations and industrial robotics where functional safety certification dominates procurement decisions.
- Industrial Automation:Gesture-enabled robotics face unharmonized IEC standards across jurisdictions, forcing redundant certification pathways. Assembly lines in automotive manufacturing absorb acoustic arrays where optical occlusion limits camera reliability.
- Smart Home:Consumer-grade vision systems operate lighting, climate, and entertainment controls through television-integrated pipelines.
- Robotics:Service and manufacturing robots require explainable gesture-recognition algorithms under EU AI Act transparency requirements.
- Virtual Reality:Head-mounted displays incorporate hand tracking for immersive interaction.
Deployment scale favors Smart Home; Industrial Automation claims the highest per-unit value capture.
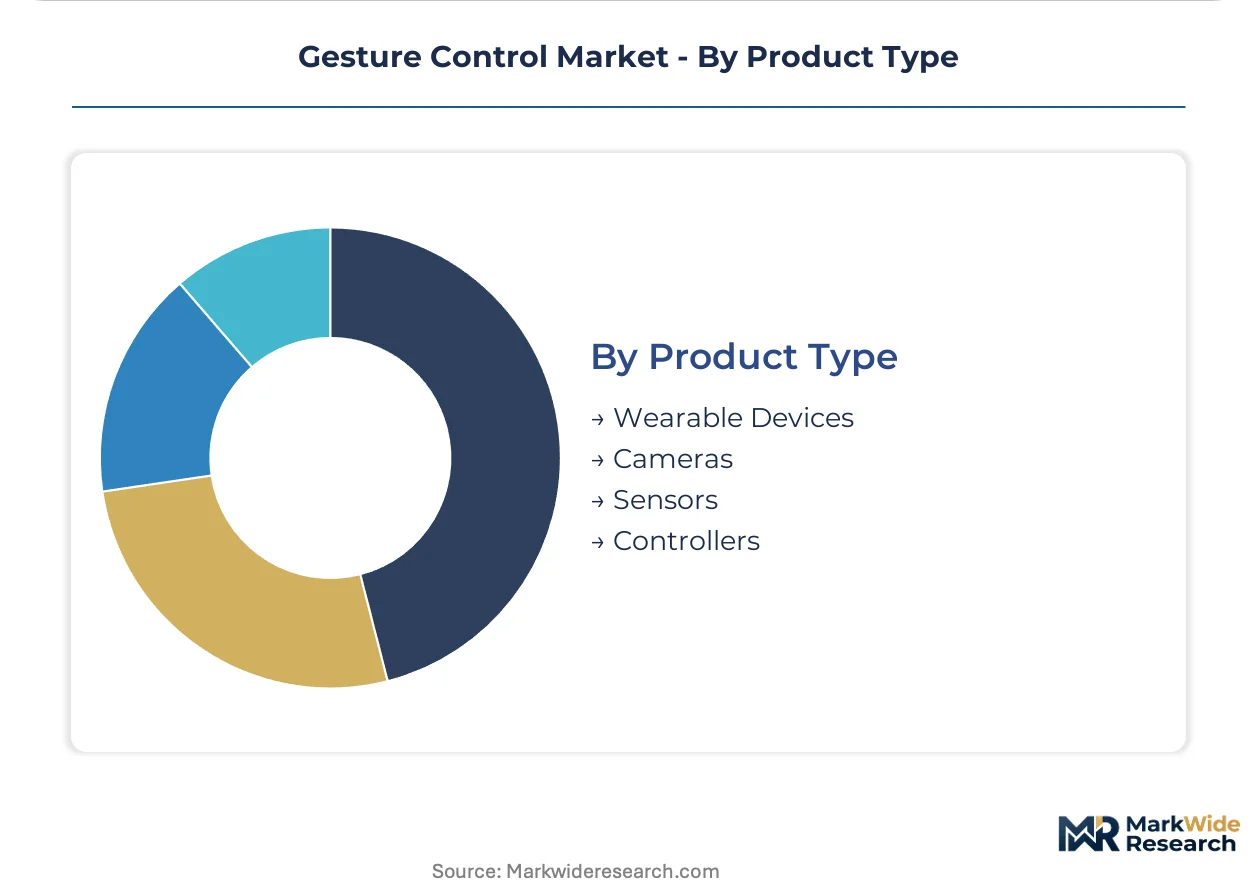
Product Type:
Supply concentration clusters with MEMS foundries possessing proprietary calibration IP, while controller hardware faces commoditization pressure.
- Sensors:MEMS foundry partnerships in Dresden and Eindhoven create defendable margin positions through proprietary sensor fusion algorithms. Specialized calibration engineers command premium compensation, constraining production scaling.
- Cameras:Mature supply chains enable consumer price points for sub-centimeter spatial resolution modules.
- Wearable Devices:EU REACH compliance constrains material selection for housings, while RoHS directives limit heavy-metal content in soldered modules.
- Controllers:Discrete gesture processors face displacement as mobile platforms integrate inference directly into Snapdragon architectures.
Margin pools concentrate in Sensors; Controllers face the steepest price compression from platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Shenzhen and Dubai Internet City concentrate gesture module assembly operations. Tax holidays in these zones attract MEMS foundry partnerships from Dresden and Eindhoven. Supply chains route through these corridors to serve automotive OEMs in Stuttgart and consumer electronics manufacturers in Seoul.
United States
Automotive HMI mandates from NHTSA compel Detroit-based OEMs to integrate touchless controls into electric vehicle cabins. FCC equipment authorization requirements govern radio-frequency sensors deployed in consumer products. Silicon Valley clusters anchor RealSense depth-sensing development for industrial automation clients.
Germany
Post-pandemic hygiene protocols in Munich and Berlin hospitals prioritize non-contact interfaces on diagnostic equipment. ECE R79 type-approval frameworks govern steering-control exemptions for gesture-enabled automotive systems. Bavarian automotive assembly lines deploy ultrasonic arrays where dust and steam occlude optical systems.
China
Smart television manufacturers in Shenzhen integrate proprietary vision pipelines for domestic consumer markets. MIIT standards govern electromagnetic compatibility for gesture sensors deployed in mobile devices. Yangtze River Delta foundries scale silicon photonics substrates for mid-range module production.
Japan
Clinical environments in Tokyo and Osaka mandate non-contact interfaces to minimize pathogen transmission on shared medical equipment. METI industrial policy supports MEMS foundry partnerships for sensor fusion algorithm development. Nagoya automotive clusters evaluate camera-to-UI pipelines for next-generation HMI subsystems.
South Korea
Consumer electronics manufacturers in Seoul embed gesture inference directly into mobile platforms to reduce bill-of-materials overhead. MFDS medical device regulations constrain wearable gesture controller deployments in healthcare settings. Busan-Ulsan industrial corridors test acoustic arrays for manufacturing automation where optical systems fail.
Gesture Control Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around vertically integrated technology conglomerates with captive semiconductor fabrication capabilities. Three archetypes dominate: platform-integrated mobile chip vendors, discrete sensor module specialists, and end-device OEMs with proprietary pipelines. Competitive dynamics revolve around MEMS foundry partnerships and strategic licensing of calibration IP.
Among platform-integrated vendors, Qualcomm Technologies, Inc. and Intel Corporation exemplify the mobile and industrial automation vectors respectively. Samsung Electronics Co., Ltd. occupies a position bridging component supply and end-device integration. These three anchors represent how scale advantages in adjacent semiconductor markets translate into gesture control positioning through backward integration into sensor architectures and forward control over UI pipeline deployment.
| Leading Market Players |
|---|
| Sony Corporation |
| Intel Corporation |
| Apple Inc. |
| Microchip Technology Inc. |
| Qualcomm Technologies, Inc. |
| Microsoft Corporation |
| Samsung Electronics Co., Ltd. |
| Infineon Technologies AG |
| Alphabet Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon photonics wafer pricing indices cascade through MEMS foundry partnerships in Dresden and Eindhoven, compressing module costs for mid-range automotive deployments while premium camera-to-UI pipelines command 40-60% markups from vertically integrated suppliers serving Munich OEMs.
Pricing Analysis
Short lead-time premiums of 15-25% apply to automotive Tier 1 suppliers facing NHTSA compliance deadlines, while spot inventory from Yangtze River Delta foundries trades at discounts for consumer electronics manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates automotive-grade certified modules from industrial ultrasonic arrays and consumer vision systems. Cost compression in mid-range vision modules is intensifying because silicon photonics substrates displace discrete infrared LED assemblies. Consumer electronics manufacturers exhibit highest price sensitivity, while automotive OEMs prioritize certification reliability over unit economics.
Supply Chain Analysis
Freight cost volatility from Asia-Europe routes adds 8-12% landed cost variance for camera module shipments originating in Shenzhen and Seoul. Supply concentrates in Taiwan for CMOS image sensors, Germany for automotive-grade MEMS calibration, and China for silicon photonics substrate scaling. Raw material dependencies span rare-earth dopants for photonic waveguides, high-purity silicon wafers, and specialized optical glass. Single-source vulnerability clusters with proprietary sensor fusion algorithms held by Dresden foundries. Distribution runs through Free Trade Zones in Shenzhen and Dubai Internet City before final assembly integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU AI Act algorithmic transparency requirements erect a cost-of-compliance moat that favors incumbent suppliers with captive regulatory affairs capabilities, squeezing unqualified entrants from European automotive and healthcare procurement lists.
For Market Incumbents: Deepen backward integration into MEMS foundry partnerships to defend margin positions against Qualcomm's Snapdragon inference integration threat. Prioritize ECE R79 certification investment for automotive HMI subsystems to lock out second-tier competitors lacking type-approval track records. For New Entrants and Emerging Players: Industrial ultrasonic system integrators represent the most penetrable channel partner type for bypassing saturated vision-based automotive segments. Target Bavarian manufacturing facilities where dust and steam occlusion creates white space unavailable to camera-dependent incumbents. Pursue project-based go-to-market angles with acoustic array deployments in automotive assembly lines. For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS calibration IP holders in Eindhoven and Dresden where talent scarcity constrains production scaling. Long-term viability hinges on regulatory compliance capabilities rather than hardware cost advantages alone. Watch for IEC functional-safety standard harmonization announcements as inflection indicators for robotics segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Partnership | Dresden calibration IP anchors defendable supply positions against commoditized controller hardware. |
| Regulatory Certification Investment | ECE R79 type-approval unlocks Stuttgart and Wolfsburg OEM procurement lists for HMI subsystems. |
| Platform Integration | Snapdragon inference embedding reduces Android OEM bill-of-materials overhead for mobile gesture modules. |
| Ultrasonic Array Expansion | Bavarian manufacturing deployments exploit optical occlusion limits in automotive assembly environments. |
| EU AI Act Compliance Service | Explainable algorithm consulting captures emerging revenue streams from German healthcare transparency mandates. |
Methodological Framework
Document review covered SEC filings from Intel and Qualcomm, EU regulatory databases, and automotive type-approval records, complemented by interviews with MEMS foundry engineers, Tier 1 supplier procurement managers, and OEM platform integration leads. Secondary validation drew from NHTSA guidance documents, ECE R79 framework texts, and MIIT electromagnetic compatibility standards. Bottom-up module shipment estimates triangulated against top-down automotive HMI content projections.
Cross-referencing historical silicon photonics adoption curves against expert panel inputs anchored growth assumptions across the analysis window. Segmentation dimensions modeled include sensing modality, end-user vertical, application context, and hardware form factor. CAGRs derived from unit economics trajectories in automotive and consumer electronics verticals, with input from foundry capacity expansion timelines and regulatory compliance cost curves.
Caveats apply where IEC functional-safety standard harmonization delays or MEMS talent scarcity in Eindhoven could materially shift the outlook for industrial robotics deployment. Forecasts reflect documented assumptions around OEM procurement consolidation patterns and silicon photonics substrate maturation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Industrial Controllers Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Latin America Proximity Sensors Market