
 Capacitive Tactile Sensor Market | 2026-2036
Capacitive Tactile Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Tactile Sensor Market Outlook
Asset-light manufacturing partnerships and foundry leasing arrangements are reshaping competitive entry in capacitive tactile sensors. Texas Instruments Incorporated leverages its analog foundry relationships to sustain wafer supply without captive fabrication. Infineon Technologies AG anchors European automotive qualification pipelines through dedicated MEMS capacity. Synaptics Incorporated competes via fabless agility, concentrating design resources on force-sensing algorithms rather than process equipment.
Capacitive tactile sensors detect and quantify physical contact through changes in electrical capacitance between conductive electrodes, typically employing copper or indium tin oxide traces on polyimide or glass substrates with dielectric layers measuring 10-100 micrometers. These devices convert mechanical stimuli into digital signals for human-machine interface control, process automation feedback, and safety-critical touch detection. Touch sensors dominate consumer electronics volume, while force sensors command premium positioning in surgical robotics and precision assembly where multi-axis pressure resolution determines system performance. Pressure sensors in automotive interface applications represent the fastest-expanding segment as dashboard digitization eliminates rotary dials and mechanical switches.
FDA 21 CFR Part 820 quality system requirements govern medical device integrations, while EU REACH restrictions on halogenated flame retardants constrain substrate material selection for products entering European medical and automotive channels. EPA hazardous substance reporting under TSCA Section 8 affects U.S.-based manufacturers sourcing specialized dielectric coatings. Stakeholders must monitor evolving automotive functional safety standards and medical device cybersecurity frameworks to preserve market access across regulated end-use segments.
Market Dynamics
Automotive OEMs are eliminating mechanical switchgear in favor of capacitive interfaces, forcing sensor manufacturers to qualify for ISO 26262 functional safety while managing dielectric material transitions under REACH and F-Gas constraints.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbons in sensor manufacturing is accelerating adoption of plasma-enhanced chemical vapor deposition alternatives for dielectric layer deposition.
- Surgical Robotics:Force-sensing tactile arrays enable sub-millimeter tissue manipulation, with da Vinci systems driving qualification demand for medical-grade polyimide substrates.
- German Automotive Cluster:BMW, Mercedes-Benz, and Volkswagen integration timelines are compressing supplier development cycles for haptic feedback modules.
Market Restraints
- Indium Supply Concentration:Over 80% of indium refining occurs in Chinese smelters, creating price volatility for ITO electrode deposition.
- REACH Substance Restrictions:ECHA candidate list expansion for halogenated flame retardants is disqualifying established substrate formulations from European medical device channels.
- Optical Sensing Substitution:Time-of-flight proximity modules in premium smartphones are displacing capacitive force sensors in gesture detection applications.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for electronic components are attracting sensor packaging investments to offset China-plus-one supply chain strategies.
- Soft Robotics Convergence:Integration of stretchable conductive polymers with microfluidic channels opens wearable rehabilitation device segments.
- US IRA Clean Vehicle Credits:Domestic content requirements for EV tax incentives are reshoring sensor assembly to Michigan and Tennessee automotive corridors.
Industry Challenges
- MEMS-CMOS Process Integration:Foundry capacity for combined capacitive sensing and signal conditioning remains constrained at tier-one semiconductor manufacturers.
- FDA 21 CFR Part 820 Certification Timelines:Medical device quality system documentation extends product qualification cycles by 18-24 months versus industrial applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Tactile Sensor Market |
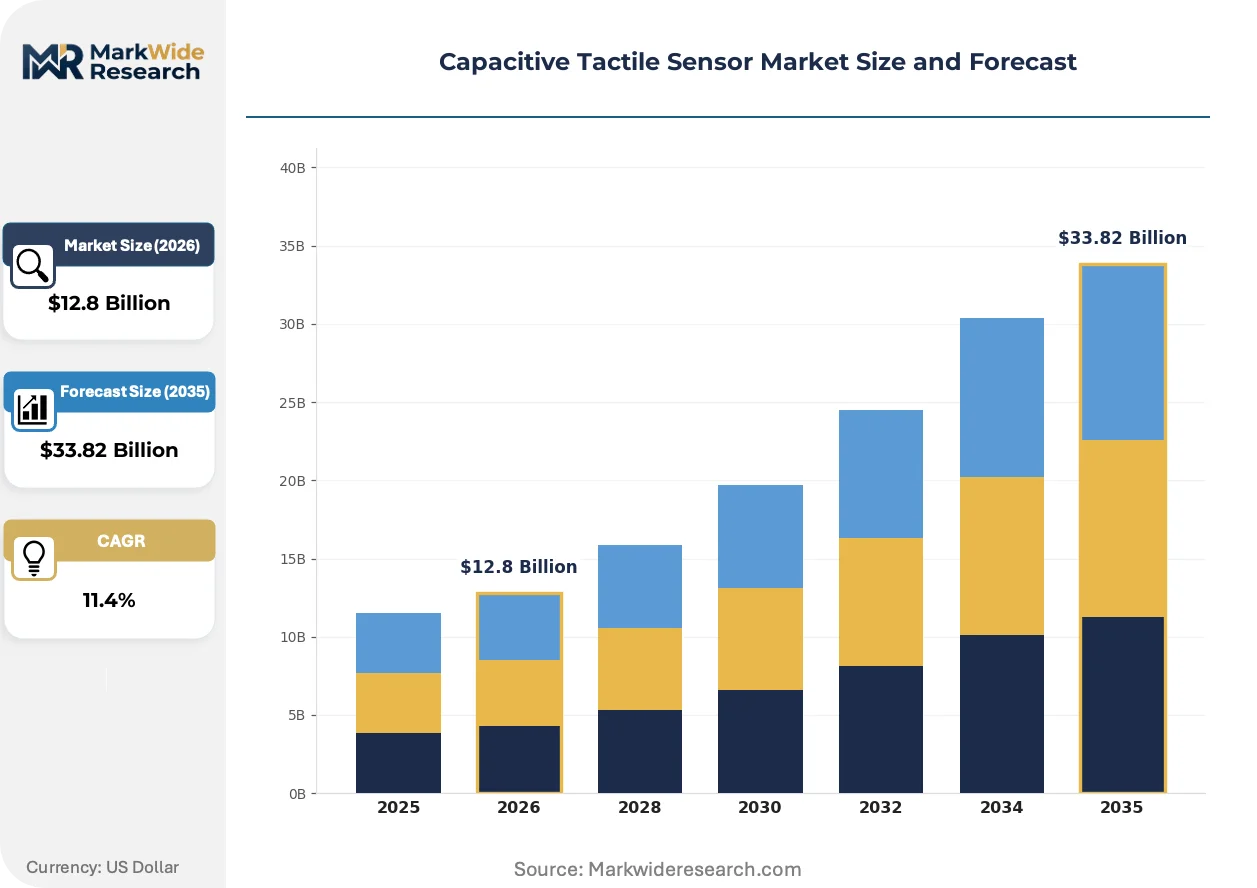
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touch Sensors, Pressure Sensors, Proximity Sensors, Force Sensors Application: Consumer Electronics, Automotive Interface, Industrial Automation, Medical Devices Technology: Analog Sensors, Digital Sensors, Wireless Sensors, Capacitive Touch Technology End User: OEMs, Tier-1 Suppliers, Manufacturers, System Integrators |
| Companies Covered | Texas Instruments Incorporated, NXP Semiconductors, Infineon Technologies AG, STMicroelectronics, Analog Devices, Inc., Microchip Technology Inc., Synaptics Incorporated, Renesas Electronics Corporation, Azoteq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Tactile Sensor Market Strategic Shifts
Capacitive tactile sensing is transitioning from discrete component supply to embedded system integration, with algorithmic force reconstruction and materials science convergence defining competitive differentiation.
Self-capacitance-to-mutual-capacitance architecture migration is collapsing the trade-off between multi-touch resolution and power consumption in automotive center-stack applications. Tier-1 suppliers are adopting this topology for 2026 model year launches. The shift is collapsing BOM counts by eliminating discrete controllers previously required for proximity and touch detection.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of dielectric coatings for medical sensor substrates. ECHA sunset dates for PFAS-based surface treatments are accelerating fluorine-free plasma polymer development. German and French medical device manufacturers are qualifying silicone-nitride alternatives ahead of 2025 enforcement windows.
Automotive procurement teams are consolidating sensor specifications across platform architectures, compressing supplier qualification from model-specific to modular family approvals. This pattern displaces niche sensor vendors unable to meet Volkswagen Group or Stellantis consolidated technical standards. The concentration is most visible in South Korea, where Hyundai Mobis and Samsung Electro-Mechanics are absorbing tier-two design houses into captive development programs.
Capacitive Tactile Sensor Market Segmentation
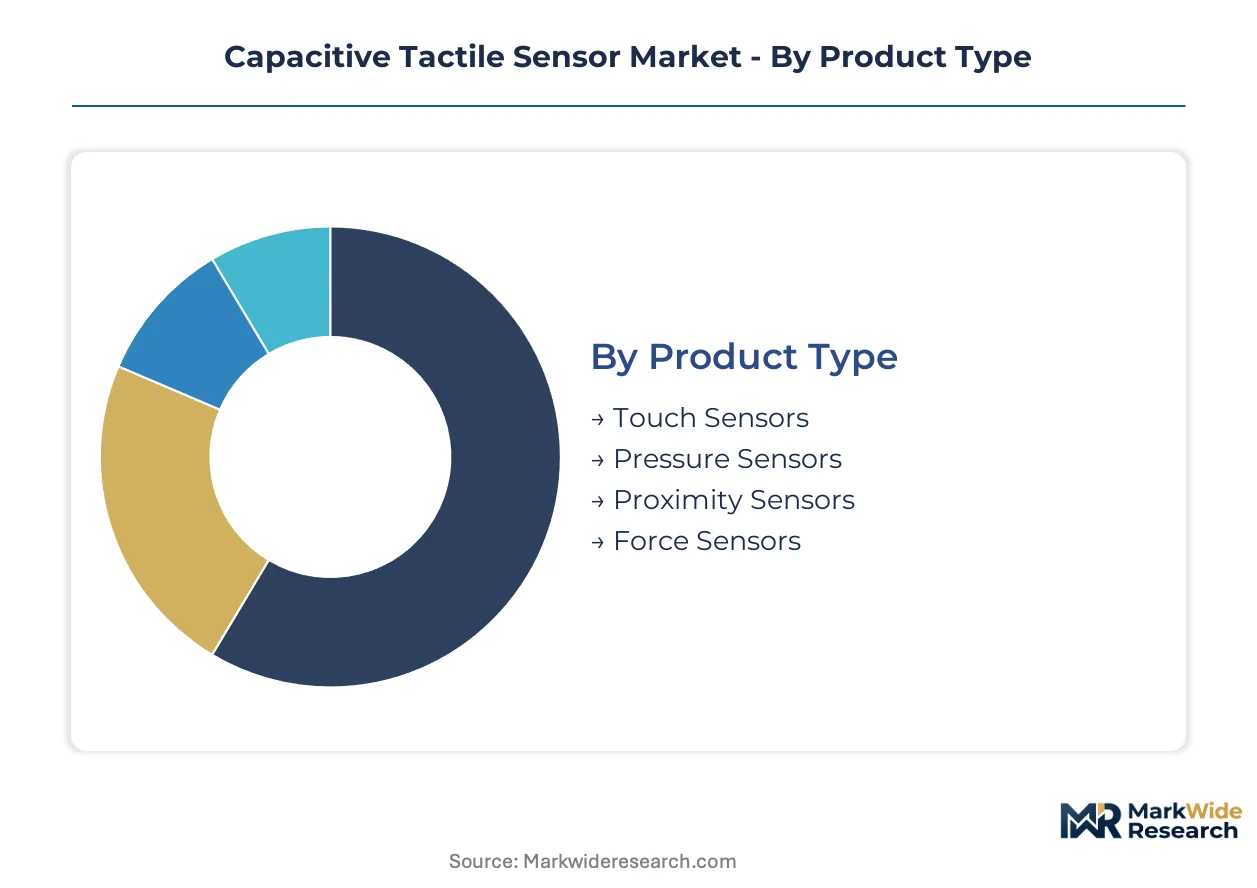
Capacitive tactile sensor architectures diverge sharply across force resolution requirements, interface protocols, and supply chain integration models. Each segmentation dimension reveals distinct margin structures and qualification barriers that determine competitive positioning.
Product Type:
Automotive digitization and surgical robotics are compressing development cycles across force-sensitive variants.
- Touch Sensors:These devices detect surface contact through mutual-capacitance electrode arrays on polyimide substrates, typically resolving single-point activation without pressure quantification. Consumer electronics manufacturers in South Korea and Taiwan dominate procurement volumes, with smartphone bezel elimination driving ultra-thin form factors.
- Force Sensors:Multi-layer structures with elastomeric dielectrics measure z-axis pressure through capacitance change rates, enabling gram-level resolution for robotic manipulation. Da Vinci surgical systems and precision assembly lines in Germany specify medical-grade polyimide substrates with ISO 13485 traceability.
- Pressure Sensors:Automotive haptic feedback modules in Michigan and Tennessee qualify these for center-stack and steering wheel integration under ISO 26262 functional safety requirements.
- Proximity Sensors:Self-capacitance architectures detect hand approach without physical contact, displacing infrared alternatives in premium appliance interfaces.
The dominant share belongs to Touch Sensors, while Force Sensors is closing the gap fastest.
Application:
End-use concentration patterns reflect diverging certification timelines and volume economics.
- Automotive Interface:Dashboard digitization eliminates mechanical switchgear, with BMW and Mercedes-Benz compressing supplier qualification to modular family approvals. Capacitive center-stack modules must satisfy EU REACH substrate restrictions and NHTSA distraction guidelines simultaneously.
- Consumer Electronics:Smartphone, tablet, and wearable manufacturers in Shenzhen and Seoul specify ultra-low-power architectures with sub-millimeter stack heights. Force-sensing integration in trackpads and styluses is displacing resistive alternatives.
- Medical Devices:FDA 21 CFR Part 820 quality systems extend product qualification cycles by 18-24 months versus industrial applications, favoring established suppliers with documentation infrastructure.
- Industrial Automation:Collaborative robot skin arrays and safety-rated touch panels demand IEC 61508 SIL ratings, with German automotive suppliers absorbing tier-two design houses into captive programs.
Automotive Interface commands the largest revenue pool, though Medical Devices exhibits the steepest expansion trajectory as surgical robotics penetration deepens.
Technology:
Signal conditioning integration determines BOM complexity and foundry access requirements.
- Digital Sensors:Integrated ADC and preprocessing circuits reduce host processor loading, with Texas Instruments and Infineon foundry partnerships securing wafer supply. Automotive OEMs specify these for deterministic latency in safety-critical touch detection.
- Analog Sensors:Raw capacitance outputs require external signal conditioning, preserving cost positioning in high-volume consumer electronics where discrete controller elimination matters less.
- Wireless Sensors:BLE and proprietary RF protocols enable distributed skin arrays in soft robotics and wearable rehabilitation devices, with stretchable conductive polymer integration opening new form factors.
- Capacitive Touch Technology:Self-capacitance-to-mutual-capacitance architecture migration collapses multi-touch resolution and power consumption trade-offs, with tier-1 suppliers adopting this topology for 2026 model year launches.
Digital Sensors holds the installed base advantage, while Wireless Sensors is gaining share fastest through soft robotics convergence.
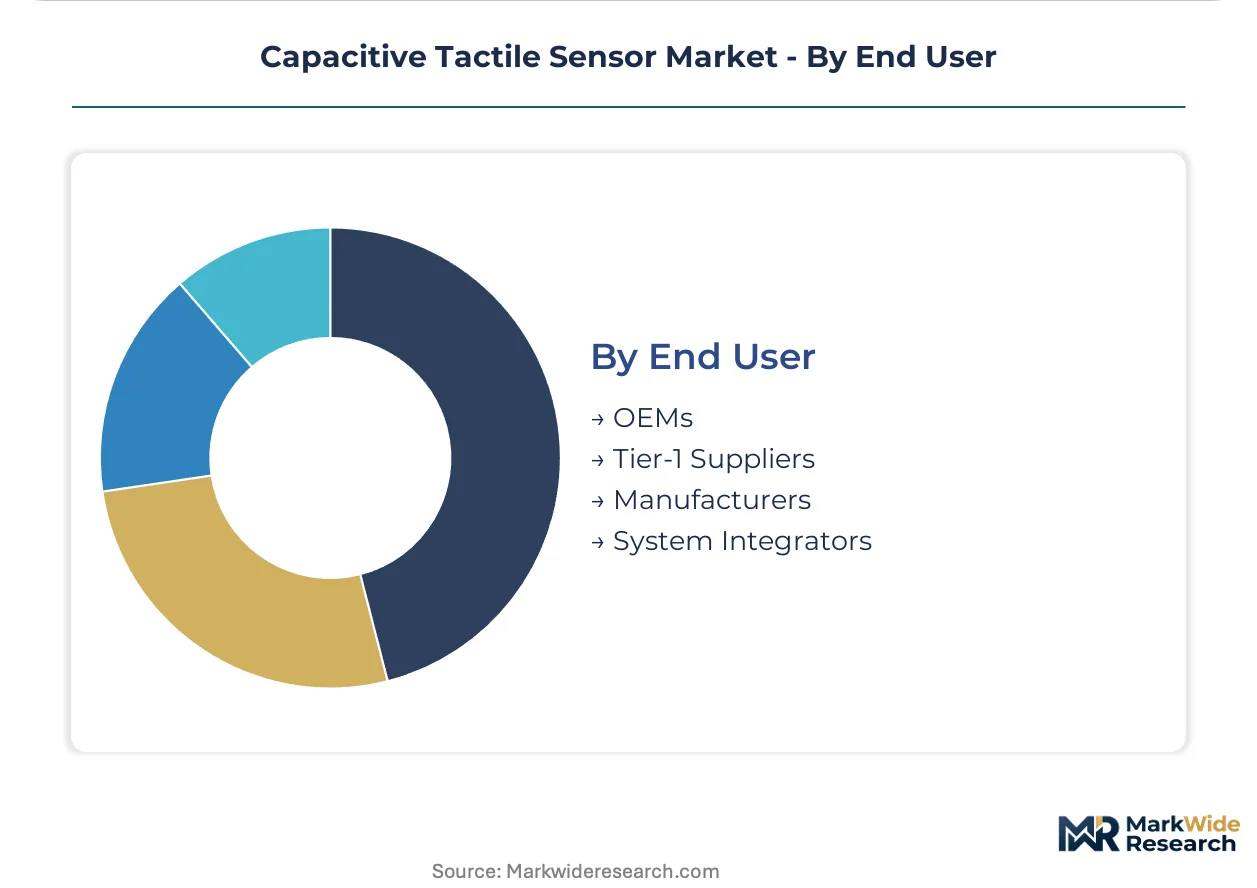
End User:
Supply chain position determines specification influence and margin capture.
- OEMs:Automotive and medical device original equipment manufacturers consolidate sensor specifications across platform architectures, displacing niche vendors unable to meet Volkswagen Group or Stellantis technical standards. Direct procurement teams negotiate dielectric material transitions under REACH and F-Gas constraints.
- Tier-1 Suppliers:Hyundai Mobis and Samsung Electro-Mechanics absorb tier-two design houses into captive development programs, controlling qualification pipelines for haptic feedback modules.
- System Integrators:Industrial automation and robotics specialists assemble multi-vendor tactile arrays, with FDA cybersecurity frameworks and EU AI Act requirements complicating cross-border system deployment.
- Manufacturers:Contract electronics manufacturers in India PLI scheme corridors perform sensor packaging and calibration, offsetting China-plus-one supply chain strategies.
Tier-1 Suppliers capture the dominant procurement volume, while System Integrators is expanding most quickly through collaborative robot deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in capacitive tactile sensors track automotive and consumer electronics manufacturing footprints, with surplus generation concentrated in fabrication-heavy economies and deficit absorption in assembly-dominant markets.
United States
Domestic EV production under IRA clean vehicle credits is reshoring sensor module assembly to Michigan and Tennessee automotive corridors. NHTSA distraction guidelines and EPA TSCA Section 8 reporting constrain dielectric coating imports. Texas Instruments leverages analog foundry partnerships to sustain wafer supply without captive fabrication.
Germany
BMW, Mercedes-Benz, and Volkswagen integration timelines compress supplier development cycles for haptic feedback modules. EU F-Gas Regulation phase-down accelerates plasma-enhanced chemical vapor deposition alternatives for dielectric layers. Baden-Württemberg and Bavaria host the dominant automotive qualification pipelines for ISO 26262 functional safety.
South Korea
Hyundai Mobis and Samsung Electro-Mechanics absorb tier-two design houses into captive development programs for center-stack digitization. MFDS medical device frameworks and KBA automotive standards govern export certification. Seoul Capital Area concentrates procurement volume for smartphone and EV interface sensors.
China
Indium refining concentration—over 80% of global capacity—creates price volatility for ITO electrode deposition in downstream sensor manufacturing. MIIT industrial standards and dual carbon goals reshape domestic fab expansion. Yangtze River Delta and Pearl River Delta clusters dominate touch sensor volume production for consumer electronics.
India
PLI scheme production-linked incentives for electronic components attract sensor packaging investments to offset China-plus-one supply chain strategies. BIS certification requirements and DGFT import substitution policies favor domestic assembly. Gujarat and Tamil Nadu emerging as contract manufacturing hubs for automotive and industrial sensor modules.
Capacitive Tactile Sensor Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in a structure that rewards foundry access and automotive qualification pipelines. The vendor base arranges into three tiers: IDMs with captive MEMS capacity, fabless design houses concentrating on algorithmic differentiation, and tier-1 automotive suppliers absorbing niche players. Consolidation pressure intensifies as OEM procurement teams consolidate specifications across platform architectures. Two competitive moves dominate: foundry leasing arrangements for capacity-constrained MEMS-CMOS integration, and modular family approvals replacing model-specific qualification cycles.
Among semiconductor IDMs with analog and MEMS heritage, Texas Instruments Incorporated, Infineon Technologies AG, and Synaptics Incorporated exemplify divergent strategic postures. Texas Instruments represents the foundry-partnership model sustaining wafer supply without fabrication ownership. Infineon anchors European automotive qualification through dedicated capacity investments. Synaptics occupies the fabless-agility position, concentrating design resources on force-sensing architectures rather than process equipment. These three patterns—foundry-leverage, captive-capacity, and design-specialization—structure competitive rivalry across automotive and medical device segments.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| NXP Semiconductors |
| Infineon Technologies AG |
| STMicroelectronics |
| Analog Devices, Inc. |
| Microchip Technology Inc. |
| Synaptics Incorporated |
| Renesas Electronics Corporation |
| Azoteq |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion feeds directly into landed cost spreads for polyimide substrate imports, amplifying price differentiation between automotive OEMs with long-term offtake contracts and spot-buying industrial integrators.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for force-sensing arrays, with premium-mid-economy pricing differentiation driven by ISO 26262 certification tier and volume scale. Cost compression in standard-grade touch sensors is intensifying because Chinese foundries are absorbing polyimide lamination steps previously performed in Germany. Automotive procurement teams exhibit the lowest price sensitivity due to functional safety liability exposure, while consumer electronics manufacturers in Shenzhen negotiate aggressively on per-unit wafer costs.
Supply Chain Analysis
Foxconn, Jabil, and Sanmina hold dominant contract-manufacturing capacity for sensor module assembly, with backend packaging concentrated in China, Vietnam, and Mexico. Dielectric coating formulations draw from indium refining in Chinese smelters, medical-grade polyimide substrates from Japanese suppliers, and copper electrode sputtering targets from German specialty metal processors. Single-source vulnerability in ITO electrode deposition creates supply chain risk given over 80% refining concentration. Distribution runs through tier-1 automotive suppliers and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as surgical robotics and soft robotics applications splinter qualification requirements, creating niche entry points for specialists outside automotive consolidation paths.
For Market Incumbents: Build captive MEMS-CMOS integration moats by securing foundry partnerships at tier-one semiconductor manufacturers before capacity constraints harden. Absorb tier-two design houses in South Korea and Germany to control haptic feedback module qualification pipelines. Optical sensing substitution in smartphones threatens capacitive force sensor positioning; counter by deepening medical device documentation infrastructure to extend FDA 21 CFR Part 820 certification advantages. For New Entrants and Emerging Players: Establish a beachhead in soft robotics rehabilitation devices where stretchable conductive polymer integration remains undersupplied. Target wearable sensor arrays for post-surgical recovery monitoring, leveraging India's PLI scheme packaging corridors for cost positioning. Pursue system integrator partnerships rather than direct OEM qualification to bypass 18-24 month automotive approval cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded capacitive sensing divisions outside core automotive or medical focus. Five-to-ten year viability hinges on algorithmic force reconstruction capabilities replacing hardware differentiation. Monitor ECHA sunset date enforcement for PFAS-based dielectric coatings as inflection indicator for fluorine-free plasma polymer specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Securement | Texas Instruments and Infineon analog foundry relationships sustain wafer supply without fabrication ownership. |
| Medical Device Certification Investment | FDA 21 CFR Part 820 quality system documentation extends product qualification cycles by 18-24 months versus industrial applications. |
| PFAS-Free Dielectric Reformulation | EU REACH Annex XVII restrictions accelerate silicone-nitride alternative qualification ahead of ECHA enforcement windows. |
| India PLI Scheme Manufacturing Footprint | Production-linked incentives for electronic components attract sensor packaging investments to offset China-plus-one supply chain strategies. |
| Soft Robotics Convergence Development | Integration of stretchable conductive polymers with microfluidic channels opens wearable rehabilitation device segments. |
Study Parameters
A spread of perspectives from automotive platform engineers, medical device regulatory affairs leads, MEMS foundry operations managers, and tier-1 supplier procurement directors converged on the working assumptions. Primary interview data combined with secondary validation from SEC 10-K filings, EU ECHA substance restriction databases, FDA 510(k) clearance records, and automotive production registration data. Bottom-up unit economics triangulated against top-down segment sizing across the analysis window.
Demand-supply balance modeling anchored projections, with segmentation across sensor type, application vertical, signal conditioning technology, and end-user supply chain position. CAGRs derived from installed base turnover rates and content-per-vehicle trajectories in automotive digitization. Forecast inputs incorporated ISO 26262 functional safety adoption curves and REACH substance restriction phase-down timelines without year-specific anchoring.
Stress conditions across indium price volatility, foundry capacity utilization, and EU F-Gas Regulation enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about surgical robotics penetration and automotive haptic feedback module adoption. Quarterly review of ECHA candidate list expansions and MFDS medical device framework updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market