
 Middle East and Africa Pressure Sensors Market | 2026-2036
Middle East and Africa Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pressure Sensors Market Foresight
Process automation buyers in petrochemical complexes are collapsing legacy mechanical gauge procurement in favor of digital pressure sensing architectures. ABB Ltd. leverages its integrated automation portfolio to anchor large turnkey instrumentation contracts across Gulf Cooperation Council states. Honeywell International Inc. sustains channel dominance through calibrated distribution partnerships with regional system integrators. Schneider Electric differentiates via edge-computing-enabled pressure transmitters that compress commissioning timelines for brownfield retrofits.
Pressure sensors are electromechanical transducers that convert fluid or gas pressure into standardized electrical output signals, typically operating across ranges from millibars to thousands of bars with accuracy classes down to 0.025 percent of span. These devices serve critical safety and process control functions in hazardous environments where overpressure protection, leak detection, and flow inference determine operational integrity. Gauge sensors occupy the largest installed base across Middle East and Africa hydrocarbon infrastructure due to their compatibility with vented reference atmospheric pressure measurement. Capacitive technology captures the fastest expansion trajectory as operators demand higher resolution for low-pressure differential applications in cleanroom and filtration monitoring. Differential sensors concentrate margin pools in custody transfer metering where fiscal accuracy requirements justify premium pricing.
Saudi Arabia's SFDA and UAE's MOHAP enforce equipment conformity frameworks that pressure sensor vendors must satisfy for medical and industrial device market access. South Africa's national standards body administers SANS certification aligned with IECEx for explosive atmosphere equipment, while Nigeria's Department of Petroleum Resources mandates periodic calibration traceability for upstream instrumentation. Stakeholders must monitor how Gulf states harmonize their emerging local content requirements with existing international accreditation regimes to avoid supply chain qualification fragmentation.
Market Dynamics
Oil and gas operators across the Middle East and Africa are collapsing legacy mechanical gauge architectures in favor of digital pressure sensing systems, compressing procurement cycles and forcing vendor consolidation around integrated automation portfolios.
Growth Catalysts
- Vision 2030 industrial diversification:Saudi Arabia's manufacturing city expansions are generating concentrated demand for process instrumentation across new petrochemical and specialty chemical facilities.
- IECEx harmonization in South Africa:The SANS certification alignment with international explosive atmosphere standards is streamlining equipment qualification for multinational operators.
- Capacitive technology maturation:Higher resolution differential sensing is opening cleanroom and filtration monitoring applications previously unserved by piezoresistive alternatives.
Market Restraints
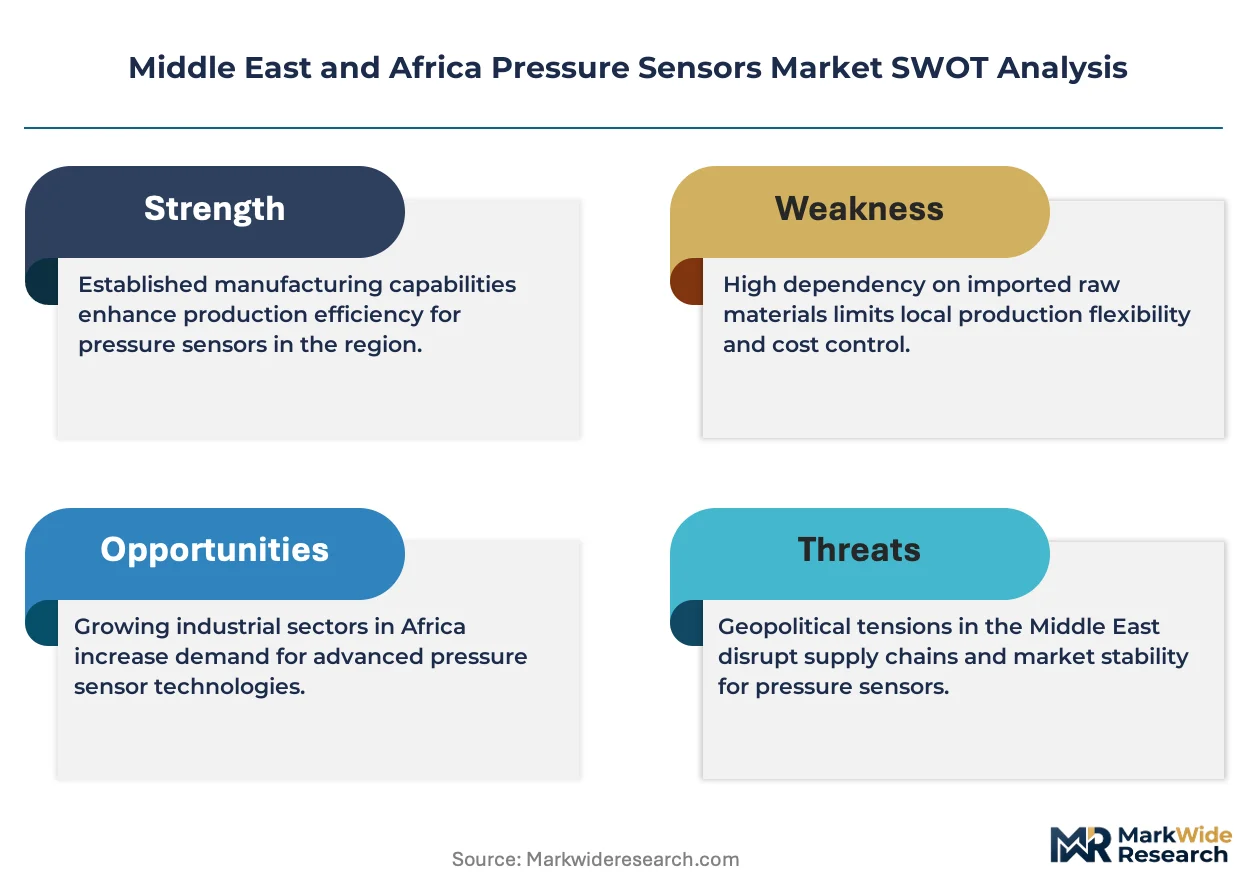
- Input cost volatility in semiconductor substrates:Silicon wafer price fluctuations transmit directly to MEMS sensor manufacturing economics, compressing margin buffers for mid-tier suppliers.
- Supply concentration in East Asian foundries:Pressure sensor die fabrication concentrates in Taiwan and South Korea, exposing procurement timelines to geopolitical shipping lane disruptions.
- Calibration infrastructure gaps:Nigeria's Department of Petroleum Resources mandates traceable calibration protocols that local service providers struggle to satisfy, extending equipment commissioning cycles.
Strategic Opportunities
- Edge-computing transmitter integration:Brownfield retrofit projects across UAE's aging upstream infrastructure favor pressure transmitters with embedded diagnostics that compress commissioning timelines.
- Medical device conformity pathways:Saudi SFDA and UAE MOHAP equipment frameworks create dual-registration efficiencies for vendors serving both industrial and healthcare verticals.
- Custody transfer metering premiumization:Fiscal accuracy requirements in hydrocarbon export terminals justify differential sensor pricing tiers that capture margin pools unavailable in standard process applications.
Industry Challenges
- Commissioning engineer scarcity:Specialized pressure transmitter calibration and loop verification skills concentrate with regional system integrators, constraining end-user self-sufficiency.
- Legacy system integration friction:Digital pressure architectures face protocol translation complexity when interfacing with decades-old distributed control systems prevalent in Gulf petrochemical complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pressure Sensors Market |
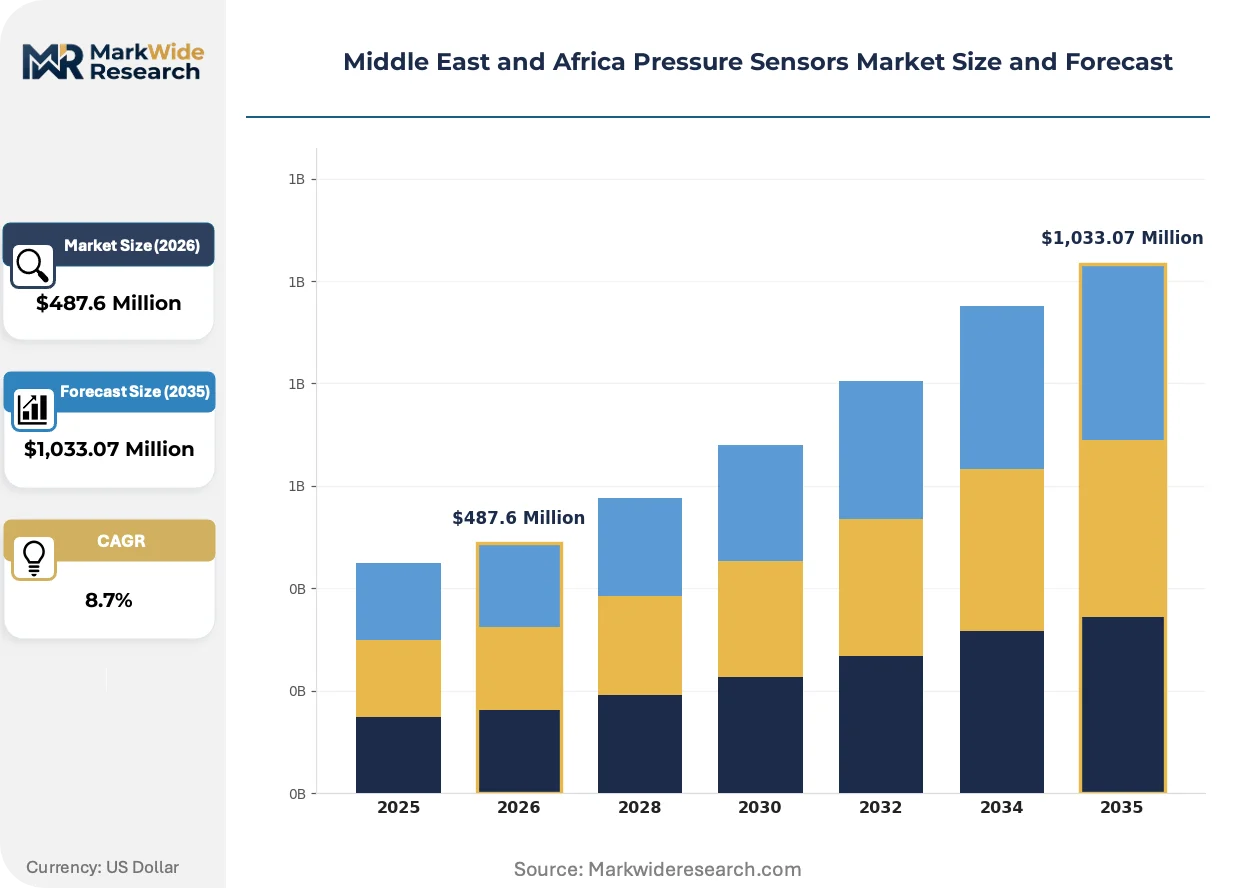
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Gauge Sensors, Differential Sensors, Sealed Sensors Technology: Piezoelectric, Capacitive, Strain Gauge, Optical End User: Manufacturing, Oil & Gas, Automotive, Aerospace Installation: In-line, Flush Mount, Remote Mount, Low Pressure |
| Companies Covered | ABB Ltd., Honeywell International Inc., Schneider Electric, TE Connectivity, Sensata Technologies, Inc., Emerson Electric Co., Amphenol Corporation, Bosch Sensortec GmbH, Endress+Hauser AG, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pressure Sensors Market Shifts & Advancements
Digital pressure sensing architectures are compressing the traditional mechanical gauge installed base while regulatory conformity frameworks and procurement model evolution reshape competitive positioning across Middle East and Africa industrial corridors.
Capacitive pressure sensing technology is supplanting piezoresistive alternatives in low-pressure differential applications where resolution requirements exceed 0.05 percent accuracy. Cleanroom operators in UAE pharmaceutical manufacturing and Saudi semiconductor fabrication facilities are specifying capacitive transmitters for filtration monitoring. This displacement is compressing the addressable market for traditional strain-gauge architectures in precision applications while opening premium pricing tiers for vendors with capacitive portfolios.
South Africa's SANS certification alignment with IECEx standards is eliminating duplicate testing burdens for explosive atmosphere equipment. Manufacturers now qualify once for regional access across multiple industrial sectors. Oil and gas operators in Nigeria and Angola are leveraging this harmonization to consolidate supplier panels, favoring vendors with pre-certified product families over those requiring jurisdiction-specific validation.
Integrated automation procurement is consolidating discrete instrument purchases into turnkey instrumentation contracts. Petrochemical buyers in Saudi Arabia's Jubail and Yanbu industrial cities are bundling pressure sensing with distributed control systems and safety instrumented systems. Channel intermediaries without calibration partnerships or commissioning capabilities face margin compression as direct vendor relationships with regional system integrators capture specification influence.
Middle East and Africa Pressure Sensors Market Segmentation
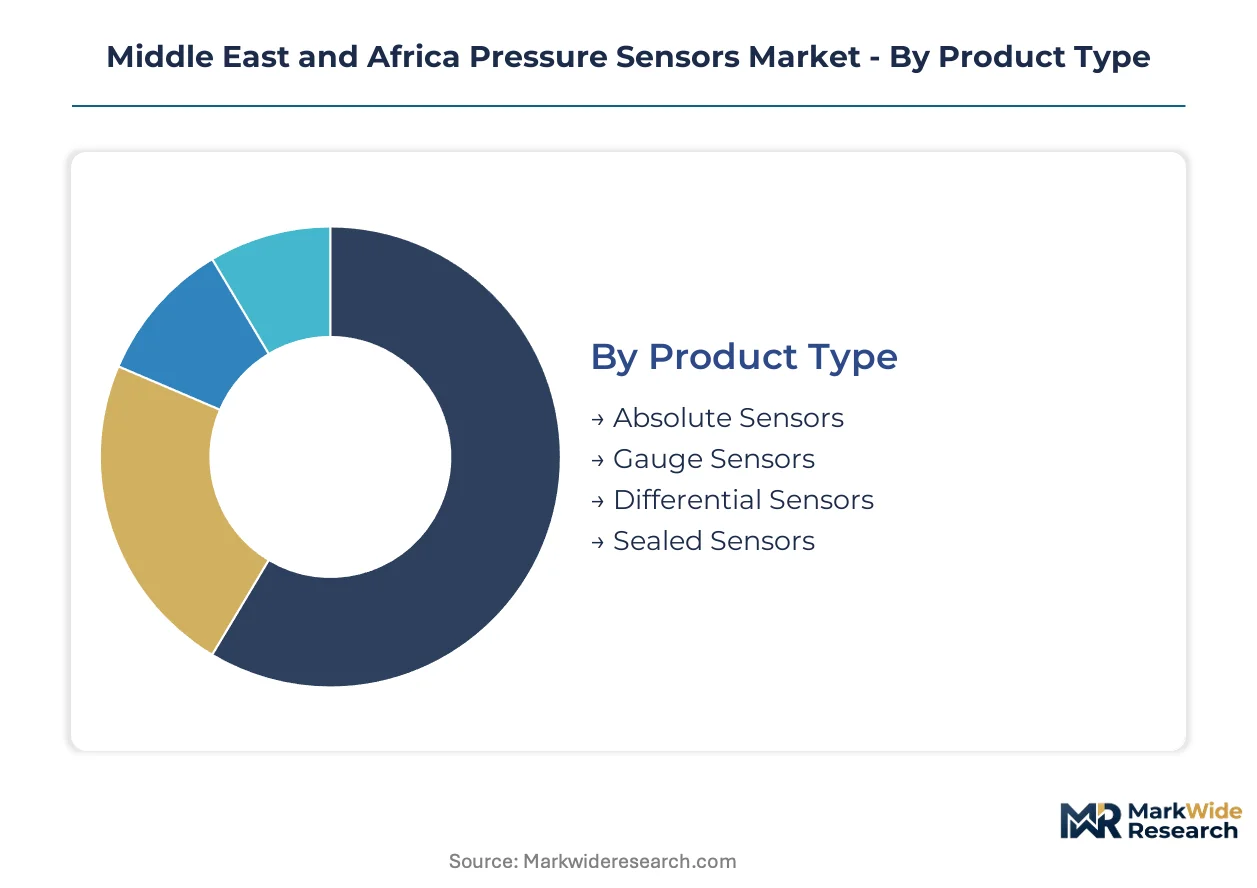
Pressure sensor procurement across Middle East and Africa industrial corridors fragments across four structural dimensions. Each segmentation axis reveals distinct margin concentration patterns that vendors must navigate to capture specification influence in hydrocarbon, manufacturing, and emerging aerospace verticals.
Product Type:
Margin pools concentrate in differential sensing architectures where fiscal accuracy requirements justify premium pricing tiers unavailable in standard gauge applications.
- Gauge Sensors:These devices measure pressure relative to atmospheric reference through vented designs. Saudi Aramco's upstream infrastructure and UAE's ADNOC downstream complexes anchor the largest installed base across the region's hydrocarbon corridors.
- Differential Sensors:Twin-pressure-port architectures calculate pressure variance between two process points with accuracy classes reaching 0.025 percent of span. Custody transfer metering at Ras Tanura and Zueitina export terminals generates concentrated demand where measurement uncertainty directly impacts revenue recognition.
- Absolute Sensors:Sealed vacuum reference designs serve altitude compensation and barometric applications in aerospace testing facilities.
- Sealed Sensors:Hermetic construction prevents process contamination in subsea wellhead monitoring where saltwater ingress destroys standard vented elements.
Gauge sensors hold installed capacity. Differential sensors are rotating up the share rankings.
Technology:
Technology selection maps directly to resolution requirements and hazardous area certification complexity across the region's explosive atmosphere installations.
- Capacitive:Dielectric displacement sensing achieves sub-millibar resolution for cleanroom and pharmaceutical filtration monitoring. UAE's Dubai Science Park and Saudi's KAUST research facilities specify capacitive transmitters where piezoresistive noise floors exceed tolerance bands.
- Piezoelectric:Crystal-based dynamic pressure measurement dominates high-frequency vibration monitoring in rotating equipment protection systems. Saudi petrochemical complexes deploy piezoelectric accelerometer-pressure hybrid sensors for compressor surge detection.
- Strain Gauge:Bonded foil and thin-film resistive elements provide cost-optimized solutions for general process monitoring in South African mining hydraulics.
- Optical:Fiber Bragg grating and interferometric designs eliminate electrical ignition sources in Zone 0 hydrogen handling at Morocco's green ammonia pilot projects.
Piezoelectric architectures retain the largest deployment footprint. Capacitive technology is climbing the fastest as precision applications multiply.
End User:
End-use concentration patterns reflect the region's hydrocarbon dependency and Vision 2030 manufacturing diversification timeline.
- Oil & Gas:Upstream wellhead monitoring, midstream pipeline leak detection, and downstream catalytic cracker pressure control consume the dominant procurement volume. Nigeria's Department of Petroleum Resources mandates calibration traceability that extends commissioning cycles for international suppliers.
- Manufacturing:Jubail and Yanbu industrial cities generate concentrated demand for process instrumentation as specialty chemical and automotive component facilities ramp operations.
- Automotive:Tire pressure monitoring and fuel rail sensing concentrate in Morocco's Renault-Nissan assembly complexes and South Africa's component export zones.
- Aerospace:MRO facilities in Dubai South and Cairo's aviation cluster deploy precision pressure calibration standards for pitot-static testing.
Oil and gas maintains the dominant revenue share. Manufacturing is gaining share fastest as industrial city buildouts accelerate.
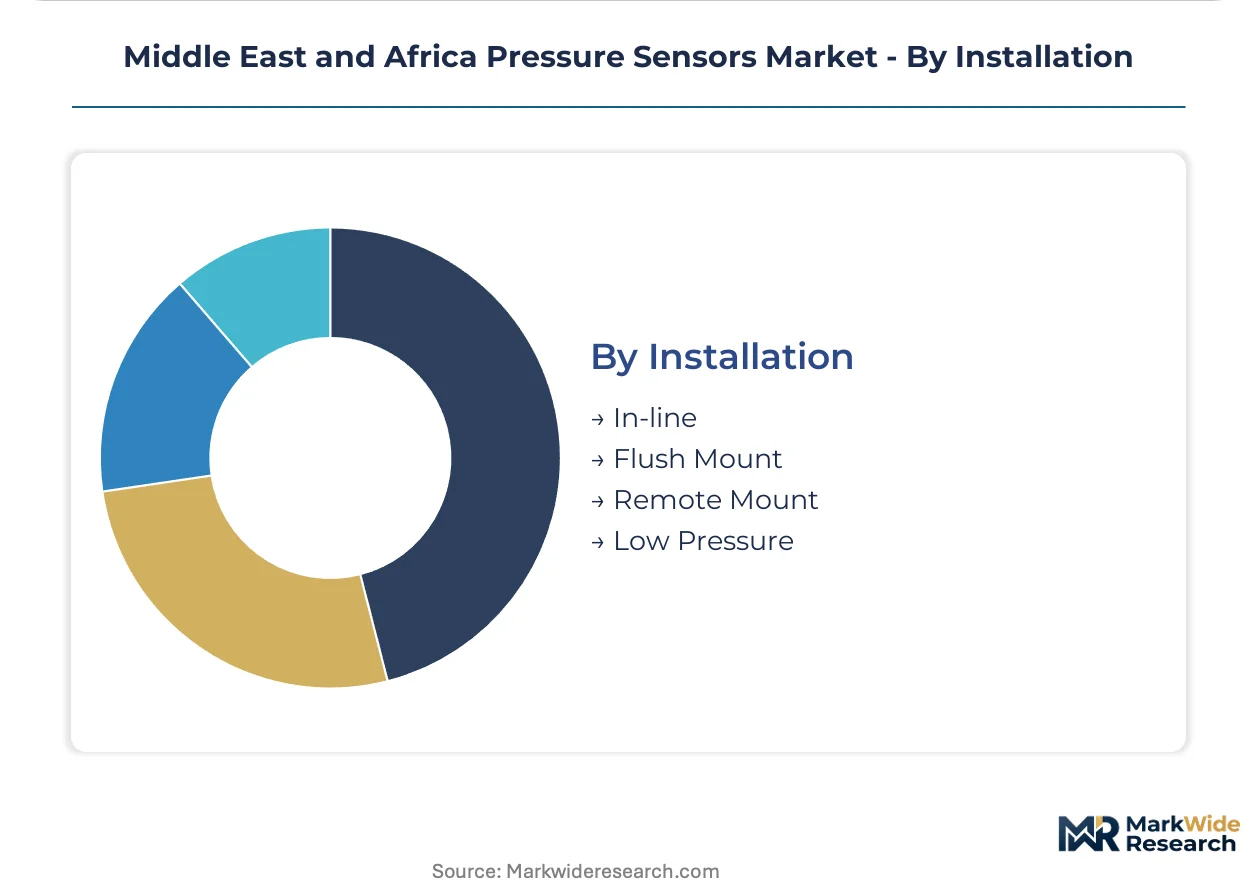
Installation:
Installation geometry determines seal reliability and maintenance accessibility in the region's extreme temperature and sand-laden atmospheric conditions.
- In-line:Threaded or flanged process connections dominate standard piping configurations. Saudi pipeline infrastructure specifies in-line transmitters with 316L stainless steel wetted parts for sour service compatibility.
- Flush Mount:Diaphragm-fronted designs eliminate cavity accumulation in viscous or slurry applications. UAE's aluminum smelters deploy flush mount sensors in cryolite bath pressure monitoring.
- Remote Mount:Capillary-filled impulse line configurations separate electronics from high-temperature or high-radiation process zones. South Africa's Koeberg nuclear facility specifies remote mount architectures for primary coolant loop monitoring.
- Low Pressure:Large diaphragm area designs amplify minute pressure differentials in HVAC duct monitoring and cleanroom differential pressure indication.
In-line configurations hold installed capacity. Flush mount designs are rotating up the share rankings as slurry applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The East-West Pipeline corridor anchors Saudi Arabia's position as the region's dominant pressure sensor procurement hub, while the Trans-Saharan gas pipeline network underwrites Nigeria's upstream instrumentation demand.
Saudi Arabia
Jubail and Yanbu industrial cities generate concentrated demand for process instrumentation as specialty chemical facilities ramp under Vision 2030. SFDA equipment conformity frameworks mandate pre-market validation for devices serving medical and industrial verticals. Ras Tanura export terminals deploy differential sensors for custody transfer metering where fiscal accuracy requirements justify premium procurement.
United Arab Emirates
ADNOC downstream complexes and Dubai South aerospace MRO facilities anchor dual-track demand for hydrocarbon and precision calibration applications. MOHAP device registration pathways create dual-registration efficiencies for vendors serving healthcare and industrial sectors. Dubai Science Park specifies capacitive transmitters for pharmaceutical cleanroom monitoring where resolution thresholds exceed piezoresistive capabilities.
South Africa
SANS certification alignment with IECEx standards eliminates duplicate testing burdens for explosive atmosphere equipment across mining and petrochemical installations. The national standards body administers hazardous area qualification that multinational operators leverage for supplier panel consolidation. Koeberg nuclear facility specifies remote mount architectures for primary coolant loop monitoring in high-radiation process zones.
Nigeria
The Department of Petroleum Resources mandates calibration traceability for upstream instrumentation that extends commissioning cycles for international suppliers. Zueitina export terminal differential metering generates concentrated demand where measurement uncertainty impacts revenue recognition. Local service providers struggle to satisfy traceable calibration protocols, creating qualification bottlenecks for equipment deployment.
Morocco
Renault-Nissan assembly complexes in Tangier-Med automotive zone drive tire pressure monitoring and fuel rail sensing demand. Green ammonia pilot projects at renewable hydrogen handling facilities specify optical pressure sensing to eliminate electrical ignition sources in Zone 0 environments. The country's phosphates mining corridor generates process instrumentation demand for slurry pressure monitoring in beneficiation plants.
Middle East and Africa Pressure Sensors Market Competitive Landscape
Listed leaders compete with private specialists across integrated automation portfolios, with channel structure determining specification influence more than product differentiation alone. The vendor base stratifies around three archetypes: diversified automation conglomerates bundling instrumentation with control systems, component specialists focusing on sensor die fabrication and transmitter assembly, and regional system integrators capturing commissioning and calibration service revenue. Consolidation pressures favor turnkey contract winners, while mid-tier suppliers face margin compression from semiconductor input volatility and East Asian foundry concentration.
Within the diversified automation tier, ABB Ltd. and Honeywell International Inc. anchor large instrumentation contracts across Gulf Cooperation Council petrochemical complexes. Schneider Electric occupies a position emphasizing edge-computing-enabled architectures that compress brownfield retrofit timelines. TE Connectivity and Sensata Technologies, Inc. represent the component-specialist vector, with Sensata's portfolio exemplifying the premium differential sensing tier where fiscal accuracy requirements justify pricing separation from standard process applications.
| Leading Market Players |
|---|
| ABB Ltd. |
| Honeywell International Inc. |
| Schneider Electric |
| TE Connectivity |
| Sensata Technologies, Inc. |
| Emerson Electric Co. |
| Amphenol Corporation |
| Bosch Sensortec GmbH |
| Endress+Hauser AG |
| Others |
Supply & Pricing Matrix
Wafer-scale MEMS fabrication economics in Taiwan and South Korea compress unit costs for high-volume die production while simultaneously concentrating pricing power among foundry operators serving pressure sensor module assemblers across the Middle East and Africa.
Pricing Analysis
Volume-discount tiering structures separate IECEx-certified transmitters for Saudi Aramco turnkey contracts from standard process sensors procured by South African mining operators. Price differentiation rests on certification grade and after-sales calibration bundling. Cost compression in mid-tier gauge sensors intensifies as Taiwanese foundry output expands. System integrators capturing commissioning contracts exhibit lowest price sensitivity; independent maintenance shops in Nigeria face acute margin pressure.
Supply Chain Analysis
Inventory lead-times for pressure sensor die extend from foundry allocation cycles in Taiwan, South Korea, and Japan through assembly stages in Malaysia and China. Raw material dependencies center on silicon wafers, ceramic substrates, and specialty encapsulants. Single-source vulnerability concentrates in East Asian MEMS fabrication. Distribution runs through calibrated regional system integrators who anchor specification influence in Gulf petrochemical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineer scarcity across Nigeria and Angola fragments deployment timelines and concentrates service revenue with regional system integrators who control calibration infrastructure.
For Market Incumbents: Fortify channel control through exclusive calibration partnerships with Jubail and Yanbu industrial city maintenance providers. Backward integration into MEMS die design reduces exposure to Taiwanese foundry allocation volatility. Anchor specification influence via pre-certified IECEx product families that collapse competitor qualification timelines. For New Entrants and Emerging Players: Calibration service gaps in Nigeria's upstream sector offer white-space entry where international suppliers struggle with Department of Petroleum Resources traceability mandates. Target South Africa's SANS harmonization pathway for explosive atmosphere equipment to leverage single-qualification regional access. Deploy direct field engineering teams to compress commissioning cycles that incumbent distributors cannot match. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional system integrators with captive calibration laboratories and long-term service contracts. Long-term viability favors vendors with dual-registration efficiency across Saudi SFDA and UAE MOHAP medical-industrial device frameworks. Monitor Gulf local content requirement harmonization as inflection signal for supplier panel consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Transmitter Integration | Embedded diagnostics in Schneider Electric architectures compress UAE brownfield retrofit commissioning timelines. |
| Dual-Registration Pathway Investment | Saudi SFDA and UAE MOHAP conformity efficiency opens medical and industrial verticals for component specialists. |
| Calibration Infrastructure Buildout | Local traceable calibration capability satisfies Nigeria DPR mandates and accelerates equipment deployment cycles. |
| Capacitive Technology Portfolio Expansion | Sub-millibar resolution captures UAE pharmaceutical cleanroom and Saudi semiconductor fabrication specifications. |
| Turnkey Instrumentation Contract Pursuit | Integrated automation bundling with DCS and SIS systems anchors specification influence in Jubail petrochemical complexes. |
Research Methodology
A standing panel of instrumentation procurement managers at Gulf petrochemical complexes, calibration service engineers, and regional system integrators provided ongoing calibration against secondary data. Primary fieldwork combined structured interviews with maintenance directors at Saudi Aramco facilities, plant engineers in South African mining operations, and biomedical equipment specialists at UAE healthcare systems. Secondary validation drew from IECEx certification databases, SANS standards publications, customs import records for pressure transmitter HS codes, and SEC filings of listed automation vendors. Bottom-up demand modeling triangulated against top-down industrial instrumentation spend estimates.
Consistency checks validated volume and value outputs against regional hydrocarbon capital expenditure disclosures and industrial city buildout timelines across the projection horizon. Segmentation dimensions modeled encompass product type, sensing technology, end-use vertical, and installation geometry alongside certification tier and procurement channel structure. CAGRs derived from fitted growth curves applied to baseline capacity installations, with trajectory adjustments for Vision 2030 manufacturing diversification pace and IECEx harmonization adoption rates.
Underlying assumptions cover sustained hydrocarbon facility investment, stable East Asian foundry output, and gradual Gulf local content requirement harmonization, with deviation risk concentrated in semiconductor substrate price volatility and geopolitical shipping lane disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Parking Sensors Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Sensor Fusion Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Position Sensor Market