
 Magnetoresistance Sensor Market | 2026-2036
Magnetoresistance Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
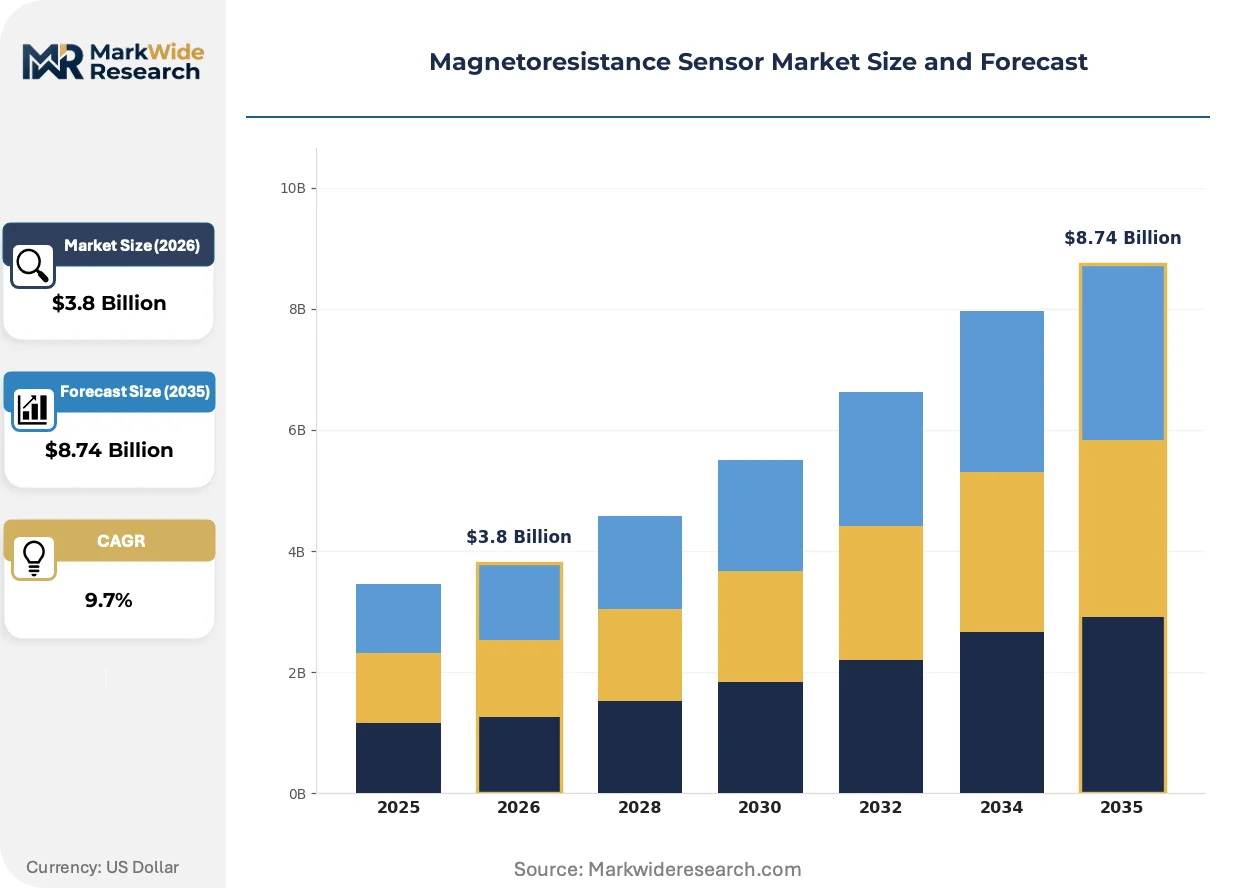
Magnetoresistance Sensor Market Outlook
Automotive electrification is realigning the end-use vertical mix, pulling demand from conventional combustion platforms toward battery management and motor control systems. Infineon Technologies AG leverages its power semiconductor heritage to anchor magnetoresistance sensor supply for traction inverters. TDK Corporation sustains leadership in TMR technology for high-precision position feedback. Allegro MicroSystems specializes in current sensing for EV drivetrains, occupying a defensible niche as OEMs consolidate supplier bases.
A magnetoresistance sensor detects magnetic field variations through changes in electrical resistance of ferromagnetic materials, typically operating with sensitivity ranges from millioersteds to kilooersteds for industrial and automotive feedback loops. The device converts mechanical position or electrical current into digital signals without physical contact, eliminating wear in high-cycle applications. TMR and GMR product types dominate margin pools due to superior signal-to-noise ratios and thermal stability. Position tracking and current sensing applications lead volume uptake, while motion sensing in consumer robotics accelerates fastest off a smaller base.
NHTSA mandates on functional safety and EU Green Deal emissions benchmarks shape product standards by requiring redundant sensing architectures in safety-critical automotive modules. EMA medical device regulations and FDA diagnostic equipment rules extend compliance burdens into healthcare applications, where magnetic isolation protects patient-connected electronics. Stakeholders must monitor how REACH material restrictions on rare-earth processing affect TMR stack manufacturing costs and supply continuity.
Market Dynamics
Automotive electrification is compressing design cycles and forcing sensor suppliers to validate redundant architectures for traction inverters and battery management systems. NHTSA functional safety mandates and EU Green Deal emissions benchmarks are tightening accuracy thresholds while OEMs consolidate supplier bases.
Growth Catalysts
- NHTSA Functional Safety Mandates:Redundant sensing architectures in EV drivetrains are mandating dual magnetoresistance sensor configurations for position tracking and current feedback loops.
- TMR Stack Thermal Stability:Tunnel magnetoresistance technology delivers superior signal-to-noise ratios under extreme temperatures, enabling adoption in motor control modules.
- Germany-China-US Production Clusters:Concentrated EV manufacturing hubs in these three markets are pulling specialized sensor procurement toward regional supply bases.
Market Restraints
- Rare-Earth Processing Concentration:TMR manufacturing depends on controlled rare-earth element supply chains concentrated in limited geographies, exposing cost volatility.
- REACH Material Restrictions:ECHA regulations on heavy metals and chemical substances in sensor stack materials are extending compliance timelines and qualification costs.
- Hall Effect Substitution:Lower-cost Hall effect sensors continue displacing magnetoresistance devices in non-safety-critical consumer and industrial applications.
Strategic Opportunities
- Medical Device Magnetic Isolation:FDA diagnostic equipment rules and EMA medical device regulations are creating demand for isolated current sensing in patient-connected electronics.
- Consumer Robotics Motion Sensing:Precision position feedback requirements in collaborative robots and drones are accelerating TMR adoption off a smaller volume base.
- EU AI Act Compliance:Automated decision-making systems in industrial automation are mandating verified sensor inputs for algorithmic accountability.
Industry Challenges
- ISO 26262 Certification Timelines:Automotive functional safety qualification cycles extend 18-24 months, compressing product launch windows for new sensor platforms.
- Legacy System Integration Friction:Industrial automation retrofit projects face signal compatibility constraints when upgrading from analog Hall devices to digital magnetoresistance outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetoresistance Sensor Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MAG, TMR, AMR, GMR End User: Automotive, Consumer Electronics, Industrial Automation, Healthcare Application: Motion Sensing, Position Tracking, Current Sensing, Magnetic Field Measurement Technology: Analog, Digital, Hybrid, Integrated |
| Companies Covered | Infineon Technologies AG, TDK Corporation, Allegro MicroSystems, Inc., NVE Corporation, NXP Semiconductors, Honeywell International Inc., TE Connectivity Ltd., STMicroelectronics, Asahi Kasei Microdevices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetoresistance Sensor Market Strategic Shifts
Sensor architectures are converging with power electronics packaging, embedding magnetoresistance dies directly into inverter modules and motor housings. This integration is eliminating discrete sensor assemblies and rewiring value capture toward semiconductor suppliers.
TMR multilayer stack technology is integrating cobalt-iron-boron magnetic free layers with magnesium oxide tunnel barriers to achieve sub-millioersted sensitivity. Tier 1 automotive suppliers are adopting these devices for high-resolution rotor position detection in permanent magnet synchronous motors. The technology is integrating sensing and conditioning electronics into single-package solutions that compress board space and assembly cost.
EU Green Deal emissions benchmarks are mandating verified energy efficiency measurements in industrial motor systems above 750 watts. Member states are transposing these rules into national efficiency regulations requiring certified current sensing for compliance documentation. German machine builders are responding by specifying calibrated TMR current sensors with digital output interfaces.
Buyer concentration among EV platform suppliers is consolidating procurement decisions toward integrated inverter-sensor subsystems. Tier 1 power electronics manufacturers are displacing discrete component distributors as the primary specification channel. This shift is most visible in China, where domestic EV platform providers are vertically integrating sensor selection into inverter design teams.
Magnetoresistance Sensor Market Segmentation
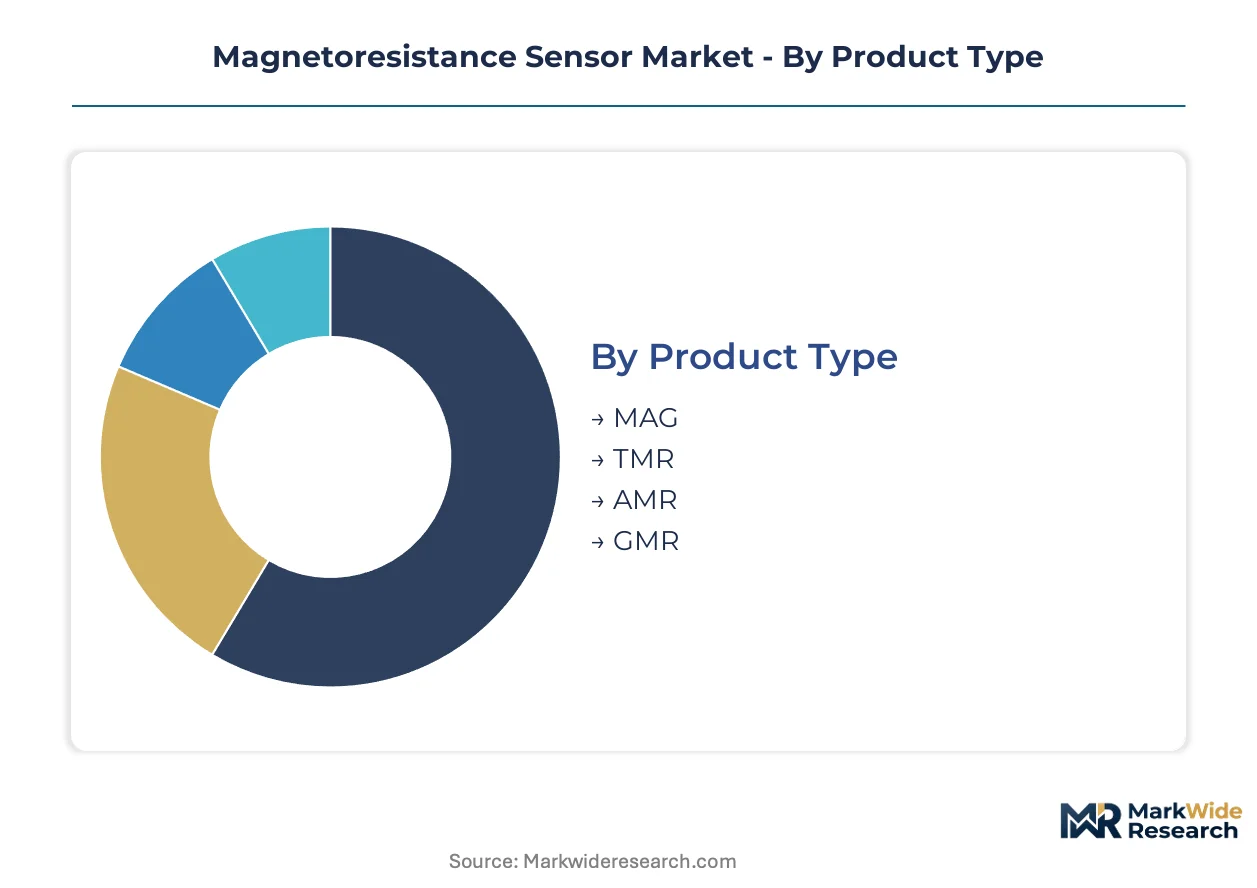
Magnetoresistance sensor architectures fragment across four distinct axes. Product type determines thermal performance and signal fidelity. End-user concentration in automotive electrification is compressing design cycles and consolidating procurement decisions.
Product Type:
Volume concentrates in mature magnetoresistance technologies, while premium margin pools accrue to advanced multilayer stacks.
- TMR:Tunnel magnetoresistance stacks integrate cobalt-iron-boron free layers with magnesium oxide tunnel barriers, achieving sub-millioersted sensitivity for high-resolution rotor position detection in permanent magnet synchronous motors. German machine builders specify TMR devices for certified energy efficiency documentation under EU Green Deal transpositions.
- GMR:Giant magnetoresistance sensors employ alternating ferromagnetic and non-magnetic thin films, delivering robust thermal stability for traction inverter current sensing in NHTSA-mandated redundant architectures. EV drivetrain suppliers in the United States and China are consolidating procurement toward GMR-based modules for battery management systems.
- AMR:Anisotropic magnetoresistance devices serve cost-sensitive industrial position feedback applications with moderate accuracy requirements.
- MAG:Conventional magnetoresistance sensors retain presence in legacy automotive and consumer electronics platforms facing Hall effect substitution pressure.
Today's leader: TMR. Tomorrow's challenger: GMR.
End User:
Application maturity separates established automotive demand from emerging healthcare and robotics uptake.
- Automotive:Battery management and motor control systems mandate redundant position tracking and current sensing for functional safety compliance. OEM supplier base consolidation in Germany, China, and the United States is pulling specialized procurement toward integrated inverter-sensor subsystems.
- Industrial Automation:EU Green Deal efficiency regulations above 750 watts require calibrated current sensing with digital output interfaces. German machine builders specify TMR sensors for compliance documentation.
- Healthcare:FDA diagnostic equipment rules and EMA medical device regulations create demand for magnetic isolation in patient-connected electronics.
- Consumer Electronics:Collaborative robots and precision drones accelerate TMR adoption for motion sensing off a smaller volume base.
Automotive commands current procurement volume. Healthcare offers the steepest expansion trajectory.
Application:
Functional criticality distinguishes safety-mandated sensing from performance-optimizing feedback.
- Position Tracking:High-resolution rotor angle detection in permanent magnet synchronous motors enables field-oriented control algorithms. TMR multilayer stacks achieve the angular precision required for EV traction inverters.
- Current Sensing:Non-contact measurement of busbar and phase currents eliminates shunt resistor power dissipation. Redundant GMR configurations satisfy NHTSA functional safety mandates for battery management systems.
- Motion Sensing:Consumer robotics and drone stabilization systems demand compact, low-latency magnetic feedback.
- Magnetic Field Measurement:Laboratory and industrial process control applications require calibrated vector magnetometry.
Position tracking anchors revenue. Motion sensing climbs the fastest.
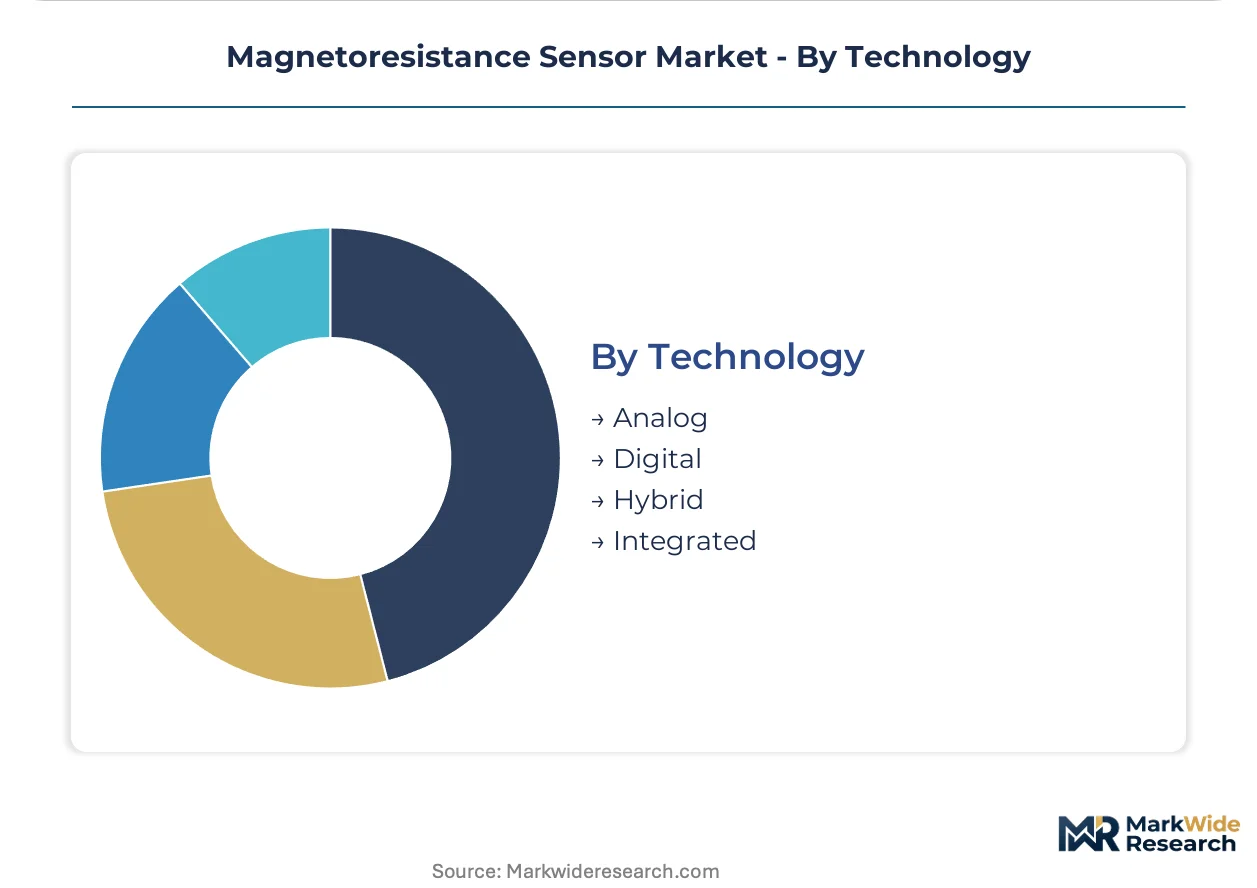
Technology:
Integration depth separates discrete component suppliers from semiconductor-embedded solution providers.
- Integrated:Single-package solutions combine sensing elements with conditioning electronics and digital interfaces, compressing board space and assembly cost. Tier 1 automotive suppliers adopt these for motor control modules.
- Digital:SPI and SENT protocol outputs eliminate analog signal conditioning, simplifying microcontroller interface design for battery management systems.
- Analog:Voltage-proportional outputs retain presence in legacy industrial retrofit projects facing signal compatibility constraints.
- Hybrid:Mixed-signal architectures bridge analog sensing front-ends with digital back-end processing for flexible system integration.
Integrated solutions capture margin expansion. Digital outputs gain specification share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling magnetoresistance sensor production toward jurisdictions with favorable compliance-cost structures, particularly where EV incentives offset REACH and functional-safety qualification burdens.
United States
NHTSA functional-safety mandates and IRA clean-vehicle tax credits are accelerating EV platform development. The Inflation Reduction Act's domestic content requirements favor local sensor procurement. Detroit-area power electronics clusters are consolidating inverter-sensor subsystem specifications toward integrated architectures.
Germany
EU Green Deal emissions benchmarks and national efficiency regulations above 750 watts mandate certified current sensing. The KBA enforces type-approval standards for automotive safety systems. Bavarian machine builders specify TMR sensors for compliance documentation in industrial motor applications.
China
Dual carbon goals and MIIT new-energy vehicle mandates compress design cycles for traction inverters. SAMR standardization efforts align sensor accuracy requirements with NHTSA thresholds. Yangtze River Delta EV production clusters are vertically integrating sensor selection into inverter design teams.
Japan
METI industrial efficiency standards and automotive electrification roadmaps drive precision position-feedback demand. JIS certification requirements maintain technical barriers for imported sensor modules. Chubu-region automotive suppliers are adopting TMR stacks for permanent magnet synchronous motor control.
South Korea
Motor vehicle emissions regulations and K-EV battery initiative subsidies expand domestic EV manufacturing capacity. MFDS medical device rules create parallel demand for magnetic isolation in diagnostic equipment. Seoul Capital Area electronics conglomerates are backward-integrating sensor procurement into power semiconductor divisions.
Magnetoresistance Sensor Market Competitive Environment
Backward integration dominates the current landscape as Tier 1 automotive suppliers absorb discrete component distributors into captive specification channels. The vendor base stratifies across three tiers: integrated semiconductor conglomerates with power electronics heritage, specialized magnetic sensor fabricators, and regional component distributors facing displacement. Consolidation pressure concentrates procurement decisions among EV platform providers in Germany, China, and the United States. Technology licensing and capacity expansion represent the dominant competitive moves as qualification timelines compress.
Among integrated semiconductor suppliers, Infineon Technologies AG anchors the power-electronics-heritage archetype, while TDK Corporation exemplifies the specialized magnetic-materials fabricator position. Allegro MicroSystems occupies a defensible niche within current-sensing specialists serving safety-critical automotive modules. These three entities collectively represent the competitive vectors—integrated solutions, materials science depth, and application-specific specialization—that define margin capture in magnetoresistance sensor supply.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| TDK Corporation |
| Allegro MicroSystems, Inc. |
| NVE Corporation |
| NXP Semiconductors |
| Honeywell International Inc. |
| TE Connectivity Ltd. |
| STMicroelectronics |
| Asahi Kasei Microdevices |
| Others |
Value Chain & Pricing Dynamics
Cobalt-iron-boron free layer costs cascade from rare-earth processing facilities through TMR stack manufacturers into tiered sensor pricing. REACH compliance burdens and IRA domestic content rules reshape how buyers absorb these input premiums across automotive and industrial segments.
Pricing Analysis
Distributor margins compress as Tier 1 automotive suppliers consolidate procurement through direct inverter-sensor subsystem contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262-certified automotive modules from industrial-grade position sensors and cost-constrained consumer electronics. Pricing pressure stems from Hall effect substitution in non-safety-critical applications where buyers prioritize unit cost over signal fidelity. Automotive OEMs exhibit lowest price sensitivity due to functional safety mandates, while consumer electronics manufacturers drive hardest bargain.
Supply Chain Analysis
Domestic content requirements in the United States, Germany, and China reshape sourcing patterns for magnetoresistance sensor manufacturing. Rare-earth element processing concentrates in China, with cobalt and iron-boron alloy production anchored in Germany and Japan. TMR multilayer stacks draw from magnesium oxide tunnel barrier substrates and precision lithography equipment concentrated in East Asian semiconductor fabrication clusters. Single-source vulnerability in rare-earth supply chains exposes cost volatility. Distribution runs through captive procurement channels at EV platform providers rather than independent component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The magnetoresistance sensor market compounds regulatory tailwinds into durable demand, with NHTSA functional safety mandates and EU Green Deal efficiency rules mandating redundant sensing architectures through 2035.
For Market Incumbents: Extend certification portfolios to capture ISO 26262 ASIL-D ratings for traction inverter applications before design cycles compress further. Backward integration into TMR stack manufacturing insulates margin from rare-earth volatility. Hall effect sensor vendors with automotive ambitions represent the primary competitive threat. For New Entrants and Emerging Players: TMR multilayer process expertise offers entry into medical device magnetic isolation where FDA diagnostic equipment rules create compliance moats. Healthcare applications present the most penetrable white space given lower incumbent concentration versus automotive. Partner with German machine builders seeking EU Green Deal efficiency certification for industrial motor systems. For Investors and Strategic Acquirers: Consolidation pressure builds where Tier 1 power electronics manufacturers absorb discrete sensor suppliers into captive specification channels. Long-term viability favors integrated semiconductor conglomerates with power electronics heritage over standalone magnetic sensor fabricators. Watch for EV platform provider vertical integration announcements as inflection signal for distributor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| TMR Stack Capacity Expansion | Secures supply for German machine builders under EU Green Deal efficiency mandates. |
| ISO 26262 Certification Investment | Unlocks automotive procurement decisions consolidating toward safety-rated suppliers. |
| Medical Device Partnership | Captures FDA-isolated current sensing demand in patient-connected diagnostic equipment. |
| Backward Integration into Rare-Earth Processing | Insulates margin from REACH compliance cost volatility in TMR manufacturing. |
| Integrated Inverter-Sensor Subsystem Development | Aligns with Tier 1 supplier consolidation of EV drivetrain procurement channels. |
Study Parameters
Multiple input streams — primary interviews with Tier 1 automotive procurement officers, power electronics platform engineers, and industrial automation R&D directors; secondary validation against SEC semiconductor filings, MIIT new-energy vehicle production databases, and ECHA REACH substance restriction updates — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against expert panel assessments anchored volume projections across the analysis window. Segmentation modeling incorporated product type, end-use vertical, application function, and technology integration depth. CAGRs derived from regression analysis of automotive electrification penetration curves and industrial efficiency regulation adoption timelines.
The model holds under stable rare-earth supply conditions and continued NHTSA functional safety mandate enforcement; deviation in REACH material restriction scope or Hall effect sensor performance breakthroughs would shift trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Temperature Monitoring Devices Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Temperature Transmitter Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Semiconductor Sensor Market