
 Mucinoses Management Market | 2026-2036
Mucinoses Management Market Size, Share, and Industry Trends Forecast 2026-2036
Mucinoses Management Market Foresight
Biologics manufacturing and precision-targeted delivery systems are rewriting the clinical economics of mucinoses care. GSK plc leverages its established immunology infrastructure to sustain development pipelines across inflammatory skin conditions. Almirall, S.A anchors its position through specialized dermatology commercialization networks in European markets. Merck & Co., Inc competes via R&D intensity in cytokine-modulating therapies with mucinosis-relevant mechanisms.
Mucinoses management encompasses the diagnosis, pharmacologic intervention, and long-term monitoring of disorders characterized by abnormal mucin deposition in dermal and subcutaneous tissues, with treatment regimens typically involving corticosteroid-sparing protocols and immunomodulatory agents formulated for sustained tissue penetration. The primary purpose spans symptom control, functional restoration, and prevention of irreversible fibrotic sequelae in cutaneous and systemic variants. Among product categories, biologics command the fastest expansion as payers recalibrate coverage for refractory cases, while topicals retain volume leadership in early-stage lichen myxedematosus. Hospital end users concentrate margin pools through infusion center economics, though home care delivery is gaining traction for self-administered systemic options.
FDA orphan drug designations and EMA PRIME eligibility pathways shape investment allocation by compressing development timelines for rare mucinosis subtypes, while HIPAA compliance requirements influence real-world evidence collection strategies for post-market surveillance. The EU MDR framework imposes stricter clinical evidence thresholds on device-drug combination products used in transdermal delivery. Stakeholders must monitor evolving payer evidence requirements for biologic step-therapy protocols versus first-line authorization in academic referral networks.
Market Dynamics
FDA orphan drug designations and EMA PRIME eligibility pathways compress development timelines for rare mucinosis subtypes, reshaping how biopharmaceutical firms allocate R&D capital across inflammatory skin disease portfolios.
Growth Catalysts
- Accelerated FDA pathways:Orphan drug designation reduces regulatory burden for preclinical mucinosis candidates, shortening time-to-market for therapies addressing populations under 200,000 patients.
- Academic medical center concentration:Specialized dermatology departments at Johns Hopkins, Mayo Clinic, and University of Pennsylvania anchor prescriber education networks that drive biologic adoption curves.
- Subcutaneous delivery platforms:Self-administered injection systems reduce infusion center dependency, expanding addressable patient pools beyond hospital-centric care models.
Market Restraints
- Plasma-derived raw material volatility:Immunoglobulin feedstock costs fluctuate with donor collection economics, compressing margins for antibody-based mucinosis therapies.
- European manufacturing concentration:Single-source biologics production in Ireland and Belgium creates geopolitical exposure for supply continuity.
- Diagnostic code fragmentation:ICD-10 subclassification gaps between lichen myxedematosus and scleromyxedema delay reimbursement authorization.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA's conditional approval pathway for cell therapies enables earlier commercial entry for fibroblast-targeting mucinosis interventions.
- Home infusion channel expansion:Partnerships with specialty pharmacy networks bypass hospital margin capture for maintenance dosing regimens.
- Real-world evidence mandates:EMA's DARWIN EU initiative creates funded access to longitudinal patient data for post-market mucinosis therapy validation.
Industry Challenges
- Dermatopathologist workforce scarcity:Fellowship-trained specialists capable of distinguishing pretibial myxedema from other mucinoses number fewer than 400 across US academic centers.
- Legacy EMR interoperability:Hospital systems using Cerner and Epic variants struggle to standardize mucinosis severity scoring for multicenter trial recruitment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mucinoses Management Market |
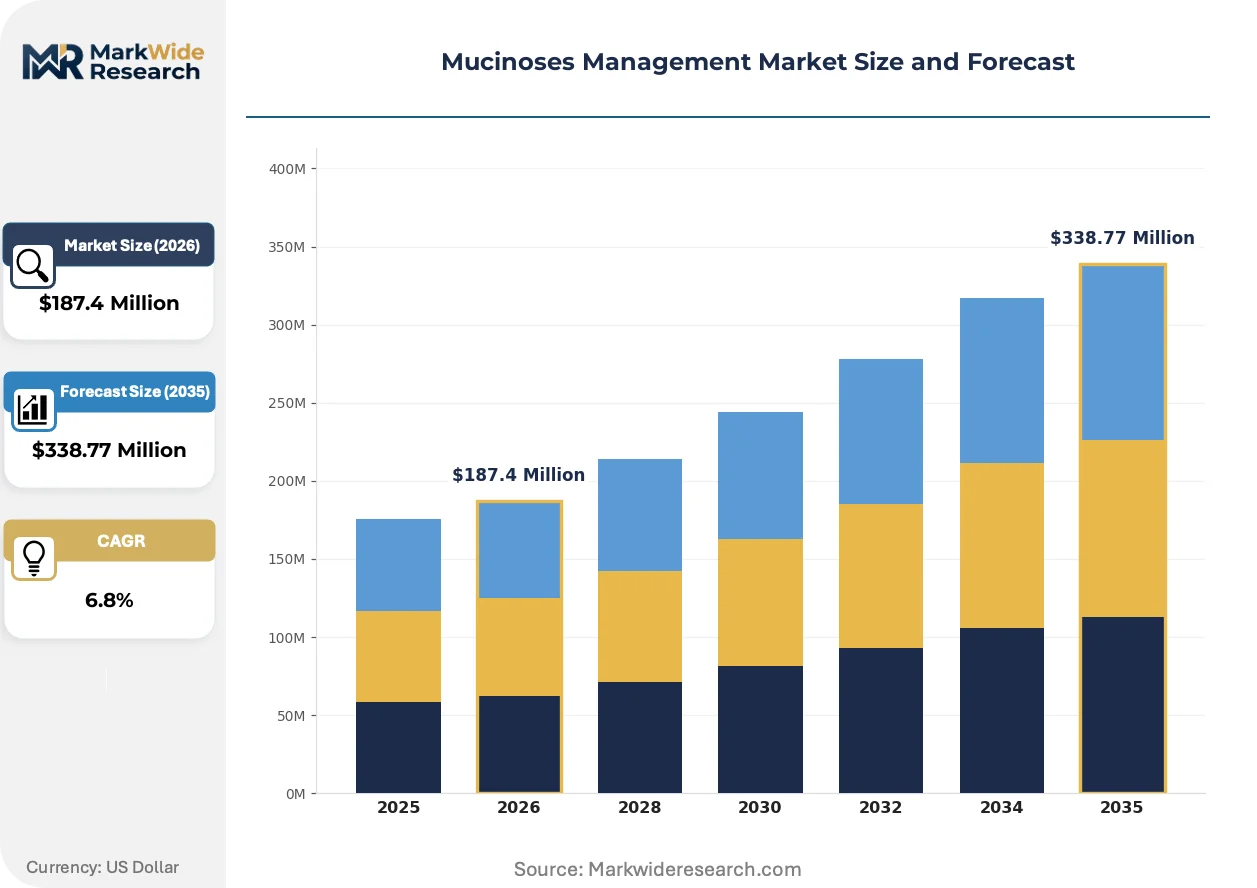
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topicals, Systemics, Biologics, Compounding Agents Application: Dermatology, Rheumatology, Orthopedics, Pulmonology End User: Clinics, Hospitals, Home Care, Research Institutions Delivery Mode: Injectable, Oral, Transdermal, Intranasal |
| Companies Covered | GSK plc, Almirall, S.A, Merck & Co., Inc, Bausch Health, Sandoz International GmbH, Pfizer Inc, AstraZeneca, Sanofi, Alencure Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mucinoses Management Market Shifts & Advancements
Biologics manufacturing and precision-targeted delivery systems are rewriting the clinical economics of mucinoses care, compressing development cycles while fragmenting traditional site-of-care models.
Subcutaneous IL-6 receptor antagonists are migrating from intravenous infusion protocols to patient-administered home injection systems. Academic dermatology departments at Stanford and University of California San Francisco pilot these transitions for refractory lichen myxedematosus cases. The shift collapses reimbursement structures built around hospital outpatient infusion center economics.
EMA's Medical Device Regulation imposes stricter clinical evidence thresholds on wearable drug delivery systems used in transdermal biologic administration. Manufacturers must now submit prospective randomized data for combination products previously cleared via predicate device pathways. German and French notified bodies enforce these standards most aggressively, delaying market entry for novel patch-pump integrations.
Specialty pharmacy benefit managers consolidate prior authorization workflows for step-therapy protocols governing biologic access. Express Scripts and CVS Caremark now require documented corticosteroid failure before approving IL-1 and IL-6 pathway inhibitors. This behavioral shift concentrates prescribing influence within managed care organizations rather than academic referral networks, most visible in California and Texas Medicaid programs.
Mucinoses Management Market Segmentation
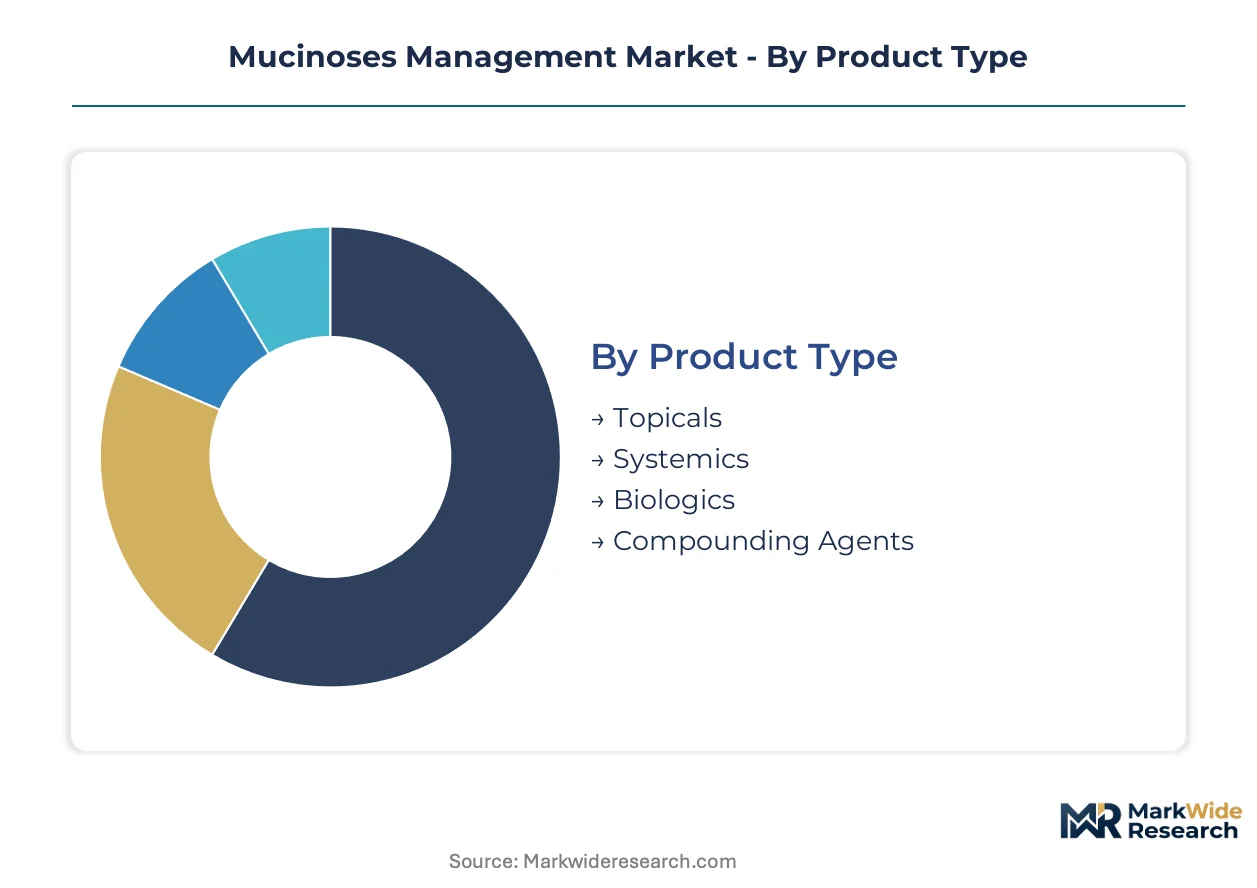
Mucinoses management segments reflect divergent clinical economics across care settings and therapeutic modalities. Product type stratification separates volume-driven topical formulations from high-margin biologic therapies, while delivery mode choices reshape site-of-care economics and patient access patterns.
Product Type:
Cost tier stratification separates commodity corticosteroid formulations from precision-targeted immunomodulatory therapies with manufacturing complexity premiums.
- Topicals:Corticosteroid and calcineurin inhibitor formulations dominate early-stage lichen myxedematosus protocols. Academic dermatology centers at University of Pennsylvania and Stanford anchor prescriber training for corticosteroid-sparing topical regimens, though payer step-therapy requirements delay biologic escalation.
- Biologics:IL-6 pathway inhibitors and IL-1 antagonists command premium positioning for refractory scleromyxedema cases. Johns Hopkins and Mayo Clinic infusion centers concentrate demand for intravenous tocilizumab protocols, while subcutaneous delivery platforms expand addressable pools beyond hospital capture.
- Systemics:Conventional immunosuppressants including methotrexate and mycophenolate mofetil bridge topical failure and biologic qualification.
- Compounding Agents:Pharmacy-compounded topical formulations serve patients with contact sensitivities to commercial excipients.
Topicals command the established base. The steepest expansion runs through biologics.
Application:
Clinical specialty boundaries determine prescriber authority and reimbursement pathway complexity for mucinosis interventions.
- Dermatology:Fellowship-trained dermatopathologists at academic medical centers anchor diagnostic workflows for lichen myxedematosus versus scleromyxedema differentiation. Cutaneous manifestations drive initial presentation and topical therapy initiation across US referral networks.
- Rheumatology:Systemic involvement with autoimmune overlap syndromes routes patients to rheumatology-led biologic protocols. Mayo Clinic and Cleveland Clinic co-management models concentrate complex cases requiring cytokine modulation expertise.
- Orthopedics:Pretibial myxedema with associated arthropathy triggers orthopedic consultation for functional impairment assessment.
- Pulmonology:Rare pulmonary mucinosis variants require pulmonology involvement for airway-centered disease management.
Dermatology anchors volume concentration. Rheumatology exhibits the steepest patient share gains.
End User:
Customer type fragmentation reflects divergent margin capture models across institutional and ambulatory settings.
- Hospitals:Academic medical centers concentrate infusion center economics for intravenous biologic administration. Johns Hopkins, Stanford, and University of California San Francisco anchor clinical trial recruitment and prescriber education networks that shape adoption curves for novel therapies.
- Home Care:Self-administered subcutaneous injection systems bypass hospital outpatient margins and expand geographic reach for maintenance dosing. Specialty pharmacy partnerships with Express Scripts and CVS Caremark consolidate prior authorization workflows for step-therapy compliance.
- Clinics:Community dermatology practices manage early-stage disease with topical protocols and systemic escalation monitoring.
- Research Institutions:FDA orphan drug trial sites and EMA PRIME-eligible studies concentrate at NIH-funded centers.
Hospitals retain the established revenue base. Home care delivery platforms are gaining share fastest.
Delivery Mode:
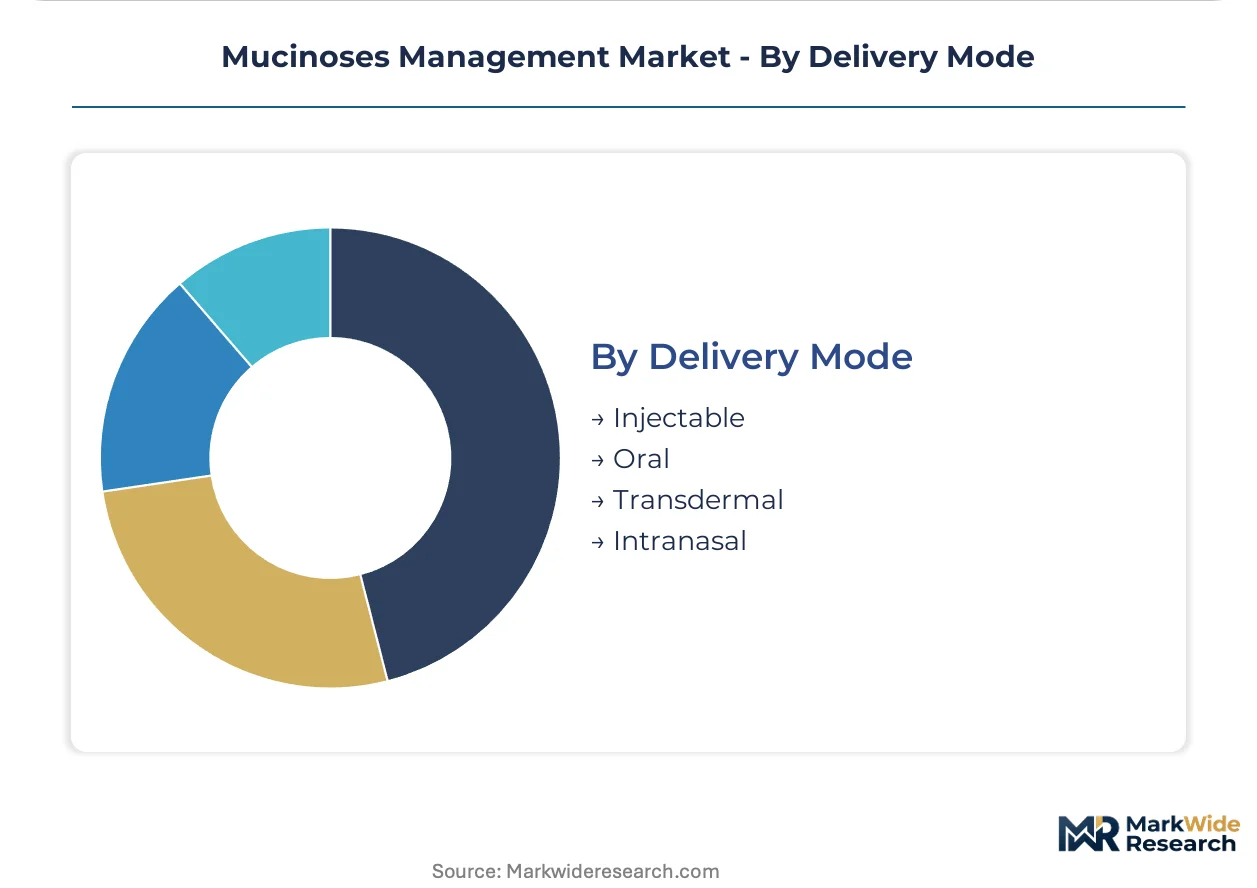
Volume concentration in parenteral administration reflects biologic formulation requirements, though oral and transdermal platforms reshape patient convenience expectations.
- Injectable:Intravenous infusion dominates biologic administration for refractory cases, with subcutaneous migration reducing site-of-care dependency. FDA-approved IL-6 receptor antagonists now include patient-administered options that collapse traditional hospital capture models.
- Oral:Small-molecule immunosuppressants and corticosteroid taper protocols sustain volume leadership in maintenance phases.
- Transdermal:EMA MDR compliance requirements impose stricter clinical evidence thresholds on wearable patch-pump combinations for biologic delivery.
- Intranasal:Experimental delivery platforms for localized mucinosis variants remain preclinical.
Injectable formulations command the established base. Transdermal platforms represent the most rapid technology transition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialty pharmacy networks anchor buyer concentration across mature markets, with regulatory acceleration pathways reshaping geographic investment priorities for mucinosis therapeutics development.
United States
Johns Hopkins, Mayo Clinic, and Stanford anchor prescriber education networks that drive biologic adoption curves for refractory cases. FDA orphan drug designation compresses development timelines for rare mucinosis subtypes under 200,000 patients. The Greater Boston cluster concentrates clinical trial recruitment for IL-6 pathway inhibitors.
Germany
Specialized dermatology departments at Charité Berlin and University Hospital Heidelberg manage complex scleromyxedema referrals from across Central Europe. EMA PRIME eligibility pathways accelerate assessment timelines for breakthrough mucinosis therapies. The Rhine-Main region hosts notified bodies enforcing stricter MDR clinical evidence thresholds on wearable drug delivery systems.
Japan
PMDA's conditional approval pathway for regenerative medicine enables earlier commercial entry for fibroblast-targeting interventions. Tokyo and Osaka academic centers pilot subcutaneous delivery transitions that collapse traditional hospital capture models. The country's aging demographics expand addressable pools for maintenance dosing regimens.
United Kingdom
NHS specialized commissioning frameworks concentrate biologic access decisions within regional dermatology networks. Guy's and St Thomas' NHS Foundation Trust anchors diagnostic workflows for lichen myxedematosus differentiation. MHRA post-Brexit regulatory autonomy enables accelerated pathways for therapies addressing diagnostic code fragmentation.
France
ANSM enforces pharmacovigilance requirements for plasma-derived immunoglobulin therapies used in mucinosis protocols. Parisian academic hospitals coordinate multicenter real-world evidence collection under EMA's DARWIN EU initiative. The Île-de-France region concentrates manufacturing investment for antibody-based therapeutics facing raw material volatility.
Mucinoses Management Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented prescribing influence networks. Large-cap pharmaceutical groups anchor biologic development pipelines through established immunology infrastructure, while mid-tier dermatology specialists concentrate commercialization expertise. Two archetypes dominate: diversified immunology platforms leveraging cross-indication manufacturing scale, and focused dermatology players with specialized prescriber relationships. Competitive moves center on subcutaneous delivery platform licensing and specialty pharmacy network partnerships that bypass hospital margin capture.
Within the diversified immunology tier, GSK plc and Pfizer Inc occupy positions anchored by cytokine-modulating therapy portfolios spanning multiple inflammatory indications. Almirall, S.A exemplifies the dermatology-specialist archetype through European commercialization concentration. Merck & Co., Inc sits within the R&D-intensive tier with established presence in precision-targeted mechanisms. These three represent distinct strategic postures rather than direct substitutability in prescriber decision frameworks.
| Leading Market Players |
|---|
| GSK plc |
| Almirall, S.A |
| Merck & Co., Inc |
| Bausch Health |
| Sandoz International GmbH |
| Pfizer Inc |
| AstraZeneca |
| Sanofi |
| Alencure Biotech |
| Others |
Supply & Pricing Matrix
The Rhine-Main region's biologics manufacturing concentration in Germany and Belgium generates asymmetric pricing power for plasma-derived immunoglobulin feedstocks, compressing margins for antibody-based mucinosis therapies while amplifying cost volatility for downstream formulators.
Pricing Analysis
Cost-plus contracts indexed to plasma collection economics dominate biologic procurement, with immunoglobulin feedstock costs fluctuating with donor availability. Price differentiation separates originator biologics from biosimilar alternatives, with certification tier and volume scale determining access rebates. Cost compression in the biosimilar tier is intensifying because European tendering consolidates purchasing influence. Community dermatology practices exhibit highest price sensitivity, while academic medical centers anchor premium positioning through trial participation.
Supply Chain Analysis
Plasma-derived raw materials draw from donor collection networks concentrated in the United States, Germany, and Austria, with fractionation capacity clustering in Ireland and Belgium. Upstream dependencies include immunoglobulin feedstock, recombinant protein substrates, and specialized cold-chain logistics. Single-source biologics production creates geopolitical exposure for supply continuity. Distribution runs through hospital infusion centers and specialty pharmacy networks for self-administered alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA orphan drug designation tailwinds compress development timelines for rare mucinosis subtypes, positioning the market for early-cycle expansion as biologic adoption accelerates through academic referral networks.
For Market Incumbents: Build regulatory exclusivity moats through accelerated approval pathway stacking for rare disease subsets. Deepen backward integration into plasma collection infrastructure to buffer feedstock volatility. Expand subcutaneous delivery platform licensing to preempt hospital margin capture erosion from home infusion migration.
For New Entrants and Emerging Players: Pursue white-space positioning in Japan's regenerative medicine conditional approval pathway for fibroblast-targeting interventions. Target home care delivery partnerships with specialty pharmacy networks as the most penetrable channel. Anchor go-to-market strategy through real-world evidence collection mandates under EMA's DARWIN EU initiative.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors dermatology-specialist platforms with concentrated prescriber relationships over diversified immunology players. Long-term viability hinges on subcutaneous delivery transitions collapsing traditional site-of-care economics. Acquisition targets should demonstrate specialty pharmacy network access and orphan drug designation traction. Monitor FDA breakthrough therapy designations as inflection indicators for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated pathways compress timelines for scleromyxedema subsets under 200,000 patients. |
| Subcutaneous Delivery Platform Licensing | Patient-administered systems bypass hospital outpatient economics and expand geographic reach. |
| Specialty Pharmacy Network Partnership | Express Scripts and CVS Caremark consolidate prior authorization workflows for step-therapy compliance. |
| Real-World Evidence Infrastructure | EMA DARWIN EU initiative creates funded access to longitudinal patient data for post-market validation. |
| Plasma Collection Backward Integration | Captive donor networks buffer immunoglobulin feedstock volatility from European fractionation concentration. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration throughout the analysis. Primary interviews with payer access specialists and dermatopathologists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down epidemiological estimates underwent iterative triangulation.
Scenario bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs derived from indication-specific prevalence trajectories and biologic penetration curves modeled through academic medical center adoption patterns and specialty pharmacy dispensing data.
Sensitivities concentrate around diagnostic code fragmentation delays, plasma supply disruptions, and payer step-therapy protocol tightening. Forecasts reflect documented assumptions on orphan drug designation success rates and subcutaneous delivery platform conversions. Cross-checking against CMS Medicare Part B spending data and EMA PRIME eligibility tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Cerebral Vasospasm Market
Specialty Medicine
Liver Metastases Treatment Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Ovarian Cysts Market