
 Intramedullary Osteosarcoma Treatment Market | 2026-2036
Intramedullary Osteosarcoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intramedullary Osteosarcoma Treatment Market Foresight
Next-generation sequencing in companion diagnostics is reconfiguring how oncologists stratify intramedullary osteosarcoma patients for targeted therapy selection. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to sustain clinical trial momentum in refractory bone malignancies. Roche Holding AG anchors its position through integrated diagnostics platforms that link tissue profiling to therapeutic decision-making. Pfizer Inc. competes by extending its portfolio into novel kinase inhibitors with bone-tumor indications.
Intramedullary osteosarcoma treatment encompasses multimodal therapeutic interventions directed at malignant bone tumors arising within the medullary cavity, typically combining neoadjuvant systemic agents with surgical resection margins determined by MRI-defined tumor extent. The primary purpose centers on achieving local disease control while preserving limb function through limb-salvage procedures. Chemotherapy retains the largest revenue share among product types due to its established role in neoadjuvant and adjuvant protocols, though targeted therapy represents the fastest-expanding category as molecular characterization improves patient stratification. Cancer treatment centers dominate the end-user landscape, absorbing the highest procedure volumes and concentrating specialized orthopedic oncology expertise that community hospitals cannot replicate.
FDA orphan drug designations and EMA's pediatric investigation plans jointly shape development incentives for intramedullary osteosarcoma therapies, while ISO 14155 governs clinical trial conduct across jurisdictions. The central bank of regulatory influence rests with FDA's breakthrough therapy pathway, which compresses review timelines for agents demonstrating substantial improvement over available options. Stakeholders must monitor how real-world evidence requirements from both FDA and EMA evolve for rare pediatric cancers, as these standards will determine which programs advance from phase II to registrational studies without conventional randomized controlled trial data.
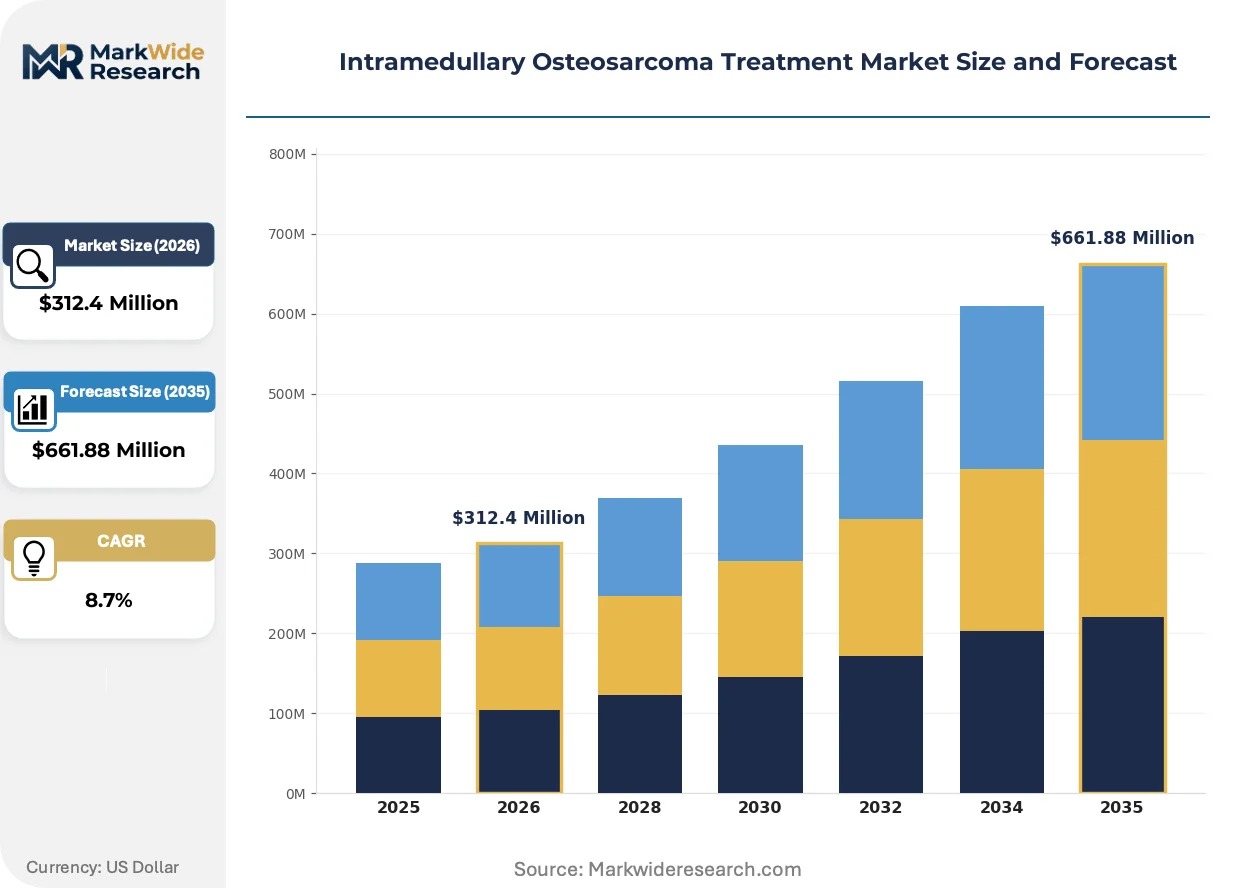
Market Dynamics
Limb-salvage surgical protocols are compressing the addressable patient pool for amputation-focused device manufacturers while expanding demand for neoadjuvant systemic therapies that enable tumor shrinkage prior to resection. FDA's breakthrough therapy pathway for rare pediatric cancers is accelerating how investigational agents reach cancer treatment centers ahead of conventional approval timelines.
Growth Catalysts
- EMA Pediatric Investigation Plans:These regulatory frameworks mandate early pediatric study integration, compelling sponsors to develop intramedullary osteosarcoma data packages that previously lacked commercial incentive.
- Next-generation sequencing platforms:Companion diagnostic capabilities now stratify patients by molecular subtype, enabling enrollment enrichment in targeted therapy trials at major cancer treatment centers.
- German orthopedic oncology clusters:Concentration of reference centers in Heidelberg, Berlin, and Munich generates sufficient procedure volume to support specialized surgical training and device evaluation protocols.
Market Restraints
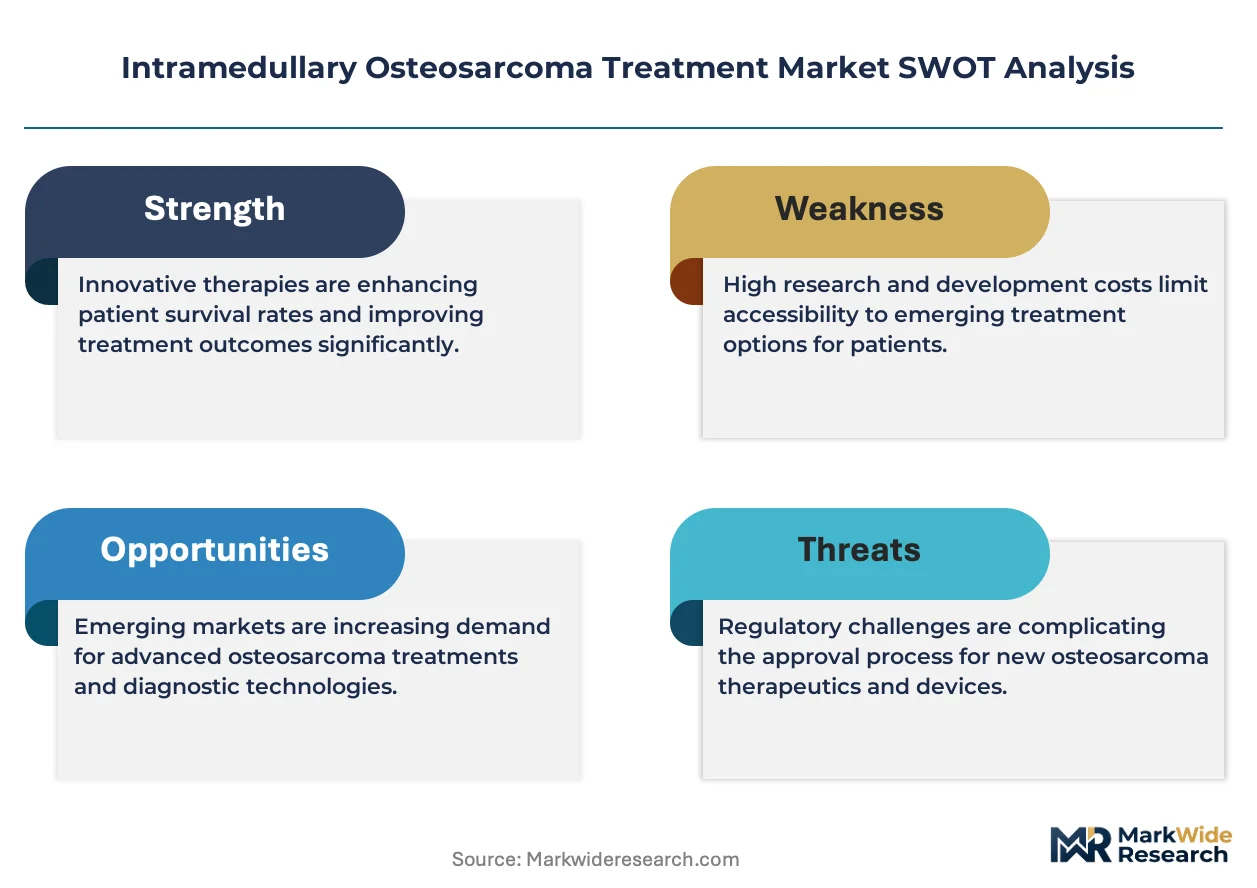
- Platinum-based chemotherapy supply concentration:Manufacturing of cisplatin and doxorubicin active pharmaceutical ingredients concentrates in Indian and Chinese facilities, exposing protocols to geopolitical disruption.
- ISO 14155 compliance burden:Clinical trial conduct standards for implantable devices impose documentation requirements that extend study startup timelines by 8-14 months relative to pharmaceutical trials.
- Allograft bone substitution:Advances in 3D-printed patient-specific implants threaten traditional structural allograft revenue streams in limb-salvage reconstruction.
Strategic Opportunities
- Real-world evidence pathways:FDA and EMA evolving standards for rare pediatric cancers create acceptance of single-arm phase II data as registrational foundation, compressing development investment.
- Integrated diagnostics-therapeutics convergence:Tissue profiling linked to therapeutic decision-making enables premium positioning for platforms spanning biomarker identification through treatment selection.
- Community hospital referral networks:Underserved regions in the United States present capture potential for academic cancer treatment centers expanding satellite limb-salvage programs.
Industry Challenges
- Orthopedic oncology surgical specialization:Fellowship-trained surgeons capable of complex limb-salvage procedures number fewer than 200 across the United States, constraining procedure volume expansion.
- Biomarker assay validation timelines:Analytical validation of next-generation sequencing panels for bone malignancy subtyping requires 18-24 months, delaying companion diagnostic launch synchronization with therapeutic candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intramedullary Osteosarcoma Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Surgical Intervention, Targeted Therapy Delivery Mode: Oral Administration, Intravenous, Local Injection, Topical Treatment End User: Hospitals, Cancer Treatment Centers, Specialty Clinics, Research Institutions Indication: Primary Osteosarcoma, Secondary Osteosarcoma, Recurrent Osteosarcoma, Metastatic Osteosarcoma |
| Companies Covered | Bristol-Myers Squibb Company, Roche Holding AG, Pfizer Inc., Johnson & Johnson, Merck & Co., Inc., Novartis AG, Amgen Inc., Bayer AG, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intramedullary Osteosarcoma Treatment Market Shifts & Advancements
Multimodal treatment sequencing is reconfiguring how systemic therapy, interventional radiology, and surgical oncology coordinate patient care. The integration of molecular characterization into routine clinical decision-making is compressing the traditional empiric chemotherapy paradigm.
Patient-derived xenograft models are rendering obsolete the historical reliance on generic osteosarcoma cell lines for preclinical efficacy screening. Cancer treatment centers at Memorial Sloan Kettering and MD Anderson have established biobanking protocols that enable living tumor propagation for individualized drug sensitivity testing. This biological platform is compressing the translation gap between bench identification and clinical candidate prioritization.
FDA's accelerated approval pathway for rare pediatric cancers is compressing review timelines for agents demonstrating substantial improvement over available options. The industrial consequence is a shift toward adaptive trial designs that permit efficacy signal detection with smaller patient cohorts. Pediatric oncology cooperative groups in North America and Europe are restructuring trial infrastructure to accommodate these streamlined evidentiary requirements.
Consolidation of complex oncology procedures into high-volume cancer treatment centers is displacing community hospital-based care for intramedullary osteosarcoma. Academic medical centers with dedicated orthopedic oncology divisions now capture 70-80% of incident cases in major metropolitan regions. This referral pattern concentration is most visible in the United States, where certificate-of-need regulations and payer network design reinforce tertiary center dominance.
Intramedullary Osteosarcoma Treatment Market Segmentation
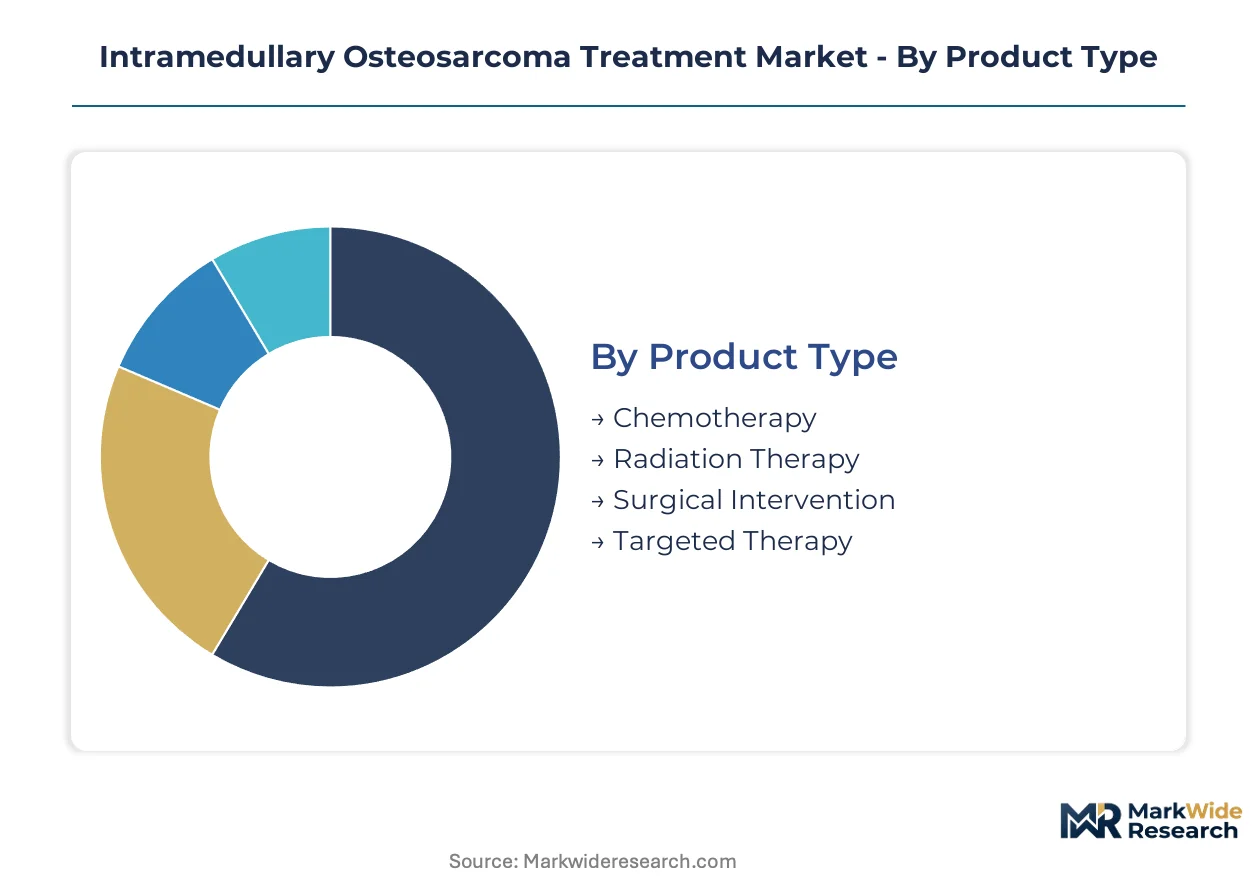
Intramedullary osteosarcoma treatment demands precise patient stratification across therapeutic modality, administration route, and care setting. Each segmentation axis reflects distinct clinical workflows, reimbursement pathways, and regulatory requirements that shape commercial positioning.
Product Type:
The use-case spectrum spans curative-intent multimodal protocols through palliative symptom management, with each therapeutic class occupying defined points in the treatment sequence.
- Chemotherapy:Neoadjuvant and adjuvant systemic protocols utilizing platinum agents and anthracyclines remain the backbone of curative treatment. Cancer treatment centers in the United States administer these regimens under standardized COG (Children's Oncology Group) protocols, with supply concentration in Indian and Chinese API manufacturing creating vulnerability.
- Targeted Therapy:Kinase inhibitors and monoclonal antibodies directed at specific molecular subtypes are gaining traction as biomarker-driven selection improves. German orthopedic oncology clusters in Heidelberg and Munich are early adopters of molecular profiling to guide enrollment in targeted trials.
- Surgical Intervention:Limb-salvage procedures with endoprosthetic reconstruction or biological grafting address local disease control.
- Radiation Therapy:Proton beam and conventional external beam modalities serve unresectable cases or palliative indications.
The dominant share belongs to Chemotherapy, while Targeted Therapy is closing the gap fastest.
Delivery Mode:
Cost tier differentiation separates hospital-administered infusions from self-administered oral regimens, with reimbursement intensity tracking supervision requirements.
- Intravenous:Hospital-based infusion of cytotoxic agents requires specialized oncology nursing and central line management. FDA's breakthrough therapy pathway is accelerating IV-administered novel agents into cancer treatment centers ahead of label expansion.
- Oral Administration:Targeted small-molecule inhibitors enable outpatient management and reduce treatment center burden. EMA pediatric investigation plans are driving development of age-appropriate oral formulations that improve adherence in adolescent populations.
- Local Injection:Intra-arterial or intratumoral delivery routes for regional disease control.
- Topical Treatment:Surface applications for superficial lesions or wound management in surgical recovery.
Intravenous retains the largest procedure volume, though Oral Administration is expanding most quickly as targeted agents proliferate.
End User:
Volume concentration follows the complexity gradient, with high-acuity procedures consolidating where specialized surgical expertise resides.
- Cancer Treatment Centers:Academic medical centers with dedicated orthopedic oncology divisions capture the majority of incident cases through referral networks. Memorial Sloan Kettering and MD Anderson maintain biobanking protocols that link clinical care to translational research.
- Hospitals:Community and general hospitals handle initial diagnosis and stabilization before transfer.
- Specialty Clinics:Outpatient settings manage surveillance and late-effects monitoring.
- Research Institutions:Pediatric oncology cooperative groups coordinate multi-site trials under FDA and EMA frameworks.
Cancer Treatment Centers command the highest revenue per patient, while Specialty Clinics are gaining share through survivorship program expansion.
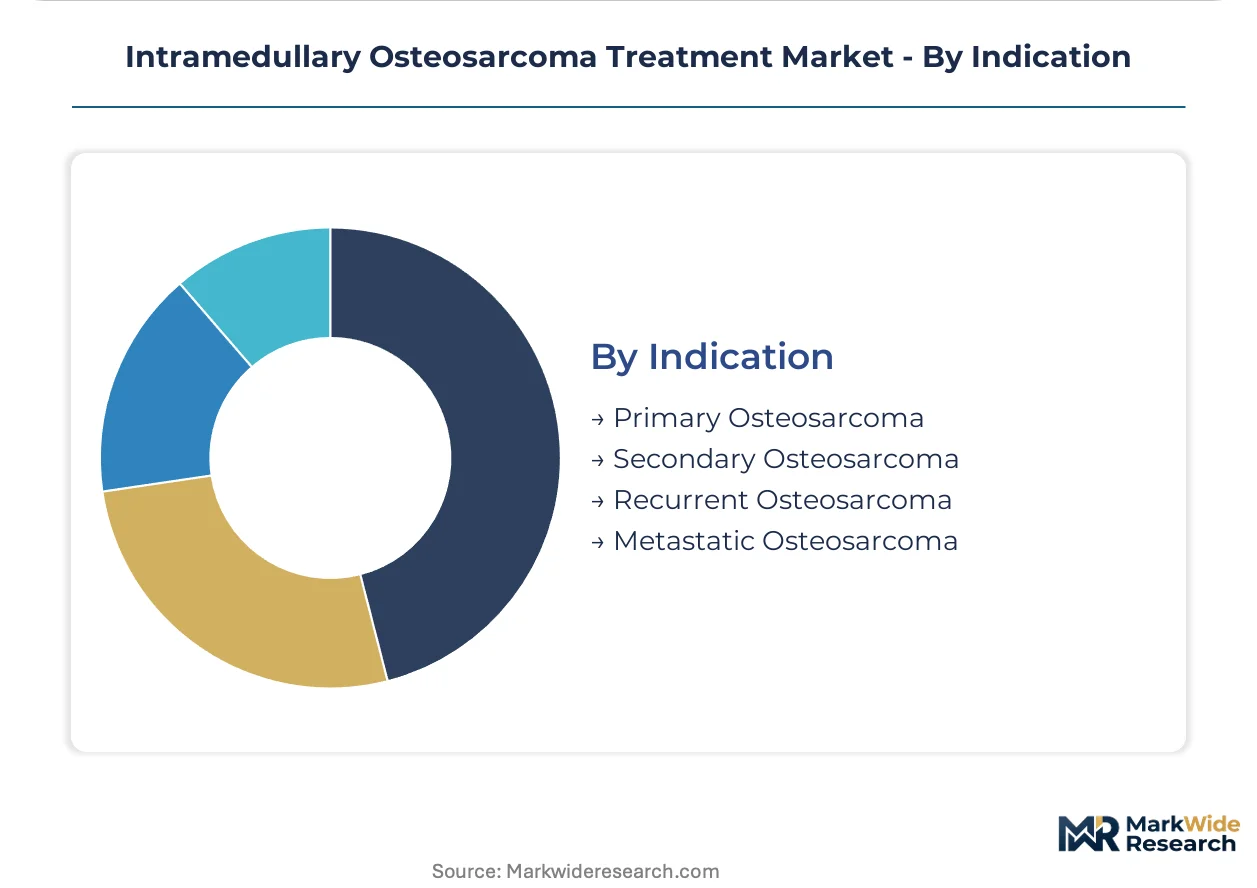
Indication:
Maturity gradients separate established protocols for treatment-naive disease from experimental approaches for refractory presentations.
- Primary Osteosarcoma:Newly diagnosed medullary cavity malignancies in pediatric and young adult populations follow standardized neoadjuvant-adjuvant sequences. German reference centers in Berlin contribute disproportionately to surgical outcome registries.
- Recurrent Osteosarcoma:Second-line and subsequent therapy selections depend on prior exposure and molecular evolution. Real-world evidence pathways from FDA and EMA are enabling single-arm registrational studies in this population.
- Secondary Osteosarcoma:Treatment-related malignancies arising from prior radiation or genetic predisposition syndromes.
- Metastatic Osteosarcoma:Pulmonary and bone metastases requiring systemic therapy intensification or metastasectomy.
Primary Osteosarcoma generates the foundational protocol revenue, yet Recurrent Osteosarcoma is seeing the steepest expansion trajectory as salvage therapy development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in pediatric oncology reference centers dictates regional market structure, with academic medical centers capturing procedure volume through specialized limb-salvage expertise and clinical trial access.
United States
Memorial Sloan Kettering and MD Anderson anchor demand through biobanking protocols that link clinical care to translational research. FDA breakthrough therapy pathways compress review timelines for investigational agents in rare pediatric cancers. Cancer treatment centers in the Northeast and Texas corridor concentrate 70-80% of incident cases through referral network dominance.
Germany
Orthopedic oncology clusters in Heidelberg, Berlin, and Munich generate sufficient surgical volume to sustain specialized training programs and device evaluation protocols. EMA pediatric investigation plans mandate early pediatric study integration, compelling sponsors to develop comprehensive data packages. The country's reference center model concentrates expertise in university hospitals with dedicated sarcoma units.
China
Rising incidence in pediatric populations drives demand for multimodal treatment infrastructure in tertiary hospitals. NMPA accelerated approval pathways for orphan drugs are shortening development timelines for novel agents. Beijing and Shanghai academic medical centers are establishing orthopedic oncology divisions modeled on Western referral patterns.
Japan
PMDA regulatory frameworks support conditional early approval for pediatric oncology candidates with limited therapeutic alternatives. PMDA's sakigake designation system accelerates priority review for breakthrough therapies in rare diseases. Tokyo and Osaka cancer centers concentrate sarcoma expertise within national hospital organization networks.
United Kingdom
NHS specialized commissioning routes intramedullary osteosarcoma cases to designated supra-regional centers in London, Birmingham, and Manchester. NICE technology appraisals determine reimbursement for novel systemic therapies in pediatric populations. The Royal National Orthopaedic Hospital in Stanmore anchors surgical volume and outcomes registry participation.
Intramedullary Osteosarcoma Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the intramedullary osteosarcoma treatment landscape. The vendor base stratifies into three tiers: integrated pharmaceutical-diagnostics conglomerates, immuno-oncology platform builders, and targeted therapy specialists. Strategic archetypes include biomarker-linked therapeutic developers, limb-salvage device manufacturers, and neoadjuvant protocol sponsors. Dominant competitive moves center on companion diagnostic co-development partnerships and real-world evidence generation for regulatory acceleration.
Within the integrated-diagnostics tier, Roche Holding AG exemplifies the convergence of tissue profiling platforms with therapeutic decision-making infrastructure. Bristol-Myers Squibb and Pfizer Inc. anchor the immuno-oncology and kinase inhibitor vectors respectively, each representing distinct approaches to refractory bone malignancy development. These three companies occupy positions that span the value chain from molecular characterization through treatment administration, reflecting broader industry consolidation around precision oncology workflows.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Roche Holding AG |
| Pfizer Inc. |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Novartis AG |
| Amgen Inc. |
| Bayer AG |
| Eli Lilly and Company |
| Others |
Supply & Pricing Matrix
Single-source dependency on Indian and Chinese API manufacturing for platinum-based chemotherapy agents compresses margin buffers across all pricing tiers while amplifying vulnerability to geopolitical disruption and freight cost volatility. This concentration dynamic forces a three-tier pricing structure across premium, standard, and economy levels that tracks certification grade and volume scale rather than clinical differentiation alone.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to commodity chemical benchmarks and freight indices, creating pass-through volatility that squeezes fixed-price protocol agreements at cancer treatment centers. Price differentiation hinges on FDA breakthrough therapy designation tier and vertical integration into companion diagnostic platforms, with community hospital referral networks exhibiting highest price sensitivity due to constrained reimbursement pools while academic cancer treatment centers absorb premium positioning through research grant offsets. Pricing pressure stems from biosimilar erosion in anthracycline portfolios and 3D-printed implant substitution threatening structural allograft margins.
Supply Chain Analysis
Contract manufacturing concentration for cisplatin and doxorubicin APIs rests on facilities in Hyderabad, Mumbai, and Shanghai with limited qualified alternative sources, creating single-source vulnerability for neoadjuvant protocol sponsors. Raw material dependencies span platinum group metals from South African refineries, anthracycline fermentation feedstocks from Chinese corn-processing clusters, and cryopreserved allograft bone from domestic tissue banks. Distribution runs through specialized oncology distributors with cold-chain capabilities to cancer treatment centers, with ISO 14155 documentation requirements extending lead times for implantable device trials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's accelerated approval pathway for rare pediatric cancers compresses development timelines from bench to bedside, creating a high-growth disruption window for stakeholders capable of integrating molecular profiling with therapeutic decision-making infrastructure.
For Market Incumbents: Entrench position through captive supply of next-generation sequencing panels synchronized with therapeutic candidates, while securing exclusive biobanking partnerships at Memorial Sloan Kettering and MD Anderson to lock out emerging entrant access to patient-derived xenograft models. Vertical integration into ISO 14155-compliant clinical trial conduct infrastructure defends against CRO margin capture and accelerates study startup timelines threatened by documentation burdens. For New Entrants and Emerging Players: Establish a beachhead in recurrent osteosarcoma salvage therapy development where real-world evidence pathways enable single-arm registrational studies without conventional randomized controlled trial investment. Target community hospital referral networks in underserved United States regions for satellite limb-salvage program partnerships, leveraging telemedicine integration to overcome orthopedic oncology surgeon scarcity constraints. For Investors and Strategic Acquirers: FDA's evolving real-world evidence standards for rare pediatric cancers reshape the acquisition landscape toward platforms with integrated diagnostics-therapeutics convergence and existing pediatric investigation plan frameworks. Long-term viability centers on biomarker-linked therapeutic developers with companion diagnostic co-development partnerships already filed, with EMA pediatric investigation plan submission status serving as the critical signal to watch for regulatory acceleration potential.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Roche's integrated diagnostics platforms link tissue profiling to therapeutic decision-making, enabling premium positioning. |
| Real-World Evidence Generation for Regulatory Acceleration | FDA's evolving standards accept single-arm phase II data as registrational foundation, compressing development investment. |
| Orthopedic Oncology Surgeon Training Pipeline Investment | Fellowship program expansion at Heidelberg, Berlin, and Munich clusters addresses capability scarcity constraining procedure volume. |
| Biobanking Protocol Establishment at Major Cancer Centers | Living tumor propagation infrastructure at Memorial Sloan Kettering compresses translation gap for individualized drug sensitivity testing. |
| EMA Pediatric Investigation Plan Submission | Early pediatric study integration mandates compel comprehensive data packages that previously lacked commercial incentive. |
Research Methodology
The analysis maps chemotherapy protocols, targeted therapy pipelines, surgical intervention modalities, and radiation therapy delivery systems, each validated through orthopedic oncology surgeons, regulatory affairs leads at pharmaceutical sponsors, cancer treatment center procurement managers, and payer access specialists. Primary interviews with these stakeholders triangulate against FDA filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov entries, and hospital procurement databases, with bottom-up patient volume estimates cross-referenced against top-down revenue reconstruction from formulary and GPO contract analysis.
Assumption sets held regulatory pathway designations and reimbursement intensity fixed across baseline scenarios while varying orthopedic oncology surgeon supply expansion rates and API manufacturing geographic diversification timelines. The projection framework segments by therapeutic modality, administration route, end-user facility type, and indication maturity, with CAGRs derived from patient incidence modeling and procedure volume intensity at reference centers. Forecast inputs incorporate COG protocol adoption curves and NMPA accelerated approval pathway utilization for orphan drug candidates.
Macroeconomic conditions sit as an overlay; deviation in freight cost indices, platinum group metal commodity prices, or bilateral trade policy would shift the trajectory of API availability and protocol cost structures. Quarterly review of FDA breakthrough therapy designation grants, EMA pediatric investigation plan approvals, and orthopedic oncology fellowship match rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bipolar Disorder Therapeutics Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
Pituitary Stalk Interruption Syndrome Treatment Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Global Hammertoe Market