
 Electronic Display Market | 2026-2036
Electronic Display Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Display Market Intelligence
Buyer concentration among automotive OEMs is restructuring procurement dynamics across the Electronic Display Market. Samsung Electronics leverages in-house semiconductor production to dominate premium panel supply. LG Electronics anchors large-format OLED capacity for digital signage and broadcast applications. Unilumin competes aggressively on cost in the LED billboard segment across Asia.
Electronic displays are optoelectronic devices that modulate light through liquid crystals, organic diodes, or inorganic micro-LEDs to render visual information, typically measured by resolution density, refresh rate, and color gamut coverage, serving as human-machine interfaces across consumer, industrial, and mobility platforms. OLED technology leads in premium smartphone and wearable applications where self-emissive pixels enable thinner form factors and deeper contrast ratios. LCD remains the margin workhorse in gaming monitors and aviation displays where cost sensitivity and proven supply chains sustain volume dominance. MicroLED occupies an early-stage position in transparent screens and large-format commercial installations where modular assembly justifies current manufacturing premiums.
FCC equipment authorization rules shape electromagnetic compatibility requirements for displays sold into US consumer electronics channels, while REACH and RoHS frameworks in Europe restrict cadmium, lead, and mercury content in backlight assemblies and driver circuits. China's GB standards and MIIT certifications govern display energy efficiency and blue-light emission thresholds for domestic product registration. Stakeholders must monitor divergence between regional chemical compliance regimes and emerging e-waste recovery mandates as panel refresh cycles compress and material recovery obligations expand.
Market Dynamics
Automotive OEM procurement concentration around curved dashboard panels is compressing supplier margins and forcing display manufacturers to co-locate engineering teams near vehicle assembly plants in Germany, Japan, and the United States.
Growth Catalysts
- REACH chemical restrictions:European reformulation mandates for backlight films are accelerating substitution of cadmium-based quantum dots with indium phosphide alternatives, opening procurement windows for compliant material suppliers.
- Micro-LED modular assembly:Transparent screen installations in retail and corporate environments are scaling as tile-based construction reduces field replacement costs and enables custom aspect ratios.
- Shenzhen-Guangzhou manufacturing clusters:Concentrated panel finishing capacity in China's Pearl River Delta is shortening logistics lead times for ASEAN-bound shipments of commercial display systems.
Market Restraints
- Indium supply concentration:Over 80% of refined indium for ITO electrodes originates from Chinese smelters, exposing transparent electrode costs to export quota volatility.
- OLED deposition equipment scarcity:Canon Tokki and Sunic System dominate vapor deposition chamber supply, creating 18-month order backlogs for new OLED fab capacity.
- Aviation certification timelines:FAA and EASA airworthiness approvals for cockpit displays require 3-5 year validation cycles that freeze technology refresh rates.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for display module assembly are attracting component suppliers to set up finishing operations in Uttar Pradesh and Tamil Nadu.
- Digital signage as-a-service:Hardware-plus-content subscription models are displacing capital purchase arrangements in North American quick-service restaurant chains.
- Dual carbon goals in China:MIIT energy efficiency mandates for display products are creating premium positioning for low-power IGZO backplane technology in domestic procurement.
Industry Challenges
- Driver IC design talent scarcity:Mixed-signal semiconductor expertise for TCON and source driver architectures concentrates in Taiwan and South Korea, constraining new entrant fab ramp schedules.
- Legacy avionics integration:ARINC 661 widget specification compliance requires dedicated engineering teams to bridge 20-year-old cockpit software stacks with modern LCD and OLED hardware interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Display Market |
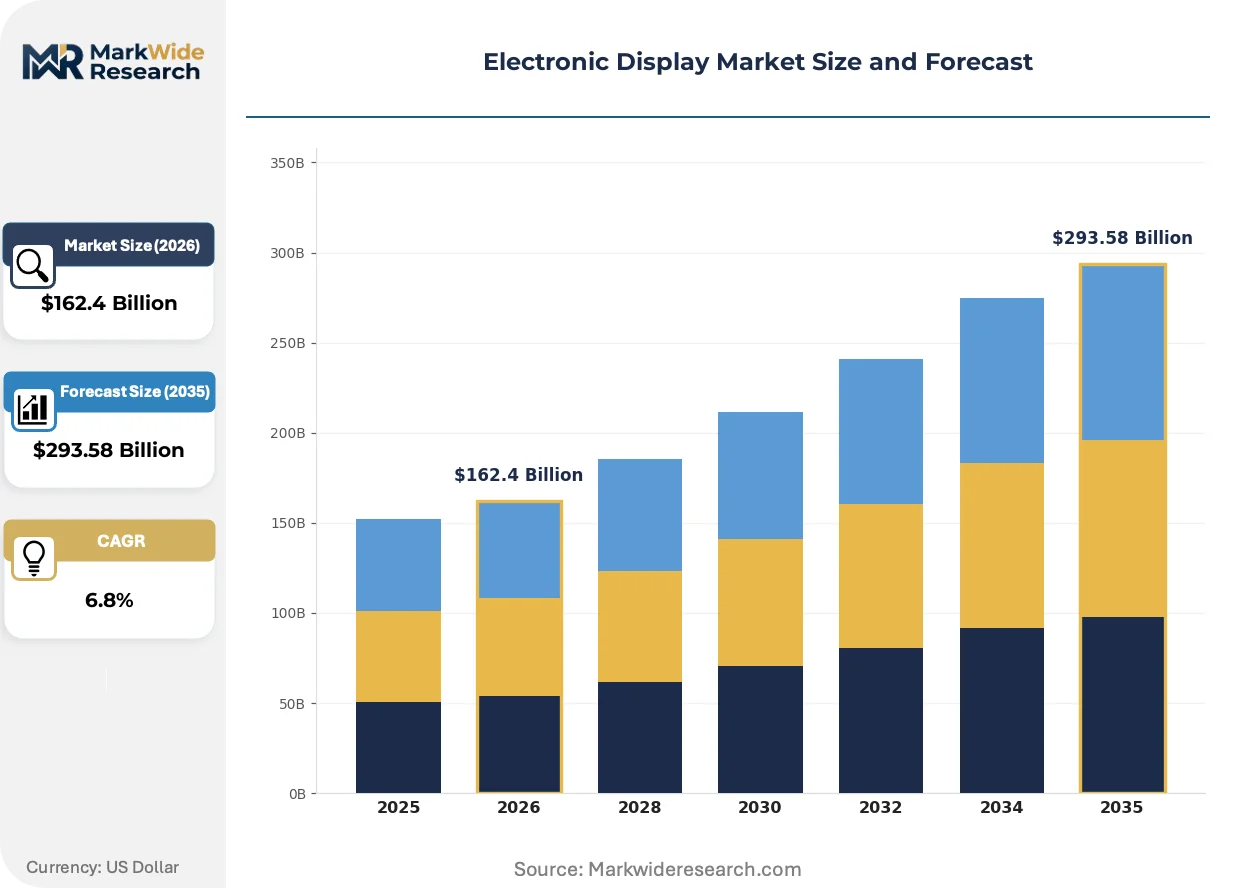
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $293.58 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Display Technology: LCD, OLED, QLED, MicroLED, E-Ink, DLP Application: Consumer Electronics, Digital Signage, Automotive Dashboards, Wearable Devices, Gaming Monitors, Aviation Displays End User Industry: Entertainment Providers, Aerospace Sector, Vehicle Manufacturers, Sports Equipments, Smart Device Makers, Medical Instruments Product Form: Flexible Displays, Transparent Screens, Curved Panels, Flat Panels, 3D Displays, Touchscreen Panels |
| Companies Covered | Liantronics, Absen, Samsung Electronics, Planar Systems, Daktronics, LG Electronics, Unilumin, NanoLumens, Leyard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Display Market Strategic Shifts & Innovations
Panel architecture is bifurcating between premium self-emissive technologies and cost-optimized LCD derivatives, with manufacturing investment flowing toward equipment that can serve both smartphone and automotive form factors.
Mini-LED backlighting with thousands of local dimming zones is electrifying premium notebook and tablet positioning, as Apple and Samsung Electronics adopt the technology for high-end product lines. Automotive tier-1 suppliers are evaluating mini-LED for curved instrument clusters where thermal management constraints rule out OLED. The structural consequence is compression of conventional edge-lit LCD share in segments above 500 nits brightness requirements.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are forcing display manufacturers to validate CO2-based heat pump drying systems for polarizer lamination processes. Industrial consequence includes 15-20% capital cost increases for new module assembly lines in European facilities. Automotive display suppliers serving Stuttgart and Munich OEMs are accelerating pilot lines to secure process qualification ahead of 2027 compliance deadlines.
Fleet operators in logistics and ride-hailing are unbundling display hardware from telematics service contracts, treating in-vehicle screens as replaceable peripherals rather than integrated systems. This behavior shift is fragmenting procurement authority between IT departments and vehicle maintenance teams. The pattern is most visible in North American commercial vehicle deployments where 3-4 year replacement cycles now apply to cabin displays independently of powertrain refresh schedules.
Electronic Display Market Segmentation
Display markets fragment across incompatible manufacturing processes and certification regimes. Technology choices lock buyers into specific supply chains for 5-7 year procurement cycles. Form factor decisions cascade through thermal design, optical bonding, and assembly automation requirements.
Display Technology:
Standardization dominates high-volume segments while customization commands premium positioning in specialized applications.
- LCD:Twisted nematic and in-plane switching architectures leverage mature TFT backplane fabrication. Gaming monitor procurement in Taiwan and South Korea sustains volume leadership despite margin compression from OLED alternatives.
- OLED:Self-emissive organic stacks deposited through vacuum thermal evaporation enable sub-2mm panel thickness. Wearable device makers in Shenzhen concentrate demand around flexible polyimide substrates for curved wrist-worn form factors.
- QLED:Quantum dot enhancement films boost color volume in high-end television panels. Cadmium-free indium phosphide cores satisfy REACH compliance for European consumer electronics channels.
- MicroLED:Gallium nitride microchips transferred via mass pick-and-place bonding enable modular tile construction. Transparent retail installations in Dubai and Singapore justify current manufacturing premiums through reduced field replacement costs.
- E-Ink:Bistable electrophoretic particles maintain image without power draw. Logistics labeling and e-reader applications in Germany and Japan anchor demand stability.
- DLP:Digital micromirror devices project high-lumen imagery through Texas Instruments' proprietary MEMS fabrication. Cinema projection and automotive head-up displays remain primary consumption channels.
Leading the category by volume: LCD. Growing fastest: MicroLED.
Application:
Volume concentration varies sharply across customer procurement authority and replacement cycle length.
- Consumer Electronics:Smartphones, tablets, and televisions absorb over half of global panel output. Samsung Electronics and Apple procurement calendars drive quarterly demand volatility through concentrated launch windows.
- Digital Signage:Large-format commercial installations require 50,000-hour luminance stability guarantees. Quick-service restaurant chains across North America are shifting from capital purchase to hardware-as-a-service subscription models.
- Automotive Dashboards:Curved instrument clusters demand optical bonding expertise for vibration resistance. German and Japanese OEMs are co-locating display engineering teams near final assembly plants to compress development cycles.
- Wearable Devices:Circular and rectangular form factors below 2-inch diagonal dominate smartwatch specifications. Fitness tracker demand from Guangdong manufacturers is accelerating flexible OLED substrate qualification.
- Gaming Monitors:144Hz+ refresh rates and 1ms response times differentiate premium positioning. Esports venue procurement in South Korea and China sustains high-refresh LCD volume despite OLED encroachment.
- Aviation Displays:FAA and EASA certification mandates 3-5 year validation timelines that freeze technology adoption rates. Cockpit LCD retrofits for Boeing and Airbus platforms sustain legacy supply chain relationships.
Highest shipment volume: Consumer Electronics. Steepest expansion trajectory: Automotive Dashboards.
End User Industry:
Margin structure diverges between price-sensitive volume buyers and specification-rigid certified applications.
- Entertainment Providers:Cinema chains and theme parks demand 10,000-nit outdoor visibility and 100,000-hour operational life. Stadium screen procurement concentrates in the Middle East and Southeast Asia around mega-event construction cycles.
- Aerospace Sector:ARINC 661 widget compliance bridges 20-year-old cockpit software with modern hardware interfaces. Boeing and Airbus tier-1 suppliers maintain dedicated engineering teams for legacy avionics integration.
- Vehicle Manufacturers:Center stack and rear-seat entertainment specifications diverge between luxury and mass-market platforms. Stuttgart and Munich OEMs are accelerating pilot lines for F-Gas Regulation compliance ahead of 2027 deadlines.
- Sports Equipments:Golf simulators and fitness machines integrate touch overlays for interactive training interfaces. North American country club procurement sustains mid-size panel demand.
- Smart Device Makers:Foldable phone hinge durability testing consumes 200,000-cycle mechanical validation resources. Samsung Electronics and Huawei specification teams drive flexible display roadmapping.
- Medical Instruments:Diagnostic imaging requires DICOM calibration for grayscale accuracy. FDA 510(k) clearance timelines extend display qualification by 18-24 months beyond consumer electronics norms.
Dominant procurement volume: Smart Device Makers. Fastest contract value growth: Aerospace Sector.
Product Form:
Manufacturing equipment compatibility constrains form factor proliferation despite design flexibility advances.
- Flexible Displays:Polyimide substrate handling through roll-to-roll processing enables cylindrical and foldable geometries. Samsung Display's A3 fab in Asan anchors global supply concentration.
- Transparent Screens:MicroLED tile assemblies achieve 60-70% optical transparency for retail window installations. Corporate headquarters in London and New York are piloting transparent video wall deployments.
- Curved Panels:1000R-1800R radius specifications dominate gaming monitor and automotive dashboard applications. Thermal stress management during glass bending limits supplier qualification to tier-1 panel makers.
- Flat Panels:Conventional rectangular form factors sustain lowest manufacturing cost through standardized mother glass cutting. Volume television procurement in India and Brazil anchors demand stability.
- 3D Displays:Lenticular lens and parallax barrier approaches deliver glasses-free depth perception. Medical visualization and military training simulators sustain niche demand.
- Touchscreen Panels:Projected capacitive sensor integration adds 15-20% module cost for interactive functionality. Kiosk and point-of-sale procurement across North America and Europe sustains mid-volume demand.
Flat Panels command volume leadership. Transparent Screens are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium refining concentrates in Chinese smelters supplying transparent electrode feedstock for display manufacturing worldwide. Panel finishing capacity clusters around specific metropolitan manufacturing zones where logistics infrastructure and component ecosystems enable rapid assembly turnaround.
China
MIIT energy efficiency certifications and dual carbon goals are tightening domestic display product registration requirements. Shenzhen and Guangzhou manufacturing clusters absorb over half of global panel finishing operations. Guangdong province suppliers are shortening logistics lead times for ASEAN-bound commercial display systems through concentrated mother glass cutting and polarizer lamination capacity.
South Korea
Samsung Electronics and LG Electronics procurement calendars drive quarterly demand volatility through concentrated smartphone and television launch windows. The country's national electronics regulator enforces strict electromagnetic compatibility standards under KC certification mandates. Asan and Paju industrial complexes anchor global OLED deposition capacity, though Canon Tokki equipment backlogs constrain fab expansion timelines.
United States
FCC equipment authorization rules shape electromagnetic compatibility requirements for consumer electronics channel entry. FAA airworthiness validation cycles freeze cockpit display technology refresh rates at 3-5 year intervals. Michigan and Ohio automotive assembly corridors are attracting co-located display engineering teams from tier-1 suppliers serving Detroit OEMs.
Germany
EU F-Gas Regulation phase-down schedules are forcing CO2-based heat pump drying validation for polarizer lamination processes by 2027. Stuttgart and Munich OEMs are accelerating pilot lines for compliant automotive display module assembly. Bavaria and Baden-Württemberg host concentrated automotive tier-1 supplier engineering operations for curved instrument cluster development.
Japan
METI industrial policy supports domestic display material and equipment supplier competitiveness against Korean and Chinese rivals. JIS standards govern product quality benchmarks for domestic and export market access. Chubu and Kansai manufacturing belts sustain specialized chemical supply for liquid crystal and organic semiconductor deposition processes.
Electronic Display Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue modular LED tile and transparent screen specializations. The vendor base stratifies across three tiers: integrated semiconductor-display conglomerates controlling premium panel supply, specialized LED billboard fabricators competing on cost, and niche transparent display assemblers serving commercial installation markets. Dominant competitive moves include co-location of engineering teams near automotive assembly plants and backward integration into driver IC and backlight component supply.
Among Korean electronics conglomerates, Samsung Electronics and LG Electronics occupy positions exemplifying integrated semiconductor-display capability. Samsung Electronics leverages in-house chip production for premium panel supply chain control. LG Electronics anchors large-format OLED capacity for digital signage and broadcast applications. Chinese LED specialists including Unilumin and Leyard represent cost-optimized billboard segment positioning across Asian commercial installation markets.
| Leading Market Players |
|---|
| Liantronics |
| Absen |
| Samsung Electronics |
| Planar Systems |
| Daktronics |
| LG Electronics |
| Unilumin |
| NanoLumens |
| Leyard |
| Others |
Cost & Logistics Intelligence
Captive in-house production of driver ICs and TCON architectures anchors Samsung Electronics' premium panel pricing power while compressing margins for outsourced competitors dependent on Taiwan and South Korea foundry capacity. This integration choice simultaneously secures supply continuity during equipment backlogs and enables three-tier pricing structure across premium, standard, and economy levels based on semiconductor content and optical bonding complexity.
Pricing Analysis
Warranty and luminance-stability guarantees bundled into hardware-as-a-service contracts for North American quick-service restaurant chains are displacing transactional capital purchases. Price differentiation rests on certification grade for FAA and EASA airworthiness tiers versus consumer electronics FCC authorization. Cost compression in automotive curved dashboard segments is intensifying because OEMs are consolidating procurement authority and demanding co-located engineering support. Quick-service restaurant chains exhibit highest price sensitivity; aviation and medical instrument buyers show lowest sensitivity due to validation timeline rigidity.
Supply Chain Analysis
Specialized mixed-signal semiconductor design talent concentrates in Taiwan and South Korea, constraining new entrant fab ramp schedules and extending order backlogs for OLED deposition equipment. Geographic supply concentration centers on China for indium refining and polarizer lamination, South Korea for OLED deposition capacity, and Japan for liquid crystal and organic semiconductor chemical supply. Raw material dependencies draw from refined indium for ITO electrodes, gallium nitride microchips for MicroLED transfer, and polyimide substrates for flexible displays. Single-source vulnerability around Canon Tokki vapor deposition chamber supply creates 18-month equipment procurement risk. Distribution runs through Shenzhen-Guangzhou manufacturing clusters for ASEAN-bound commercial systems and Asan-Paju industrial complexes for premium OLED panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons construct a cost-of-compliance story that favors incumbent display manufacturers with validated CO2-based heat pump drying systems, erecting capital-intensive barriers against undercapitalized entrants.
For Market Incumbents: Acquire specialized driver IC design teams in Taiwan and South Korea to secure mixed-signal semiconductor expertise that constrains competitor fab ramps. Consolidate optical bonding and polarizer lamination capacity in European facilities ahead of 2027 F-Gas Regulation compliance deadlines to defend against emerging Chinese entrants with lower environmental compliance costs. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for component suppliers to establish display module finishing operations in Uttar Pradesh and Tamil Nadu, bypassing entrenched China-Korea supply concentration. Target transparent MicroLED retail installations in Dubai and Singapore where modular tile construction justifies manufacturing premiums and field replacement cost reduction drives procurement decisions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive tier-1 suppliers seeking captive display engineering capabilities for curved instrument cluster development. Long-term viability favors manufacturers with backward integration into driver IC supply and validated F-Gas-compliant process equipment. The signal to watch is Canon Tokki equipment backlog duration as an inflection indicator for OLED fab expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Design | Samsung Electronics leverages in-house semiconductor production to dominate premium panel supply chains. |
| CO2-Based Heat Pump Drying Validation | Stuttgart and Munich OEMs accelerate pilot lines for EU F-Gas Regulation compliance ahead of deadlines. |
| Co-Location of Engineering Teams | German and Japanese automotive OEMs compress development cycles through proximity to vehicle assembly plants. |
| Modular MicroLED Tile Assembly Scale-Up | Transparent retail installations in Dubai and Singapore reduce field replacement costs through tile-based construction. |
| Hardware-as-a-Service Subscription Launch | North American quick-service restaurant chains displace capital purchases with bundled content contracts. |
Research Approach
Independent corroboration across procurement executives at automotive tier-1 suppliers, display manufacturing plant managers in Shenzhen and Guangzhou, and regulatory affairs specialists at MIIT and ECHA underwrites the qualitative findings. Primary interviews with OLED deposition equipment specialists, polarizer lamination process engineers, and aviation certification consultants combined with secondary validation from SEC filings, MIIT energy efficiency certification databases, and customs trade data for indium and gallium nitride substrates. Bottom-up panel shipment aggregation and top-down electronics industry value chain triangulation cross-validate volume estimates.
Rate-of-change decomposition across display technology substitution curves, automotive content-per-vehicle expansion, and regional manufacturing cluster growth drives the analytical framework. Segmentation dimensions modeled include display technology type, application vertical, end-user industry, and product form factor across the projection horizon. CAGRs derive from fitted adoption curves for OLED versus LCD penetration, with specific inputs from aviation certification timeline constraints and REACH chemical reformulation schedules.
The model assumes a particular technology adoption path; alternative pathways for MicroLED modular assembly would alter the outlook if manufacturing premiums compress faster than projected. Forecasts reflect assumptions around Canon Tokki equipment availability, indium export quota stability, and F-Gas Regulation enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Video Wall Display Market
Display Technologies
Screenless Display Market
Display Technologies
Wireless Display Market
Display Technologies
Display Material Market
Display Technologies
Middle East and Africa Industrial Display Market
Display Technologies
Seven Segment Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
North America Industrial Display Market
Display Technologies
3D Display Market
Display Technologies
Global Magic Wall Interactive Surface Market
Display Technologies
Polarizing Film for Displays Market
Display Technologies
Projector Screen Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Multi-Touch Screen Market
Display Technologies
Touch Screen Module Market