
 Ultra High Definition (UHD) Panel (4K) Market | 2026-2036
Ultra High Definition (UHD) Panel (4K) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Definition (UHD) Panel (4K) Market Analytics
Project finance tied to Gen 8.6 OLED lines is rewriting competitive entry barriers, allowing foundry-style operators to scale without full balance-sheet ownership of glass-melting assets. Samsung Display Co., Ltd. leverages its captive quantum-dot inkjet deposition to sustain margins in premium QLED tiers. BOE Technology Group Co., Ltd. anchors massive government-backed capacity in Hefei and Wuhan, dominating domestic procurement for commercial display panels. LG Display Co., Ltd. competes through white-OLED specialization in large-format home theater segments.
An Ultra High Definition (UHD) Panel (4K) is a flat-panel display device comprising at least 3840 by 2160 pixels, manufactured through photolithographic patterning of thin-film transistors on glass substrates with color filters aligned per subpixel. It renders four times the pixel density of Full HD, enabling immersive home theater, precision medical imaging, and broadcast monitoring applications where fine detail preservation matters. LED backlighting retains volume leadership across residential and retail end users due to cost-engineered supply chains in China and Taiwan, while OLED commands margin pools in premium home theater and commercial display segments where contrast ratio drives specification. MicroLED remains pre-commercial for most applications but attracts R&D concentration from gaming monitor developers seeking sub-millisecond response without burn-in risk.
FCC equipment authorization rules in the United States mandate electromagnetic compatibility testing for all UHD panels, shaping design cycles and certification costs for brands exporting into North America. Ecodesign requirements under the EU Green Deal restrict standby power for displays above 50 inches, pushing manufacturers toward integrated power-management ASICs and ambient light sensors. China's GB standards on display energy efficiency, enforced by SAMR, create tiered market access where premium efficiency ratings unlock government procurement channels. Stakeholders must monitor how evolving HDR certification regimes from content platforms interact with hardware brightness specifications to determine which technology roadmaps retain specification relevance.
Market Dynamics
Gen 8.6 OLED project finance is concentrating capital requirements among foundry-style operators, decoupling display manufacturing from glass-melting asset ownership and compressing entry barriers for fabless panel designers.
Growth Catalysts
- Streaming platform mandates:Live sports broadcasters face deliverable requirements above 1080p, forcing 4K workflow upgrades across production chains.
- China's dual carbon goals:MEE enforcement pushes fabs toward low-temperature polysilicon processes that reduce energy intensity per substrate processed.
- Medical imaging precision:Radiology departments specify UHD panels for diagnostic workstations where pixel-level detail preservation affects clinical outcomes.
Market Restraints
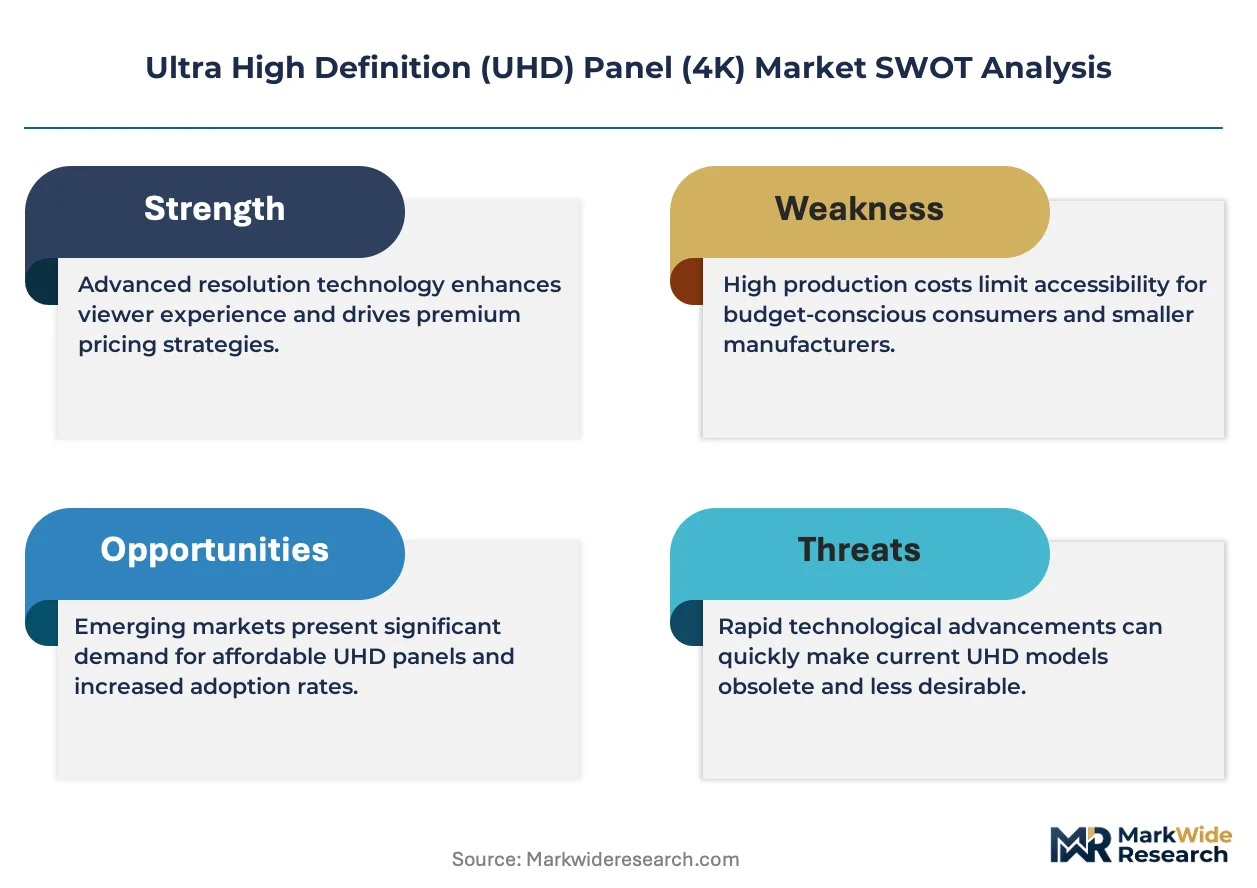
- Input cost volatility:Indium tin oxide prices fluctuate with rare earth export quotas, squeezing margin stability for sputtering-dependent manufacturers.
- Supply concentration risk:Driver IC fabrication clusters in Taiwan create single-geography vulnerability for timing controller procurement.
- Technical limitation:OLED burn-in susceptibility restricts deployment in always-on commercial signage applications despite superior contrast ratios.
Strategic Opportunities
- Underpenetrated medical vertical:Surgical navigation systems in India remain largely HD-specified, creating upgrade runway as hospital infrastructure modernizes.
- Regulatory tailwind:EU Green Deal ecodesign requirements for standby power push integrated power-management ASIC adoption, favoring suppliers with ambient light sensor integration.
- Technology convergence:Quantum-dot enhancement layers combined with mini-LED backlights enable premium tier positioning without full OLED capex exposure.
Industry Challenges
- Capex intensity:Gen 8.5+ photolithography equipment requires depreciation cycles exceeding product generation lifespans, straining capital allocation discipline.
- Certification timeline friction:FCC electromagnetic compatibility testing for North American market entry extends design cycles by four to six months.
- Skill gap in deposition:Inkjet quantum-dot manufacturing lacks sufficient process engineers with combined fluid dynamics and semiconductor fabrication expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Definition (UHD) Panel (4K) Market |
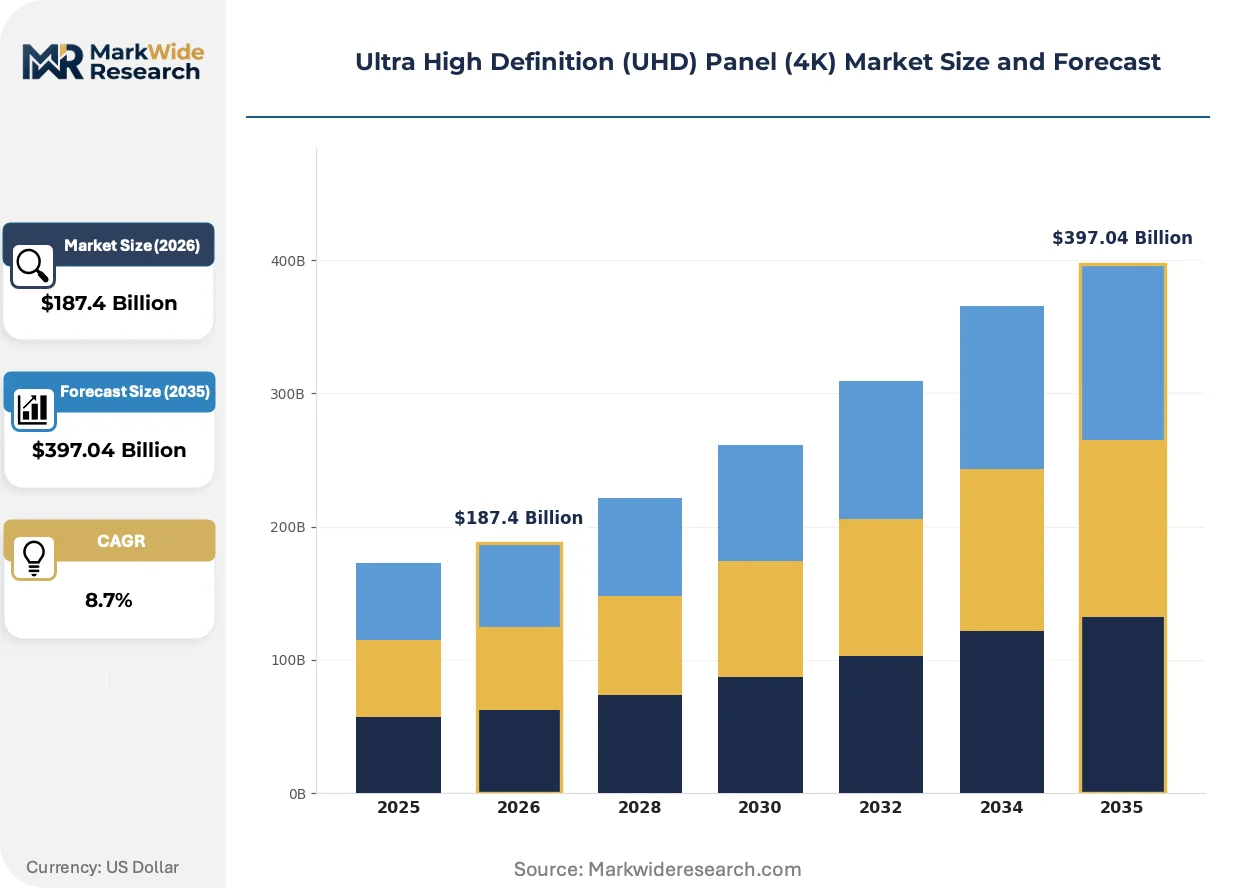
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, MicroLED Application: Home Theater, Commercial Display, Gaming, Broadcasting End User: Residential, Retail, Education, Healthcare Technology: Smart TV, Ultra Wide, HDR, 3D |
| Companies Covered | AU Optronics Corp. (AUO), Japan Display Inc., Samsung Display Co., Ltd., CSOT (China Star Optoelectronics Technology Co., Ltd.), Sharp Corporation, LG Display Co., Ltd., Innolux Corporation, TCL Technology, BOE Technology Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Definition (UHD) Panel (4K) Market Evolving Landscape
Display technology roadmaps are diverging between cost-optimized LED volumes and premium OLED margin pools, with micro-LED positioning for gaming monitor segments demanding sub-millisecond response.
Mini-LED backlighting arrays with thousands of dimming zones are migrating from professional broadcast monitors into high-end residential televisions. Post-production houses in Los Angeles and London adopted these first for HDR mastering workflows. Consumer electronics brands now source similar specifications for home theater lines, compressing the price gap against entry OLED tiers.
Ecodesign requirements under the EU Green Deal restrict standby power consumption for displays above 50 inches diagonal. Manufacturers respond with integrated power-management ASICs and ambient light sensors that dim panels in unoccupied rooms. Premium efficiency ratings unlock government procurement channels under China's GB standards enforced by SAMR, creating tiered market access.
Broadcasters now specify HDR certification compatibility as a procurement gate, not merely resolution. Content platforms including streaming services mandate specific brightness and color gamut performance for their "certified" hardware partnerships. This specification shift most visibly affects South Korea's display cluster, where Gen 8.5+ lines serve premium TV OEMs seeking platform approval badges.
Ultra High Definition (UHD) Panel (4K) Market Segmentation
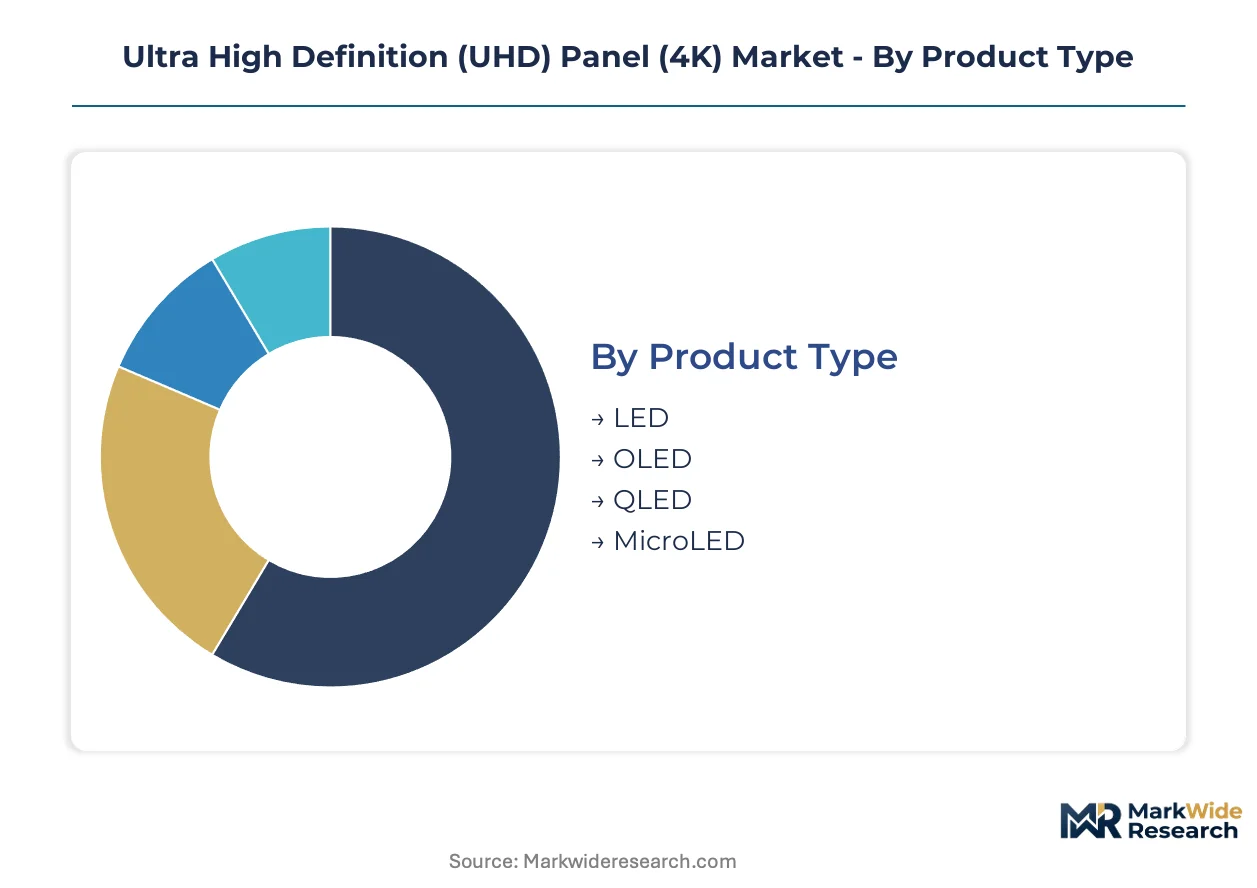
UHD panel purchasing decisions hinge on technology trade-offs between cost, contrast performance, and longevity. Manufacturers align production capacity across these dimensions to capture distinct margin pools in residential and commercial channels.
Product Type:
Cost tier differentiation separates volume leaders from premium positioning strategies.
- LED:Edge-lit and direct-lit configurations dominate residential installations where procurement budgets prioritize unit economics over contrast specifications. China's display fabs in Hefei and Wuhan supply cost-optimized backlights for retail channel volume.
- OLED:Self-emissive pixels enable infinite contrast ratios through individual subpixel control, commanding specification preference in South Korea's home theater segment where broadcasters mandate HDR mastering compatibility. White-OLED architectures from LG Display anchor large-format premium tiers despite burn-in susceptibility in always-on applications.
- QLED:Quantum-dot enhancement layers boost color gamut coverage without OLED's organic degradation risks.
- MicroLED:Inorganic III-V compound emitters deliver sub-millisecond response times for gaming monitor developers.
LED holds installed capacity. OLED is rotating up the share rankings.
Application:
End-use context determines brightness, durability, and connectivity requirements.
- Home Theater:Dark-room viewing prioritizes contrast ratio and black-level performance, driving specification toward OLED and mini-LED backlight arrays with thousands of dimming zones. Post-production houses in Los Angeles adopted these specifications first, compressing price gaps against entry OLED tiers in consumer channels.
- Commercial Display:Digital signage and corporate conferencing demand 16/7 or 24/7 operational durability where LED backlighting retains cost advantages. Burn-in risks restrict OLED deployment despite superior color performance.
- Gaming:Low input lag and high refresh rates dominate procurement criteria.
- Broadcasting:HDR certification compatibility functions as a procurement gate beyond raw resolution metrics.
Home Theater commands average selling price premiums. Gaming is expanding most quickly as monitor specifications converge with television performance tiers.
End User:
Customer type shapes volume scale and specification sensitivity.
- Residential:Individual consumers purchase through retail and e-commerce channels where 55-inch and 65-inch diagonal sizes concentrate demand. China's GB energy efficiency ratings influence purchasing decisions through tiered electricity cost visibility.
- Healthcare:Radiology departments specify UHD panels for diagnostic workstations where pixel-level detail preservation affects clinical outcomes. Procurement cycles extend 18-24 months with stringent calibration requirements.
- Retail:Digital signage networks prioritize brightness and reliability over color accuracy.
- Education:Classroom and auditorium installations balance budget constraints with durability needs.
Residential absorbs production volume. Healthcare offers steepest expansion trajectory as diagnostic imaging infrastructure modernizes.
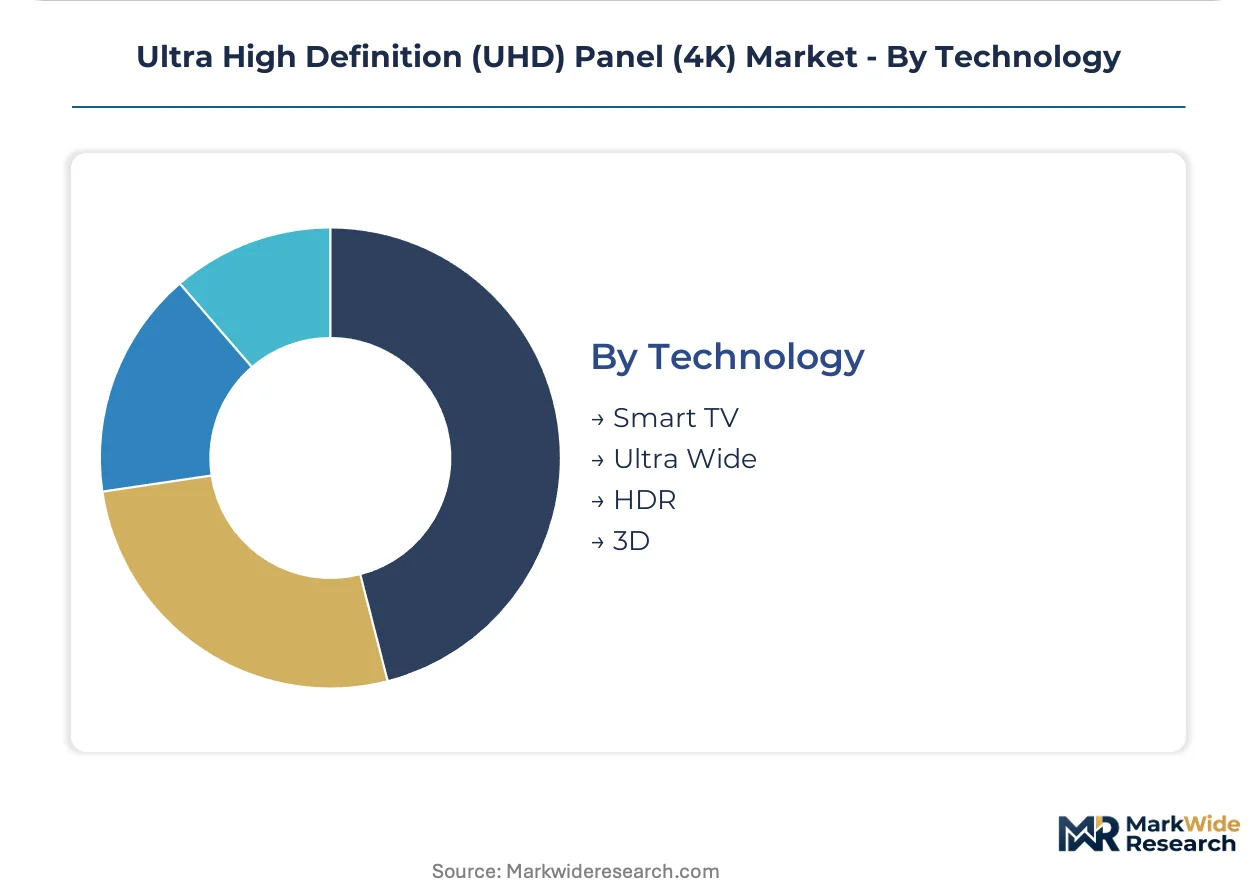
Technology:
Maturity stage differentiates proven deployments from emerging specification layers.
- Smart TV:Integrated operating systems and streaming application ecosystems now function as baseline expectations rather than premium features. FCC equipment authorization rules mandate electromagnetic compatibility testing for connectivity modules.
- HDR:High dynamic range certification from content platforms determines hardware brightness specifications. Streaming services mandate specific nit output and color gamut performance for certified hardware partnerships.
- Ultra Wide:21:9 aspect ratios address productivity and immersive gaming use cases.
- 3D:Autostereoscopic and glasses-dependent formats retain niche medical and industrial visualization applications.
Smart TV represents baseline configuration. HDR is climbing the fastest as content platform certification regimes harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in UHD panels reveal concentrated production in East Asian fabs against dispersed consumption across North American and European retail channels. South Korea and China run structural surpluses. The United States and Germany absorb inbound volumes for final assembly and brand distribution.
China
Domestic procurement for commercial display panels drives volume, with healthcare infrastructure modernization expanding diagnostic workstation specifications. SAMR enforces GB standards on display energy efficiency, creating tiered market access where premium ratings unlock government channels. Hefei and Wuhan anchor massive government-backed capacity serving both domestic OEMs and export assembly operations.
South Korea
Broadcasters mandate HDR mastering compatibility for home theater procurement, concentrating demand around Gumi and Paju display clusters. The national regulator enforces electromagnetic compatibility frameworks aligned with FCC equipment authorization benchmarks. Gen 8.5+ lines in these clusters supply premium TV OEMs seeking platform certification badges from streaming services.
United States
Post-production houses in Los Angeles adopted mini-LED specifications first, compressing price gaps against entry OLED tiers in adjacent consumer channels. FCC equipment authorization rules mandate electromagnetic compatibility testing, extending design cycles by four to six months for brands exporting into North America. Content platform certification regimes from streaming services now determine hardware brightness specifications for procurement.
Japan
METI industrial policy supports next-generation deposition process development for quantum-dot enhancement layers. Precision medical imaging applications specify UHD panels for diagnostic workstations where pixel-level detail preservation affects clinical outcomes. Display technology R&D concentrates in Kanto corridor facilities serving both domestic healthcare OEMs and export monitor brands.
Germany
EU Green Deal ecodesign requirements restrict standby power for displays above 50 inches, pushing manufacturers toward integrated power-management ASICs and ambient light sensors. Industrial automation and broadcast monitoring applications sustain procurement for high-refresh-rate panels. Bavaria-based systems integrators specify German-market panels for digital signage networks prioritizing 16/7 operational durability.
Ultra High Definition (UHD) Panel (4K) Market Competitive Landscape
On the supply side, the industry is consolidating around foundry-style operators that decouple display manufacturing from glass-melting asset ownership. Capital requirements concentrate among project finance vehicles backing Gen 8.6 OLED lines. Three archetypes dominate: captive quantum-dot specialists, government-backed volume fabricators, and white-OLED large-format specialists. Competitive moves center on strategic partnerships for deposition process licensing and capacity expansion through equipment lease structures rather than full balance-sheet ownership.
Among East Asian display specialists, Samsung Display Co., Ltd., BOE Technology Group Co., Ltd., and LG Display Co., Ltd. occupy positions across distinct technology vectors. Samsung Display Co., Ltd. exemplifies the captive materials archetype through quantum-dot inkjet deposition capabilities. BOE Technology Group Co., Ltd. represents government-backed scale fabrication with concentrated capacity in Hefei and Wuhan production complexes. LG Display Co., Ltd. anchors the white-OLED specialization tier for large-format home theater segments. These three fabricators collectively illustrate how technology roadmaps diverge between cost-optimized LED volumes and premium OLED margin pools.
| Leading Market Players |
|---|
| AU Optronics Corp. (AUO) |
| Japan Display Inc. |
| Samsung Display Co., Ltd. |
| CSOT (China Star Optoelectronics Technology Co., Ltd.) |
| Sharp Corporation |
| LG Display Co., Ltd. |
| Innolux Corporation |
| TCL Technology |
| BOE Technology Group Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Hefei and Wuhan production complexes anchor global LCD substrate capacity, concentrating glass-melting and photolithography assets under government-backed operators whose scale economics transmit downstream into tiered procurement leverage for OEM buyers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the UHD panel market. Premium tiers extract value through HDR certification badges from streaming platforms and quantum-dot enhancement layers, while standard configurations compete on per-unit economics for residential volume. Price differentiation hinges on certification grade and volume scale, with cost compression in entry OLED tiers intensifying as mini-LED backlights narrow specification gaps. Healthcare procurement committees exhibit lowest price sensitivity due to 18-24 month calibration cycles and diagnostic liability exposure.
Supply Chain Analysis
Indium tin oxide feedstock and driver IC wafer fabrication draw from concentrated upstream nodes in China, Taiwan, and South Korea. Rare earth export quotas from China's Ministry of Commerce create commodity price volatility for sputtering-dependent manufacturers, while Taiwan's timing controller clusters present single-geography vulnerability. Distribution runs through brand OEM assembly in Mexico and Eastern Europe for North American and EU final delivery, with foundry-style operators increasingly leasing Gen 8.6 equipment rather than owning glass-melting assets outright.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FCC electromagnetic compatibility certification and EU Green Deal ecodesign compliance creates switching costs that lock in incumbent specification relationships.
For Market Incumbents: Harden position through captive quantum-dot inkjet deposition capabilities that substitute technology threats from micro-LED developers seeking gaming monitor share. Expand backward integration into low-temperature polysilicon processes to meet China's MEE dual carbon enforcement while securing driver IC supply through equity stakes in Taiwanese foundry capacity.
For New Entrants and Emerging Players: Pursue surgical navigation system upgrades in Indian hospital infrastructure where diagnostic workstation specifications remain largely HD-tier and procurement modernization creates white-space runway. Target foundry-style service models that lease Gen 8.6 photolithography equipment rather than owning glass-melting assets, reducing capex barriers against BOE and CSOT scale positions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors deposition process specialists with combined fluid dynamics and semiconductor fabrication expertise as OLED burn-in limitations sustain premium tier relevance. Long-term viability rests on quantum-dot enhancement layer roadmaps converging with mini-LED backlights rather than full organic emitter transitions. Watch for HDR certification regime fragmentation across streaming platforms as the inflection signal determining which hardware specifications retain procurement gate status.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Dot Enhancement Layer Licensing | Samsung Display's captive inkjet deposition capabilities create technology transfer revenue from monitor OEMs seeking premium color gamut without OLED capex. |
| Gen 8.6 OLED Project Finance Vehicles | Foundry-style operators decouple display manufacturing from glass-melting ownership, compressing entry barriers for fabless panel designers. |
| Integrated Power-Management ASIC Development | Ambient light sensor integration meets EU Green Deal standby power restrictions for displays above 50 inches diagonal. |
| Low-Temperature Polysilicon Process Migration | China's MEE enforcement pushes fabs toward energy intensity reductions per substrate processed, unlocking government procurement channels under SAMR tiered ratings. |
| Medical Imaging Calibration Service Bundling | Radiology department procurement cycles extend 18-24 months with stringent requirements, creating recurring revenue attachment for diagnostic workstation suppliers. |
Research Methodology
Cross-validation between primary interviews with display fab process engineers, OEM procurement directors, and streaming platform hardware certification leads anchors the qualitative findings against secondary sources including FCC equipment authorization filings, SAMR GB standard enforcement notices, and EU Ecodesign Directive regulatory impact assessments. Bottom-up capacity modeling from Hefei, Wuhan, Gumi, and Paju production complexes triangulates against top-down demand segmentation from residential, healthcare, and broadcast end-use channels.
Calibration against historical pricing trajectories in LED and OLED technology transitions informs the analytical framework across the analysis window. Segmentation dimensions modeled include display technology type, application vertical, end-user category, and regional regulatory cluster. CAGRs derive from supply-demand balance assessments incorporating foundry-style capacity expansion timelines and streaming platform certification regime evolution. Forecast inputs include indium tin oxide price volatility indices and driver IC lead time fluctuations from Taiwanese fabrication clusters.
Macroeconomic conditions sit as an overlay; deviation in consumer electronics replacement cycles and healthcare capital expenditure budgets would shift the trajectory. Forecasts reflect documented assumptions around OLED burn-in mitigation progress and micro-LED cost reduction curves. Cross-checking against hyperscaler hardware partnership announcements and broadcaster HDR mastering procurement specifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Backlit Displays Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Global Display Panel Market
Display Technologies
Plasma Display Module Market
Display Technologies
Glass-Free HD 3D Display Market
Display Technologies
Flexible Screens Market
Display Technologies
Global Touchable Holographic Display Market
Display Technologies
North America Industrial Display Market
Display Technologies
Glasses Free 3D Display Market
Display Technologies
AMOLED Display Market
Display Technologies
Masks for Display Panel Market
Display Technologies
E-Paper Display Market
Display Technologies
Multi-Function Display Market
Display Technologies
Portable Video Wall Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Visual Computing Market