
 Display Port Market | 2026-2036
Display Port Market Size, Share, and Industry Trends Forecast 2026-2036
Display Port Market Analysis
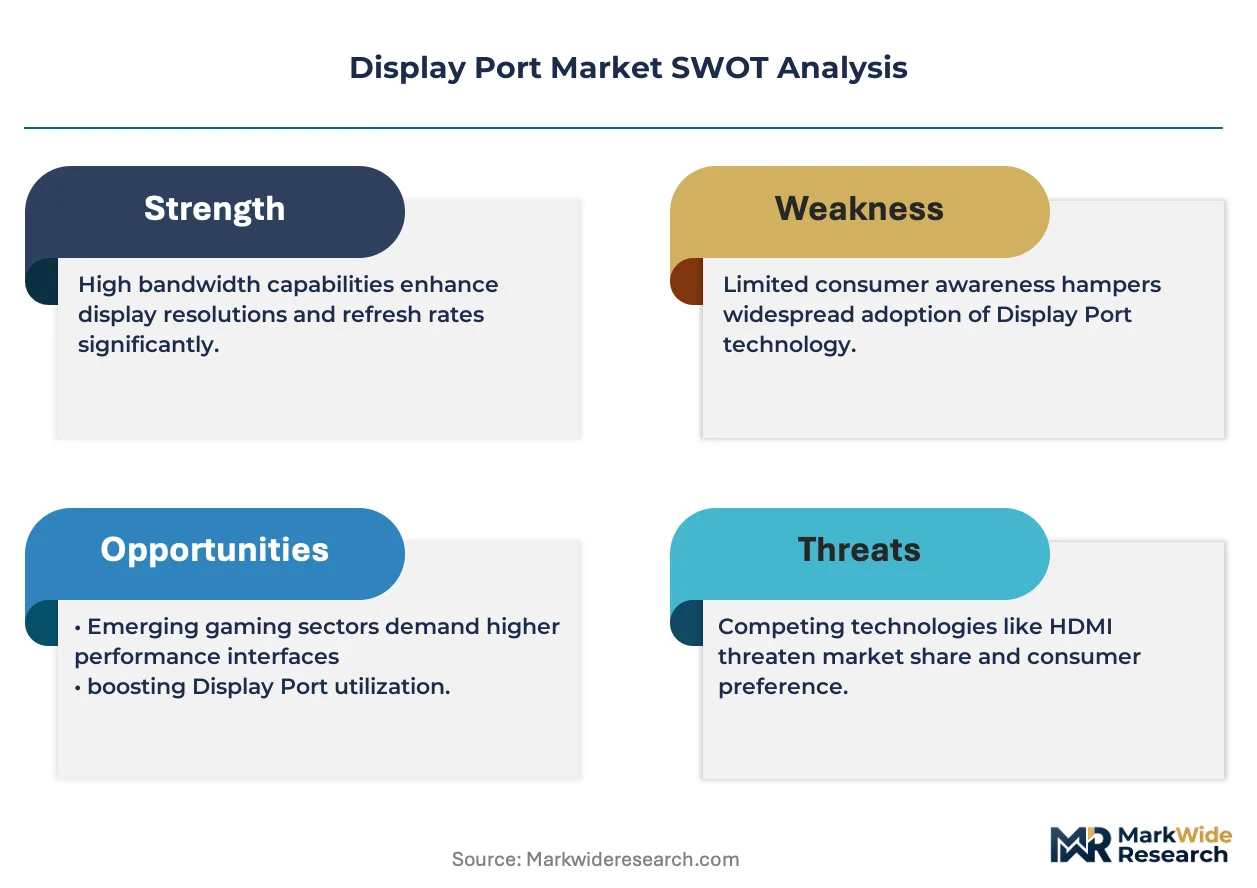
High Bit Rate 3 certification is unwinding legacy interface dependencies across premium monitor ecosystems. Intel Corporation leverages its integrated graphics architecture to sustain Display Port controller dominance in mainstream PC platforms. NVIDIA Corporation anchors high-end GPU output through dedicated Display Port 2.1 implementations. Parade Technologies specializes in signal conditioning ICs that extend physical layer performance at elevated data rates.
Display Port constitutes a digital display interface standard transmitting packetized video, audio, and auxiliary data over differential signaling pairs typically operating at 1.62 to 20 Gbps per lane depending on protocol revision. The specification employs embedded clocking and micro-packet architecture to eliminate dedicated timing channels, serving primary commercial purpose in driving high-resolution panels with minimal electromagnetic interference across compact device form factors. USB-C Display Port alternate mode captures expanding volume as laptop and tablet OEMs consolidate physical connectors, while Embedded Display Port maintains entrenched position in direct panel-to-processor links for thermal-constrained mobile designs. Optical Display Port variants address extended-reach medical imaging and digital signage backbones where copper attenuation limits cable runs.
VESA membership standards, FCC Part 15 emissions rules, and EU RoHS substance restrictions collectively shape interface hardware design cycles and market access preconditions for cable and semiconductor suppliers. The EU Green Deal circularity requirements are forcing modular connector designs with repairable assembly architectures. Stakeholders must monitor VESA's roadmap convergence with MIPI and HDMI specifications to anticipate protocol redundancy risks in next-generation display subsystems.
Market Dynamics
VESA's DisplayPort 2.1 specification rollout is compressing upgrade cycles across monitor OEM supply chains, forcing simultaneous retooling of signal conditioning silicon and cable assembly lines to support 80 Gbps aggregate bandwidth.
Growth Catalysts
- High-refresh-rate gaming:Console and PC manufacturers require DisplayPort 2.1 for 4K at 240Hz output, pulling premium panel demand through Shenzhen-Guangzhou manufacturing clusters.
- EU Green Deal circularity:Modular connector mandates accelerate repairable designs, extending hardware replacement intervals while preserving interface upgrade paths.
- USB-C convergence:Laptop OEMs consolidate physical ports through DisplayPort alternate mode, reducing BOM complexity and chassis cutout count.
Market Restraints
- Copper attenuation limits:Passive cable runs beyond three meters suffer signal degradation, forcing active retimer ICs that inflate per-unit cost.
- HDMI 2.1 substitution:Television and streaming device manufacturers default to HDMI for consumer-facing ports, capping DisplayPort penetration in living-room displays.
- MIPI DSI competition:Mobile and tablet designs bypass DisplayPort entirely for direct processor-to-panel links in thermal-constrained form factors.
Strategic Opportunities
- Optical DisplayPort variants:Medical imaging and digital signage backbones require extended-reach solutions where copper fails, opening specialized cable assembly markets.
- India PLI scheme:Electronics manufacturing incentives attract display module assembly, creating captive demand for Embedded DisplayPort controllers in Noida and Chennai corridors.
- FCC Part 15 relaxation:Shielding requirement adjustments for short internal cables reduce EMI compliance burden in compact device designs.
Industry Challenges
- High Bit Rate 3 certification backlog:VESA's testing queue delays product launches by 8-14 weeks, compressing revenue recognition windows.
- Signal integrity engineering scarcity:Fewer than two hundred engineers globally possess deep expertise in 20 Gbps per lane physical layer design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Port Market |
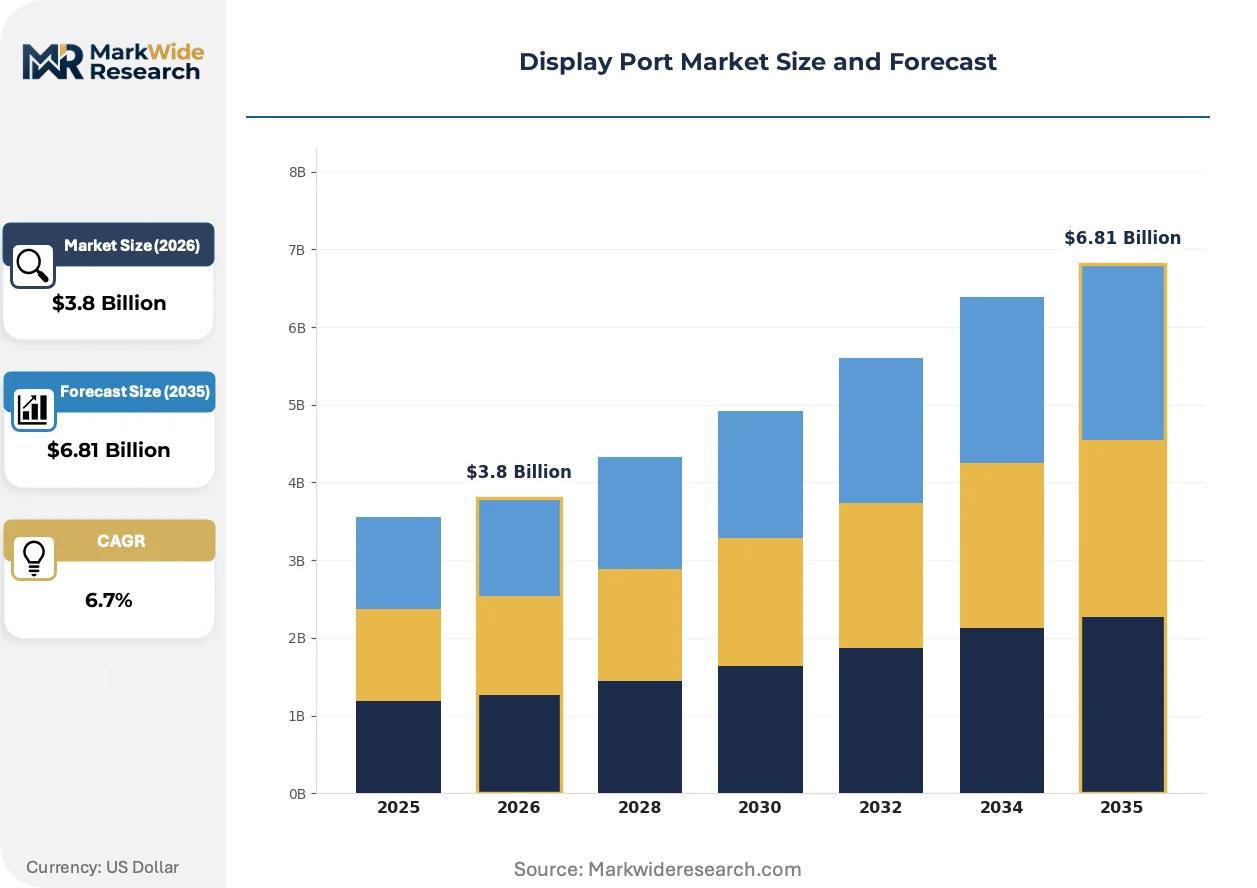
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Display Port, Mini Display Port, USB-C Display Port, Optical Display Port, Embedded Display Port Technology: Display Stream Compression, Multi-Stream Transport, Adaptive Sync, High Bit Rate 3, Forward Error Correction Application: Desktop Graphics, Gaming Consoles, Digital Signage, Medical Imaging, Virtual Reality Platforms End User: Consumer Electronics Manufacturers, Broadcast Equipment Producers, Design Studios, Simulation Centers, Research Facilities |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, NXP Semiconductors, STMicroelectronics, Parade Technologies, Analogix Semiconductor, Lattice Semiconductor, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Port Market Emerging Trajectories
Active optical cable technology is displacing copper in professional and medical applications, while regulatory pressure on repairability is reshaping connector mechanical design. Procurement patterns are compressing as monitor OEMs consolidate qualified supplier lists around vertically integrated signal conditioning vendors.
Multi-lane retimer integration is miniaturizing. Parade Technologies and Analogix now embed four full DisplayPort 2.1 lanes with equalization and redriver functions in sub-4mm² die footprints. Gaming monitor OEMs in Taiwan and South Korea are adopting these consolidated packages to reduce PCB layer count. This integration is miniaturizing signal conditioning subsystems from discrete multi-chip spreads to single-die solutions, collapsing board space requirements by sixty percent.
EU RoHS substance restrictions are tightening cadmium and lead exemptions for connector plating. Cable assemblers in Dongguan and Shenzhen must transition to palladium-nickel or pure tin finishes ahead of December 2025 deadlines. High-volume consumer monitor supply chains face the steepest compliance cost increases, with some Tier-2 assemblers exiting the DisplayPort cable market entirely.
Enterprise procurement of docking stations is consolidating around USB-C DisplayPort alternate mode as the single-cable standard. IT departments at financial services and healthcare organizations in the US and Germany are mandating universal dock compatibility across laptop fleets. This standardization is eroding proprietary docking connector ecosystems and redirecting volume through VESA-certified USB-C controller suppliers.
Display Port Market Segmentation
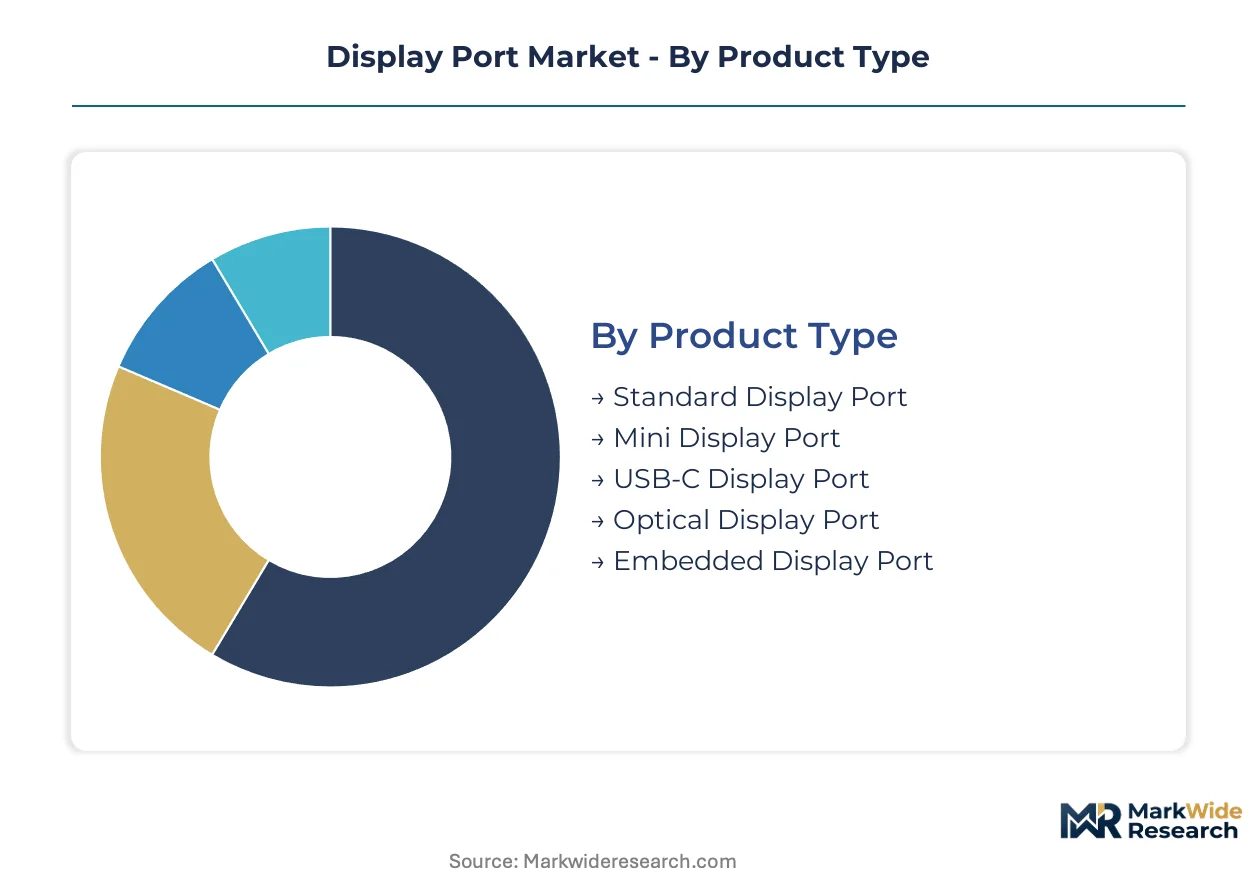
Display Port market segmentation reveals how interface variants compete against substitute technologies across different power, form factor, and bandwidth requirements. Each category exposes distinct vulnerability to HDMI 2.1, MIPI DSI, or proprietary alternatives depending on application constraints.
Product Type:
USB-C Display Port and Embedded Display Port face intensifying substitution pressure from MIPI DSI in mobile designs, while copper-based variants confront active optical cable displacement in extended-reach professional installations.
- Standard Display Port:Full-size connector delivering up to 80 Gbps aggregate bandwidth through four differential lane pairs. Gaming monitor OEMs in Taiwan and South Korea specify this variant for 4K 240Hz panels, though HDMI 2.1 substitution limits living-room display penetration.
- USB-C Display Port:Alternate mode repurposing USB-C physical layer for video transmission, consolidating power delivery and data on one connector. Laptop OEMs across Shenzhen-Guangzhou manufacturing clusters are standardizing on this variant to reduce chassis cutout count and BOM complexity.
- Mini Display Port:Compact 20-pin connector retaining full protocol compatibility in reduced footprint. Apple Computer and legacy notebook designs remain primary demand sources.
- Optical Display Port:Fiber-optic physical layer eliminating copper attenuation for medical imaging suites and digital signage backbones requiring runs beyond 50 meters.
- Embedded Display Port:Direct panel-to-processor interface without external connector, dominating thermal-constrained tablet and ultrabook designs where MIPI DSI competition is fiercest.
Embedded Display Port anchors the volume base while USB-C Display Port gains share at the steepest rate.
Technology:
Cost tier stratification separates premium implementations with full feature enablement from economy configurations stripping optional capabilities for price-sensitive monitor segments.
- High Bit Rate 3:Physical layer revision pushing 20 Gbps per lane, enabling 80 Gbps aggregate throughput for uncompressed 8K 60Hz or 4K 240Hz output. VESA certification queues currently extend 8-14 weeks, compressing product launch windows for monitor OEMs.
- Display Stream Compression:Visually lossless compression algorithm reducing bandwidth requirements by up to 3:1 without perceptible quality degradation. High-refresh-rate gaming panels leverage DSC to achieve 4K 240Hz within existing cable infrastructure.
- Multi-Stream Transport:Packet multiplexing enabling single Display Port connection to drive multiple independent displays. Enterprise docking station deployments specify MST for multi-monitor workstation configurations.
- Adaptive Sync:Variable refresh rate synchronization eliminating screen tearing without proprietary hardware. AMD FreeSync and NVIDIA G-Sync compatibility certification drives gaming monitor adoption.
- Forward Error Correction:Reed-Solomon coding protecting data integrity at elevated data rates where bit error probability rises. Critical for optical variant implementations.
High Bit Rate 3 anchors the volume base while Display Stream Compression expands most quickly as panel resolutions outpace cable bandwidth economics.
Application:
Customer type concentration varies sharply across segments, with enterprise procurement patterns diverging from consumer electronics volume cycles.
- Desktop Graphics:Discrete GPU output driving high-refresh-rate monitors for gaming and professional visualization. NVIDIA and AMD reference designs specify Display Port 2.1 as primary output, though HDMI 2.1 co-existence dilutes interface exclusivity.
- Gaming Consoles:Sony PlayStation and Microsoft Xbox manufacturers are expanding Display Port adoption for VR headset tethering and high-refresh-rate output, pulling premium panel demand through manufacturing clusters.
- Digital Signage:Commercial display networks requiring extended cable runs and 24/7 reliability. Optical variants capture share as copper attenuation limits constrain traditional installations.
- Medical Imaging:Diagnostic display systems demanding color accuracy and signal integrity over extended distances. FDA 510(k) clearance requirements favor proven interface standards with established validation protocols.
- Virtual Reality Platforms:Head-mounted displays requiring high bandwidth, low latency, and minimal motion-to-photon delay. Meta and HTC specifications are standardizing on Display Port for PC-tethered VR.
Desktop Graphics anchors the volume base while Virtual Reality Platforms climb the fastest as headset shipments accelerate.
End User:
Geographic concentration of qualified suppliers shapes procurement patterns, with Shenzhen-Guangzhou corridor dominance forcing tier-2 assemblers toward specialized niche segments.
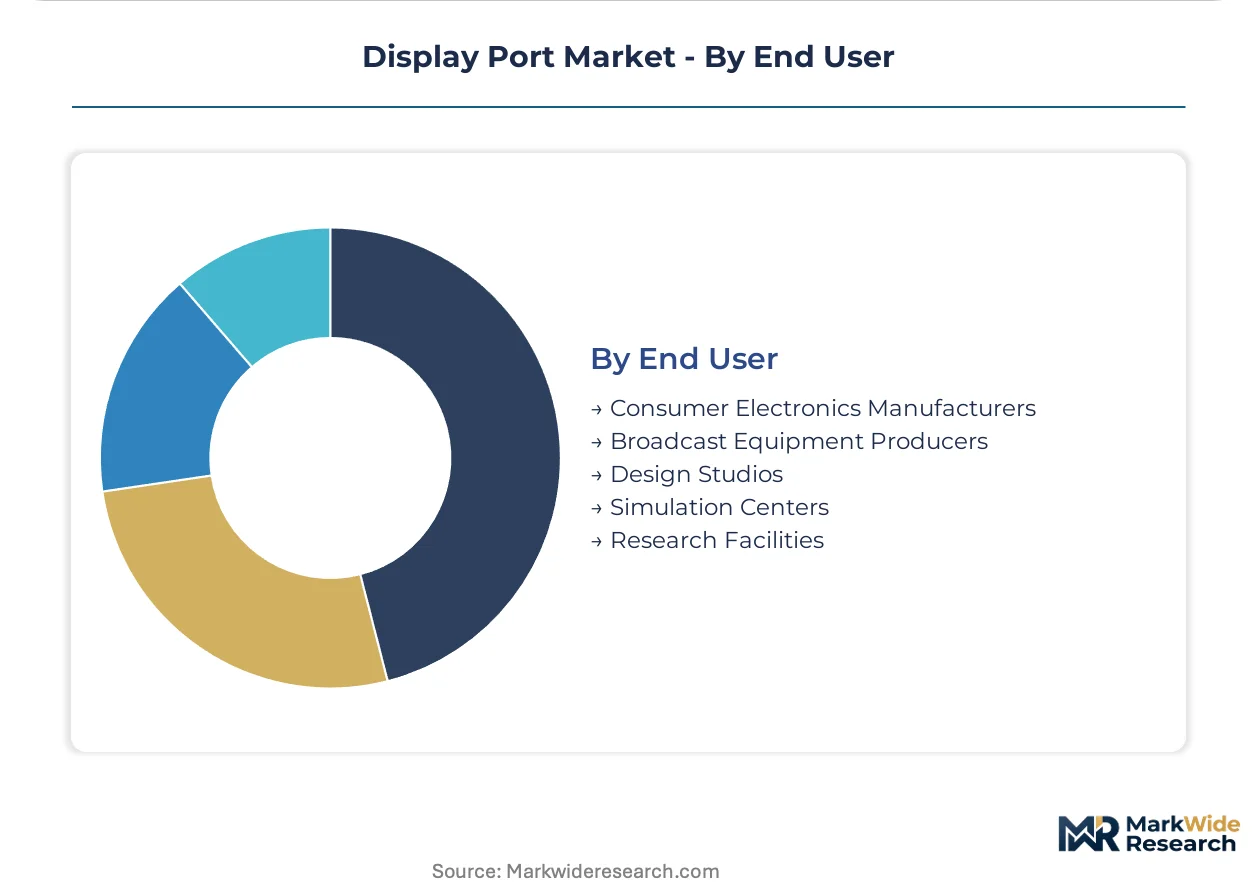
- Consumer Electronics Manufacturers:Monitor, laptop, and tablet OEMs specifying interface controllers in volume production. Dell, HP, and Lenovo procurement teams are consolidating qualified supplier lists around vertically integrated signal conditioning vendors.
- Broadcast Equipment Producers:Professional video infrastructure requiring genlock compatibility and reference-grade timing precision. Sony and Blackmagic Design integrate Display Port for monitoring and playout applications.
- Design Studios:Creative workstations demanding color-accurate 10-bit output for video editing and 3D rendering. Adobe Creative Cloud certification influences hardware procurement specifications.
- Simulation Centers:Military and commercial flight training systems requiring multi-channel synchronized output. Lockheed Martin and CAE specify Display Port for visual system integration.
- Research Facilities:Scientific visualization and data analysis installations. CERN and national laboratory procurement favor open standards with documented signal integrity specifications.
Consumer Electronics Manufacturers anchor the volume base while Research Facilities gain share at the steepest rate as visualization requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified DisplayPort controller and cable assembly suppliers cluster disproportionately in East Asian manufacturing corridors, with Shenzhen-Guangzhou electronics clusters processing the majority of global monitor OEM procurement. Regulatory divergence across major economies is fragmenting certification requirements and reshaping where final assembly occurs.
China
Domestic gaming monitor OEMs and laptop manufacturers in the Pearl River Delta drive High Bit Rate 3 controller demand for 4K 240Hz panels. MIIT enforces GB standards for electromagnetic compatibility in display interfaces, tightening shielding specifications for internal cable assemblies. Dongguan-based cable assemblers face RoHS transition deadlines for cadmium-free connector plating by December 2025.
United States
Enterprise IT procurement of USB-C docking stations concentrates demand among financial services and healthcare organizations in New York and Chicago metro areas. FCC Part 15 emissions rules govern shielding requirements for DisplayPort cables, with recent adjustments reducing compliance burden for short internal laptop cabling. Austin and San Jose host design centers for GPU and signal conditioning semiconductor development.
Germany
Industrial automation and medical imaging equipment manufacturers in Bavaria and Baden-Württemberg specify optical DisplayPort variants for extended-reach installations. EU Green Deal circularity mandates accelerate modular connector designs with repairable assembly architectures, forcing retooling of cable assembly lines. Stuttgart-area automotive display suppliers are qualifying Embedded DisplayPort for next-generation cockpit panels.
South Korea
Display panel manufacturers in Gyeonggi Province anchor global supply for high-refresh-rate gaming monitors requiring DisplayPort 2.1 output capability. MFDS medical device regulations influence diagnostic display certification protocols, favoring established interface standards with documented signal integrity. Samsung and LG procurement teams are consolidating qualified supplier lists around vertically integrated controller vendors.
India
Electronics manufacturing incentives under the PLI scheme attract display module assembly to Noida and Chennai corridors, creating captive demand for Embedded DisplayPort controllers in tablet and laptop production. BIS certification requirements for IT hardware are expanding to cover display interface components. Tamil Nadu-based EMS providers are building capability for monitor OEM subcontracting.
Display Port Market Vendor Landscape
Concentration sits with semiconductor vendors possessing integrated graphics or discrete GPU architectures that anchor DisplayPort controller specification in downstream OEM designs. The competitive structure fragments between GPU architects, signal conditioning specialists, and programmable logic providers. Two strategic archetypes dominate: vertically integrated platform vendors controlling reference design specifications, and fabless mixed-signal specialists delivering physical layer optimization. Competitive moves center on VESA certification queue positioning and multi-lane retimer integration to collapse board space requirements.
Among GPU and platform architects, Intel Corporation and NVIDIA Corporation anchor competitive positioning through reference design control in mainstream PC and high-end gaming segments respectively. Parade Technologies exemplifies the signal conditioning specialist archetype, occupying a position in physical layer performance extension at elevated data rates. These three entities represent the tiered competitive structure: platform vendors specifying interface requirements, and mixed-signal specialists executing physical layer implementation.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Advanced Micro Devices |
| NXP Semiconductors |
| STMicroelectronics |
| Parade Technologies |
| Analogix Semiconductor |
| Lattice Semiconductor |
| Texas Instruments |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Shenzhen-Guangzhou cable assemblers and Taiwan-based retimer IC suppliers lock in both supply access and price visibility for DisplayPort 2.1 controller volumes, insulating tier-1 monitor OEMs from spot-market volatility in signal conditioning silicon.
Pricing Analysis
EU RoHS substance restrictions dictate the pricing tier structure across connector plating finishes, with palladium-nickel certifications commanding premium positioning over pure tin alternatives. Three-tier pricing structure across premium, standard, and economy levels separates VESA-certified active optical cables from uncertified copper assemblies and generic panel-link components. Cost compression in economy-tier copper cable runs is intensifying because Dongguan assemblers face December 2025 cadmium-free transition deadlines. Consumer monitor OEMs exhibit highest price sensitivity, while medical imaging integrators accept substantial premiums for FDA-validated optical variants.
Supply Chain Analysis
Port congestion along Shenzhen-Hong Kong trade lanes elevates inbound logistics costs for retimer IC shipments originating from Taiwan and South Korea foundries. Controller silicon concentrates in Taiwan, South Korea, and the United States, while cable assembly feeds from China, Vietnam, and India. Raw material dependencies span gallium arsenide substrates, palladium-nickel plating chemistries, and fluoropolymer fiber cladding. Single-source vulnerability sits with TSMC advanced-node capacity for multi-lane retimer dice. Distribution runs through vertically integrated OEM procurement teams consolidating qualified supplier lists around Parade Technologies and Analogix.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The DisplayPort market is recovering from cyclical compression as gaming console refresh cycles and monitor panel upgrade supercycles converge, with VESA certification backlogs now clearing after pandemic-era testing queue accumulation.
For Market Incumbents: Fortify VESA certification queue positioning through dedicated testing lane reservations, compressing 8-14 week backlog windows for High Bit Rate 3 product launches. Deepen backward integration into retimer IC design to capture the sixty percent board-space reduction from multi-lane consolidation. Signal conditioning expertise scarcity represents the core threat; anchor procurement teams in Shenzhen-Guangzhou with captive engineering talent pools. For New Entrants and Emerging Players: VESA certification fast-track partnerships with existing queue holders offer the most viable entry vector for fabless mixed-signal specialists. Optical DisplayPort variants for medical imaging and digital signage backbones present the most penetrable white-space, with copper attenuation limits creating natural demand displacement. Target India's Noida-Chennai corridor through PLI-linked display module assembly relationships, embedding Embedded DisplayPort controllers in tablet and laptop subcontracting flows. For Investors and Strategic Acquirers: Fabless physical-layer specialists with proven 20 Gbps per lane design teams represent the priority acquisition archetype, with fewer than two hundred engineers globally possessing requisite signal integrity expertise. Long-term viability hinges on interface standard persistence against MIPI DSI and HDMI 2.1 substitution pressure across the next decade. Watch VESA roadmap convergence announcements with MIPI and HDMI specifications as the critical inflection signal for protocol redundancy risk assessment.| Strategic Initiative | Industry Significance |
|---|---|
| VESA Certification Fast-Track Investment | Testing queue positioning compresses product launch windows for monitor OEMs competing on 4K 240Hz panel timing. |
| Multi-Lane Retimer Integration | Single-die consolidation from Parade Technologies and Analogix collapses PCB layer count requirements by sixty percent. |
| Optical Variant Development | Fiber-optic physical layers capture medical imaging and digital signage demand where copper attenuation constrains cable runs. |
| India PLI Scheme Participation | Noida and Chennai corridor incentives create captive demand for Embedded DisplayPort controllers in laptop assembly. |
| EU Green Deal Compliance Retooling | Modular connector designs with repairable assembly architectures satisfy circularity mandates while preserving upgrade paths. |
Methodological Framework
Cross-validation between semiconductor foundry shipment disclosures and monitor OEM procurement data anchors the qualitative findings in measurable supply-side activity. Primary interviews with VESA certification engineers, GPU platform architects, cable assembly procurement leads, and signal conditioning IC design directors combined with secondary validation from SEC semiconductor filings, MIIT GB standard publications, and EU RoHS exemption registry updates. Bottom-up bill-of-materials aggregation across DisplayPort controller, retimer, and cable assembly tiers triangulates against top-down gaming monitor and laptop shipment forecasts.
Sensitivity analysis on retimer IC yield assumptions and VESA certification throughput rates frames the forecast confidence intervals across the projection horizon. Segmentation dimensions modeled include product type, physical layer revision, application vertical, and end-user procurement archetype, with regional manufacturing cluster concentration as an industry-specific overlay. CAGRs derive from panel resolution upgrade elasticities and interface substitution probability matrices. Gaming refresh-rate specifications and USB-C alternate mode adoption curves serve as primary demand-side inputs.
Decision-makers should treat outputs as directional under stable VESA standard continuity and intact Shenzhen-Guangzhou manufacturing corridor access assumptions; material deviation in either would warrant model refresh. Optical variant cost-down trajectories and MIPI DSI penetration in thermal-constrained tablets represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
AMOLED Display Market
Display Technologies
Head-Mounted Display Market
Display Technologies
Quantum Dot Display Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Electroluminescent Display Market
Display Technologies
Touch Screen Film Market
Display Technologies
Global OLED Market
Display Technologies
Global Smartphone Display Panel Market
Display Technologies
North America Computer Monitor Market
Display Technologies
Low Power Display Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Global LED Digital Signage Market
Display Technologies
Collaboration Display Market
Display Technologies
Wireless Display Market
Display Technologies
Cathode Ray Tube Display Market
Display Technologies
Gaming Monitors Market