
 Global Cell and Gene Therapy Thawing Equipment Market | 2026-2036
Global Cell and Gene Therapy Thawing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell and Gene Therapy Thawing Equipment Market Foresight
Multi-source procurement for precision thermal control components is realigning supply strategies across cell therapy equipment vendors. Thermo Fisher Scientific leverages its life sciences distribution network to sustain instrument service contracts across North American biomanufacturing clusters. Cytiva anchors its position through integrated workflow solutions that span cryopreservation through thawing. Sartorius AG competes on modular platform architectures that accommodate varying batch sizes in contract development settings.
Cell and gene therapy thawing equipment comprises engineered thermal transfer systems designed to recover cryopreserved biological materials from ultra-low temperatures through controlled warming profiles, typically operating within precision ranges of 37°C to 45°C with ramp rates measured in degrees per minute to preserve cell viability. These systems serve the critical manufacturing step between cryogenic storage and therapeutic administration or downstream processing. Dry heat machines currently occupy the premium tier of product type segmentation due to their contamination risk profile and compatibility with closed-system manufacturing requirements. Automated thawing solutions represent the fastest-expanding technology category as pharmaceutical companies seek to reduce operator variability and embed process analytical technology into release workflows.
The FDA's current Good Manufacturing Practice expectations for cell therapy products, coupled with EMA's Advanced Therapy Medicinal Products framework, establish validation thresholds that filter out non-compliant equipment vendors. ISO 20387 biobanking standards and regional pharmacopeial chapters on cell processing further constrain acceptable thermal recovery protocols. Stakeholders must monitor how emerging programmable thawing devices integrate with distributed manufacturing models and point-of-care preparation workflows.
Market Dynamics
The transition from manual water-bath thawing to automated dry-heat systems is compressing vendor margins while elevating technical barriers to market entry. Pharmaceutical manufacturers now mandate programmable thermal profiles and integrated data logging as baseline procurement requirements.
Growth Catalysts
- FDA Cell Therapy Manufacturing Guidance:The agency's emphasis on closed-system processing and process analytical technology validation drives biopharma firms toward automated thawing platforms with embedded compliance documentation.
- CAR-T Manufacturing Scale-Up:Commercial cell therapy production facilities in the United States, Germany, and Japan are installing high-throughput thawing stations to match batch sizes exceeding 10 billion cells per lot.
- Cryopreservation Media Advances:Dimethyl sulfoxide-free formulations compatible with rapid thawing protocols expand the addressable market for precision thermal recovery equipment in stem cell banking.
Market Restraints
- Precision Component Supply Concentration:Peltier elements and platinum resistance temperature detectors source predominantly from Chinese and Japanese suppliers, exposing equipment vendors to input cost volatility and extended lead times.
- Validation Burden:EMA's Advanced Therapy Medicinal Products framework requires extensive IQ/OQ/PQ documentation that extends sales cycles by 12-18 months for new equipment entrants.
- Water-Bath Substitute Persistence:Academic research centers and early-stage biotechs continue deploying low-cost circulating water baths for non-clinical applications, capping premium equipment penetration in price-sensitive segments.
Strategic Opportunities
- Point-of-Care Preparation Workflows:Decentralized cell therapy administration in hospital outpatient settings creates demand for portable, countertop thawing devices with simplified operator interfaces.
- India's Biomanufacturing Incentives:The country's PLI scheme for pharmaceuticals and CDSCO's streamlined medical device regulations attract thawing equipment vendors seeking manufacturing cost advantages.
- Blockchain-Enabled Cold Chain Integration:Convergence of thawing equipment with distributed ledger temperature monitoring addresses regulatory demands for immutable chain-of-custody records in commercial cell therapy distribution.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Equipment vendors struggle to hire specialists capable of bridging thermal engineering, cell biology, and regulatory documentation requirements.
- Legacy LIMS Integration Friction:Automated thawing systems must interface with diverse laboratory information management systems already deployed across contract manufacturing organizations, complicating implementation timelines.
- Patent Thicket Navigation:Proprietary thermal profile algorithms and closed-system cartridge designs generate licensing disputes between established players and emerging competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell and Gene Therapy Thawing Equipment Market |
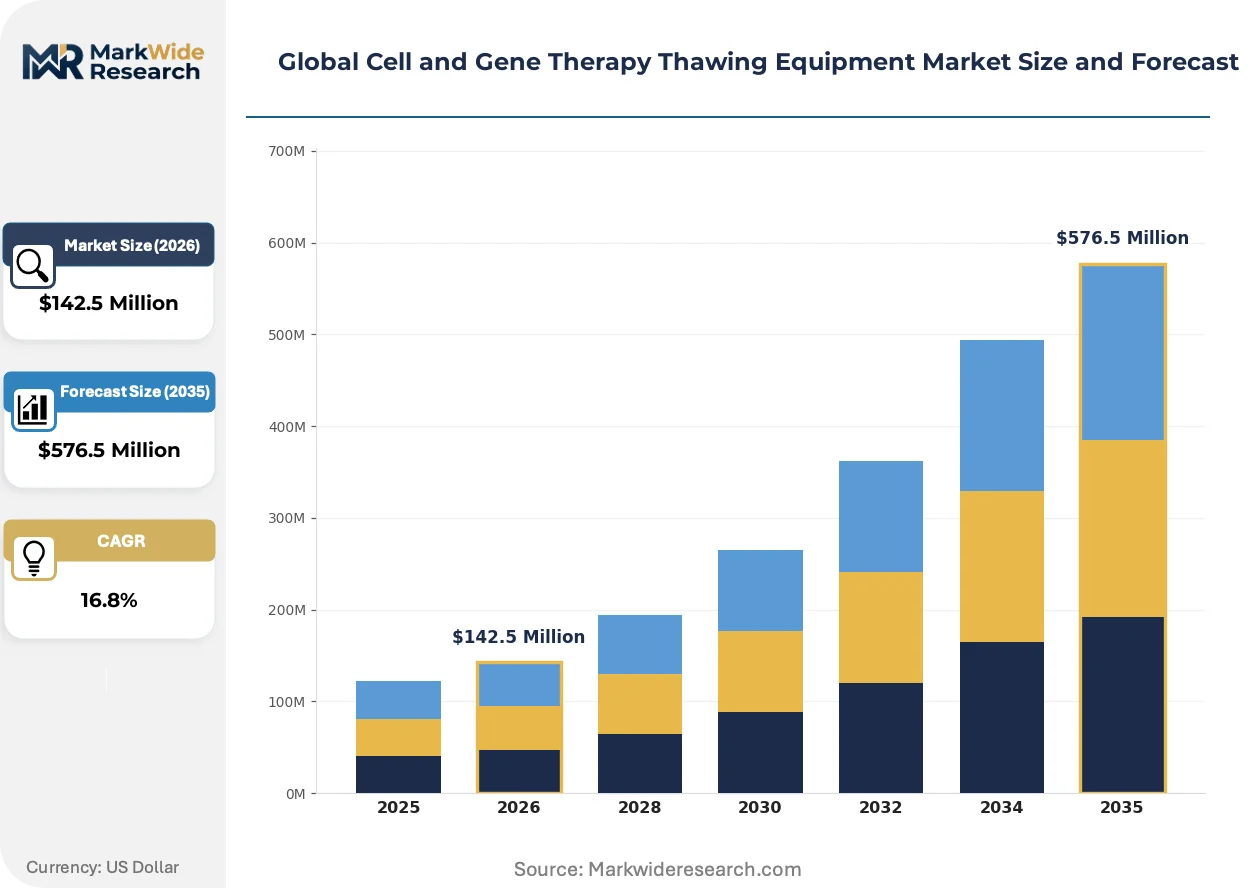
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $576.5 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Baths, Microwave Thawers, Dry Heat Machines, Cryogenic Containers End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Biotech Firms Application: Stem Cell Therapy, Oncology Treatments, Genetic Disorders, Tissue Engineering Technology: Rapid Thawing Systems, Automated Thawing Solutions, Manual Thawing Techniques, Programmable Thawing Devices |
| Companies Covered | Cytiva, Thermo Fisher Scientific, Helmer Scientific, Boekel Scientific, Sartorius AG, Eppendorf AG, BioLife Solutions, Cryoport Systems, SARSTEDT AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell and Gene Therapy Thawing Equipment Market Shifts & Advancements
Programmable thawing technology is displacing fixed-parameter equipment as cell therapy manufacturers pursue lot-to-lot reproducibility. Three developments are compressing the competitive landscape and redefining procurement criteria.
Radio-frequency thawing is consolidating technical interest among equipment developers seeking to eliminate conductive heat transfer limitations. This electromagnetic approach enables volumetric warming of cryopreserved cell suspensions without surface overheating. Large-scale gene therapy manufacturers in the United States are piloting these systems for viral vector thawing applications. The technology is consolidating competitive positioning around thermal uniformity metrics rather than ramp rate specifications alone.
EMA's Medical Device Regulation reclassification of automated thawing equipment as Class IIa devices intensifies conformity assessment requirements for vendors serving European markets. Manufacturers must now engage notified bodies for CE marking rather than self-certifying under previous directives. German and Swiss equipment suppliers are absorbing these compliance costs into premium pricing while repositioning service contracts as recurring revenue anchors.
Biopharma procurement teams are unbundling equipment purchases from mandatory service agreements, reversing historical vendor lock-in strategies. Contract development and manufacturing organizations now negotiate separate thermal qualification support and preventive maintenance contracts. This behavioral shift is most pronounced among mid-cap cell therapy sponsors in the Boston and San Diego bioclusters seeking operational flexibility across multiple equipment platforms.
Global Cell and Gene Therapy Thawing Equipment Market Segmentation
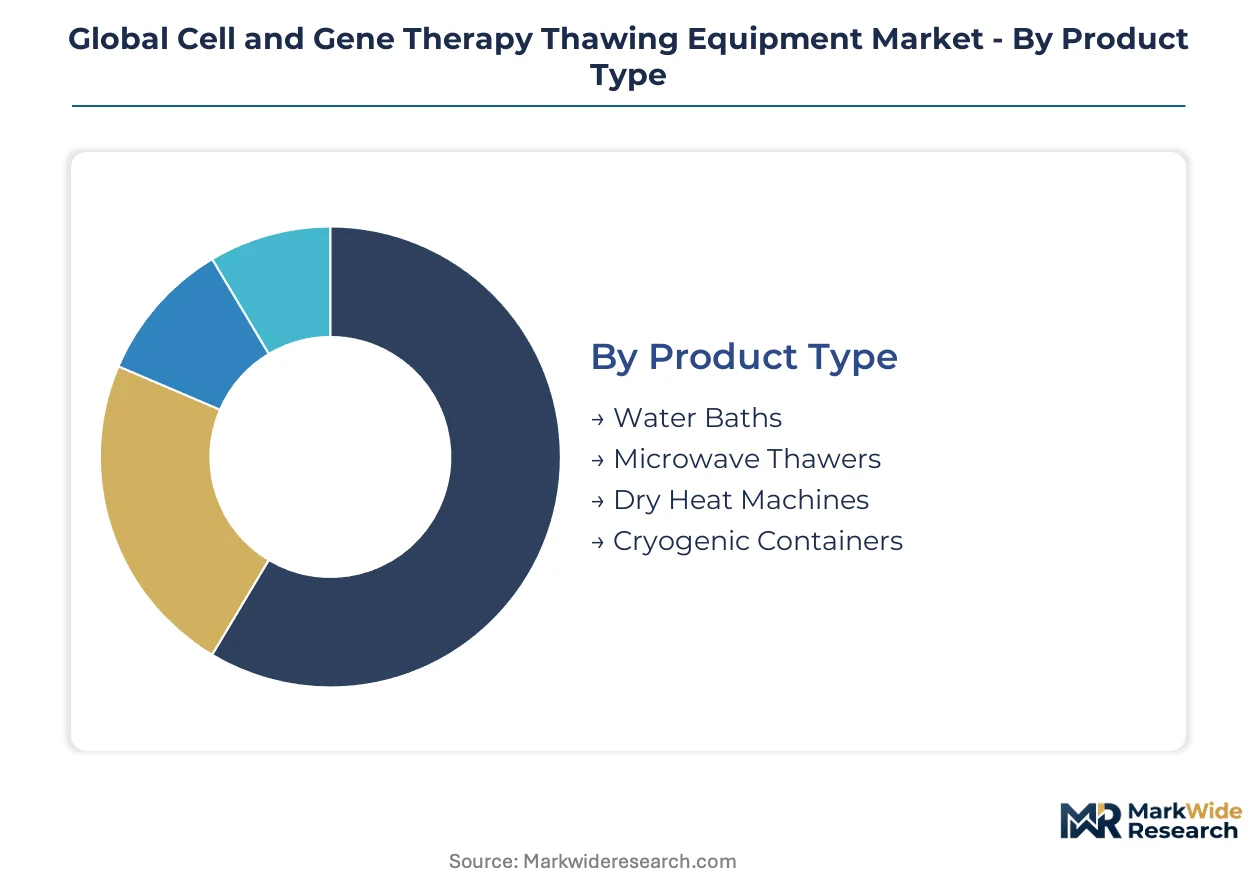
Segmentation in cell and gene therapy thawing equipment reveals divergent procurement logic across buyer types. Pharmaceutical manufacturers prioritize validated automation for commercial batches, while research settings tolerate manual methods for experimental flexibility.
Product Type:
Cost tier separates institutional buyers from budget-constrained laboratories in this category.
- Dry Heat Machines:These systems employ conductive heating elements and sealed chambers to eliminate water-borne contamination risks. Demand concentrates among United States pharmaceutical manufacturers scaling CAR-T production, driven by FDA guidance on closed-system processing and process analytical technology integration.
- Automated Thawing Solutions:Programmable thermal profile systems with embedded data logging and IQ/OQ/PQ documentation packages. German biotech clusters and Japanese gene therapy facilities are expanding procurement fastest, pressured by EMA Medical Device Regulation conformity requirements and PMDA quality management system mandates.
- Water Baths:Circulating temperature-controlled baths remain standard in academic research centers for non-clinical applications.
- Microwave Thawers:Electromagnetic warming systems offering rapid volumetric heat distribution for large-volume cryopreserved materials.
- Cryogenic Containers:Passive thermal mass vessels for transport and temporary holding of cryogenic specimens.
Volume sits with water baths in research settings; growth tilts toward dry heat machines.
End User:
Application maturity determines equipment sophistication requirements across customer types.
- Pharmaceutical Companies:Commercial-scale cell therapy manufacturers requiring batch records, audit trails, and thermal qualification documentation for regulatory submissions. These buyers in the United States and Germany are consolidating procurement around multi-unit thawing stations capable of processing 10 billion-cell batches.
- Biotech Firms:Venture-funded developers of novel modalities seeking modular platforms that accommodate varying batch sizes through contract manufacturing transitions. Boston and San Diego bioclusters are unbundling equipment purchases from service agreements to retain operational flexibility.
- Research Laboratories:Academic and government institutions prioritizing cost efficiency over validation depth for preclinical studies.
- Hospitals:Medical centers preparing point-of-care cell therapies in outpatient settings, creating demand for simplified countertop devices.
Procurement volume concentrates with pharmaceutical companies; biotech firms are expanding most quickly.
Application:
Regulatory pathway complexity shapes equipment specification intensity across therapeutic areas.
- Oncology Treatments:CAR-T and tumor-infiltrating lymphocyte therapies demanding precise thermal recovery to preserve effector cell function. Manufacturing facilities in the United States, Germany, and Japan are installing high-throughput thawing infrastructure to match commercial batch requirements.
- Stem Cell Therapy:Hematopoietic and mesenchymal stem cell applications where dimethyl sulfoxide-free cryopreservation media enable rapid thawing protocols. CDSCO's streamlined medical device regulations in India are attracting equipment vendors to serve emerging stem cell banking operations.
- Genetic Disorders:Gene therapy vector preparation and patient cell modification workflows.
- Tissue Engineering:Scaffold-based regenerative applications with specialized thermal recovery requirements for three-dimensional constructs.
Revenue concentrates in oncology treatments; stem cell therapy applications are gaining share fastest.
Technology:
Operator skill availability and documentation burden drive automation adoption curves.
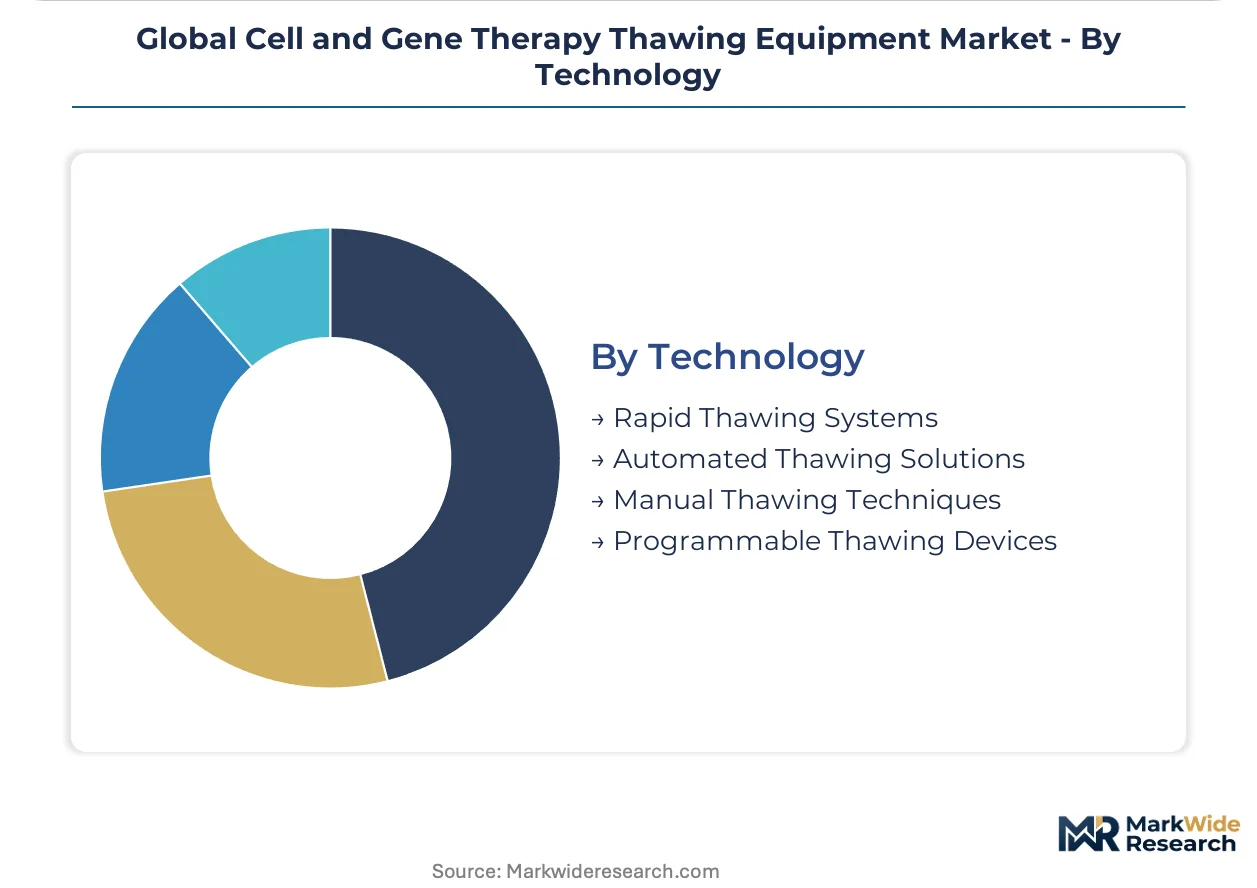
- Programmable Thawing Devices:Microprocessor-controlled systems enabling lot-to-lot reproducibility through stored thermal profiles and integrated process analytical technology. EMA's reclassification of automated thawing equipment as Class IIa medical devices is intensifying conformity assessment requirements for European market entry.
- Rapid Thawing Systems:Radio-frequency and electromagnetic approaches enabling volumetric warming without surface overheating. Large-scale gene therapy manufacturers in the United States are piloting these systems for viral vector applications, consolidating competitive positioning around thermal uniformity metrics.
- Automated Thawing Solutions:Robotic handling systems with barcode tracking and electronic batch record generation.
- Manual Thawing Techniques:Operator-dependent methods including hand-warming and uncontrolled water immersion, persisting in price-sensitive academic segments.
Installed base remains with manual techniques; programmable devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers in the United States, Germany, and Japan account for the majority of precision thawing equipment procurement, driven by commercial cell therapy manufacturing scale-up and regulatory mandates for closed-system processing.
United States
CAR-T production facilities in Massachusetts and California are installing multi-unit thawing stations capable of processing 10 billion-cell batches. FDA guidance on cell therapy manufacturing controls mandates process analytical technology validation, pushing biopharma firms toward automated platforms with embedded compliance documentation. The Boston and San Diego bioclusters are unbundling equipment purchases from service agreements to retain operational flexibility across contract manufacturing transitions.
Germany
German biotech clusters in Munich and Heidelberg are expanding procurement of programmable thermal profile systems fastest among European markets. EMA's Medical Device Regulation reclassification of automated thawing equipment as Class IIa devices intensifies conformity assessment requirements, with German and Swiss suppliers absorbing compliance costs into premium pricing. Bavarian equipment vendors are repositioning service contracts as recurring revenue anchors to offset regulatory overhead.
Japan
PMDA quality management system mandates are accelerating adoption of validated thawing infrastructure among gene therapy facilities in the Kanto region. Japanese pharmaceutical manufacturers prioritize thermal qualification documentation for regulatory submissions, favoring systems with integrated IQ/OQ/PQ packages. The Osaka-Kobe biomanufacturing corridor is consolidating procurement around vendors offering localized technical support and preventive maintenance networks.
India
Stem cell banking operations in Maharashtra and Gujarat are attracting thawing equipment vendors seeking manufacturing cost advantages under the PLI scheme for pharmaceuticals. CDSCO's streamlined medical device regulations reduce entry barriers for precision thermal recovery equipment in emerging cell therapy markets. Bangalore-based contract research organizations are piloting rapid thawing protocols compatible with dimethyl sulfoxide-free cryopreservation media formulations.
Switzerland
Swissmedic oversight of advanced therapy medicinal products establishes stringent validation thresholds that filter equipment vendors serving the Basel biopharma corridor. Gene therapy developers in the Lake Geneva region require programmable thawing devices with blockchain-enabled cold chain integration for immutable chain-of-custody records. Zurich-based precision engineering firms are supplying thermal control components to equipment manufacturers facing supply concentration risks in Asian markets.
Global Cell and Gene Therapy Thawing Equipment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors seek to bridge thermal engineering, cell biology, and regulatory documentation capabilities. The vendor base concentrates around three tiers: diversified life sciences conglomerates with integrated workflow solutions, modular platform specialists serving contract development settings, and precision component fabricators supplying Peltier elements and temperature detectors. Two competitive moves define current positioning: technology licensing agreements that accelerate programmable thawing device development, and geographic expansion into India's emerging biomanufacturing clusters under PLI scheme incentives.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Cytiva exemplify archetypes leveraging life sciences distribution networks and integrated cryopreservation-to-thawing workflows respectively. Sartorius AG occupies a position among modular platform specialists competing on architectures that accommodate varying batch sizes. These three entities represent distinct strategic postures: network-anchored service contract sustainability, workflow-integrated system bundling, and flexibility-optimized contract manufacturing accommodation.
| Leading Market Players |
|---|
| Cytiva |
| Thermo Fisher Scientific |
| Helmer Scientific |
| Boekel Scientific |
| Sartorius AG |
| Eppendorf AG |
| BioLife Solutions |
| Cryoport Systems |
| SARSTEDT AG & Co. KG |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up equipment specialists have consolidated mid-tier thawing system manufacturers across Germany and Switzerland, compressing supplier diversity while hardening pricing discipline through captive service contract bundling. This ownership concentration amplifies margin defense capabilities against Asian component cost volatility, yet simultaneously limits buyer negotiating leverage in multi-year validation support agreements.
Pricing Analysis
Volume concentrates in water-bath substitutes for academic laboratories, while margins accrue to programmable dry-heat systems serving commercial CAR-T manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated automation platforms from CE-marked clinical systems and research-grade manual equipment. Cost compression in the standard tier is intensifying because EMA Medical Device Regulation conformity assessments inflate vendor overhead. Academic research centers exhibit highest price sensitivity, whereas pharmaceutical manufacturers prioritize thermal qualification documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and Japan anchor hub-and-spoke patterns for precision thermal control components serving European and Asia-Pacific biomanufacturing clusters. Peltier elements and platinum resistance temperature detectors draw predominantly from Chinese and Japanese fabrication facilities, creating single-source vulnerability for equipment vendors dependent on just-in-time thermal sensor procurement. Distribution runs through authorized service partners rather than direct vendor-to-manufacturer channels, preserving technical qualification integrity while elongating lead times for spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell and gene therapy thawing equipment market operates as a cost-of-compliance story where EMA's Medical Device Regulation reclassification erects barrier-to-entry moats favoring incumbents with established notified body relationships and documented quality management systems.
For Market Incumbents: Extend service contract penetration through localized preventive maintenance networks in the Osaka-Kobe and Boston bioclusters, countering emerging modular platform specialists threatening account control. Deepen backward integration into thermal sensor calibration capabilities to reduce exposure to Chinese supply concentration. Prioritize blockchain-enabled cold chain integration development to defend premium positioning against radio-frequency thawing entrants. For New Entrants and Emerging Players: Enter via India's PLI scheme for pharmaceuticals, exploiting CDSCO's streamlined medical device regulations and Maharashtra stem cell banking demand for cost-optimized rapid thawing protocols. Target portable countertop devices for hospital outpatient point-of-care preparation workflows, where simplified operator interfaces and reduced validation documentation requirements lower competitive barriers. Pursue technology licensing partnerships with German precision engineering firms to accelerate programmable thermal profile algorithm development. For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed modular platform specialists with existing CE marking and localized technical support infrastructure in German-speaking markets. Long-term viability hinges on regulatory compliance durability rather than hardware innovation velocity, positioning validated IQ/OQ/PQ documentation capabilities as the scarcest asset class. Watch FDA draft guidance on distributed manufacturing models as the critical inflection signal for point-of-care device demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Class IIa Medical Device Certification | Notified body engagement separates compliant vendors from self-certified research equipment suppliers in European markets. |
| Blockchain-Enabled Cold Chain Integration | Immutable temperature records address Swissmedic chain-of-custody requirements for commercial gene therapy distribution. |
| Backward Integration into Thermal Sensors | In-house platinum resistance detector production insulates margin structure from Japanese component lead time volatility. |
| Point-of-Care Device Miniaturization | Countertop form factors unlock hospital outpatient settings beyond centralized manufacturing facility procurement. |
| Radio-Frequency Thawing Platform Development | Volumetric warming technology consolidates competitive positioning around thermal uniformity metrics for viral vector applications. |
Research Methodology
Document review covered FDA cell therapy manufacturing guidance, EMA Advanced Therapy Medicinal Products framework documentation, and ISO 20387 biobanking standards, complemented by interviews with bioprocess engineering directors, regulatory affairs specialists at thawing equipment vendors, contract manufacturing organization procurement managers, and thermal control component suppliers. Secondary validation drew from PMDA quality management system filings, CDSCO medical device registration databases, and Swissmedic advanced therapy oversight reports. Bottom-up equipment shipment data triangulated against top-down pharmaceutical manufacturing capacity expansion announcements across the analysis window.
Historical shipment patterns cross-referenced against expert panel input on programmable thawing device adoption curves shaped the analytical framework. Segmentation dimensions modeled include product type automation level, end-user regulatory pathway maturity, and application-specific thermal profile complexity. CAGRs were derived through iterative reconciliation of vendor revenue disclosures with facility installation tracking across the projection horizon. Cryopreservation media formulation advances and distributed manufacturing regulatory evolution served as industry-specific forecast sensitivity inputs.
Revisions become necessary when FDA guidance on closed-system processing materializes in final form, when Peltier element supply disruptions extend lead times beyond equipment vendor inventory buffers, or when blockchain cold chain standards achieve regulatory recognition. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Gene Therapy Products Market