
 Middle East and Africa Specialty Chemicals Market | 2026-2036
Middle East and Africa Specialty Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Specialty Chemicals Market Foresight
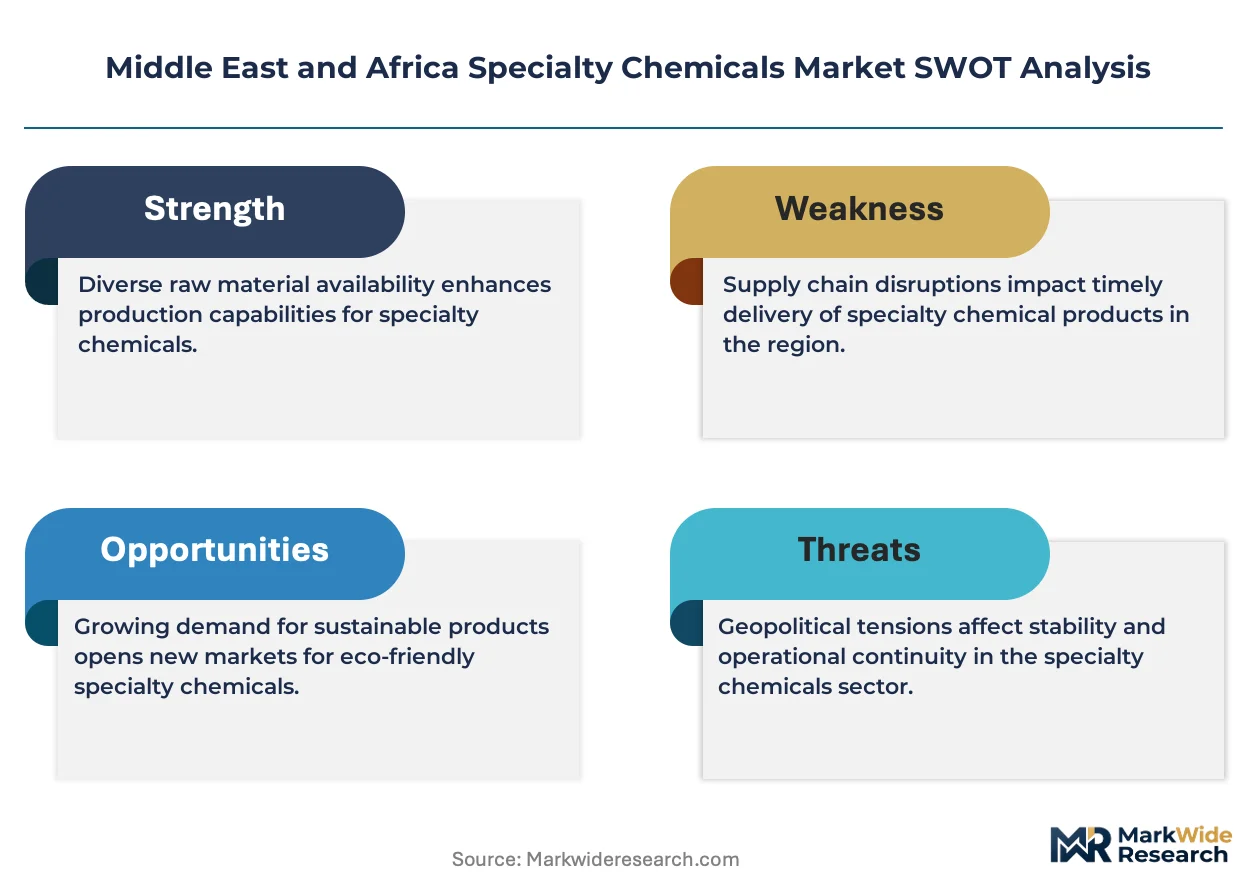
Petrochemical feedstock availability in Saudi Arabia is shifting downstream investment toward higher-margin specialty derivatives. SABIC leverages its integrated methane-to-chemicals complex to sustain captive supply of performance polymer intermediates. Sadara Chemical Company anchors the kingdom's specialty polyurethane and glycol ether output through its Jubail facility. Clariant AG competes on catalyst and additive technology leadership for regional refinery and plastics customers.
Middle East and Africa specialty chemicals comprise formulated products and performance materials engineered at molecular level to deliver specific functional effects—typically active at concentrations below five percent by weight in end-use matrices. These substances modify surface energy, reaction kinetics, rheology, or durability in industrial processes and consumer goods. Coatings and adhesives segments dominate current revenue pools, with automotive refinish and marine protective applications commanding premium pricing. Water treatment chemicals represent the fastest-growing application dimension, driven by desalination capacity expansion and produced-water management requirements across Gulf oil producers. Construction end-use demand concentrates in waterproofing membranes and tile adhesives as Gulf states execute infrastructure diversification programs.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations restrict volatile organic compound content in architectural coatings, compelling reformulation across imported and locally manufactured product lines. South Africa's National Regulator for Compulsory Specifications enforces SANS building material standards that govern adhesive bond strength and coating fire resistance ratings. The EU REACH regulation's extraterritorial influence persists through supply chain disclosure requirements affecting chemicals exported from Middle East and Africa into European downstream markets. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national standards regimes when configuring regional product portfolios and certification strategies.
Market Dynamics
SASO's VOC limits on architectural coatings are forcing immediate reformulation across Gulf-based production lines, compressing margins for importers while creating captive demand for local low-emission synthesis capacity.
Growth Catalysts
- Desalination infrastructure buildout:Gulf states are expanding reverse osmosis and thermal distillation capacity, generating sustained demand for antiscalants and biocides in water treatment chemical portfolios.
- SASO technical regulations:Mandatory VOC ceilings in Saudi architectural coatings are redirecting formulation investment toward compliant resin systems and solvent-free curing technologies.
- Upstream petroleum chemical intensity:Enhanced oil recovery operations across Kuwait and the UAE are absorbing specialty surfactants and corrosion inhibitors at volumes that justify dedicated local blending facilities.
Market Restraints
- Naphtha and natural gas liquid volatility:Feedstock cost swings in Saudi Arabia's methane-to-chemicals complexes compress margin predictability for downstream specialty derivative producers.
- Import dependency in sub-Saharan Africa:South Africa and Nigeria rely on European and Asian supply for high-purity electronic-grade chemicals, exposing operations to currency fluctuation and shipping disruption.
- Substitution by bio-based alternatives:Plant-derived surfactants and fermentation-sourced solvents are displacing synthetic equivalents in personal care and home care formulations bound for EU export markets.
Strategic Opportunities
- Egyptian construction chemical penetration:New administrative capital development and Suez Canal economic zone infrastructure are absorbing waterproofing admixtures and tile adhesives at volumes that exceed current local supply.
- Circular economy mandates:UAE's post-consumer plastic recycling targets are creating demand for compatibilizers and odor-masking additives in recycled polymer streams.
- Digital distribution platforms:B2B chemical marketplaces are disintermediating traditional distributor networks in South Africa, enabling direct manufacturer-to-contractor sales of standardized construction chemical grades.
Industry Challenges
- Specialized formulation chemist scarcity:Gulf universities produce insufficient graduates with polymer science and surface chemistry expertise, forcing producers to recruit from European and Asian talent pools.
- Dual certification burden:Products exported to EU markets must simultaneously satisfy SASO domestic standards and REACH disclosure requirements, extending compliance timelines by eight to fourteen months.
- Legacy ERP integration:Batch tracking and quality management system upgrades required for regulatory traceability are stalling at mid-sized UAE and Saudi blending facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Specialty Chemicals Market |
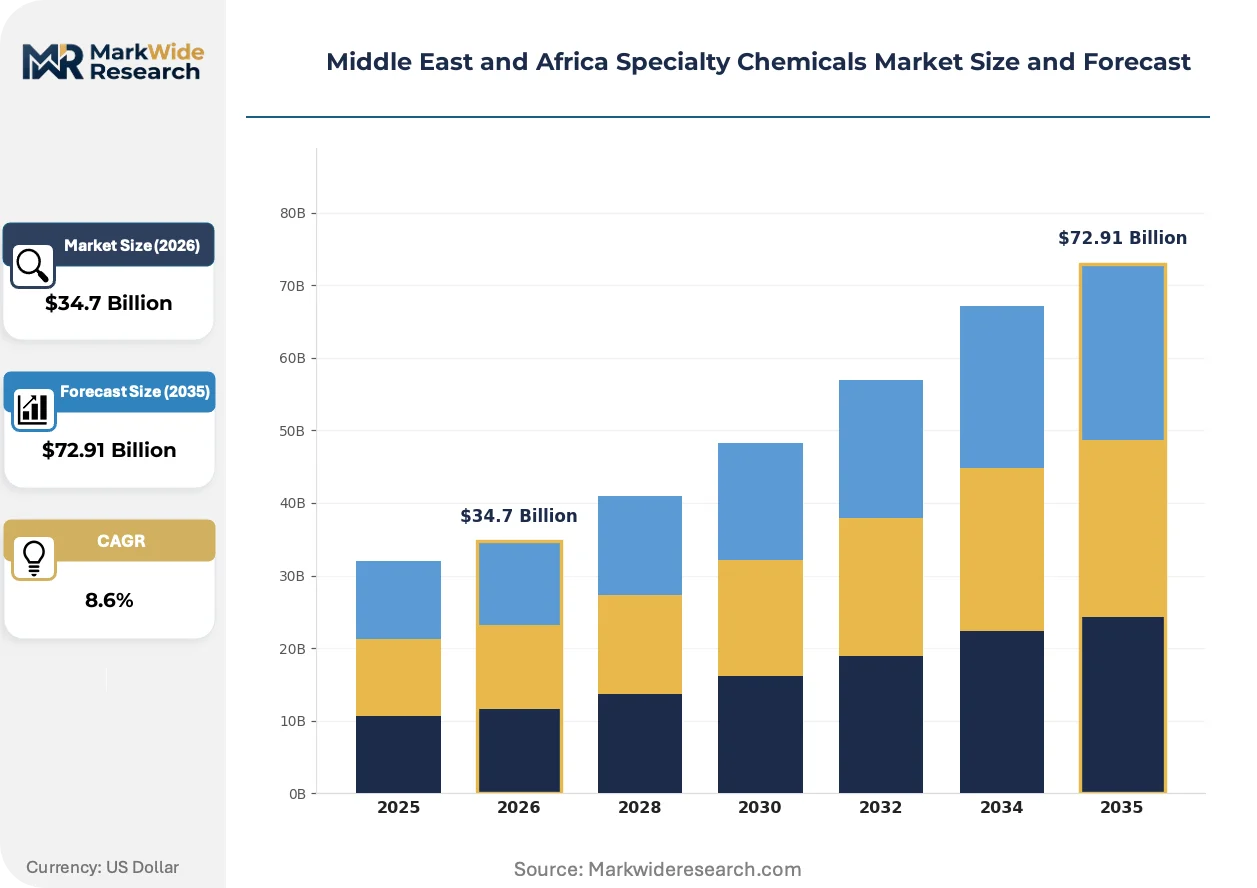
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Inks, Sealants End Use Industry: Aerospace, Automotive, Construction, Electronics Form: Liquid, Powder, Granules, Paste Application: Surface Treatment, Water Treatment, Agriculture, Cleaning |
| Companies Covered | SABIC, Sadara Chemical Company, Saudi Specialty Chemical Industries Co Ltd., Thebe Unico, AECI Ltd., Clariant AG, AkzoNobel N.V., Evonik Industries AG, BASF SE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Specialty Chemicals Market Shifts & Advancements
Formulation science is pivoting toward molecular precision and regulatory pre-compliance, with Gulf producers investing in predictive modeling to anticipate VOC restrictions before they crystallize into enforceable standards.
Waterborne epoxy curing systems are overtaking solvent-based alternatives in marine protective coatings for UAE and Saudi shipyard maintenance contracts. Dry-dock operators in Dubai Maritime City are specifying high-solids formulations to meet port authority environmental permits. This transition is compressing demand for aromatic hydrocarbon diluents while expanding local capacity for amine hardener synthesis.
REACH disclosure requirements are reshaping supply chain documentation for Middle East and Africa producers exporting into European downstream markets. Importers now demand full substance identity and tonnage band registration from Gulf suppliers. South African adhesive manufacturers are responding by consolidating formulation platforms to reduce unique chemical identities requiring registration.
Direct procurement from specialty chemical manufacturers is displacing traditional distributor relationships among large Saudi and UAE construction conglomerates. Emaar and Saudi Binladin Group are negotiating annual volume contracts for concrete admixtures and waterproofing membranes. This concentration is most visible in Dubai's commercial tower segment, where single-source supply agreements now cover eighty percent of superstructure chemical requirements.
Middle East and Africa Specialty Chemicals Market Segmentation
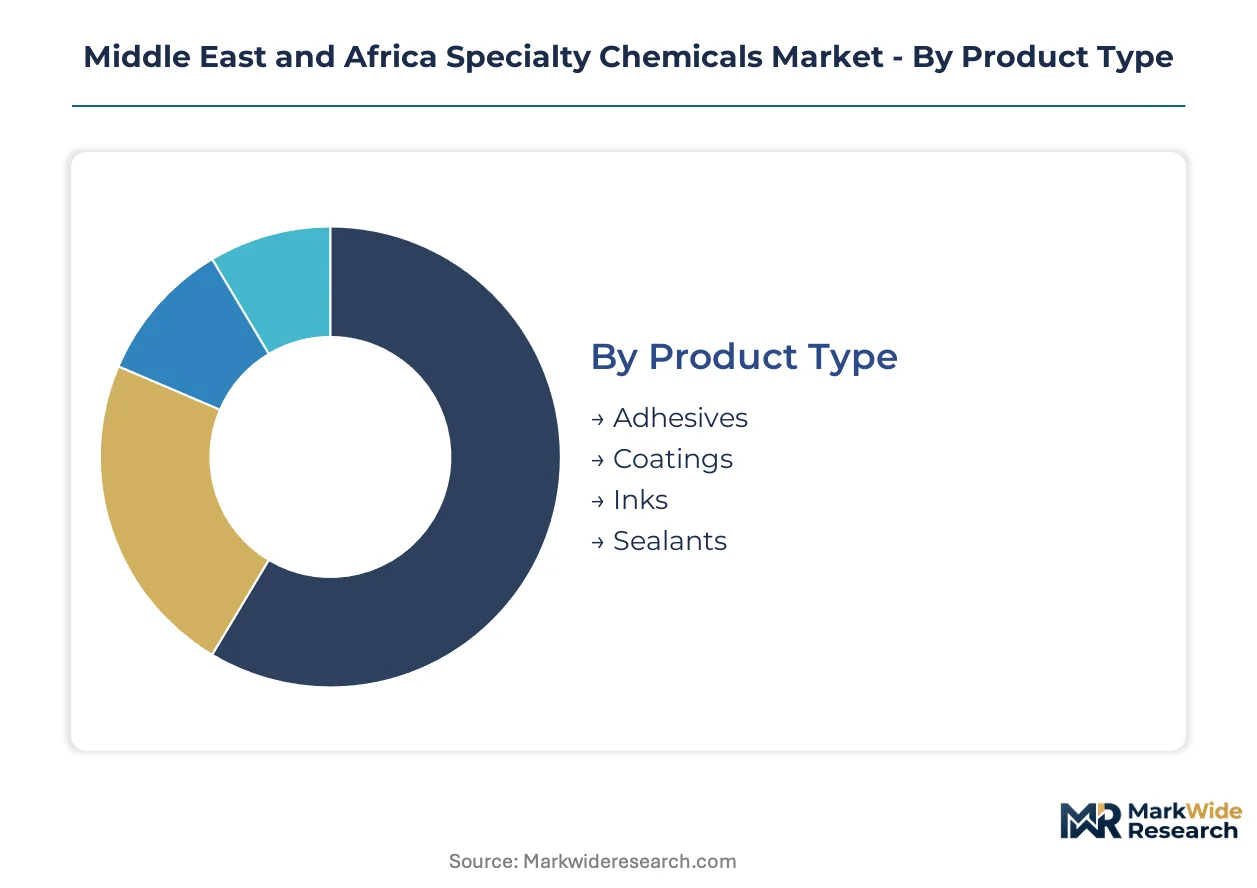
Specialty chemicals in the Middle East and Africa derive commercial value from precise molecular engineering rather than commodity scale. Segmentation reveals how formulation specificity, regulatory compliance, and end-use performance requirements fragment demand across distinct technical and application boundaries.
Product Type:
Performance specifications and curing chemistry differentiate competitive positioning across formulated product categories.
- Adhesives:Structural acrylics, epoxies, and polyurethane systems dominate industrial bonding applications. Saudi construction conglomerates specify high-temperature-resistant grades for curtain wall installation in Riyadh and Jeddah commercial towers.
- Coatings:Waterborne epoxy and high-solids polyurethane formulations command premium positioning. UAE marine maintenance yards in Dubai Maritime City are converting from solvent-based systems to comply with port authority environmental permits.
- Inks:UV-curable and solvent-flexographic varieties serve packaging and commercial printing segments. South African label converters require food-contact-compliant formulations for export-bound agricultural packaging.
- Sealants:Silicone and silyl-modified polymer chemistries address expansion joint and glazing applications. Egyptian new administrative capital infrastructure projects specify movement-capable grades for seismic accommodation.
Mature deployment sits with Coatings. Newer deployment is concentrated in Adhesives.
End Use Industry:
Customer procurement scale and technical specification intensity vary sharply across industrial verticals.
- Aerospace:Chromate-free pretreatments and qualified sealant systems meet OEM airworthiness standards. MRO facilities in the UAE absorb aerospace-grade chemicals for A380 and 777 maintenance contracts.
- Automotive:Refinish coatings and structural adhesives follow OEM color matching and crashworthiness protocols. Saudi Arabia's vehicle assembly plants source pre-treatment chemicals for localized production lines.
- Construction:Waterproofing membranes, concrete admixtures, and tile adhesives represent the largest volume concentration. Qatar's infrastructure buildout absorbs superplasticizers and crystalline waterproofing at scale.
- Electronics:High-purity solvents and conformal coatings serve PCB fabrication and semiconductor packaging. South Africa relies on imported electronic-grade chemicals for limited domestic assembly operations.
Volume leadership resides with Construction. Steepest expansion trajectory belongs to Electronics.
Form:
Physical state determines handling infrastructure, packaging requirements, and application equipment compatibility across supply chains.
- Liquid:Pumpable dispersions and solutions dominate continuous industrial processes. Gulf water treatment facilities specify liquid antiscalants for direct injection into reverse osmosis trains.
- Powder:Redispersible polymer powders and dry-blend admixtures enable extended shelf stability. Nigerian cement producers import powder superplasticizers for on-site concrete batching.
- Granules:Controlled-release fertilizers and water treatment media require specific dissolution kinetics. Moroccan phosphate processing operations utilize granular flotation reagents.
- Paste:Thixotropic sealants and mastics accommodate vertical and overhead application without sag. Saudi shipyards specify paste-consistency epoxy fairing compounds for hull repair.
Liquid formulations retain installed base dominance. Powder formats are gaining share fastest in remote construction logistics.
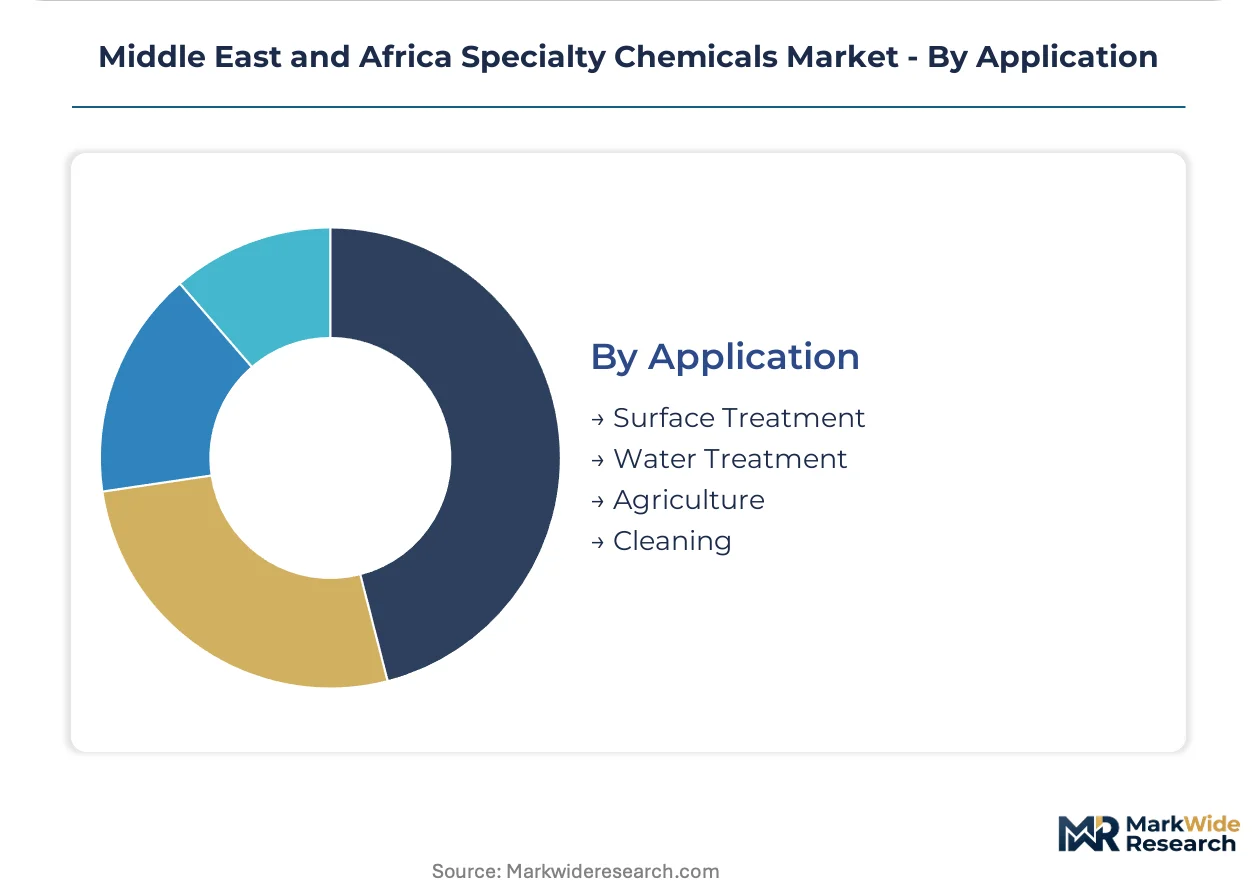
Application:
Functional outcome requirements drive specification intensity and pricing differentiation across use cases.
- Surface Treatment:Conversion coatings, cleaners, and activation chemistries prepare substrates for subsequent operations. UAE aluminum extruders deploy zirconium-based pretreatments ahead of powder coating lines.
- Water Treatment:Antiscalants, biocides, and coagulants manage membrane fouling and microbial control. Saudi desalination capacity expansion sustains demand for phosphonate and polymer-based scale inhibitors.
- Agriculture:Adjuvants, micronutrient chelates, and controlled-release coatings enhance input efficiency. Egypt's Nile Delta farming operations specify surfactant blends for pesticide application optimization.
- Cleaning:Industrial degreasers and institutional sanitizers balance efficacy with effluent compliance. South African food processing plants require HACCP-aligned cleaning chemical portfolios.
Surface Treatment commands established specification depth. Water Treatment exhibits the most rapid demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's methane reserves anchor regional feedstock availability. Gulf petrochemical complexes convert this advantage into specialty derivative output. Sub-Saharan markets remain import-dependent for high-purity grades.
Saudi Arabia
Jubail's industrial city absorbs specialty polyurethane and glycol ether production for construction and automotive applications. SASO technical regulations enforce VOC ceilings in architectural coatings, compelling reformulation across domestic manufacturing lines. Sadara Chemical Company's integrated facility anchors the kingdom's downstream specialty chemical capacity.
United Arab Emirates
Estidama Pearl Rating System mandates redirect formulation demand toward low-VOC coatings and sealants for green building compliance. Dubai Maritime City shipyards specify waterborne epoxy systems to satisfy port authority environmental permits. Emaar and Saudi Binladin Group negotiate direct annual volume contracts for concrete admixtures.
South Africa
The National Regulator for Compulsory Specifications enforces SANS building material standards governing adhesive bond strength and coating fire resistance ratings. Construction sector demand concentrates in waterproofing membranes and concrete admixture grades. AECI Ltd. competes on explosives and specialty chemical distribution across mining and agricultural verticals.
Egypt
New administrative capital development and Suez Canal economic zone infrastructure absorb waterproofing admixtures and tile adhesives at volumes exceeding current local supply. The country's agricultural heartland specifies surfactant blends for pesticide application optimization in Nile Delta farming operations. Egyptian construction chemical penetration lags behind Gulf capacity.
Qatar
Infrastructure buildout for global sporting events absorbed superplasticizers and crystalline waterproofing at scale. Produced-water management requirements across upstream petroleum operations sustain demand for specialty surfactants and corrosion inhibitors. Qatar's chemical sector remains concentrated in downstream derivatives from Ras Laffan gas processing.
Middle East and Africa Specialty Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation technology and feedstock integration. The market structures around three tiers: integrated petrochemical giants with captive methane supply, European specialty chemical houses with catalyst and additive portfolios, and regional distributors serving construction and water treatment end-uses. Dominant competitive moves include backward integration into performance polymer intermediates and strategic partnerships for local blending capacity.
Among Gulf-based integrated producers, SABIC and Sadara Chemical Company exemplify the feedstock-anchored archetype, leveraging methane-to-chemicals complexes for captive supply. European specialists Clariant AG and BASF SE occupy positions defined by catalyst technology and construction chemical formulation expertise. South Africa's AECI Ltd. represents the regional distribution and mining chemicals model.
| Leading Market Players |
|---|
| SABIC |
| Sadara Chemical Company |
| Saudi Specialty Chemical Industries Co Ltd. |
| Thebe Unico |
| AECI Ltd. |
| Clariant AG |
| AkzoNobel N.V. |
| Evonik Industries AG |
| BASF SE |
| Others |
Supply & Pricing Matrix
Polymer chemist scarcity in Jubail Industrial City and the UAE's Khalifa Industrial Zone Abu Dhabi compresses labor-cost differentials into pricing-tier spreads across Gulf specialty chemical production. SASO-mandated VOC compliance adds certification-grade premiums that separate compliant resin systems from legacy formulations still serving price-sensitive sub-Saharan import markets.
Pricing Analysis
Technical service bundling separates Gulf-based producers from unbundled Asian imports competing on spot price alone. Three-tier pricing structure across premium certified, standard compliant, and economy unbundled levels reflects SASO certification status and after-sales formulation support. Cost compression in economy-tier imports intensifies because naphtha feedstock volatility squeezes margin buffers for non-integrated blenders. Construction conglomerates in Saudi Arabia and the UAE exhibit lowest price sensitivity due to direct procurement contracts, while Nigerian cement producers importing powder admixtures face acute price pressure from currency fluctuation.
Supply Chain Analysis
Formulation chemist availability constraints in Saudi Arabia, the UAE, and South Africa tether production capacity expansion to expatriate recruitment cycles from European and Asian talent pools. Methane feedstock draws from Saudi Arabia's integrated complexes, performance polymer intermediates from Sadara's Jubail facility, and electronic-grade solvents from German and Japanese specialty houses. Single-source vulnerability concentrates in high-purity electronic chemicals where South African assembly operations rely entirely on imported grades. Distribution runs through construction chemical distributors in sub-Saharan Africa and direct manufacturer-to-contractor channels in Gulf states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: specialized formulation chemist scarcity props pricing power for integrated producers with captive talent pipelines and backward integration into performance intermediates.
For Market Incumbents: Anchor domestic capacity against Asian import substitution by expanding low-VOC synthesis lines ahead of anticipated SASO ceiling reductions. Defend margin position through backward integration into amine hardener production for waterborne epoxy systems, neutralizing feedstock volatility that compresses non-integrated blenders. Prioritize certification pre-investment to compress the eight-to-fourteen-month dual SASO-REACH compliance timeline that stalls mid-sized competitors.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in Egyptian construction chemicals offers white-space entry before local supply catches administrative capital demand. Target waterproofing admixture and tile adhesive segments where import dependency exceeds current Gulf capacity. Pursue digital B2B marketplace distribution to disintermediate traditional South African distributor networks and capture standardized construction chemical volumes.
For Investors and Strategic Acquirers: The window for entry favors regional distributors with construction vertical specialization and captive Gulf blending relationships. Long-term viability hinges on feedstock integration depth and regulatory compliance infrastructure rather than formulation technology alone. Watch Egyptian local supply buildout as the inflection signal: domestic capacity additions there will compress import-premium capture and redirect competitive focus to sub-Saharan logistics networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Performance Intermediates | SABIC's methane-to-chemicals complex secures captive supply against naphtha volatility. |
| Low-VOC Manufacturing Transition | SASO compliance deadlines force reformulation investment ahead of enforceable standards. |
| Long-term Supply Agreement | Emaar's direct procurement contracts lock superplasticizer volumes for Dubai tower construction. |
| Joint Venture for Local Blending | Sadara's Jubail facility anchors Saudi specialty polyurethane output for regional construction. |
| Digital Distribution Platform Launch | B2B marketplaces disintermediate South African construction chemical distributor networks. |
Research Methodology
Independent corroboration across plant managers at Gulf petrochemical complexes, procurement leads at Saudi construction conglomerates, distribution channel partners in South Africa, and technical R&D directors at European specialty houses underwrites the qualitative findings. Secondary validation draws from SASO technical regulation filings, REACH disclosure databases, customs and trade data for Middle East and Africa chemical flows, and SEC 10-K filings of listed specialty chemical producers. Bottom-up segment sizing triangulates against top-down macroeconomic demand modeling across construction, automotive, and water treatment end-uses.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions span product type, end-use industry, physical form, and application, with additional granularity on regulatory compliance tier and feedstock integration status. CAGRs derive from historical trajectory analysis adjusted for policy inflection points and capacity buildout schedules. Forecast inputs incorporate desalination capacity expansion pipelines, SASO regulatory phase-in timelines, and Egyptian infrastructure project award schedules.
Underlying measurement precision varies by segment; water treatment chemicals and construction admixtures carry tighter precision than electronic-grade specialties where import dependency obscures local demand quantification. Forecasts reflect documented assumptions on feedstock cost trajectories, regulatory enforcement intensity, and talent migration patterns. Supply disruption from shipping chokepoints, currency crises in sub-Saharan import markets, and accelerated bio-based substitution in EU-bound formulations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Lithopone Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Chemical Hardener Compounds Market
Specialty Compounds
United Kingdom Collagen Peptides Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Acetyl Serine Market
Specialty Compounds
Dextran Sulfate Sodium Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Thiocolchicoside Market