
 Thiocolchicoside Market | 2026-2036
Thiocolchicoside Market Size, Share, and Industry Trends Forecast 2026-2036
Thiocolchicoside Market Insights
Aftermarket service revenue from chronic pain management programs is rewriting how pharmaceutical firms capture lifetime value from muscle relaxant portfolios. Sanofi leverages its hospital formulary relationships across Western Europe to sustain high-margin injection sales. Lupin Limited anchors its position through backward integration into thiocolchicoside API production, while Alkem Laboratories Limited competes aggressively on oral solid dosage cost structures in emerging markets.
Thiocolchicoside is a semisynthetic sulfur-containing derivative of colchicine, functioning as a centrally acting muscle relaxant with GABA-mimetic and glycinergic properties at the spinal cord level; it is synthesized through selective thiomethylation of colchicine followed by purification to pharmaceutical grade. The compound primarily serves acute musculoskeletal spasm relief, postoperative rigidity, and neurological movement disorders requiring rapid onset parenteral administration. Tablets dominate volume consumption in outpatient settings where cost sensitivity and self-administration drive preference, while injections command premium positioning in perioperative hospital use due to faster bioavailability and controlled dosing. The topical solutions segment remains nascent but attracts R&D investment as dermatological and transdermal delivery technologies advance.
The EMA's pharmacovigilance framework and the FDA's muscle relaxant safety labeling requirements shape formulation development and post-market surveillance obligations for manufacturers targeting regulated markets. India's CDSCO enforces bioequivalence standards for generic thiocolchicoside entrants, filtering substandard producers from the export supply base. Stakeholders must monitor evolving regulatory divergence between stringent markets and price-sensitive geographies when allocating manufacturing capacity and dossier investment.
Market Dynamics
EMA pharmacovigilance tightening for muscle relaxants is forcing manufacturers to rebuild clinical documentation frameworks and reformulate existing products, compressing margins while elevating compliance costs across European supply chains.
Growth Catalysts
- Surgical volume expansion:Rising hospital admissions for orthopedic and spinal procedures in India and Brazil are expanding the addressable patient base for perioperative muscle relaxant protocols.
- REACH compliance migration:European manufacturers upgrading sulfur-containing API handling standards are inadvertently improving batch consistency and reducing impurity profiles for export markets.
- Transdermal delivery R&D:Advances in microneedle patch technology are opening new administration routes for patients intolerant to oral or parenteral thiocolchicoside formulations.
Market Restraints
- Colchicine feedstock volatility:Autumn crocus cultivation concentration in Kashmir and southeastern Europe exposes API producers to climatic yield fluctuations and geopolitical supply interruptions.
- Generic substitution pressure:India's CDSCO bioequivalence waivers for certain oral solid strengths are accelerating price erosion in export markets where regulatory arbitrage is possible.
- Neurotoxicity labeling expansion:EMA's updated contraindication guidance for patients with seizure disorders is narrowing the eligible population for high-dose parenteral administration.
Strategic Opportunities
- Sub-Saharan Africa hospital buildout:Chinese infrastructure financing of tertiary care facilities in Kenya and Nigeria is creating first-time demand for perioperative formularies previously unavailable.
- Chronic pain program integration:Bundling thiocolchicoside with physiotherapy protocols in German outpatient clinics is capturing recurring revenue streams beyond acute episode prescribing.
- PLI scheme API reshoring:India's production-linked incentive scheme for critical drug intermediates is subsidizing domestic thiocolchicoside precursor capacity that can displace European import dependence.
Industry Challenges
- Analytical method transfer complexity:Migrating pharmacovigilance data collection from paper-based adverse event reporting to EudraVigilance-compatible electronic systems requires specialized regulatory IT talent scarce among mid-size Indian exporters.
- Sterile manufacturing capex thresholds:EMA's updated Annex 1 requirements for parenteral product environmental monitoring are demanding facility upgrades that strain balance sheets of family-owned API-to-finished-dose integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thiocolchicoside Market |
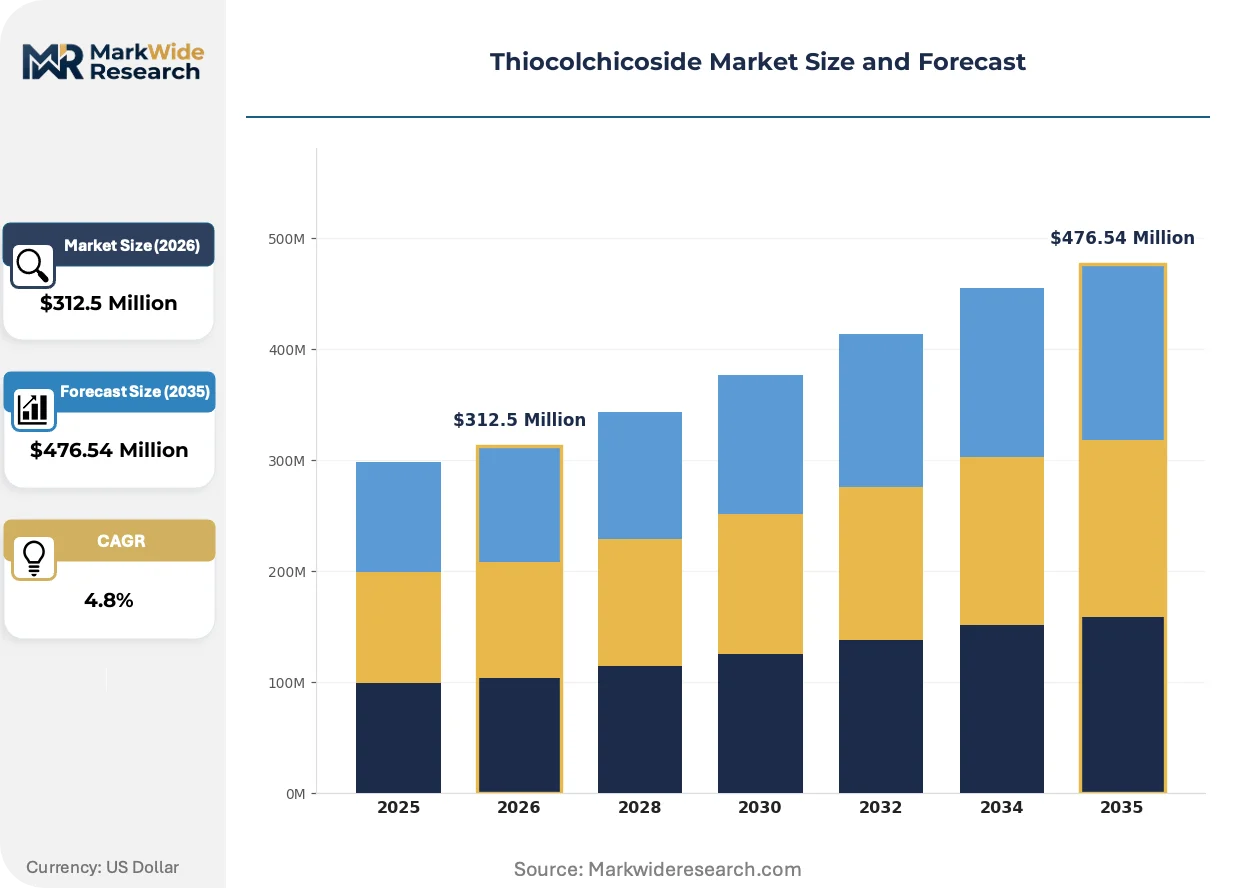
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Topical Solutions Application: Muscle Spasms, Pain Management, Neurological Disorders, Anti-inflammatory Treatment End User: Hospitals, Clinics, Outpatient Facilities, Pharmacies Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Sanofi, Mylan N.V., Teva Pharmaceutical Industries Ltd., Alchem International, Indena, Lupin Limited, Alkem Laboratories Limited, Sun Pharmaceutical Industries, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thiocolchicoside Market Trends and Innovations
Formulation science and regulatory data infrastructure are converging to reshape how muscle relaxant products are developed, monitored, and reimbursed across hospital and ambulatory settings.
Liposomal encapsulation technology is hybridizing conventional thiocolchicoside pharmacokinetics by extending plasma half-life and reducing CNS penetration-related adverse events. German and Swiss contract research organizations are advancing Phase II-ready candidates targeting postoperative spasm with reduced sedation profiles. This hybridizing approach is compressing the competitive window for conventional immediate-release tablets in premium hospital segments.
EMA's implementation of the Clinical Trials Information System (CTIS) under Regulation EU No 536/2014 is mandating centralized protocol submission and safety reporting for all new muscle relaxant indications. Sponsors must now harmonize multi-country trial designs under a single assessment procedure, raising documentation burdens but accelerating pan-European market access timelines. Parenteral product developers with existing EMA rapporteur relationships are capturing disproportionate advantage in the new framework.
Hospital procurement consortia in France and Italy are consolidating muscle relaxant purchasing through tender frameworks that unbundle device-administered injections from commodity oral solids. Regional health authorities are awarding multi-year supply contracts to manufacturers demonstrating end-to-end traceability from API source to patient administration. This consolidation is most visible in Lombardy and Ile-de-France, where three-year framework agreements now cover over sixty percent of public hospital thiocolchicoside expenditure.
Thiocolchicoside Market Segmentation
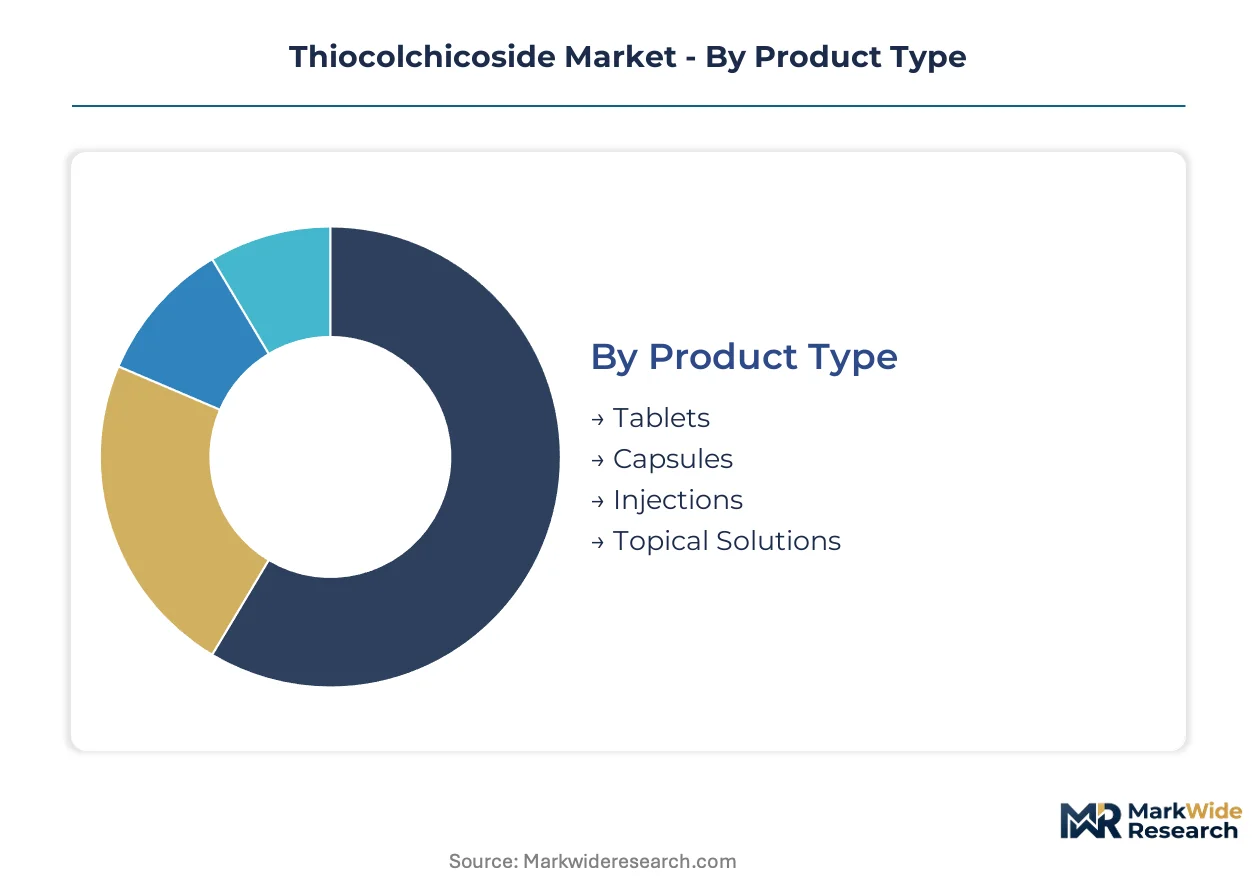
Thiocolchicoside market dynamics diverge sharply across administration routes and care settings. Tablets and injections serve fundamentally different clinical workflows, while hospital procurement operates on entirely separate commercial logic from retail pharmacy.
Product Type:
Cost tier stratification separates chronic outpatient therapy from acute perioperative intervention, with manufacturing complexity and bioavailability requirements driving margin structures.
- Tablets:Immediate-release oral solids containing 4mg or 8mg thiocolchicoside dominate ambulatory prescribing for musculoskeletal spasm. Demand concentrates in Indian retail pharmacies where price sensitivity and self-administration preferences align; CDSCO bioequivalence enforcement filters substandard generics from export channels.
- Injections:Parenteral formulations in ampoule or vial presentation deliver rapid onset for postoperative rigidity and neurological emergencies. Hospital formularies in France and Italy capture premium positioning through tender frameworks; EMA Annex 1 compliance demands sterile facility investments that exclude smaller API integrators.
- Capsules:Modified-release oral dosage forms offer gastric protection for patients with NSAID co-therapy. European specialty pharmacies stock these for polypharmacy populations.
- Topical Solutions:Transdermal gels and patches remain developmental, with microneedle delivery research advancing in Swiss and German CRO pipelines.
Tablets command the established base. The steepest expansion runs through injections as surgical volumes climb in Brazil and India.
Application:
Clinical indication shapes dosing protocol, duration of therapy, and reimbursement pathway across musculoskeletal and neurological practice areas.
- Muscle Spasms:Acute skeletal muscle hyperactivity from trauma or overuse represents the foundational indication. Orthopedic clinics in Lombardy and Ile-de-France bundle thiocolchicoside with physiotherapy protocols.
- Pain Management:Perioperative and chronic pain protocols incorporate muscle relaxant adjuvants to reduce opioid burden. German outpatient pain programs generate recurring prescription streams beyond acute episodes.
- Neurological Disorders:Movement disorders and spasticity conditions require specialized neurology consultation. EMA's expanded seizure disorder contraindications narrow eligible populations for high-dose parenteral use.
- Anti-inflammatory Treatment:Adjunctive use with NSAIDs or corticosteroids addresses inflammatory component of musculoskeletal conditions. Rheumatology practices in Spain and Portugal favor combination approaches.
Muscle spasm therapy anchors volume. Pain management applications are gaining share fastest as multimodal analgesia protocols spread.
End User:
Customer type determines formulary access, procurement mechanism, and clinical decision authority in thiocolchicoside purchasing.
- Hospitals:Tertiary care facilities with surgical and emergency departments drive injection demand through centralized purchasing. Chinese-financed hospital buildouts in Kenya and Nigeria create first-time formulary access.
- Clinics:Specialist outpatient settings including orthopedics and pain management prescribe oral solids with procedure bundling. German clinic chains integrate thiocolchicoside into standardized care pathways.
- Outpatient Facilities:Ambulatory surgical centers and day-case units require rapid-turnaround muscle relaxant protocols. Italian regional health authorities consolidate purchasing across these settings.
- Pharmacies:Community and hospital dispensaries handle prescription fulfillment and patient counseling. Indian retail pharmacy networks manage high-volume tablet distribution with thin margins.
Hospitals retain the premium segment. Clinics represent the fastest-climbing channel as outpatient procedure migration accelerates.
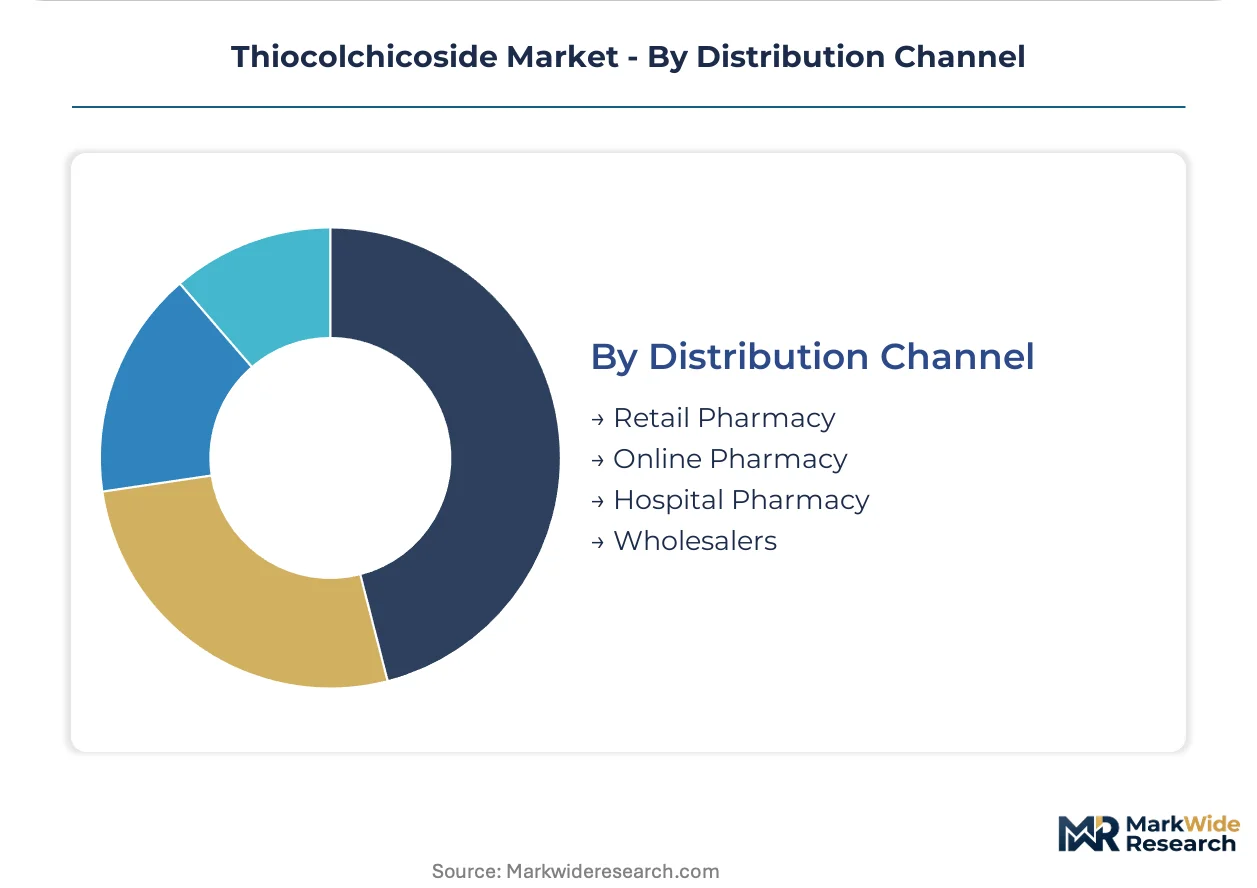
Distribution Channel:
Supply chain configuration dictates traceability requirements, margin capture, and patient access speed across regulated and informal pathways.
- Retail Pharmacy:Brick-and-mortar dispensaries dominate tablet volume in price-sensitive markets. Indian pharmacy chains leverage backward integration into API sourcing for cost advantage.
- Online Pharmacy:E-commerce platforms expand access in markets with pharmacy deserts or mobility constraints. Regulatory divergence between stringent and permissive jurisdictions shapes permissible service areas.
- Hospital Pharmacy:In-house dispensaries control formulary compliance and inventory for parenteral products. French and Italian hospital consortia award multi-year supply contracts with end-to-end traceability requirements.
- Wholesalers:Regional distributors aggregate demand across fragmented retail networks. European full-line wholesalers face margin compression from direct manufacturer-hospital contracting.
Retail pharmacy maintains volume leadership. Hospital pharmacy captures the steepest margin expansion as tender consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes thiocolchicoside predominantly in oral tablet form through retail pharmacy networks, while France and Italy drive premium injection volumes through hospital tender frameworks. Germany's outpatient pain programs generate recurring prescription streams that diverge from acute episodic use elsewhere. Brazil's surgical volume expansion is reshaping perioperative demand patterns in Latin America.
India
Domestic API production and contract manufacturing for export markets continue scaling as hospital surgical volumes rise. CDSCO enforces bioequivalence standards that filter substandard generics from export channels. Maharashtra and Gujarat host concentrated API-to-finished-dose integrators supplying regulated European markets.
France
Hospital procurement consortia consolidate muscle relaxant purchasing through multi-year tender frameworks covering over sixty percent of public hospital expenditure. EMA pharmacovigilance requirements reshape formulation standards and clinical documentation obligations. The Île-de-France region anchors premium injection demand through centralized formulary management.
Germany
Outpatient pain programs bundle thiocolchicoside with physiotherapy protocols, capturing recurring revenue beyond acute episodes. The Clinical Trials Information System mandates centralized protocol submission for new muscle relaxant indications. Bavarian and Baden-Württemberg clinic chains integrate the compound into standardized care pathways.
Italy
Regional health authorities in Lombardy award framework agreements unbundling device-administered injections from commodity oral solids. EMA's updated Annex 1 requirements for parenteral products demand sterile facility investments. Northern Italian manufacturing clusters supply traceable API source documentation for hospital contracts.
Brazil
Rising orthopedic and spinal procedure volumes expand the addressable patient base for perioperative muscle relaxant protocols. ANVISA regulates import quality standards for sulfur-containing API derivatives. São Paulo's tertiary care facilities drive injection demand through consolidated purchasing arrangements.
Thiocolchicoside Market Competitive Landscape
Capability concentration sits with integrated API-to-formulation specialists; scale advantage sits with diversified pharmaceutical conglomerates. The market structures around three tiers: backward-integrated Indian manufacturers, European hospital formulary incumbents, and generic solid-dose exporters. Dominant competitive moves include sterile manufacturing facility upgrades for EMA compliance and chronic pain program partnerships capturing lifetime patient value.
Among European hospital formulary incumbents, Sanofi exemplifies premium injection positioning through established rapporteur relationships. Within the Indian integrated manufacturing tier, Lupin Limited and Alkem Laboratories Limited occupy positions anchored by domestic API production and cost-optimized oral solid structures respectively. Sun Pharmaceutical Industries represents the diversified generic exporter archetype spanning multiple dosage forms and regulatory markets.
| Leading Market Players |
|---|
| Sanofi |
| Mylan N.V. |
| Teva Pharmaceutical Industries Ltd. |
| Alchem International |
| Indena |
| Lupin Limited |
| Alkem Laboratories Limited |
| Sun Pharmaceutical Industries |
| Takeda Pharmaceutical Company Limited |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European sterile manufacturing facilities is compressing supplier margins while elevating pricing power for EMA Annex 1 compliant integrators serving hospital tender frameworks. CDSCO bioequivalence enforcement in India simultaneously filters low-cost tablet exporters from premium regulated channels, creating divergent pricing postures across oral and parenteral segments.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement in France and Italy, while spot purchasing persists in Indian retail pharmacy channels. Three-tier pricing structure across premium injection, standard oral solid, and economy generic tablet levels reflects EMA compliance certification and sterile facility investments. Cost compression in Indian export tablet tiers is intensifying because CDSCO waivers for certain strengths accelerate regulatory arbitrage. Hospital formulary buyers exhibit lowest price sensitivity due to bundled tender frameworks; retail pharmacy chains in emerging markets show highest sensitivity to per-unit procurement costs.
Supply Chain Analysis
Colchicine feedstock cultivation centers on Kashmir and southeastern Europe, exposing API producers to climatic yield fluctuations and geopolitical interruptions. Thiocolchicoside manufacturing draws from autumn crocus harvesting, sulfur-containing intermediate processing, and sterile finishing capacity. Single-source vulnerability in Kashmir crocus fields creates concentrated supply risk for European and Indian formulators alike. Distribution runs through hospital pharmacy consortia in Western Europe and fragmented retail networks in South Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment; EMA pharmacovigilance documentation requirements and sterile facility certification create switching costs that protect incumbent hospital formulary positions.
For Market Incumbents: Insulate premium injection positioning by deepening sterile manufacturing capacity in Northern Italy and Bavaria ahead of Annex 1 enforcement waves. Secure multi-year tender renewals in Lombardy and Ile-de-France by embedding end-to-end API traceability systems that emerging Indian exporters cannot replicate. Counter generic substitution pressure through chronic pain program partnerships that capture recurring prescription streams beyond acute episodes.
For New Entrants and Emerging Players: Build out transdermal delivery capabilities targeting patients intolerant to oral or parenteral administration, where microneedle R&D in Swiss and German CRO pipelines remains pre-commercial. Target Sub-Saharan Africa hospital buildouts in Kenya and Nigeria financed by Chinese infrastructure lending, where first-time formulary access creates uncontested white space. Pursue contract manufacturing partnerships with established API producers rather than greenfield sterile facility investments.
For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated Indian manufacturers with CDSCO-certified export capacity and existing European rapporteur relationships. Long-term viability across the projection horizon rests on regulatory data infrastructure capabilities rather than commodity scale. Watch for EMA Clinical Trials Information System adoption velocity as signal of which sponsors will capture accelerated pan-European market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Compliance Investment | Sterile facility upgrades in Northern Italy exclude smaller API integrators from hospital tender participation. |
| Chronic Pain Program Integration | German outpatient clinic partnerships capture recurring revenue streams beyond acute episode prescribing. |
| Backward Integration into API Production | Maharashtra and Gujarat integrators secure captive colchicine derivative supply against Kashmir yield volatility. |
| Transdermal Delivery R&D Partnership | Swiss and German CRO collaborations advance microneedle patches for patients intolerant to conventional routes. |
| Sub-Saharan Africa Hospital Formulary Entry | Chinese-financed tertiary care buildouts in Kenya and Nigeria create first-time perioperative demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital formulary directors, CDSCO regulatory affairs leads, sterile manufacturing plant managers, and pain management clinic administrators. Secondary validation drew from EMA submissions, FDA muscle relaxant safety labeling updates, ClinicalTrials.gov protocol registrations, and Indian customs API export data. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Calibration against historical surgical admission trends and perioperative drug utilization patterns informed projection mechanics across the analysis window. Segmentation dimensions included administration route, care setting, regional regulatory cluster, and pain program integration depth. CAGRs were derived from elasticity-adjusted volume trajectories incorporating EMA pharmacovigilance compliance cost burdens and Indian PLI scheme capacity additions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese API producers or rapid transdermal technology breakthroughs would shift outcomes materially. Cross-checking against hospital procurement database benchmarks and GPO contract award frequencies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Global Masterbatch Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
High Performance Foam Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Global Black Masterbatch Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Polyurea Market
Specialty Compounds
Acrylic Pad Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Lentein Market
Specialty Compounds
Plasma Powder Market
Specialty Compounds
Potassium Gluconate Market