
 Middle East and Africa Sealants Market | 2026-2036
Middle East and Africa Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sealants Market Foresight
Silicone is expanding its share in facade and glazing applications across the Middle East and Africa Sealants Market as architects specify longer service intervals in extreme desert climates. Sika AG leverages its regional manufacturing footprint in the UAE to supply project-specific formulations for Dubai's commercial tower pipeline. Henkel AG & Co. KGaA anchors its position through construction adhesives distribution partnerships spanning Saudi Arabia and Egypt. Dow competes on advanced polymer science, sustaining technical service teams that validate structural glazing designs for Gulf-based engineering consultants.
Sealants are elastomeric compounds formulated from polymers such as silicones, polyurethanes, acrylics, or butyl rubbers, engineered to fill gaps between substrates while accommodating thermal movement, moisture ingress, and vibration through elongation capacities typically exceeding 200%. Their primary commercial purpose is to create durable, flexible barriers that maintain building envelope integrity, vehicle panel sealing, or electronic component protection across temperature extremes from -40°C to 150°C. Polyurethane formulations dominate volume in construction weatherproofing and bonding applications where high modulus and paint compatibility command premium positioning. Silicone leads margin pools in structural glazing and aerospace electronics, where certification requirements and performance guarantees create defensible pricing. Acrylic occupies cost-sensitive segments in interior sealing and DIY renovation channels across North African markets.
Saudi Arabia's Saudi Building Code and South Africa's SANS 2001-CC1 standards mandate VOC emission thresholds and fire-performance classifications that filter non-compliant imports from Asian suppliers. The UAE's Ministry of Energy and Infrastructure enforces green building regulations aligned with Estidama Pearl Rating criteria, directing public project procurement toward low-VOC silicone and hybrid sealant systems. Nigeria's Federal Ministry of Works applies SONCAP conformity assessment to imported construction chemicals, creating compliance barriers for uncertified entrants. Stakeholders must monitor evolving harmonization between Gulf Standardization Organization sealant specifications and European REACH substance restrictions, as this convergence will reshape raw material sourcing and product registration requirements across the region.
Market Dynamics
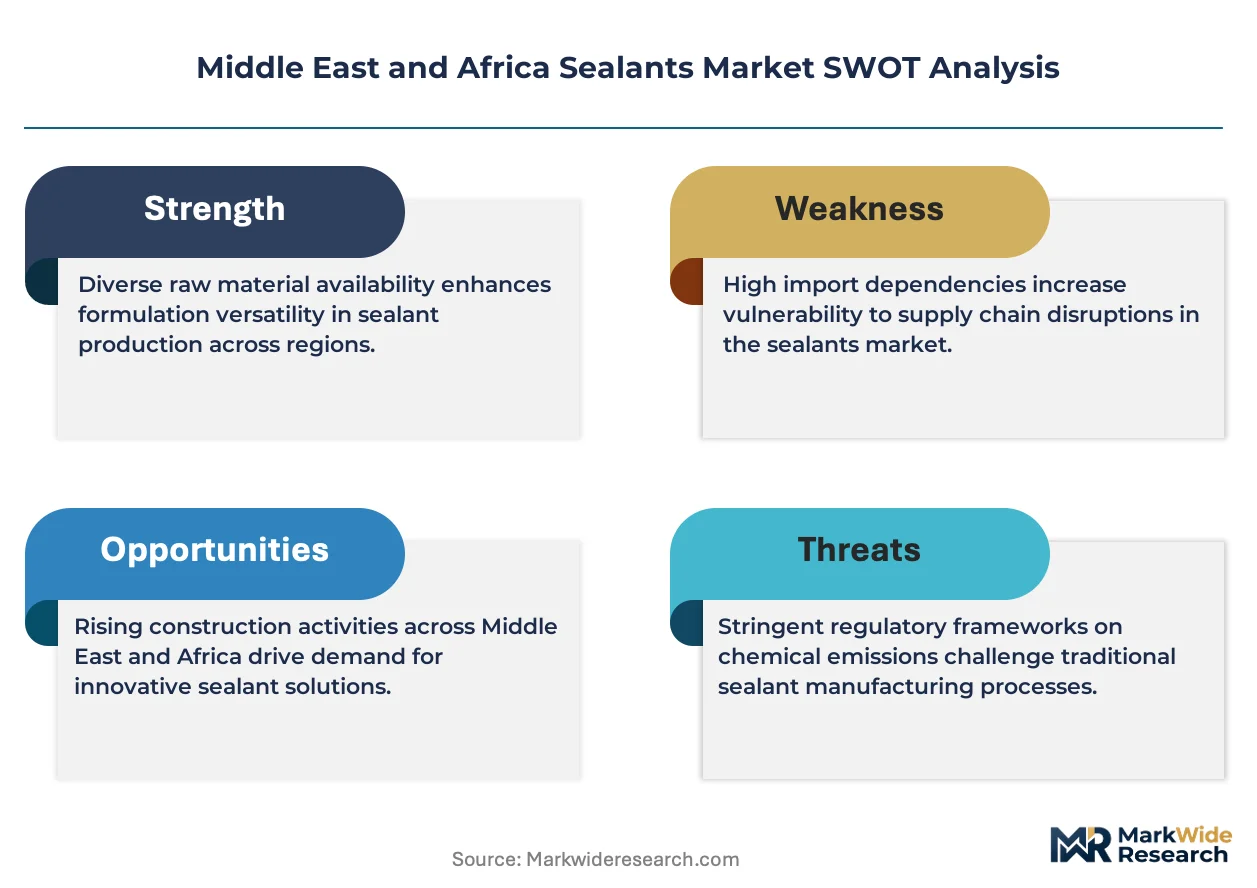
Gulf Cooperation Council construction codes and South Africa's SANS standards are tightening VOC emission thresholds, forcing reformulation of polyurethane and silicone sealant portfolios across the Middle East and Africa Sealants Market.
Growth Catalysts
- Estidama Pearl Rating criteria:UAE public procurement mandates low-emission sealant systems for commercial towers, redirecting specification toward certified silicone and hybrid formulations.
- Nigerian infrastructure rehabilitation:Federal Ministry of Works road and bridge contracts generate concentrated demand for high-performance weatherproofing compounds in West African climates.
- Saudi Building Code enforcement:Fire-performance classifications for facade applications are filtering uncertified Asian imports and elevating compliant domestic and European supply.
Market Restraints
- Petrochemical feedstock volatility:Polyol and siloxane precursor costs fluctuate with crude oil pricing, compressing margin stability for polyurethane and silicone formulators.
- Asian import concentration:Uncertified low-cost sealant volumes from unregulated manufacturers undercut pricing in North African DIY channels.
- Curing-rate limitations in extreme heat:Standard polyurethane formulations face application window constraints above 45°C ambient temperatures in Gulf summer conditions.
Strategic Opportunities
- Egyptian new capital construction:Administrative city megaprojects create demand for structural glazing and expansion joint systems in a historically undersupplied market.
- Hybrid sealant technology convergence:Silane-terminated polyurethane chemistry combines silicone weathering resistance with polyurethane paint compatibility, opening specification in high-end residential.
- SONCAP compliance services:Nigerian conformity assessment requirements create value-add channel opportunities for distributors offering technical documentation and testing support.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-VOC silicone modification and hybrid polymer synthesis remains concentrated in European and Gulf-based technical centers.
- Multi-jurisdiction registration timelines:Separate Gulf Standardization Organization, Saudi SFDA, and UAE MOHAP product approvals extend market entry cycles for new formulations.
- Legacy substrate compatibility:Historic building renovation in Moroccan and Tunisian medinas requires sealants compatible with deteriorated stone and lime mortar interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sealants Market |
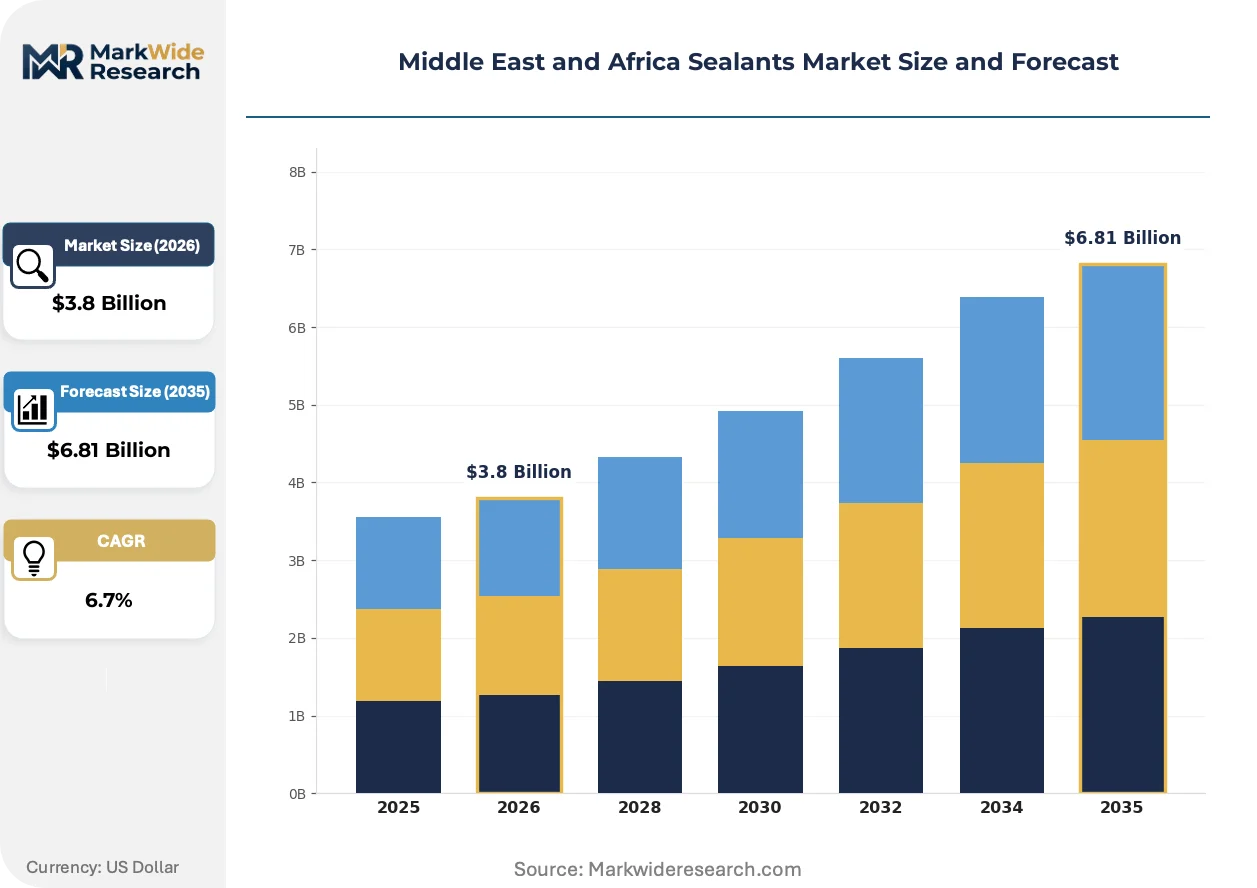
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Butyl End User: Construction, Automotive, Aerospace, Electronics Application: Weatherproofing, Bonding, Soundproofing, Insulation Installation Method: Manual, Mechanical, Automated, Others |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Sika AG, Dow, H.B. Fuller Company, Arkema Group, Soudal Holding N.V., Wacker Chemie AG, Pidilite Industries Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sealants Market Shifts & Advancements
Material science advances and procurement pattern shifts are restructuring competitive positioning in the Middle East and Africa Sealants Market, with formulation chemistry and compliance capability becoming primary differentiators.
Silane-terminated polyether technology is electrifying facade sealing specifications by combining silicone UV stability with polyurethane mechanical strength and paint adhesion. UAE-based engineering consultants are specifying these hybrids for Dubai's commercial tower pipeline where 25-year service guarantees are now standard. The technology is compressing market share for conventional polyurethane in premium weatherproofing segments.
Saudi Arabia's Saudi Building Code and South Africa's SANS 2001-CC1 standards are mandating VOC emission thresholds and fire-performance classifications that filter non-compliant imports. Formulators must redesign solvent-based portfolios or exit these markets. The regulatory friction is most acute in Saudi public infrastructure, where SFDA registration now requires third-party emission testing.
Engineering-procurement-construction firms are consolidating sealant procurement under single-source framework agreements with technical service capabilities. Regional distributors with in-house application engineering are displacing pure trading houses in Saudi and UAE commercial projects. This concentration is most visible in UAE megaprojects, where main contractors now require sealant suppliers to validate structural glazing designs through captive technical teams.
Middle East and Africa Sealants Market Segmentation
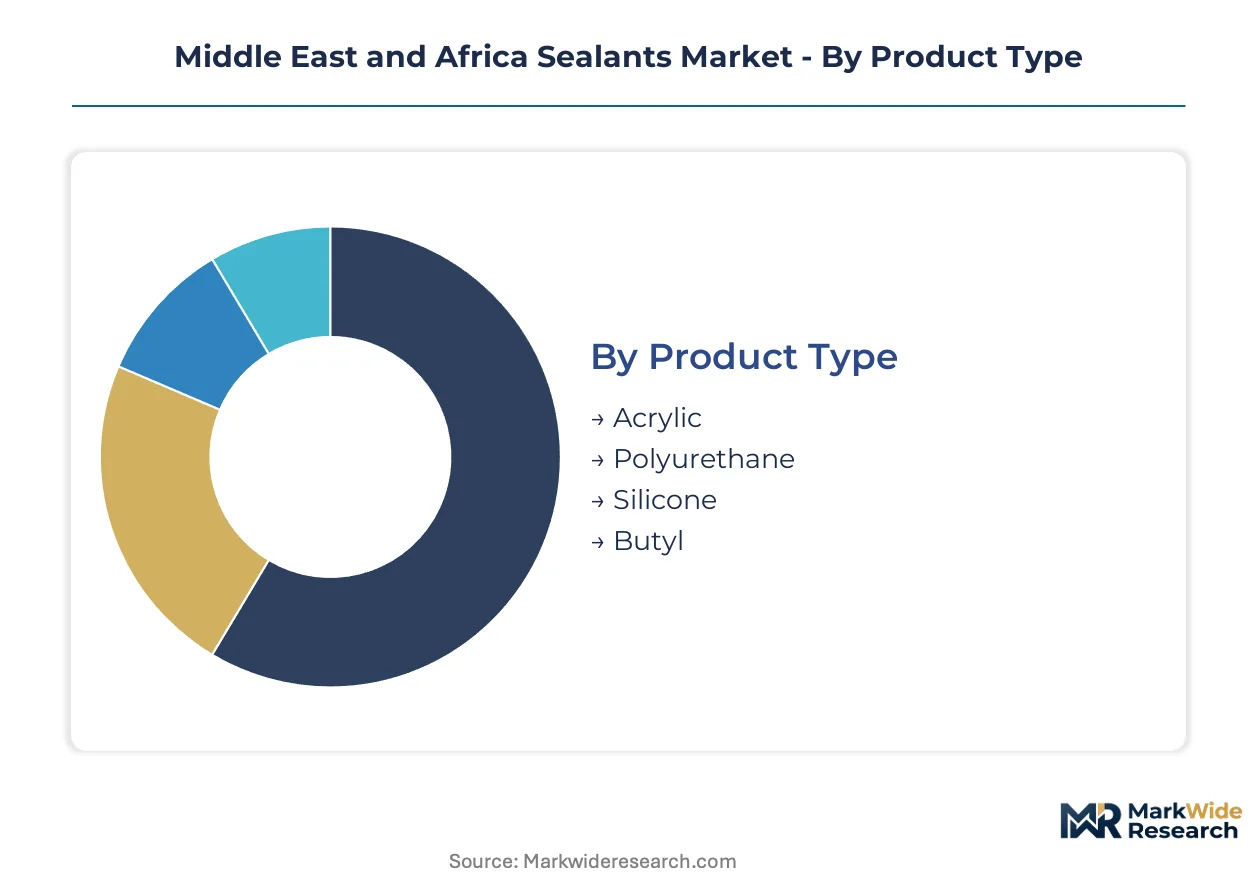
Segmentation in the Middle East and Africa Sealants Market reveals how formulation chemistry, end-use durability requirements, and installation constraints reshape procurement patterns. Construction codes in Saudi Arabia and the UAE filter product categories by VOC compliance, while Nigerian infrastructure tenders favor specific application methods.
Product Type:
Capital intensity varies sharply across chemistries, with silicone requiring specialized siloxane synthesis infrastructure and hybrid R&D facilities.
- Silicone:Polysiloxane backbone formulations deliver UV stability and thermal resistance from -50°C to 200°C. UAE megaprojects specify these for structural glazing where 25-year service guarantees are mandatory. Saudi Building Code VOC thresholds filter solvent-based alternatives, redirecting premium specification toward low-emission silicone systems.
- Polyurethane:Isocyanate-cured polymers combine high modulus with paint compatibility for facade weatherproofing. Nigerian Federal Ministry of Works road contracts generate concentrated demand in West African climates where bonding strength and flexibility must coexist. Petrochemical feedstock volatility compresses margin stability for regional formulators.
- Acrylic:Water-based emulsions serve cost-sensitive interior sealing across North African DIY channels.
- Butyl:Isobutylene-isoprene rubber compounds provide vapor barrier performance in HVAC and roofing applications.
Polyurethane absorbs the bulk of installed capacity; silicone is expanding most quickly.
End User:
Application durability requirements segment customers by certification burden and technical service intensity.
- Construction:Building envelope sealing dominates volume, with Gulf Cooperation Council commercial towers specifying hybrid formulations for expansion joints and curtain walls. Estidama Pearl Rating criteria mandate low-emission systems in UAE public procurement.
- Automotive:Direct glazing and body sealing applications require fast-cure formulations compatible with automated assembly lines.
- Aerospace:Fuel tank and cabin pressure sealing demands FAA- and EASA-certified silicones with traceable batch documentation.
- Electronics:Potting and encapsulation compounds protect PCBs from moisture and thermal cycling in Saudi and South African manufacturing clusters.
Construction commands the largest revenue pool; electronics is climbing the fastest on industrial diversification programs.
Application:
Performance specifications diverge by exposure severity and substrate movement tolerance.
- Weatherproofing:Exterior facade and roofing seals must accommodate 30% joint movement while resisting sand abrasion and salt corrosion. Dubai's commercial tower pipeline specifies silane-terminated polyether hybrids for 25-year durability guarantees.
- Bonding:Structural adhesion applications in Egyptian new capital construction require modulus-matched formulations for concrete and steel interfaces.
- Soundproofing:Mass-loaded acoustic sealants serve interior partition systems in Saudi residential towers.
- Insulation:Thermal barrier compounds support HVAC efficiency targets in South African SANS-compliant buildings.
Weatherproofing anchors specification volume; bonding is gaining share fastest on infrastructure rehabilitation cycles.
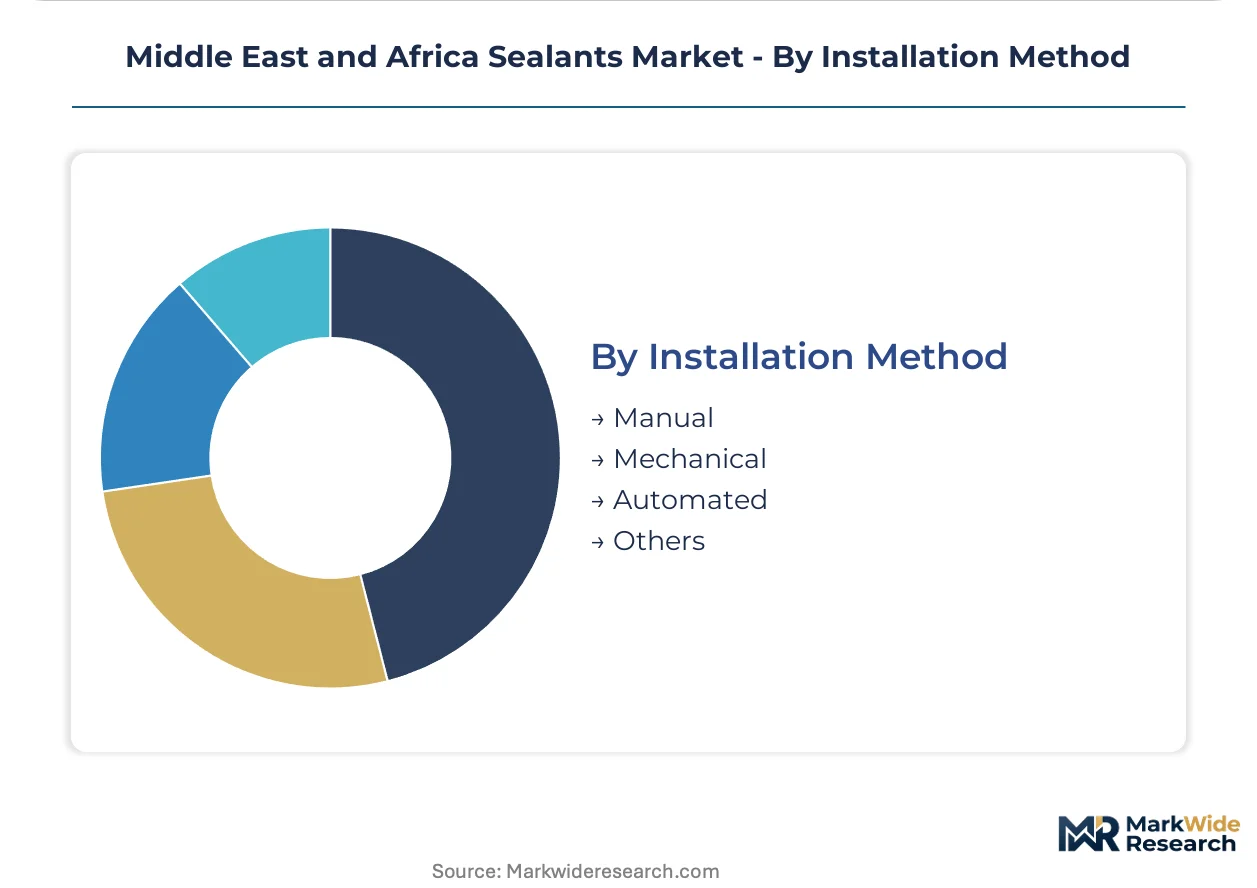
Installation Method:
Labor cost structures and project scale determine equipment investment requirements.
- Manual:Cartridge and sausage-pack application dominates renovation and small-scale commercial work across Moroccan and Tunisian medinas where historic substrate compatibility constrains mechanization.
- Mechanical:Pneumatic dispensing systems accelerate high-volume facade sealing in UAE megaprojects.
- Automated:Robotic application lines serve automotive OEM assembly plants in South Africa and Egypt.
- Others:Specialized spray and roller methods address roofing and waterproofing membranes.
Manual methods retain the widest deployment base; automated installation is expanding most quickly on manufacturing foreign direct investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Gulf commercial towers and West African infrastructure rehabilitation, with regulatory divergence across jurisdictions reshaping procurement patterns. Saudi Arabia and the UAE anchor premium specification volumes through megaproject pipelines. South Africa and Nigeria concentrate mid-market expansion on building code enforcement and federal contracting.
United Arab Emirates
Dubai's commercial tower pipeline and Abu Dhabi's cultural district construction specify silane-terminated polyether hybrids for 25-year facade guarantees. The Ministry of Energy and Infrastructure enforces Estidama Pearl Rating criteria that mandate low-VOC silicone systems in public procurement. Technical service teams validate structural glazing designs for engineering consultants concentrated in Dubai Design District.
Saudi Arabia
Riyadh's giga-projects and Red Sea tourism developments drive specification of fire-rated polyurethane and silicone formulations for curtain wall applications. The Saudi Building Code and SFDA registration requirements filter uncertified Asian imports through third-party emission testing protocols. Jeddah's industrial city hosts regional manufacturing footprints supplying project-specific formulations to western province construction sites.
South Africa
Johannesburg commercial rehabilitation and Cape Town residential retrofits generate demand for SANS 2001-CC1 compliant weatherproofing compounds. The South African National Standards institute mandates VOC emission thresholds and fire-performance classifications for facade applications. Durban's manufacturing corridor concentrates electronics potting compound demand from automotive and industrial diversification programs.
Nigeria
Federal Ministry of Works road and bridge contracts in Lagos and Abuja create concentrated demand for high-performance bonding and expansion joint systems. SONCAP conformity assessment requirements impose compliance barriers on imported construction chemicals through technical documentation and testing protocols. Port Harcourt's oil infrastructure maintenance generates specialized demand for chemical-resistant sealing formulations.
Egypt
New Administrative Capital construction and Suez Canal Economic Zone development specify structural glazing and concrete bonding systems for government district towers. The country's national construction regulator applies building envelope performance standards that elevate certified import procurement over unregulated regional supply. Cairo's contractor ecosystem consolidates procurement under framework agreements with technical service capabilities.
Middle East and Africa Sealants Market Competitive Landscape
Capacity expansion dominates the current landscape as formulators localize production to satisfy Gulf megaproject timelines and circumvent import certification friction. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive siloxane synthesis, regional formulators with project-specific technical service teams, and trading houses serving cost-sensitive North African renovation channels. Two strategic archetypes command premium positioning: integrated polymer science specialists and application engineering distributors. Geographic expansion and hybrid technology licensing represent the dominant competitive moves, with M&A activity concentrated in Egyptian and Saudi distribution assets.
Among European-based chemical conglomerates, Sika AG and Henkel AG & Co. KGaA exemplify the integrated technical service archetype, anchoring positions through regional manufacturing footprints and construction adhesives distribution partnerships. Dow occupies a position representing advanced polymer science capabilities, with technical validation services for structural glazing specifications. These three entities sit within the premium-tier competitive vector where 25-year service guarantees and regulatory compliance documentation determine specification outcomes.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow |
| H.B. Fuller Company |
| Arkema Group |
| Soudal Holding N.V. |
| Wacker Chemie AG |
| Pidilite Industries Ltd. |
| Others |
Supply & Pricing Matrix
Siloxane precursor costs cascade through three pricing tiers as polyol and isocyanate feedstock volatility compresses margins for polyurethane formulators serving Gulf megaprojects. Raw material concentration in Saudi petrochemical complexes and European siloxane synthesis facilities shapes procurement power across the Middle East and Africa Sealants Market.
Pricing Analysis
Volume splits across premium silicone, mid-tier polyurethane, and economy acrylic segments with price differentiation driven by certification grade and after-sales technical service bundling. Pricing pressure intensifies in North African DIY channels where uncertified Asian imports undercut compliant formulations. Construction contractors in UAE megaprojects exhibit lowest price sensitivity due to 25-year service guarantee requirements, while Moroccan renovation specialists face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Johannesburg operate hub-and-spoke patterns feeding project sites across the Middle East and Africa Sealants Market. Supply concentrates in Saudi Arabia, Germany, and China for siloxane intermediates, isocyanate precursors, and acrylic emulsions respectively. Single-source vulnerability in siloxane feedstock creates structural risk for silicone formulators. Distribution runs through EPC framework agreements with captive technical service teams displacing pure trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race as players pursue captive siloxane synthesis to secure margin control against petrochemical feedstock volatility.
For Market Incumbents: Extend technical service capabilities into Egyptian and Nigerian distribution assets to defend against hybrid-technology entrants. Backward integration into siloxane production secures supply certainty for 25-year guarantee commitments. SFDA and SONCAP certification investments create switching costs for specification-locked Gulf and West African projects. For New Entrants and Emerging Players: E-commerce platforms serving North African DIY renovation channels offer the lowest barrier to market entry. White-space exists in Egyptian New Administrative Capital bonding applications and Nigerian SONCAP compliance services. Technical documentation partnerships with local testing laboratories accelerate market access without manufacturing footprint. For Investors and Strategic Acquirers: Egyptian distribution assets changing hands is the leading indicator that consolidation momentum is accelerating in North Africa. Mid-cap formulators with hybrid polymer R&D capabilities and existing Gulf Standardization Organization registrations represent viable acquisition targets. Watch for Saudi giga-project award announcements as inflection signals for capacity utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Synthesis | Captive supply of polysiloxane intermediates insulates margin stability from crude-linked feedstock volatility. |
| Hybrid Sealant Technology Licensing | Silane-terminated polyether chemistry transfers open premium weatherproofing specifications previously locked by incumbents. |
| SONCAP Compliance Service Expansion | Technical documentation and testing support creates value-add differentiation in Nigerian federal contracting channels. |
| Egyptian Distribution Asset Acquisition | New Administrative Capital megaproject proximity secures structural glazing and concrete bonding specification access. |
| Estidama Certification Investment | Low-VOC formulation validation unlocks UAE public procurement mandates under Pearl Rating criteria. |
Research Methodology
Multi-period observation of raw material price indices, regulatory filing timelines, and megaproject award flows anchored the trend analysis, supplemented by interviews with sealant formulators, EPC procurement managers, and distribution channel partners. Secondary validation drew from Gulf Standardization Organization technical bulletins, Saudi SFDA registration databases, UAE Ministry of Energy procurement disclosures, and customs trade flow records. Bottom-up project pipeline enumeration and top-down chemical consumption estimates were triangulated to cross-check volume assumptions.
Input-output matrices mapped formulation chemistry, end-use durability requirements, and installation constraints against regional regulatory clusters across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application exposure severity, and jurisdiction-specific compliance burden. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion announcements. Industry-specific forecast inputs incorporated Estidama Pearl Rating adoption rates and Nigerian Federal Ministry of Works contract award velocities.
The model holds under stable petrochemical feedstock pricing and sustained Gulf megaproject execution; deviation in crude volatility spikes or construction financing disruptions would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market
Adhesives & Sealants
EMEA Epoxy Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Canada Adhesives Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Chlorinated Polyolefin Adhesion Promoter Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
South America Acrylic Adhesives Market