
 Middle East Construction Chemicals Market | 2026-2036
Middle East Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Construction Chemicals Market Foresight
The divergence between premium and commodity tiers in construction chemicals is hardening as giga-projects demand certified high-performance admixtures while smaller contractors still buy generic formulations. Sika AG leverages its regional formulation labs to anchor premium positioning across Gulf markets. BASF competes through backward integration into raw material supply for concrete admixtures.
Construction chemicals encompass admixtures, sealants, protective coatings, and repair compounds formulated with polymers, silica fume, and corrosion inhibitors to modify concrete rheology, durability, and setting characteristics under extreme desert temperatures and saline exposure. Their primary purpose is extending structural service life in aggressive environments while enabling faster construction cycles. Admixtures command the deepest margin pools due to formulation complexity and project-specific customization requirements. Protective coatings represent the fastest-expanding category as offshore and coastal infrastructure multiplies across the Arabian Peninsula.
Saudi Building Code, UAE Fire and Life Safety Code, and Dubai Municipality structural regulations collectively mandate performance-certified materials for commercial and infrastructure applications, creating compliance barriers for uncertified imports. Engineers and contractors now face procurement decisions that balance specification stringency against total applied cost across project lifecycles. Stakeholders must monitor how evolving green building standards and carbon-accounting requirements reshape material selection criteria before specification locks occur.
Market Dynamics
Giga-project pipelines across the Arabian Peninsula are forcing specification upgrades that bifurcate the supplier base into certified performance-grade formulators and commodity traders. Saudi Vision 2030 infrastructure mandates now require third-party certified admixtures for all concrete above 50 MPa, compressing procurement timelines and elevating technical service capabilities into competitive prerequisites.
Growth Catalysts
- Saudi Building Code enforcement:Mandatory performance certification for structural concrete applications creates procurement pull toward pre-qualified admixture suppliers with regional testing capabilities.
- Offshore energy infrastructure:Coastal and subsea projects across the UAE and Qatar demand specialized corrosion-inhibiting formulations with extended service-life guarantees under saline exposure.
- Polycarboxylate ether (PCE) technology:Next-generation superplasticizers enable high-strength concrete placement in ambient temperatures exceeding 45°C, unlocking summer construction windows previously uneconomical.
Market Restraints
- Naphtha and ethylene oxide volatility:Key feedstock price swings compress margin stability for formulators lacking captive petrochemical supply.
- Import dependency for specialty monomers:Concentrated European and Asian supply of PCE raw materials exposes regional blenders to freight cost spikes and currency mismatch risks.
- Technical service scarcity:Limited pool of concrete technologists capable of field-trial optimization and mix-design integration constrains premium supplier expansion.
Strategic Opportunities
- Egyptian infrastructure acceleration:New administrative capital and Suez Canal development zones lack established local admixture capacity, creating first-mover positioning for Gulf-based formulators with logistics networks.
- Carbon-accounting integration:Embodied carbon disclosure requirements in green building rating systems enable low-clinker concrete solutions to capture specification preference and price premiums.
- Digital dosing systems:IoT-enabled admixture metering and real-time rheology monitoring create aftermarket service revenue streams and customer lock-in beyond commodity supply.
Industry Challenges
- Certification timeline compression:Accelerated project delivery schedules leave insufficient weeks for full-scale trial mixes and third-party validation before specification lock.
- Skill migration from site to lab:Shortage of technicians capable of translating specification requirements into batch-plant executable mix designs delays technical onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Construction Chemicals Market |
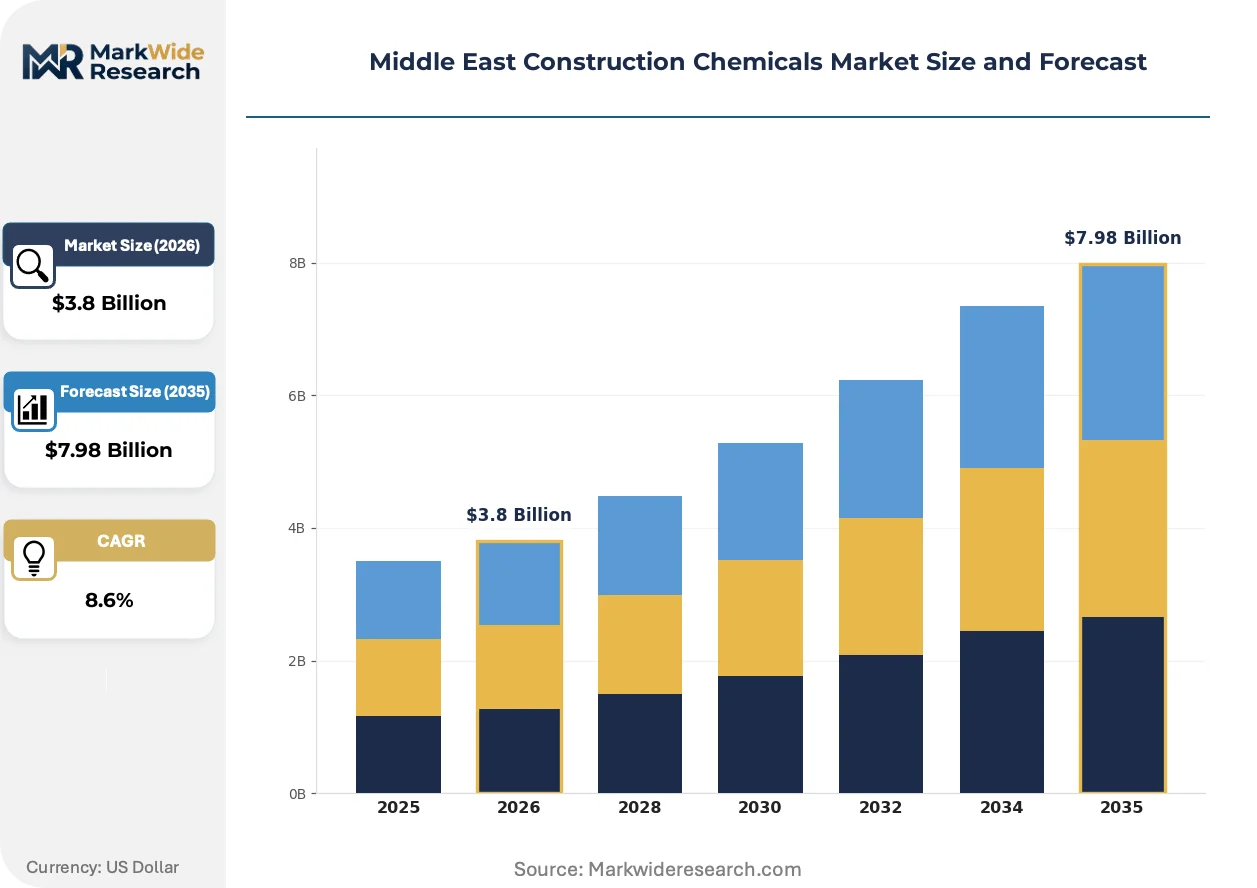
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Protective Coatings, Concrete Repair Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Builders, Engineers, Architects Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | Saint-Gobain, Saudi Readymix, Sika AG, Fosroc International Limited, Ahlia Chemicals Company, Mapei S.p.A., BASF, Master Builders Solutions, Dow, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Construction Chemicals Market Shifts & Advancements
Formulation science and project delivery models are converging to compress the traditional specification-to-pour cycle. Three developments are restructuring how performance is validated, procured, and guaranteed across the region's most demanding concrete applications.
Self-consolidating concrete (SCC) admixture systems are modularizing project execution by eliminating vibration requirements and enabling complex form geometries previously unbuildable. NEOM and Red Sea Project contractors are specifying SCC for 60% of vertical structures to accelerate pour rates and reduce labor exposure to extreme heat. This technology is modularizing the relationship between structural design freedom and construction program compression.
SFDA technical regulations for construction chemicals, aligned with Gulf Standardization Organization frameworks, now mandate factory production control certifications and traceability documentation for all structural admixtures. Industrial consequence includes exclusion of uncertified imports from Saudi giga-project supply chains. Specialty formulators with in-house quality laboratories are capturing specification preference by pre-positioning compliant documentation packages.
Integrated project delivery (IPD) contracting is consolidating procurement authority into single-source concrete performance guarantees rather than discrete material supply. EPC contractors on Qiddiya and Diriyah Gate developments now require admixture suppliers to assume rheology risk and warranty compressive strength outcomes. This shift is most visible in Saudi Arabia where developer balance sheets absorb performance-risk transfer premiums that commodity traders cannot underwrite.
Middle East Construction Chemicals Market Segmentation
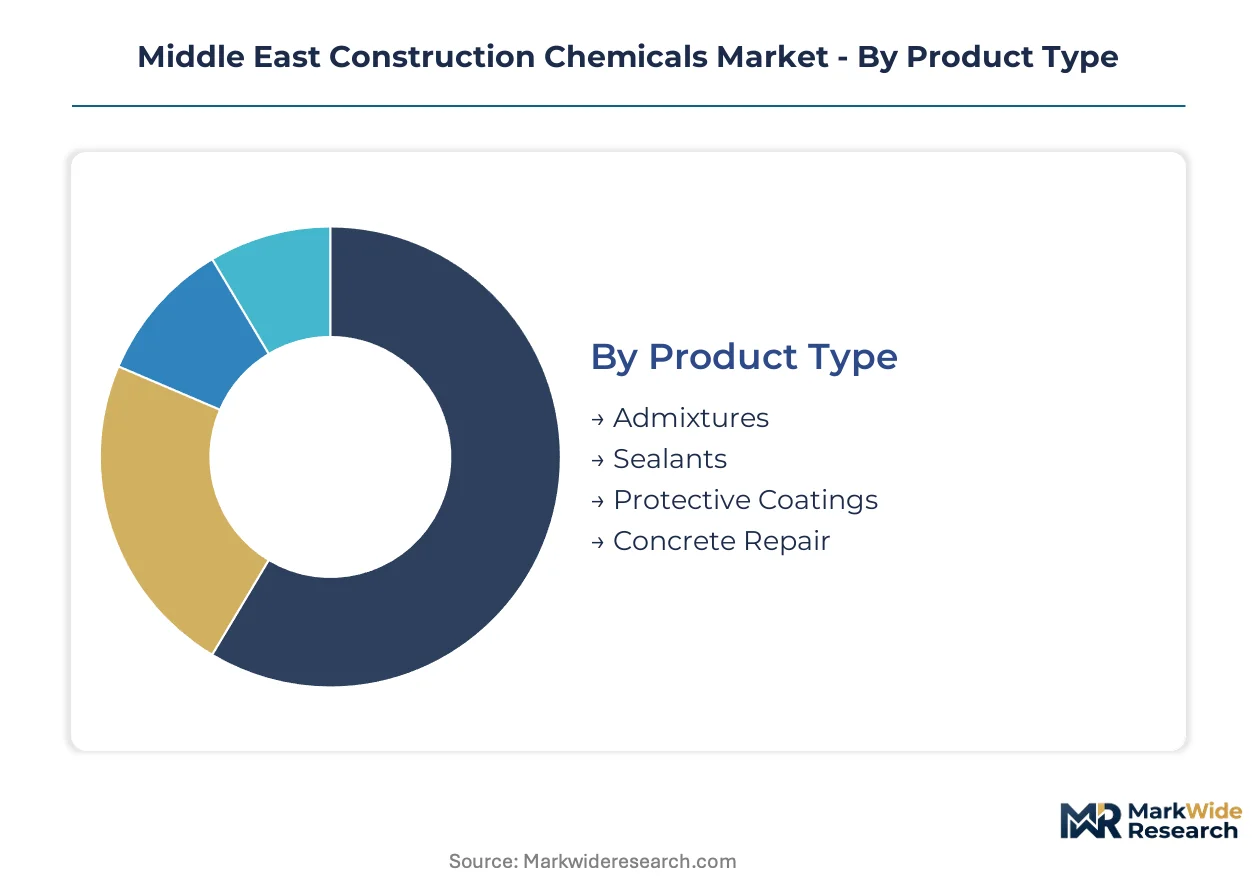
Construction chemicals in the Middle East span formulations with radically different integration requirements — from site-dosed admixtures embedded in every cubic meter of concrete to standalone repair compounds applied years after initial construction. Specification pathways diverge based on whether products require continuous technical service or function as transactional commodities.
Product Type:
Admixtures demand deepest integration into batch-plant operations and mix-design workflows, while protective coatings and repair materials operate as standalone applications with lighter technical touchpoints.
- Admixtures:Polycarboxylate ether and naphthalene-based formulations modify concrete rheology, retardation, and strength development. Saudi giga-projects consume these at scale for high-strength concrete above 50 MPa, with procurement tied to Saudi Building Code certification requirements.
- Protective Coatings:Epoxy, polyurethane, and cementitious systems shield steel reinforcement and concrete surfaces from chloride ingress and carbonation. Offshore platforms and coastal infrastructure across the UAE and Qatar drive specification intensity for extended service-life guarantees under saline exposure.
- Sealants:Polyurethane and silicone formulations accommodate structural movement while maintaining weatherproofing integrity.
- Concrete Repair:Structural mortars, injection resins, and corrosion inhibitors restore degraded elements without full replacement.
Volume placements concentrate in Admixtures; the faster expansion belongs to Protective Coatings.
Application:
Cost tier stratification separates specification-grade infrastructure work from price-sensitive residential volume, with commercial and industrial occupying intermediate positions.
- Infrastructure:Bridges, tunnels, airports, and rail systems mandate performance-certified materials with third-party validation. NEOM, Red Sea Project, and Qiddiya developments in Saudi Arabia specify admixtures with guaranteed rheology outcomes, compressing procurement timelines and elevating technical service capabilities into competitive prerequisites.
- Commercial:High-rise towers, hospitality, and retail complexes balance aesthetic finish requirements with accelerated construction programs. Dubai and Riyadh commercial developments specify self-consolidating concrete for complex form geometries and reduced labor exposure to extreme heat.
- Residential:Mid-rise housing and villa developments prioritize cost efficiency over performance certification.
- Industrial:Petrochemical facilities, power plants, and manufacturing floors require chemical-resistant flooring and heavy-duty protective systems.
Residential commands the largest absolute volume; infrastructure captures the steepest expansion trajectory as giga-project pipelines accelerate.
End User:
Technical capability depth varies sharply across buyer types, with engineers and architects driving specification upstream while contractors execute procurement downstream.
- Engineers:Structural and materials engineers embed performance requirements into contract documents, translating Saudi Building Code and Dubai Municipality regulations into enforceable material specifications. Their mix-design authority determines admixture selection before competitive bidding begins.
- Contractors:EPC firms and concrete specialists assume rheology risk under integrated project delivery contracts, requiring suppliers to warranty compressive strength outcomes rather than simply supply materials.
- Builders:Volume homebuilders and mid-tier developers prioritize total applied cost and logistics reliability.
- Architects:Aesthetic and sustainability criteria influence coating and finish selections, particularly for exposed concrete and heritage restoration.
Contractors process the highest transaction volume; engineers control the specification gateway with upstream authority.
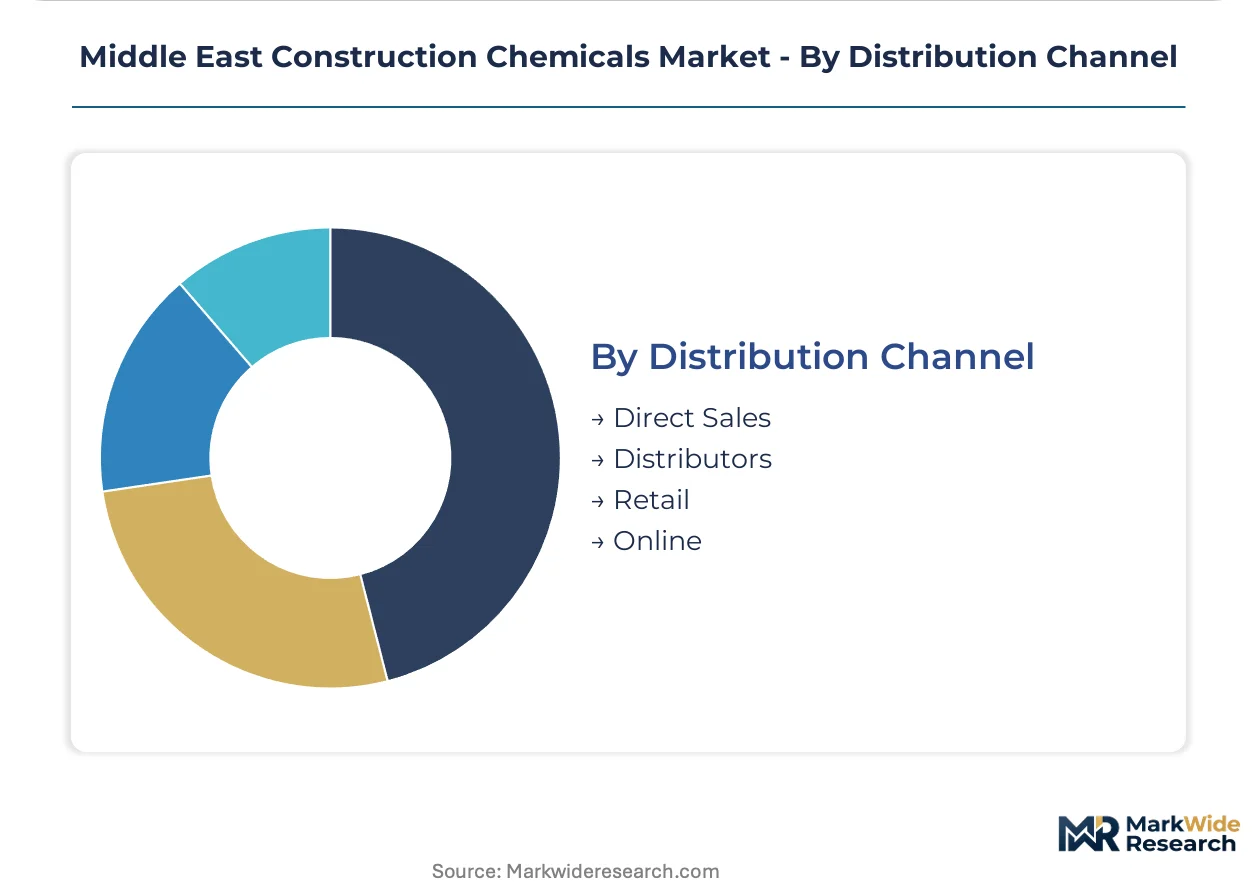
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating certified performance grades and intermediaries handling commodity volume.
- Direct Sales:Sika AG and BASF maintain technical salesforces for giga-project accounts, embedding formulation laboratories and field technicians within contractor operations. Direct relationships enable rapid mix-design optimization and documentation compliance for Saudi Vision 2030 mandates.
- Distributors:Regional chemical distributors serve mid-tier contractors with stocked inventory and credit terms, though limited technical service constrains access to premium specification tiers.
- Retail:Hardware chains and construction supply yards handle repair compounds, sealants, and small-batch admixtures for maintenance and minor works.
- Online:Emerging procurement channel for standardized products with clear specifications and repeat purchase patterns.
Direct Sales anchor the premium tier; Distributors capture the broadest geographic reach across secondary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors regional demand as Saudi Vision 2030 giga-projects concentrate specification-grade admixture procurement within the Saudi capital. The city hosts the densest clustering of formulation laboratories and technical service teams serving NEOM, Qiddiya, and Diriyah Gate developments.
Saudi Arabia
NEOM and Red Sea Project developments drive specification intensity for high-strength concrete above 50 MPa. SFDA technical regulations now mandate factory production control certifications for all structural admixtures, excluding uncertified imports from giga-project supply chains. Riyadh-based formulation laboratories pre-position compliant documentation packages to capture procurement preference.
United Arab Emirates
Offshore energy platforms and coastal infrastructure across Abu Dhabi and Dubai demand corrosion-inhibiting formulations with extended service-life guarantees. Dubai Municipality structural regulations mandate performance-certified materials for commercial applications, creating compliance barriers for uncertified products. Jebel Ali industrial zone concentrates protective coatings manufacturing for subsea pipeline projects.
Qatar
North Field expansion and liquefied natural gas infrastructure sustain demand for specialized concrete solutions under saline exposure. The country's national construction regulator enforces Gulf Standardization Organization frameworks for structural materials. Ras Laffan Industrial City hosts the primary concentration of petrochemical-resistant flooring and heavy-duty protective system applications.
Egypt
New administrative capital and Suez Canal development zones lack established local admixture capacity, creating first-mover positioning opportunities. The country's central construction authority issues performance standards aligned with regional Gulf frameworks. Cairo-Alexandria corridor development absorbs imported formulation expertise from Gulf-based suppliers with established logistics networks.
Kuwait
Silk City and Boubyan Island developments require specialized concrete solutions for marine and desert exposure conditions. The national standards body mandates third-party validation for structural admixtures in infrastructure applications. Al-Zour refinery expansion anchors industrial protective coatings demand for chemical-resistant flooring systems.
Middle East Construction Chemicals Market Competitive Landscape
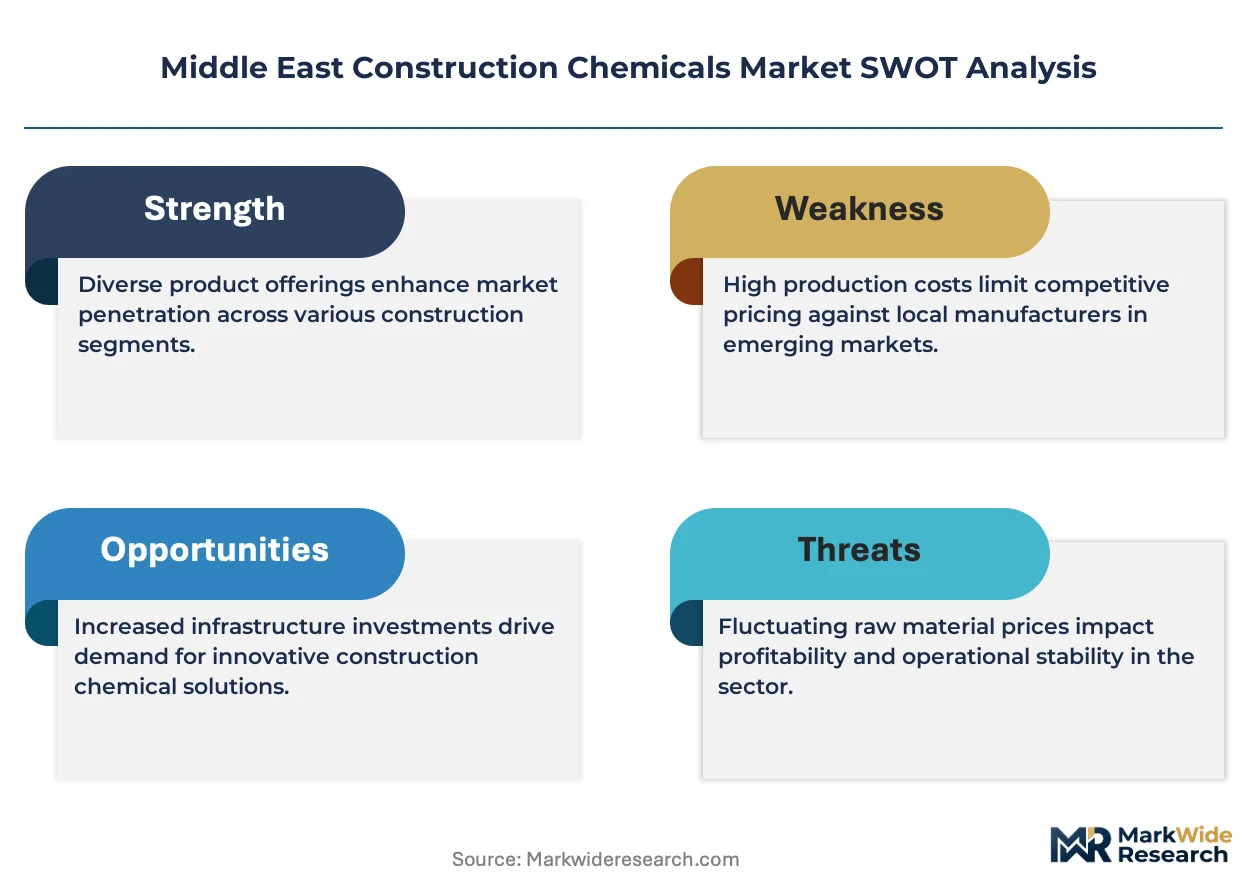
Premium-margin players sit above commodity-margin players across certification capability and technical service depth. The supplier base bifurcates into certified performance-grade formulators with regional testing laboratories and import-dependent commodity traders lacking documentation compliance. Three archetypes dominate: multinational formulators with captive raw material supply, regional blenders with logistics networks but limited technical service, and specialty distributors serving price-sensitive residential volume. Consolidation pressure intensifies through backward integration into petrochemical feedstocks and strategic partnerships for digital dosing system deployment.
Within the multinational formulator tier, Sika AG and BASF exemplify premium positioning through regional formulation laboratories and field-embedded technical teams. Fosroc International Limited occupies a position bridging international formulation expertise with Gulf market adaptation. These anchors represent the certification-capable segment capturing specification authority on Saudi Vision 2030 mandates.
| Leading Market Players |
|---|
| Saint-Gobain |
| Saudi Readymix |
| Sika AG |
| Fosroc International Limited |
| Ahlia Chemicals Company |
| Mapei S.p.A. |
| BASF |
| Master Builders Solutions |
| Dow |
| Others |
Supply & Pricing Matrix
SFDA factory production control certifications now gate both qualified supply and premium-tier pricing access across Saudi giga-project supply chains. Contractors lacking compliant documentation packages face automatic exclusion from specification-grade procurement, compressing margin pools into certified formulators while commodity traders compete on undifferentiated volume.
Pricing Analysis
Performance-guarantee pricing anchors the premium tier, with admixture suppliers assuming rheology risk and warrantying compressive strength outcomes under integrated project delivery contracts. Three-tier pricing structure across certified performance, standard compliance, and economy commodity levels separates Sika AG and BASF from regional blenders and import-dependent traders. Cost compression in the economy tier is intensifying because naphtha and ethylene oxide feedstock volatility squeezes formulators lacking captive petrochemical supply. Residential builders and mid-tier contractors exhibit the highest price sensitivity, while NEOM and Qiddiya developers absorb performance-risk transfer premiums without material substitution.
Supply Chain Analysis
Regional distribution centers in Jebel Ali, Riyadh, and Dammam anchor hub-and-spoke patterns serving batch-plant operations across the Arabian Peninsula. Manufacturing concentration in Germany, China, and South Korea feeds specialty monomer supply for polycarboxylate ether superplasticizers, with European and Asian producers controlling PCE raw material output. Single-source vulnerability for PCE technology exposes regional blenders to freight cost spikes and currency mismatch risks. Distribution runs through direct technical salesforces for giga-project accounts, with stocked inventory channels handling mid-tier contractor volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. Saudi Building Code enforcement and SFDA technical regulations create a barrier-to-entry moat that rewards pre-qualified suppliers with regional testing capabilities while excluding uncertified imports from structural concrete applications.
For Market Incumbents: Acquire in-house quality laboratories and factory production control certifications to defend specification authority on Saudi Vision 2030 mandates. Backward integration into naphtha and ethylene oxide feedstocks mitigates margin compression from petrochemical price volatility. Capacity expansion in Riyadh formulation hubs captures procurement preference as NEOM and Red Sea Project timelines accelerate. For New Entrants and Emerging Players: Egyptian infrastructure acceleration opens a window for Gulf-based formulators with established logistics networks to capture first-mover positioning in the new administrative capital and Suez Canal development zones. The country's central construction authority issues performance standards aligned with regional Gulf frameworks, creating regulatory familiarity for compliant entrants. Digital dosing system partnerships with concrete batch-plant operators offer a service-revenue entry path beyond commodity supply. For Investors and Strategic Acquirers: Accelerated certification timeline compression on giga-projects is the leading indicator that technical service scarcity will deepen competitive moats for laboratory-equipped formulators. The five-to-ten year viability window favors acquisition targets with captive raw material supply and embedded field-technical teams. Watch for SFDA documentation pre-positioning as the signal of procurement-ready positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive naphtha and ethylene oxide supply stabilizes margin pools against raw material volatility. |
| Regional Formulation Laboratory Expansion | Riyadh-based testing capabilities compress certification timelines for Saudi Building Code compliance. |
| Digital Dosing System Deployment | IoT-enabled admixture metering creates aftermarket service revenue and customer lock-in beyond commodity supply. |
| Long-term Supply Agreement with Giga-Project Developers | Integrated project delivery contracts transfer rheology risk and warranty outcomes to admixture suppliers. |
| Joint Venture with Egyptian Distribution Networks | Cairo-Alexandria corridor development absorbs imported formulation expertise from Gulf-based suppliers. |
Research Methodology
Multi-period observation of admixture procurement volumes, certification timeline compression, and giga-project pipeline acceleration anchored the trend analysis, supplemented by interviews with concrete technologists, EPC contractor procurement leads, batch-plant operations managers, and SFDA regulatory affairs specialists. Secondary validation drew from Saudi Building Code enforcement records, Dubai Municipality structural regulation filings, Gulf Standardization Organization framework documentation, customs and trade data for construction chemical imports, and SEC 10-K disclosures from multinational formulators. Bottom-up segmentation modeling and top-down macroeconomic triangulation cross-checked volume and value estimates.
Input-output matrices mapped polycarboxylate ether technology adoption, self-consolidating concrete specification rates, and protective coatings intensity across infrastructure, commercial, residential, and industrial applications throughout the forecast period. Segmentation dimensions included product type grade tier, end-use industry vertical, regional production hub concentration, and certification compliance level. CAGRs were derived from regression analysis against construction spend forecasts and material intensity coefficients. Industry-specific inputs incorporated summer construction window economics above 45°C ambient temperatures and saline exposure service-life guarantees for offshore infrastructure.
The model assumes a particular technology adoption path for PCE superplasticizers; alternative pathways for naphthalene-based formulations or emerging bio-admixtures would alter the outlook for premium-tier pricing power. Forecasts reflect documented assumptions regarding Saudi Vision 2030 project delivery schedules and SFDA enforcement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Alum Market
Chemicals
Ferric Oxide Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Pyrimidine Market
Chemicals
Malic Acid Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
CHPTAC Market
Chemicals
Paint Stripper Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Welding Chemicals Market
Chemicals
SLS and LABSA Market
Chemicals
Cumene Market
Chemicals
Triethanolamine Market
Chemicals
Pyrogallol Market