
 United Kingdom Collagen Peptides Market | 2026-2036
United Kingdom Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Collagen Peptides Market Insights
Scotland's emerging biotech manufacturing corridor is reshaping domestic supply dynamics for collagen-derived ingredients. Rousselot leverages its specialized gelatin expertise to anchor premium pharmaceutical-grade supply chains. Gelita AG sustains competitive positioning through backward integration into raw material sourcing. Protein Works differentiates via direct-to-consumer channel control and flavor innovation in sports nutrition formats.
Collagen peptides comprise short-chain amino acid sequences derived from enzymatic hydrolysis of native collagen, typically achieving molecular weights between 2,000 and 5,000 Daltons for optimal bioavailability in human tissue repair and dermal matrix support. Hydrolyzed collagen dominates value generation due to its solubility advantages in functional beverage applications, while liquid collagen formats represent the fastest-growing delivery mechanism as convenience-seeking consumers shift from powder reconstitution. Nutraceuticals capture the largest margin pool among application segments, though cosmetics brands are accelerating procurement of marine-sourced variants for topical formulation integration.
The Food Standards Agency enforces novel food authorization for non-traditional collagen sources, while EFSA guidelines on health claims constrain marketing language around joint and skin benefits. BSI standards for food-grade gelatin purity create compliance thresholds that filter smaller importers. MHRA oversight of collagen-containing medical devices adds a secondary regulatory layer for wound care applications. Stakeholders must monitor evolving FSA enforcement patterns around marine collagen import documentation and anticipate whether post-Brexit divergence from EU novel food catalogs will accelerate or complicate product registration pathways.
Market Dynamics
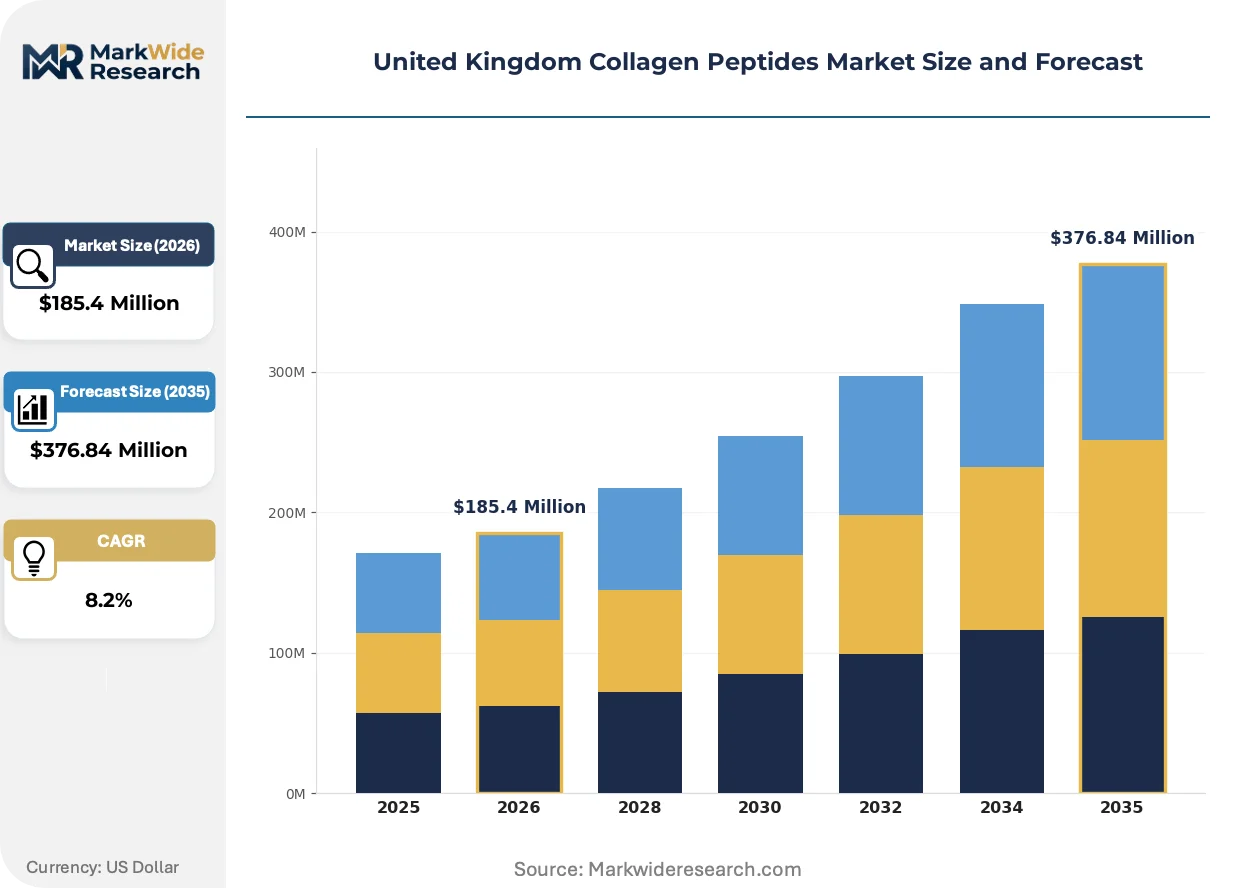
The United Kingdom collagen peptides market is being fundamentally restructured by the Food Standards Agency's novel food authorization framework, which extends development timelines for marine-sourced variants and creates a two-tier compliance landscape between established bovine/porcine suppliers and emerging entrants.
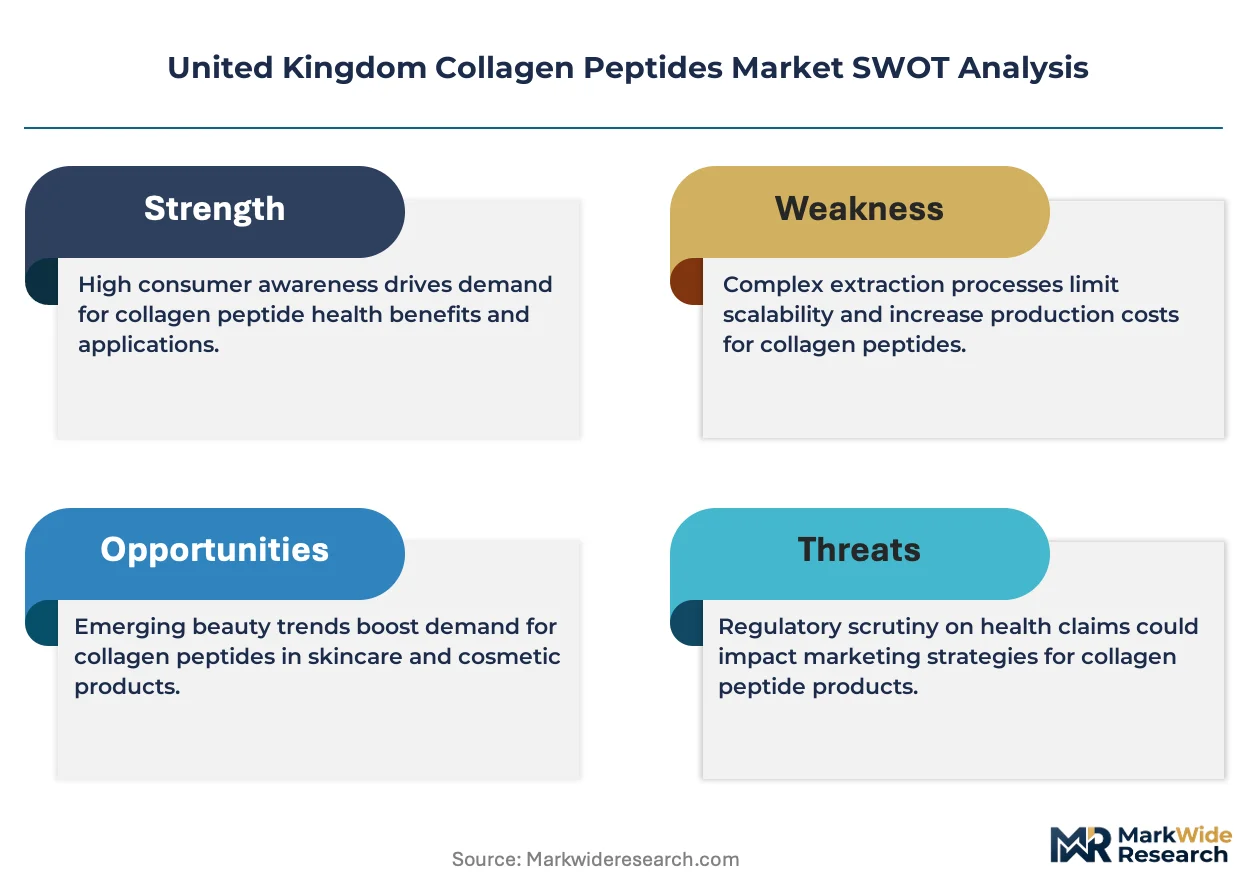
Growth Catalysts
- Nutraceutical demand from fitness corridors:England's metropolitan wellness clusters are absorbing hydrolyzed collagen powder at accelerating rates, driven by sports nutrition brands reformulating recovery products around clinically substantiated amino acid profiles.
- FSA novel food pathway maturation:The regulatory framework is stabilizing, giving larger manufacturers predictable registration costs and defensible positions against unapproved imports from non-UK suppliers.
- Marine sourcing technology:Advanced enzymatic hydrolysis systems are unlocking scalable extraction from North Atlantic fishery byproducts, diversifying raw material bases beyond traditional livestock origins.
Market Restraints
- Raw material concentration:Bovine hide supply chains concentrate in South American processing hubs, exposing UK formulators to currency volatility and shipping cost spikes.
- EFSA health claim constraints:The European Food Safety Authority's strict evidentiary standards for joint and skin benefit claims prevent direct-to-consumer messaging that drives category growth in less regulated markets.
- Technical solubility limitations:Marine-derived peptides exhibit inferior cold-water dissolution compared to mammalian equivalents, restricting their deployment in ready-to-drink functional beverages.
Strategic Opportunities
- Scotland's biotech manufacturing corridor:Aberdeen and Dundee clusters offer underutilized fermentation and purification capacity suitable for pharmaceutical-grade collagen peptide production.
- Medical device integration:MHRA-regulated wound care applications represent a high-margin channel where collagen's hemostatic properties command premium pricing against synthetic alternatives.
- Direct-to-consumer subscription models:Digital-native brands are bypassing traditional retail pharmacy distribution, capturing recurring revenue through personalized dosing regimens and flavor customization.
Industry Challenges
- Novel food dossier compilation expertise:The FSA's comprehensive toxicological and compositional data requirements exceed the regulatory affairs capabilities of most mid-sized UK ingredient suppliers.
- Cross-batch bioactivity standardization:Maintaining consistent molecular weight distributions and peptide chain lengths across production runs demands capital-intensive analytical infrastructure that smaller processors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Collagen Peptides Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $376.84 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Powder, Liquid Collagen Application: Nutraceuticals, Functional Foods, Cosmetics, Pharmaceuticals End User: Nutrition Companies, Cosmetic Brands, Healthcare Providers, Fitness Industry Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Rousselot, Gelita AG, Peptan UK, Protein Works, Collagen Solutions, Weishardt Holding SA, Nitta Gelatin, Tessenderlo Group, Vital Proteins LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Collagen Peptides Market Trends and Innovations
Delivery format innovation is compressing the traditional powder-dominant category, with liquid and ready-to-drink formulations capturing convenience-oriented consumers who reject reconstitution steps. Technology convergence between enzymatic processing and precision fermentation is simultaneously expanding source material options and improving functional performance.
Enzymatic hydrolysis technology is migrating from batch reactor configurations toward continuous flow systems that reduce processing time and improve peptide consistency. Large-scale nutraceutical contract manufacturers in England are retrofitting existing gelatin facilities with membrane filtration upgrades. This technological shift is compressing capital requirements for mid-tier entrants while raising quality thresholds that commodity importers struggle to meet.
The Food Standards Agency's evolving enforcement posture on marine collagen import documentation is tightening traceability requirements for non-traditional sources. Processors must now demonstrate chain-of-custody from fishery to finished ingredient, with particular scrutiny of heavy metal and allergen profiles. Scotland-based manufacturers with established North Atlantic supplier relationships are responding fastest, while continental European importers face extended customs clearance delays.
Consumer purchasing patterns are fragmenting across channel types, with pharmacy loyalty eroding in favor of specialized online retailers and brand-direct storefronts. Sports nutrition buyers in London and Manchester are consolidating purchases through subscription platforms that bundle collagen with complementary supplements. This behavioral shift is most visible among 25-40 year-old urban professionals who prioritize convenience over professional consultation.
United Kingdom Collagen Peptides Market Segmentation
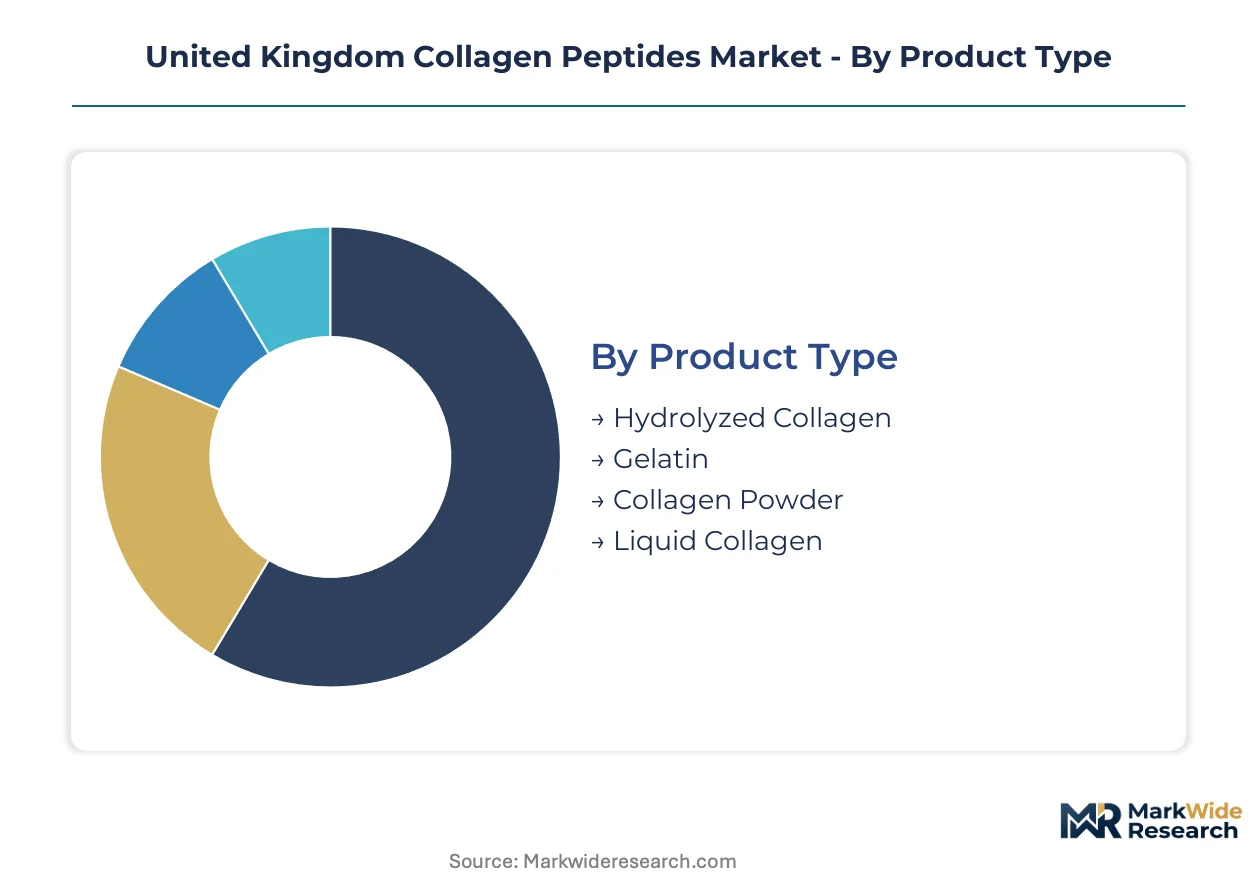
Segmentation in the United Kingdom collagen peptides market reveals divergent velocity profiles across product formats and channel structures. Cycle times vary dramatically, with liquid formats and online channels turning inventory faster than powder variants and traditional retail.
Product Type:
Hydrolyzed collagen and liquid formats command the shortest replenishment cycles, while gelatin and powder variants tie up working capital longer due to bulk purchasing patterns and slower consumption rates.
- Hydrolyzed Collagen:Enzymatically cleaved peptides achieve molecular weights between 2,000 and 5,000 Daltons for optimal intestinal absorption. Sports nutrition manufacturers in England's metropolitan corridors absorb volumes fastest, driven by clinically substantiated amino acid profiles in recovery formulations.
- Liquid Collagen:Pre-dissolved aqueous solutions eliminate reconstitution friction for convenience-seeking consumers. Manchester and London subscription platforms report the steepest uptake acceleration among 25-40 year-old urban professionals prioritizing grab-and-go consumption.
- Gelatin:Partially hydrolyzed collagen with gelling functionality serves food texture applications and capsule shells.
- Collagen Powder:Bulk dry formats retain cost advantages for price-sensitive buyers and recipe-flexible home preparation.
Hydrolyzed collagen anchors the volume base while liquid collagen gains share at the steepest rate.
Application:
Margin concentration and regulatory burden separate nutraceuticals and pharmaceuticals from functional foods and cosmetics, with the former pair demanding longer development timelines but capturing superior returns.
- Nutraceuticals:Dietary supplement formulations dominate procurement volumes, with EFSA health claim constraints forcing indirect benefit messaging. England's fitness corridors absorb hydrolyzed powder at rates exceeding other geographies within the United Kingdom.
- Pharmaceuticals:MHRA-regulated wound care and drug delivery applications command premium pricing against synthetic alternatives. Scotland's emerging biotech manufacturing corridor is capturing pharmaceutical-grade production contracts.
- Functional Foods:Beverage and snack fortification applications face FSA novel food authorization hurdles for marine-sourced variants.
- Cosmetics:Topical dermal matrix support products accelerate marine collagen procurement despite solubility limitations in cold-water formulations.
Nutraceuticals generate the largest margin pool while cosmetics marine sourcing expands most quickly.
End User:
Procurement sophistication and volume scale distinguish nutrition companies from cosmetic brands, with healthcare providers and fitness industry buyers occupying intermediate positions on both dimensions.
- Nutrition Companies:Formulators of sports recovery and wellness products drive bulk hydrolyzed collagen demand. Direct-to-consumer channel control allows flavor innovation and personalized dosing regimens that bypass traditional pharmacy distribution.
- Healthcare Providers:Hospital systems and wound care clinics source pharmaceutical-grade materials under MHRA oversight. Procurement concentrates on hemostatic and tissue repair applications where collagen commands synthetic-premium pricing.
- Cosmetic Brands:Topical formulation specialists prioritize marine-sourced peptides for dermal matrix marketing claims.
- Fitness Industry:Gyms and personal trainer networks distribute through affiliated retail or direct recommendation channels.
Nutrition companies anchor the volume base while healthcare providers expand procurement fastest.
Distribution Channel:
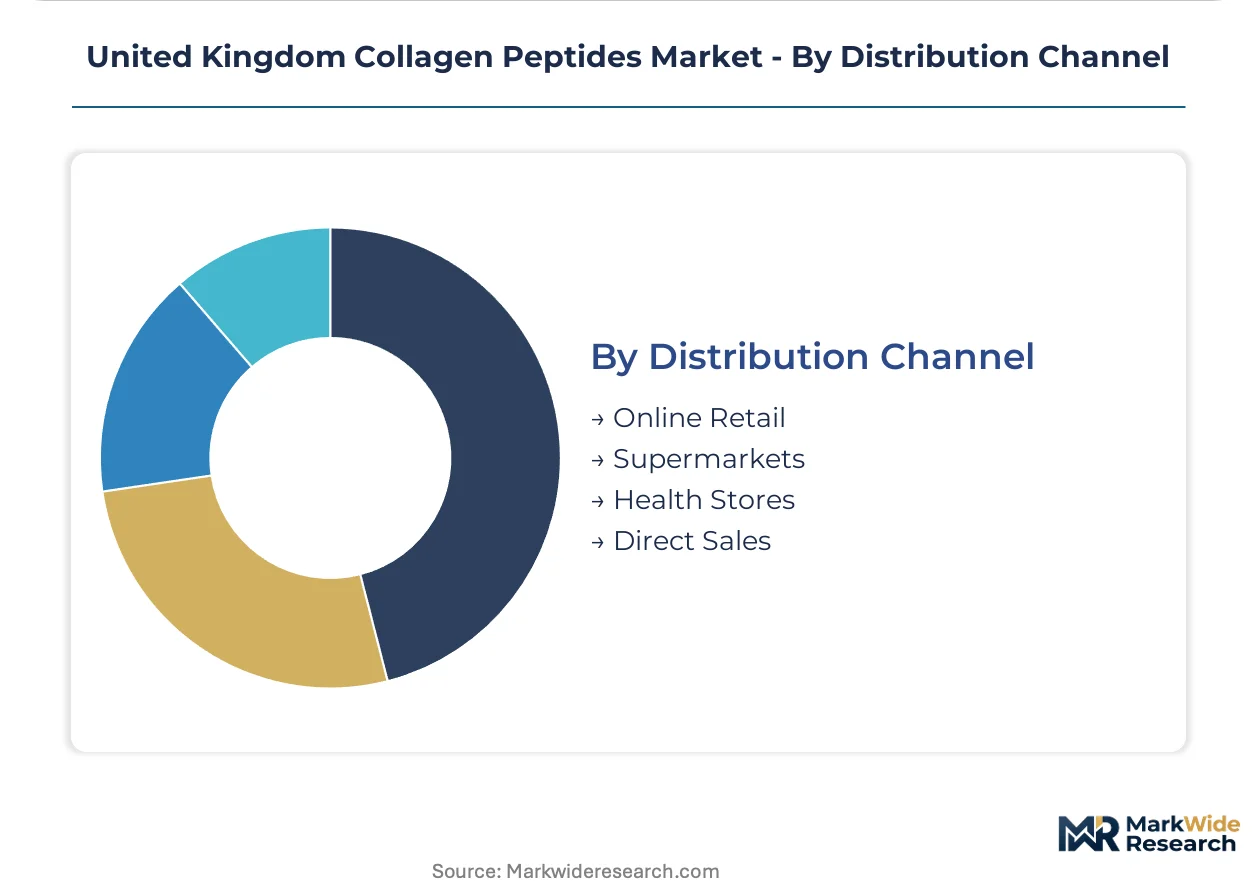
Customer acquisition economics and inventory velocity favor online retail and direct sales over supermarkets and health stores, with the latter pair requiring slotting fees and longer payback periods.
- Online Retail:Specialized supplement platforms and generalist marketplaces capture subscription-driven recurring revenue. Digital-native brands leverage this channel for flavor customization and personalized regimen bundling.
- Direct Sales:Brand-controlled storefronts and subscription platforms eliminate intermediary margins. Protein Works and comparable direct-to-consumer operators exploit this structure for customer data capture and loyalty program deployment.
- Supermarkets:Mass retail placement demands trade spend and competes on price with private label alternatives.
- Health Stores:Pharmacy and specialist retail retain professional consultation value for skeptical first-time buyers.
Online retail anchors the volume base while direct sales gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material processing for collagen peptides concentrates in South American bovine hide hubs and North Atlantic fishery zones, exposing United Kingdom formulators to currency volatility and shipping cost spikes. England's metropolitan wellness corridors absorb hydrolyzed powder volumes fastest, while Scotland's biotech manufacturing corridor reshapes domestic supply dynamics.
England
London and Manchester subscription platforms report steepest uptake acceleration among 25-40 year-old urban professionals prioritizing grab-and-go liquid collagen consumption. The Food Standards Agency enforces novel food authorization for marine-sourced variants entering through eastern ports. Sports nutrition manufacturers in Birmingham and Leeds retrofit existing gelatin facilities with membrane filtration upgrades for peptide consistency.
Scotland
Aberdeen and Dundee clusters offer underutilized fermentation and purification capacity suitable for pharmaceutical-grade collagen peptide production under MHRA oversight. The Scottish Environment Protection Agency monitors effluent discharge from enzymatic hydrolysis operations. North Atlantic fishery byproduct supply chains from Peterhead processors diversify raw material bases beyond traditional livestock origins.
Wales
Cardiff-based nutraceutical contract manufacturers serve mid-tier brands seeking FSA-compliant novel food dossier compilation support. Natural Resources Wales regulates wastewater from collagen extraction facilities in coastal processing zones. The Welsh Government's life sciences investment programs target marine biotechnology scale-up in Swansea Bay innovation corridors.
Northern Ireland
Belfast pharmaceutical-grade gelatin producers supply cross-border wound care applications under dual UK-EU regulatory alignment pressures. The Northern Ireland Environment Agency enforces REACH-equivalent chemical safety standards for imported raw materials. Port of Belfast logistics hubs face extended customs clearance delays for continental European collagen peptide imports.
United Kingdom Collagen Peptides Market Competitive Landscape
Specialized gelatin multinationals and direct-to-consumer digital natives split the market between premium pharmaceutical-grade supply chains and convenience-oriented subscription platforms. The vendor base concentrates around three strategic archetypes: backward-integrated raw material processors with captive hide and fishery sourcing, nutraceutical formulators with flavor innovation capabilities, and medical-grade specialists serving MHRA-regulated wound care applications. Dominant competitive moves include membrane filtration technology licensing for mid-tier entrants and direct-to-consumer channel control bypassing traditional pharmacy distribution.
Among continental European raw material processors, Rousselot and Gelita AG exemplify the backward-integrated archetype with specialized gelatin expertise anchoring premium supply chains. Protein Works occupies a position within the direct-to-consumer tier, leveraging subscription platform control and flavor customization to capture recurring revenue from fitness-conscious demographics.
| Leading Market Players |
|---|
| Rousselot |
| Gelita AG |
| Peptan UK |
| Protein Works |
| Collagen Solutions |
| Weishardt Holding SA |
| Nitta Gelatin |
| Tessenderlo Group |
| Vital Proteins LLC |
| Others |
Pricing and Supply Chain Analysis
Freight corridors connecting Rotterdam to Felixstowe transmit South American hide shipping cost volatility directly into UK formulator procurement budgets, compressing margins on economy-grade collagen while pharmaceutical-grade variants retain pricing power through MHRA certification scarcity.
Pricing Analysis
FSA novel food authorization dictates the pricing tier structure across the United Kingdom collagen peptides market, separating MHRA-certified pharmaceutical grades from commodity nutraceutical powders. Premium-mid-economy pricing differentiation rests on molecular weight consistency and peptide chain length verification, with cold-water solubility performance commanding additional margin. Cost compression in standard-grade hydrolyzed collagen intensifies because Brazilian real volatility elevates raw material landed costs. Nutrition companies exhibit highest price sensitivity due to subscription model pressure, while wound care clinics accept premium pricing for hemostatic-grade materials.
Supply Chain Analysis
Bovine hide feedstock draws from Brazilian and Argentine processing hubs, with North Atlantic fishery byproducts diversifying marine-sourced peptide origins. Enzymatic hydrolysis equipment, membrane filtration systems, and analytical testing infrastructure constitute critical capital dependencies. Single-source vulnerability concentrates in South American hide supply chains exposed to currency fluctuation and port congestion. Distribution runs through direct-to-consumer subscription platforms, specialized online retailers, and pharmacy networks, with brand-controlled channels capturing superior margin retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized regulatory dossier compilation expertise represents the scarcest capability in this market, filtering mid-sized processors from FSA novel food approval pathways and concentrating premium production contracts among incumbents with dedicated toxicological data infrastructure.
For Market Incumbents: Harden supply chain resilience through captive sourcing partnerships with Peterhead fishery processors, insulating against South American currency volatility. Deepen backward integration into North Atlantic marine raw materials before continental European competitors secure equivalent traceability documentation. Lock in pharmaceutical-grade capacity expansion at Aberdeen biotech clusters to preempt emerging entrants from MHRA-regulated wound care contracts. For New Entrants and Emerging Players: Pursue liquid collagen format innovation targeting Manchester and London subscription platforms, where convenience-seeking demographics show lowest brand loyalty and highest trial willingness. Scotland's underutilized fermentation capacity offers white-space manufacturing access without England's saturated sports nutrition competition. Lead with flavor customization and personalized dosing regimens that incumbent powder specialists cannot replicate without channel restructuring. For Investors and Strategic Acquirers: Carve-out targets emerge from continental European gelatin multinationals seeking to divest non-core UK nutraceutical assets. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale, favoring acquisition of FSA-authorized facilities over greenfield capacity builds. Watch for FSA enforcement pattern shifts on marine collagen import documentation as inflection indicator for compliant asset valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FSA Novel Food Dossier Investment | Defensible market access against unapproved continental European imports. |
| Scotland Biotech Corridor Capacity Expansion | Captures pharmaceutical-grade production contracts under MHRA oversight. |
| Direct-to-Consumer Subscription Platform Buildout | Eliminates pharmacy intermediary margins and enables flavor personalization. |
| North Atlantic Fishery Byproduct Integration | Diversifies raw material base beyond volatile South American hide supply chains. |
| Continuous Flow Enzymatic System Upgrade | Compresses processing time and improves peptide consistency for premium tiers. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs directors at novel food authorization consultancies, procurement leads at England-based sports nutrition formulators, and technical R&D managers at Scottish biotech manufacturing clusters, then refined through secondary validation against FSA enforcement bulletins, EFSA health claim registers, MHRA medical device guidance documents, and customs trade flow records, with bottom-up volume estimates triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and distribution channel. CAGRs were derived from regression analysis of historical adoption curves and forward-looking capacity expansion announcements, incorporating EFSA health claim constraint evolution and FSA novel food pathway maturation as industry-specific forecast inputs.
Sensitivities concentrate around FSA enforcement intensity on marine collagen import documentation, EFSA evidentiary standard revisions for joint and skin benefit claims, and South American currency volatility transmission into raw material costs. Cross-checking against customs import volume data and GMP facility inspection records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Opacifiers Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Specialty Sorbents Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Polyimide Coatings Market
Specialty Compounds
Pneumatic Seal Market
Specialty Compounds
Galactoarabinan Market