
 Middle East and Africa Adhesives Market | 2026-2036
Middle East and Africa Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Adhesives Market Outlook
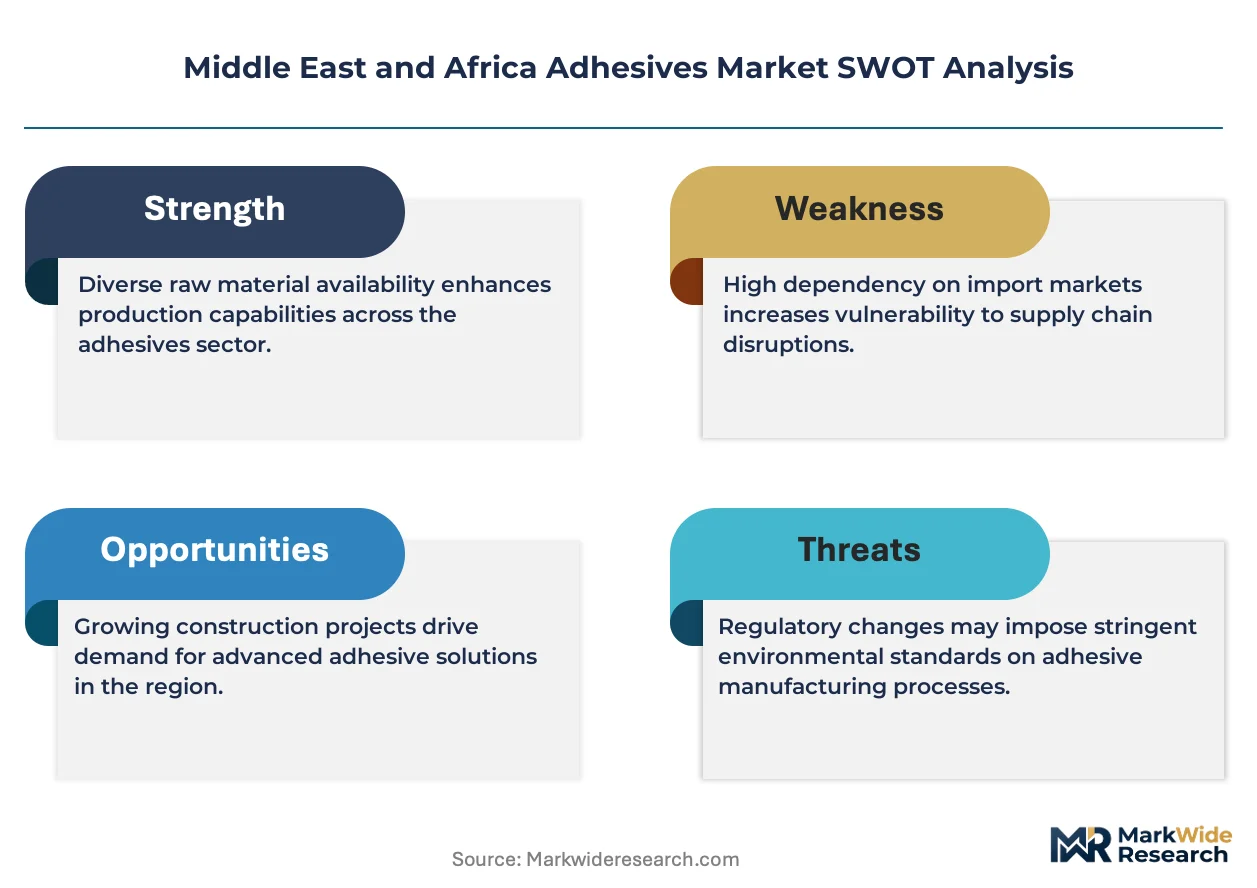
Asset-light leasing models for specialty chemical production equipment are rewriting competitive entry dynamics across the Middle East and Africa adhesives landscape. Henkel AG & Co. KGaA leverages its regional formulation centers to sustain proximity advantages in hot melt and reactive systems. Dow anchors its position through captive supply of petrochemical feedstocks from Gulf-based crackers. Sika AG specializes in construction-grade polyurethane and epoxy platforms, dominating infrastructure bonding specifications across the GCC.
Adhesives are non-metallic substances applied to surfaces that develop structural attachment through chemical polymerization, physical drying, or cooling solidification, with bond strengths typically ranging from flexible pressure-sensitive holds to rigid structural joints exceeding substrate failure limits. Their primary purpose is to replace or supplement mechanical fasteners in assemblies where weight reduction, stress distribution, or sealed interfaces matter. Epoxy formulations command premium positioning in automotive and electronics bonding where thermal resistance and dimensional stability justify higher formulation costs. Water-based technology is gaining fastest in packaging and light industrial applications as environmental compliance tightens across the region, though solvent-based systems retain share in high-performance coating and sealing roles where rapid cure and chemical resistance remain non-negotiable.
Saudi Arabia's SFDA and the UAE's MOHAP enforce product safety frameworks that extend into industrial chemical labeling and hazard communication, while REACH-aligned import standards from European trading partners filter formulation chemistry available to regional blenders. South Africa's Department of Forestry, Fisheries and the Environment applies air quality regulations that restrict solvent-based adhesive use in populated industrial zones, channeling investment toward compliant water-based and reactive alternatives. Stakeholders must monitor how Gulf state local content requirements and carbon intensity benchmarks reshape supplier qualification criteria for megaproject procurement.
Market Dynamics
Megaproject procurement in Saudi Arabia and the UAE is compressing qualification timelines for adhesive suppliers while Gulf state local content mandates reshape supply chain geography.
Growth Catalysts
- SFDA and MOHAP safety frameworks:Saudi Arabia's SFDA and the UAE's MOHAP enforce industrial chemical labeling standards that elevate compliant formulation houses above informal competitors in megaproject tenders.
- NEOM and Red Sea construction:Saudi Arabia's gigaproject pipeline generates concentrated demand for structural bonding systems in facade and infrastructure applications at volumes unseen elsewhere in the region.
- Water-based technology maturation:Advances in emulsion polymerization are closing the performance gap with solvent systems in packaging and light industrial bonding across South African manufacturing zones.
Market Restraints
- Petrochemical feedstock volatility:Regional blenders remain exposed to naphtha and propylene price swings from Gulf-based crackers, compressing margin predictability for commodity-grade hot melt producers.
- Specialty resin import concentration:High-performance epoxy and polyurethane intermediates concentrate through Jebel Ali and Port of Durban, creating single-point vulnerability for inland African markets.
- Cure-rate limitations in reactive systems:Two-component epoxies and polyurethanes face throughput constraints in high-speed automotive assembly lines versus mechanical fastening alternatives.
Strategic Opportunities
- East African infrastructure buildout:Ethiopia and Kenya transport corridor investments lack established adhesive supply infrastructure, creating first-mover positioning for compliant formulation entrants.
- Carbon intensity benchmarking:Gulf state procurement offices are embedding embodied carbon thresholds in megaproject specifications, advantaging low-VOC water-based and bio-based platform suppliers.
- UV-curable technology convergence:Hybrid UV/moisture cure systems are penetrating electronics and medical device assembly in South Africa's industrial heartland where precision bonding meets throughput demands.
Industry Challenges
- Formulation chemist scarcity:The region lacks sufficient trained polymer scientists capable of adapting global platforms to local substrate conditions and climate extremes.
- REACH-aligned import documentation:European trading partner chemical disclosure requirements create extended qualification cycles for regional blenders seeking cross-border supply contracts.
- Legacy solvent system retrofit costs:South African converters face capital outlays for drying equipment and ventilation upgrades to meet DFFE air quality enforcement in populated industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Adhesives Market |
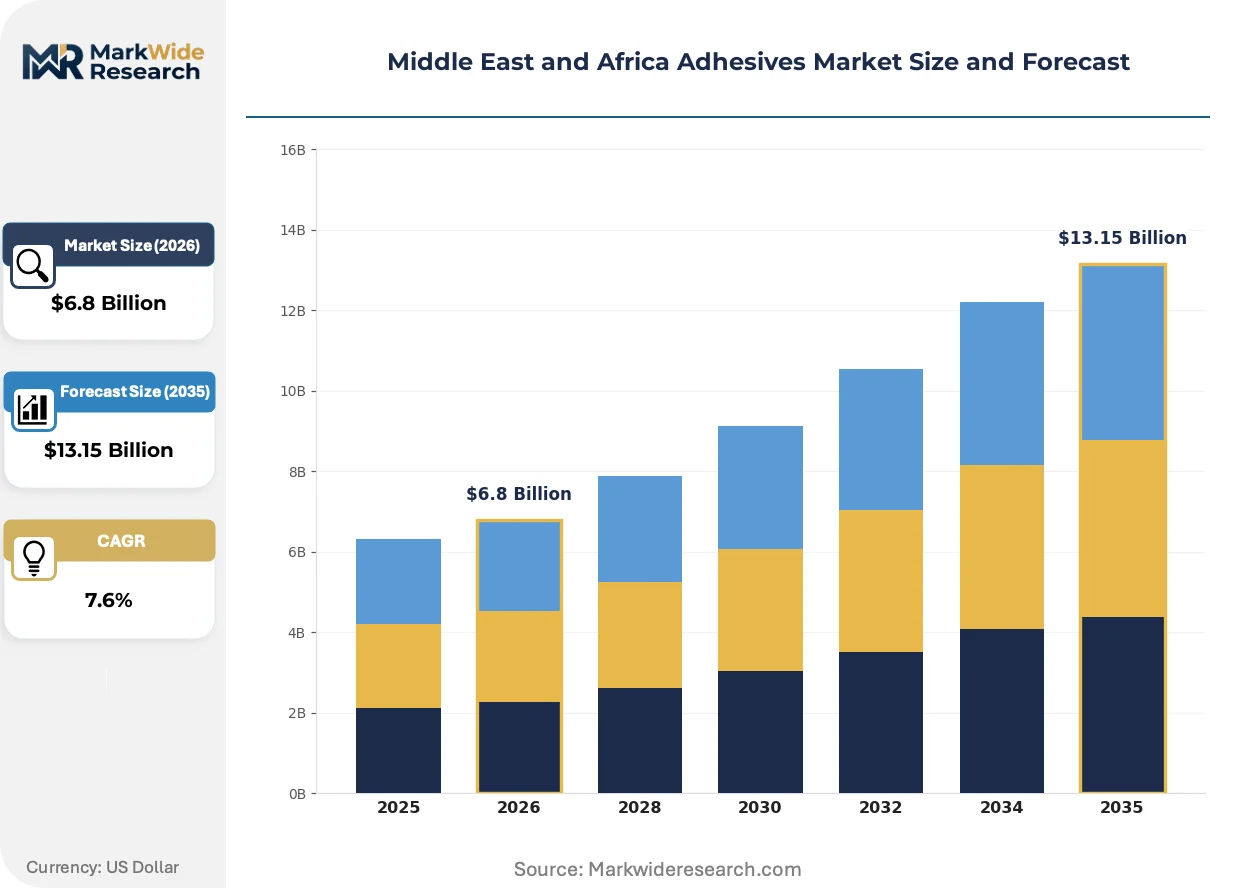
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone End User: Construction, Automotive, Electronics, Packaging Technology: Water-based, Solvent-based, Hot Melt, Reactive Application: Bonding, Coating, Sealing, Filling |
| Companies Covered | Henkel AG & Co. KGaA, Dow, Arkema Group, H.B. Fuller Company, Sika AG, 3M Company, Huntsman International LLC, Avery Denison Corporation, The Industrial Group Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Adhesives Market Strategic Shifts
Adhesive markets across the Middle East and Africa are experiencing platform substitution driven by environmental compliance, construction methodology evolution, and procurement digitization in megaproject channels.
Smart dispensing and automated meter-mix equipment is digitizing application consistency in GCC structural bonding operations. Construction contractors at NEOM and Red Sea developments are deploying IoT-enabled dispensing systems to reduce waste and document cure parameters for quality assurance. The technology is digitizing labor productivity benchmarks while compressing skill requirements for field application crews.
South Africa's Department of Forestry, Fisheries and the Environment applies air quality regulations that restrict solvent-based adhesive use in populated industrial zones. The enforcement channels investment toward compliant water-based and reactive alternatives among packaging converters and furniture manufacturers. Johannesburg and Durban industrial precincts are witnessing accelerated capital redeployment into low-emission formulation platforms.
Asset-light equipment leasing is altering capital deployment patterns among regional adhesive compounders. Specialty chemical production equipment lessors are enabling mid-scale entrants to bypass fixed-asset barriers in Egyptian and Moroccan markets. The model is most visible in hot melt and pressure-sensitive adhesive segments where batch flexibility outweighs scale economies.
Middle East and Africa Adhesives Market Segmentation
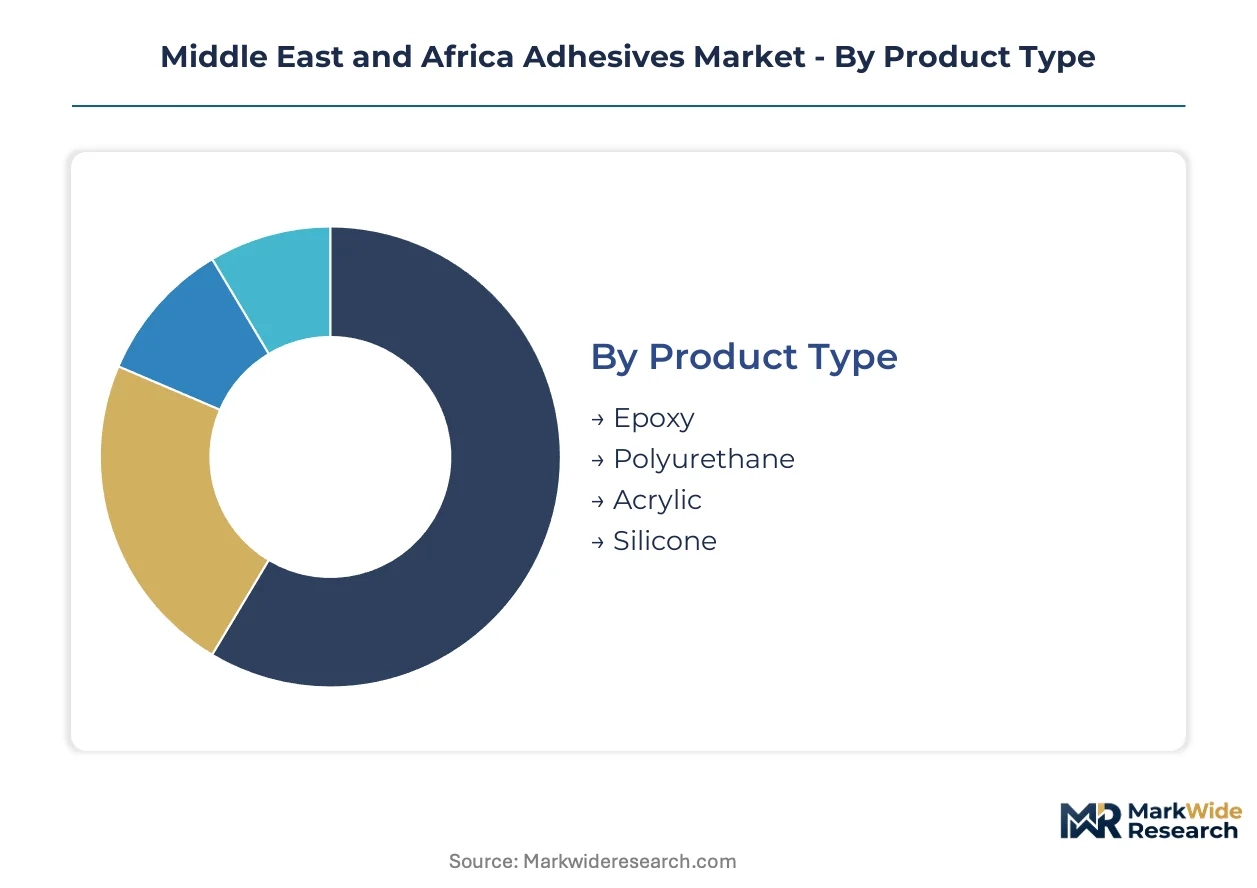
Adhesive selection across the Middle East and Africa hinges on substrate compatibility, cure conditions, and project-specific performance thresholds. Procurement teams in Saudi megaprojects and South African manufacturing zones weight these dimensions differently, creating distinct segment performance profiles.
Product Type:
Cost tier positioning separates commodity formulations from premium structural platforms in regional procurement.
- Epoxy:Two-component thermosetting systems deliver superior thermal resistance and dimensional stability under mechanical load. NEOM infrastructure specifications favor epoxy platforms for structural steel bonding and composite facade attachment where substrate failure must precede joint failure.
- Polyurethane:Flexible elastomeric bonds accommodate thermal cycling and vibration across dissimilar materials. UAE construction contractors specify polyurethane for expansion joint sealing and curtain wall glazing where movement tolerance exceeds 15% elongation.
- Acrylic:Rapid-cure formulations dominate South African packaging lines and light industrial assembly.
- Silicone:High-temperature stability serves HVAC ductwork and automotive underhood applications.
Epoxy commands the established base in Gulf megaproject procurement. The steepest expansion runs through polyurethane as facade system complexity increases across GCC commercial towers.
End User:
Application environment dictates adhesive specification intensity from field-cured construction joints to cleanroom electronics assembly.
- Construction:Structural bonding, waterproofing, and facade integration consume the highest formulation volumes. Saudi Arabia's gigaproject pipeline concentrates demand for high-performance systems capable of withstanding desert thermal cycling and salt-laden coastal atmospheres.
- Automotive:Lightweighting imperatives drive adhesive substitution for spot welding in panel bonding and NVH reduction. Moroccan and South African vehicle assembly plants are qualifying structural acrylics and epoxy platforms for body-in-white applications.
- Electronics:Miniaturization trends favor precision dispensing of conductive and thermally conductive adhesives.
- Packaging:Water-based systems dominate folding carton and corrugated bonding under South African DFFE enforcement.
Construction anchors volume concentration through 2035. Electronics is gaining share fastest as regional PCB assembly and medical device manufacturing scales in South Africa and Egypt.
Technology:
Environmental compliance trajectories are reordering technology preference curves across national regulatory jurisdictions.
- Water-based:Acrylic and polyurethane emulsions eliminate VOC emissions during drying. South African packaging converters are retrofitting lines to meet DFFE air quality mandates in Johannesburg and Durban industrial precincts.
- Solvent-based:Rapid evaporation cure retains dominance in high-performance coating and sealing where chemical resistance and outdoor durability are non-negotiable. Saudi and UAE specifications still permit solvent systems for infrastructure waterproofing.
- Hot Melt:Thermoplastic EVA and polyolefin formulations serve high-speed packaging and product assembly.
- Reactive:Two-component epoxies and polyurethanes cure through chemical polymerization rather than solvent loss.
Solvent-based technology holds the incumbent position in GCC construction. Water-based platforms are expanding most quickly as South African enforcement tightens and Gulf procurement offices embed carbon intensity benchmarks.
Application:
Functional purpose determines formulation specification depth from structural load transfer to surface protection.
- Bonding:Structural attachment replaces or supplements mechanical fasteners across load-bearing assemblies. NEOM and Red Sea developments specify structural acrylics and epoxies for steel-composite hybrid construction.
- Sealing:Elastomeric joints prevent moisture and air infiltration across building envelopes and transportation platforms. UAE curtain wall contractors specify silicone and polyurethane sealants for high-rise glazing systems.
- Coating:Protective films adhere to substrates for corrosion resistance and aesthetic finish.
- Filling:Gap-filling formulations accommodate irregular joint geometries in renovation and repair.
Bonding captures the largest formulation volume. Sealing is climbing the fastest as building envelope performance standards tighten across Saudi and UAE commercial construction codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction procurement teams in Saudi Arabia and megaproject developers in the UAE dominate adhesive demand across the Middle East and Africa, while South African packaging converters and Egyptian industrial manufacturers anchor secondary volume concentrations.
Saudi Arabia
NEOM and Red Sea gigaprojects generate structural bonding demand at scales unmatched elsewhere in the region. SFDA industrial chemical labeling standards elevate compliant formulation houses above informal competitors in megaproject tenders. Riyadh and the Eastern Province concentrate procurement activity where high-performance epoxy and polyurethane systems face desert thermal cycling requirements.
United Arab Emirates
MOHAP safety frameworks enforce hazard communication standards that filter supplier participation in Dubai and Abu Dhabi construction channels. Curtain wall contractors specify silicone and polyurethane sealants for high-rise glazing systems across the emirates. Jebel Ali serves as the dominant import gateway for specialty resin intermediates feeding Gulf megaproject demand.
South Africa
The Department of Forestry, Fisheries and the Environment applies air quality regulations that restrict solvent-based adhesive use in Johannesburg and Durban industrial precincts. Packaging converters retrofit lines toward water-based acrylic emulsions under DFFE enforcement pressure. Automotive assembly plants in Eastern Cape and Gauteng qualify structural acrylics for body-in-white lightweighting applications.
Egypt
Asset-light equipment leasing models enable mid-scale adhesive compounders to bypass fixed-asset barriers in Cairo and Alexandria production zones. The country's national environmental regulator channels investment toward compliant water-based formulations in populated industrial areas. Suez Canal economic zone developments attract packaging and light industrial adhesive suppliers seeking African market access.
Morocco
Vehicle assembly plants in Casablanca and Tangier Med industrial zones drive adhesive substitution for spot welding in panel bonding applications. National industrial standards align with European trading partner chemical disclosure requirements, extending qualification cycles for regional blenders. Automotive OEM procurement offices embed performance thresholds that favor reactive system suppliers with proven North African logistics capabilities.
Middle East and Africa Adhesives Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates premium formulation capabilities among multinational chemical houses while fragmenting commodity-grade supply among regional blenders. Three strategic archetypes dominate: petrochemical-integrated feedstock suppliers, construction-specialist system houses, and packaging-focused emulsion compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves as entrants seek qualification for Saudi megaproject procurement channels.
Among European-integrated chemical conglomerates, Henkel AG & Co. KGaA and Sika AG exemplify the construction-specialist archetype, while Dow represents the petrochemical-integrated feedstock position. These three companies anchor the premium-tier competitive vector through proximity advantages in Gulf-based formulation centers and captive supply relationships with regional crackers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Dow |
| Arkema Group |
| H.B. Fuller Company |
| Sika AG |
| 3M Company |
| Huntsman International LLC |
| Avery Denison Corporation |
| The Industrial Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Gulf-based petrochemical crackers is compressing margin predictability for commodity-grade adhesive producers while elevating bargaining leverage for buyers of solvent-based formulations. This utilization dynamic forces regional blenders toward asset-light leasing models and specialty platform differentiation to escape price-driven commoditization.
Pricing Analysis
Certification level (SFDA/MOHAP-compliant versus informal) creates the primary spread between premium and economy tiers in megaproject procurement. Three-tier pricing structure across project-qualified, standard industrial, and commodity spot levels dominates transactional flows. Pricing pressure stems from feedstock volatility in naphtha and propylene markets, compressing margins for hot melt producers without captive supply. Packaging converters in South African industrial zones exhibit highest price sensitivity due to DFFE compliance retrofit costs, while NEOM procurement offices prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms from Gulf megaproject developers are forcing working capital restructuring among regional compounders without petrochemical-integrated balance sheets. Geographic supply concentrates in Saudi Arabia, the UAE, and South Africa for formulation capacity, with specialty epoxy and polyurethane intermediates sourcing from European and Asian producers. Raw material dependencies center on propylene derivatives, acrylic monomers, and isocyanate intermediates. Single-source vulnerability runs through Jebel Ali and Port of Durban as import gateways for inland African markets. Distribution runs through direct specification sales for construction-grade systems and chemical distributor networks for industrial maintenance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based technology maturation is disrupting incumbent solvent-system positions as Gulf procurement offices embed carbon intensity benchmarks and South African DFFE enforcement tightens. This regulatory-technological convergence compresses qualification timelines while opening white-space for compliant formulation entrants.
For Market Incumbents: Harden qualification moats by deepening captive feedstock relationships with Gulf crackers and accelerating certification investment for SFDA/MOHAP megaproject compliance. Expand technical service capabilities in Riyadh and Dubai to defend against asset-light leasing entrants targeting mid-scale packaging converters. Prioritize backward integration into emulsion polymerization to offset raw material volatility exposure.
For New Entrants and Emerging Players: East African transport corridor investments in Ethiopia and Kenya present adhesive supply infrastructure gaps where first-mover positioning remains available. Target packaging converters in Egyptian and Moroccan industrial zones through equipment-leasing partnerships that bypass fixed-asset barriers. Pursue go-to-market alignment with European trading partner REACH documentation capabilities to accelerate cross-border qualification cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among construction-specialist system houses with established megaproject specification relationships. Long-term viability favors formulation platforms with demonstrated climate adaptation for desert thermal cycling and salt-laden coastal exposure. Monitor carbon intensity benchmark adoption velocity in Gulf state procurement offices as inflection indicator for water-based and bio-based platform acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emulsion Polymerization | Captive acrylic production reduces exposure to monomer price volatility from Asian suppliers. |
| SFDA/MOHAP Certification Investment | Compliance elevates formulation houses above informal competitors in Saudi and UAE megaproject tenders. |
| Asset-Light Equipment Leasing Partnerships | Leasing models enable mid-scale entrants to bypass fixed-asset barriers in Egyptian and Moroccan markets. |
| East African Distribution Infrastructure Buildout | Ethiopia and Kenya corridor investments lack established adhesive supply networks, creating first-mover positioning. |
| UV-Curable Technology Platform Development | Hybrid cure systems penetrate South African electronics assembly where precision bonding meets throughput demands. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with adhesive plant managers, procurement leads at GCC construction contractors, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, Gulf petrochemical industry reports, and regulatory filings from SFDA and MOHAP. Bottom-up volume modeling from end-use segment consumption patterns was triangulated against top-down value estimates derived from regional production capacity and import flow analysis.
Forecast inputs across the projection horizon incorporated product type segmentation by chemistry platform, technology tier by environmental compliance trajectory, end-use intensity from construction methodology evolution, and regional regulatory cluster differentiation. CAGRs were derived from elasticity-adjusted demand projections tied to megaproject pipeline visibility and manufacturing sector capital expenditure plans. Modeled variables included formulation chemist scarcity constraints, REACH-aligned import documentation cycle times, and carbon intensity benchmark adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by petrochemical-integrated suppliers or accelerated DFFE enforcement beyond current trajectories would shift outcomes. Macroeconomic deviation in Gulf construction spending, regulatory harmonization changes, or breakthrough cure-rate improvements in reactive systems would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Glass Adhesive Market
Adhesives & Sealants
Packaging Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Tile and Stone Adhesive Market
Adhesives & Sealants
Pvc Based Adhesive Market
Adhesives & Sealants
UV-Curable Adhesives Market