
 Middle East and Africa Solar PV Inverters Market | 2026-2036
Middle East and Africa Solar PV Inverters Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Solar PV Inverters Market Foresight
Silicon carbide is repositioning power semiconductor economics in solar PV inverters across the Middle East and Africa, trimming switching losses and enabling higher power density in desert-rated enclosures. Huawei Technologies leverages its integrated digital power platform to dominate utility-scale deployments in Saudi Arabia and Egypt. SMA Solar Technology anchors its regional position through localized service networks and thermal engineering optimized for ambient temperatures above 50°C. Sungrow Power Supply competes aggressively on cost-adjusted efficiency metrics in South African commercial and industrial rooftop segments.
A solar PV inverter converts direct current generated by photovoltaic modules into grid-compliant alternating current, with modern units achieving maximum power point tracking efficiencies above 99% and operating across voltage windows from 200V to 1500V depending on system architecture. String inverters occupy the largest installed base across Middle Eastern utility projects due to modular redundancy and lower balance-of-system costs at scale. Hybrid inverters represent the fastest-growing product category as Nigerian and Kenyan off-grid commercial users pair solar generation with lithium-ion storage to circumvent grid instability. Three-phase technology leads technology segmentation in utility procurement, while single-phase units sustain residential growth in Moroccan and Tunisian distributed solar programs.
Saudi Arabia's SFDA-equivalent energy regulator and South Africa's NERSA enforce grid code compliance that mandates reactive power control and low-voltage ride-through capabilities, effectively filtering out uncertified inverter suppliers. The UAE's MOHAP-aligned standardization body and Morocco's national electricity utility ONEE specify IEC 62109 and IEEE 1547-derived testing protocols that extend product qualification timelines. Egypt's NREA and Israel's Public Utilities Authority impose local content requirements that force manufacturers to establish assembly or warehousing presence. Stakeholders must monitor how divergent certification timelines across these jurisdictions affect project commissioning schedules and inventory positioning.
Market Dynamics
Silicon carbide semiconductor adoption is compressing inverter form factors while Saudi Arabia's gigawatt-scale procurement mandates force rapid qualification cycles that filter traditional suppliers.
Growth Catalysts
- NEOM and Red Sea Project procurement:Centralized utility tenders in Saudi Arabia mandate smart inverter architectures with reactive power control, creating immediate demand for certified three-phase systems.
- South Africa's NERSA grid modernization mandates:Low-voltage ride-through requirements and tightened efficiency standards accelerate replacement cycles in commercial and industrial rooftop segments.
- Hybrid inverter technology convergence:Nigerian and Kenyan off-grid commercial users pair solar generation with lithium-ion storage to circumvent grid instability, expanding addressable market beyond pure grid-tied applications.
Market Restraints
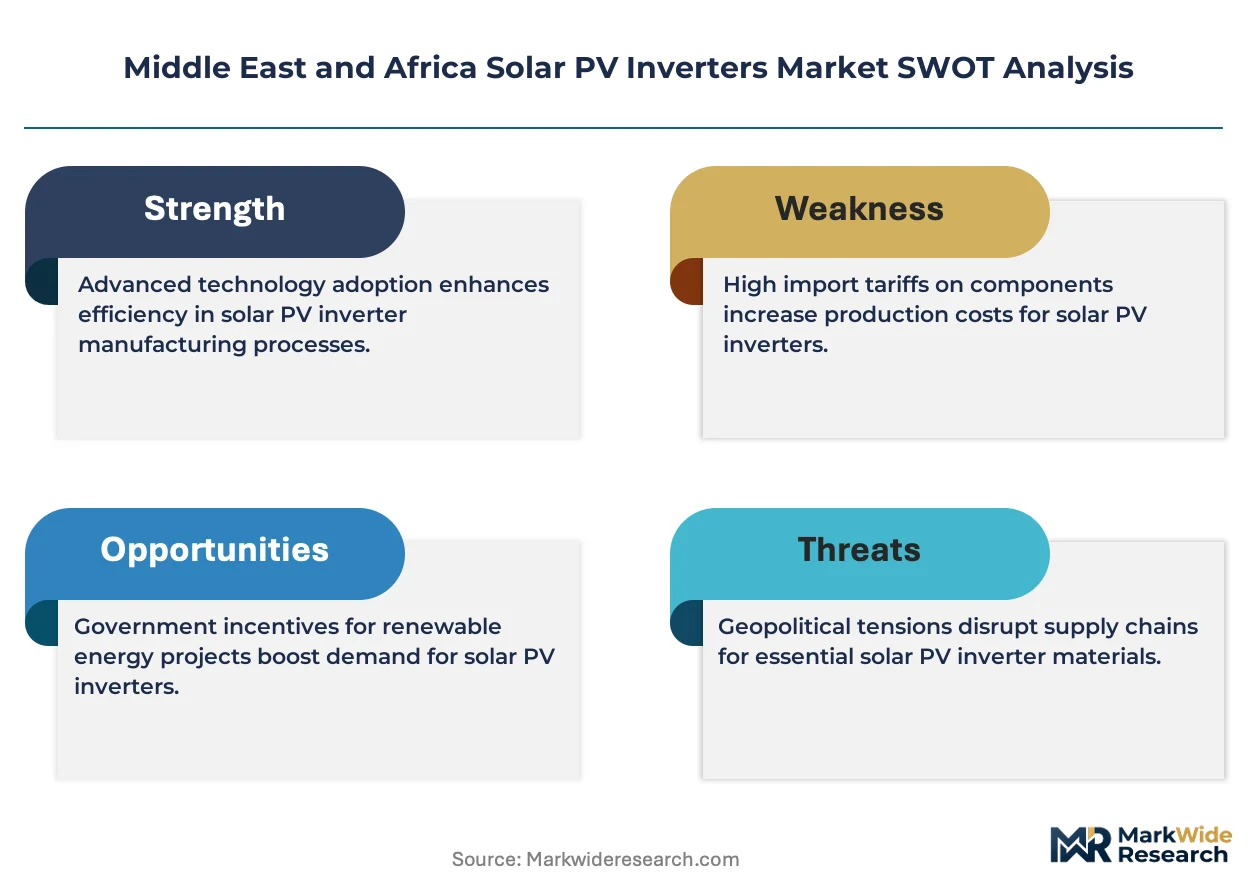
- Power semiconductor supply concentration:Silicon carbide substrate fabrication concentrates among East Asian suppliers, exposing Middle Eastern and African integrators to input cost volatility and allocation constraints.
- Extended IEC 62109 certification timelines:Divergent testing protocols across Egypt's NREA, Morocco's ONEE, and the UAE's standardization body compress project commissioning windows and strain inventory positioning.
- Thermal engineering limitations in desert-rated enclosures:Ambient temperatures exceeding 50°C in Gulf Cooperation Council states degrade conventional inverter lifespans, forcing premium thermal management investments that raise system-level costs.
Strategic Opportunities
- Underpenetrated East African commercial segment:Ethiopian and Tanzanian distributed solar programs lack established inverter service networks, creating first-mover advantage for localized technical support investments.
- Morocco's ONEE rural electrification mandates:National utility procurement of single-phase residential inverters for village-scale mini-grids opens volume channels distinct from utility-scale competition.
- Digital power platform convergence:Integration of inverter controls with SCADA and energy management systems enables recurring software revenue streams from Saudi utility operators seeking predictive maintenance capabilities.
Industry Challenges
- Power electronics engineering talent scarcity:Specialized skills in wide-bandgap semiconductor design and desert thermal modeling concentrate in East Asian and European labor pools, constraining local assembly expansion in Egypt and Saudi Arabia.
- Multi-jurisdiction certification complexity:Simultaneous compliance with Saudi SFDA-equivalent energy regulations, South African NERSA grid codes, and Moroccan ONEE testing protocols extends product development cycles and fragments SKU strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Solar PV Inverters Market |
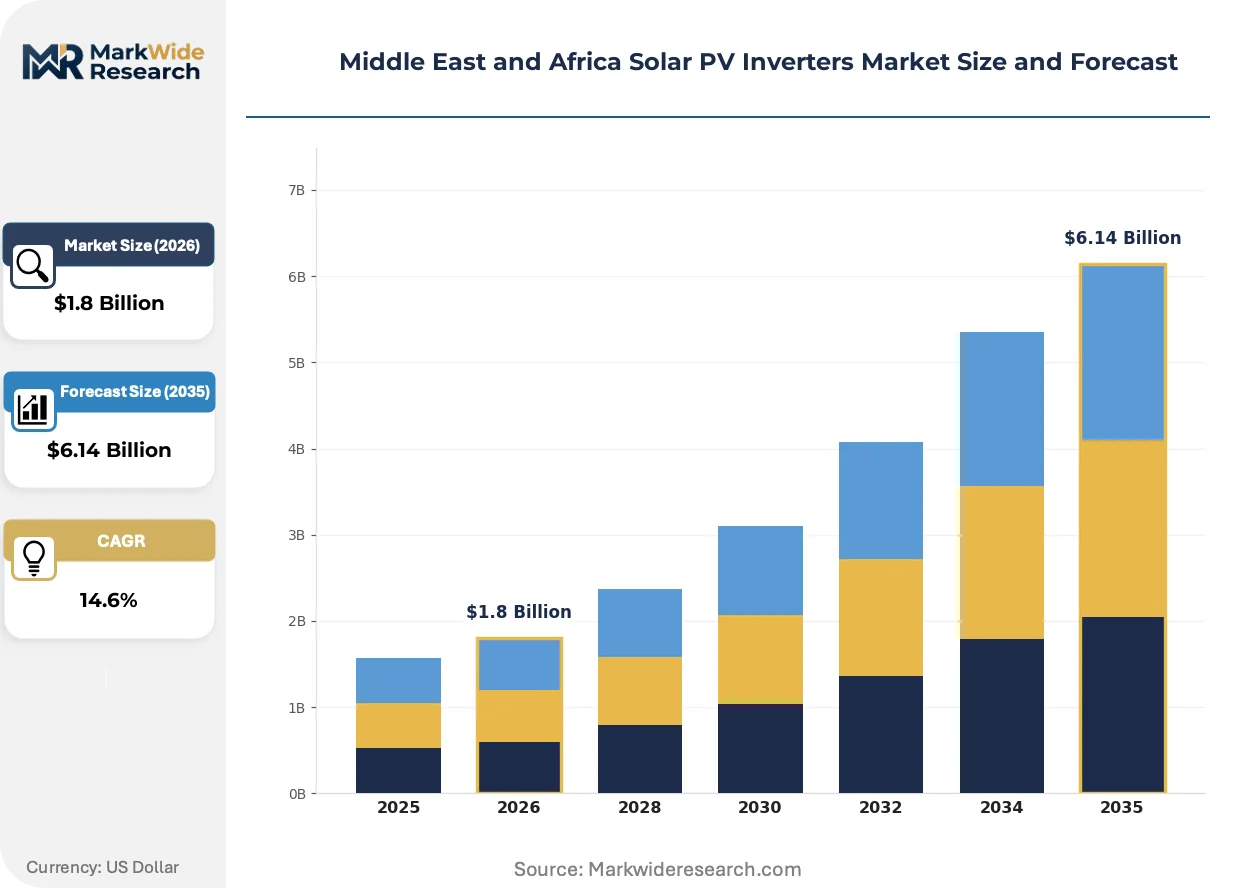
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Microinverters, Power Optimizers, Hybrid Inverters End User: Residential, Commercial, Industrial, Utilities Installation Type: On-grid, Off-grid, Hybrid, Standalone Technology: Single-phase, Three-phase, Multi-mode, Smart Inverters |
| Companies Covered | Huawei Technologies, Sungrow Power Supply, SMA Solar Technology, FIMER SpA, SolarEdge Technologies, Delta Electronics, Schneider Electric, Siemens, GOODWE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Solar PV Inverters Market Shifts & Advancements
Wide-bandgap semiconductor deployment and digital control architectures are compressing inverter footprints while regulatory divergence across Middle Eastern and African jurisdictions forces modular qualification strategies.
Silicon carbide MOSFETs are integrating into three-phase string inverter designs to slash switching losses and enable 1500V DC bus architectures. Saudi utility-scale developers adopt these systems aggressively for NEOM-phase installations. The technology is integrating power conversion and grid-forming capabilities into single enclosures, eliminating separate transformer requirements and reducing balance-of-system costs.
South Africa's NERSA has tightened reactive power control mandates for inverters above 100kW, forcing firmware updates across installed commercial fleets. The regulation compresses supplier response windows to 90 days for compliance certification. Moroccan and Tunisian distributed solar programs face parallel pressure as ONEE adopts IEEE 1547-derived testing protocols that extend product qualification timelines.
Buyer concentration among Saudi and UAE utility procurement desks is forcing inverter suppliers to unbundle hardware from long-term service contracts. Developers now negotiate predictive maintenance and spare parts availability as separate line items. This pattern is most visible in Egyptian competitive bidding rounds where NREA evaluates total cost of ownership over asset life rather than upfront capital expenditure.
Middle East and Africa Solar PV Inverters Market Segmentation
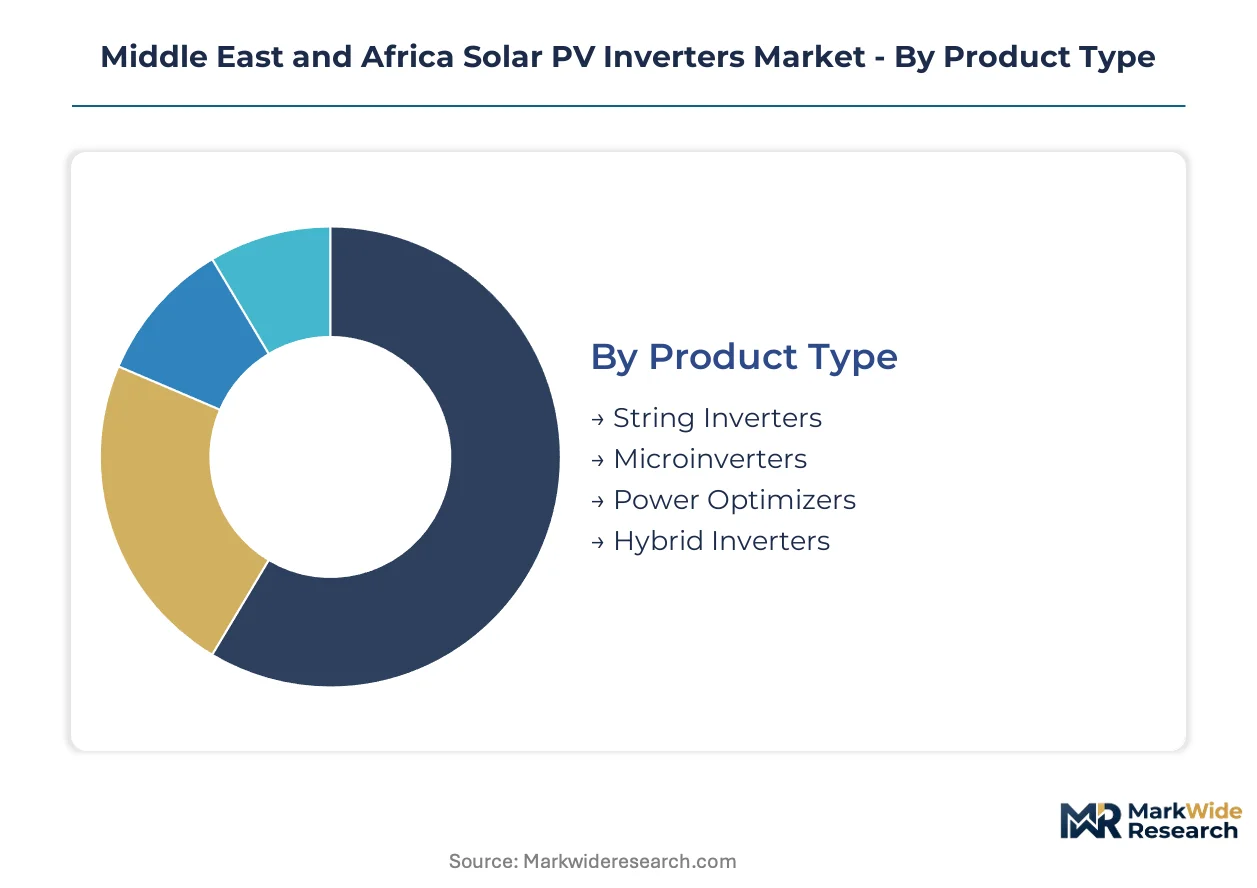
Segmentation in this market reflects divergent thermal engineering requirements across desert climates and the regulatory fragmentation that shapes procurement specifications. Understanding how product architectures align with end-use economics and grid code mandates enables precise positioning across Saudi utility tenders and East African commercial deployments.
Product Type:
Standardized enclosures dominate high-volume utility procurement while modular designs with field-replaceable power stages address serviceability constraints in remote African installations.
- String Inverters:Modular three-phase units with 99% maximum power point tracking efficiency and 1500V DC input capability. NEOM and Red Sea Project developers in Saudi Arabia specify these for gigawatt-scale solar parks due to redundant architecture and lower balance-of-system costs.
- Hybrid Inverters:Integrated DC-AC conversion with bidirectional battery charging controllers and grid-forming capability. Nigerian and Kenyan off-grid commercial users deploy these with lithium-ion storage to circumvent grid instability, representing the steepest expansion trajectory in this category.
- Microinverters:Module-level power electronics with per-panel maximum power point tracking for shaded or heterogeneous arrays. Moroccan residential programs specify these for rooftop retrofits in dense urban fabric.
- Power Optimizers:DC-to-DC converters paired with centralized inverters to mitigate mismatch losses. South African commercial installers favor these for aging module fleets with degraded performance uniformity.
Leading the category by volume: String Inverters. Growing fastest: Hybrid Inverters.
End User:
Procurement scale ranges from distributed residential volumes through concentrated utility tenders that dictate supplier qualification timelines across multiple jurisdictions.
- Utilities:Centralized procurement desks in Saudi Arabia and the UAE mandate smart inverter architectures with reactive power control and low-voltage ride-through per NERSA and SFDA-equivalent grid codes.
- Commercial:Rooftop and carport installations across South African malls and Egyptian manufacturing facilities. NERSA efficiency mandates accelerate replacement cycles in this segment.
- Industrial:C&I off-takers with captive generation needs and power purchase agreement structures. Nigerian manufacturers pair solar with diesel backup through hybrid configurations.
- Residential:Distributed programs in Morocco and Tunisia with single-phase inverter specifications. ONEE rural electrification mandates drive village-scale mini-grid procurement.
Highest revenue concentration: Utilities. Fastest volume expansion: Commercial.
Installation Type:
Grid interconnection status determines inverter firmware complexity and certification requirements across Middle Eastern and African regulatory regimes.
- On-grid:Synchronized operation with utility frequency and voltage references. Saudi and UAE utility-scale deployments require IEC 62109 certification and reactive power dispatch capability.
- Off-grid:Standalone frequency formation without grid reference. Kenyan and Ethiopian rural commercial users deploy these where transmission infrastructure is absent.
- Hybrid:Seamless transfer between grid-tied and islanded operation. Nigerian C&I segments prioritize this architecture for grid instability resilience.
- Standalone:Pure off-grid systems with battery-centric design. Tanzanian mini-grid developers specify these for remote agricultural processing loads.
Dominant configuration: On-grid. Emerging fastest: Hybrid.
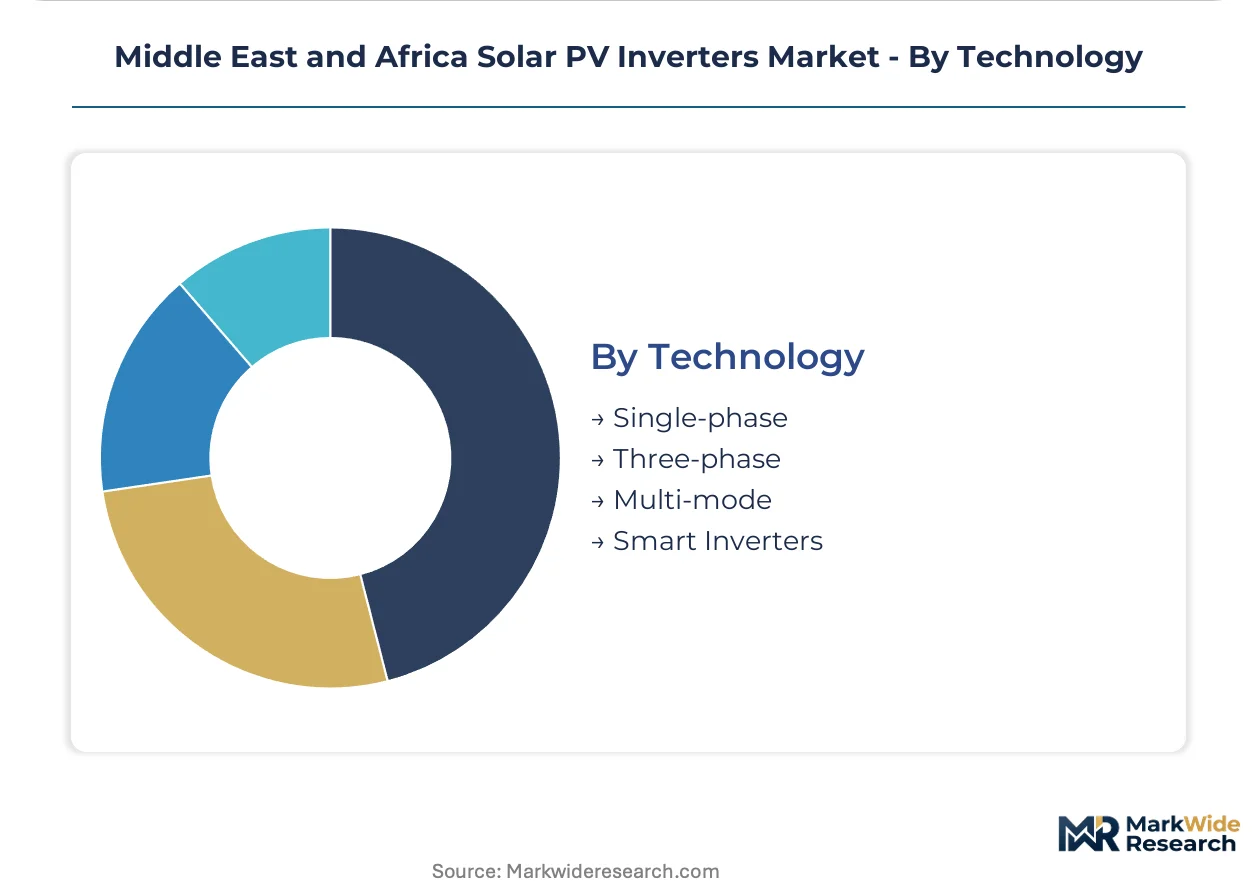
Technology:
Phase topology and control intelligence segment the market from basic residential units through utility-grade systems with predictive maintenance integration.
- Three-phase:Balanced AC output for commercial and utility-scale systems above 10kW. Saudi procurement mandates specify these for NEOM-phase installations with 1500V DC bus architectures.
- Smart Inverters:Grid-supportive functions including volt-var control, frequency-watt response, and remote firmware update capability. South African NERSA mandates drive adoption above 100kW thresholds.
- Single-phase:Split-phase or single-phase output for residential systems below 10kW. Moroccan and Tunisian distributed programs specify these for rooftop retrofits.
- Multi-mode:Configurable operation across grid-tied, off-grid, and hybrid states through software-defined control. East African commercial segments favor these for operational flexibility.
Widest installed base: Three-phase. Advancing most rapidly: Smart Inverters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement desks in Saudi Arabia and the UAE concentrate regional demand, while grid modernization mandates in South Africa and Morocco compress project timelines across divergent certification regimes.
Saudi Arabia
NEOM and the Red Sea Project drive centralized procurement of three-phase string and smart inverter systems above 100kW. The SFDA-equivalent energy regulator mandates reactive power control and low-voltage ride-through capabilities that filter uncertified suppliers. Riyadh and the Eastern Province host the primary deployment clusters where gigawatt-scale solar parks require desert-rated thermal engineering.
United Arab Emirates
Utility-scale developers in Dubai and Abu Dhabi accelerate adoption of 1500V DC bus architectures with silicon carbide power semiconductors. MOHAP-aligned standardization bodies specify IEC 62109-derived testing protocols that extend product qualification timelines. The Emirates' procurement desks unbundle hardware from long-term service contracts, forcing predictive maintenance negotiations as separate commercial terms.
South Africa
NERSA grid modernization mandates tighten efficiency standards and low-voltage ride-through requirements for commercial and industrial rooftop segments above 100kW. The regulator compresses supplier response windows to 90 days for compliance certification firmware updates. Johannesburg and Cape Town industrial zones anchor replacement cycle demand as aging inverter fleets face accelerated obsolescence.
Morocco
ONEE rural electrification mandates drive village-scale mini-grid procurement of single-phase residential inverters below 10kW. The national utility adopts IEEE 1547-derived testing protocols that fragment SKU strategies for distributed solar programs. Casablanca and Rabat concentrate commercial installer networks serving rooftop retrofit demand in dense urban fabric.
Egypt
NREA competitive bidding rounds evaluate total cost of ownership over asset life rather than upfront capital expenditure, shifting procurement evaluation frameworks. Local content requirements force manufacturers to establish assembly or warehousing presence to qualify for utility tenders. The Nile Delta and Greater Cairo regions host manufacturing investment responding to these domestic sourcing mandates.
Middle East and Africa Solar PV Inverters Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers navigate multi-jurisdiction certification complexity. The vendor base concentrates around three archetypes: integrated digital power platform operators, thermal engineering specialists optimized for desert climates, and cost-adjusted efficiency competitors in commercial rooftop segments. Capacity expansion into local assembly facilities and technology licensing agreements represent the primary competitive vectors as Egyptian and Saudi content requirements harden.
Within the integrated platform tier, Huawei Technologies anchors utility-scale positioning through its digital power architecture. SMA Solar Technology exemplifies the thermal engineering specialist archetype with service networks optimized for ambient temperatures above 50°C. Sungrow Power Supply occupies the cost-adjusted efficiency position in South African commercial and industrial segments. These three entities collectively represent the strategic positioning spectrum that other competitors must navigate.
| Leading Market Players |
|---|
| Huawei Technologies |
| Sungrow Power Supply |
| SMA Solar Technology |
| FIMER SpA |
| SolarEdge Technologies |
| Delta Electronics |
| Schneider Electric |
| Siemens |
| GOODWE |
| Others |
Supply & Pricing Matrix
Sovereign-backed procurement desks in Saudi Arabia and the UAE anchor inverter pricing discipline through centralized utility tenders that unbundle hardware from service contracts, compressing margin capture for suppliers lacking local assembly presence. This ownership pattern concentrates volume leverage among state-linked buyers while forcing manufacturers to absorb certification and thermal engineering premiums to qualify for gigawatt-scale deployment.
Pricing Analysis
Volume-vs-margin split in this market separates utility-scale procurement from commercial rooftop segments. Project-based transactional pricing dominates Saudi NEOM tenders where NREA evaluates total cost of ownership, while South African C&I segments face price differentiation driven by NERSA certification grade and after-sales bundling. Pricing pressure stems from silicon carbide substrate allocation constraints among East Asian suppliers. Utility buyers exhibit lowest price sensitivity due to sovereign financing; Nigerian off-grid commercial users show highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with silicon carbide substrate fabrication concentrated in China, Japan, and South Korea, exposing Middle Eastern integrators to input cost volatility. Power semiconductor wafers, thermal management components, and magnetics draw from these geographies. Tariff exposure on wide-bandgap materials presents structural risk. Distribution runs through EPC contractors and utility procurement desks rather than open channel networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over silicon carbide sourcing and desert-rated thermal engineering capabilities determines qualification for Saudi utility tenders. Players are pursuing backward integration into power semiconductor supply to secure allocation priority.
For Market Incumbents: Acquire local assembly facilities in Egypt and Saudi Arabia to satisfy NREA and SFDA-equivalent content requirements. Secure captive supply agreements with silicon carbide substrate producers to defend against allocation constraints. Deepen firmware development capabilities to meet NERSA's 90-day compliance windows for reactive power control updates. For New Entrants and Emerging Players: Silicon carbide-based compact inverter designs offer entry wedge into Ethiopian and Tanzanian commercial segments lacking established service networks. Target East African C&I rooftops where hybrid configurations for grid instability resilience remain underpenetrated. Deploy direct technical support investments as primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor thermal engineering specialists with IEC 62109 certification portfolios in South Africa and Morocco. Long-term viability hinges on qualification breadth across multiple Middle Eastern and African regulatory regimes. Watch NERSA and ONEE protocol harmonization efforts as inflection signal for inventory consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Establishment | Egyptian NREA content requirements force warehousing presence to qualify for utility tenders. |
| Silicon Carbide Supply Agreement | Captive substrate allocation from East Asian suppliers hedges against power semiconductor volatility. |
| Desert Thermal Engineering Investment | Ambient ratings above 50°C in GCC states differentiate service life and warranty positioning. |
| Multi-Jurisdiction Certification Expansion | Simultaneous SFDA-equivalent, NERSA, and ONEE compliance compresses competitor response windows. |
| Digital Power Platform Integration | SCADA and predictive maintenance bundling unlocks recurring revenue from Saudi utility operators. |
Research Methodology
Multi-period observation of inverter procurement volumes, certification timelines, and grid code amendments anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from IEA renewable energy reports, national regulator filings with NERSA and ONEE, project development databases tracking NEOM and Red Sea phases, and customs records of power semiconductor imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approach distributed value and volume across product type, end user, installation configuration, and technology tier dimensions. CAGRs derived from fitted growth curves applied to utility-scale procurement trajectories in Saudi Arabia and commercial replacement cycles in South Africa. Forecast inputs incorporated silicon carbide adoption curves, NERSA mandate implementation schedules, and Egyptian local content threshold escalations throughout the projection horizon.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting semiconductor substrate flows, sovereign liquidity constraints on Saudi gigawatt-scale tenders, and technological disruption from alternative wide-bandgap materials. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
GCC Solar Microinverter Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
US Solar Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar Kiosk Market