
 Middle East and Africa Transformer Market | 2026-2036
Middle East and Africa Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Transformer Market Insights
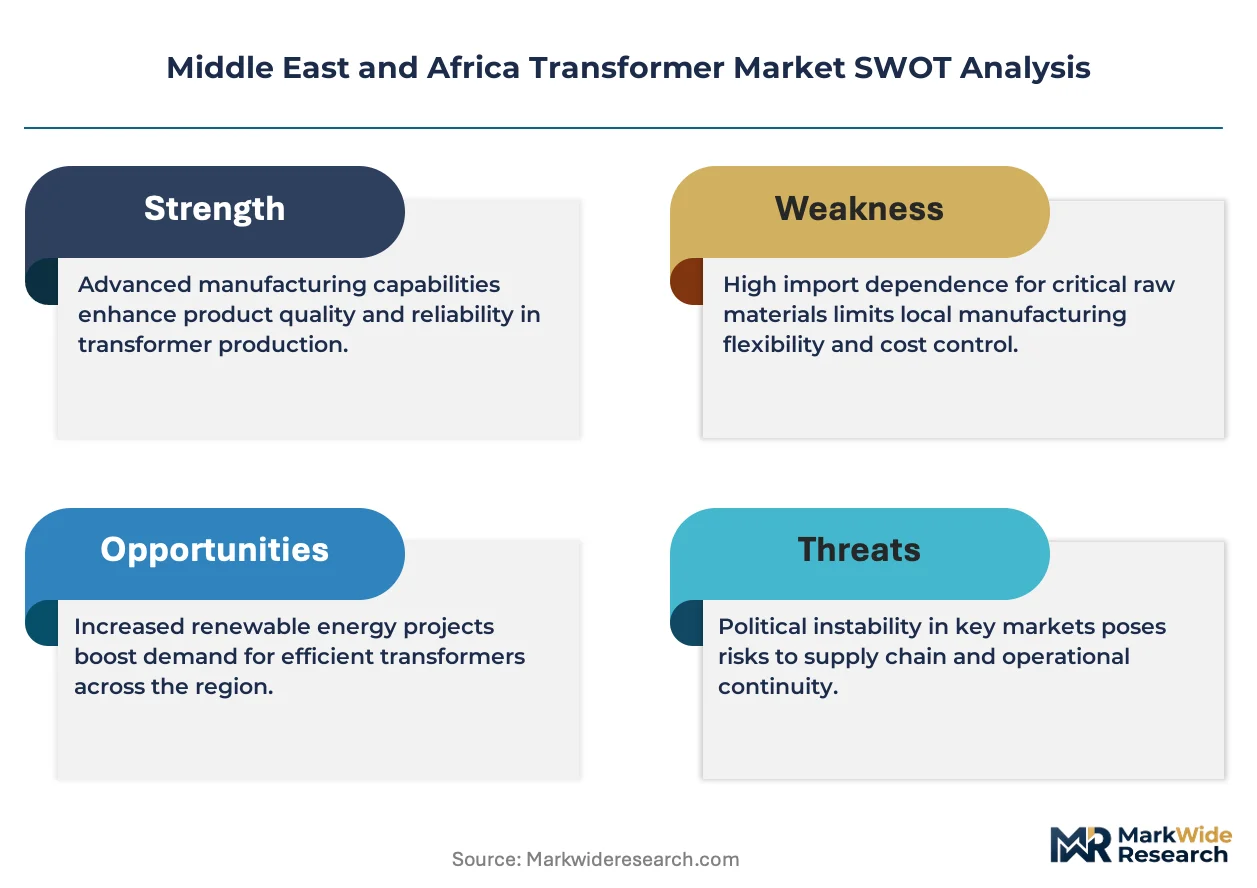
The EU Green Deal's extraterritorial influence on supply chain emissions disclosure is realigning procurement criteria for Middle Eastern utilities sourcing European-manufactured transformer cores. Hitachi Energy leverages its regional service hubs to sustain long-term maintenance contracts across Gulf utilities. Siemens AG anchors its position through localized production partnerships that bypass import tariff exposures. Elsewedy Electric competes on cost-engineered distribution units tailored to North African grid specifications.
A transformer is an electromagnetic apparatus that transfers electrical energy between circuits through magnetic induction, typically operating at frequencies of 50 Hz or 60 Hz with voltage ratings spanning from distribution-level 11 kV to ultra-high-voltage 765 kV classes. Its primary industrial purpose is to enable efficient power transmission over distance by stepping voltage up for transport and down for end-use consumption. Power transformers capture the dominant share of capital expenditure across Middle Eastern utilities building new interconnection corridors, while distribution transformers face accelerating replacement cycles in aging North African networks. Smart technology adoption remains nascent outside Gulf Cooperation Council markets, where grid digitalization budgets support intelligent monitoring and predictive diagnostics.
Saudi Arabia's central energy regulator mandates efficiency standards aligned with IEC 60076 loss classes, while South Africa's NERSA enforces grid code compliance that shapes transformer specification requirements for independent power producers. Egypt's Egyptian Electricity Holding Company imposes localization thresholds that condition market access on domestic manufacturing content. Stakeholders must monitor how divergent national certification regimes affect cross-border equipment mobility and aftermarket service economics.
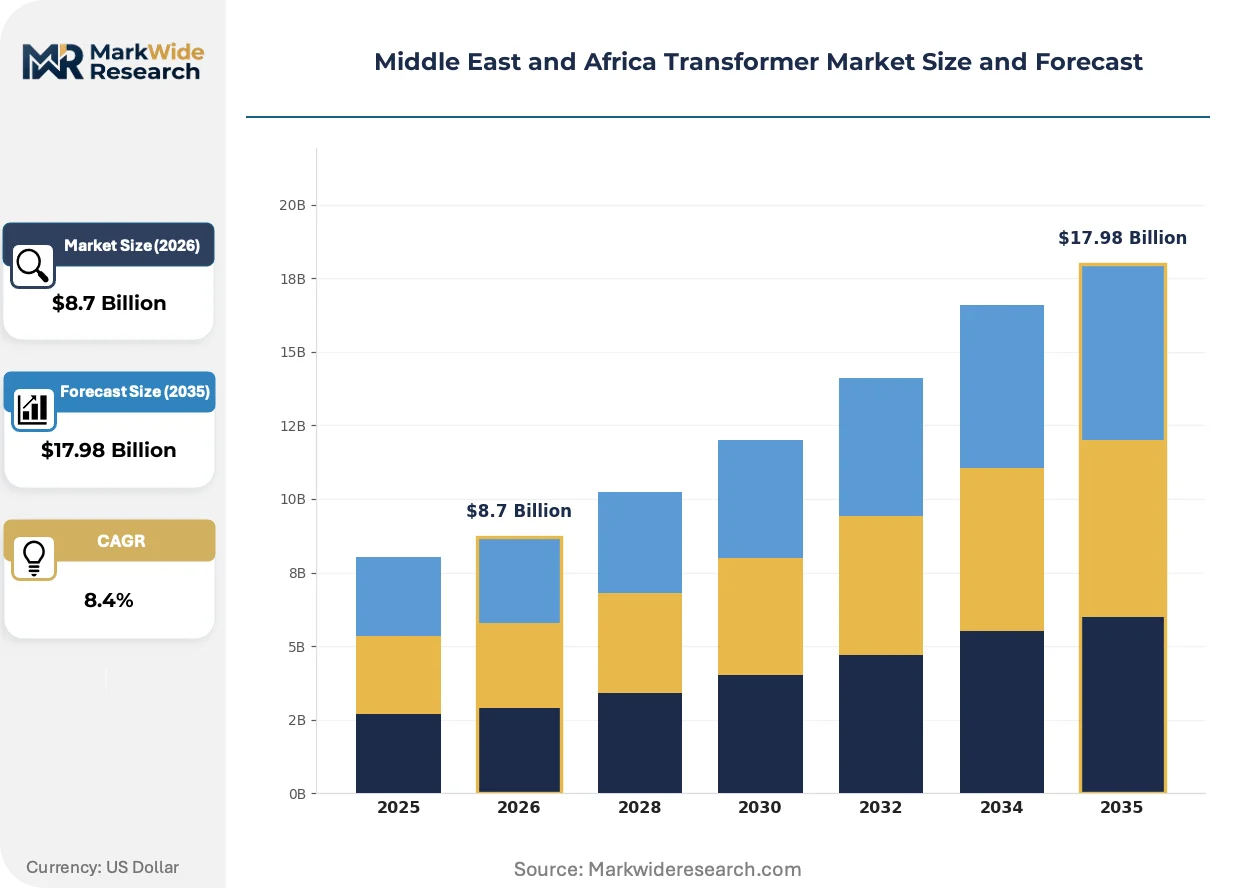
Market Dynamics
Gulf Cooperation Council utilities are accelerating transformer procurement cycles to synchronize grid capacity with renewable energy interconnection timelines, compressing traditional equipment lead times from 18 months to 12 months for strategic projects.
Growth Catalysts
- Saudi Arabia's National Energy Framework:Grid modernization mandates under this regulatory push are accelerating procurement of high-voltage units for transmission network expansion.
- Renewable capacity additions:Solar and wind projects across the Gulf Cooperation Council are expanding transmission networks and driving demand for power transformers.
- Egyptian localization thresholds:Domestic manufacturing content requirements imposed by the Egyptian Electricity Holding Company are conditioning market access and stimulating local production investment.
Market Restraints
- Grain-oriented electrical steel supply concentration:Import dependency on specialized core materials creates input cost volatility and exposes procurement to currency fluctuation risk.
- Technical limitation in 765 kV class manufacturing:Limited regional capability for ultra-high-voltage units forces reliance on external suppliers for interconnection corridor projects.
- Regulatory friction from divergent certification regimes:Saudi Arabia's IEC 60076 alignment versus South Africa's NERSA grid code compliance creates cross-border equipment mobility barriers.
Strategic Opportunities
- Underpenetrated North African replacement cycles:Aging distribution networks in Morocco and Algeria present accelerated replacement demand for cost-engineered distribution transformers.
- Technology convergence of digital monitoring and predictive diagnostics:Grid digitalization budgets within Gulf Cooperation Council utilities support intelligent transformer monitoring system integration.
- EU Green Deal extraterritorial influence:Supply chain emissions disclosure requirements are realigning procurement criteria for European-manufactured transformer cores sourced by Middle Eastern utilities.
Industry Challenges
- Skill gap in predictive maintenance engineering:Gulf utilities face shortage of technicians trained in dissolved gas analysis and thermal imaging diagnostics for smart transformer fleets.
- Capex intensity for test bay certification:Domestic manufacturers in Egypt and South Africa must invest in high-voltage impulse testing infrastructure to meet utility qualification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Transformer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Transformer, Distribution Transformer, Instrument Transformer, Auto Transformer Technology: Conventional, Smart, Liquid-Filled, Dry-Type End User: Utilities, Industrial Sector, Commercial Sector, Residential Sector Usage Scenario: Renewable Integration, Grid Expansion, Load Balancing, Voltage Regulation |
| Companies Covered | Hitachi Energy, Toshiba Corporation, Siemens AG, Saudi Power Transformers Company, alfanar Group, ABB, Elsewedy Electric, Eaton Corporation Plc, General Electric Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Transformer Market Trends and Innovations
Transformer technology evolution across the Middle East and Africa is bifurcating between Gulf digitalization imperatives and North African cost-optimization priorities, with regulatory divergence accelerating product specification fragmentation.
Amorphous metal core technology is rewriting efficiency benchmarks for distribution transformers deployed in Saudi Arabian and Emirati smart grid pilots. State-led infrastructure programs specify these cores for new urban substations. The technology is compressing no-load loss margins and forcing recalibration of procurement evaluation criteria across Gulf utilities.
South Africa's NERSA enforces grid code compliance that shapes transformer specification requirements for independent power producers connecting to the national transmission backbone. This regulatory architecture mandates specific impedance characteristics and tap changer configurations. IPPs are responding by pre-qualifying equipment against NERSA technical standards before financial close.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles across Egyptian and Moroccan utilities. Procurement departments now separate transformer supply from long-term aftermarket service agreements. This behavioral shift is most visible in Cairo and Casablanca, where state utilities pilot competitive tendering for predictive maintenance services independent of original equipment manufacturer relationships.
Middle East and Africa Transformer Market Segmentation
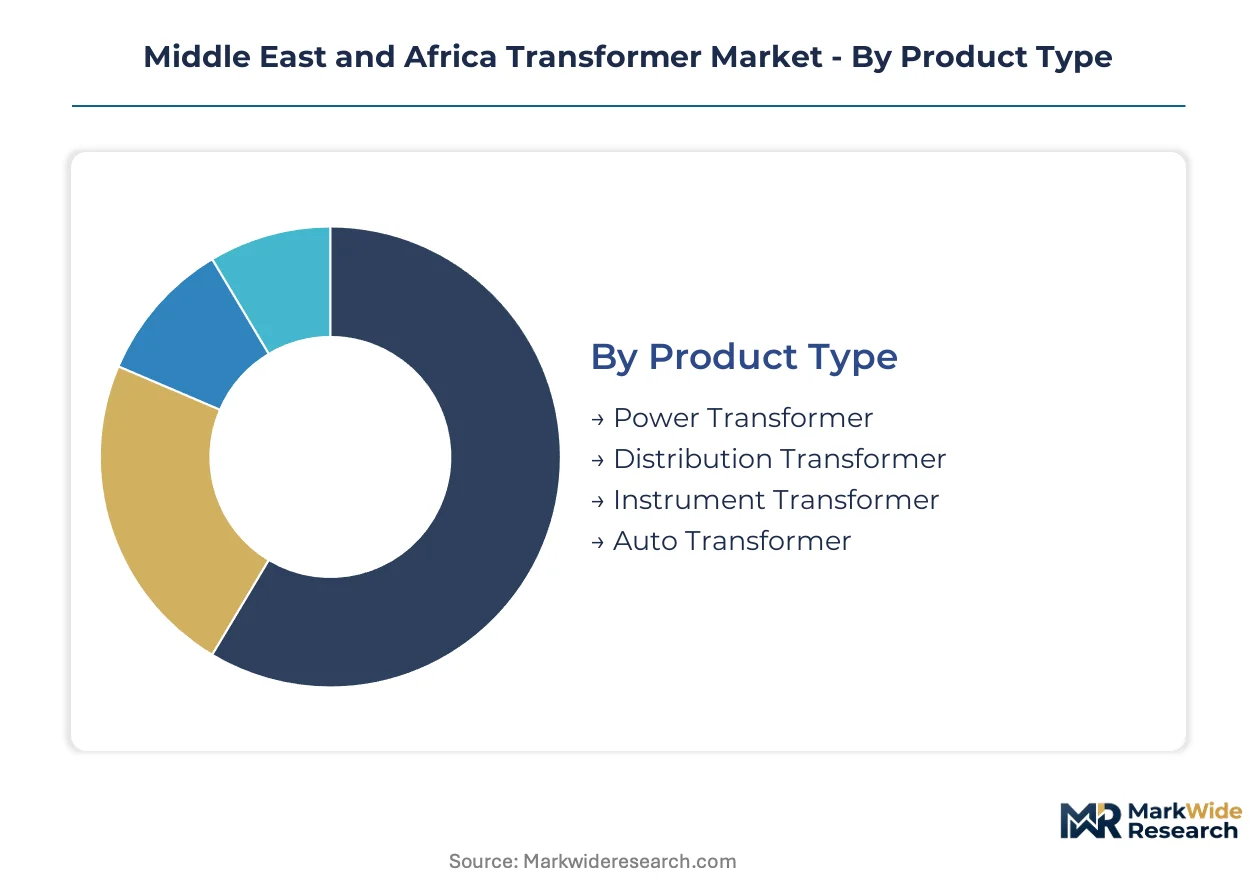
Transformer procurement across the Middle East and Africa fragments sharply across voltage classes and intelligence tiers, with capital allocation patterns diverging between Gulf states building interconnection corridors and North African utilities managing aging distribution assets. Understanding these fault lines reveals where equipment margins concentrate and which technology trajectories command premium pricing.
Product Type:
Capital intensity escalates dramatically with voltage class, separating billion-dollar transmission investments from standardized distribution unit procurement.
- Power Transformer:These high-voltage units ranging from 132 kV to 765 kV employ grain-oriented electrical steel cores and mineral oil insulation systems engineered for decades-long service life. Saudi Arabia's transmission network expansion and UAE interconnection projects concentrate demand here, with procurement cycles compressing from 18 months to 12 months for strategic renewable integration corridors.
- Distribution Transformer:Operating at 11 kV to 33 kV, these units step voltage down for final delivery to industrial and residential loads. Aging networks in Morocco and Algeria are accelerating replacement demand, with Egyptian localization mandates forcing manufacturers to establish domestic assembly capacity to access state utility tenders.
- Instrument Transformer:Current and potential transformers provide measurement and protection functions for metering and relay systems. Gulf Cooperation Council digitalization budgets support intelligent monitoring integration into these units.
- Auto Transformer:Single-winding designs offer cost and efficiency advantages for specific voltage ratio applications. Limited deployment in regional interconnection projects where impedance characteristics permit their use.
Most installed capacity flows through Distribution Transformer. Expansion is steepest in Power Transformer.
Technology:
Technology selection maps directly to grid modernization maturity, with premium intelligent systems commanding price multiples in Gulf markets while cost-optimized conventional units dominate North African procurement.
- Conventional:Standard electromagnetic designs without embedded monitoring capabilities represent the installed base across North African utilities. These units rely on scheduled maintenance rather than predictive diagnostics, aligning with constrained capital budgets in Egypt and Algeria.
- Smart:Digital transformers integrate dissolved gas analysis sensors, thermal monitoring, and remote diagnostics for predictive maintenance. Saudi Arabian and Emirati state-led infrastructure programs specify these for new urban substations, with IEC 61850 protocol compliance becoming a de facto procurement threshold.
- Liquid-Filled:Mineral oil or ester-based insulation dominates high-power applications where thermal management is critical. South Africa's NERSA grid code shapes specification requirements for IPPs connecting to the national transmission backbone.
- Dry-Type:Cast resin or vacuum-pressure-impregnated designs eliminate fire and environmental risks for indoor installations. Commercial and residential sector demand concentrates in dense urban developments across Dubai and Riyadh.
Conventional technology retains the largest installed footprint. Smart technology is climbing the fastest.
End User:
Customer type determines specification complexity, with utilities driving standardization and industrial buyers demanding customized impedance and tap changer configurations.
- Utilities:State-owned transmission and distribution companies across the Gulf Cooperation Council dominate capital allocation for power sector equipment. These entities specify IEC 60076-aligned efficiency standards and are unbundling service contracts from equipment supply.
- Industrial Sector:Mining, petrochemical, and manufacturing facilities require specialized transformer specifications for heavy motor starting loads and harmonic-rich environments. South Africa's independent power producers pre-qualify equipment against NERSA technical standards before financial close.
- Commercial Sector:Real estate developers and facility managers prioritize compact footprint and fire safety in dense urban installations. Dry-type units gain preference for high-rise developments.
- Residential Sector:Distribution-level units serving housing developments and individual dwellings represent high-volume, low-margin procurement with minimal specification differentiation.
Utilities command the dominant share of capital deployment. Industrial Sector procurement is expanding most quickly.
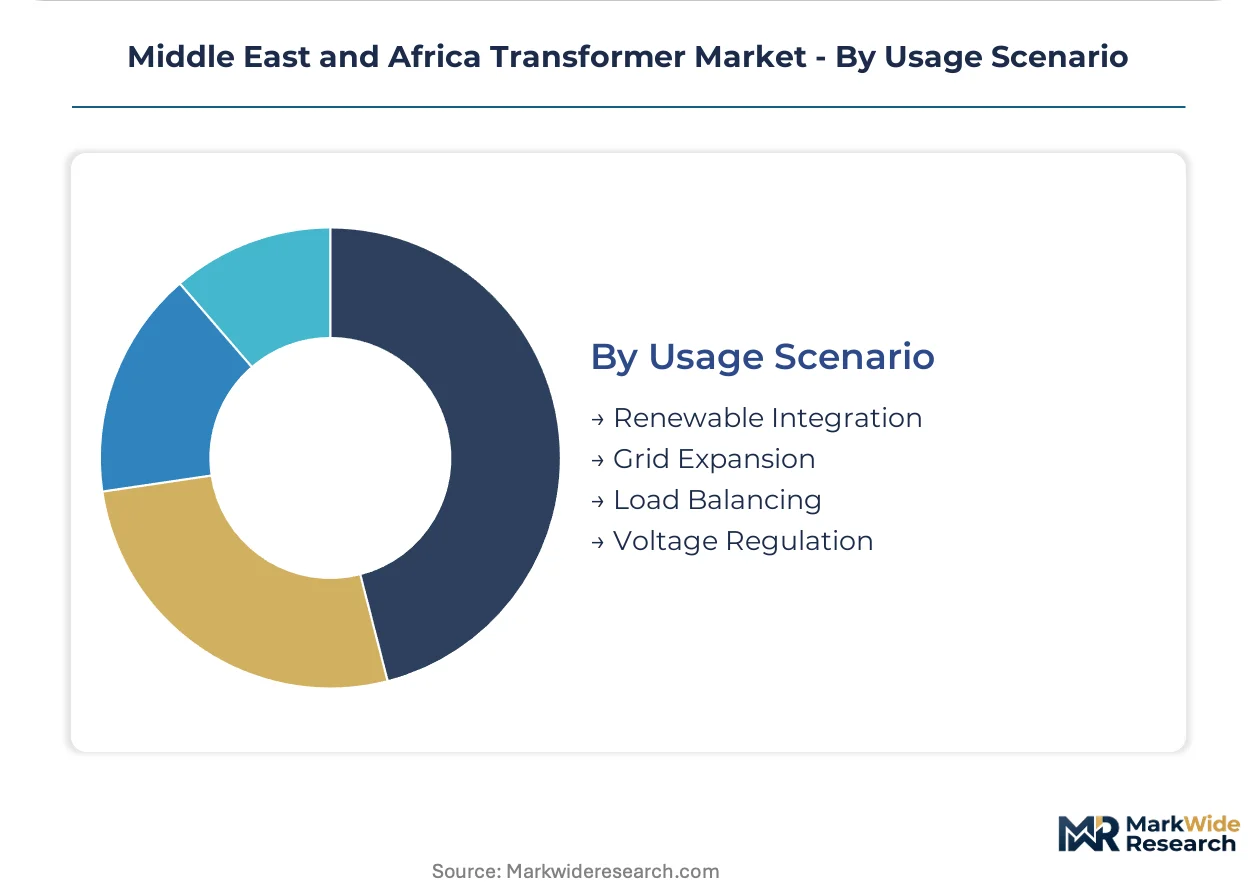
Usage Scenario:
Application context shapes transformer specification priorities, with renewable integration imposing unique thermal cycling and voltage fluctuation tolerances.
- Renewable Integration:Solar and wind interconnection demands transformers engineered for bidirectional power flow and intermittent loading profiles. Saudi Arabia's renewable capacity additions are expanding transmission networks and driving procurement of high-voltage units with enhanced thermal cycling capability.
- Grid Expansion:New transmission corridors and substation buildouts require power transformers with extended voltage regulation ranges. UAE and Saudi interconnection projects concentrate demand here.
- Load Balancing:Tap-changing transformers manage voltage stability across fluctuating demand patterns. Distribution networks in aging North African grids require replacement units with modern on-load tap changer mechanisms.
- Voltage Regulation:Dedicated regulation transformers maintain power quality for sensitive industrial and commercial loads. Gulf Cooperation Council grid digitalization budgets support intelligent monitoring integration for these applications.
Grid Expansion accounts for the largest committed capital. Renewable Integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Riyadh, Dubai, and Johannesburg anchor transformer procurement decisions across the Middle East and Africa. These technical workforces concentrate within state utility planning departments and engineering consultancies that specify equipment for billion-dollar grid investments. Their expertise shapes regional procurement standards and vendor qualification protocols.
Saudi Arabia
Renewable interconnection corridors and urban substation buildouts drive transformer demand. The national energy framework mandates grid modernization with IEC 60076-aligned efficiency standards. Riyadh-based Saudi Power Transformers Company and alfanar Group concentrate domestic manufacturing capacity to serve state-led infrastructure programs.
United Arab Emirates
Smart grid pilots and interconnection projects with neighboring Gulf states accelerate high-voltage unit procurement. Dubai's utility regulator enforces digitalization budgets that specify intelligent monitoring capabilities. Abu Dhabi and Dubai host the region's densest clusters of engineering consultancies specifying transformer equipment for mega-projects.
Egypt
Distribution network rehabilitation and renewable energy zones create dual demand streams. The Egyptian Electricity Holding Company imposes localization thresholds conditioning market access on domestic manufacturing content. Cairo and the Suez Canal Economic Zone concentrate assembly operations established to meet utility procurement requirements.
South Africa
Independent power producer connections to the national transmission backbone drive specialized transformer specifications. NERSA enforces grid code compliance that shapes impedance and tap changer requirements. Johannesburg and Cape Town anchor the technical workforce pre-qualifying equipment against national standards before financial close.
Morocco
Aging distribution networks in Casablanca and Rabat accelerate replacement demand for cost-engineered units. The national utility pilots competitive tendering that unbundles equipment supply from aftermarket service agreements. Industrial zones near Tangier Med concentrate manufacturing investments serving both domestic and re-export markets.
Middle East and Africa Transformer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Middle East and Africa transformer market. The vendor base separates into integrated manufacturers with captive core steel processing, regional assemblers leveraging localized partnerships, and technology licensors supplying designs to licensed fabricators. Three archetypes dominate: Gulf-based integrated producers, European-Japanese technology leaders, and North African cost-engineered specialists. Competitive moves concentrate on capacity expansion near demand centers and strategic partnerships that bypass import tariff exposures.
Among technology leaders, Hitachi Energy and Siemens AG exemplify the integrated service archetype, anchoring positions through regional service hubs and localized production partnerships. Elsewedy Electric occupies a position within the cost-engineered tier, representing Egyptian-based manufacturers competing on distribution units tailored to North African grid specifications. These three companies illustrate the market's structural segmentation between premium technology providers and regional cost optimizers.
| Leading Market Players |
|---|
| Hitachi Energy |
| Toshiba Corporation |
| Siemens AG |
| Saudi Power Transformers Company |
| alfanar Group |
| ABB |
| Elsewedy Electric |
| Eaton Corporation Plc |
| General Electric Company |
| Others |
Pricing and Supply Chain Analysis
Amorphous metal core adoption in Saudi Arabian and Emirati smart grid pilots is compressing no-load loss benchmarks while simultaneously concentrating procurement power among Gulf utilities with capital to specify premium efficiency tiers. This technology transition is reshaping cost economics for distribution transformers and forcing recalibration of supplier qualification protocols across the Middle East and Africa.
Pricing Analysis
Three-tier pricing structure across premium smart-monitoring, standard IEC 60076-compliant, and economy conventional units governs transformer procurement. Price differentiation hinges on IEC 61850 protocol certification and grain-oriented electrical steel core grade. Pricing pressure stems from Egyptian localization mandates forcing manufacturers to absorb domestic assembly costs. State utilities in Saudi Arabia and the UAE show lowest price sensitivity; North African distribution network operators exhibit highest.
Supply Chain Analysis
Regional distribution centers in Jebel Ali, Dubai, and Casablanca anchor hub-and-spoke patterns for transformer equipment across the Middle East and Africa. Manufacturing concentrates in Saudi Arabia, Egypt, and South Africa for domestic market access. Supply chains draw from Japanese and European sources for grain-oriented electrical steel, mineral oil insulation, and tap changer mechanisms. Single-source vulnerability in 765 kV class ultra-high-voltage units creates procurement risk for interconnection corridor projects. Distribution runs through state utility tendering platforms and EPC contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa transformer market represents a late-cycle quality story where Gulf Cooperation Council grid digitalization budgets are shifting procurement criteria toward premium intelligent monitoring specifications and predictive diagnostics capabilities.
For Market Incumbents: Extend service contract unbundling strategies to capture recurring revenue from predictive maintenance contracts independent of original equipment supply. Deepen backward integration into grain-oriented electrical steel processing to insulate margins from currency-driven input cost volatility. State utility procurement departments in Cairo and Casablanca are separating transformer supply from long-term aftermarket agreements, threatening bundled equipment-plus-service margins. For New Entrants and Emerging Players: Launch via technology licensing partnerships with European or Japanese design houses to bypass capex-intensive test bay certification requirements. Target Morocco and Algeria's aging distribution network replacement cycles with cost-engineered conventional units tailored to North African grid specifications. Egyptian localization thresholds condition market access on domestic manufacturing content, creating an entry pathway through Cairo-based assembly joint ventures. For Investors and Strategic Acquirers: Valuations sit cheapest among Egyptian and South African domestic manufacturers lacking high-voltage impulse testing infrastructure. Long-term viability favors integrated producers with captive core steel processing and regional service hub networks. The signal to watch is Saudi Power Transformers Company and alfanar Group capacity expansion announcements, which would indicate state-led infrastructure program acceleration and premium-tier demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Processing | Captive grain-oriented electrical steel supply insulates Saudi manufacturers from yen-euro currency volatility. |
| Smart Grid Pilot Technology Licensing | European-Japanese design houses transfer amorphous metal core specifications to Gulf-based assemblers. |
| Localization Joint Venture Formation | Cairo-based assembly operations satisfy Egyptian Electricity Holding Company domestic content thresholds. |
| Predictive Maintenance Service Unbundling | Moroccan and Egyptian utilities now tender dissolved gas analysis contracts separately from equipment supply. |
| High-Voltage Test Bay Certification Investment | Domestic manufacturers in Johannesburg and Cape Town meet NERSA grid code compliance for IPP connections. |
Research Methodology
Multiple input streams — utility procurement officer interviews, EPC contractor project pipelines, and regulatory filing analysis — were reconciled to construct demand estimates across the Middle East and Africa transformer market. Primary fieldwork engaged transmission planning engineers at Gulf Cooperation Council utilities, independent power producer development teams in South Africa, and manufacturing operations directors at Egyptian and Saudi production facilities. Secondary validation drew from IEC standard publication records, national grid code filings with Saudi Arabia's central energy regulator and South Africa's NERSA, and customs trade data for grain-oriented electrical steel imports. Bottom-up unit deployment forecasts triangulated against top-down utility capital expenditure budgets.
Data-stream reconciliation anchored the analytical framework across voltage class, technology tier, and end-user segmentation dimensions. Power transformer demand from renewable interconnection corridors and distribution transformer replacement cycles in aging North African networks were modeled separately. CAGRs were derived from equipment lead time compression trends and state-led infrastructure program procurement schedules. Forecast inputs incorporated solar and wind capacity addition timelines, Egyptian localization threshold enforcement patterns, and Gulf Cooperation Council grid digitalization budget allocations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under grain-oriented electrical steel supply disruption or divergent national certification regime fragmentation. Outputs reflect documented assumptions regarding regulatory enforcement continuity and utility capital commitment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Europe Oil Filled Distribution Transformer Market
Transformers
North America Smart Transformers Market
Transformers
HVDC Converter Transformers Market
Transformers
Middle East Distribution Transformer Market
Transformers
Current Transformer Market
Transformers
Power Transformer Market
Transformers
Liquid Filled Transformer Market
Transformers
Global Transformer Market
Transformers
Box Transformer Substation Market
Transformers
China Transformer Market
Transformers
Industrial Control Transformers Market
Transformers
Green Transformer Market
Transformers
Liquid-Immersed Transformers Market
Transformers
United States Power Transformer Market
Transformers
EHV & UHV (above 330KV) Power Transformers Market
Transformers
Asia-Pacific Power Transformer (Below 100 MVA) Market