
 Solar Panel Glass Market | 2026-2036
Solar Panel Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Glass Market Insights
Project finance and green-bond structures for utility-scale solar arrays is rewriting procurement economics for panel glass, lowering the capital threshold for developers to specify premium coated substrates. Xinyi Solar Holdings Ltd. leverages integrated float-glass furnaces to control raw material costs across its supply chain. Saint-Gobain anchors European supply through its specialized low-iron production lines. Borosil Renewables Ltd. dominates India's domestic tempered-glass segment with furnace configurations optimized for local silica grades.
Solar panel glass is a thermally or chemically strengthened silica-based sheet engineered with iron content below 0.1 percent to maximize photon transmission, typically manufactured through the float process and subsequently heat-treated to withstand mechanical loads and thermal cycling in photovoltaic modules. Low-iron glass leads volume shipments due to its superior transmittance profile, while anti-reflective coated variants command margin premiums in high-efficiency module assemblies. Utility-scale applications absorb the largest share of thick-substrate output, whereas residential installations increasingly specify laminated configurations for enhanced durability.
China's MEE enforces emissions benchmarks on float-glass kilns, while the EU Green Deal and REACH frameworks constrain heavy-metal content in coating chemistries, compelling reformulation investments across exporters. India's BIS certification mandates mechanical strength testing for imported solar glass, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor evolving carbon-border adjustment mechanisms and corresponding national recycling mandates to align capacity planning with regulatory trajectories.
Market Dynamics
Float-glass furnace economics and embodied-carbon accounting are restructuring competitive advantage across solar panel glass manufacturing, as integrated producers capture margin through captive silica sourcing and emissions-compliant kiln configurations.
Growth Catalysts
- Utility-scale solar procurement:Project finance structures for gigawatt-scale arrays specify high-transmission substrates, pulling volume through long-term offtake agreements with glass suppliers.
- China's dual carbon goals:MEE emissions benchmarks on float-glass kilns accelerate furnace upgrades, tightening supply of compliant output and favoring integrated producers with in-house energy assets.
- EU Green Deal implementation:REACH constraints on heavy-metal coating chemistries compel reformulation investments, creating first-mover advantage for European suppliers with established low-iron production lines.
Market Restraints
- Silica sand concentration:High-purity silica deposits concentrate in limited geographies, exposing float-glass producers to input cost volatility and freight exposure.
- Furnace asset intensity:Float-glass kilns require continuous operation and substantial energy input, locking capital and constraining supply elasticity during demand surges.
- India's BIS certification:Mechanical strength testing mandates for imported solar glass create compliance barriers and timeline friction for non-domestic suppliers.
Strategic Opportunities
- Anti-reflective coating penetration:High-efficiency module assemblers in China and the United States specify coated variants at margin premiums, expanding addressable value per square meter.
- Recycling infrastructure buildout:EU end-of-life mandates for photovoltaic modules create demand for glass recovery and re-melting services, opening circular-economy revenue streams.
- Laminated residential configurations:Distributed solar installers in the United States increasingly specify dual-glass laminates for durability, shifting product mix toward higher-value substrates.
Industry Challenges
- Skilled furnace operations:Float-glass kiln management requires specialized thermal engineering expertise, constraining capacity expansion timelines and raising labor costs.
- Carbon-border adjustment compliance:Exporters to the European Union must document embodied-carbon footprints across silica mining, melting, and coating processes, extending certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Glass Market |
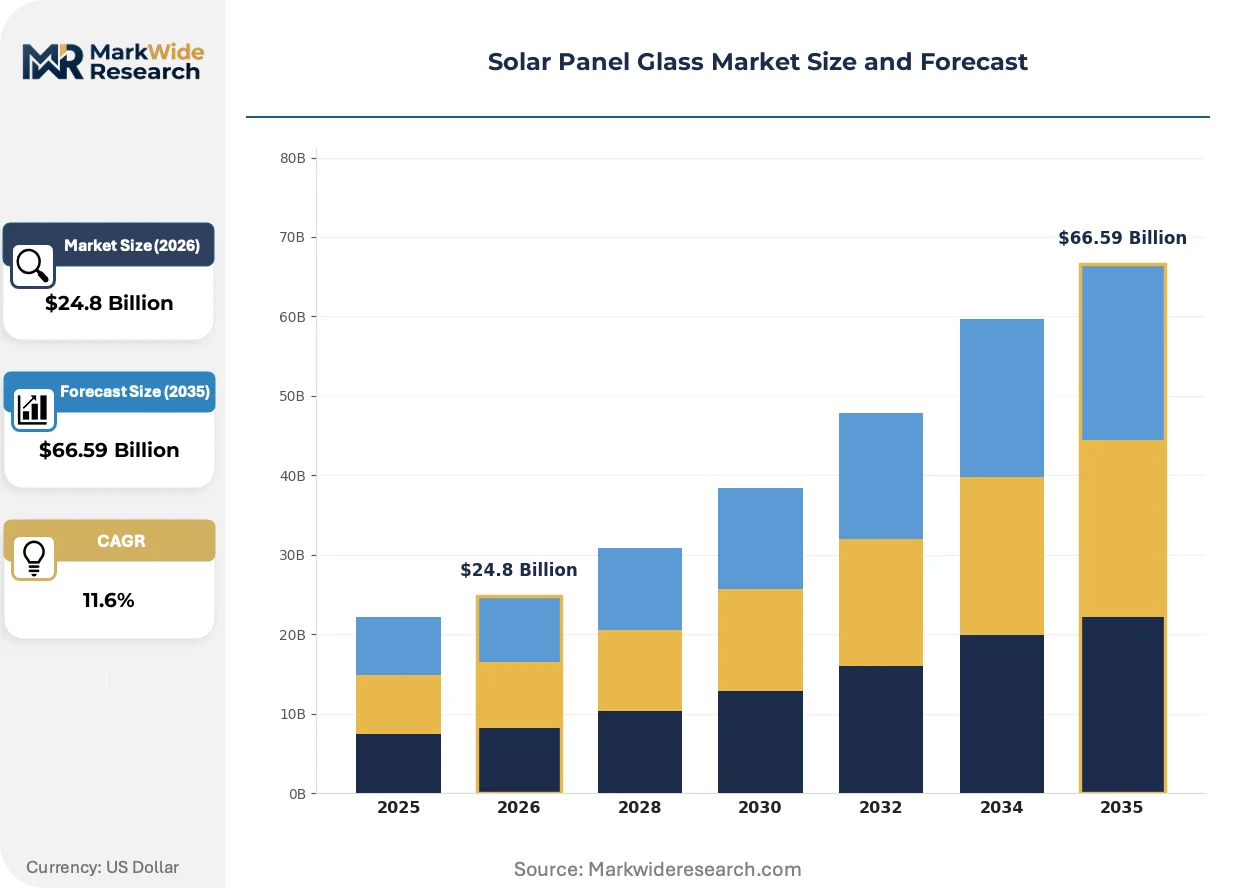
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Low-iron Glass, Coated Glass, Laminated Glass Application: Residential, Commercial, Utility-scale, Off-grid Systems Thickness: 3mm, 4mm, 6mm, 10mm Coating Type: Anti-reflective, Hydrophobic, Anti-soiling, UV Protection |
| Companies Covered | Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd., AGC Inc., Saint-Gobain, IRICO Group New Energy Co., Ltd., Guardian Glass, Nippon Sheet Glass Co., Ltd., CSG Holding Co. Ltd., Borosil Renewables Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Glass Market Trends and Innovations
Manufacturing process convergence and substrate functionalization are redefining product architecture, as glass producers integrate coating deposition directly into float-line operations.
Thin-film photovoltaic integration is hybridizing solar panel glass specifications, as cadmium-telluride and perovskite module assemblers demand substrates with modified thermal expansion coefficients and surface roughness profiles. First Solar and domestic Chinese thin-film producers specify these variants for utility-scale deployments. This convergence is compressing the addressable market for conventional crystalline-silicon optimized glass while expanding substrate customization services.
China's MEE emissions benchmarks are tightening kiln efficiency standards, compelling float-glass producers to invest in oxy-fuel combustion and waste-heat recovery systems. Furnace operators face retrofit capital requirements or capacity retirement. European exporters to China must demonstrate equivalent emissions intensity or risk market access restrictions, accelerating technology transfer partnerships.
Direct procurement from float-glass producers is displacing distributor-mediated supply for tier-one module assemblers, as volume buyers negotiate furnace-dedicated output and technical co-development agreements. This channel compression concentrates purchasing power among the largest photovoltaic manufacturers. The pattern is most visible in China and India, where domestic glass supply anchors module export strategies.
Solar Panel Glass Market Segmentation
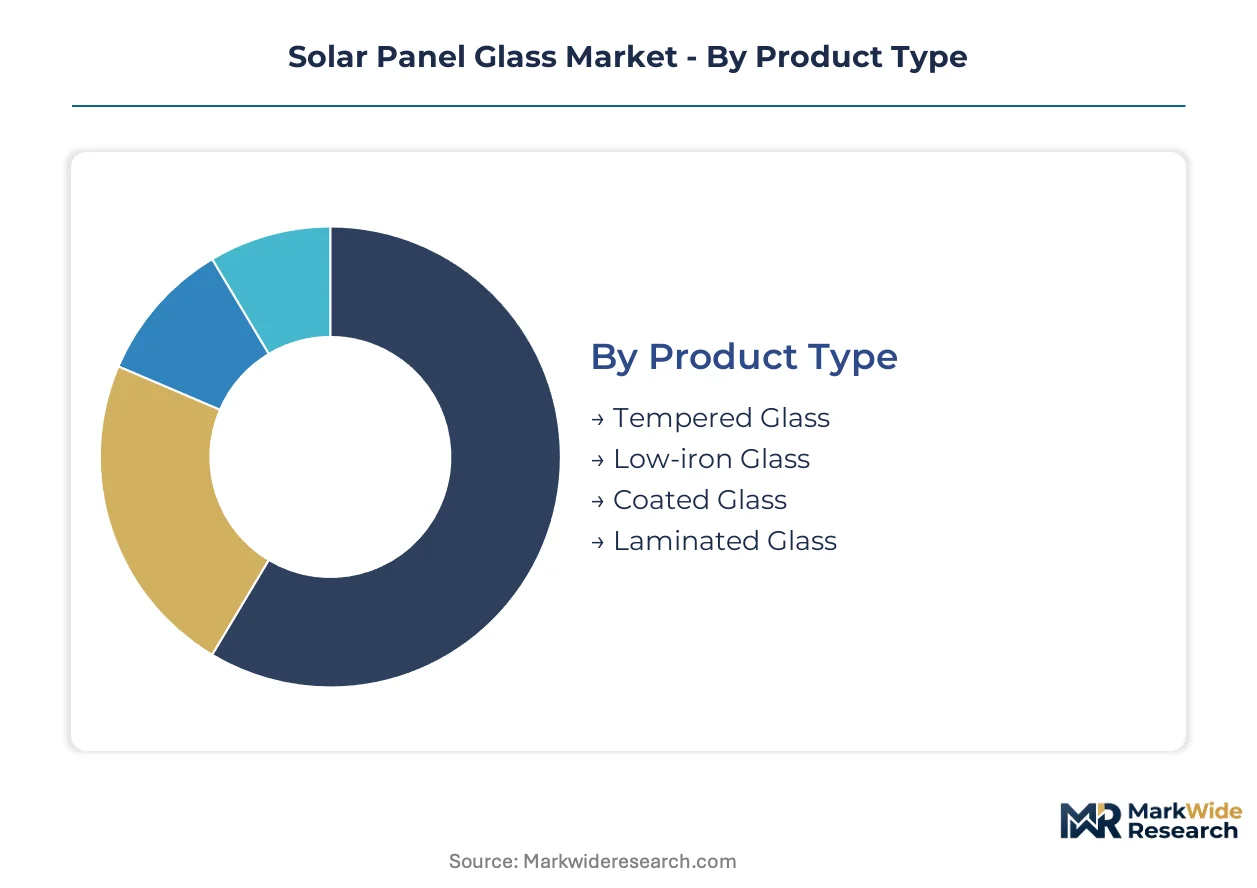
Glass substrate selection dictates module efficiency curves and field durability. Procurement patterns across product types, applications, thickness grades, and coating chemistries reveal how tier-one assemblers balance transmission performance against mechanical reliability and embodied-carbon compliance.
Product Type:
After-sales service intensity varies sharply across glass product categories, with coated and laminated variants demanding specialized field diagnostics and replacement protocols that tempered and standard low-iron substrates rarely require.
- Low-iron Glass:Engineered with iron content below 0.1 percent to maximize photon transmission through the visible spectrum. Utility-scale developers in China and the United States specify this substrate for gigawatt-scale arrays where every percentage point of transmission translates to measurable energy yield gains.
- Tempered Glass:Thermally strengthened through controlled heating and rapid cooling cycles to withstand mechanical loads and thermal cycling. India's domestic module assemblers source tempered variants from Borosil Renewables and Xinyi Solar to meet BIS mechanical strength mandates for rooftop installations.
- Coated Glass:Deposited with nano-scale anti-reflective or functional layers to boost transmission and reduce soiling adhesion. Premium pricing reflects coating equipment capex and chemistry reformulation costs under REACH heavy-metal constraints.
- Laminated Glass:Dual-glass configurations with interlayer bonding for enhanced durability and PID resistance. Distributed solar installers in the United States increasingly specify laminated structures for residential applications requiring 25-year performance warranties.
Low-iron glass holds the largest share; momentum sits with coated variants as high-efficiency module assemblers absorb margin premiums for transmission gains.
Application:
Cost tier stratification separates utility-scale procurement—driven by project finance structures and long-term offtake agreements—from residential and commercial segments where installer relationships and distributor networks shape purchasing patterns.
- Utility-scale:Gigawatt-scale solar farms specify thick-substrate, high-transmission glass through furnace-dedicated procurement contracts. China's dual carbon goals and the EU Green Deal tighten embodied-carbon standards for components feeding these projects.
- Residential:Distributed rooftop installations demand laminated and coated variants for durability and aesthetic integration. US installers specify dual-glass laminates to differentiate on warranty terms and hail resistance.
- Commercial:Mid-scale rooftop and ground-mount systems balance performance specifications against capital constraints. Indian commercial developers favor domestically certified tempered glass to avoid BIS import compliance friction.
- Off-grid Systems:Remote and rural electrification projects prioritize cost-optimized tempered glass with standard transmission profiles. African and Southeast Asian off-grid deployments source from Chinese exporters with streamlined logistics.
Utility-scale applications absorb the greatest volume; residential distributed solar is climbing the fastest as installer networks expand specification authority.
Thickness:
Volume concentration in 3mm and 4mm substrates reflects module lightweighting trends, while thicker grades retain niche utility in structural applications and extreme climate zones requiring enhanced mechanical margins.
- 3mm:Ultra-thin float-glass output optimized for lightweight module architectures and reduced aluminum framing requirements. Chinese module exporters specify 3mm substrates to minimize freight costs for containerized shipments.
- 4mm:Dominant thickness for crystalline-silicon modules balancing mechanical strength against weight and material cost. Float-glass producers configure furnace output splits around 4mm demand from tier-one assemblers.
- 6mm:Structural-grade thickness for utility-scale ground-mount systems in high-wind and heavy-snow load zones. Limited demand concentration in northern China and central US utility corridors.
- 10mm:Specialized thickness for concentrated solar power and building-integrated photovoltaic applications requiring thermal mass and structural integration. European BIPV developers specify 10mm for facade and skylight installations.
4mm thickness commands the greatest shipment volume; 3mm substrates are gaining share fastest as module lightweighting accelerates.
Coating Type:
Margin structure across coating chemistries reflects formulation complexity, patent positions, and regulatory compliance burdens—particularly REACH heavy-metal constraints and MEE emissions benchmarks affecting coating deposition processes.
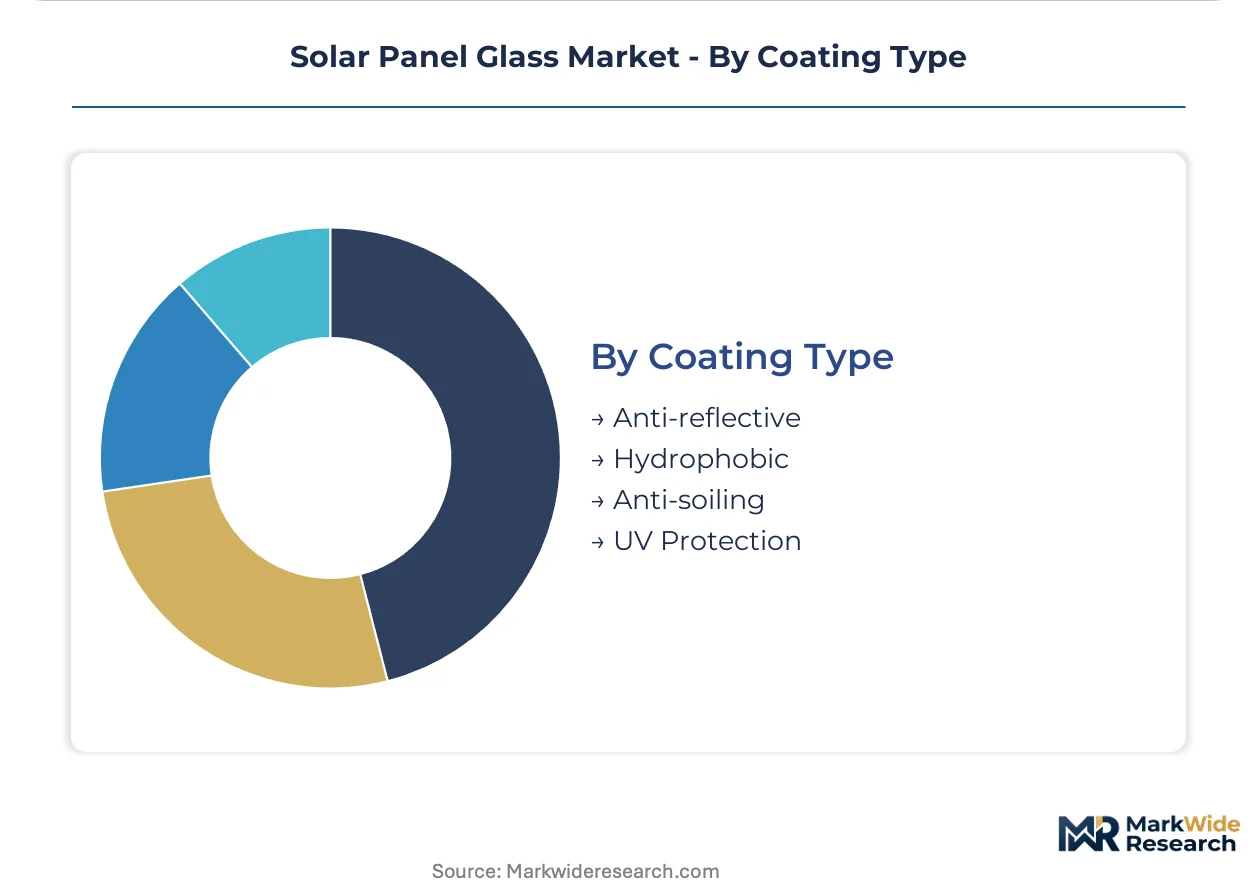
- Anti-reflective:Nano-porous silica or sol-gel coatings reducing surface reflection from 4 percent to below 1 percent. Tier-one Chinese and US module producers specify anti-reflective coatings for premium product lines.
- Anti-soiling:Hydrophobic surface treatments minimizing dust and organic adhesion in arid climates. Middle Eastern and Indian utility-scale developers prioritize anti-soiling coatings to reduce cleaning frequency and water consumption.
- Hydrophobic:Water-repellent coatings for high-humidity and coastal environments where moisture degradation accelerates. Southeast Asian module assemblers integrate hydrophobic glass for tropical deployment conditions.
- UV Protection:Absorptive coatings filtering ultraviolet wavelengths to reduce polymer backsheet and encapsulant degradation. Niche specification for high-altitude and equatorial installations with elevated UV flux.
Anti-reflective coatings hold the largest share; anti-soiling treatments are expanding most quickly as arid-climate utility-scale deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and the EU Green Deal are tightening embodied-carbon standards for solar components, redirecting procurement flows toward domestic manufacturers with emissions-compliant kiln configurations.
China
Utility-scale solar farms in Inner Mongolia and Xinjiang are driving volume procurement of high-transmission glass through long-term offtake agreements. The MEE enforces emissions benchmarks on float-glass kilns, accelerating furnace upgrades among producers. Xinyi Solar Holdings anchors supply from integrated float-glass furnaces in Anhui and Jiangsu provinces.
India
Domestic module assembly capacity expansion in Gujarat and Tamil Nadu is pulling tempered-glass demand from local suppliers. BIS certification mandates mechanical strength testing for imported solar glass, creating compliance barriers for non-domestic suppliers. Borosil Renewables dominates the domestic tempered-glass segment with furnace configurations optimized for local silica grades.
United States
Project finance structures for gigawatt-scale arrays in Texas and California specify premium coated substrates, lowering capital thresholds for developers. The IRA production tax credits incentivize domestic module assembly, indirectly supporting glass procurement localization. First Solar and domestic thin-film producers in Ohio and Arizona specify modified substrates for utility-scale deployments.
Germany
Building-integrated photovoltaic installations in Bavaria and Baden-Württemberg demand 10mm structural-grade glass for facade integration. REACH constraints on heavy-metal coating chemistries compel reformulation investments among exporters to the EU. Saint-Gobain anchors European supply through specialized low-iron production lines in the Saarland region.
Japan
Residential rooftop installations in Kanto and Kansai regions increasingly specify laminated configurations for enhanced durability and PID resistance. METI efficiency standards for photovoltaic components indirectly shape glass transmission requirements. Nippon Sheet Glass occupies a position among domestic suppliers serving precision-oriented module assemblers in the Nagoya industrial corridor.
Solar Panel Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across furnace-dedicated procurement and technical co-development agreements. The market structure concentrates among integrated float-glass producers with captive silica sourcing and emissions-compliant kiln configurations. Three archetypes dominate: integrated energy-asset owners, specialized low-iron producers, and coating-technology licensors. Competitive moves center on furnace retrofit investments for MEE compliance and direct procurement contracts displacing distributor-mediated supply.
Among China-based producers, Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd., and CSG Holding Co. Ltd. exemplify the integrated archetype with in-house float-glass furnace networks. Saint-Gobain represents the European specialized producer segment, while Borosil Renewables Ltd. anchors India's domestic tempered-glass supply. These companies occupy positions that reflect national industrial policy alignment—Chinese players leverage scale and integration, European suppliers emphasize regulatory compliance and premium positioning, and Indian manufacturers capture domestic certification advantages.
| Leading Market Players |
|---|
| Xinyi Solar Holdings Ltd. |
| Flat Glass Group Co., Ltd. |
| AGC Inc. |
| Saint-Gobain |
| IRICO Group New Energy Co., Ltd. |
| Guardian Glass |
| Nippon Sheet Glass Co., Ltd. |
| CSG Holding Co. Ltd. |
| Borosil Renewables Ltd. |
| Others |
Pricing and Supply Chain Analysis
Float-glass furnace undercapacity in China's Jiangsu and Anhui provinces is tightening supply elasticity and amplifying pricing power for integrated producers with MEE-compliant kiln configurations. This utilization squeeze concentrates margin capture among Xinyi Solar Holdings and Flat Glass Group while forcing tier-two assemblers toward longer-term offtake commitments to secure volume.
Pricing Analysis
Certification level creates the primary spread across the solar panel glass market, with BIS-certified tempered variants for India's rooftop segment commanding distinct premiums over standard low-iron exports. Three-tier pricing structure across anti-reflective coated, standard low-iron, and economy tempered grades reflects furnace-dedicated procurement contracts versus spot-market transactions. Cost compression in economy tempered grades is intensifying because Chinese exporters are absorbing freight exposure to maintain volume share in African and Southeast Asian off-grid deployments. Utility-scale developers with project finance backing exhibit lowest price sensitivity, while commercial installers in India face acute margin pressure from BIS compliance costs.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard among Chinese float-glass producers supplying tier-one module assemblers, tightening working capital requirements for furnace operators. Geographic supply concentration rests on China, India, and Germany as the three dominant production hubs, with China's integrated producers controlling captive silica sourcing from Anhui deposits. Raw material dependencies center on high-purity silica sand, soda ash, and specialized coating chemistries subject to REACH heavy-metal constraints. Single-source vulnerability from concentrated silica deposits in limited geographies exposes producers to input cost volatility. Distribution runs through direct procurement contracts displacing distributor-mediated supply for volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film photovoltaic substrates optimized for cadmium-telluride and perovskite thermal expansion coefficients represent a material substitution threat that crystalline-silicon glass incumbents must navigate through technical co-development partnerships.
For Market Incumbents: Entrench furnace-dedicated procurement relationships with tier-one module assemblers in China and the United States to lock volume commitments before thin-film alternatives scale. Accelerate oxy-fuel combustion retrofits to meet tightening MEE emissions benchmarks and defend margin position against carbon-border adjustment exposure in EU markets. Prioritize backward integration into captive silica mining to insulate input costs from freight volatility. For New Entrants and Emerging Players: India's commercial rooftop segment represents the most penetrable entry point given BIS certification barriers that exclude established Chinese exporters from direct competition. Anti-soiling coating specialization for Middle Eastern utility-scale developers offers a technical differentiation vector with limited incumbent concentration. A go-to-market angle anchored on localized furnace configuration for regional silica grades bypasses freight disadvantages against integrated Chinese producers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEE-compliant kiln retrofits and oxy-fuel combustion upgrades, favoring asset-light coating-technology licensors over furnace operators. Acquisition targets with established low-iron production lines and REACH-compliant coating chemistries offer defensive positioning through regulatory moats. The signal to watch is furnace utilization rates in China's Jiangsu corridor as a leading indicator of pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Combustion Retrofit | MEE emissions compliance secures market access for Chinese furnace operators against carbon-border restrictions. |
| Direct Procurement Contracting | Furnace-dedicated offtake agreements with First Solar and domestic Chinese thin-film producers compress distributor margins. |
| Anti-Reflective Coating Scale-Up | REACH-compliant nano-porous silica deposition captures margin premiums from high-efficiency module assemblers. |
| Silica Sourcing Integration | Captive mining in Anhui province insulates Xinyi Solar from freight exposure and input cost volatility. |
| Laminated Glass Configuration Expansion | Dual-glass interlayer bonding meets US residential installer demand for 25-year performance warranties. |
Research Methodology
Desk research of customs trade filings, SEC 10-K disclosures from glass and module producers, and MEE emissions benchmark documentation preceded structured interviews with float-glass plant managers, procurement leads at tier-one photovoltaic module assemblers, and EPC contractors active in utility-scale solar development. Primary fieldwork with distribution channel partners and technical R&D directors at coating equipment suppliers combined with secondary validation against project development databases and IEA renewable energy deployment reports. Bottom-up volume triangulation across furnace output splits and top-down demand modeling from module assembly capacity expansions anchored the analytical framework.
Assumptions regarding MEE emissions benchmark enforcement intensity, REACH heavy-metal coating chemistry compliance timelines, and IRA production tax credit continuity were held fixed across the projection horizon while module efficiency curves and thin-film market penetration rates were varied in sensitivity scenarios. Segmentation dimensions modeled include glass product type, application scale, thickness grade, coating chemistry, and regional regulatory framework cluster. CAGRs were derived from regression analysis of historical furnace output against module deployment data, incorporating silica sand price indices and energy cost trajectories as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in Chinese electricity pricing for industrial consumers, EU carbon-border adjustment implementation speed, or Indian BIS certification enforcement rigor would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory compliance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Skin Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Chile Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market