
 Solar Power Tracker Market | 2026-2036
Solar Power Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Power Tracker Market Insights
The EU Green Deal's renewable energy targets is realigning procurement criteria for European utility developers. Nextracker leverages its distributed manufacturing model to sustain delivery timelines across multiple continents. Array Technologies anchors the North American utility segment through centralized drive architecture. Soltec competes aggressively in bifacial-compatible tracker designs for high-albedo desert installations.
A solar power tracker is a mechanical system that orients photovoltaic modules toward the sun using single or dual axis rotation, typically achieving 0.5-degree positional accuracy through sensor-driven motor control. Its primary purpose is maximizing energy yield per installed watt by minimizing angle-of-incidence losses throughout diurnal and seasonal cycles. Single axis trackers dominate installed capacity due to favorable levelized cost of energy economics on flat terrain. Dual axis configurations command premium positioning in concentrated solar power applications where precise focal alignment determines thermal conversion efficiency. Smart trackers with machine learning-based predictive algorithms represent the fastest-growing technology subset, capturing margin pools through software-defined performance optimization and remote diagnostic capabilities.
FERC interconnection standards in the United States, CE marking requirements under EU machinery directives, and India's CEA grid code specifications collectively shape product certification pathways and market access timelines for tracker manufacturers. The EU AI Act's emerging provisions on autonomous control systems will extend compliance obligations to algorithmically managed tracking platforms. Stakeholders must monitor evolving bifacial compatibility standards and regional content requirements as procurement criteria harden across jurisdictions.
Market Dynamics
Bifacial module penetration is compressing tracker qualification timelines as developers demand hardware that captures rear-side irradiance across high-albedo desert installations. NREL certification protocols now dominate procurement prequalification, forcing manufacturers to validate structural load models against accelerated degradation cycles.
Growth Catalysts
- EU Green Deal renewable targets:European utility developers are rewriting procurement specifications to prioritize trackers with embedded carbon accounting and circular material passports.
- Single-axis tracker economics:Levelized cost of energy advantages on flat terrain continue displacing fixed-tilt installations across utility-scale solar pipelines in the southwestern United States.
- Machine learning control systems:Predictive algorithms that anticipate cloud transients and optimize slew rates are capturing margin pools through software-defined yield enhancement.
Market Restraints
- Steel input cost volatility:Galvanized structural steel accounts for substantial bill-of-materials exposure, with tariff fluctuations between the United States and Mexico disrupting landed cost forecasting.
- Geographic supply concentration:Drive motor and gearbox manufacturing clusters in China's industrial heartland create vulnerability to port congestion and export licensing delays.
- Bifacial compatibility gaps:Legacy tracker architectures lack the row-spacing geometry and torque tube clearance to prevent rear-side shading losses on east-west tracking configurations.
Strategic Opportunities
- Saudi Arabia gigawatt-scale tenders:The kingdom's renewable energy procurement office is mandating local content thresholds that favor joint ventures with domestic steel fabrication and civil construction capabilities.
- EU AI Act autonomous control provisions:Algorithmic tracking platforms will face new conformity assessment pathways, creating first-mover advantage for vendors with pre-certified predictive control systems.
- Agricultural solar integration:Elevated tracker architectures that maintain ground clearance for mechanized farming operations are opening dual-use revenue streams in Spain's arid agricultural zones.
Industry Challenges
- Structural engineering talent scarcity:Finite element analysis specialists capable of validating tracker designs against IEC 62817 torsional load standards command premium compensation and extended hiring cycles.
- Certification timeline compression:NREL's bankability validation process now requires concurrent mechanical testing and financial stress modeling, extending product launch schedules by multiple quarters.
- Legacy SCADA integration friction:Smart tracker communication protocols must bridge proprietary inverter networks and utility telemetry systems, complicating commissioning workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Power Tracker Market |
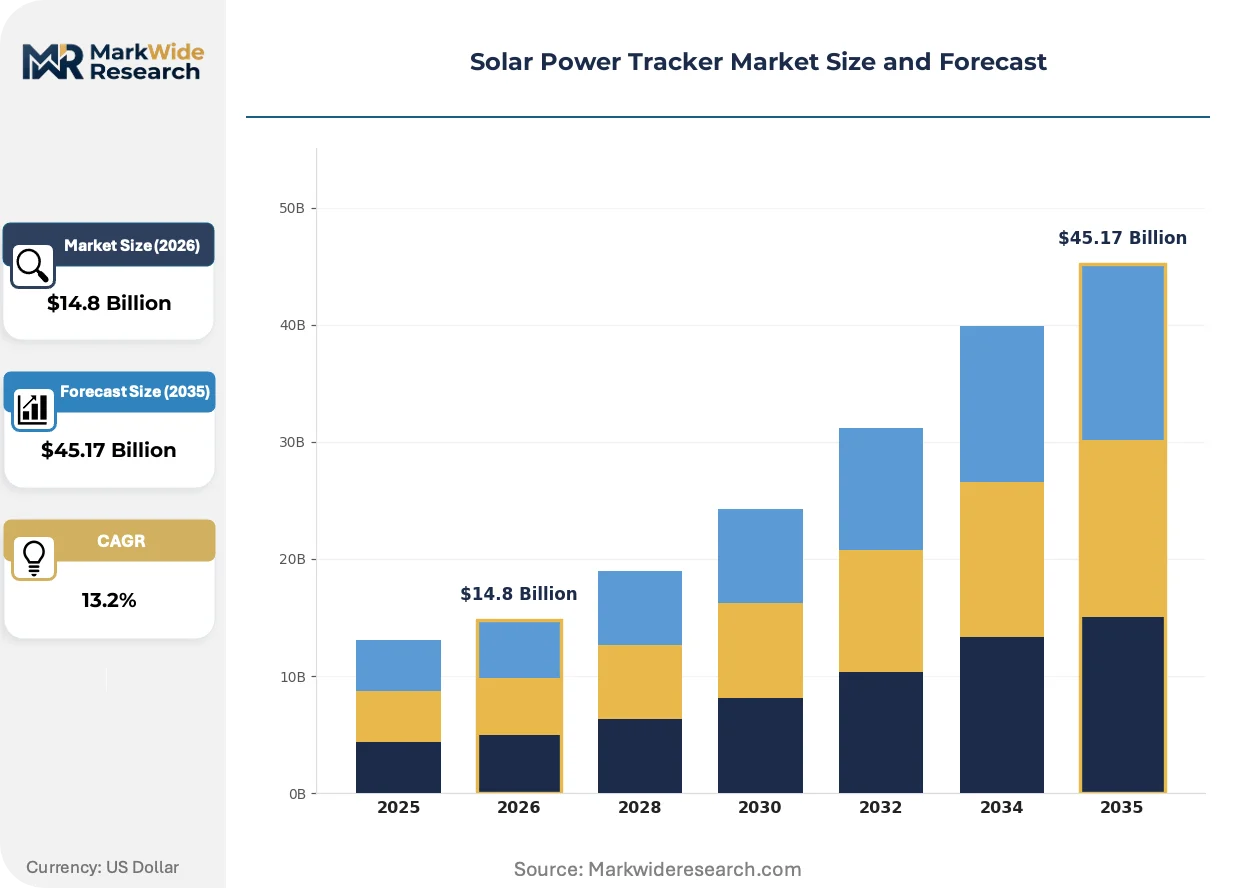
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $45.17 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Fixed Tilt, Smart Trackers Technology: PV Tracking, Concentrated Solar Power, Hybrid Systems, Advanced Control End User: Utility Scale, Commercial, Residential, Agricultural Installation Type: Ground Mounted, Rooftop, Floating, Bifacial |
| Companies Covered | Nextracker, Arctech Solar, Array Technologies, TrinaTracker, PV Hardware, Soltec, GameChange Solar, FTC Solar, Ideematec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Power Tracker Market Trends and Innovations
Tracker hardware is converging with predictive software and bifacial module architectures, creating integrated systems where mechanical precision and algorithmic control jointly determine energy yield. This convergence is redrawing competitive boundaries between structural fabricators and energy analytics providers.
Distributed torque tube architectures with independent row control are electrifying tracker responsiveness to granular irradiance variability. Utility developers in Spain and Saudi Arabia are deploying these systems to minimize row-to-row shading losses during low-sun-angle morning and evening periods. The technology is compressing the performance gap between single-axis and dual-axis configurations without the mechanical complexity of full two-axis rotation.
The EU AI Act's emerging provisions on autonomous control systems will extend CE marking obligations to algorithmically managed tracking platforms. Manufacturers must now document decision transparency and fail-safe behaviors for machine learning-driven slew commands. European utility procurement teams are beginning to require AI conformity documentation alongside traditional machinery safety certifications.
Developer procurement departments are unbundling tracker supply from engineering-procurement-construction contracts, creating direct vendor relationships that bypass traditional EPC intermediaries. This channel shift concentrates buying power with independent power producers and asset owners in the southwestern United States. Long-term service agreements and predictive maintenance subscriptions are displacing upfront hardware margins as the primary revenue anchor.
Solar Power Tracker Market Segmentation
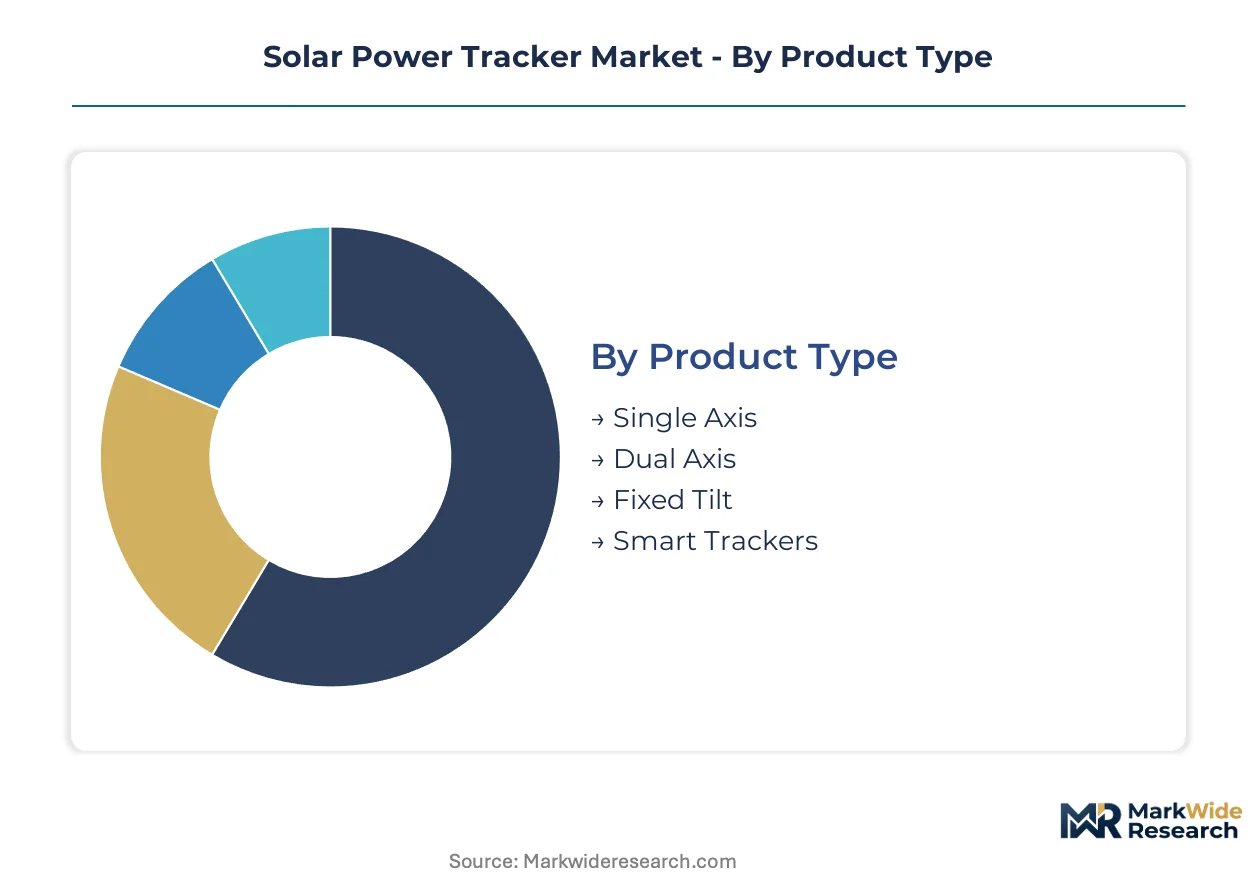
Tracker segmentation determines capital deployment strategies and technology roadmaps for developers. Product architecture choices cascade through steel procurement volumes, foundation engineering requirements, and software integration complexity.
Product Type:
Capital intensity varies sharply across mechanical configurations, with motor count and structural steel tonnage driving upfront project finance requirements.
- Single Axis:One rotational degree of freedom tracks the sun's east-west path across the sky. Utility-scale pipelines in the southwestern United States favor this architecture for its favorable levelized cost of energy on flat desert terrain with minimal grading requirements.
- Dual Axis:Azimuth and elevation rotation achieve precise perpendicular alignment to solar rays throughout seasonal declination changes. Concentrated solar power plants in Spain deploy these systems where focal accuracy determines thermal conversion efficiency and molten salt storage economics.
- Fixed Tilt:Static mounting at fixed inclination angles eliminates motorized components entirely. Distributed commercial installations with constrained rooftop footprints or rocky ground conditions select this lowest-capital option despite yield penalties.
- Smart Trackers:Embedded sensor arrays and edge computing modules enable predictive slew algorithms and remote diagnostic telemetry. Machine learning-based control systems are capturing margin pools through software-defined performance optimization.
Single axis absorbs the bulk of installed capacity; smart trackers are expanding most quickly.
Technology:
Application context determines whether tracking serves photovoltaic conversion or thermal concentration, with distinct precision and durability specifications.
- PV Tracking:Silicon module orientation maximizes incident irradiance capture across diurnal cycles. Bifacial compatibility requirements are compressing row-spacing geometries and torque tube clearance specifications for rear-side irradiance optimization.
- Concentrated Solar Power:Mirror or lens alignment focuses sunlight onto thermal receivers for steam generation. Saudi Arabia's gigawatt-scale tenders specify sub-degree tracking accuracy to maintain receiver temperature stability and turbine efficiency.
- Hybrid Systems:Combined photovoltaic and thermal capture leverages shared tracking infrastructure. Agricultural zones in Spain deploy these configurations to generate electricity while maintaining ground clearance for mechanized farming operations.
- Advanced Control:Predictive algorithms anticipate cloud transients and optimize slew rates to minimize mechanical wear. The EU AI Act's emerging provisions will extend CE marking obligations to these algorithmically managed platforms.
PV tracking dominates current deployment volumes; advanced control systems are climbing the fastest.
End User:
Customer scale determines procurement sophistication, with utility developers wielding direct vendor relationships that bypass traditional EPC intermediaries.
- Utility Scale:Gigawatt-class solar farms with centralized inverters and substation interconnection. Independent power producers in the southwestern United States unbundle tracker supply from engineering-procurement-construction contracts to concentrate buying power.
- Commercial:Behind-the-meter installations serving industrial load centers with peak-shaving objectives. Flat rooftop and carport configurations in Spain favor elevated single-axis architectures with distributed electrical architecture.
- Residential:Small-scale ground-mount or rooftop systems with limited structural load capacity. Fixed tilt dominates this price-sensitive segment due to tracker cost premiums and permitting complexity.
- Agricultural:Dual-use agrivoltaic installations maintaining ground clearance for crop cultivation or livestock grazing. Arid agricultural zones are opening revenue streams through elevated tracker designs compatible with mechanized farming.
Utility scale commands the majority of tracker procurement value; agricultural applications are gaining share fastest.
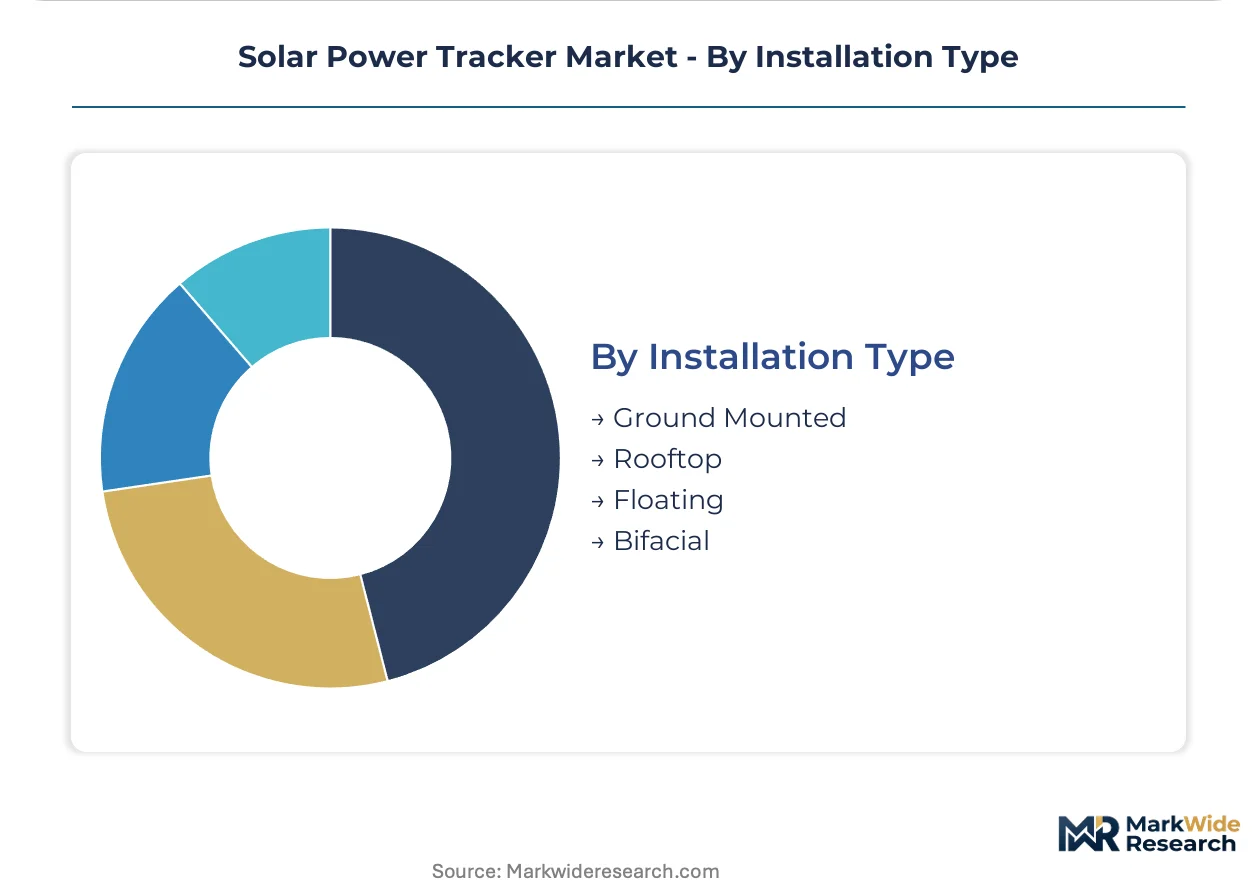
Installation Type:
Foundation engineering and environmental exposure requirements segment hardware durability specifications and maintenance protocols.
- Ground Mounted:Driven pile or ballasted foundations on graded earth surfaces. Desert installations in Saudi Arabia specify corrosion-resistant coatings and sand-ingress sealing for drive motor enclosures.
- Rooftop:Structural attachment to commercial building frames with weight and wind-load constraints. Spain's commercial sector favors low-profile single-axis designs that minimize ballast requirements and parapet interference.
- Floating:Pontoon or tension-mooring systems on reservoirs and quarry lakes. Water surface cooling enhances module efficiency while tracking maximizes yield per acre of water coverage.
- Bifacial:Configurations optimized for rear-side irradiance capture on high-albedo surfaces. NREL certification protocols now validate structural load models against accelerated degradation cycles for these installations.
Ground mounted represents the dominant installation base; bifacial configurations are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors the southwestern United States corridor where utility-scale solar deployment concentrates. Tracker procurement flows through independent power producers with direct vendor relationships. Steel fabrication clusters in Monterrey, Mexico supply structural components across the border.
United States
FERC interconnection standards shape tracker certification timelines for utility developers. The Inflation Reduction Act's domestic content bonuses redirect procurement toward North American steel sources. Arizona's Sonoran Desert hosts gigawatt-scale installations where single-axis trackers maximize yield on flat, graded terrain.
Spain
EU Green Deal renewable targets compress project development cycles for Iberian solar pipelines. CE marking requirements under machinery directives extend to algorithmic control systems. Andalusia's arid agricultural zones deploy elevated trackers compatible with mechanized farming operations.
Saudi Arabia
The kingdom's renewable energy procurement office mandates local content thresholds for gigawatt-scale tenders. The national regulator specifies sub-degree tracking accuracy for thermal receiver stability. Eastern Province steel fabrication joint ventures anchor domestic supply chain development.
China
Dual carbon goals accelerate concentrated solar power deployment in northwestern desert provinces. GB standards govern structural load validation for export-bound tracker hardware. Xinjiang's industrial corridor hosts drive motor and gearbox manufacturing clusters serving global demand.
Germany
EU AI Act provisions on autonomous control systems extend conformity assessment to predictive tracking platforms. REACH compliance shapes coating specifications for corrosion-resistant structural steel. Bavaria's precision engineering sector supplies sensor arrays for smart tracker edge computing modules.
Solar Power Tracker Market Competitive Landscape
Premium-margin players sit above commodity-margin players across software integration and predictive control capabilities. The vendor base stratifies into three tiers: integrated hardware-software providers, structural fabricators with licensed control systems, and regional steel specialists. Strategic archetypes include distributed manufacturing platforms, centralized drive architecture specialists, and bifacial-compatible design innovators. Competitive moves concentrate on unbundling tracker supply from EPC contracts and securing long-term service agreement revenue streams.
Within the integrated tier, Nextracker and Array Technologies occupy positions exemplifying divergent mechanical philosophies. Arctech Solar represents the Chinese manufacturing scale archetype. Soltec anchors European specialization in high-albedo desert configurations. These named entities illustrate how competitive positioning fragments across geographic origin and architectural approach rather than consolidating around unified technical standards.
| Leading Market Players |
|---|
| Nextracker |
| Arctech Solar |
| Array Technologies |
| TrinaTracker |
| PV Hardware |
| Soltec |
| GameChange Solar |
| FTC Solar |
| Ideematec |
| Others |
Pricing and Supply Chain Analysis
Galvanized structural steel tonnage anchors tracker economics, flowing from Mexican fabrication clusters through tariff-sensitive border logistics into three-tier pricing structures across premium, standard, and economy levels in the southwestern United States.
Pricing Analysis
Energy yield guarantees anchor value-based pricing, with smart tracker vendors commanding software-defined premiums against commodity hardware tiers. Price differentiation separates NREL-certified bifacial-compatible architectures from legacy fixed-tilt alternatives. Cost compression in standard-tier single-axis systems is intensifying because steel input volatility and qualification timeline extensions squeeze margin pools. Utility-scale independent power producers exhibit lowest price sensitivity, prioritizing bankability validation and long-term service bundling over upfront capital outlay.
Supply Chain Analysis
Container freight rates from Chinese industrial heartlands to Saudi Arabia's Eastern Province and Spain's Mediterranean ports dictate landed cost forecasting precision for drive motor and gearbox assemblies. Manufacturing clusters in China, Mexico, and Germany feed structural steel, precision sensors, and control electronics respectively. Single-source vulnerability concentrates in Xinjiang-sourced torque tube drive systems. Distribution runs through direct vendor relationships with independent power producers that displace traditional EPC intermediaries in the southwestern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's autonomous control provisions erect compliance moats that favor pre-certified predictive tracking vendors against uncertified challengers entering European procurement pipelines.
For Market Incumbents: To counter algorithmic control commoditization, Nextracker and Array Technologies should deepen backward integration into sensor array production and secure captive steel supply from Monterrey fabrication joint ventures. Pre-certifying machine learning slew algorithms against emerging EU conformity assessment pathways preserves margin pools in European utility tenders.
For New Entrants and Emerging Players: Agricultural solar integrators in Spain's Andalusian zones represent the most penetrable white-space target, with elevated tracker architectures for mechanized farming operations commanding limited incumbent focus. Joint venture structures with domestic civil construction capabilities unlock Saudi Arabia's local content thresholds.
For Investors and Strategic Acquirers: NREL certification queue elongation is the leading indicator that bankability validation capacity constrains market entry, favoring acquisition targets with concurrent mechanical testing and financial stress modeling capabilities. Targets with embedded carbon accounting and circular material passport systems align with EU Green Deal procurement hardening.
| Strategic Initiative | Industry Significance |
|---|---|
| NREL Bankability Pre-Certification | Accelerates procurement prequalification timelines for bifacial-compatible tracker architectures. |
| EU AI Act Conformity Assessment | Extends CE marking obligations to machine learning-driven slew command systems. |
| Monterrey Steel Fabrication Joint Venture | Secures tariff-advantaged structural component supply for North American utility pipelines. |
| Predictive Maintenance Subscription Launch | Displaces upfront hardware margins with recurring revenue from remote diagnostic telemetry. |
| Agrivoltaic Elevated Architecture Development | Opens dual-use revenue streams in Spain's arid agricultural zones with mechanized farming clearance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with utility planning officers, EPC procurement leads, tracker product engineers, and grid interconnection specialists. FERC interconnection databases, NREL certification logs, EU machinery directive filings, and Saudi renewable energy tender documents supplied quantitative validation. Bottom-up project pipeline aggregation and top-down steel consumption modeling cross-checked volume estimates across the analysis window.
Granular modeling tracked single-axis, dual-axis, and smart tracker configurations separately across utility-scale, commercial, and agricultural end-use segments. Technology splits between PV tracking, concentrated solar power, and hybrid systems incorporated bifacial compatibility coefficients and machine learning control penetration rates. CAGRs derived from regression against historical deployment curves and forward-projected LCOE differentials, with steel price indices and interconnection queue durations as sensitivity inputs.
Caveats apply where tariff fluctuations between the United States and Mexico, port congestion in Chinese industrial heartlands, or EU AI Act implementation delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Laminator Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Solar Rack Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Thin Film Photovoltaic Sales Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Czech Republic Solar Energy Market